
 ESD Clamshell Market | 2026-2036
ESD Clamshell Market Size, Share, and Industry Trends Forecast 2026-2036
ESD Clamshell Market Foresight
Aftermarket recycling and refurbishment of used ESD clamshells is reconfiguring margin pools away from virgin material sales toward closed-loop logistics services. Desco Industries leverages its North American distribution network to sustain channel control across industrial end users. 3M anchors its position through R&D intensity in conductive coating formulations. Protektive Pak specializes in multi-compartment designs that dominate medical device packaging applications.
ESD clamshells are thermoformed protective enclosures manufactured from electrically dissipative polymers, typically surface resistivity between 10^4 and 10^11 ohms per square, designed to shield static-sensitive components from electrostatic discharge damage during handling, transit, and storage. The primary industrial purpose centers on protecting semiconductors, printed circuit boards, and medical electronics from field-induced failures. Hinged and single-piece configurations lead the product type landscape due to their compatibility with automated handling equipment, while recyclable plastics represent the fastest-growing material trajectory as OEMs face supply chain sustainability mandates. Electronics packaging occupies the dominant application position, though medical supplies demand commands premium pricing through sterilization-compatible material requirements.
EPA guidelines on industrial plastic waste streams and REACH chemical restrictions in Europe constrain PVC-heavy formulations, redirecting formulation investment toward compliant polyethylene and polypropylene alternatives. FDA device packaging standards for sterile electronics further tighten material selection criteria for medical end users. Stakeholders must monitor evolving ESG disclosure rules across multiple jurisdictions, as carbon accounting for single-use protective packaging reshapes procurement criteria and supplier qualification protocols.
Market Dynamics
REACH chemical restrictions across Europe are redirecting formulation investment away from PVC-heavy clamshells toward polyethylene and polypropylene alternatives, compressing legacy supply chains while elevating compliant material premiums.
Growth Catalysts
- Taiwan Semiconductor Manufacturing:Advanced packaging nodes below 3nm require precision ESD protection during wafer transit, sustaining clamshell consumption intensity per unit shipped.
- EU Green Deal packaging mandates:Circular economy directives for electronics packaging accelerate demand for recyclable thermoformed enclosures with verified carbon footprints.
- Conductive polymer compounding:Carbon nanotube and inherently dissipative polymer blends enable thinner-wall designs without sacrificing surface resistivity performance.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and polyethylene resin prices fluctuate with crude oil benchmarks, compressing margins for converters locked into annual supply contracts.
- Taiwan-South Korea supply concentration:Over 60% of semiconductor-grade clamshell production clusters in two East Asian manufacturing corridors, exposing buyers to single-source risk.
- Technical performance ceiling:Thermoformed plastics cannot achieve the sub-10^4 ohm surface resistivity required for certain military-grade components without metalized inserts that compromise recyclability.
Strategic Opportunities
- Vietnam electronics corridor expansion:Samsung and Foxconn assembly relocation from China creates greenfield demand for localized ESD packaging supply.
- Medical device sterilization compatibility:Gamma and ethylene oxide-stable conductive formulations command 40-60% pricing premiums over standard electronics grades.
- Closed-loop logistics services:Reverse logistics platforms for clamshell collection, cleaning, and redeployment capture recurring revenue streams beyond virgin product sales.
Industry Challenges
- ESD certification timeline compression:ANSI/ESD S20.20 and IEC 61340-5-1 audit cycles now require annual recertification, straining quality engineering resources at mid-tier converters.
- Legacy ERP integration friction:Track-and-trace serialization requirements for medical device packaging demand API connectivity with customer MES systems that smaller molders lack capital to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ESD Clamshell Market |
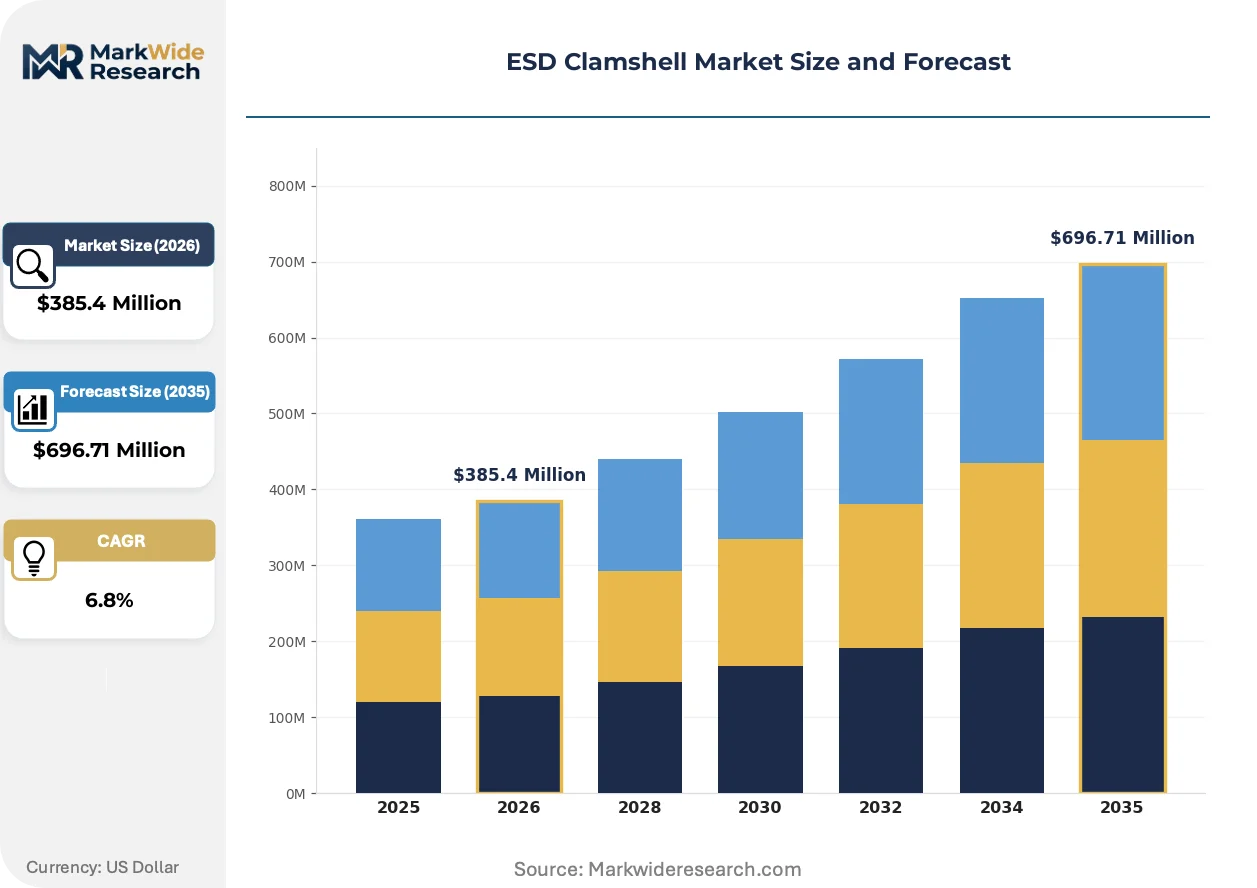
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Piece, Multi-Compartment, Hinged, Clamshell Trays Material: Polyethylene, Polypropylene, PVC, Recyclable Plastics Application: Electronics Packaging, Retail Packaging, Industrial Use, Medical Supplies End User: Manufacturers, Retailers, Distributors, OEMs |
| Companies Covered | 3M, Desco Industries, Tektronix, Static Control Components, Conductive Containers, Elcom, Protektive Pak, Integrated Packaging Films, GWP Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ESD Clamshell Market Shifts & Advancements
Material science breakthroughs and regulatory chemistry restrictions are converging to dismantle established PVC-based supply chains while elevating performance-demanding applications in medical and aerospace verticals.
Thermoformed polypropylene with inherently dissipative additive packages is collapsing the cost-performance tradeoff that previously favored PVC in mid-tier electronics applications. Medical device manufacturers in Germany and Switzerland now specify these formulations for single-use surgical electronics kits, accepting modest premiums for sterilization compatibility and simplified regulatory filing.
REACH Annex XVII restrictions on phthalate plasticizers took full effect across EU member states in 2025, rendering legacy PVC clamshell formulations non-compliant for electronics exports. Convertors in Poland and Czechia accelerated migration to polyethylene and polypropylene alternatives, though tooling amortization for new thermoforming molds extends payback periods to 18-24 months.
Direct procurement relationships between semiconductor fabs and specialized molders are displacing distributor intermediaries in East Asian supply chains. TSMC and Samsung now qualify clamshell suppliers directly against internal cleanliness and dimensional tolerance specifications, compressing channel margins while rewarding converters with captive metrology capabilities. This pattern is most visible in Hsinchu and Pyeongtaek manufacturing corridors.
ESD Clamshell Market Segmentation
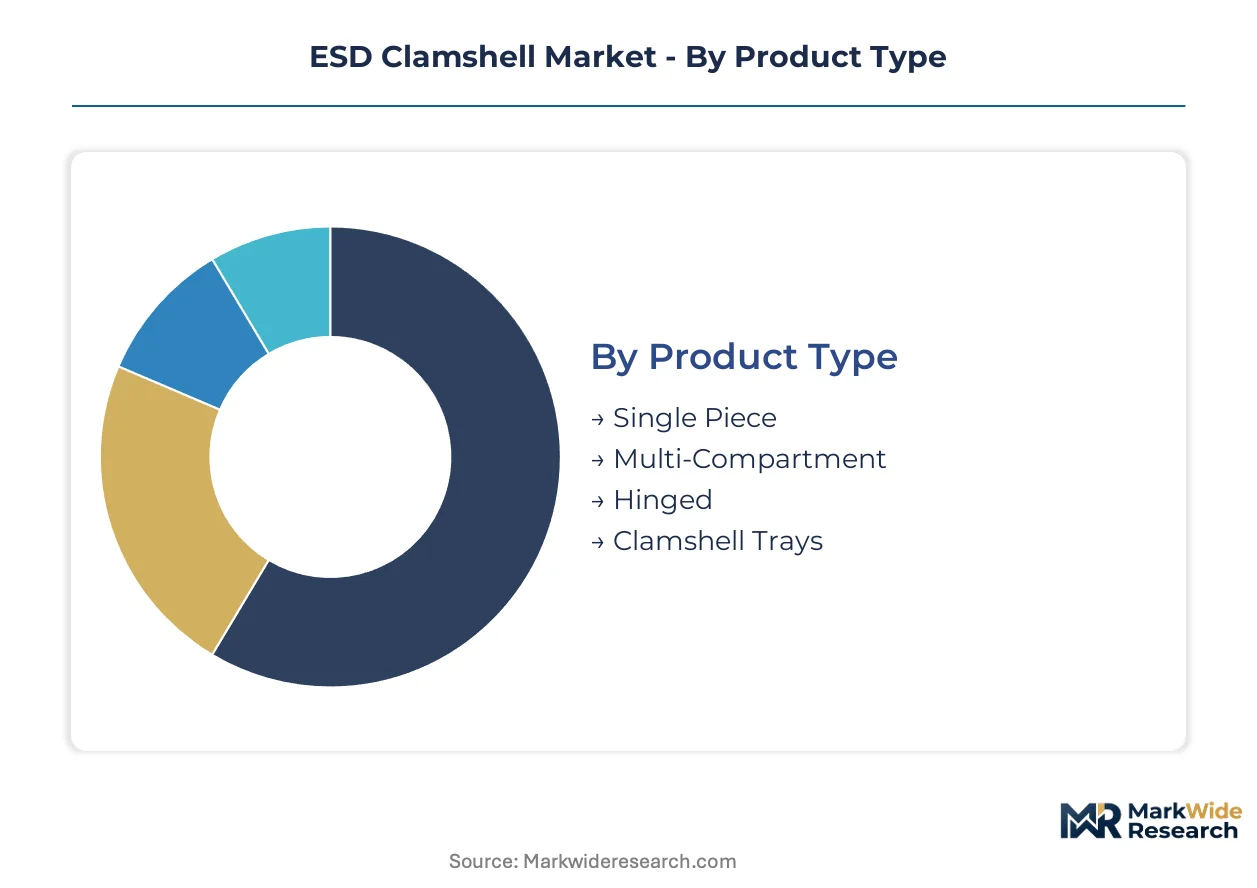
ESD clamshell segmentation reveals divergent margin structures across product architectures and material chemistries. Service intensity varies dramatically—medical-grade clamshells demand sterilization validation and lot traceability, while standard electronics packaging operates on volume-driven replenishment models.
Product Type:
After-sales service intensity escalates with design complexity, as multi-compartment and hinged configurations require dimensional recalibration and hinge fatigue testing over repeated use cycles.
- Hinged:Dual-panel construction with integrated living hinge enables automated handling compatibility and repeated access without lid separation. Demand concentrates in Taiwan and South Korea semiconductor fabs, where TSMC and Samsung specify these for wafer shuttle containers requiring cleanroom compatibility.
- Multi-Compartment:Partitioned cavities accommodate multiple component geometries within single enclosure, reducing packaging SKU proliferation for contract electronics manufacturers. Medical device OEMs in Germany and Switzerland absorb premium pricing for surgical kit configurations validated to gamma sterilization protocols.
- Single Piece:Unitary thermoformed shell without articulation points offers lowest unit cost and fastest cycle times.
- Clamshell Trays:Shallow-profile designs optimized for automated pick-and-place integration.
Hinged configurations hold the largest share; momentum sits with multi-compartment designs for medical electronics consolidation.
Material:
Cost tier stratification separates commodity resins from performance-engineered formulations, with regulatory compliance premiums widening spreads between PVC alternatives and legacy grades.
- Recyclable Plastics:Post-industrial and post-consumer polypropylene blends with verified carbon footprints satisfy EU Green Deal packaging mandates. Electronics OEMs in Vietnam and Mexico now specify these for ESG disclosure compliance, accepting 15-25% premiums over virgin formulations.
- Polypropylene:Inherently dissipative additive packages enable thinner-wall designs without sacrificing surface resistivity performance between 10^4 and 10^11 ohms per square. REACH Annex XVII phthalate restrictions accelerated converter migration from PVC in Poland and Czechia.
- Polyethylene:Lower density option favored for cost-sensitive consumer electronics transit protection.
- PVC:Legacy formulation facing formulation obsolescence across European export markets.
Polypropylene dominates current volume; recyclable plastics are climbing the fastest as sustainability procurement criteria harden.
Application:
Application segmentation maps directly to sterilization burden and regulatory filing intensity, with medical verticals demanding extensive validation documentation.
- Electronics Packaging:Dominant volume segment encompassing semiconductor wafer protection, printed circuit board transit, and component shipping. Taiwan and South Korea fabs drive consumption intensity for sub-3nm advanced packaging nodes requiring precision ESD protection.
- Medical Supplies:Gamma and ethylene oxide-stable conductive formulations command substantial pricing premiums over standard electronics grades. Swiss and German surgical electronics manufacturers specify these for single-use sterile kits with simplified regulatory filing pathways.
- Industrial Use:General manufacturing protection for automation components and instrumentation.
- Retail Packaging:Consumer-facing display and theft-deterrent applications with minimal ESD performance requirements.
Electronics packaging retains the largest share; medical supplies deliver the steepest expansion trajectory through sterilization-compatible material premiums.
End User:
Customer type determines procurement sophistication, with OEMs and semiconductor fabs increasingly bypassing distribution intermediaries for direct converter relationships.
- OEMs:Original equipment manufacturers in consumer electronics and medical devices specify clamshell performance parameters directly, qualifying suppliers against internal cleanliness and dimensional tolerance standards. Samsung and Foxconn relocation to Vietnam created greenfield demand for localized supply qualification.
- Manufacturers:Component and subsystem producers purchasing standard grades through distribution channels.
- Distributors:Channel intermediaries facing margin compression as direct procurement relationships proliferate in East Asia.
- Retailers:End-of-chain purchasers with minimal technical specification involvement.
OEMs command the largest procurement volume; manufacturers are gaining share fastest as contract electronics manufacturing scales in Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Semiconductor fabs in Taiwan and South Korea absorb premium pricing for precision-grade protection, while contract manufacturers in Vietnam and Mexico prioritize cost minimization in standard electronics transit applications.
United States
Medical device OEMs in Minnesota and California drive demand for sterilization-compatible clamshells with gamma-stable conductive formulations. FDA device packaging standards tighten material selection criteria for sterile electronics kits. The Twin Cities corridor hosts concentrated surgical electronics manufacturing requiring validated lot traceability.
Germany
REACH Annex XVII phthalate restrictions eliminated PVC formulations from electronics export supply chains by 2025. Industrial converters in Bavaria and Baden-Württemberg accelerated migration to polypropylene alternatives with 18-24 month tooling amortization cycles. Stuttgart's automotive electronics cluster specifies thinner-wall dissipative designs for component transit protection.
China
Domestic semiconductor self-sufficiency programs under MIIT guidance expanded captive packaging demand for wafer protection. Yangtze River Delta fabs in Shanghai and Wuxi now qualify clamshell suppliers directly against internal cleanliness specifications. Shenzhen contract manufacturers absorb volume-driven replenishment for consumer electronics export assembly.
South Korea
Samsung and SK Hynix advanced packaging nodes below 3nm sustain consumption intensity for precision ESD protection during wafer shuttle operations. MFDS medical device standards create parallel demand for sterilization-compatible formats in Seoul's surgical electronics sector. Pyeongtaek's semiconductor corridor concentrates direct procurement relationships bypassing distribution intermediaries.
Vietnam
Samsung and Foxconn assembly relocation from China generated greenfield demand for localized ESD packaging supply. Electronics manufacturers in Bac Ninh and Hai Phong provinces specify recyclable polypropylene formulations for ESG disclosure compliance. Northern industrial zones absorb 15-25% premiums for verified carbon footprint materials under EU customer mandates.
ESD Clamshell Market Competitive Landscape
Specialized material formulators and precision thermoforming specialists split the market between performance-engineered and cost-optimized supply tiers. The vendor base clusters around three strategic archetypes: integrated polymer compounders with captive additive technology, precision molders serving semiconductor fabs with direct qualification pathways, and regional converters leveraging distribution scale for standard electronics applications. Dominant competitive moves include backward integration into conductive additive compounding and geographic expansion through greenfield molding capacity in Southeast Asian electronics corridors.
Among North American fabricators, Desco Industries anchors the distribution-controlled tier through industrial end-user channel relationships, while 3M exemplifies the R&D-intensive compounder archetype with conductive coating formulation capabilities. Protektive Pak occupies a position within the medical-specialist segment, representing multi-compartment design expertise for surgical kit applications. These three companies illustrate the strategic divergence between scale-driven distribution, technology-led material science, and vertical-focused application engineering that defines competitive positioning across the market.
| Leading Market Players |
|---|
| 3M |
| Desco Industries |
| Tektronix |
| Static Control Components |
| Conductive Containers |
| Elcom |
| Protektive Pak |
| Integrated Packaging Films |
| GWP Group |
| Others |
Supply & Pricing Matrix
Hsinchu and Pyeongtaek semiconductor corridors concentrate precision-grade clamshell production, granting qualified molders pricing leverage over fabs requiring sub-3nm wafer protection. This geographic clustering elevates premiums for captive metrology capabilities while compressing margins for distributors bypassed in direct procurement relationships.
Pricing Analysis
After-sales service contracts for clamshell collection, cleaning, and redeployment capture recurring revenue streams beyond virgin product sales. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade sterilization-compatible formulations from standard electronics transit protection and commodity consumer packaging. Cost compression in standard electronics tiers intensifies because contract manufacturers in Vietnam and Mexico prioritize unit cost minimization. OEM semiconductor fabs show least price sensitivity; retail display applications absorb greatest pricing pressure.
Supply Chain Analysis
Extended payment terms from semiconductor fabs strain working capital for mid-tier converters lacking supply-chain finance facilities. Taiwan, South Korea, and China concentrate precision thermoforming capacity for wafer-grade protection. Carbon nanotube additives, polypropylene resin, and conductive polymer masterbatches constitute critical input dependencies. Single-source vulnerability persists where over 60% of semiconductor-grade production clusters in two East Asian manufacturing corridors. Distribution runs through direct procurement relationships displacing channel intermediaries in advanced packaging supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ESD clamshell markets reward defensive positioning through regulatory entrenchment—REACH compliance and FDA sterilization validation create switching costs that lock qualified suppliers into multi-year procurement cycles.
For Market Incumbents: Entrench position through backward integration into conductive additive compounding and captive metrology capabilities that TSMC and Samsung specifications demand. Add molding capacity in Vietnam's Bac Ninh corridor to capture Foxconn and Samsung assembly relocation demand. Certification investment in gamma-stable formulations protects against emerging medical-specialist entrants from Germany and Switzerland. For New Entrants and Emerging Players: Build out closed-loop logistics platforms for clamshell refurbishment and redeployment, targeting the aftermarket service tier where virgin material sales face margin compression. Vietnam electronics manufacturing zones offer most penetrable geography given greenfield supply qualification requirements. Go-to-market angle should emphasize ESG-compliant recyclable formulations with verified carbon footprints for EU customer mandates. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision molders with direct fab qualification pathways over distribution-dependent regional converters. Long-term viability hinges on regulatory compliance capabilities expanding beyond REACH into FDA medical device standards. Acquisition target archetype: specialized converters with captive additive technology and Southeast Asian molding footprint. Signal to watch: accelerated direct procurement adoption by semiconductor fabs eliminating distributor intermediaries.| Strategic Initiative | Industry Significance |
|---|---|
| Conductive Additive Backward Integration | Captive carbon nanotube compounding secures formulation control against resin price volatility. |
| Vietnam Greenfield Molding Capacity | Localized supply qualification captures Samsung and Foxconn assembly relocation demand. |
| Gamma Sterilization Validation Investment | FDA-compliant pathways unlock 40-60% pricing premiums in surgical electronics kits. |
| Closed-Loop Logistics Platform Buildout | Reverse logistics services capture recurring revenue beyond virgin clamshell sales. |
| Direct Fab Procurement Relationship Development | TSMC and Samsung qualification bypasses distributor margin compression. |
Research Methodology
Cross-validation between primary fieldwork with semiconductor packaging engineers and secondary analysis of customs trade data anchors the qualitative findings. Conversations with thermoforming plant managers, ESD compliance auditors at fabs, medical device procurement leads, and conductive polymer R&D directors informed demand segmentation. Secondary sources included ECHA REACH registration databases, FDA 510(k) device packaging filings, and SEC disclosures from polymer compounders. Bottom-up clamshell consumption estimates triangulated against top-down electronics production forecasts.
Calibration against historical price elasticity patterns and capacity utilization rates across Taiwan and South Korea manufacturing corridors shaped the projection framework. Segmentation dimensions modeled include product architecture, material chemistry grade, application sterilization burden, and end-user procurement sophistication. CAGRs derived from elasticity-adjusted volume projections and value-per-unit trends. Industry-specific inputs encompassed semiconductor node advancement timelines and EU Green Deal packaging mandate implementation trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed polymer compounders would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Packaging Market
Electrostatic Discharge (ESD) Packaging
ESD Tray Market
Electrostatic Discharge (ESD) Packaging
India Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
ESD Safe Matting Market
Electrostatic Discharge (ESD) Packaging
ESD Workstations Market
Electrostatic Discharge (ESD) Packaging
Saudi Arabia Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Packaging Market
Electrostatic Discharge (ESD) Packaging
ESD Totes Market
Electrostatic Discharge (ESD) Packaging
ESD Foldable Container Market
Electrostatic Discharge (ESD) Packaging
Shielding Bags Market
Electrostatic Discharge (ESD) Packaging
South Korea Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Metallic Static Shielding Bags Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Flooring Market
Electrostatic Discharge (ESD) Packaging
UAE Electrostatic Discharge (ESD) Films Market