
 ESD Foldable Container Market | 2026-2036
ESD Foldable Container Market Size, Share, and Industry Trends Forecast 2026-2036
ESD Foldable Container Market Foresight
Polypropylene with carbon-black loading is recalibrating cost structures across standard and heavy-duty container lines. Schoeller Allibert leverages integrated European molding networks to sustain volume leadership in conductive logistics. ORBIS Corporation anchors North American automotive programs through captive resin compounding and regional plant density. Bekuplast GmbH differentiates via precision-fit custom containers for German pharmaceutical cleanrooms.
An ESD foldable container is a collapsible, electrically conductive storage unit engineered to dissipate static charges between 10^3 and 10^9 ohms surface resistance, typically injection-molded from carbon-filled polymers to protect sensitive components during transit and warehousing. Standard containers command the broadest volume base across electronics assembly floors, while custom containers capture concentrated margin pools in aerospace kitting operations where dimensional tolerances tighten. Polypropylene dominates material throughput due to recyclability and fatigue resistance, though conductive plastics formulations are gaining specification in pharmaceutical cold-chain applications where both static control and chemical inertness matter.
FDA cGMP guidelines for pharmaceutical packaging integrity and the EPA's emerging per- and polyfluoroalkyl substances restrictions are elevating material traceability requirements across US end-use sectors. The EU REACH regulation and CE marking directives compel European manufacturers to document conductive additive chemistries and recyclate content ratios. Stakeholders must monitor evolving substance restrictions and decide whether to regionalize compound formulations or pursue unified global material platforms.
Market Dynamics
Semiconductor fabs in Taiwan and South Korea are driving procurement intensity for electrostatic-dissipative logistics assets, while EU REACH regulations on persistent organic pollutants compress material formulation options. This tension between demand concentration and supply-side chemical compliance is restructuring competitive positioning.
Growth Catalysts
- EU REACH Regulation:Tightening specifications for conductive plastics are forcing manufacturers to document additive chemistries and recyclate content, creating specification barriers that favor established compounders with testing infrastructure.
- Taiwan Semiconductor Fabrication:Expanding wafer foundries are scaling procurement of ESD-rated foldable containers for cleanroom component transport, pulling volume through specialized distributors.
- Carbon-Black Polypropylene:Improved fatigue resistance and recyclability are displacing legacy conductive ABS in standard container lines, opening specification windows for injection molders with compounding partnerships.
Market Restraints
- Petroleum-Derived Feedstock Volatility:Polypropylene resin costs fluctuate with naphtha cracking margins, compressing gross margins for container producers without long-term supply agreements.
- Carbon Black Supply Concentration:Three suppliers control furnace black production for conductive grades, creating input bottlenecks when specialty rubber demand spikes.
- Conductive Coating Substitution:Spray-applied static-dissipative films on standard containers threaten unit economics in low-cycle-count applications.
Strategic Opportunities
- Indian Electronics Manufacturing:PLI scheme incentives for semiconductor and mobile device assembly are creating first-mover windows for ESD logistics providers establishing local molding partnerships.
- Pharmaceutical Cold-Chain Convergence:Dual requirements for static control and chemical inertness in biologics distribution are opening specification opportunities for conductive plastic formulations with enhanced barrier properties.
- Closed-Loop Rental Models:Pooling systems for foldable containers are displacing single-use corrugated in automotive tier-one supplier networks, shifting revenue from unit sales to per-trip fees.
Industry Challenges
- Surface Resistance Calibration:Maintaining 10^3 to 10^9 ohm consistency across temperature and humidity ranges requires specialized metrology capabilities that smaller molders lack.
- Multi-Site Certification Burden:FDA cGMP and CE marking documentation must be replicated across regional production facilities, extending compliance timelines for expansion programs.
- Legacy ERP Integration:RFID-enabled smart containers face interoperability friction with incumbent warehouse management systems at mid-tier electronics distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ESD Foldable Container Market |
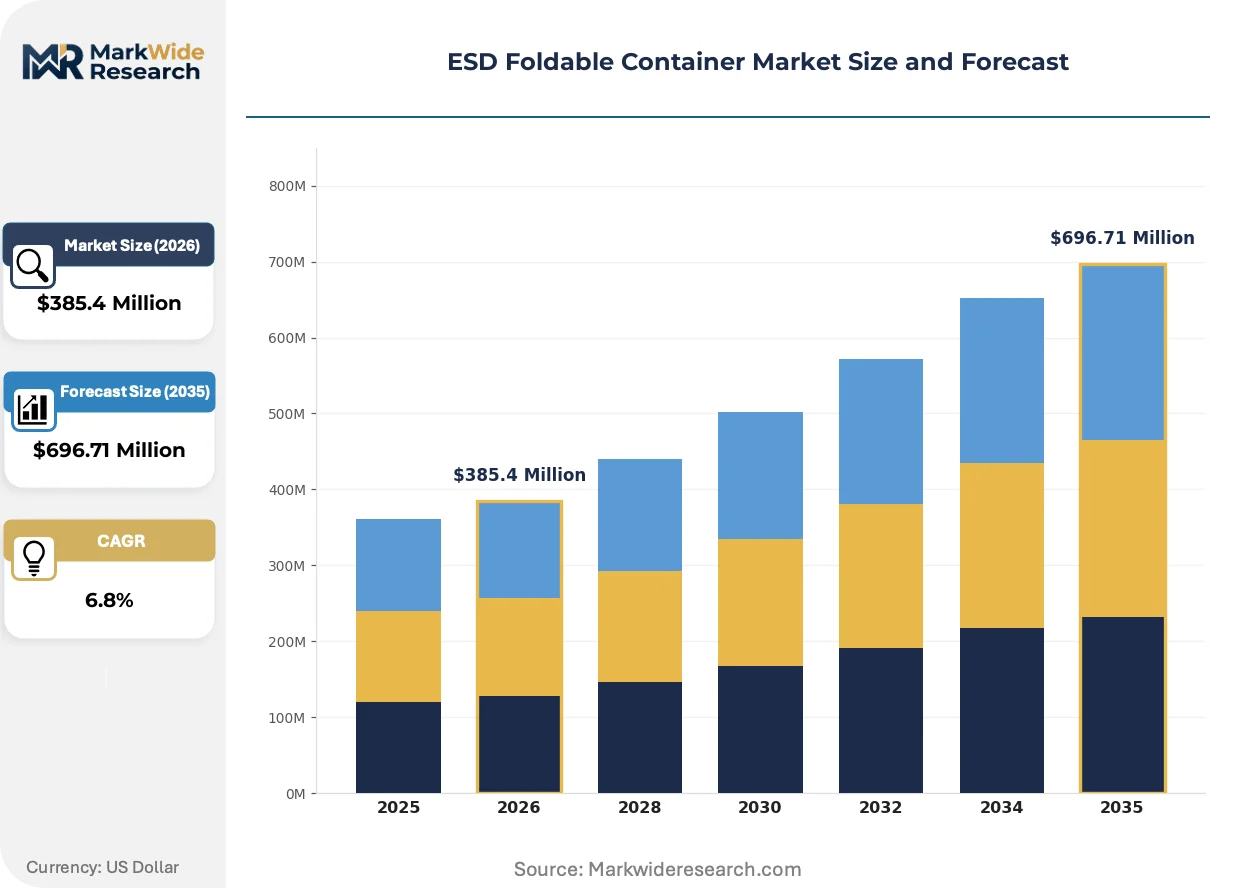
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Containers, Custom Containers, Stackable Containers, Heavy-Duty Containers Material: Polypropylene, Polyethylene, Conductive Plastics, Reinforced Fabrics End User: Electronics, Automotive, Aerospace, Pharmaceuticals Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Schoeller Allibert, SSI Schaefer, ORBIS Corporation, Bekuplast GmbH, Loadhog Limited, RPP Containers, Quantum Storage Systems, Flexcon Container, AUER Packaging GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ESD Foldable Container Market Shifts & Advancements
Material science advances and regulatory documentation requirements are compressing product development cycles while expanding the addressable application set beyond traditional electronics assembly.
Multi-wall carbon nanotube masterbatches are electrifying conductive polymer formulations by enabling lower loadings than carbon black while preserving mechanical properties. Medical device manufacturers are piloting these compounds for surgical kitting containers where both static control and sterilization compatibility matter. The technology is electrifying margin structures by reducing per-unit material costs and extending container service life.
REACH Annex XVII restrictions on perfluorinated compounds are forcing reformulation of anti-static additives previously reliant on fluorinated surfactants. Compounders must validate alternative ionic conductive polymers through extended migration testing. Pharmaceutical cold-chain applications face the steepest compliance burden, with EMA guidance pushing toward documented additive safety profiles.
Consolidated procurement desks at automotive OEMs are compressing supplier rosters and demanding integrated fleet management services rather than discrete container sales. Tier-one electronics distributors are responding with vendor-managed inventory arrangements that shift ownership risk upstream. South Korean battery manufacturers exemplify this pattern, negotiating multi-year container pooling contracts with performance-based pricing tied to damage rates.
ESD Foldable Container Market Segmentation
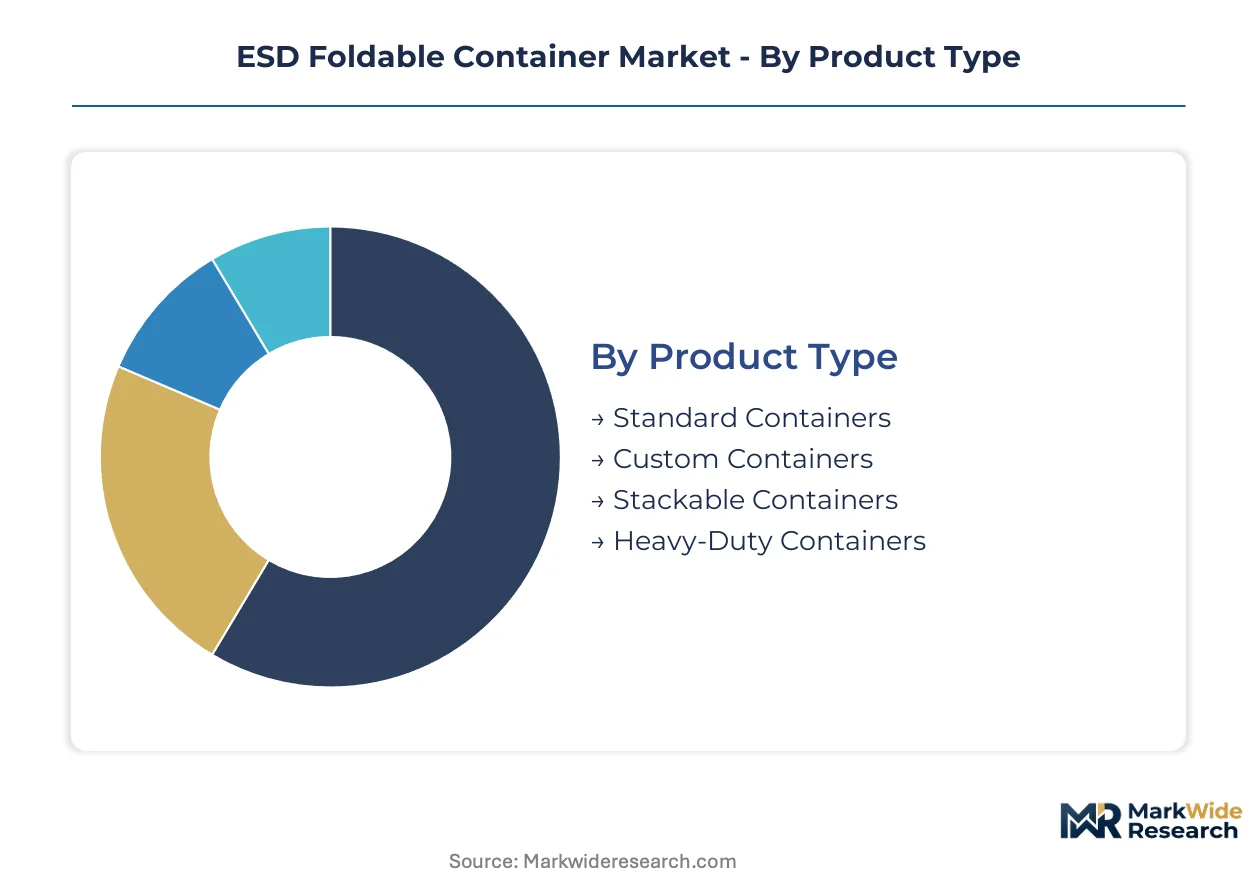
ESD foldable container procurement decisions pivot on surface resistance specifications, load-cycle durability, and cleanroom compatibility. Manufacturers must align product portfolios across four distinct segmentation axes to capture volume in electronics assembly while penetrating premium aerospace and pharmaceutical applications.
Product Type:
Buyers select container configurations based on handling frequency, dimensional constraints, and total cost of ownership across rental versus purchase models.
- Standard Containers:Injection-molded polypropylene units with carbon-black loading dominate high-volume electronics assembly floors in Taiwan and South Korea. Semiconductor fabs specify these for wafer transport trays where 10^4 to 10^6 ohm surface resistance prevents electrostatic discharge damage.
- Custom Containers:Precision-engineered dimensions and modified stacking interfaces command premium positioning in aerospace kitting operations. Boeing and Airbus tier-one suppliers require tolerances within ±0.5mm for automated retrieval systems, tightening vendor qualification requirements.
- Stackable Containers:Interlocking foot-and-lid designs maximize cubic efficiency in warehouse racking systems. Automotive tier-one suppliers in Germany favor these for just-in-sequence component delivery.
- Heavy-Duty Containers:Reinforced wall sections and metal hinge inserts accommodate loads exceeding 50kg in industrial distribution networks.
Volume sits with Standard Containers; growth tilts toward Custom Containers.
Material:
Compound selection determines recyclability credentials, chemical resistance, and compliance with evolving substance restrictions under REACH and FDA guidelines.
- Polypropylene:Carbon-filled grades offer fatigue resistance across 500+ collapse cycles and compatibility with existing recycling streams. Taiwanese electronics manufacturers specify this material for closed-loop pooling programs.
- Conductive Plastics:Multi-wall carbon nanotube masterbatches enable lower additive loadings than carbon black while preserving mechanical properties. Medical device manufacturers pilot these compounds for surgical kitting containers requiring sterilization compatibility.
- Polyethylene:Lower stiffness than polypropylene limits application to short-cycle logistics where cost minimization dominates.
- Reinforced Fabrics:Collapsible textile-based units serve field service operations where weight reduction outweighs durability requirements.
Polypropylene captures current volume; Conductive Plastics are climbing the fastest as pharmaceutical specifications tighten.
End User:
Industry-specific certification requirements and damage-cost economics drive specification divergence across customer segments.
- Electronics:Semiconductor fabs and contract manufacturers generate baseline demand for ESD-rated logistics across wafer, PCB, and finished device handling.
- Pharmaceuticals:Biologics distribution demands dual compliance with static control and FDA cGMP packaging integrity guidelines. Cold-chain applications favor conductive plastics with enhanced moisture barrier properties.
- Automotive:Battery cell manufacturers negotiate multi-year pooling contracts with performance-based pricing tied to damage rates.
- Aerospace:Precision kitting for MRO operations commands longest product development cycles and highest margin structures.
Electronics anchors installed base; Pharmaceuticals shows steepest expansion trajectory.
Distribution Channel:
Channel selection reflects customer scale, technical support requirements, and integration complexity with incumbent warehouse management systems.
- Direct Sales:Container manufacturers maintain dedicated account teams for automotive OEMs and semiconductor fabs requiring vendor-managed inventory arrangements.
- Distributors:Specialized industrial logistics distributors serve mid-tier electronics manufacturers with technical specification support and local stocking.
- Wholesale:Volume resellers move standard container lines to smaller contract manufacturers with limited technical procurement resources.
- Online Retail:Digital channels capture replacement volume and small-quantity orders from maintenance and repair operations.
Direct Sales commands largest transaction values; Distributors are gaining share fastest among expanding regional electronics clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in East Asian electronics manufacturing corridors where semiconductor fabs and contract manufacturers drive procurement intensity for electrostatic-dissipative logistics assets.
Taiwan
Wafer foundries in Hsinchu and Tainan Science Parks are scaling ESD container fleets for cleanroom component transport. The National Development Council's industrial park incentives support logistics infrastructure upgrades. Taichung's precision machinery cluster is integrating conductive container pooling into automated material handling systems.
South Korea
Battery cell manufacturers in Gyeonggi Province negotiate multi-year container contracts with damage-rate pricing structures. MFDS pharmaceutical packaging guidelines are elevating material traceability requirements for biologics distribution. Busan's port logistics hub is adopting RFID-enabled smart containers for semiconductor export consolidation.
Germany
Automotive tier-one suppliers in Baden-Württemberg favor stackable containers for just-in-sequence component delivery. EU REACH Annex XVII restrictions on perfluorinated compounds are forcing conductive additive reformulations. Bavaria's pharmaceutical cleanrooms specify precision-fit custom containers with documented additive safety profiles.
United States
FDA cGMP guidelines for pharmaceutical packaging integrity are elevating certification burdens across biologics distribution networks. EPA emerging restrictions on per- and polyfluoroalkyl substances compress material formulation options. Michigan's automotive battery manufacturing corridor is adopting closed-loop rental models for foldable container fleets.
India
PLI scheme incentives for semiconductor and mobile device assembly are creating first-mover windows for ESD logistics providers. BIS standards for electrostatic control materials are tightening import specifications. Karnataka's Electronics City and Tamil Nadu's Sriperumbudur cluster are establishing local molding partnerships for conductive container production.
ESD Foldable Container Market Competitive Landscape
Capacity expansion dominates the current landscape as established compounders build testing infrastructure to meet REACH documentation requirements. The vendor base organizes around three tiers: integrated European molding networks, North American automotive-focused producers, and precision specialists serving pharmaceutical cleanrooms. Strategic archetypes include volume leaders with captive resin compounding, regional champions leveraging plant density, and custom engineering shops capturing aerospace margins. M&A activity and geographic expansion represent the dominant competitive moves as players seek additive chemistry expertise and regional production footprints.
Among European-integrated specialists, Schoeller Allibert and Bekuplast GmbH exemplify archetypes built on molding network density and precision engineering respectively. ORBIS Corporation anchors the North American tier with automotive program focus. These three occupy positions across the volume-premium spectrum without overlapping segment concentration.
| Leading Market Players |
|---|
| Schoeller Allibert |
| SSI Schaefer |
| ORBIS Corporation |
| Bekuplast GmbH |
| Loadhog Limited |
| RPP Containers |
| Quantum Storage Systems |
| Flexcon Container |
| AUER Packaging GmbH |
| Others |
Supply & Pricing Matrix
Carbon-black masterbatch costs transmit directly from three concentrated furnace-black suppliers through to container manufacturers, then bifurcate into contract-based long-term offtake pricing for automotive OEMs and transactional per-unit sales for mid-tier electronics distributors. This input-cost pathway forces molders without captive compounding partnerships into margin compression when specialty rubber demand spikes, while integrated compounders sustain pricing power through additive chemistry documentation that satisfies EU REACH Annex XVII requirements.
Pricing Analysis
Volume concentrates in standard polypropylene containers for semiconductor fabs, while margin pools accrue to custom-engineered units for aerospace kitting where ±0.5mm tolerances command premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates FDA cGMP-certified pharmaceutical containers from general electronics-grade units and undifferentiated wholesale lines. Cost compression in the standard tier is intensifying because carbon-black supply concentration limits formulation flexibility. Mid-tier electronics contract manufacturers exhibit highest price sensitivity, while pharmaceutical cleanroom operators prioritize documented additive safety profiles over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from automotive OEMs and semiconductor fabs force container manufacturers to qualify secondary compounders in Germany and Taiwan alongside primary suppliers in South Korea. Raw material flows draw from petroleum-derived polypropylene resin, furnace-grade carbon black, and multi-wall carbon nanotube masterbatches. Single-source vulnerability concentrates in carbon black feedstock when rubber tire demand surges. Distribution runs through specialized industrial logistics distributors with local stocking capabilities for mid-tier electronics clusters, while direct sales teams manage vendor-managed inventory for multinational OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon-black supply concentration creates a supply-constrained market structure where qualified additive compounders prop pricing power through REACH documentation barriers that smaller molders cannot replicate.
For Market Incumbents: To counter spray-applied static-dissipative film substitution in low-cycle-count applications, Schoeller Allibert and ORBIS Corporation should deepen backward integration into captive resin compounding and expand testing infrastructure for multi-site FDA cGMP certification. Capacity addition in India's Karnataka and Tamil Nadu clusters captures PLI scheme procurement windows before local molding partnerships mature. For New Entrants and Emerging Players: The price-point gap between aerospace custom containers and standard electronics units offers entry space for precision-engineered mid-tier products serving pharmaceutical cold-chain convergence. India's semiconductor assembly corridors represent the most penetrable geography, with BIS standards tightening import specifications and favoring local production partnerships. A go-to-market angle anchored in RFID-enabled smart container integration with warehouse management systems addresses legacy ERP interoperability friction at mid-tier distributors. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision custom engineering shops in Germany with documented REACH additive chemistries and established aerospace supplier qualifications. Long-term viability across a 5-10 year window rests on additive chemistry expertise migration from carbon black to multi-wall carbon nanotube formulations. The signal to watch is EMA guidance migration toward mandatory additive safety profile documentation for pharmaceutical applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive carbon-black formulation control insulates margin from petroleum feedstock volatility and supply bottlenecks. |
| Multi-Site FDA cGMP Certification | Documented quality systems unlock pharmaceutical biologics distribution with performance-based pricing structures. |
| RFID-Enabled Smart Container Development | Sensor integration addresses warehouse management system interoperability gaps at mid-tier electronics distributors. |
| Local Molding Partnerships in India | PLI scheme incentives for semiconductor assembly create first-mover procurement advantages before BIS standards fully tighten. |
| Carbon Nanotube Masterbatch Transition | Lower additive loadings preserve mechanical properties while reducing per-unit material costs and extending service life. |
Research Methodology
Multi-period observation of carbon-black pricing volatility, REACH regulatory amendment timelines, and semiconductor fab capital expenditure cycles anchored the trend analysis, supplemented by interviews with container manufacturing plant managers, procurement leads at Taiwanese wafer foundries, pharmaceutical packaging compliance officers, and automotive tier-one supplier logistics directors. Secondary validation drew from ECHA REACH registration databases, FDA cGMP guidance documents, SEC 10-K filings from listed compounders, and customs trade data for conductive polymer resin flows. Bottom-up container shipment estimates and top-down electronics manufacturing value-chain sizing were triangulated to constrain forecast ranges.
Segment-weighting across the analysis window applied differential growth assumptions to standard versus custom container lines, polypropylene versus conductive plastics material categories, and direct sales versus distributor channel structures. Modeled dimensions included product type, material formulation, end-use industry vertical, and geographic production cluster. CAGRs were derived from regression against semiconductor fab equipment spending and pharmaceutical cold-chain infrastructure investment indicators. Forecast inputs incorporated EU REACH Annex XVII substance restriction implementation schedules and MFDS pharmaceutical packaging guideline evolution.
Inputs from ECHA registration databases and FDA guidance documents were available through the study window; gaps in real-time carbon-black spot pricing and confidential aerospace supplier contract terms introduce uncertainty bands around margin projections. Deviation in EU perfluorinated compound restriction timelines or Taiwan semiconductor fab construction delays would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrostatic Discharge (ESD) Packaging
India Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
ESD Safe Matting Market
Electrostatic Discharge (ESD) Packaging
ESD Totes Market
Electrostatic Discharge (ESD) Packaging
South Korea Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Packaging Market
Electrostatic Discharge (ESD) Packaging
ESD Workstations Market
Electrostatic Discharge (ESD) Packaging
UAE Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
ESD Tray Market
Electrostatic Discharge (ESD) Packaging
Shielding Bags Market
Electrostatic Discharge (ESD) Packaging
Metallic Static Shielding Bags Market
Electrostatic Discharge (ESD) Packaging
ESD Clamshell Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Packaging Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Flooring Market
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
Saudi Arabia Electrostatic Discharge (ESD) Films Market