
 ESD Safe Matting Market | 2026-2036
ESD Safe Matting Market Size, Share, and Industry Trends Forecast 2026-2036
ESD Safe Matting Market Foresight
China's expanding electronics manufacturing footprint is reshaping regional supply dynamics for static-control flooring. Desco Industries leverages integrated material compounding to sustain North American channel dominance. SCS anchors its position through deep distributor relationships across precision assembly sectors. 3M competes on multi-layer polymer formulations that extend performance life in high-wear environments.
ESD safe matting consists of electrically conductive or dissipative polymer layers, typically vinyl or rubber compounds with carbon-loaded matrices, engineered to ground electrostatic charges below damage thresholds for sensitive components. The product primarily protects semiconductors, printed circuit boards, and aerospace avionics from catastrophic electrostatic discharge during assembly, testing, and handling operations. Vinyl mats dominate volume shipments due to cost-efficient calendering processes and broad chemical resistance, while rubber mats command premium positioning in heavy-duty aerospace and telecommunications maintenance bays where abrasion tolerance determines replacement cycles. Interlocking installation formats represent the fastest-growing configuration as modular cleanroom layouts gain traction over permanent adhesive bonding.
IEC 61340-5-1 governs material resistance parameters and grounding verification protocols across European and Asian procurement specifications, directly filtering supplier qualification rosters. OSHA workplace safety directives in the United States mandate static-control measures in flammable-material handling zones, embedding matting into operational compliance budgets. China's GB standards for electronics manufacturing enforce surface resistivity testing, creating a dual-certification burden for export-oriented producers. Stakeholders must monitor evolving regional test methodologies and polymer sustainability mandates as qualification criteria diverge.
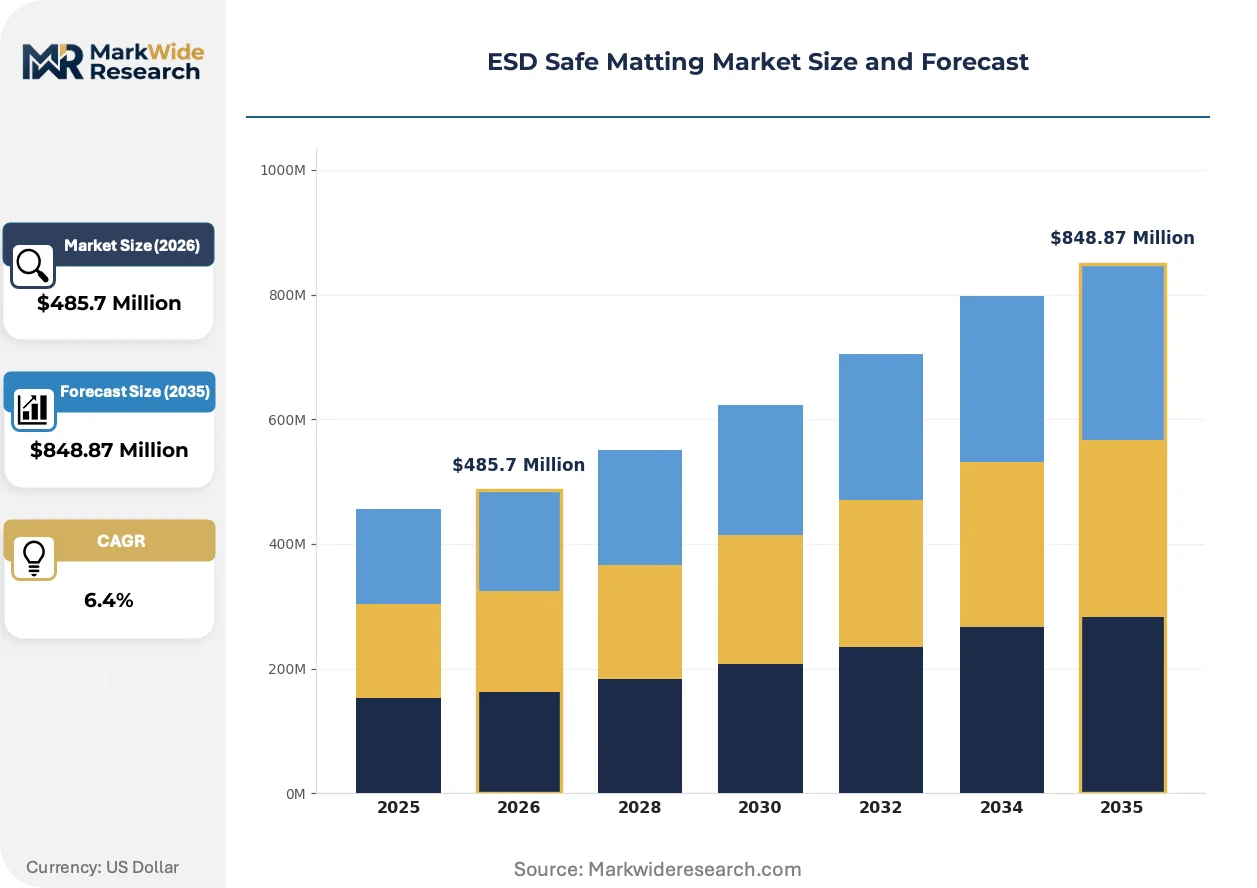
Market Dynamics
Modular cleanroom architectures are fragmenting procurement patterns for static-control flooring, pulling volume away from permanent adhesive installations toward reconfigurable interlocking systems that accommodate rapid production line rebalancing.
Growth Catalysts
- Semiconductor fabrication expansion:Taiwan and South Korea are commissioning new wafer fabs that specify dissipative vinyl matting for gowning areas and tool staging zones, tightening supplier qualification timelines.
- IEC 61340-5-1 harmonization:European and Asian procurement offices are converging on unified surface resistivity testing protocols, reducing dual-certification burdens for cross-border mat suppliers.
- Carbon-loaded rubber compounding:Aerospace maintenance bays in Germany and Japan are specifying abrasion-tolerant rubber matrices for telecommunications equipment servicing, extending replacement cycles beyond vinyl alternatives.
Market Restraints
- Petrochemical feedstock volatility:Vinyl mat production depends on PVC resin and plasticizer pricing tied to naphtha cracking economics, compressing margin buffers for calendering specialists.
- East Asian supply concentration:Carbon black and conductive polymer additive production clusters in eastern China, exposing Western converters to shipping cost spikes and customs processing delays.
- RoHS substance restrictions:European ECHA scrutiny of legacy phthalate plasticizers is forcing reformulation cycles that disrupt established supply relationships and qualification dossiers.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for mobile phone and component assembly are creating first-mover openings for ESD flooring installers in Tamil Nadu and Karnataka greenfield facilities.
- Biodegradable polymer matrices:Bio-based polyurethane alternatives to petroleum-derived vinyl are attracting sustainability-mandated buyers in Nordic electronics assembly operations.
- Direct-to-facility digital channels:Specialized industrial distributors are launching configuration tools that bypass traditional electrical supply houses, capturing specification authority earlier in cleanroom design workflows.
Industry Challenges
- Grounding verification technician scarcity:Facilities maintenance teams lack personnel trained in IEC 61340-5-1 resistance testing protocols, delaying commissioning and inflating third-party inspection costs.
- Multi-standard certification complexity:Suppliers must simultaneously maintain GB standard compliance for Chinese domestic sales, OSHA documentation for US exports, and CE marking for European shipments, fragmenting quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ESD Safe Matting Market |
| Market Size in 2026 | $485.7 Million |
| Market Size in 2035 | $848.87 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl Mats, Rubber Mats, Carpet Mats, Foam Mats Application: Electronics Manufacturing, Aerospace, Laboratories, Telecommunications Installation: Adhesive, Loose Lay, Custom Fit, Interlocking Thickness: 1mm, 2mm, 3mm, 5mm |
| Companies Covered | Desco Industries, SCS, ACL Staticide Inc., RS Pro, Bertech, COBA Europe, Transforming Technologies LLC, Botron Company Inc., 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ESD Safe Matting Market Shifts & Advancements
Material science advances and procurement digitization are compressing specification cycles for static-control flooring, while regulatory convergence is collapsing the number of qualified supplier pools across major electronics manufacturing corridors.
Copper-nanowire embedded polymer substrates are achieving volume conductivity at loadings below carbon-black thresholds, enabling thinner calendered profiles without sacrificing charge dissipation rates. Advanced packaging facilities in Taiwan are piloting these substrates for wafer-level chiplet assembly zones. The technology is rendering obsolete thick-section vinyl mats that previously dominated cost-sensitive PCB assembly floors.
REACH substance restrictions are accelerating substitution of ortho-phthalate plasticizers in European-bound vinyl mat production, with converters reformulating around terephthalate and bio-based alternatives to maintain market access. German automotive electronics suppliers are demanding full material disclosure documentation upstream of mat procurement decisions. The regulatory pressure is compressing supplier qualification timelines and favoring compounders with in-house polymer science capabilities.
Facility managers are unbundling mat replacement cycles from comprehensive MRO contracts, negotiating direct relationships with specialized ESD flooring vendors for scheduled refresh programs. Electronics contract manufacturers in China's Pearl River Delta are adopting usage-based refresh models tied to contamination monitoring rather than fixed calendar intervals. The purchasing pattern shift is disintermediating general industrial distributors and concentrating volume with technical specialists who bundle installation and testing services.
ESD Safe Matting Market Segmentation
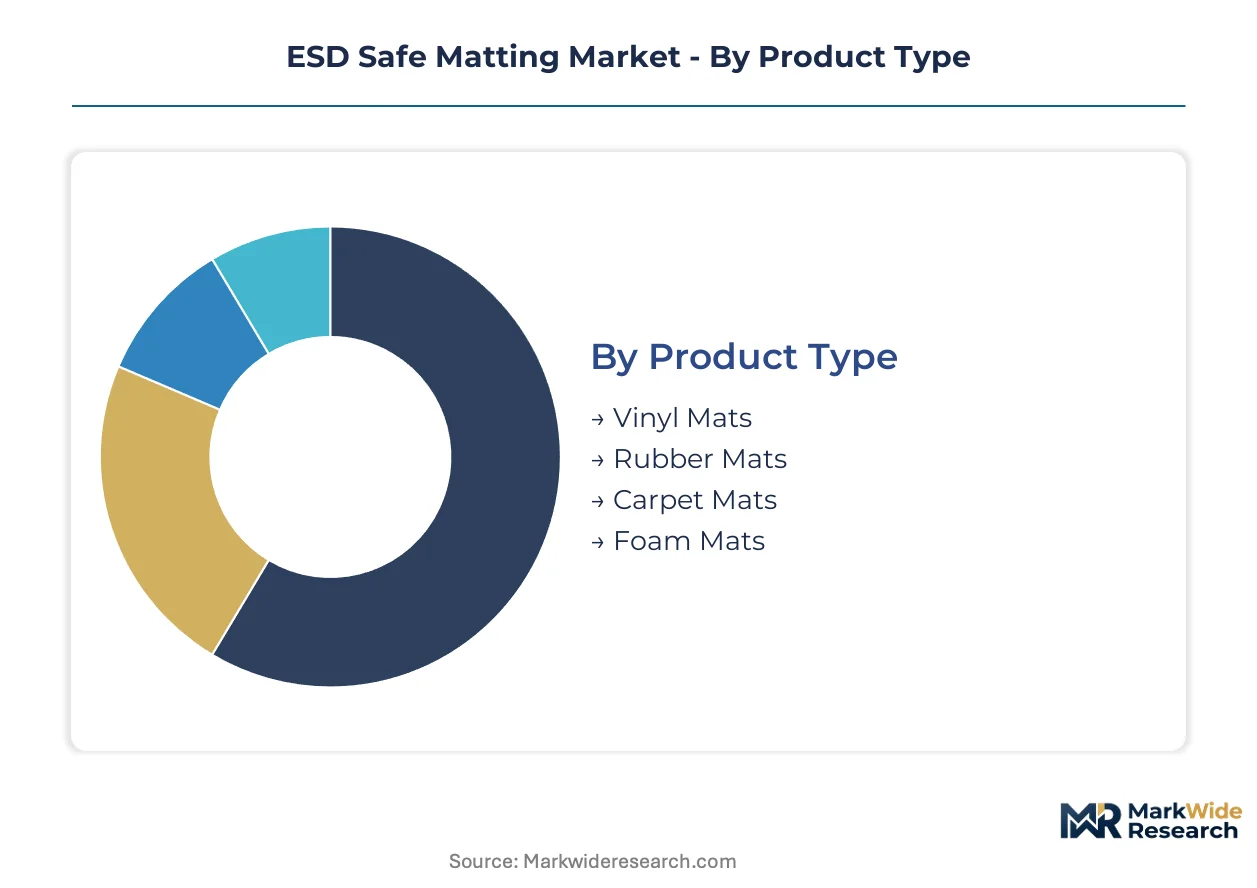
ESD safe matting procurement diverges sharply across material chemistry, installation permanence, and operational environment. Semiconductor fabs, aerospace hangars, and electronics contract manufacturers each impose distinct performance thresholds that reshape supplier qualification criteria and replacement economics.
Product Type:
Material selection spans cost-efficient vinyl formulations through aerospace-grade rubber compounds, with each chemistry carrying specific conductivity profiles and mechanical durability trade-offs.
- Vinyl Mats:Calendered PVC layers loaded with carbon black achieve surface resistivity between 10^6 and 10^9 ohms. Taiwan's wafer fabs specify these for gowning zones and tool staging areas where chemical resistance and cost efficiency outweigh abrasion tolerance. Naphtha-derived feedstock volatility compresses margin buffers for dedicated vinyl compounders.
- Rubber Mats:Nitrile or EPDM matrices with embedded conductive fillers withstand forklift traffic and petroleum exposure in German aerospace maintenance bays. Replacement cycles extend three to four times beyond vinyl alternatives, justifying premium positioning for telecommunications infrastructure servicing.
- Carpet Mats:Tufted conductive fibers bonded to dissipative backing serve administrative cleanroom corridors where comfort underfoot and static control must coexist.
- Foam Mats:Closed-cell polyurethane structures cushion standing assembly workers in high-volume PCB soldering operations across China's Pearl River Delta.
The dominant share belongs to Vinyl Mats, while Rubber Mats is closing the gap fastest.
Application:
End-use environments impose divergent certification burdens and performance lifespans, fragmenting supplier portfolios across precision assembly sectors.
- Electronics Manufacturing:Surface-mount assembly lines in South Korea and China's eastern corridor specify dissipative flooring for EPA zones where component damage thresholds sit below 100 volts. IEC 61340-5-1 compliance filters procurement rosters aggressively.
- Aerospace:MRO facilities in Germany and Japan demand abrasion-tolerant rubber systems for avionics bench testing where jet fuel exposure and heavy tooling coexist.
- Laboratories:Analytical instrument suites in Nordic pharmaceutical operations prioritize chemical spill resistance alongside static dissipation.
- Telecommunications:Central equipment rooms in India's expanding 5G infrastructure specify interlocking formats for rapid reconfiguration during hardware refresh cycles.
Electronics Manufacturing commands volume leadership, though Aerospace generates the highest per-square-meter procurement values.
Installation:
Permanence preferences are shifting as production line rebalancing accelerates, pulling procurement away from bonded systems toward modular alternatives.
- Adhesive:Permanent epoxy bonding dominates legacy semiconductor cleanrooms where contamination control protocols resist substrate movement.
- Loose Lay:Unbonded rolls enable rapid deployment in temporary assembly pop-ups and contract manufacturer overflow facilities.
- Custom Fit:CNC-cut profiles accommodate irregular equipment footprints in precision metrology suites.
- Interlocking:Puzzle-edge vinyl tiles support modular cleanroom architectures in Taiwan and South Korea where fab reconfiguration cycles compress below 18 months.
Interlocking formats are expanding most quickly, while Adhesive retains installed base dominance in legacy facilities.
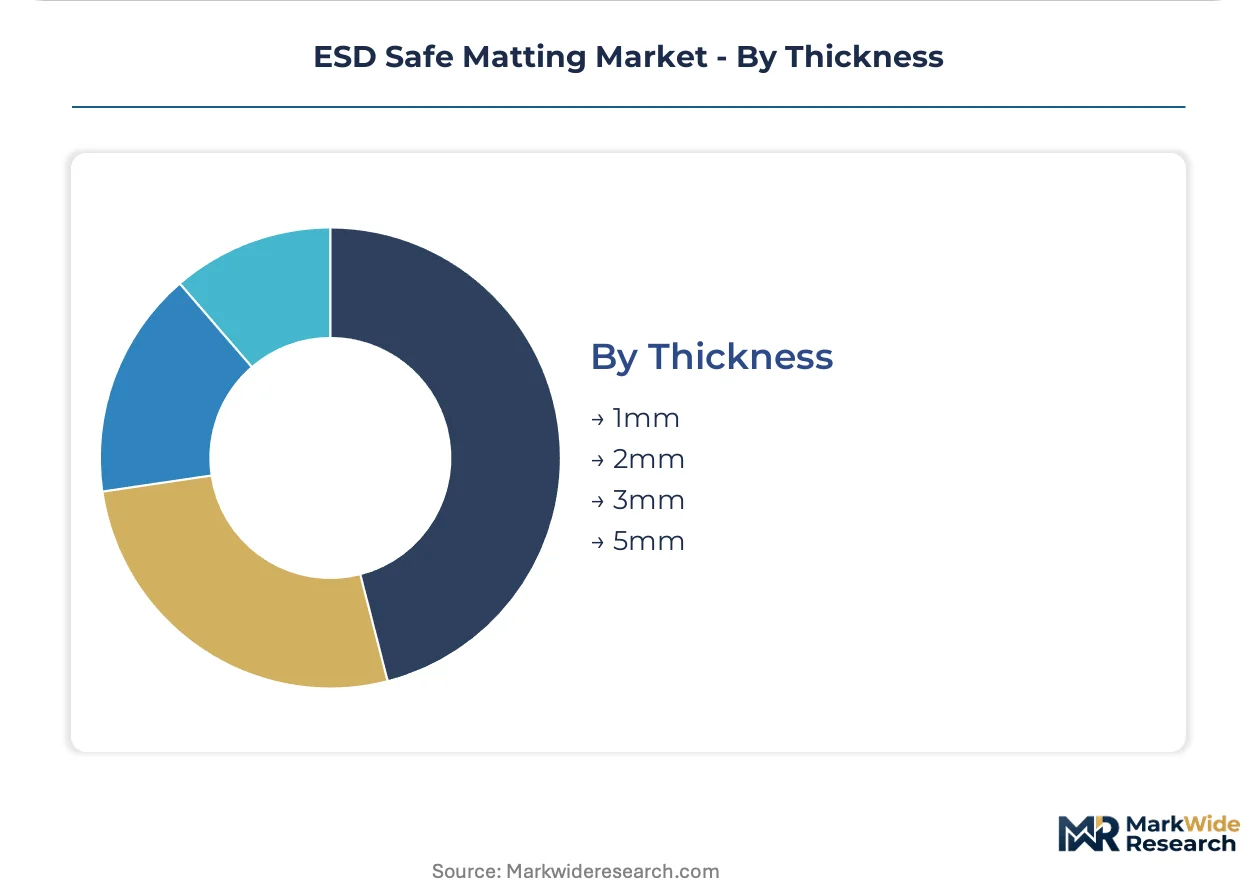
Thickness:
Profile depth correlates directly with mechanical load tolerance and conductivity pathway length, creating specification tiers across duty cycles.
- 1mm:Ultra-thin calendered sheets serve light-traffic inspection stations where space constraints override durability requirements.
- 2mm:Standard-duty profiles balance cost and performance for electronics assembly benches across China's manufacturing corridor.
- 3mm:Intermediate thickness dominates volume shipments for general-purpose EPA flooring in contract manufacturing environments.
- 5mm:Heavy-section rubber systems absorb impact in German aerospace hangars where dropped tooling threatens substrate integrity.
The 2mm and 3mm specifications together anchor procurement volume, with 5mm profiles gaining traction in heavy-duty maintenance applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mat consumption patterns diverge sharply by geography. Taiwan and South Korea deploy dissipative vinyl for semiconductor gowning zones. Germany and Japan specify abrasion-tolerant rubber for aerospace MRO. China's eastern corridor balances cost-driven vinyl with modular interlocking formats for rapid line reconfiguration.
China
Electronics contract manufacturers in the Pearl River Delta and Yangtze River Delta anchor volume demand for 2mm and 3mm vinyl matting. GB standards for surface resistivity testing enforce dual-certification burdens on export-oriented producers. Shenzhen and Suzhou assembly clusters are adopting usage-based refresh models tied to contamination monitoring rather than fixed replacement intervals.
Taiwan
New wafer fab commissioning by TSMC and competitors is tightening supplier qualification timelines for gowning area matting. IEC 61340-5-1 compliance filters procurement rosters aggressively for EPA zone flooring. Hsinchu Science Park and Tainan technology corridors specify dissipative vinyl for tool staging zones with compressed 18-month reconfiguration cycles.
South Korea
Memory and logic semiconductor expansion by Samsung and SK Hynix is driving specification authority toward modular interlocking formats. MFDS-aligned workplace safety protocols embed static-control measures into operational compliance budgets. Pyeongtaek and Yongin fab clusters are piloting copper-nanowire embedded substrates for advanced packaging zones.
Germany
Aerospace MRO facilities in Hamburg and Bavaria command premium positioning for nitrile rubber systems with extended replacement cycles. ECHA scrutiny of ortho-phthalate plasticizers is forcing REACH-compliant reformulation for European-bound vinyl production. Stuttgart and Munich automotive electronics suppliers now demand full material disclosure documentation upstream of procurement decisions.
United States
OSHA workplace safety directives mandate static-control measures in flammable-material handling zones across electronics assembly operations. Desco Industries leverages integrated material compounding to sustain channel dominance in North American distribution. California and Texas precision assembly clusters are unbundling mat replacement cycles from comprehensive MRO contracts toward direct vendor relationships.
ESD Safe Matting Market Competitive Landscape
Capability concentration sits with compounders possessing in-house polymer science expertise; scale advantage sits with distributors commanding electrical supply house relationships. The vendor base stratifies across three tiers: integrated material compounders, specialized flooring distributors, and diversified industrial conglomerates. Dominant competitive moves include strategic partnerships with cleanroom design firms and geographic expansion through certified installer networks.
Among North American specialists, Desco Industries exemplifies the integrated compounder archetype through captive control of carbon-loaded matrix production. SCS and 3M occupy positions at opposite ends of the spectrum—SCS anchoring distributor-centric relationship models across precision assembly sectors, 3M representing diversified industrial technology platforms that compete on multi-layer polymer formulations. These three entities collectively illustrate the competitive tension between material science depth and channel scale in static-control flooring procurement.
| Leading Market Players |
|---|
| Desco Industries |
| SCS |
| ACL Staticide Inc. |
| RS Pro |
| Bertech |
| COBA Europe |
| Transforming Technologies LLC |
| Botron Company Inc. |
| 3M |
| Others |
Supply & Pricing Matrix
Carbon black and conductive polymer additive production clusters in eastern China concentrate upstream supply power with compounders possessing captive feedstock access, compressing margin buffers for Western converters dependent on spot resin markets. Vinyl mat pricing stratifies across aerospace-grade rubber formulations, IEC 61340-5-1 certified dissipative systems, and economy-grade calendered PVC for light-assembly benches.
Pricing Analysis
Long-term offtake contracts dominate procurement for Taiwan and South Korea semiconductor fabs, insulating gowning-area mat suppliers from naphtha-derived PVC volatility while spot purchasing prevails among China's contract manufacturers. Price differentiation hinges on IEC 61340-5-1 certification tier and volume scale, with aerospace MRO buyers in Germany and Japan exhibiting lowest sensitivity due to extended replacement cycle economics. Cost compression in standard-duty vinyl intensifies as loose-lay formats displace adhesive-bonded systems among price-sensitive electronics assemblers.
Supply Chain Analysis
Export-control scrutiny of carbon-nanotube and copper-nanowire conductive technologies limits technology transfer to Chinese compounders, fragmenting advanced substrate sourcing between Taiwan, South Korea, and Japan. Raw material flows draw from Saudi naphtha crackers for PVC resin, German carbon black specialists for conductivity matrices, and Malaysian rubber processors for nitrile formulations. Single-source vulnerability concentrates in eastern China's conductive additive corridor. Distribution runs through electrical supply houses and direct-to-facility digital channels serving cleanroom design firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ESD safe matting demand tracks semiconductor capital expenditure cycles, with Taiwan and South Korea fab commissioning schedules indicating recovery momentum across the analysis window.
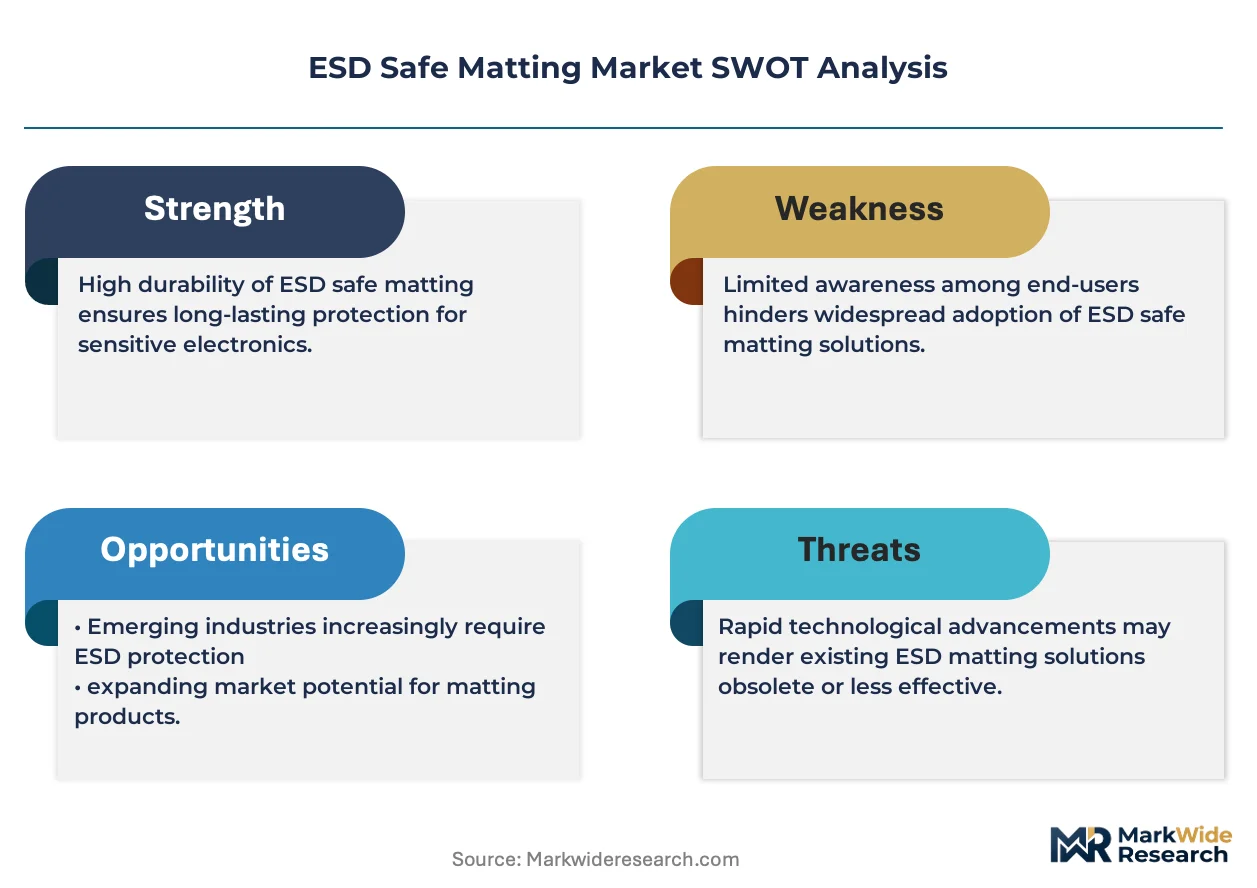
For Market Incumbents: Insulate qualification dossiers from REACH substance restrictions by accelerating terephthalate plasticizer reformulation ahead of ECHA enforcement timelines. Deepen backward integration into carbon-loaded matrix compounding to defend margin position against petrochemical feedstock volatility. Prioritize certified installer network expansion in India's Tamil Nadu and Karnataka electronics corridors. For New Entrants and Emerging Players: Biodegradable polyurethane matting for Nordic electronics assembly operations represents the most penetrable entry point, given sustainability-mandated procurement criteria and limited incumbent bio-based formulation expertise. India's PLI-scheme electronics manufacturing facilities offer second-mover positioning for interlocking format specialists. Partner with cleanroom design software vendors to embed specification authority upstream of distributor channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed flooring distributors possessing regional electrical supply house relationships but lacking in-house polymer science capabilities. Five-to-ten year viability favors compounders with REACH-compliant formulation pipelines and Taiwan fab qualification status. Watch copper-nanowire substrate adoption rates in South Korea advanced packaging zones as inflection indicator for vinyl displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Reformulation | ECHA scrutiny of ortho-phthalates forces plasticizer substitution to maintain European market access. |
| Copper-Nanowire Substrate Development | Taiwan wafer fabs pilot thinner conductive profiles that extend replacement cycles beyond carbon-black alternatives. |
| Direct-to-Facility Digital Channel Launch | Specialized distributors bypass electrical supply houses to capture specification authority in cleanroom design workflows. |
| Certified Installer Network Expansion | India's PLI-scheme electronics clusters demand bundled installation and IEC 61340-5-1 testing capabilities. |
| Bio-Based Polyurethane Scale-Up | Nordic automotive electronics suppliers mandate full material disclosure upstream of mat procurement decisions. |
Research Methodology
A spread of perspectives from cleanroom facility managers, ESD flooring procurement leads, polymer compounding engineers, certified installation contractors, and semiconductor fab operations directors converged on the working assumptions. Primary fieldwork combined with secondary validation from IEC 61340-5-1 certification databases, ECHA substance restriction filings, customs trade data for PVC resin and carbon black flows, and SEC disclosures from diversified industrial conglomerates. Bottom-up segment sizing and top-down demand triangulation anchored volume estimates.
Demand-supply balance dynamics across vinyl and rubber chemistries, installation format permanence preferences, and regional certification burdens shaped the analytical framework throughout the projection horizon. Segmentation dimensions modeled include material type, installation configuration, thickness specification, end-use environment, and regional regulatory cluster. CAGRs derived from facility expansion pipelines, fab commissioning schedules, and replacement cycle economics. Forecast inputs incorporated naphtha cracking margin forecasts and REACH compliance timeline probabilities.
Stress conditions across petrochemical feedstock volatility bands, semiconductor capex contraction scenarios, and ECHA enforcement intensity levels were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding Taiwan and South Korea fab buildout schedules and India's PLI scheme disbursement continuity. Material shifts in copper-nanowire substrate cost-competitiveness or accelerated biodegradable polymer performance parity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrostatic Discharge (ESD) Packaging
Shielding Bags Market
Electrostatic Discharge (ESD) Packaging
ESD Tray Market
Electrostatic Discharge (ESD) Packaging
ESD Clamshell Market
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Packaging Market
Electrostatic Discharge (ESD) Packaging
India Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
ESD Totes Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Saudi Arabia Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Flooring Market
Electrostatic Discharge (ESD) Packaging
South Korea Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Packaging Market
Electrostatic Discharge (ESD) Packaging
ESD Workstations Market
Electrostatic Discharge (ESD) Packaging
UAE Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Metallic Static Shielding Bags Market
Electrostatic Discharge (ESD) Packaging
ESD Foldable Container Market