
 Electrostatic Discharge (ESD) Flooring Market | 2026-2036
Electrostatic Discharge (ESD) Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Electrostatic Discharge (ESD) Flooring Market Insights
Cleanroom operators and semiconductor fabricators are redrawing procurement priorities for ESD flooring across Asia-Pacific and North American facilities. StaticWorx leverages its conductive and dissipative technology portfolio to anchor premium installations in electronics manufacturing. Mohawk Group sustains broad manufacturing scale across vinyl and carpet ESD tile categories. Forbo Flooring Systems differentiates through specialized epoxy formulations targeting aerospace assembly environments.
Electrostatic Discharge (ESD) Flooring comprises conductive, dissipative, or anti-static surface materials engineered to control electrostatic discharge within defined resistance ranges, typically between 10^4 and 10^9 ohms, protecting sensitive electronic components from catastrophic failure. Vinyl ESD flooring dominates volume across electronics manufacturing floors due to lower installed cost and chemical resistance, while epoxy ESD flooring commands margin pools in cleanroom applications requiring seamless, monolithic surfaces with stringent particulate control. Dissipative technology leads current specification sheets, though dual-function systems combining static shielding with thermal conductivity are gaining traction in precision instrument maker facilities.
IEC 61340-5-1, ANSI/ESD S20.20, and ISO 9001 certification frameworks govern product validation, installation auditing, and ongoing compliance verification across supplier bases. These standards shape demand by mandating third-party testing and documented resistance measurements before facility commissioning. Stakeholders must monitor evolving regional interpretations of grounding continuity requirements and decide whether to certify through centralized laboratories or pursue in-house metrology capabilities.
Market Dynamics
Semiconductor fabricators are tightening ESD flooring specifications as cleanroom complexity escalates and sub-10nm chip production demands stricter particulate and static control protocols. This specification compression is forcing material suppliers to recalibrate formulation chemistry and installation methodologies.
Growth Catalysts
- IEC 61340-5-1 Mandates:Third-party resistance testing requirements are expanding addressable demand across electronics manufacturing facilities in Germany and Japan.
- Epoxy Formulation Advances:Seamless monolithic surfaces with integrated grounding grids are capturing specification share in aerospace assembly environments.
- China:Domestic microchip producers scaling captive fabrication capacity are driving concentrated procurement of dissipative vinyl systems.
Market Restraints
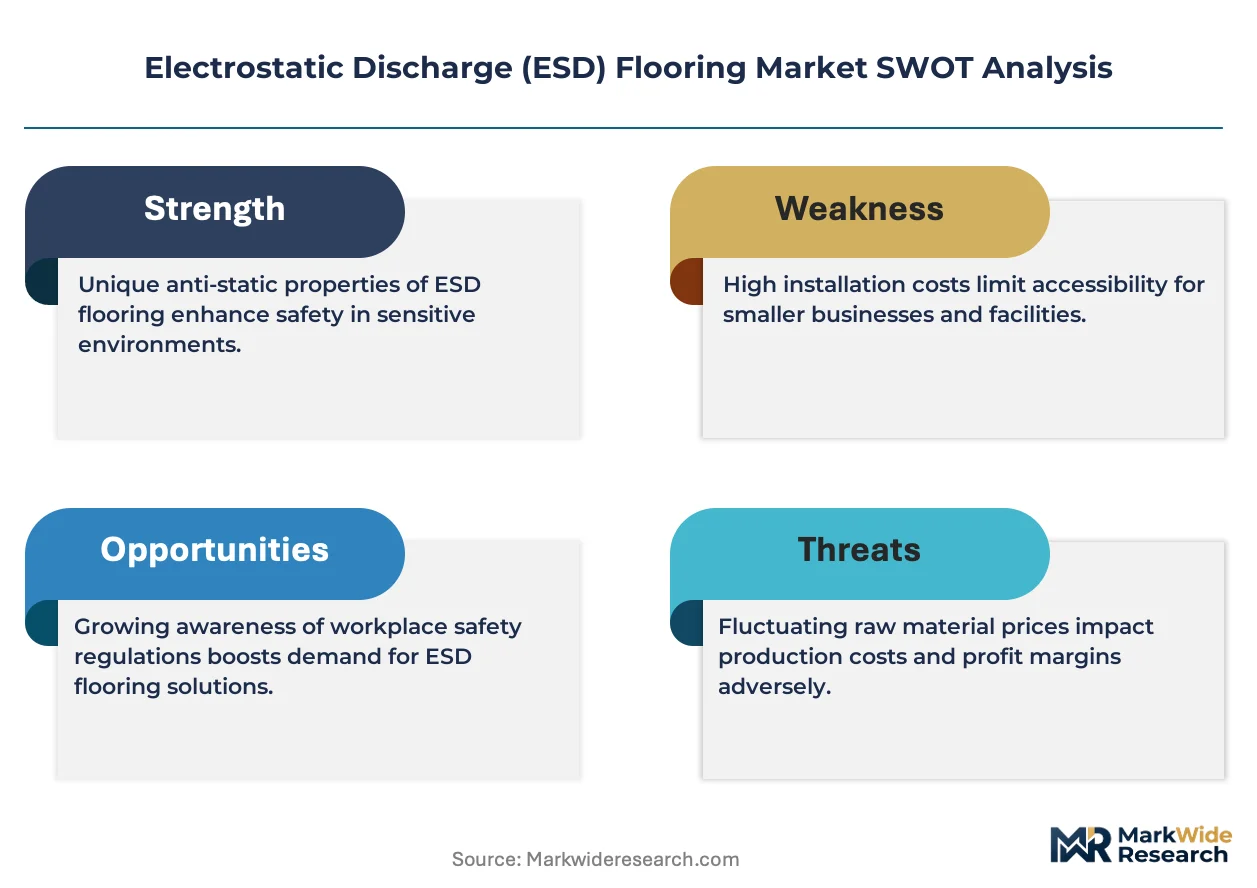
- Copper Grounding Grid Volatility:Embedded conductive mesh costs fluctuate with London Metal Exchange pricing, compressing margin pools for installation contractors.
- Epoxy Resin Supply Concentration:Specialty chemical feedstock production clusters in the Rhine-Ruhr industrial corridor create geographic vulnerability for seamless flooring formulations.
- ANSI/ESD S20.20 Compliance Friction:Divergent regional interpretation of resistance measurement protocols extends facility commissioning timelines.
Strategic Opportunities
- India:PLI scheme incentives for semiconductor packaging facilities are opening specification windows for domestic ESD flooring installation capacity.
- Thermal-Conductive Dual Function:Convergence of static shielding with heat dissipation properties targets precision instrument calibration laboratories.
- Direct Specification:End-user engineering teams are bypassing traditional distributor channels to negotiate directly with formulation specialists.
Industry Challenges
- Certified Installer Scarcity:Grounding continuity testing and megohmmeter operation require specialized technician training that outpaces vocational program output.
- Legacy Subfloor Compatibility:Existing concrete moisture vapor emission rates often exceed epoxy adhesion thresholds, demanding costly remediation before ESD system installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrostatic Discharge (ESD) Flooring Market |
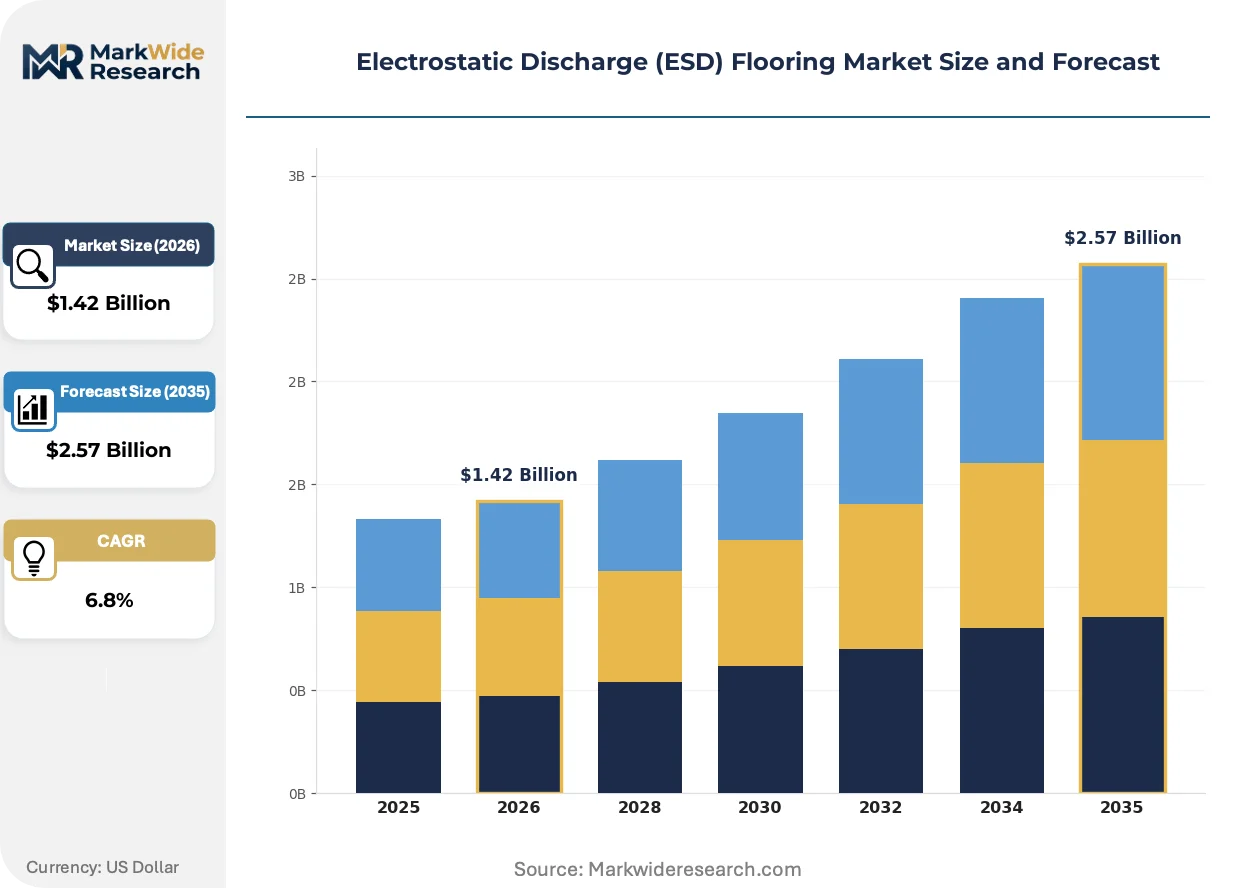
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl ESD Flooring, Rubber ESD Flooring, Epoxy ESD Flooring, Carpet ESD Tiles, PVC ESD Sheets Technology: Conductive, Dissipative, Static Shielding, Anti-Static Coating, Dual-Function, Thermally Conductive Application: Electronics Manufacturing, Cleanrooms, Laboratories, Data Centers, Aerospace Assembly End User: Semiconductor Fabricators, Microchip Producers, Electronic Assemblers, Precision Instrument Makers, Component Suppliers |
| Companies Covered | Armstrong, Interface, Mohawk Group, Huilian, Forbo Flooring Systems, StaticWorx, Tarkett, SelecTech (StaticStop), Gerflor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrostatic Discharge (ESD) Flooring Market Trends and Innovations
Material science breakthroughs and procurement model compression are reconfiguring how ESD flooring systems are specified, installed, and validated across precision manufacturing environments.
Conductive polymer nanocomposites are displacing traditional carbon-fiber-loaded vinyl formulations in high-traffic semiconductor cleanrooms. Taiwan-based fabricators are specifying these materials for 300mm wafer production floors. The shift is compressing replacement cycles from seven years to four while elevating performance guarantees.
REACH restrictions on phthalate plasticizers are forcing European vinyl compounders to reformulate dissipative tile chemistry. The industrial consequence is a six-to-nine-month qualification delay for new material submissions. German automotive electronics suppliers are responding by pre-qualifying alternative epoxy systems ahead of specification deadlines.
Facility engineering teams are consolidating vendor relationships from multi-source bidding to sole-source partnerships with full-service installation specialists. Distributor networks in North America are losing specification influence to direct manufacturer engagement. This consolidation is most visible among Texas and Arizona-based semiconductor greenfield projects.
Electrostatic Discharge (ESD) Flooring Market Segmentation
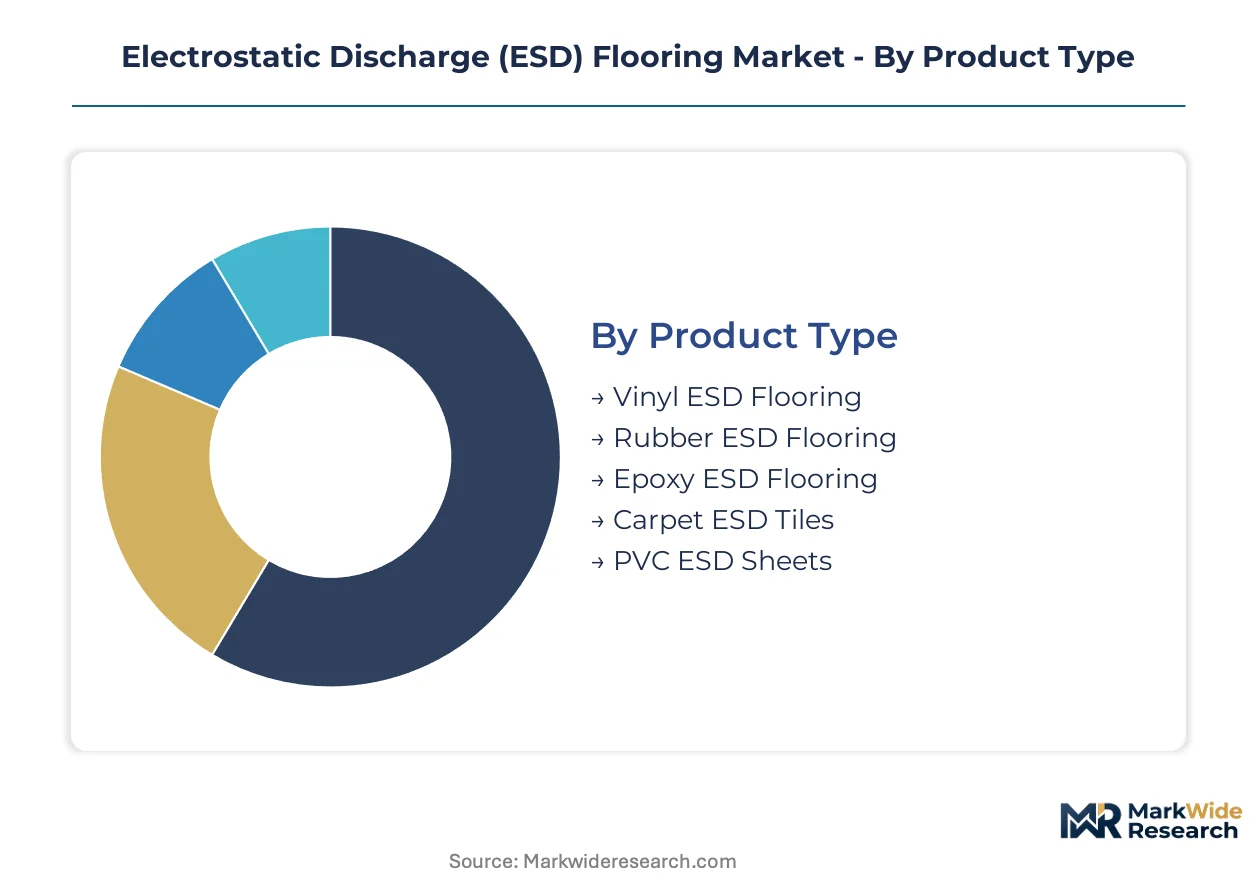
ESD flooring procurement decisions hinge on precise alignment between surface resistance specifications and facility contamination protocols. Semiconductor fabricators demand segment-specific validation against IEC 61340-5-1 grounding continuity requirements before commissioning.
Product Type:
Regulatory differentiation across flooring substrates determines qualification timelines and regional market access, with REACH phthalate restrictions forcing reformulation cycles in European vinyl compounders.
- Vinyl ESD Flooring:Carbon-fiber-loaded PVC formulations deliver installed cost advantages and chemical resistance for high-traffic electronics manufacturing floors. Taiwan-based 300mm wafer fabricators specify these systems for replacement cycles compressed from seven years to four. IEC 61340-5-1 resistance documentation accompanies every shipment.
- Epoxy ESD Flooring:Seamless monolithic surfaces with integrated copper grounding grids command premium positioning in aerospace assembly environments requiring stringent particulate control. German automotive electronics suppliers pre-qualify these systems ahead of specification deadlines to circumvent REACH-related delays.
- Rubber ESD Flooring:Resilient elastomer compositions target precision instrument calibration laboratories needing ergonomic load distribution alongside static control.
- Carpet ESD Tiles:Modular nylon constructions with conductive backing serve administrative zones within cleanroom complexes where foot traffic volume exceeds chemical exposure risk.
- PVC ESD Sheets:Roll-format homogeneous surfaces reduce seam count in large-format semiconductor bay installations.
Vinyl ESD flooring handles the majority of throughput; epoxy ESD flooring is expanding most quickly on specification share.
Technology:
Cost tier separation between baseline anti-static coatings and engineered conductive nanocomposites widens as sub-10nm chip production demands escalate.
- Dissipative:Surface resistance between 10^6 and 10^9 ohms dominates current specification sheets across electronics manufacturing facilities. China-based domestic microchip producers scale captive procurement of these systems as fabrication capacity expands.
- Conductive:Lower resistance ranges below 10^6 ohms serve explosive atmosphere environments and battery assembly operations where charge accumulation risks ignition.
- Static Shielding:Metallic layer laminations protect sensitive components during transport and temporary staging.
- Anti-Static Coating:Surface-applied treatments offer retrofit options for legacy facilities avoiding full flooring replacement.
- Dual-Function:Convergence of static control with thermal conductivity properties targets precision instrument maker facilities managing heat dissipation alongside electrostatic protection.
- Thermally Conductive:Specialized formulations address calibration laboratory environments where temperature stability intersects with charge management.
Dissipative technology anchors volume demand; dual-function systems are gaining share fastest in precision manufacturing specifications.
Application:
Customer type concentration varies sharply across facility types, with cleanroom operators consolidating vendor relationships while data center engineers prioritize rapid deployment.
- Electronics Manufacturing:High-volume assembly floors prioritize chemical resistance and rapid installation turnaround. Texas and Arizona-based semiconductor greenfield projects drive concentrated procurement through direct manufacturer engagement rather than distributor networks.
- Cleanrooms:ISO 14644-compliant facilities demand seamless surfaces with documented particulate emission testing. Taiwan fabricators specify conductive polymer nanocomposites for 300mm wafer production environments.
- Laboratories:Research and development facilities balance static control against ergonomic and aesthetic considerations.
- Data Centers:Raised floor environments require underfloor grounding grid integration with cable management systems.
- Aerospace Assembly:FAA oversight and foreign object debris protocols mandate specialized epoxy formulations with embedded conductive mesh.
Electronics manufacturing absorbs the largest installation volume; cleanroom applications show the steepest specification tightening.
End User:
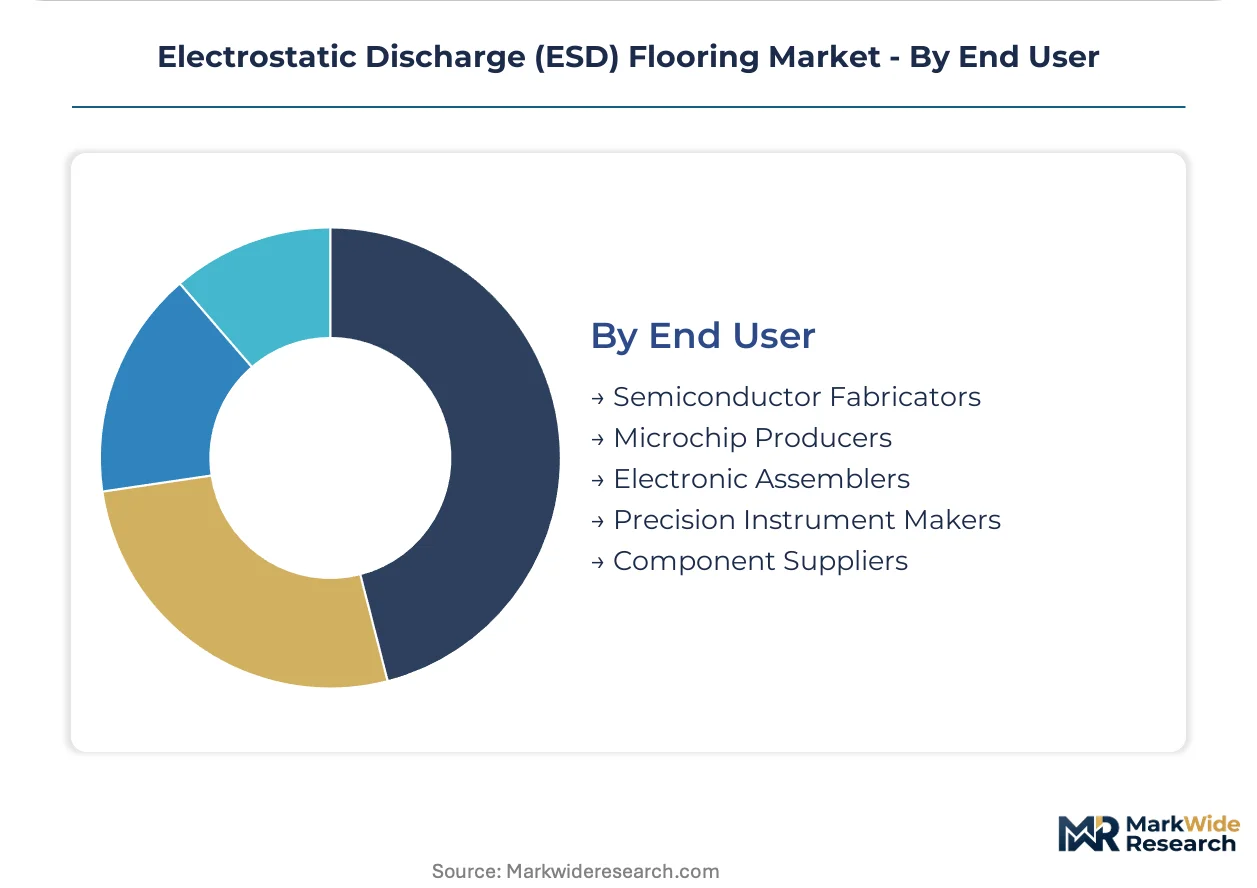
Supply concentration among semiconductor fabricators creates procurement leverage, while precision instrument makers drive innovation in dual-function performance requirements.
- Semiconductor Fabricators:Sub-10nm production protocols force specification compression across flooring resistance ranges and particulate thresholds. Facility engineering teams bypass traditional distributor channels to negotiate directly with formulation specialists.
- Microchip Producers:Domestic capacity scaling in China concentrates demand for dissipative vinyl systems with accelerated qualification timelines.
- Electronic Assemblers:Contract manufacturers prioritize installed cost and rapid commissioning over extended performance guarantees.
- Precision Instrument Makers:Calibration laboratory requirements for thermal stability alongside static control drive adoption of dual-function technologies.
- Component Suppliers:Tier-2 and tier-3 suppliers follow OEM specification cascades with delayed technology adoption cycles.
Semiconductor fabricators command the dominant procurement volume; precision instrument makers are climbing fastest on technology premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor fabricators and cleanroom operators concentrate procurement across five national manufacturing clusters where sub-10nm chip production and aerospace assembly drive specification tightening.
United States
Texas and Arizona-based semiconductor greenfield projects anchor North American demand for dissipative vinyl systems with accelerated commissioning timelines. FAA oversight of aerospace assembly facilities in the Southwest mandates specialized epoxy formulations with embedded conductive mesh for foreign object debris control. The Austin-Phoenix corridor sees direct manufacturer engagement replacing traditional distributor channels.
China
Domestic microchip producers scaling captive fabrication capacity concentrate procurement of dissipative vinyl systems across Yangtze River Delta facilities. MIIT guidelines on electronics manufacturing cleanliness intersect with SAMR product certification requirements for flooring resistance documentation. Shanghai and Suzhou industrial zones witness specification compression as 300mm wafer production expands.
Germany
Automotive electronics suppliers in Bavaria and Baden-Württemberg pre-qualify epoxy systems ahead of specification deadlines to circumvent REACH phthalate restriction delays. ECHA reformulation mandates force six-to-nine-month qualification cycles for vinyl compounders. The Rhine-Ruhr corridor remains vulnerable on specialty chemical feedstock supply for seamless flooring formulations.
Japan
Electronics manufacturing floors in Kansai and Chubu regions prioritize IEC 61340-5-1 third-party resistance testing under METI industrial standards guidance. Osaka-based fabricators specify conductive polymer nanocomposites for high-traffic cleanroom environments. JIS certification frameworks shape grounding continuity verification protocols before facility commissioning.
India
PLI scheme incentives for semiconductor packaging facilities in Gujarat and Karnataka open specification windows for domestic ESD flooring installation capacity. BIS standards alignment with IEC frameworks accelerates product validation timelines for multinational suppliers entering the market. The Delhi-Mumbai Industrial Corridor attracts greenfield electronics manufacturing investment with static control infrastructure requirements.
Electrostatic Discharge (ESD) Flooring Market Competitive Landscape
Player mix skews toward formulation specialists with installation capabilities rather than pure material suppliers. The competitive structure tiers across premium seamless epoxy providers, high-volume vinyl tile manufacturers, and regional installation contractors. Strategic archetypes include full-service specification partners, scale-driven compounders, and certified installation networks. Dominant competitive moves encompass backward integration into conductive polymer production and geographic expansion through direct engagement with facility engineering teams.
Among North American specialists, StaticWorx occupies a position within the premium installation tier, while Mohawk Group exemplifies scale-driven manufacturing across vinyl and carpet tile categories. Forbo Flooring Systems represents the European formulation specialist archetype with epoxy expertise. These three anchors illustrate how competitive positioning separates seamless system providers from modular tile suppliers in specification-intensive cleanroom and aerospace environments.
| Leading Market Players |
|---|
| Armstrong |
| Interface |
| Mohawk Group |
| Huilian |
| Forbo Flooring Systems |
| StaticWorx |
| Tarkett |
| SelecTech (StaticStop) |
| Gerflor |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between semiconductor fabricators and epoxy formulation specialists lock in copper grounding grid supply and flatten price volatility across the analysis window. These contracts tether installation contractors to fixed-margin structures while insulating premium seamless flooring tiers from London Metal Exchange fluctuations.
Pricing Analysis
Cost-plus contracts with London Metal Exchange copper indexation dominate the embedded conductive mesh tier. Three-tier pricing structure across premium seamless epoxy, standard dissipative vinyl, and economy anti-static coating tiers separates aerospace assembly specifications from electronics manufacturing floors. Price differentiation rests on IEC 61340-5-1 certification grade and installation warranty duration. Cost compression in the vinyl tier is intensifying because REACH phthalate reformulation extends qualification timelines. Contract manufacturers exhibit highest price sensitivity; cleanroom operators show lowest.
Supply Chain Analysis
Inventory cycles for specialty epoxy resins stretch sixteen to twenty weeks, forcing aerospace contractors to pre-position material ahead of specification deadlines. Formulation chemistry concentrates in Germany, China, and the United States. Conductive polymer nanocomposites draw from carbon nanotube feedstocks and vinyl resin supply. Single-source vulnerability clusters in the Rhine-Ruhr corridor for seamless flooring precursors. Distribution runs through direct manufacturer engagement with facility engineering teams, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward semiconductor fabricators consolidating vendor relationships from multi-source bidding to sole-source partnerships. This concentration compresses margin pools for installation contractors while elevating specification influence for formulation specialists.
For Market Incumbents: Consolidate backward integration into conductive polymer production to offset copper grounding grid volatility. Deepen certified installer training programs to address technician scarcity threatening commissioning timelines. Defend against emerging nanocomposite specialists by pre-qualifying alternative epoxy systems ahead of REACH-related reformulation cycles.
For New Entrants and Emerging Players: Differentiate on thermal-conductive dual-function formulations targeting precision instrument calibration laboratories. White-space exists in India's PLI scheme-driven semiconductor packaging facilities where domestic installation capacity lags demand. Target direct specification relationships with Texas and Arizona-based greenfield project engineering teams.
For Investors and Strategic Acquirers: Capital is best deployed toward formulation specialists with captive installation capabilities and IEC 61340-5-1 certification infrastructure. Long-term viability favors full-service specification partners over pure material suppliers in a market trending toward sole-source procurement. Watch for inflection when domestic microchip producers in China accelerate captive fabrication capacity scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductive Polymers | Captive nanocomposite production insulates margin pools from carbon feedstock volatility. |
| Certified Installer Network Expansion | Megohmmeter-trained technicians accelerate facility commissioning for semiconductor fabricators. |
| REACH-Compliant Formulation Pre-qualification | Alternative epoxy submissions circumvent six-to-nine-month European qualification delays. |
| Direct Specification Team Deployment | Engineer-to-engineer engagement captures Texas and Arizona greenfield project demand. |
| Thermal-Conductive Dual-Function Development | Heat dissipation properties target precision instrument maker calibration laboratory requirements. |
Research Methodology
Desk research of customs trade data, SEC filings from flooring compounders, and IEC certification databases preceded structured interviews with cleanroom facility managers, ESD flooring installation contractors, semiconductor procurement directors, and epoxy formulation chemists. Primary fieldwork across the United States, China, Germany, and Japan validated resistance measurement protocol interpretations. Secondary sources included ANSI/ESD S20.20 documentation, REACH substance restriction updates, and MIIT electronics manufacturing guidelines. Bottom-up unit demand and top-down market sizing triangulated volume estimates.
Variance decomposition across product type, technology tier, application facility, and end-user concentration shaped the analytical framework over the projection horizon. Segment-level CAGRs derived from installation volume trends, replacement cycle compression observations, and specification tightening indices. Forecast inputs incorporated copper price correlation coefficients and cleanroom construction pipeline tracking.
The analysis sits within stated boundaries; outcomes outside sustained semiconductor capital expenditure levels or altered REACH enforcement intensity would require recalibration. Forecasts reflect assumptions on certification timeline stability and installer training program throughput. Revision becomes warranted when copper grounding grid cost pass-through thresholds breach contract renegotiation clauses.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrostatic Discharge (ESD) Packaging
South Korea Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
ESD Foldable Container Market
Electrostatic Discharge (ESD) Packaging
ESD Clamshell Market
Electrostatic Discharge (ESD) Packaging
Metallic Static Shielding Bags Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Packaging Market
Electrostatic Discharge (ESD) Packaging
Saudi Arabia Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Shielding Bags Market
Electrostatic Discharge (ESD) Packaging
India Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Packaging Market
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
ESD Safe Matting Market
Electrostatic Discharge (ESD) Packaging
ESD Totes Market
Electrostatic Discharge (ESD) Packaging
ESD Tray Market
Electrostatic Discharge (ESD) Packaging
ESD Workstations Market
Electrostatic Discharge (ESD) Packaging
UAE Electrostatic Discharge (ESD) Films Market