
 Shielding Bags Market | 2026-2036
Shielding Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Shielding Bags Market Analytics
Asian contract manufacturers of shielding bags is decoupling from legacy petroleum-based supply chains as domestic resin capacity expands. 3M Company leverages its materials science portfolio to sustain premium positioning in multilayer barrier films. Protective Packaging Corporation anchors North American distribution through specialized converter networks. Desco Industries Inc. dominates static-control product channels with integrated grounding and packaging solutions.
Shielding bags are multilayer laminated enclosures, typically incorporating metallized polyester or aluminum foil layers with polyethylene substrates, engineered to attenuate electromagnetic interference and prevent electrostatic discharge damage to sensitive components. These enclosures serve semiconductor, aerospace, and medical device supply chains where surface resistivity below 10^12 ohms per square is mandatory for component integrity. Polyethylene formulations occupy the highest volume tier due to cost scalability in high-throughput electronics packaging, while Mylar laminates command margin pools in precision pharmaceutical storage where moisture and oxygen transmission rates must stay below 0.1 cc per square meter daily. Defense use applications represent the fastest-growing demand segment as military specification MIL-PRF-81705 drives adoption of resealable heat-seal closure systems with documented charge decay performance.
EPA guidelines on volatile organic compound emissions from adhesive lamination processes are reshaping domestic manufacturing compliance costs, while FDA Title 21 CFR requirements for pharmaceutical contact materials constrain substrate selection for medical-grade shielding bags. ISO 9001 and ANSI/ESD S20.20 certification frameworks govern market access for suppliers serving electronics original equipment manufacturers. Stakeholders must monitor evolving ECHA restrictions on per- and polyfluoroalkyl substances that threaten conventional moisture barrier coatings.
Market Dynamics
Semiconductor fabrication expansion in Taiwan and South Korea is concentrating procurement power among static-dissipative packaging buyers, forcing substrate suppliers to align with cleanroom-grade specifications and regional resin capacity buildouts.
Growth Catalysts
- Wafer Transport Intensification:Taiwan Semiconductor Manufacturing and Samsung Foundry are scaling 3nm and 2nm production nodes, multiplying wafer-level packaging cycles that demand surface resistivity below 10^9 ohms per square.
- REACH Compliance Arbitrage:European electronics assemblers are sourcing RoHS-certified shielding substrates ahead of ECHA's 2025 perfluoroalkyl substance restrictions, accelerating qualified supplier transitions.
- Military Specification Mandates:MIL-PRF-81705 Type I and Type III requirements for charge decay documentation are penetrating aerospace maintenance depots and defense logistics networks.
Market Restraints
- Petroleum-Based Resin Dependency:Polyethylene and metallized polyester pricing tracks naphtha and ethylene feedstock volatility from Gulf Coast and Northeast Asian crackers.
- East Asian Supply Concentration:Over 70% of metallized film laminators operate within 500 kilometers of Shanghai, Shenzhen, or Busan, creating single-point vulnerability to port congestion or power rationing.
- Adhesive Lamination Emissions:EPA volatile organic compound guidelines for solvent-based bonding processes are elevating compliance capital requirements for domestic North American converters.
Strategic Opportunities
- Indian Electronics Manufacturing:Production-linked incentive schemes for semiconductor assembly and testing are attracting Foxconn and Tata Electronics operations requiring localized ESD packaging supply.
- Biodegradable Substrate Development:Polylactic acid and starch-polymer blends with vapor-deposited aluminum layers are approaching moisture barrier parity for non-critical consumer electronics.
- Pharmaceutical Cold Chain Convergence:Cell and gene therapy distributors are specifying dual-purpose shielding bags combining electromagnetic attenuation with ultra-low temperature thermal insulation.
Industry Challenges
- ANSI/ESD S20.20 Certification Bottlenecks:Third-party auditor capacity constraints are extending qualification timelines for new bag converters entering automotive and medical device supply chains.
- Multilayer Adhesion Failure Modes:Metallized layer delamination during flex testing remains the primary cause of lot rejection in aerospace qualification protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shielding Bags Market |
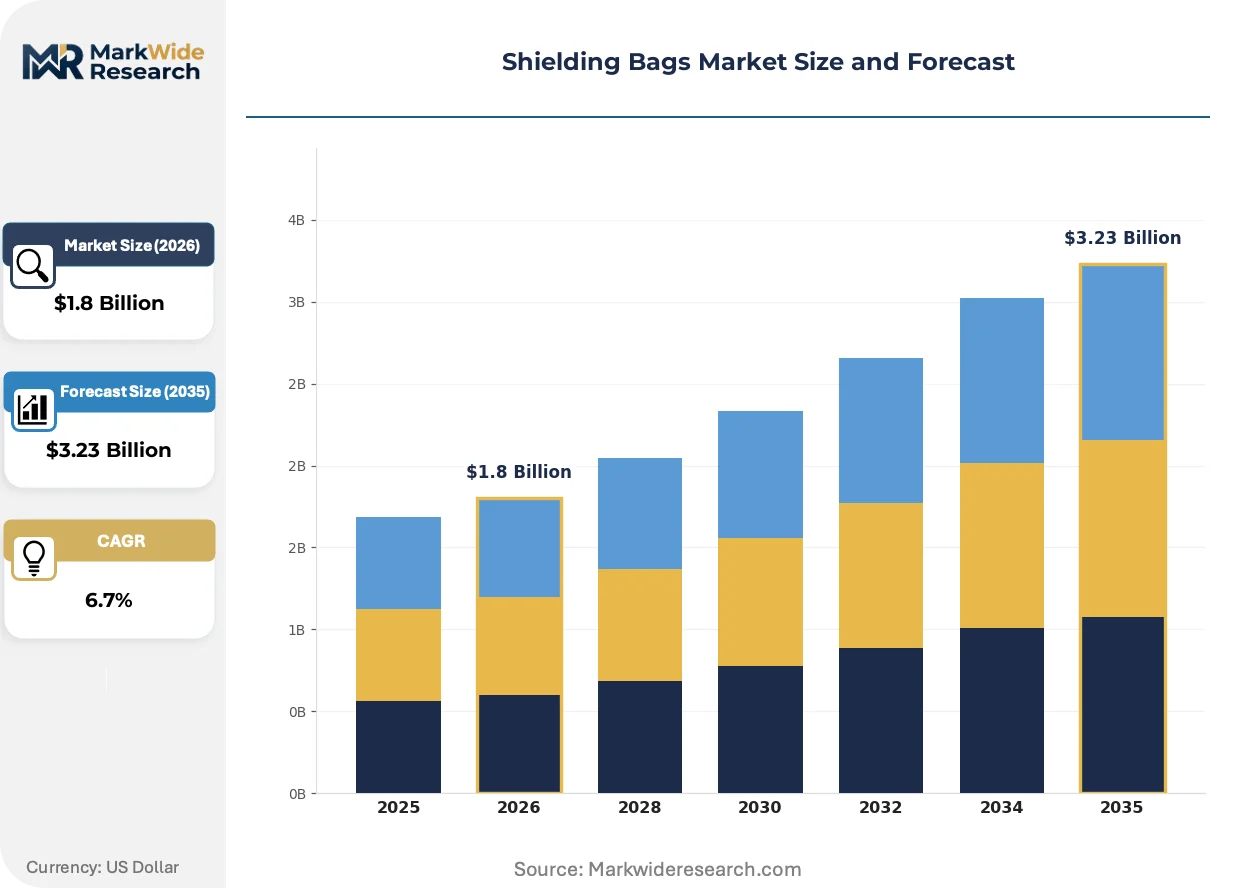
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Mylar, Vinyl, Paper Application: Electronics Packaging, Pharmaceutical Storage, Medical Devices, Defense Use Closure Type: Zip Lock, Heat Seal, Adhesive Seal, Velcro Size: Small, Medium, Large, Custom |
| Companies Covered | 3M Company, Protective Packaging Corporation, Advantek Inc., Desco Industries Inc., Teknis Limited, Dou Yee Enterprises (S) Pte Ltd, Edco Supply Corporation, Miller Packaging, Antistat Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shielding Bags Market Evolving Landscape
Materials science advances and regulatory chemistry constraints are converging to displace conventional moisture barrier coatings while semiconductor packaging geometries drive precision tolerances tighter.
Atomic layer deposition of aluminum oxide onto polyethylene terephthalate substrates is rewriting barrier performance economics. Medical device sterilization departments at Boston Scientific and Medtronic facilities are qualifying these films for implantable component packaging. The technology is compressing the cost gap between commodity metallized bags and high-performance ceramic-coated alternatives.
EU REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing reformulation of conventional moisture barrier coatings. Lamination adhesive suppliers are accelerating water-based and UV-cured alternatives through validation pipelines. Pharmaceutical contact material suppliers serving European distribution networks are prioritizing fluorine-free substrate certifications ahead of 2025 enforcement windows.
Contract manufacturers are consolidating vendor lists from twelve-plus shielding bag suppliers to three qualified partners per production site. Electronics manufacturing services providers in Vietnam and Mexico are demanding integrated grounding workstation and packaging procurement to simplify incoming inspection. This concentration is most visible among Foxconn and Pegatron facilities where total cost of ownership models now dominate unit price negotiations.
Shielding Bags Market Segmentation
Shielding bag specifications diverge sharply across end-use requirements, with semiconductor cleanrooms demanding sub-10^9 ohm surface resistivity while pharmaceutical cold chains prioritize ultra-low moisture transmission. Material selection and closure mechanics directly determine qualification for MIL-PRF-81705 defense contracts versus consumer electronics commodity procurement.
Material Type:
Customization intensity spans from commodity resin formulations to engineered multilayer laminates with atomic-layer-deposited barrier coatings.
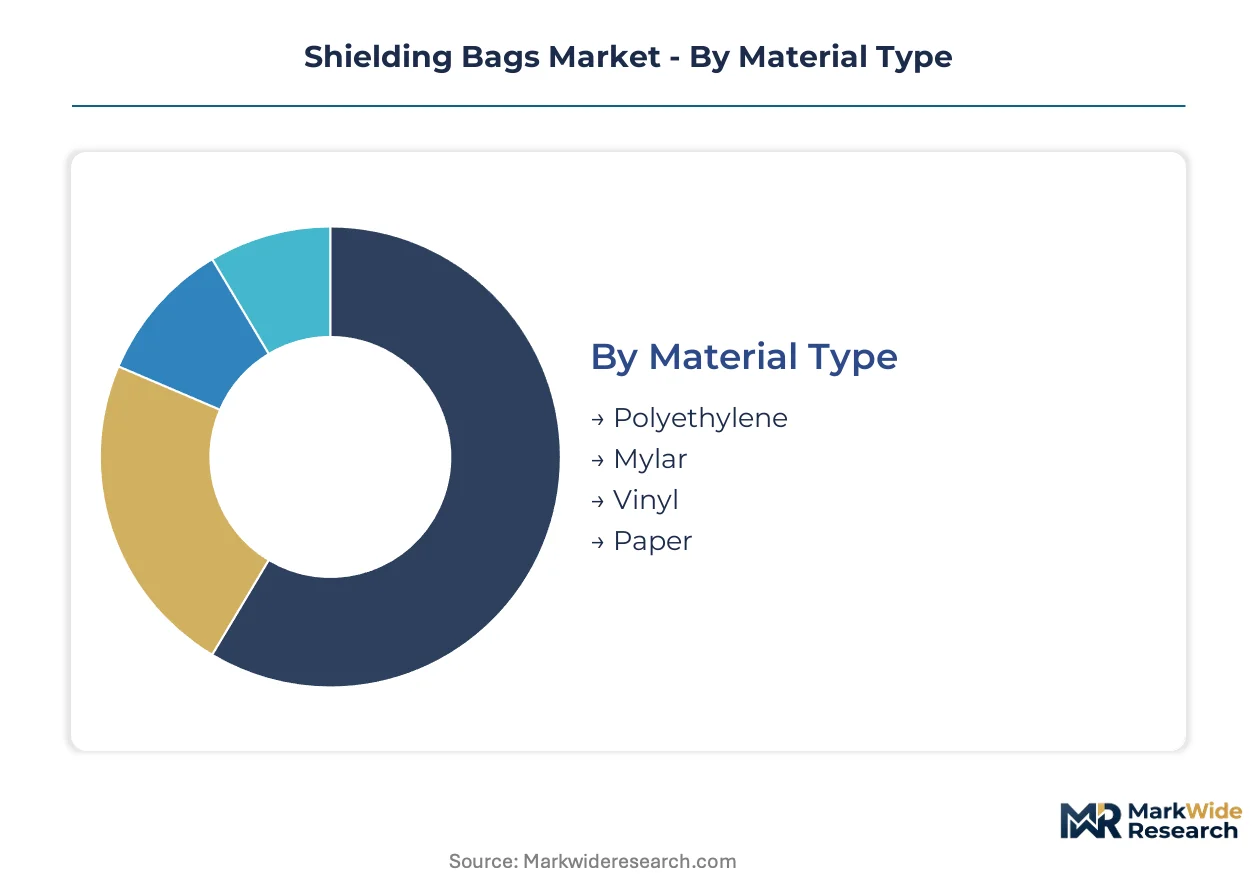
- Polyethylene:Linear low-density and metallized coextrusions dominate high-throughput electronics packaging due to cost scalability in roll-stock conversion. Taiwan and South Korea wafer fabs specify anti-static masterbatch formulations with carbon-loaded conductive layers for automated handling systems.
- Mylar:Biaxially oriented polyethylene terephthalate films with vapor-deposited aluminum achieve moisture transmission rates below 0.1 cc per square meter daily. Boston Scientific and Medtronic sterilization departments qualify these for implantable component packaging where oxygen exclusion is critical.
- Vinyl:Polyvinyl chloride formulations with embedded wire mesh grounding grids serve aerospace maintenance depots requiring visual charge dissipation verification.
- Paper:Kraft-based static-dissipative substrates with aluminum oxide coatings approach barrier parity for non-critical consumer electronics where biodegradability is prioritized.
Leading the category by volume: Polyethylene. Expanding most quickly: Mylar.
Application:
Margin pools concentrate where regulatory compliance costs create qualification barriers against commodity competitors.
- Electronics Packaging:Wafer-level chip-scale packaging cycles at TSMC and Samsung Foundry demand surface resistivity below 10^9 ohms per square. Foxconn and Pegatron facilities in Vietnam and Mexico are consolidating vendor lists to three qualified partners per site.
- Pharmaceutical Storage:Cell and gene therapy distributors specify dual-purpose bags combining electromagnetic attenuation with ultra-low temperature thermal insulation. EU REACH Annex XVII fluorine-free certifications are accelerating supplier transitions ahead of enforcement windows.
- Medical Devices:FDA Title 21 CFR compliance for pharmaceutical contact materials constrains substrate selection for implantable component packaging.
- Defense Use:MIL-PRF-81705 Type I and Type III mandates for charge decay documentation are penetrating aerospace maintenance depots and military logistics networks.
Highest margin capture: Pharmaceutical Storage. Steepest demand trajectory: Defense Use.
Closure Type:
Automation compatibility and resealability requirements split procurement between permanent heat-seal systems and reusable mechanical closures.
- Zip Lock:Interlocking polymer tracks with conductive carbon loading maintain static protection through repeated access cycles in component kitting operations.
- Heat Seal:Impulse-sealable multilayer films with documented seal integrity testing satisfy military specification mandates for tamper-evident aerospace logistics. Defense procurement networks are standardizing on this closure format for depot-level maintenance.
- Adhesive Seal:Pressure-sensitive conductive tapes offer intermediate resealability for pharmaceutical lot sampling workflows.
- Velcro:Hook-and-loop fasteners with metallized grounding strips serve rapid-access cleanroom environments where tool-free opening is mandatory.
Dominant in volume: Heat Seal. Gaining share fastest: Zip Lock.
Size:
Standardization versus bespoke dimensions tracks the automation level of downstream handling equipment.
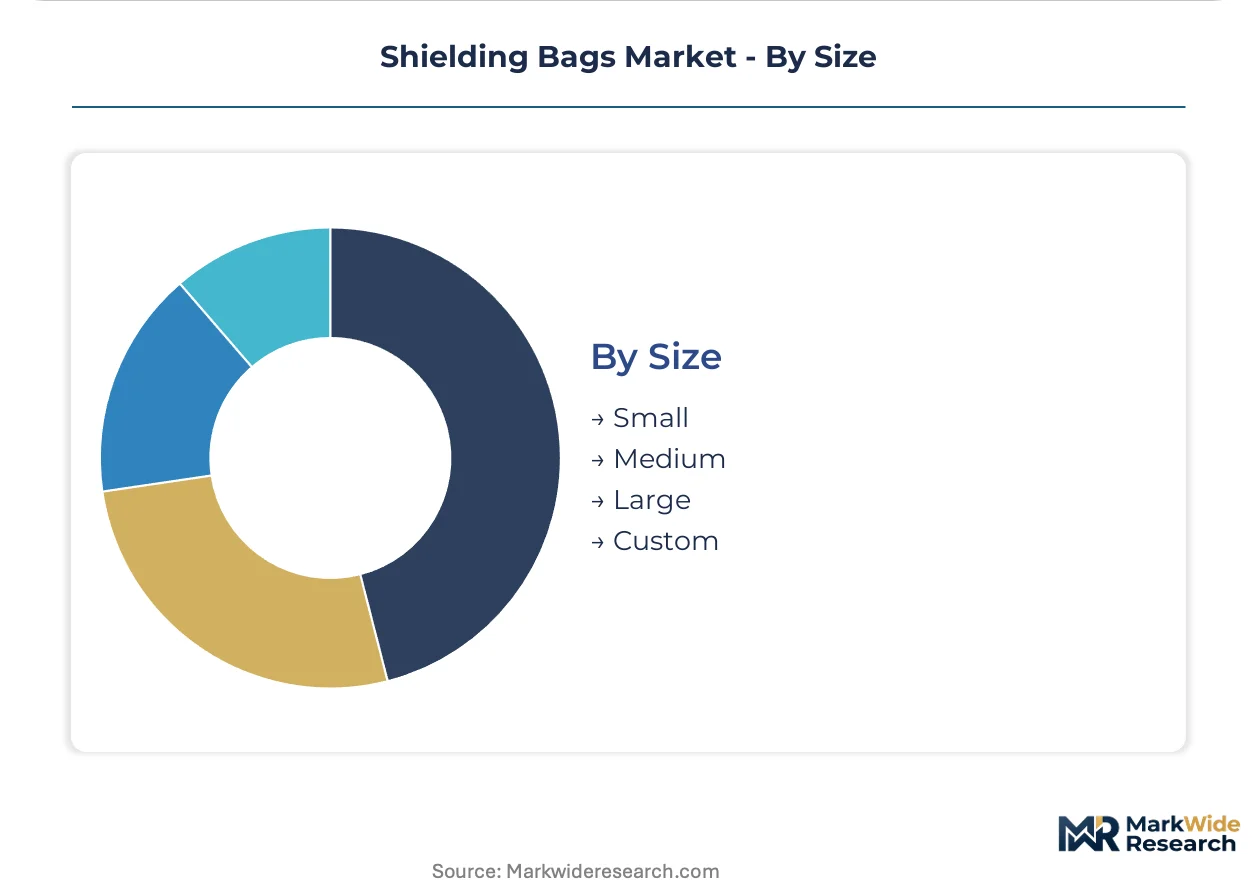
- Small:Die-cut pouches under 150mm dimension serve discrete semiconductor component packaging with automated pick-and-place compatibility.
- Medium:200-400mm formats balance manual handling ergonomics with palletization efficiency in electronics manufacturing services distribution.
- Large:Bulk shielding enclosures accommodate server motherboard and aerospace control module dimensions requiring panel-stiffening inserts.
- Custom:Engineered formats with integrated grounding tabs and vacuum-formed trays capture premium positioning in medical device sterilization departments.
Highest shipment frequency: Medium. Premium pricing concentration: Custom.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metallized polyester feedstock production clusters in East Asia and the US Gulf Coast anchor regional manufacturing footprints for shielding bag laminators. Taiwan and South Korea semiconductor foundries drive premium substrate specifications. European REACH compliance deadlines and Indian production-linked incentive schemes are redrawing procurement geography.
Taiwan
Wafer-level packaging at Taiwan Semiconductor Manufacturing facilities in Hsinchu Science Park multiplies demand for sub-10^9 ohm surface resistivity bags. The National Development Council's semiconductor advancement programs subsidize cleanroom-grade packaging localization. Tainan and Taichung industrial zones host converter operations supplying TSMC's 3nm and 2nm production nodes.
South Korea
Samsung Foundry and SK Hynix expansion in Pyeongtaek and Icheon concentrates static-dissipative packaging procurement among domestic suppliers. Ministry of Trade, Industry and Energy regulations on hazardous substance reporting align with EU REACH Annex XVII ahead of 2025 enforcement. Busan metallized film laminators serve both semiconductor and aerospace defense contractors.
United States
Defense logistics networks under MIL-PRF-81705 mandates drive heat-seal closure standardization across aerospace maintenance depots. EPA volatile organic compound guidelines for adhesive lamination elevate compliance costs for domestic converters. Texas and California electronics manufacturing clusters source through specialized distribution networks anchored by regional packaging converters.
China
Shanghai, Shenzhen and Suzhou metallized film laminators account for dominant regional capacity serving Foxconn and Pegatron facilities. MIIT standards on electromagnetic compatibility packaging converge with ANSI/ESD S20.20 certification requirements. Yangtze River Delta cleanroom logistics specifications match Taiwan and South Korea semiconductor fab standards.
India
Production-linked incentive schemes for semiconductor assembly and testing attract Foxconn and Tata Electronics operations requiring localized ESD packaging supply. Bureau of Indian Standards certification timelines extend qualification periods for new bag converters. Karnataka and Tamil Nadu electronics manufacturing clusters develop vendor consolidation patterns mirroring Vietnam and Mexico.
Shielding Bags Market Competitive Landscape
Global majors compete with regional champions across multilayer barrier film technology and cleanroom-grade certification depth. Market structure tiers between integrated materials science portfolios and specialized converter networks. Three archetypes dominate: diversified industrial conglomerates with captive resin capacity, dedicated static-control specialists with grounding workstation integration, and regional laminators serving contract manufacturer vendor consolidation. Competitive moves center on strategic partnerships for REACH-compliant substrate sourcing and capacity expansion near semiconductor fabrication clusters.
Within the materials science tier, 3M Company exemplifies premium positioning through barrier film innovation. Among North American distribution specialists, Protective Packaging Corporation anchors regional converter networks. Desco Industries Inc. occupies the integrated static-control solutions archetype, representing the convergence of grounding equipment and packaging procurement. These three entities illustrate how certification depth and geographic proximity to East Asian electronics clusters determine competitive positioning.
| Leading Market Players |
|---|
| 3M Company |
| Protective Packaging Corporation |
| Advantek Inc. |
| Desco Industries Inc. |
| Teknis Limited |
| Dou Yee Enterprises (S) Pte Ltd |
| Edco Supply Corporation |
| Miller Packaging |
| Antistat Inc. |
| Others |
Value Network & Pricing Analysis
Semiconductor foundry procurement consolidation around TSMC and Samsung Foundry anchors three-tier pricing structure across premium, standard, and economy levels. Certification depth and geographic proximity to East Asian fabrication clusters determine which tier suppliers occupy.
Pricing Analysis
Warranty-backed charge decay documentation and lot-traceability services are bundled into premium tier offerings for MIL-PRF-81705 defense contracts, while standard electronics packaging strips these to bare unit economics. Price differentiation rests on ANSI/ESD S20.20 certification tier and volume scale, with automotive and medical device segments least price-sensitive due to qualification barriers. Cost compression in commodity polyethylene formulations is intensifying because domestic resin capacity expansions in Taiwan and South Korea are eroding legacy petroleum-based supply premiums. Consumer electronics contract manufacturers exhibit highest price sensitivity as Foxconn and Pegatron facilities consolidate vendor lists to three qualified partners per site.
Supply Chain Analysis
Metallized polyester feedstock rests on vapor deposition capacity concentrated in Taiwan, South Korea, and China, with naphtha-derived polyethylene resin drawing from Gulf Coast and Northeast Asian crackers. Aluminum foil, conductive masterbatches, and cleanroom-grade adhesives constitute critical component dependencies. Single-source vulnerability looms over metallized film laminators operating within 500 kilometers of Shanghai, Shenzhen, or Busan. Distribution runs through specialized converter networks anchored by regional packaging distributors serving defense logistics and electronics manufacturing services clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where captive metallized film deposition capacity separates premium-positioned suppliers from margin-squeezed converters. Players are pursuing backward integration into resin compounding and atomic layer deposition equipment to escape feedstock volatility.
For Market Incumbents: Deploy certification depth as a moat by accelerating ANSI/ESD S20.20 auditor capacity investments ahead of automotive and medical device qualification bottlenecks. Anchor regional converter networks near emerging Foxconn and Tata Electronics facilities in India to preempt vendor consolidation patterns. Biodegradable substrate development by European competitors threatens polyethylene volume tiers; counter with fluorine-free barrier coating partnerships ahead of ECHA enforcement windows. For New Entrants and Emerging Players: Capture Indian electronics manufacturing services white space where Bureau of Indian Standards certification timelines have delayed incumbent qualification. Target pharmaceutical cold chain convergence applications requiring dual-purpose electromagnetic and thermal insulation specifications. Establish go-to-market positioning through integrated grounding workstation bundling to mirror Vietnam and Mexico procurement patterns. For Investors and Strategic Acquirers: The window for entry favors atomic layer deposition technology specialists with FDA Title 21 CFR pharmaceutical contact material pathways. Long-term viability hinges on REACH-compliant substrate sourcing capabilities as ECHA restrictions displace conventional moisture barrier coatings. Watch for MIL-PRF-81705 Type III charge decay documentation mandates penetrating aerospace maintenance depots as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polyethylene masterbatch production insulates margins from naphtha volatility at Gulf Coast crackers. |
| Atomic Layer Deposition Capacity Expansion | Boston Scientific and Medtronic sterilization departments are qualifying ceramic-coated films for implantable packaging. |
| Fluorine-Free Barrier Certification | EU REACH Annex XVII compliance opens European pharmaceutical distribution networks ahead of enforcement windows. |
| Indian Production-Linked Incentive Localization | Foxconn and Tata Electronics operations in Karnataka require localized ESD packaging supply. |
| Defense Logistics Network Qualification | MIL-PRF-81705 Type I heat-seal documentation penetrates aerospace maintenance depots and military procurement. |
Research Methodology
Multi-period observation of semiconductor fabrication capacity buildouts, REACH regulatory filing timelines, and defense procurement contract awards anchored the trend analysis, supplemented by interviews with cleanroom logistics managers, metallized film laminator operations directors, ESD packaging procurement leads at electronics manufacturing services providers, and pharmaceutical cold chain distribution specialists. Secondary validation drew from EPA volatile organic compound guideline disclosures, ECHA Annex XVII restriction proposals, FDA Title 21 CFR pharmaceutical contact material databases, and ANSI/ESD S20.20 certification registry records. Bottom-up wafer transport packaging cycle estimates triangulated against top-down electronics manufacturing cluster output projections.
Segment-weighting applied material type, application end-use, closure mechanics, and regional regulatory framework dimensions across the modeling period. CAGRs were derived from multilayer barrier film demand elasticity relative to semiconductor node advancement cycles and defense logistics modernization programs. Forecast inputs incorporated atomic layer deposition cost curve trajectories and biodegradable substrate moisture barrier performance parity timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA perfluoroalkyl substance enforcement timing and East Asian port congestion recurrence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Packaging Market
Electrostatic Discharge (ESD) Packaging
ESD Totes Market
Electrostatic Discharge (ESD) Packaging
ESD Workstations Market
Electrostatic Discharge (ESD) Packaging
UAE Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Saudi Arabia Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
South Korea Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
Metallic Static Shielding Bags Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Flooring Market
Electrostatic Discharge (ESD) Packaging
India Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
ESD Foldable Container Market
Electrostatic Discharge (ESD) Packaging
ESD Tray Market
Electrostatic Discharge (ESD) Packaging
ESD Safe Matting Market
Electrostatic Discharge (ESD) Packaging
ESD Clamshell Market
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Packaging Market