
 Aerospace Tapes Market | 2026-2036
Aerospace Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Tapes Market Analysis
Commercial aviation is restructuring the aerospace tapes demand profile as narrow-body production rates climb and wide-body programs recover. 3M leverages its adhesive chemistry portfolio to dominate high-temperature bonding segments for engine components. Nitto Denko Corporation sustains Japanese OEM relationships through specialized polyimide tape formulations. Saint-Gobain S.A. anchors European supply chains with ceramic-coated products certified for A350 and A320 programs.
Aerospace tapes are pressure-sensitive adhesive substrates engineered to withstand temperature extremes from cryogenic conditions to sustained heat exposure above 260 degrees Celsius, serving functions of structural bonding, surface protection, and electromagnetic shielding across aircraft assemblies. Structural tapes command the largest value share due to their load-bearing role in composite-to-composite and composite-to-metal joints, while electrical tapes exhibit the fastest expansion as more-electric aircraft architectures proliferate wire harness density. Surface protection tapes generate stable aftermarket volumes through MRO touch labor, though margin pools concentrate in specialized insulation grades for engine nacelles.
FAA Part 25 flammability standards and EASA CS-25 certification requirements directly shape product development cycles by mandating specific burn-length and smoke-density thresholds for cabin and cargo bay materials. China's CAAC airworthiness regulations increasingly influence tape qualification pathways as COMAC C919 production scales. Stakeholders must monitor evolving OEM qualification timelines and dual-source requirements as supply chain resilience clauses harden across Boeing and Airbus purchasing agreements.
Market Dynamics
Composite airframe production rates at Boeing and Airbus final assembly lines are compressing qualification timelines for pressure-sensitive adhesive suppliers. OEM dual-source mandates and FAA Part 25 flammability enforcement are forcing tape manufacturers to replicate certification packages across multiple production sites.
Growth Catalysts
- Narrow-body production surge:Airbus A320 and Boeing 737 MAX output targets are pulling structural bonding tape volumes at rates exceeding wide-body programs by substantial margins.
- FAA Part 25 Amendment 25-116:Updated burn-length requirements for cabin interiors are mandating flame-retardant tape upgrades across retrofit fleets and new production.
- Silicone adhesive chemistry:Advanced formulations rated for sustained 300°C exposure are penetrating engine nacelle applications previously served by mechanical fasteners.
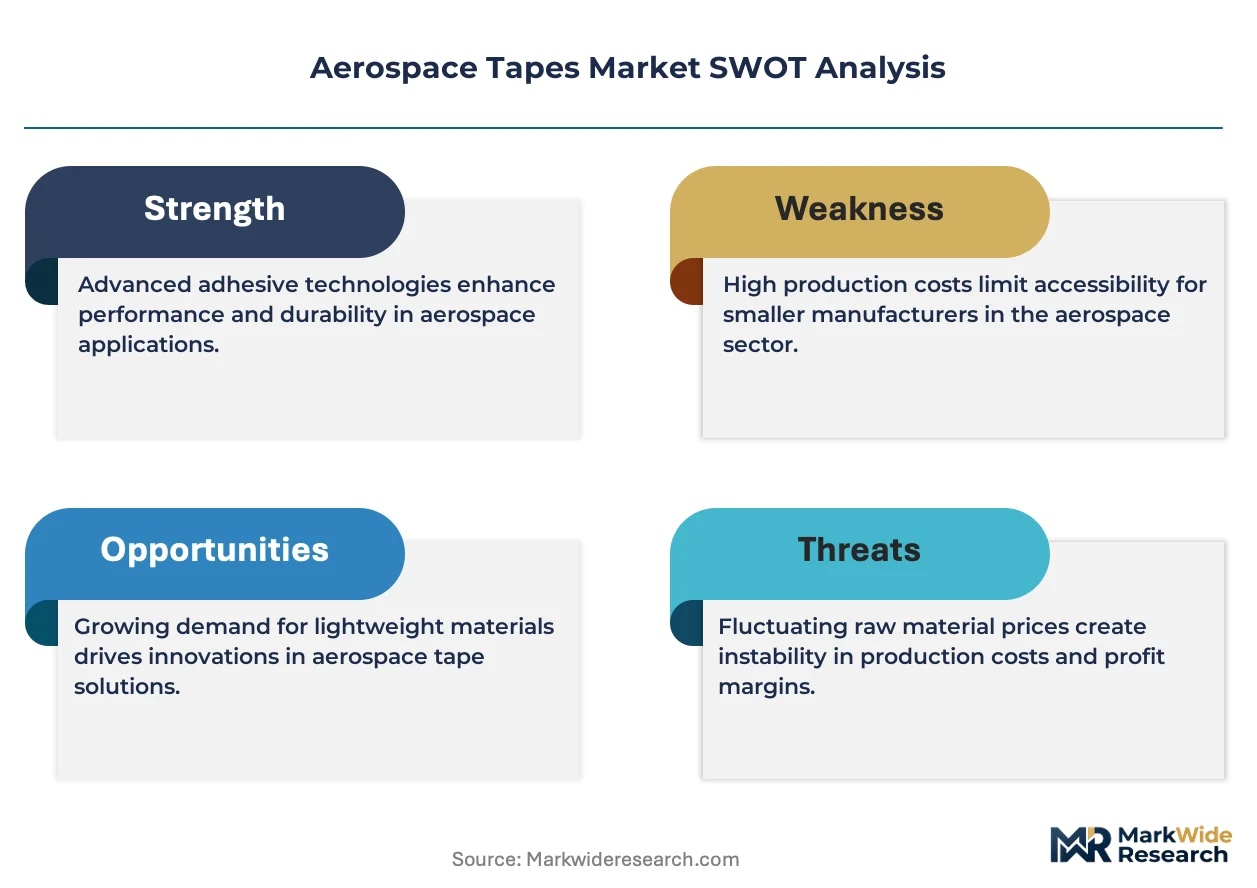
Market Restraints
- Polyimide film supply concentration:Japanese and Korean substrate producers control over seventy percent of aerospace-grade supply, exposing tape converters to allocation risk.
- Dual-source qualification costs:Boeing and Airbus purchasing agreements require redundant supplier validation, doubling certification expenditure without volume guarantees.
- Fluoropolymer release liner pricing:PTFE-coated backing materials have experienced sustained input cost pressure from semiconductor industry demand competition.
Strategic Opportunities
- Urban air mobility platforms:Electric vertical take-off aircraft manufacturers in Germany and the United States are specifying lightweight bonding tapes for rotor blade assemblies.
- REACH SVHC compliance services:European tape distributors can capture margin by pre-qualifying adhesive formulations against ECHA substance restrictions for OEM customers.
- Wire harness density expansion:More-electric aircraft architectures at COMAC and Mitsubishi Regional Jet programs are creating demand for electromagnetic shielding tape categories.
Industry Challenges
- Adhesive chemist talent scarcity:Formulation expertise combining high-temperature polymer science with FAA certification experience concentrates at a handful of regional clusters.
- Production part approval process timelines:FAA PMA and EASA ETSO certification cycles for modified tape constructions routinely extend eighteen to twenty-four months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Tapes Market |
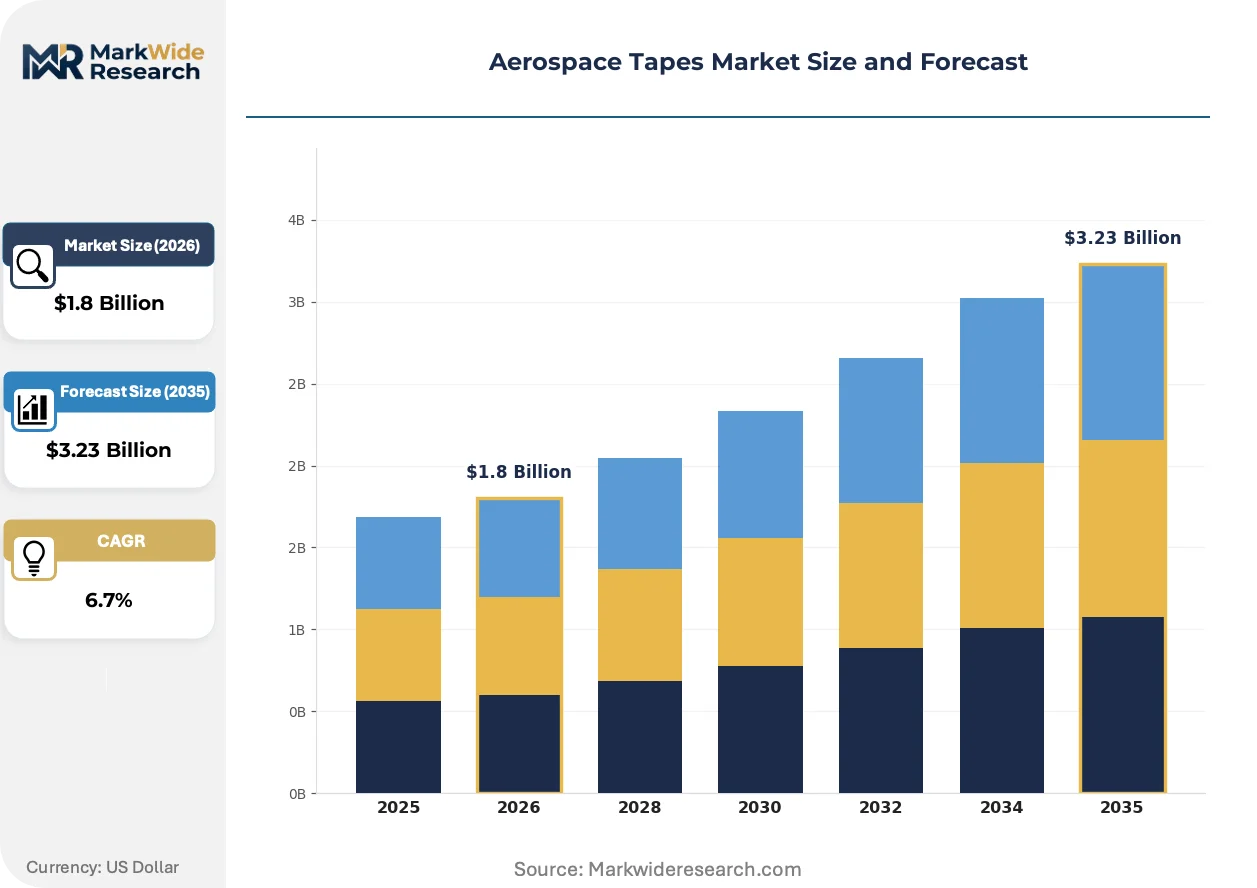
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural Tapes, Surface Protection Tapes, Electrical Tapes, Insulation Tapes Application: Interior Applications, Exterior Applications, Engine Components, Cabin Components Material: Polyimide, Aluminum Foil, Fabric, Adhesive Coated End User: Aerospace OEMs, MRO Providers, Aircraft Manufacturers, Space Agencies |
| Companies Covered | 3M, Nitto Denko Corporation, Avery Dennison Corporation, Tesa SE, Scapa Group plc, Intertape Polymer Group Inc., Saint-Gobain S.A., Berry Global Inc., Shurtape Technologies LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Tapes Market Emerging Trajectories
Adhesive substrate convergence with smart manufacturing systems is redefining how tape performance data flows back to OEM quality departments. Real-time cure monitoring and digital batch records are becoming baseline requirements rather than differentiators.
Thermally conductive acrylic formulations are expanding into battery thermal management interfaces for hybrid-electric propulsion systems. Tier-two suppliers at Lilium and Archer Aviation are specifying these tapes for cell-to-cell bonding in lithium-ion packs. The technology is expanding into applications previously reserved for liquid gap fillers, compressing the thermal interface material competitive set.
EU REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing reformulation of traditional release coatings used in tape manufacturing. Industrial consequence includes eighteen-month validation cycles for replacement silicone-based release liners. German and French aerospace clusters are most affected, with tape converters accelerating partnerships with regional chemical formulators to secure compliant supply.
Airline procurement departments are consolidating MRO consumables purchasing through integrated supply contracts with global distributors. Legacy spot-buying through local job shops is contracting at US and European carrier maintenance bases. China Eastern and Lufthansa Technik have pioneered multi-year tape supply agreements bundling volume commitments with technical support services, compressing distributor margins while locking in supplier relationships.
Aerospace Tapes Market Segmentation
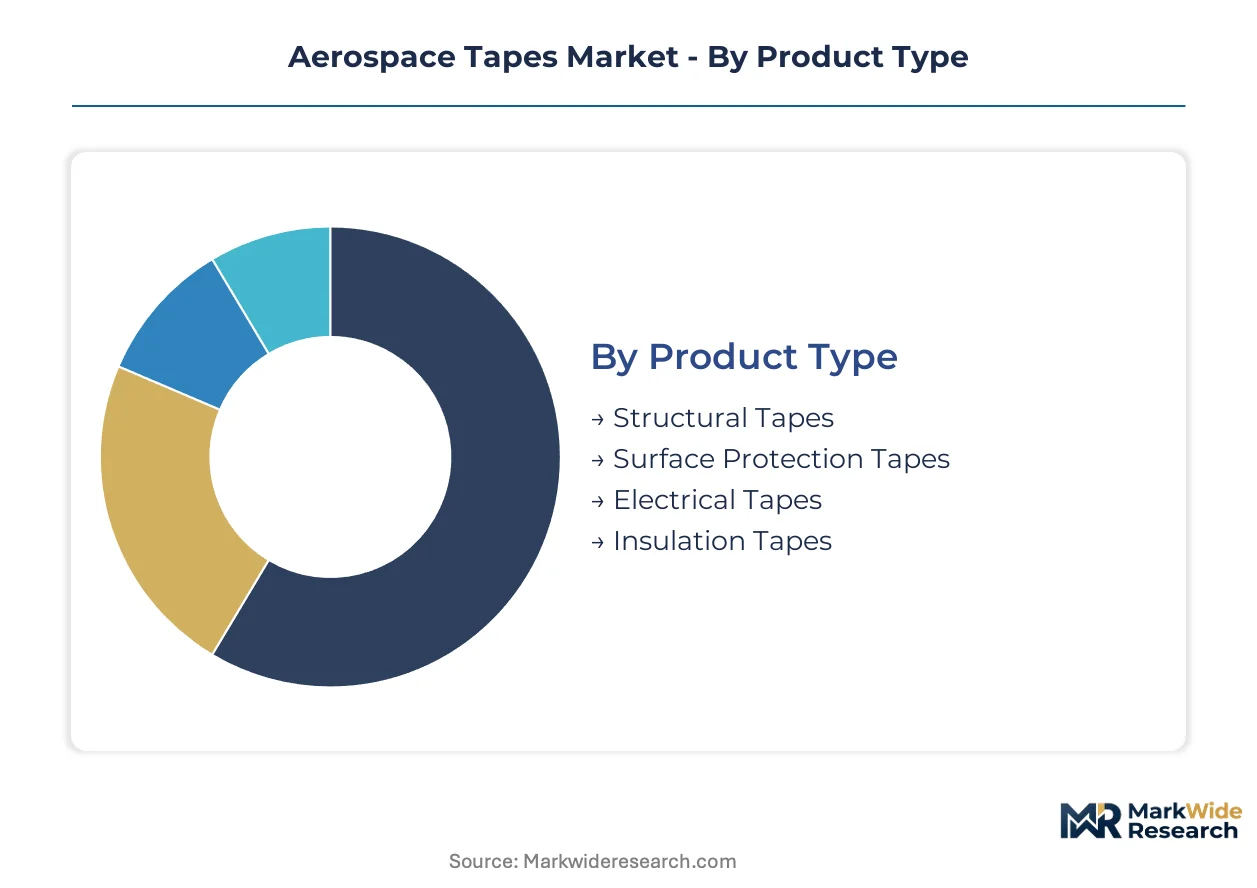
Aerospace tape procurement follows distinct technical hierarchies where certification grade, thermal rating, and substrate chemistry determine supplier selection. Each segmentation dimension reveals divergent margin structures and qualification barriers that shape competitive positioning.
Product Type:
Application criticality drives tape specification, with load-bearing and safety-rated categories commanding premium pricing and extended qualification cycles.
- Structural Tapes:High-strength adhesive substrates engineered for composite-to-composite and composite-to-metal bonding in primary airframe assemblies. Demand concentrates at Boeing and Airbus final assembly lines in the United States and Germany, where narrow-body production rates are compressing supplier lead times.
- Electrical Tapes:Dielectric-grade pressure-sensitive films for wire harness insulation and electromagnetic shielding. More-electric aircraft architectures at COMAC and Mitsubishi Regional Jet programs are accelerating specification of these materials for power distribution systems.
- Surface Protection Tapes:Temporary barrier films applied during manufacturing and MRO operations to prevent substrate damage.
- Insulation Tapes:Thermal and acoustic barrier products for engine nacelles and exhaust zones.
Volume sits with Structural Tapes; growth tilts toward Electrical Tapes.
Application:
Regulatory exposure varies sharply by aircraft zone, with cabin and engine applications subject to divergent FAA Part 25 and EASA CS-25 certification pathways.
- Interior Applications:Flame-retardant tapes for cabin panels, galleys, and seating assemblies governed by burn-length and smoke-density mandates. Retrofit fleet upgrades across United States and European carriers are sustaining aftermarket demand as FAA Amendment 25-116 enforcement tightens.
- Engine Components:High-temperature silicone and polyimide formulations rated for sustained exposure above 260°C in nacelles and thrust reversers. German and French aerospace clusters anchor European supply for A350 and A320 powerplant programs.
- Exterior Applications:Weather-resistant bonding and sealing tapes for control surfaces and aerodynamic fairings.
- Cabin Components:Decorative and functional tapes for lavatories, overhead bins, and partition walls.
Procurement volume clusters in Interior Applications; steepest expansion trajectory belongs to Engine Components.
Material:
Substrate sourcing geography directly determines supply security, with aerospace-grade polyimide film subject to pronounced concentration risk.
- Polyimide:Aromatic polymer films delivering thermal stability across cryogenic to 400°C operational windows. Japanese and Korean substrate producers control dominant share of aerospace-qualified supply, exposing tape converters to allocation constraints during demand surges.
- Adhesive Coated:Custom-formulated pressure-sensitive chemistries including acrylic, silicone, and rubber-based systems. Formulation expertise concentrates in regional clusters around Cincinnati, Tokyo, and Lyon where FAA and EASA certification experience has accumulated.
- Aluminum Foil:Conductive barrier layers for EMI shielding and thermal management applications.
- Fabric:Woven substrate tapes for abrasion-resistant surface protection and temporary holding.
Polyimide commands the value pool; Adhesive Coated categories are climbing the fastest on specialty formulation premiums.
End User:
Customer scale and procurement integration level create distinct service requirements and contract structures across the demand base.
- Aerospace OEMs:Boeing, Airbus, and COMAC final assembly operations specifying qualified materials through multi-year supply agreements with technical support obligations. Dual-source mandates are forcing tape manufacturers to replicate certification packages across redundant production sites.
- MRO Providers:Lufthansa Technik and China Eastern maintenance bases consolidating consumables purchasing through integrated supply contracts bundling volume commitments with logistics services.
- Aircraft Manufacturers:Tier-one aerostructures suppliers producing subassemblies for OEM integration.
- Space Agencies:NASA and ESA programs with specialized cryogenic and vacuum-rated tape requirements for launch vehicle and satellite applications.
Revenue concentration rests with Aerospace OEMs; margin expansion favors MRO Providers on aftermarket service attach rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates aerospace tape consumption through Boeing's final assembly lines, while production of critical polyimide substrates remains concentrated in Japan and South Korea. This geographic split between demand and supply creates qualification bottlenecks for adhesive converters serving OEM dual-source mandates.
United States
Boeing's 737 MAX and 777X production rates in Washington and South Carolina are pulling structural bonding tape volumes at narrow-body scales. FAA Part 25 Amendment 25-116 enforcement is mandating flame-retardant upgrades across retrofit fleets. Cincinnati anchors adhesive chemistry expertise where formulation specialists accumulate FAA certification experience.
Germany
Airbus A320 and A350 final assembly in Hamburg and Toulouse-adjacent supply chains drives European tape demand. EASA CS-25 certification requirements shape product development cycles alongside REACH SVHC compliance pressures. The Bavarian aerospace cluster around Munich hosts tape converters pre-qualifying formulations against ECHA substance restrictions.
China
COMAC C919 production scaling in Shanghai is creating qualification pathways for domestic and international tape suppliers. CAAC airworthiness regulations increasingly influence tape specification alongside FAA and EASA standards. The Yangtze River Delta concentration of aerostructures suppliers is compressing lead times for pressure-sensitive adhesive deliveries.
Japan
Japanese substrate producers control dominant share of aerospace-grade polyimide film supply, exposing global tape converters to allocation risk. METI industrial policy supports advanced materials development for more-electric aircraft architectures. Tokyo and Osaka regional clusters concentrate adhesive formulation expertise serving Mitsubishi Regional Jet programs.
France
Safran and Airbus powerplant programs in the Toulouse-Blagnac corridor sustain demand for high-temperature silicone formulations. EASA certification timelines for modified tape constructions extend eighteen to twenty-four months, hardening supplier relationships. The Occitanie aerospace cluster anchors European supply for engine nacelle insulation grades.
Aerospace Tapes Market Vendor Landscape
Top-tier vendors anchor premium certification tiers, while mid-scale converters occupy specialized formulation niches. The vendor base stratifies across adhesive chemistry capabilities, with polyimide substrate access determining supply security. Three archetypes dominate: diversified materials conglomerates with aerospace divisions, specialized tape converters with OEM qualification depth, and regional distributors bundling technical services with volume commitments. Competitive moves center on dual-site certification replication and REACH compliance service bundling.
Within the diversified materials tier, 3M and Saint-Gobain S.A. exemplify players with adhesive chemistry portfolios spanning high-temperature bonding segments. Nitto Denko Corporation represents the specialized converter archetype, with Japanese substrate relationships supporting polyimide tape formulation depth. These three companies occupy positions where certification accumulation and geographic proximity to OEM final assembly lines reinforce supplier status.
| Leading Market Players |
|---|
| 3M |
| Nitto Denko Corporation |
| Avery Dennison Corporation |
| Tesa SE |
| Scapa Group plc |
| Intertape Polymer Group Inc. |
| Saint-Gobain S.A. |
| Berry Global Inc. |
| Shurtape Technologies LLC |
| Others |
Supply Flow & Price Mechanics
Polyimide film spot price indices cascade through aerospace tape value chains, compressing margins for converters locked into long-term OEM supply contracts while amplifying pricing power for Japanese and Korean substrate producers who control dominant supply share.
Pricing Analysis
Margin tightening in standard-grade structural tapes reflects fluoropolymer release liner cost pressure from competing semiconductor industry demand. Three-tier pricing structure across aerospace-qualified, industrial-grade, and commercial-adhesive levels separates FAA-certified formulations from uncertified alternatives. Cost-down pressure on European converters accelerates because REACH SVHC compliance services require eighteen-month reformulation cycles. MRO procurement departments exhibit highest price sensitivity through consolidated integrated supply contracts, while engine nacelle insulation grades maintain lowest sensitivity due to thermal performance requirements.
Supply Chain Analysis
Direct-to-OEM channels handle qualification-intensive demand from Boeing and Airbus final assembly lines, while distributor-led routes serve fragmented MRO touch-labor procurement. Raw material sourcing concentrates in Japan and South Korea for polyimide substrates, the United States for silicone adhesive polymers, and Germany for ceramic coating chemistries. Aerospace-grade polyimide film supply rests on fewer than five qualified substrate producers, creating single-source vulnerability during demand surges. Distribution runs through certified converter networks that replicate FAA PMA and EASA ETSO packages across redundant production sites to satisfy dual-source mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aerospace tape supply remains structurally constrained by polyimide substrate capacity, propping pricing power for qualified converters while squeezing margins for dependent downstream players.
For Market Incumbents: Lock in polyimide substrate supply through captive partnerships with Japanese producers before allocation risk intensifies. Deepen backward integration into silicone adhesive polymer production to deflect fluoropolymer input cost volatility. Prioritize dual-site certification replication across Cincinnati and Lyon facilities to satisfy Boeing and Airbus purchasing agreement resilience clauses. For New Entrants and Emerging Players: Thermally conductive acrylic formulations for battery thermal management interfaces offer technology-first wedge into electric vertical take-off aircraft programs at Lilium and Archer Aviation. Target urban air mobility rotor blade bonding specifications where qualification timelines remain shorter than commercial aviation pathways. Pursue REACH SVHC pre-qualification service bundling for European OEM customers as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized tape converters with EASA certification depth in the Bavarian aerospace cluster around Munich. Long-term viability hinges on adhesive chemist talent accumulation and OEM relationship duration rather than asset intensity. Watch COMAC C919 production rate announcements as inflection indicator for Chinese domestic supplier qualification pathway expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Site Certification Replication | Boeing and Airbus dual-source mandates force redundant FAA PMA validation across Cincinnati and Lyon facilities. |
| REACH SVHC Pre-Qualification Services | Bavarian converters capture margin by bundling ECHA substance restriction compliance with adhesive formulations. |
| Silicone Adhesive Chemistry Expansion | Advanced formulations rated for 300°C sustained exposure displace mechanical fasteners in engine nacelle applications. |
| Urban Air Mobility Specification Capture | German and United States electric vertical take-off aircraft manufacturers specify lightweight bonding tapes for rotor assemblies. |
| Polyimide Substrate Supply Partnership | Captive relationships with Japanese producers defend against allocation risk during narrow-body production surges. |
Methodological Framework
FAA airworthiness directives, EASA certification databases, and aerospace OEM procurement disclosures formed the secondary backbone for this analysis. Primary fieldwork incorporated formulation chemists at adhesive converters, procurement leads at Boeing and Airbus tier-one suppliers, MRO consumables managers at Lufthansa Technik and China Eastern, and regulatory affairs specialists navigating CAAC qualification pathways. Bottom-up tape volume estimates by aircraft program and top-down adhesive industry revenue analysis were triangulated against customs trade data for polyimide film and silicone polymer imports.
Historical production rate analysis at commercial aircraft final assembly lines established baseline demand trajectories across the projection horizon. Segmentation modeling incorporated product type, application zone, substrate chemistry, and end-user procurement integration level. CAGRs were derived from program-specific build rate forecasts and content-per-aircraft estimates for structural bonding, electrical insulation, and surface protection tape categories. Wire harness density expansion in more-electric architectures and battery thermal management interface adoption in hybrid-electric propulsion systems served as demand swing factors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under COMAC C919 production delays or accelerated REACH Annex XVII restriction expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Tape Dispenser Market
Tapes
Hydrocolloid Tapes Market
Tapes
Edge Band Tapes Market
Tapes
Sterilization Tape Market
Tapes
India Masking Tapes Market
Tapes
Void Pattern Tamper-Evident Tapes Market
Tapes
Global Seam Sealing Tapes Market
Tapes
Strapping Supplies Market
Tapes
Pouch Tapes Market
Tapes
Industrial Tapes Market
Tapes
Acetate Cloth Tape Market
Tapes
Umbilical Tapes Market
Tapes
Splicing Tapes Market
Tapes
Medical Tapes Market
Tapes
Dry Wall Tapes Market
Tapes
UV Cured Acrylic Foam Tapes Market