
 Integrated 3D Radar Market | 2026-2036
Integrated 3D Radar Market Size, Share, and Industry Trends Forecast 2026-2036
Integrated 3D Radar Market Foresight
Defense procurement consolidation among NATO member states is recalibrating supplier relationships toward multi-year framework agreements. RTX Corporation leverages its gallium nitride foundry investments to anchor long-range phased array contracts. Northrop Grumman Corporation sustains technology leadership in airborne early warning through continuous R&D outlays. Thales Group competes across European ground-based radar tenders with localized production facilities.
Integrated 3D radar combines active electronically scanned arrays with digital beamforming to generate volumetric target tracking across azimuth, elevation, and range dimensions, typically operating in X-band through Ku-band frequencies for precision resolution. The primary purpose spans military air defense, automotive collision avoidance, and maritime navigation safety. Long-range radar and phased array technology occupy the dominant revenue positions given defense budget prioritization. Ground-based radar and solid-state radar represent the fastest-expanding categories as distributed sensor networks replace legacy rotating platforms. Frequency modulated continuous wave radar captures growing automotive share where cost sensitivity favors semiconductor-based architectures.
The US Department of Defense, EDA, and Japan's METI each impose distinct certification regimes that shape product roadmaps and market access conditions. FCC spectrum allocations in the US and EU Green Deal-linked defense procurement standards are tightening electromagnetic compatibility requirements while favoring lower-power solid-state designs. Stakeholders must monitor evolving dual-use export control classifications that could restrict technology transfer between allied defense industrial bases.
Market Dynamics
Defense procurement consolidation among NATO member states is recalibrating supplier relationships toward multi-year framework agreements, compressing vendor margins while locking in volume commitments for gallium nitride-based phased array systems.
Growth Catalysts
- Automotive ADAS mandates:NHTSA collision-avoidance rules and EU Green Deal-linked vehicle safety standards are mandating 77-81 GHz radar integration across passenger vehicle platforms.
- Gallium nitride semiconductor maturation:Solid-state transmitter advances are extending detection ranges while compressing unit costs for ground-based surveillance deployments.
- Counter-drone system proliferation:Distributed sensor networks for low-altitude threat detection are displacing legacy rotating platforms across military and critical infrastructure installations.
Market Restraints
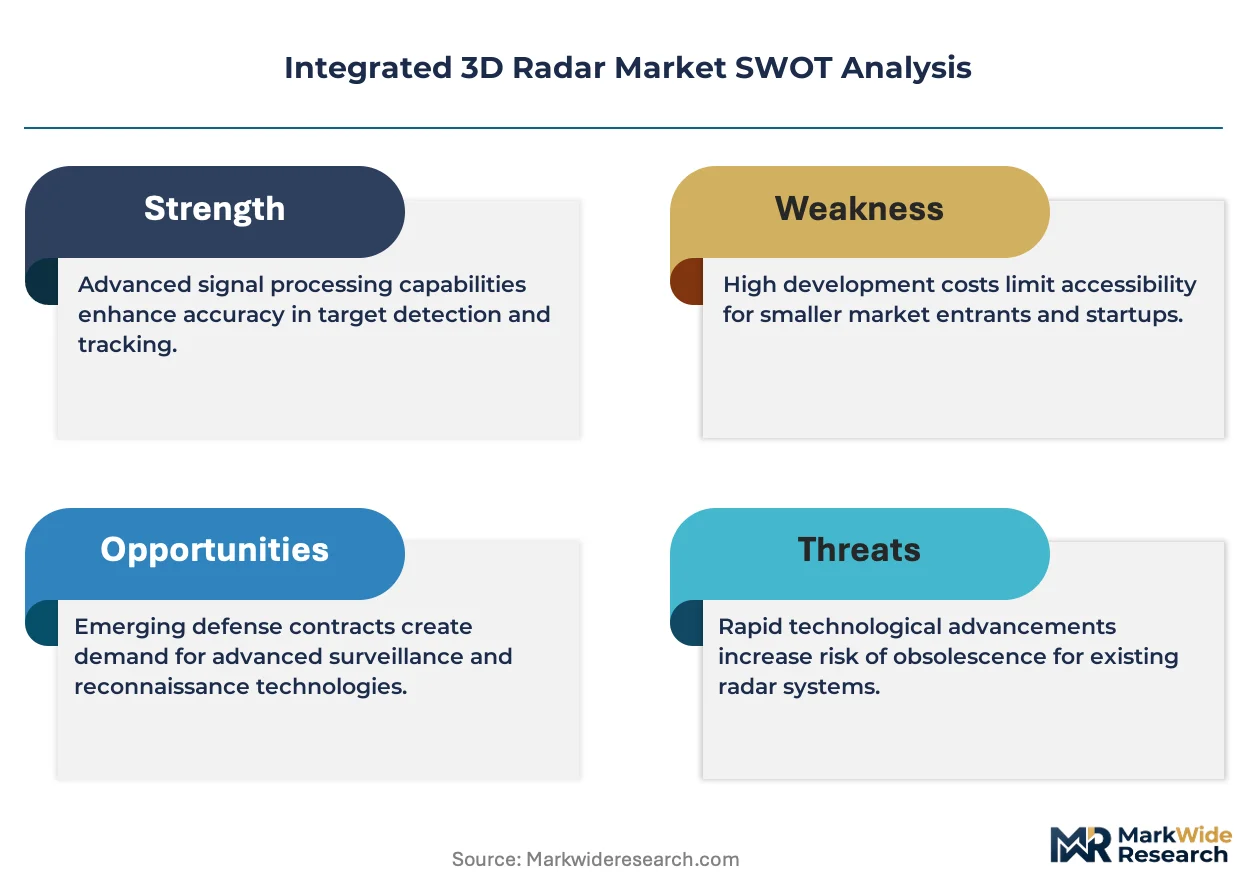
- Rare earth supply concentration:Gallium and germanium refining capacity clusters in China, exposing Western defense contractors to export control volatility and dual-use classification friction.
- Electromagnetic spectrum congestion:FCC and EDA frequency allocation disputes are compressing available bandwidth for X-band through Ku-band operations in urban corridors.
- Legacy platform lock-in:Rotating mechanical radar installations persist in maritime navigation, delaying solid-state refresh cycles due to certification inertia and crew retraining costs.
Strategic Opportunities
- Frequency modulated continuous wave convergence:Semiconductor-based FMCW architectures are penetrating automotive collision avoidance where cost sensitivity favors silicon integration over III-V compounds.
- Japan METI localization incentives:Domestic production requirements for critical defense components are creating captive demand for localized gallium nitride foundry capacity.
- Maritime autonomous navigation:Uncrewed surface vessel proliferation is generating demand for compact, solid-state radar with software-defined beamforming for harbor and coastal operations.
Industry Challenges
- Phased array calibration expertise:Active electronically scanned array manufacturing requires specialized RF engineering talent concentrated at a handful of defense primes and semiconductor foundries.
- Dual-use export control complexity:Wassenaar Arrangement classifications and national implementation variations are fragmenting technology transfer pathways between allied industrial bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Integrated 3D Radar Market |
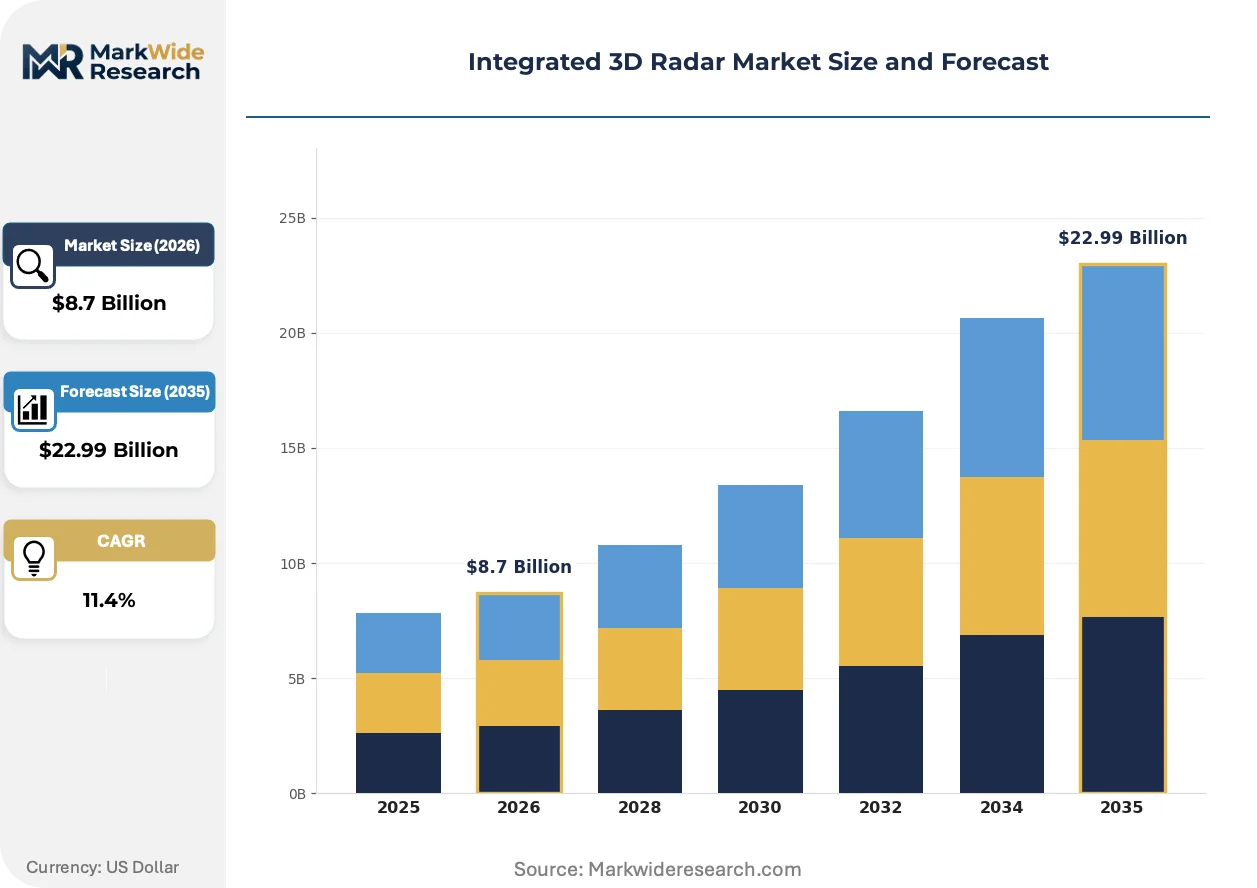
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Long-Range Radar, Short-Range Radar, Medium-Range Radar, Ground-Based Radar Application: Defense, Aerospace, Automotive, Marine Technology: Solid-State Radar, Phased Array Radar, Frequency Modulated Continuous Wave Radar, Doppler Radar End User: Government Agencies, OEMs, Research Institutions, System Integrators |
| Companies Covered | RTX Corporation, Northrop Grumman Corporation, Thales Group, BAE Systems plc, Lockheed Martin Corporation, Leonardo S.p.A., L3Harris Technologies Inc., Saab AB, Hensoldt AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Integrated 3D Radar Market Shifts & Advancements
Digital beamforming architectures are displacing analog hardware across surveillance and automotive applications, compressing development cycles while enabling software-defined performance upgrades without hardware replacement.
GaN-on-SiC transistor technology is decentralizing transmitter manufacturing by enabling foundry-scale production of high-power density modules previously requiring captive defense facility fabrication. Automotive Tier-1 suppliers are integrating these components into 4D imaging radar for Level-3 autonomous systems. The shift is compressing supplier tiers from specialized defense subcontractors to commercial semiconductor vendors.
EU Green Deal procurement standards are tightening electromagnetic compatibility requirements while mandating lower-power solid-state designs across defense and civilian applications. EDA framework agreements now embed carbon footprint thresholds for radar system manufacturing. German and French ground-based radar tenders are prioritizing localized production facilities to satisfy domestic content rules.
Long-term service agreements are displacing transactional equipment sales across NATO defense procurement, unbundling hardware from software maintenance and algorithm update subscriptions. Prime contractors are retaining ownership of digital beamforming IP while leasing processing capacity to military operators. This model is most visible in US Department of Defense multi-year indefinite delivery contracts for counter-drone sensor networks.
Integrated 3D Radar Market Segmentation
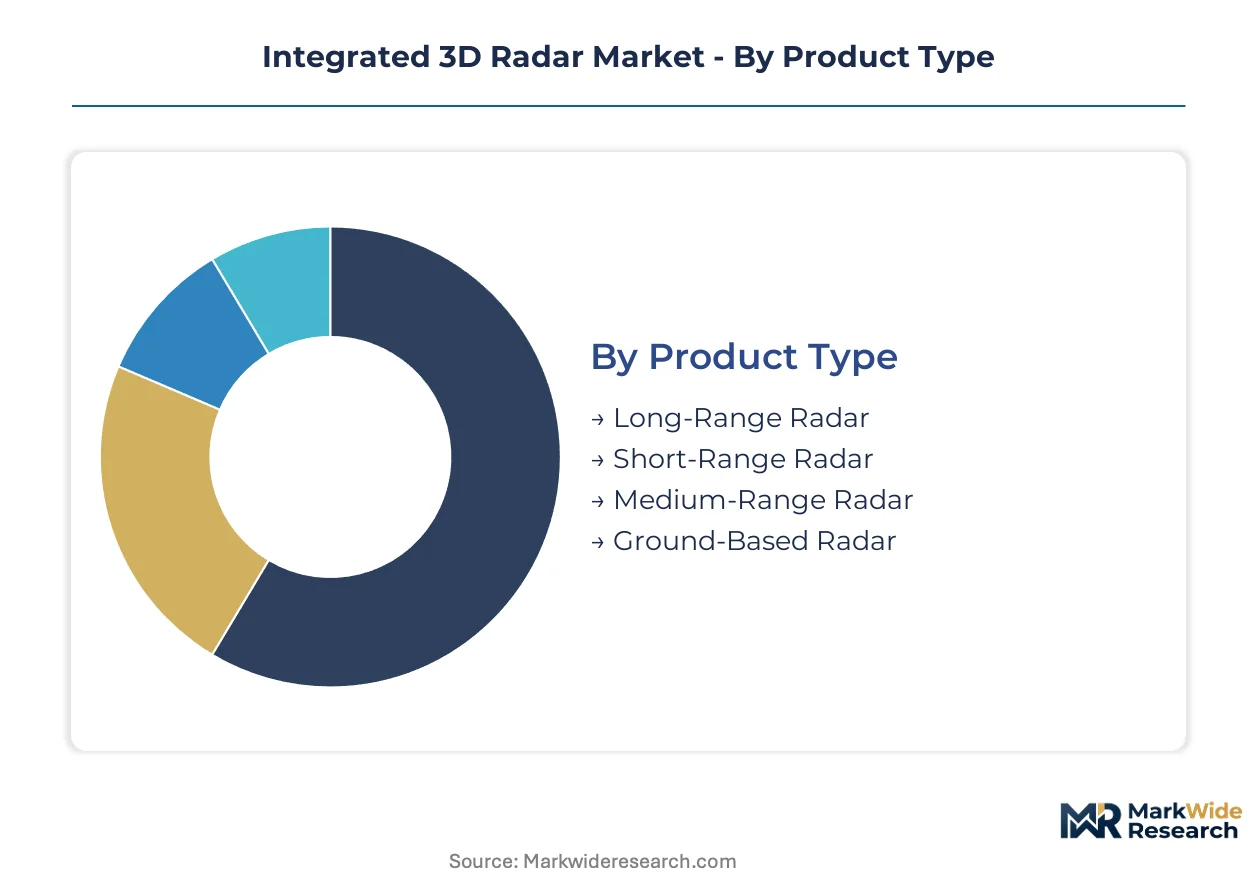
Defense procurement agencies prioritize detection range and target resolution when specifying 3D radar requirements. Automotive OEMs emphasize cost per unit and semiconductor integration. Maritime operators balance solid-state reliability against legacy platform compatibility.
Product Type:
Defense procurement agencies prioritize detection range and target resolution when selecting radar configurations for air defense and surveillance missions.
- Long-Range Radar:Active electronically scanned arrays operating in X-band through Ku-band frequencies achieve precision tracking at extended distances. NATO ground-based air defense programs in Germany and Poland are concentrating procurement on these systems to counter hypersonic threats and low-observable aircraft.
- Ground-Based Radar:Distributed sensor networks replace legacy rotating platforms for counter-drone and perimeter surveillance applications. Japan's METI localization incentives are accelerating domestic production of solid-state variants for critical infrastructure protection around Tokyo and Osaka industrial corridors.
- Short-Range Radar:Compact semiconductor-based units serve automotive collision avoidance and urban surveillance where space constraints dominate.
- Medium-Range Radar:Balanced performance specifications address maritime navigation and regional air traffic management requirements.
Long-Range Radar leads on scale; Ground-Based Radar leads on momentum.
Application:
Regulatory mandates and threat environments shape deployment velocity across end-use sectors.
- Defense:Phased array systems with gallium nitride transmitters anchor NATO multi-year framework agreements. The US Department of Defense and European Defence Agency are consolidating vendor relationships toward indefinite delivery contracts for counter-drone sensor networks.
- Automotive:NHTSA collision-avoidance rules and EU vehicle safety standards mandate 77-81 GHz radar integration across passenger platforms. German and Japanese OEMs are driving 4D imaging radar adoption for Level-3 autonomous systems.
- Aerospace:Airborne early warning platforms require lightweight, high-power density arrays for extended loiter missions.
- Marine:Uncrewed surface vessel proliferation generates demand for compact solid-state radar with software-defined beamforming in harbor and coastal zones.
Defense commands the largest committed budgets; Automotive is expanding most quickly.
Technology:
Semiconductor architecture choices determine manufacturing scalability and performance ceilings.
- Solid-State Radar:GaN-on-SiC transistor technology enables foundry-scale production of high-power density modules. Foundry investments by RTX Corporation and defense primes are compressing unit costs while extending detection ranges for ground-based surveillance.
- Frequency Modulated Continuous Wave Radar:Silicon-based architectures penetrate cost-sensitive automotive collision avoidance where III-V compound semiconductors prove economically prohibitive. Tier-1 suppliers are integrating these components into mass-market ADAS platforms.
- Phased Array Radar:Digital beamforming architectures displace analog hardware across military surveillance applications.
- Doppler Radar:Legacy implementations persist in weather monitoring and basic motion detection where upgrade cycles lag.
Solid-State Radar dominates procurement volume; Frequency Modulated Continuous Wave Radar shows the steepest expansion trajectory.
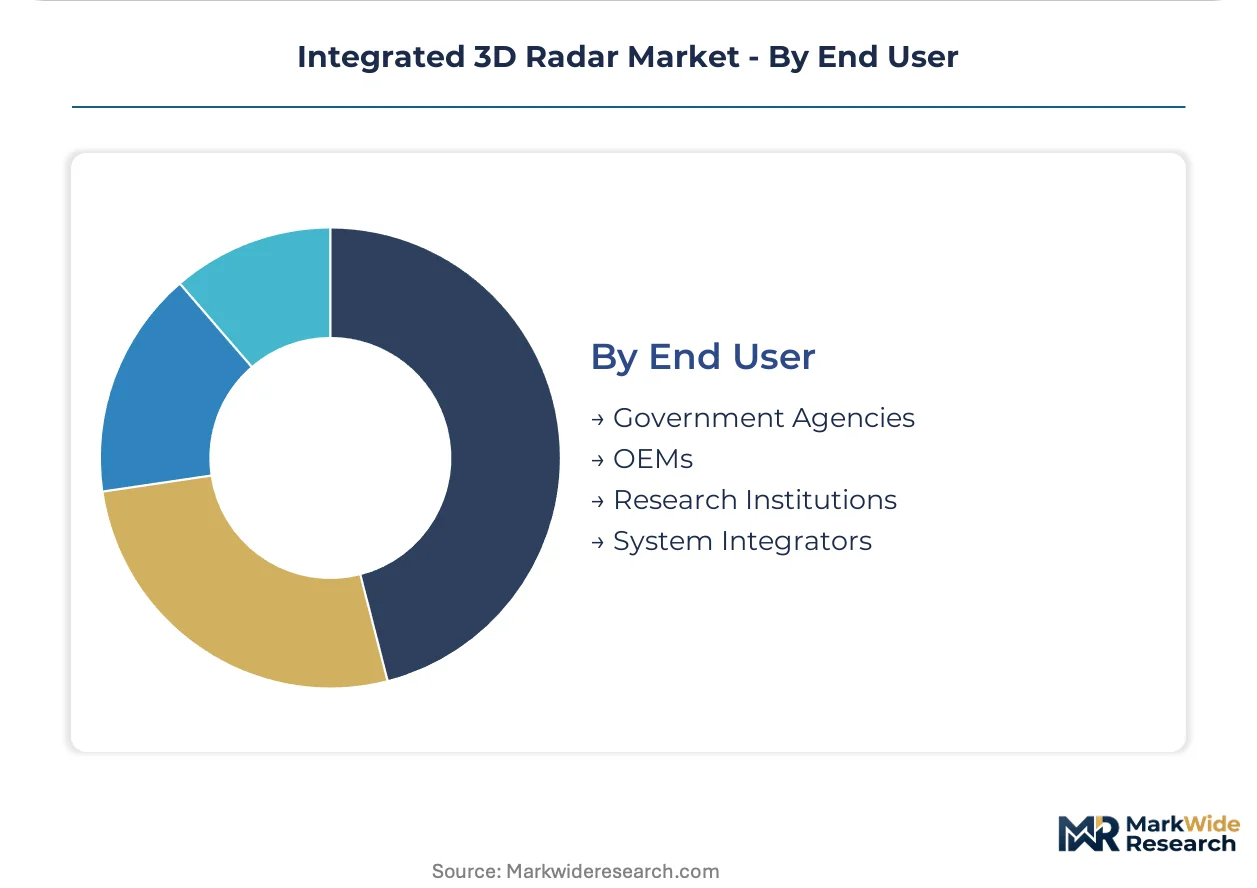
End User:
Contracting mechanisms and IP ownership structures vary sharply across buyer categories.
- Government Agencies:The US Department of Defense, Japan's METI, and European Defence Agency impose distinct certification regimes that shape product roadmaps. Long-term service agreements now unbundle hardware from software maintenance and algorithm update subscriptions.
- OEMs:Automotive and aerospace manufacturers demand captive supply arrangements for gallium nitride components to secure volume commitments.
- System Integrators:Defense subcontractors specialize in phased array calibration and RF engineering for complex installations.
- Research Institutions:Academic and national laboratory partnerships drive digital beamforming algorithm development under dual-use export control constraints.
Government Agencies anchor committed revenue; OEMs are gaining procurement influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement intensity diverges sharply between the United States and Germany, with Washington prioritizing counter-drone networks and Berlin accelerating ground-based air defense modernization through multi-year framework agreements.
United States
The US Department of Defense consolidates vendor relationships toward indefinite delivery contracts for gallium nitride-based phased array systems. FCC spectrum allocations in the 77-81 GHz band shape automotive radar deployment timelines. RTX Corporation's foundry investments in Massachusetts and Texas anchor domestic transmitter manufacturing capacity.
Germany
The European Defence Agency embeds carbon footprint thresholds in ground-based radar tenders, favoring lower-power solid-state designs. German defense procurement prioritizes localized production facilities to satisfy domestic content rules. Industrial clusters in Bavaria and Baden-Württemberg concentrate phased array calibration expertise for NATO air defense programs.
Japan
METI localization incentives accelerate domestic production of solid-state variants for critical infrastructure protection. Japan's national pharmaceutical regulator framework does not apply; instead, defense procurement standards mandate captive supply arrangements for gallium nitride components. Tokyo and Osaka industrial corridors host concentrated demand for counter-drone sensor networks.
United Kingdom
BAE Systems plc and defense primes anchor airborne early warning platform requirements through continuous R&D outlays. UK procurement agencies participate in NATO multi-year framework agreements while maintaining distinct certification regimes. Southwest England and Greater London concentrate system integration capabilities for maritime navigation safety applications.
South Korea
MFDS standards do not govern this sector; instead, national defense procurement prioritizes lightweight, high-power density arrays for extended loiter missions. Seoul Capital Area and Busan-Ulsan industrial zones concentrate semiconductor packaging expertise for automotive 4D imaging radar. Domestic OEMs drive 77-81 GHz integration across passenger vehicle platforms.
Integrated 3D Radar Market Competitive Landscape
United States producers anchor the premium defense tier; European specialists hold ground-based surveillance and maritime navigation positions. The vendor structure concentrates around five to seven primes with captive gallium nitride foundry capacity or long-term supply agreements. Three archetypes dominate: vertically integrated defense conglomerates with semiconductor fabrication assets; system integrators specializing in phased array calibration; and automotive Tier-1 suppliers pivoting from silicon to III-V compound architectures. Competitive moves center on multi-year framework agreement capture and foundry-scale GaN-on-SiC capacity expansion.
Within the defense prime tier, RTX Corporation and Northrop Grumman Corporation exemplify vertically integrated producers with captive transmitter manufacturing. Thales Group occupies a position bridging European ground-based tenders with localized production strategies. These three anchors represent contrasting geographic and structural approaches to gallium nitride supply security.
| Leading Market Players |
|---|
| RTX Corporation |
| Northrop Grumman Corporation |
| Thales Group |
| BAE Systems plc |
| Lockheed Martin Corporation |
| Leonardo S.p.A. |
| L3Harris Technologies Inc. |
| Saab AB |
| Hensoldt AG |
| Others |
Supply & Pricing Matrix
NATO defense procurement agencies concentrate buying power through multi-year framework agreements, locking in contract-based long-term offtake structures that compress vendor margins while securing gallium nitride transmitter volume. This buyer concentration enables aggressive price negotiations across phased array system tiers.
Pricing Analysis
Capacity additions in the United States and Japan are reshaping price floors for solid-state radar modules as RTX Corporation and domestic foundries expand GaN-on-SiC fabrication. Three-tier pricing structure across premium, standard, and economy levels separates military-specification arrays from commercial automotive units and legacy rotating platforms. Price differentiation centers on certification grade—FCC Part 90 defense allocations versus automotive UN ECE R79 compliance—and volume scale under NATO indefinite delivery contracts. Cost compression in the automotive tier is intensifying because silicon-based FMCW architectures displace III-V compounds. Government agencies exhibit lowest price sensitivity given mission-critical requirements, while Tier-1 automotive suppliers face acute pressure from OEM cost-down programs.
Supply Chain Analysis
Regional distribution centers in Texas, Bavaria, and Tokyo prefecture anchor hub-and-spoke patterns for gallium nitride transistor modules and phased array subassemblies. Geographic supply concentration clusters in the United States, Germany, and Japan for defense-grade fabrication, with Taiwan and South Korea feeding commercial semiconductor inputs. Raw material dependencies center on high-purity gallium substrates, silicon carbide wafers, and rare earth magnetic components for antenna positioning systems. Single-source vulnerability persists at the GaN epitaxy layer where two foundries control Western defense-qualified capacity. Distribution runs through prime contractor logistics networks rather than open market channels, reflecting security-cleared handling requirements for active electronically scanned array components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Integrated 3D Radar Market compounds steadily through defense procurement consolidation that locks in decade-long sensor network refresh cycles across NATO installations.
For Market Incumbents: Anchor multi-year framework agreement capture through captive gallium nitride foundry investments that secure transmitter supply against export control volatility. Deepen backward integration into silicon carbide substrate sourcing to mitigate rare earth concentration risk in China. Prioritize digital beamforming IP retention under long-term service agreement structures that unbundle hardware ownership from algorithm subscription revenue. For New Entrants and Emerging Players: The premium-economy price-point gap in automotive 4D imaging radar creates white-space opportunity below established defense prime cost structures. Target frequency modulated continuous wave architectures for Level-3 autonomous system penetration where semiconductor integration favors commercial foundry partnerships over captive defense facilities. Pursue METI localization incentives in Japan through joint venture structures that satisfy domestic content rules for critical infrastructure radar. For Investors and Strategic Acquirers: Defense primes with semiconductor fabrication assets are the most active acquirer in this space, consolidating phased array calibration expertise from specialized RF engineering boutiques. Long-term viability rests on recurring software maintenance revenue streams that outlast hardware depreciation schedules. Monitor FCC spectrum allocation rulings in the 77-81 GHz band as inflection indicator for automotive radar demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| GaN-on-SiC Foundry Expansion | RTX Corporation's Massachusetts and Texas facilities anchor domestic transmitter manufacturing for NATO contracts. |
| Digital Beamforming IP Retention | Prime contractors lease processing capacity to military operators while retaining algorithm ownership under service agreements. |
| METI Localization Partnership | Joint ventures in Tokyo and Osaka corridors satisfy Japan's domestic content rules for critical defense components. |
| FMCW Architecture Pivot | Tier-1 suppliers integrate silicon-based designs into mass-market ADAS platforms at cost points below III-V compounds. |
| Counter-Drone Network Deployment | US Department of Defense indefinite delivery contracts consolidate vendor relationships for distributed sensor installations. |
Research Methodology
Bottom-up defense procurement and automotive ADAS modeling reconciled against top-down gallium nitride foundry capacity tracking forms the analytical core of this study. Primary interviews with radar system procurement officers at NATO defense agencies, Tier-1 automotive supplier platform engineers, semiconductor foundry operations directors, and electromagnetic spectrum regulators supplied demand-side validation. Secondary sources include FCC equipment authorization databases, EDA framework agreement disclosures, METI industrial policy filings, and UN ECE vehicle regulation updates.
Input-output matrices connect transmitter module production volumes to phased array system deployments across military, automotive, and maritime end uses over the projection horizon. Segmentation dimensions span detection range tier, platform type, semiconductor architecture, and regional regulatory cluster. CAGRs derive from installed base refresh cycles and procurement commitment trajectories rather than extrapolation of historical shipments. Industry-specific forecast inputs incorporate gallium nitride yield improvement curves and automotive safety mandate implementation schedules.
Caveats apply where export control reclassification, rare earth supply disruption, or spectrum allocation disputes could materially shift the outlook. Forecasts reflect documented assumptions regarding defense budget continuity and semiconductor fabrication yield progression. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Navigation Satellite System Technology Market
Communication Navigation & Surveillance
Naval Tactical Communication Market
Communication Navigation & Surveillance
Latin America Inertial Systems Market
Communication Navigation & Surveillance
High Frequency Military Communications Market
Communication Navigation & Surveillance
Asia-Pacific Autonomous Navigation Market
Communication Navigation & Surveillance
Infrared Search and Track (IRST) System Market
Communication Navigation & Surveillance
Global Tactical Headset Market
Communication Navigation & Surveillance
Tactical Communications Market
Communication Navigation & Surveillance
Industrial Inertial Systems Market
Communication Navigation & Surveillance
Military GNSS Anti-Jamming Systems Market
Communication Navigation & Surveillance
Drone Transponders Market
Communication Navigation & Surveillance
Autonomous Navigation System Market
Communication Navigation & Surveillance
Advanced Surface Movement Guidance and Control System (A-SMGCS) Market
Communication Navigation & Surveillance
Navigational Inertial Systems Market
Communication Navigation & Surveillance
Global Antenna Market
Communication Navigation & Surveillance
Asia-Pacific Inertial Systems Market