
 Global Counter IED Market | 2026-2036
Global Counter IED Market Size, Share, and Industry Trends Forecast 2026-2036
Global Counter IED Market Intelligence
Performance-tier specification upgrades from legacy radio-frequency jammers to software-defined wideband systems is collapsing the viability of older hardware platforms across procurement programs. BAE Systems leverages its integrated electronic warfare portfolio to sustain long-term service contracts with British and allied forces. L3Harris Technologies anchors its position through dominance in signals intelligence architectures that feed counter-IED detection networks. Northrop Grumman Corporation differentiates via advanced radar technology leadership integrated into ground vehicle protection suites.
Counter IED encompasses integrated systems designed to detect, jam, neutralize, or protect against improvised explosive devices through electromagnetic, robotic, or kinetic means, typically operating across frequency ranges from HF through millimeter-wave bands and incorporating real-time spectral analysis. The primary purpose is force protection for military convoys, dismounted patrols, and critical infrastructure checkpoints against remotely triggered or victim-operated threats. Detection Systems and Jamming Devices represent the established revenue core, with mature margins tied to platform integration cycles and recurring sustainment. Robotics and Signal Intelligence are the fastest-expanding technology segments, driven by autonomous route clearance and predictive threat mapping requirements that reduce human exposure.
The US Department of Defense, the UK Ministry of Defence, and NATO standardization bodies shape procurement through STANAG interoperability mandates and rapid fielding authority frameworks that compress development-to-deployment timelines. These regulatory structures privilege vendors with existing certification pathways and transatlantic supply chain clearance. The EU AI Act and emerging autonomous systems governance in Europe are beginning to constrain rules-of-engagement protocols for robotic neutralization platforms. Stakeholders must monitor how algorithmic decision-making standards intersect with military exemption clauses to anticipate product liability and export control boundaries.
Market Dynamics
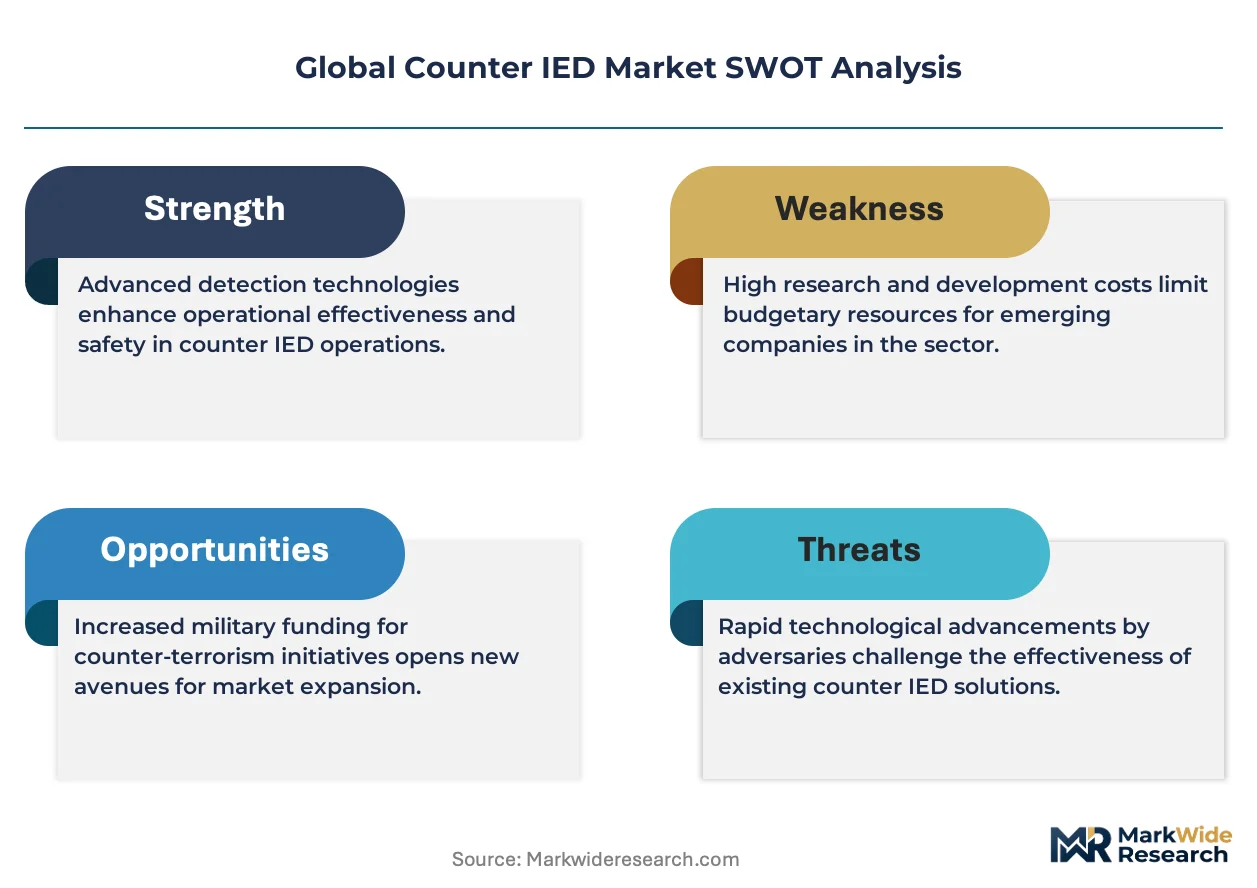
Software-defined radio architectures are collapsing procurement cycles for legacy hardware platforms across NATO defense agencies, forcing incumbent suppliers to restructure service contracts around continuous waveform updates rather than platform replacements.
Growth Catalysts
- STANAG Interoperability Mandates:NATO standardization bodies enforce common electronic warfare protocols across member states, compelling procurement alignment that expands addressable market size for certified vendors.
- Autonomous Route Clearance:Ground robotics for explosive ordnance disposal reduce human exposure in asymmetric conflict zones, driving replacement demand for manned detection systems in United States and British forces.
- Israeli Defense Export Framework:The country's Ministry of Defense licenses counter-IED technology transfer agreements that create secondary demand across Southeast Asian and Eastern European militaries.
Market Restraints
- Gallium Nitride Supply Concentration:Wideband power amplifier fabrication depends on substrate sourcing from a limited set of East Asian foundries, creating input cost volatility for jamming device manufacturers.
- EU AI Act Algorithmic Constraints:European autonomous systems governance imposes human-in-the-loop requirements for robotic neutralization platforms, delaying rules-of-engagement certification for predictive threat mapping systems.
- Spectral Crowding:Civilian 5G and satellite communications expansion compresses available electromagnetic spectrum for military jamming operations, degrading effectiveness in urban operational environments.
Strategic Opportunities
- Indian Counter-Insurgency Modernization:The Ministry of Defence's capital acquisition program for border security creates unmet demand for vehicle-mounted detection suites in high-altitude operational theaters.
- Millimeter-Wave Convergence:Integration of automotive radar chipsets with military signal processing architectures enables low-cost threat detection for checkpoint security applications.
- US Rapid Fielding Authority:Congressional funding mechanisms compress development-to-deployment timelines, rewarding vendors with pre-cleared supply chains and existing platform integration pathways.
Industry Challenges
- Electromagnetic Spectrum Certification:FCC and national military regulators impose multi-year testing protocols for new jamming waveforms, extending product launch timelines beyond technology refresh cycles.
- Legacy Platform Integration:Ground vehicle protection suites must interface with decades-old command-and-control architectures, requiring costly middleware development for each procurement program.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Counter IED Market |
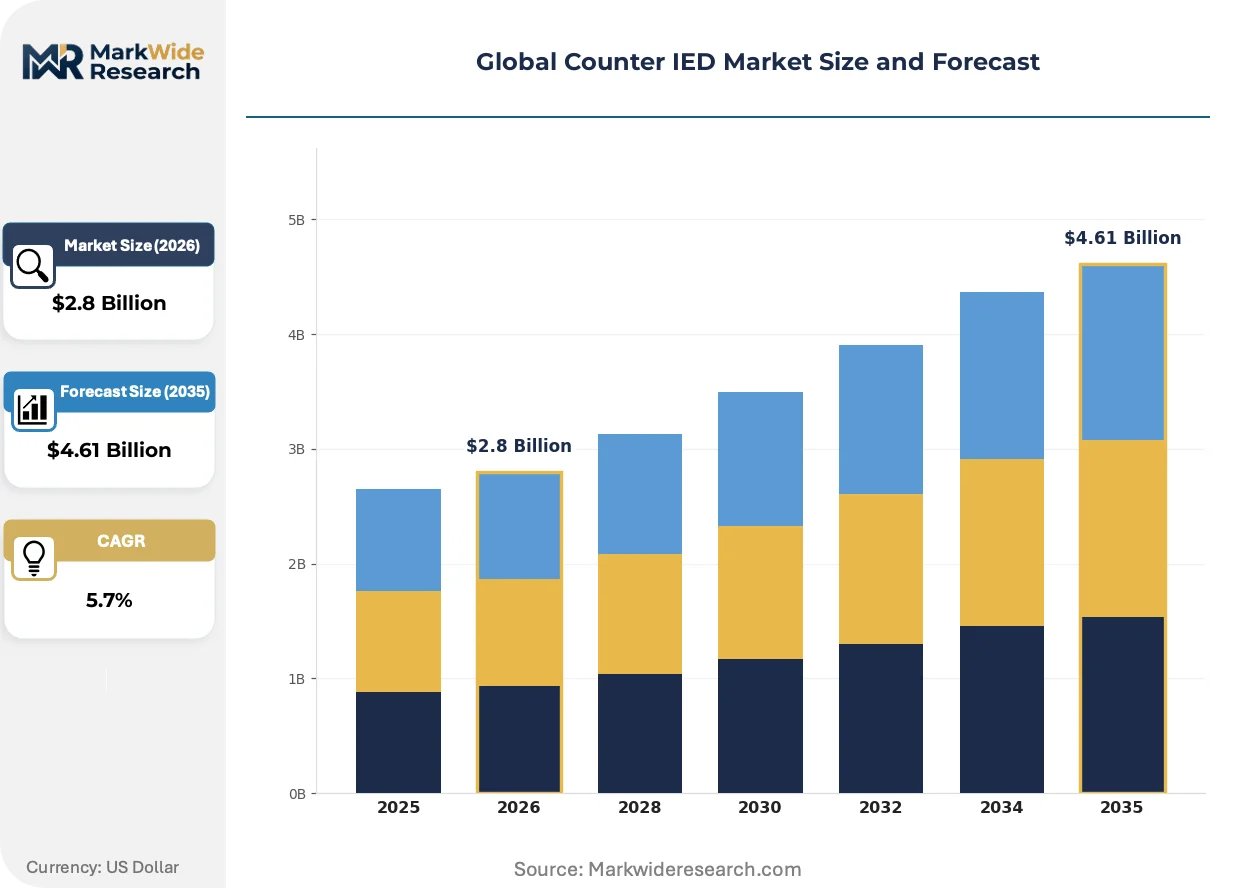
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Detection Systems, Jamming Devices, Neutralization Solutions, Protective Gear, Surveillance Equipment Technology: Radar Technology, Electromagnetic Pulse, Robotics, Signal Intelligence, Thermal Imaging Application: Military Operations, Law Enforcement, Emergency Response, Border Control, Critical Infrastructure Protection End User: Defense Agencies, Security Contractors, Police Units, Counterterrorism Teams, Disaster Management Authorities |
| Companies Covered | BAE Systems, L3Harris Technologies, Lockheed Martin Corporation, Chemring Group, Elbit Systems, Northrop Grumman Corporation, Thales Group, General Dynamics Corporation, Raytheon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Counter IED Market Strategic Shifts & Innovations
Artificial intelligence inference engines are migrating from cloud architectures to edge-deployed processors, compressing detection latency for autonomous threat classification while complicating algorithm validation protocols.
Software-defined wideband jammers are miniaturizing from vehicle-mounted racks to dismounted soldier-wearable form factors. Special operations forces in the United States and United Kingdom are fielding man-portable systems for small-unit patrol protection. This form-factor reduction is collapsing the traditional segmentation between platform-integrated and portable counter-IED equipment, forcing suppliers to unify firmware architectures across product lines.
The EU AI Act's military exemption clauses are creating regulatory fragmentation for autonomous neutralization platforms. European defense agencies must demonstrate meaningful human oversight for algorithmic targeting decisions, complicating export documentation for systems deployed outside the region. Israeli and American manufacturers are responding by bifurcating product configurations—full-autonomy variants for domestic use, human-in-the-loop architectures for European-compliant sales.
Consolidated program offices within the US Department of Defense are compressing vendor qualification timelines through single-source indefinite-delivery contracts. This procurement concentration favors suppliers with existing secret facility clearances and transatlantic logistics networks, marginalizing mid-tier competitors dependent on competitive bidding processes. The shift is most visible in ground vehicle protection suite awards, where platform prime contractors now embed counter-IED subsystems through sole-source subcontracts.
Global Counter IED Market Segmentation
Counter-IED procurement patterns diverge sharply across operational contexts, with military specifications demanding STANAG interoperability while civilian applications prioritize rapid deployment protocols. Technology selection hinges on electromagnetic spectrum clearance timelines and platform integration complexity.
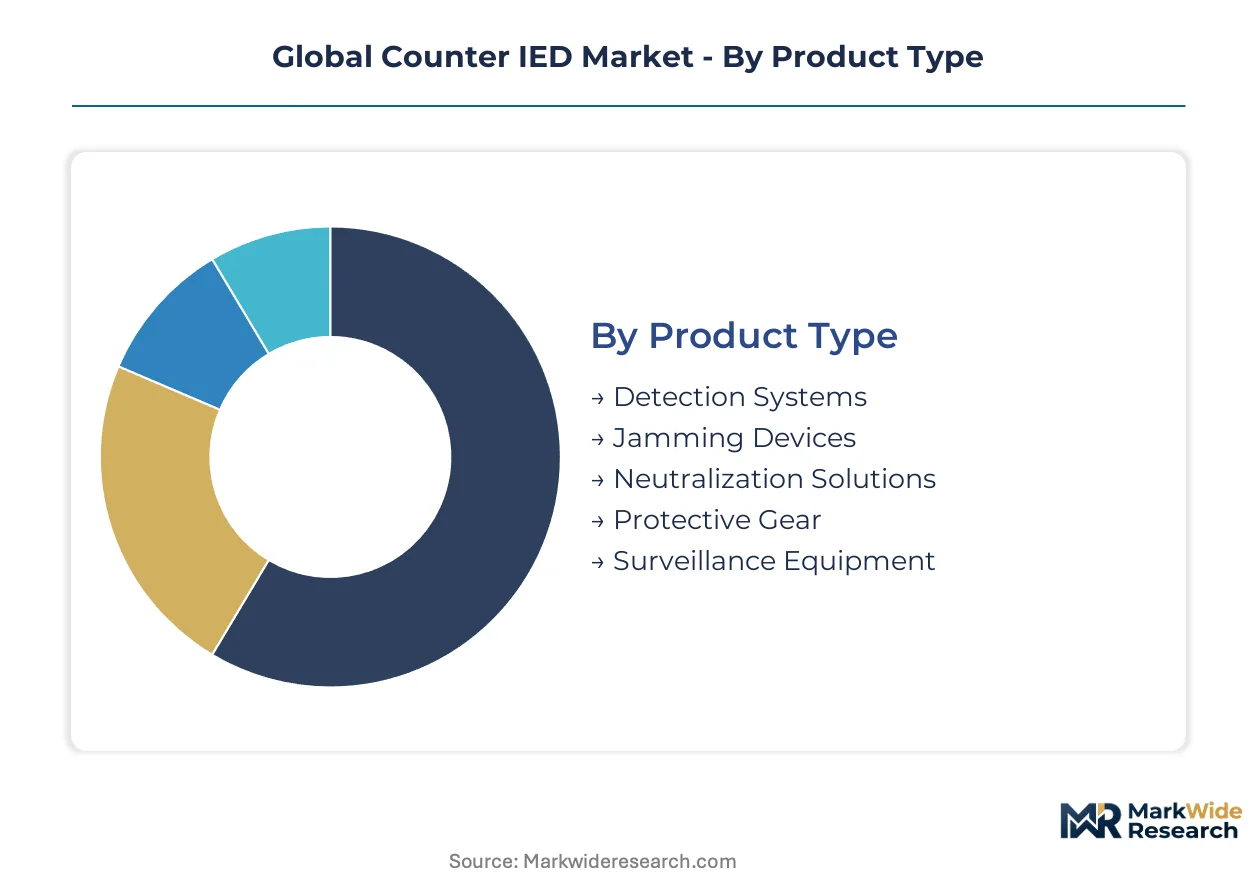
Product Type:
FCC waveform certification and NATO STANAG 4370 environmental testing create divergent compliance burdens across hardware categories, advantaging vendors with pre-cleared architectures.
- Detection Systems:Ground-penetrating radar and electromagnetic induction arrays form the core of route-clearance operations. US Army brigade combat teams and British Army explosive ordnance disposal units are consolidating procurement around vehicle-mounted multi-sensor suites that fuse metal detection with ground-penetrating radar.
- Jamming Devices:Software-defined wideband systems operating across HF through C-band frequencies now dominate convoy protection. Israeli Defense Forces and NATO expeditionary forces are driving demand for man-portable variants that collapse from vehicle-mounted racks to dismounted soldier-wearable configurations.
- Neutralization Solutions:Robotic disruptors and precision-guided kinetic tools address confirmed threats.
- Protective Gear:RF-shielded personal equipment and blast-mitigating vehicle armor address residual risk exposure.
- Surveillance Equipment:Persistent wide-area monitoring systems integrate acoustic and seismic sensors for perimeter defense.
Established volume favors Detection Systems; emerging adoption favors Jamming Devices.
Technology:
Cost tiers separate legacy hardware from software-defined architectures, with premium pricing attached to AI-enabled threat classification and autonomous navigation capabilities.
- Signal Intelligence:Real-time spectral analysis platforms intercept and geolocate command-and-control emissions prior to device activation. US Special Operations Command and UK Strategic Command are prioritizing predictive mapping systems that compress detection-to-neutralization timelines.
- Robotics:Autonomous ground vehicles with manipulator arms execute confirmed threat neutralization without human exposure. Gallium Nitride supply concentration from East Asian foundries constrains power amplifier availability for robotic platform manufacturers.
- Radar Technology:Millimeter-wave and ultra-wideband architectures enable through-wall detection capabilities.
- Electromagnetic Pulse:High-power microwave systems disrupt electronic firing circuits at standoff distances.
- Thermal Imaging:Infrared signature detection identifies buried devices through thermal differential analysis.
Defense procurement concentrates in Signal Intelligence; law enforcement budgets are climbing fastest for Robotics.
Application:
Customer maturity varies across threat environments, with asymmetric warfare theaters demanding continuous waveform updates while checkpoint security favors fixed-installation reliability.
- Military Operations:Brigade-level route clearance and convoy protection consume the majority of detection and jamming system procurement. US Rapid Fielding Authority mechanisms compress deployment timelines for urgent operational requirements in contested logistics corridors.
- Border Control:Fixed-site surveillance and mobile patrol protection address smuggling corridors and irregular migration routes. Indian Ministry of Defence capital acquisition programs for high-altitude theaters are generating unmet demand for vehicle-mounted suites.
- Law Enforcement:Urban explosive ordnance disposal and hostage rescue scenarios drive portable system requirements.
- Emergency Response:Post-blast scene security and secondary device detection protocols guide municipal procurement.
- Critical Infrastructure Protection:Perimeter hardening for energy and transportation nodes favors integrated sensor networks.
Military Operations anchor procurement volume; Border Control represents the steepest expansion trajectory.
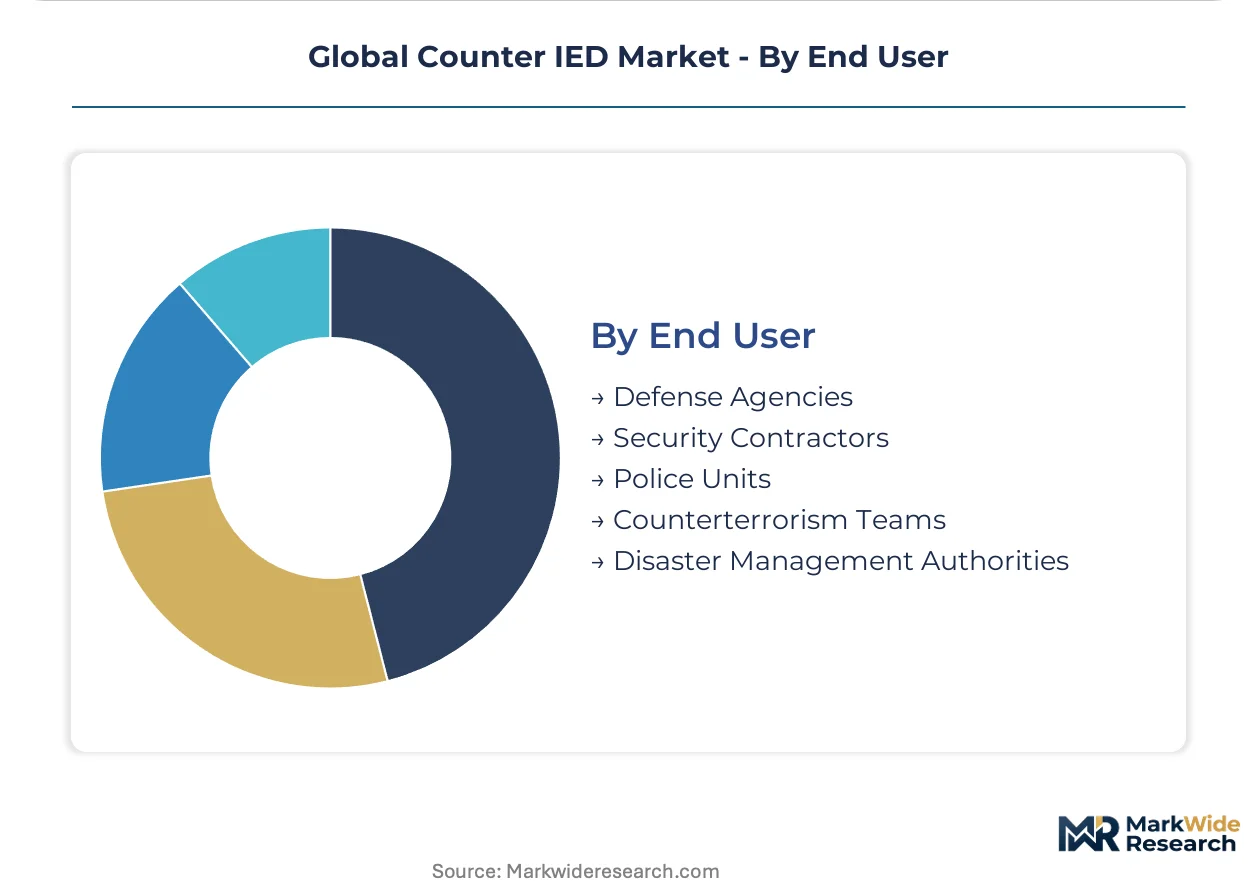
End User:
Supply chain clearance requirements fragment the addressable market, with secret facility certification mandatory for defense agency contracts while security contractors operate under commercial confidentiality protocols.
- Defense Agencies:National military establishments in the United States, United Kingdom, and Israel sustain platform-integrated system procurement through multi-year sustainment contracts. NATO standardization bodies enforce STANAG interoperability mandates that privilege vendors with transatlantic logistics networks.
- Counterterrorism Teams:Specialized units within interior ministries and federal police forces require rapid-deployment portable systems. EU AI Act algorithmic constraints impose human-in-the-loop requirements for autonomous neutralization platforms deployed by European agencies.
- Security Contractors:Private sector logistics protection and diplomatic security drive commercial procurement.
- Police Units:Municipal explosive ordnance disposal capabilities expand with federal grant funding.
- Disaster Management Authorities:Post-conflict clearance and humanitarian demining operations guide development assistance flows.
Defense Agencies concentrate procurement volume; Counterterrorism Teams are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense buyers in Israel demonstrate the lowest price elasticity, absorbing premium costs for software-defined wideband systems, while procurement offices in India and Southeast Asian militaries exhibit acute sensitivity to unit economics, compressing margins for entry-tier hardware vendors.
United States
The US Department of Defense's Rapid Fielding Authority compresses development-to-deployment timelines for urgent operational requirements in contested logistics corridors. FCC waveform certification and national military regulator testing protocols extend product launch timelines for new jamming architectures. Huntsville, Alabama and the greater Washington DC metropolitan area concentrate prime contractor engineering operations for ground vehicle protection suites.
United Kingdom
British Army explosive ordnance disposal units consolidate procurement around vehicle-mounted multi-sensor suites that fuse metal detection with ground-penetrating radar. STANAG interoperability mandates enforced by NATO standardization bodies privilege vendors with transatlantic logistics networks. The Defence Science and Technology Laboratory at Porton Down anchors spectral analysis research for predictive threat mapping systems.
Israel
Israeli Defense Forces drive demand for man-portable jamming variants that collapse from vehicle-mounted racks to dismounted soldier-wearable configurations. The Ministry of Defense licenses technology transfer agreements that create secondary demand across Southeast Asian and Eastern European militaries. Haifa and the Tel Aviv metropolitan corridor host integrated electronic warfare development clusters serving domestic and export markets.
India
The Ministry of Defence's capital acquisition program for border security generates unmet demand for vehicle-mounted detection suites in high-altitude operational theaters. BIS certification requirements and domestic procurement preferences under the Make in India initiative constrain foreign vendor market access. Bengaluru and Hyderabad concentrate defense electronics manufacturing capabilities for indigenous counter-IED subsystem development.
Germany
Bundeswehr procurement offices prioritize STANAG-compliant electronic warfare protocols that align with NATO common architecture standards. The EU AI Act imposes human-in-the-loop requirements for autonomous neutralization platforms, delaying rules-of-engagement certification for predictive systems. Munich and the Bavarian aerospace-defense cluster host subsystem integrators serving European expeditionary force requirements.
Global Counter IED Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with tier-one defense primes commanding premium pricing for platform-integrated suites while mid-tier specialists compete on rapid customization for national procurement programs. The vendor structure concentrates around three strategic archetypes: integrated electronic warfare conglomerates with multi-domain portfolios, signals intelligence specialists with spectral analysis depth, and robotics-focused disruptors with autonomous neutralization capabilities. Competitive dynamics center on sole-source subcontracting relationships with vehicle platform primes and accelerated certification pathways for STANAG-compliant architectures.
Within the integrated systems tier, BAE Systems and Northrop Grumman Corporation exemplify the full-spectrum defense prime archetype, anchoring long-term service relationships through classified facility clearances and transatlantic logistics networks. L3Harris Technologies occupies a specialist position within the signals intelligence domain, representing the architecture-centric competitor model that feeds detection network infrastructure. These three entities collectively illustrate how procurement concentration around indefinite-delivery contracts privileges incumbents with pre-cleared supply chains over mid-tier competitors dependent on competitive bidding processes.
| Leading Market Players |
|---|
| BAE Systems |
| L3Harris Technologies |
| Lockheed Martin Corporation |
| Chemring Group |
| Elbit Systems |
| Northrop Grumman Corporation |
| Thales Group |
| General Dynamics Corporation |
| Raytheon Technologies |
| Others |
Cost & Logistics Intelligence
Twelve-to-eighteen-month lead times for Gallium Nitride substrate qualification compress pricing power for jamming device manufacturers while amplifying cost pass-through to defense procurement offices in NATO member states. This inventory constraint tightens margins for wideband power amplifier suppliers and forces tier-one primes toward sole-source subcontracting arrangements that lock in multi-year sustainment pricing.
Pricing Analysis
After-market service contracts and waveform update subscriptions generate lifetime value exceeding initial hardware procurement by factors of three to five for platform-integrated detection suites. Three-tier pricing structure across premium software-defined architectures, standard hardware-defined systems, and economy-grade legacy jammers segments the addressable market by certification tier and STANAG compliance level. Cost compression in the economy tier intensifies because Indian and Southeast Asian militaries prioritize unit economics over spectral performance. Defense agencies in the United States and Israel demonstrate the lowest price sensitivity, absorbing premium costs for man-portable wideband systems with embedded AI inference engines.
Supply Chain Analysis
Inventory buffers for millimeter-wave radar chipsets and electromagnetic induction arrays rarely exceed ninety days given obsolescence risk in dual-use automotive-military component markets. Substrate fabrication concentrates in Taiwan and South Korea for GaN-on-SiC power amplifiers, while precision machining for robotic manipulator arms clusters in Germany and Japan. Raw material dependencies span rare earth elements for magnetics, high-purity aluminum nitride for thermal management, and specialty alloys for blast-mitigating armor. Single-source vulnerability in East Asian foundry capacity exposes jamming device manufacturers to allocation constraints during geopolitical disruptions. Distribution runs through prime contractor logistics networks with secret facility clearances rather than open commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as software-defined architectures displace legacy hardware platforms, creating niche entry points for specialists in autonomous navigation and edge-deployed spectral analysis.
For Market Incumbents: Fortify sole-source subcontracting relationships with vehicle platform primes by embedding counter-IED subsystems through indefinite-delivery contract vehicles. Deepen backward integration into Gallium Nitride substrate sourcing to mitigate foundry allocation risk. Accelerate certification investment for STANAG 4370 environmental testing to compress competitor qualification timelines. For New Entrants and Emerging Players: Anchor in Indian Ministry of Defence capital acquisition programs for high-altitude vehicle-mounted detection suites, where domestic procurement preferences under Make in India create partnership entry points. Target law enforcement explosive ordnance disposal units in European municipalities for portable jamming systems compliant with EU AI Act human-in-the-loop requirements. Pursue joint development agreements with Israeli Ministry of Defense-licensed technology transfer frameworks to access Southeast Asian secondary demand. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified defense conglomerates spinning off counter-IED divisions lacking platform prime relationships. Long-term viability over the next decade hinges on software-defined recurring revenue models displacing transactional hardware procurement. Monitor FCC waveform certification backlogs as an inflection indicator for vendor qualification bottlenecks that concentrate market share among pre-cleared incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| STANAG Certification Fast-Track | Compresses NATO member state procurement cycles for vendors with existing transatlantic logistics networks. |
| Software-Defined Architecture Migration | Displaces legacy hardware refresh cycles with recurring waveform subscription revenue for platform-integrated suites. |
| Gallium Nitride Supply Agreement | Secures substrate allocation from East Asian foundries to de-risk wideband power amplifier production. |
| Autonomous Route Clearance Partnership | Reduces human exposure in asymmetric theaters through robotic neutralization platform deployment. |
| EU AI Act Compliance Configuration | Enables European market access for robotic systems with bifurcated human-in-the-loop architectures. |
Research Approach
Initial hypotheses were tested against primary input from program managers at defense agencies, electronic warfare subsystem engineers, explosive ordnance disposal unit commanders, and procurement officers at NATO standardization bodies, then refined through secondary validation against SEC 10-K filings, DoD budget justification documents, EU defense procurement databases, and customs trade records for Gallium Nitride substrate imports. Bottom-up unit economics for detection and jamming system deployments were triangulated against top-down addressable market sizing derived from national military expenditure disclosures.
Variance decomposition across the projection horizon isolates technology substitution effects, regulatory compliance cost impacts, and supply chain concentration risks as distinct forecast drivers. Segmentation dimensions modeled span product type, technology architecture, operational application, and end-user clearance tier, with additional granularity for STANAG interoperability certification status. CAGRs were derived from fitted growth curves anchored to observed procurement cycle lengths and platform refresh timelines. Industry-specific inputs include FCC waveform certification backlogs, EU AI Act implementation guidance, and Indian BIS domestic content requirements.
Material uncertainties — Gallium Nitride foundry allocation disruptions, EU AI Act algorithmic constraint reinterpretations, and Indian domestic procurement preference enforcement — sit outside the modeled envelope. Forecasts reflect assumptions about sustained asymmetric warfare threat environments and continued NATO member state defense expenditure commitments. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense Cybersecurity
Maritime Cybersecurity Market
Defense Cybersecurity
Mine and IED Detection System Market
Defense Cybersecurity
Electronic Warfare Market
Defense Cybersecurity
Aviation Cyber Security Market
Defense Cybersecurity
Asia-Pacific Missiles and Missile Defense Systems Market
Defense Cybersecurity
Europe Automotive Cybersecurity Market
Defense Cybersecurity
Cyber Weapons Market
Defense Cybersecurity
Military Cybersecurity Market
Defense Cybersecurity
Asia-Pacific Cyber Weapons Market
Defense Cybersecurity
Military Sensors Cybersecurity Solutions Market
Defense Cybersecurity
Blockchain Technology in Aerospace and Defense Market
Defense Cybersecurity
High Energy Lasers Market
Defense Cybersecurity
Vehicle Cybersecurity Market
Defense Cybersecurity
Electronic Countermeasures Market
Defense Cybersecurity
Global C4I Systems Market
Defense Cybersecurity
Asia-Pacific Defense Market