
 High Energy Lasers Market | 2026-2036
High Energy Lasers Market Size, Share, and Industry Trends Forecast 2026-2036
High Energy Lasers Market Intelligence
Consolidation among specialized optics and gain media suppliers is shifting the competitive landscape for laser system integrators. Lockheed Martin Corporation leverages its prime contractor status to integrate HEL systems onto various military platforms. Northrop Grumman Corporation specializes in advanced beam control and thermal management solutions. In the industrial sector, TRUMPF GmbH + Co. KG dominates high-power fiber laser applications for material processing.
High energy lasers are directed energy systems that generate coherent light beams with output powers typically exceeding one kilowatt. Their primary purpose is to deliver concentrated thermal or kinetic energy to a target for applications ranging from military defense to industrial material processing. Fiber lasers represent the fastest-growing product type due to their superior beam quality and efficiency. Within applications, military defense commands the largest investment, while aerospace manufacturing shows significant potential for precision cutting and welding.
Export controls, governed by entities like the US Department of State under ITAR and similar frameworks in the European Union, strictly regulate the international transfer of HEL systems. Laser safety standards from the IEC and ANSI dictate operational protocols and protective measures for both military and industrial end-users. Future development will hinge on achieving higher power outputs while adhering to increasingly stringent size, weight, and power constraints for mobile platforms.
Market Dynamics
The market's central dynamic is the acceleration of technology transfer from government-funded defense programs to commercial sectors. Innovations in power scaling and ruggedization, originally for military directed energy weapons, are now creating new capabilities in industrial material processing and aerospace manufacturing.
Growth Catalysts
- Diode-Pumped Technology:The shift towards diode-pumped solid-state and fiber lasers enhances electrical-to-optical efficiency and reliability, enabling deployment on power-constrained mobile platforms like tactical vehicles and unmanned aerial systems.
- Defense Modernization Programs:Heightened geopolitical tensions are driving increased government spending on directed energy weapon systems, particularly within the United States, China, and Israel, to counter emerging drone and missile threats.
- Aerospace Manufacturing Demand:The aerospace industry's requirement for high-precision, low-heat-distortion welding and cutting of advanced alloys and composites is a significant catalyst for high-power fiber laser adoption.
Market Restraints
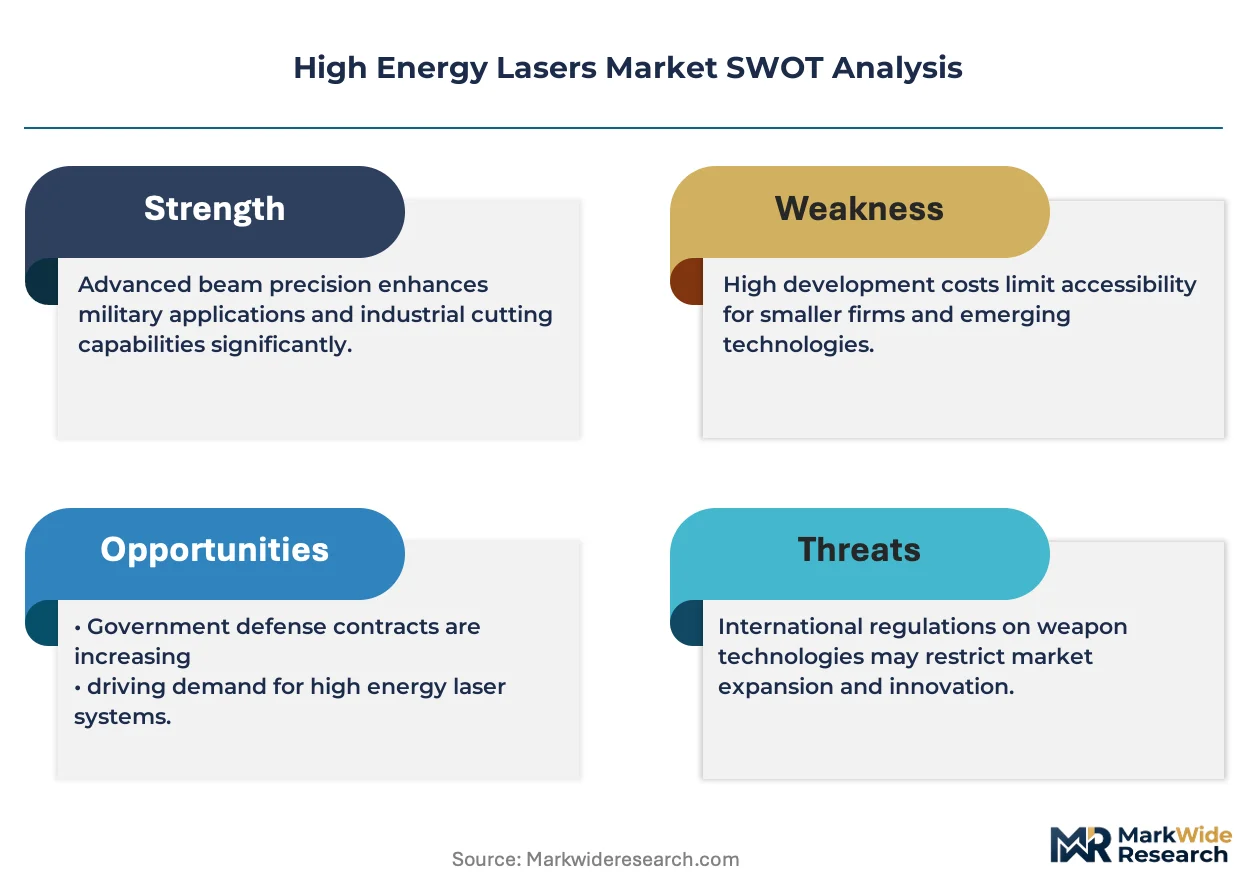
- Stringent Export Controls:Regulations such as the United States' International Traffic in Arms Regulations (ITAR) severely restrict the sale and transfer of high-power laser systems and critical components, limiting market access and international collaboration.
- Thermal Management Complexity:Dissipating waste heat from multi-kilowatt laser systems remains a primary technical barrier, adding significant size, weight, and complexity that complicates integration onto smaller platforms.
- Specialized Component Costs:The high cost and limited supply of critical components, including high-purity gain media and specialized large-mode-area optical fibers, act as a restraint on cost-effective mass production and wider commercial adoption.
Strategic Opportunities
- Space Applications:Emerging use cases in space, such as laser communications for high-bandwidth data links and the potential for orbital debris removal, represent a significant new frontier for HEL technology development and deployment.
- AI-Powered Beam Control:Integrating artificial intelligence and machine learning algorithms for adaptive optics and atmospheric turbulence compensation can dramatically improve laser effectiveness over long distances, opening new operational possibilities.
- New Defense Markets:Nations like India, South Korea, and Australia are initiating domestic directed energy research programs, creating new geographic markets for component suppliers and system integrators outside of traditional defense hubs.
Industry Challenges
- Platform Integration Hurdles:The complex engineering challenge of integrating the laser weapon system with a platform's existing power, cooling, and command-and-control infrastructure is a major operational bottleneck for defense contractors.
- Safety Standard Compliance:Adhering to rigorous operational safety standards from bodies like the IEC and ANSI requires extensive testing, training protocols, and protective equipment, adding significant cost and time to deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Energy Lasers Market |
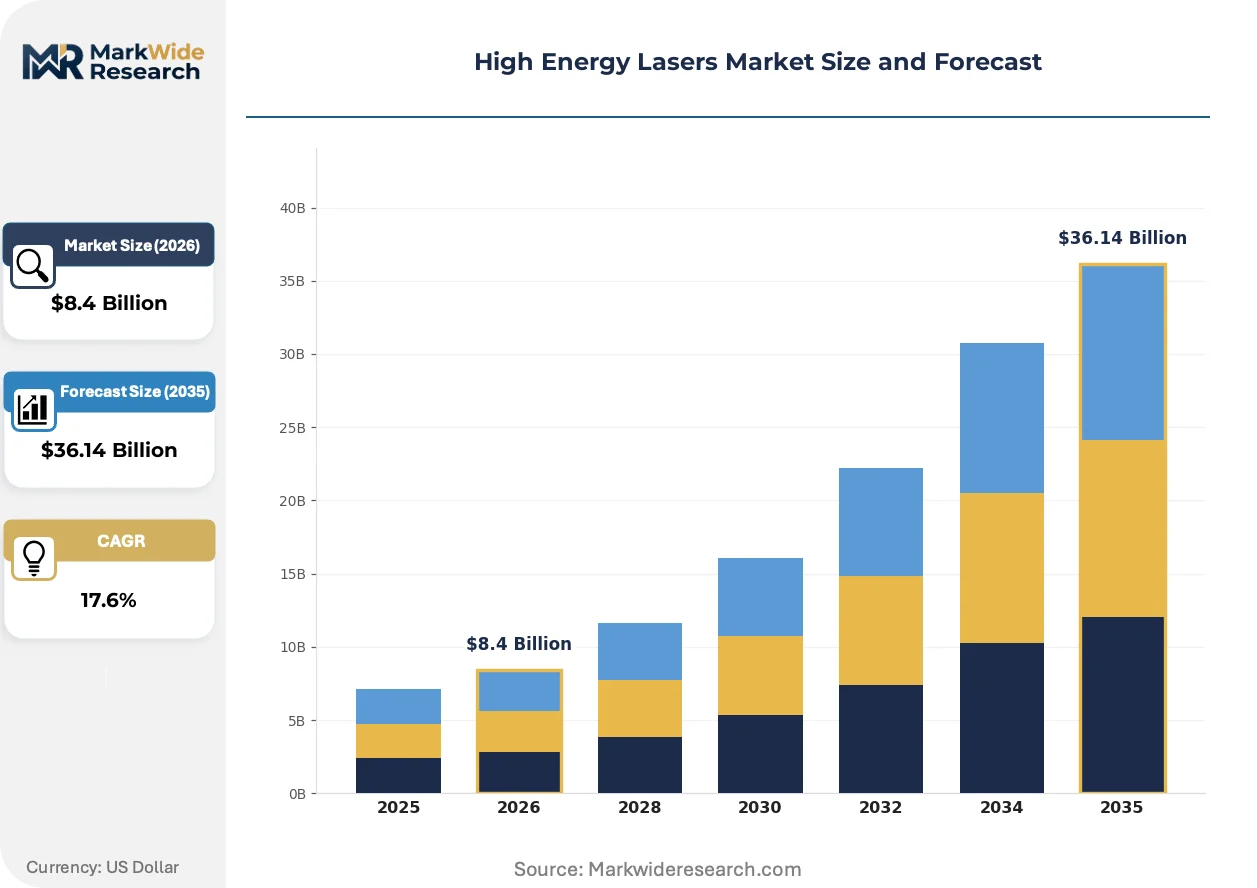
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $36.14 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Laser, Solid-State Laser, Gas Laser, Chemical Laser, Semiconductor Laser Technology: Continuous Wave, Pulsed Wave, Mode-Locked, Q-Switched, Diode Pumped Application: Military Defense, Aerospace Manufacturing, Scientific Research, Material Processing, Telecommunications End User: Defense Contractors, Optical Labs, Aerospace Firms, Industrial Manufacturers, Research Organizations |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, RTX Corporation, IPG Photonics Corporation, TRUMPF GmbH + Co. KG, Coherent, Inc., BAE Systems plc, Han's Laser Technology Industry Group Co., Ltd., Lumentum Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Energy Lasers Market Strategic Shifts & Innovations
System development is defined by a push for higher power density and greater environmental ruggedness. This effort aims to transition high energy lasers from controlled laboratory settings to functional, reliable systems capable of performing in harsh naval, airborne, and terrestrial environments.
Coherent beam combining is a key enabling technology that sums the output of multiple fiber laser amplifiers to generate a single, high-quality beam. Defense system integrators are pursuing this approach to achieve the hundreds-of-kilowatts power levels required for military applications. This technique is integrating numerous scalable, lower-power modules into a formidable high-energy weapon, bypassing the physical limits of a single laser gain medium.
The ongoing harmonization of laser safety regulations under the IEC 60825 standard is streamlining global commerce. This alignment simplifies the design and certification process for manufacturers, as a single product can meet compliance requirements across multiple international jurisdictions, including the European Union. Industrial laser producers benefit most, as they can avoid costly redesigns for specific national markets, particularly for material processing equipment.
A notable shift in acquisition strategy sees military buyers demanding fully integrated and tested laser weapon subsystems rather than discrete components. This model displaces component-level procurement and favors prime contractors who can manage the integration of power, thermal, and beam control systems. The trend is most visible in large-scale naval defense programs in the United States and allied NATO nations seeking turn-key solutions.
High Energy Lasers Market Segmentation
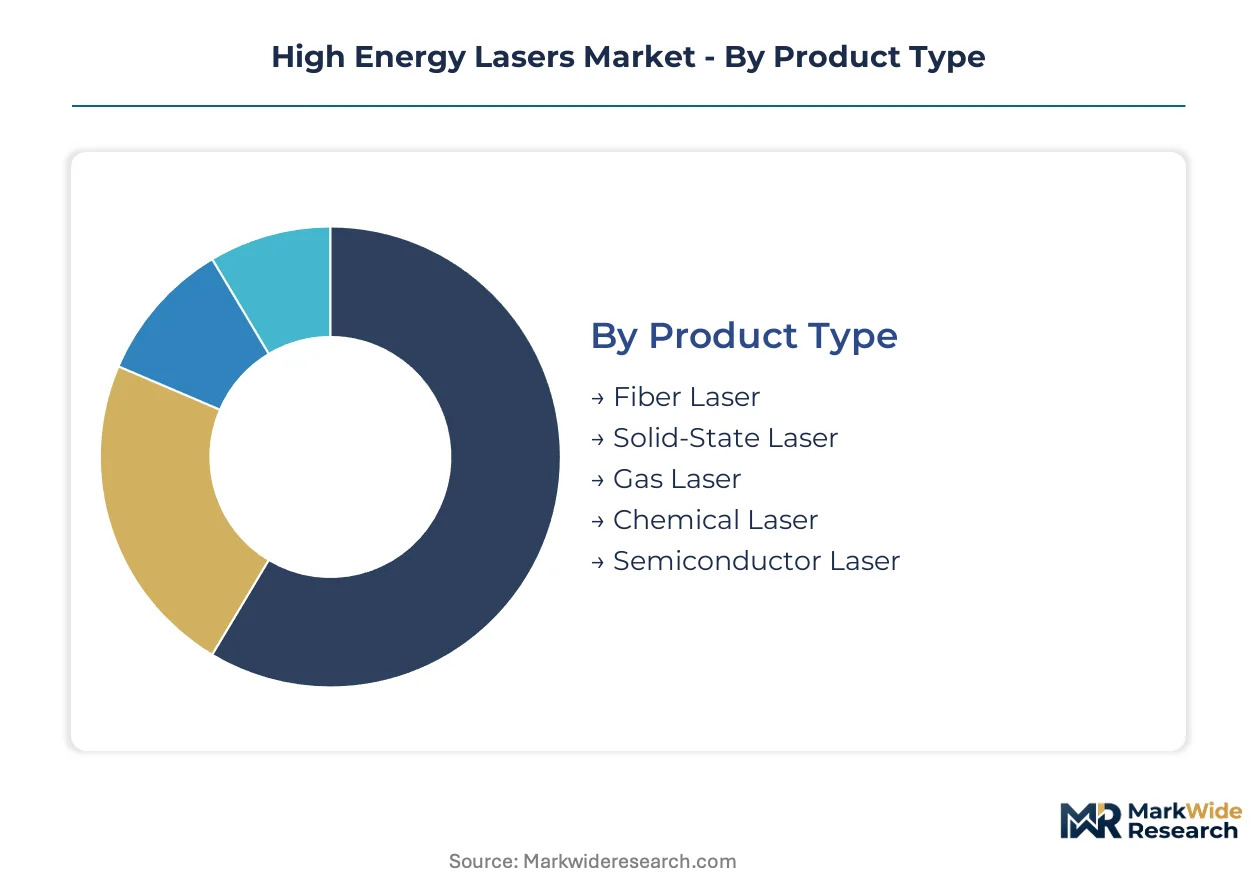
The high energy lasers market segmentation highlights diverse technological approaches and end-user requirements driving innovation and procurement. Understanding these distinct segments provides clarity on where investment and development efforts are concentrating across military and industrial sectors. Each segment reflects unique performance criteria and application priorities for laser system deployment.
Product Type:
Buyers in the high energy lasers market differentiate product selection based on beam quality, power output requirements, and operational efficiency.
- Fiber Laser:These systems generate a coherent light beam within an optical fiber doped with rare-earth elements, offering excellent beam quality and high electrical-to-optical conversion efficiency. Demand for fiber lasers concentrates in military defense, driven by their superior performance in directed energy weapon systems.
- Solid-State Laser:Solid-state lasers utilize a gain medium, such as a crystal or glass rod, pumped by diodes or flashlamps to produce high-power beams. Aerospace manufacturing demands solid-state lasers for precision cutting and welding of advanced materials, benefiting from their robust power scaling capabilities.
- Gas Laser:Gas lasers, using CO2 or excimer gases as the gain medium, deliver high power for industrial material processing applications.
- Chemical Laser:Chemical lasers produce high-power beams from exothermic chemical reactions, primarily for specialized military research programs.
- Semiconductor Laser:Semiconductor lasers, also known as diode lasers, offer compact and efficient light sources, often used as pump sources for other laser types.
Volume sits with Solid-State Laser; growth tilts toward Fiber Laser.
Technology:
Customer requirements for high energy laser technology vary significantly based on the desired energy delivery profile and target interaction.
- Continuous Wave:Continuous wave lasers emit a constant, uninterrupted beam of light, providing sustained energy delivery ideal for material processing and certain defense applications requiring thermal effects. Industrial manufacturers prioritize continuous wave technology for high-speed cutting and welding, valuing its stable power output.
- Diode Pumped:Diode-pumped technology uses semiconductor lasers to excite the gain medium, enhancing efficiency, reliability, and compactness compared to traditional pumping methods. Military programs globally are shifting to diode-pumped systems for mobile platforms, seeking improved electrical-to-optical efficiency.
- Pulsed Wave:Pulsed wave lasers deliver energy in short, high-intensity bursts, suitable for precision ablation and ranging applications.
- Mode-Locked:Mode-locked lasers produce extremely short optical pulses, finding utility in scientific research and advanced material micro-processing.
- Q-Switched:Q-switched lasers generate high-peak-power pulses, commonly employed in marking, engraving, and certain defense targeting systems.
This technology category sees Continuous Wave dominating current deployments, while Diode Pumped drives innovation.
Application:
Application needs dictate the specific power levels, beam characteristics, and operational environments for high energy laser systems.
- Military Defense:High energy lasers in military defense serve as directed energy weapons for missile and drone interception, target illumination, and surveillance, requiring high power and robust beam control. The United States, China, and Israel are increasing investment in military defense applications to counter emerging threats.
- Aerospace Manufacturing:Aerospace manufacturing utilizes high energy lasers for precision cutting, welding, and surface treatment of advanced alloys and composite materials, demanding high accuracy and minimal heat distortion. The sector's demand for lightweight, durable components drives fiber laser adoption.
- Scientific Research:Scientific research employs high energy lasers for fundamental physics experiments, fusion studies, and advanced spectroscopy.
- Material Processing:Material processing applications include cutting, welding, drilling, and surface modification across diverse industrial sectors.
- Telecommunications:Telecommunications uses lasers for high-speed data transmission in fiber optic networks and free-space optical communication.
The largest revenue contribution comes from Military Defense, with Aerospace Manufacturing experiencing the steepest expansion trajectory.
End User:
End user procurement models for high energy lasers range from large-scale government contracts to specialized industrial equipment acquisitions.
- Defense Contractors:Defense contractors integrate high energy laser systems onto military platforms, managing complex power, cooling, and command-and-control infrastructure for national defense programs. Lockheed Martin and Northrop Grumman are key defense contractors leveraging prime contractor status for HEL integration.
- Industrial Manufacturers:Industrial manufacturers deploy high-power lasers for automated production processes, including cutting, welding, and additive manufacturing, prioritizing efficiency and reliability for mass production. TRUMPF GmbH dominates high-power fiber laser applications for industrial material processing.
- Optical Labs:Optical labs utilize high energy lasers for advanced photonics research, beam characterization, and component testing.
- Aerospace Firms:Aerospace firms directly procure and operate high energy lasers for in-house manufacturing, maintenance, and repair operations.
- Research Organizations:Research organizations, including universities and government institutes, apply high energy lasers for fundamental scientific inquiry and technology development.
Overall market activity is heavily influenced by Defense Contractors, while Research Organizations represent a critical segment for technological advancement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global high energy lasers market sees innovation anchored in key technological hubs and defense-focused regions. These areas drive advancements in power scaling and beam control for both military and industrial applications. Demand for sophisticated laser systems is particularly concentrated in nations with robust defense modernization programs and advanced manufacturing sectors.
United States
The United States drives significant demand for high energy lasers in military defense and aerospace manufacturing. ITAR strictly governs export controls, influencing technology transfer and international collaboration. Defense corridors in California and Virginia concentrate R&D efforts for advanced directed energy weapon systems.
China
China's domestic defense modernization programs and expanding industrial material processing sectors fuel its high energy laser market. National GB standards guide the development and deployment of advanced laser technologies. The Yangtze River Delta region hosts numerous industrial laser manufacturers and research institutions.
Israel
Israel demonstrates robust demand for high energy lasers in advanced missile defense systems and counter-drone technologies. The Ministry of Defense oversees procurement and R&D for next-generation directed energy weapons. Tel Aviv's vibrant tech ecosystem fosters innovation in laser components and system integration.
Germany
Germany's industrial sector, especially automotive manufacturing, requires high-precision high energy lasers for material processing. IEC 60825 standards guide laser safety and operational protocols across industrial applications. Stuttgart and Aachen are key centers for laser research and advanced manufacturing.
Japan
Japan's aerospace manufacturing and scientific research sectors demand sophisticated high energy laser systems. METI actively promotes R&D initiatives for high-power laser technologies across diverse industries. The Kanto region, particularly around Tokyo, hosts a concentration of optics companies and research institutions.
High Energy Lasers Market Key Industry Players
Global majors compete with regional champions across technology development and platform integration for high energy lasers. The market exhibits a tiered structure, with prime defense contractors, specialized component suppliers, and industrial laser manufacturers forming distinct archetypes. Companies frequently pursue strategic partnerships for system integration and invest heavily in advanced R&D to enhance beam quality and power scaling capabilities. Geographic expansion into new defense markets and strategic acquisitions of specialized component firms also represent significant competitive moves.
Within the defense prime contractor archetype, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify large-scale system integrators. These corporations leverage their extensive expertise in complex platform integration, focusing on military defense applications that demand robust and reliable high energy laser systems. TRUMPF GmbH + Co. KG, a German-based company, represents a leading industrial laser manufacturer, occupying a strong position in high-power fiber laser applications for material processing. This company's focus on efficiency and precision addresses the demanding requirements of advanced manufacturing sectors.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| RTX Corporation |
| IPG Photonics Corporation |
| TRUMPF GmbH + Co. KG |
| Coherent, Inc. |
| BAE Systems plc |
| Han's Laser Technology Industry Group Co., Ltd. |
| Lumentum Holdings Inc. |
| Others |
Cost & Logistics Intelligence
Defense contractors' concentrated procurement of high energy lasers influences a hybrid pricing model that balances long-term contracts with specialized component costs. This dynamic ensures stable supply for mission-critical systems while reflecting the premium for advanced technology. The market's structure prioritizes performance and reliability over initial unit cost for defense applications.
Pricing Analysis
Integrated service and warranty bundles are standard for complex high energy laser systems, reflecting the necessity of sustained operational readiness. Pricing models often combine project-based fees for system integration with long-term service contracts, especially for defense applications. Price differentiation hinges on power output, beam quality, and the level of platform customization required. Cost compression in specialized gain media and high-power diode components exerts downward pressure on overall system costs for industrial users. Military defense buyers exhibit low price sensitivity, prioritizing performance and reliability, while industrial manufacturers are highly sensitive to efficiency and total cost of ownership.
Supply Chain Analysis
Direct sales channels and specialized integrators handle the distribution of high energy laser systems to defense contractors and large industrial manufacturers. Geographic supply concentration for critical components resides primarily in the United States, Germany, and Japan, with China also emerging for industrial laser components. The supply chain relies heavily on high-purity gain media, specialized large-mode-area optical fibers, and high-power semiconductor diodes. Regulatory restrictions, particularly ITAR in the United States, represent a significant structural risk, limiting international component sourcing and technology transfer. Single-source vulnerability for highly specialized optics also presents a supply chain challenge.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high energy lasers market presents a vertical-integration race, driven by players seeking to control critical component supply and system integration capabilities. This strategic imperative aims to secure technological advantage and mitigate supply chain risks.
For Market Incumbents: Lock in long-term contracts with defense ministries, securing multi-year development and deployment programs. Acquire specialized optics and gain media suppliers to deepen vertical integration and control critical component costs. Invest heavily in R&D for AI-powered beam control to maintain a technological edge against emerging drone and missile threats. Expand platform integration capabilities to offer turn-key solutions for naval and airborne systems.
For New Entrants and Emerging Players: Niche industrial material processing applications, particularly for advanced composites in aerospace, represent an underserved buyer archetype. Focus on developing cost-effective, high-efficiency fiber laser modules for specific manufacturing tasks. Target new defense markets like India and South Korea by offering specialized component innovation, such as advanced thermal management solutions. A go-to-market strategy emphasizing modularity and ease of integration can attract mid-tier industrial manufacturers.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking to consolidate fragmented component markets or gain access to proprietary beam control technologies. Long-term viability for high energy laser companies remains strong over the next decade, driven by defense modernization and industrial automation. Target specialized optics firms, advanced thermal management solution providers, and AI-powered beam control developers. The successful deployment of HEL systems on mobile defense platforms serves as a key signal to watch for accelerated market growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquire Specialized Component Suppliers | This move secures critical supply chains and intellectual property, strengthening a firm's competitive position in advanced laser systems. |
| Invest in AI-Powered Beam Control R&D | Enhancing laser effectiveness over long distances improves performance for military and industrial applications. |
| Expand Platform Integration Capabilities | Offering comprehensive, turn-key solutions simplifies deployment for defense contractors and industrial end-users. |
| Develop Cost-Effective Fiber Laser Modules | This targets underserved industrial segments by providing accessible, high-efficiency solutions for material processing needs. |
| Secure Long-Term Government Contracts | These contracts provide stable revenue streams and validate technological leadership in critical defense applications. |
Research Approach
Multi-period observation of defense spending trends and industrial adoption rates anchored the trend analysis, supplemented by interviews with key industry stakeholders. Primary research included conversations with defense procurement officers, industrial plant managers, laser R&D engineers, and specialized component suppliers. This qualitative data was triangulated against secondary sources such as defense modernization reports, aerospace manufacturing output data, export control regulations from the US Department of State, and global patent filings to ensure comprehensive market understanding. A blend of top-down market sizing and bottom-up validation provided robust data integrity.
An input-output matrix framework was utilized to forecast market dynamics across the analysis window, modeling interactions between various segments. Segmentation dimensions included product type, technology, application, end-user, and power output tier, providing granular insights into market evolution. Compound Annual Growth Rates (CAGRs) were derived from a combination of historical performance data, projected technology adoption rates, and anticipated investment in defense modernization programs. Industry-specific forecast inputs included global geopolitical tension assessments and aerospace production forecasts, which directly influence demand for high energy lasers.
Revisions become necessary when significant geopolitical shifts, unforeseen technological breakthroughs in beam control, or changes in international export control policies materialize. Forecasts reflect assumptions documented at the time of analysis, acknowledging inherent market uncertainties. Practitioners should monitor defense budgets, regulatory changes, and advancements in power scaling for early signals that could impact market trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense Cybersecurity
Aviation Cyber Security Market
Defense Cybersecurity
Electronic Warfare Market
Defense Cybersecurity
Global Counter IED Market
Defense Cybersecurity
Defensive Cyber Weapons Market
Defense Cybersecurity
Europe Automotive Cybersecurity Market
Defense Cybersecurity
Global C4I Systems Market
Defense Cybersecurity
Asia-Pacific Defense Market
Defense Cybersecurity
Asia-Pacific Missiles and Missile Defense Systems Market
Defense Cybersecurity
Asia-Pacific Cyber Weapons Market
Defense Cybersecurity
Military Sensors Cybersecurity Solutions Market
Defense Cybersecurity
Ballistics Targeting Software Market
Defense Cybersecurity
Europe Cyber Weapons Market
Defense Cybersecurity
Military Computers Market
Defense Cybersecurity
Cyber Weapons Market
Defense Cybersecurity
Defence Cybersecurity Market
Defense Cybersecurity
Railway Cyber Security Market