
 GCC Aviation Infrastructure Market | 2026-2036
GCC Aviation Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Aviation Infrastructure Market Foresight
Aftermarket facility maintenance revenue is rewriting profit expectations for contractors serving the GCC's aging airport stock. TAV Construction leverages its Ankara-built expertise to compete for terminal expansion tenders across the Gulf. Bechtel anchors its regional position through design-build contracts for greenfield airfield developments. AECOM differentiates via integrated digital engineering platforms that reduce construction-phase change orders.
GCC aviation infrastructure encompasses runways, control towers, hangars, and passenger terminals engineered to ICAO Category III-B landing standards and designed to withstand ambient temperatures exceeding 50°C while processing 30-90 million annual passengers. The infrastructure type segment dominates contract value, with airport terminals and runways absorbing the majority of capital allocation due to capacity constraints at Dubai International and King Abdulaziz International. Technology integration represents the fastest-expanding segment, as biometric boarding gates and satellite-based precision approach systems displace legacy radar and manual passenger processing infrastructure.
GCAA, Saudi GACA, and Qatar's CAA enforce airside safety and environmental standards that dictate pavement strength ratings, noise contours, and fuel farm separation distances for all new approvals. ICAO Annex 14 compliance requirements are forcing retrofit investments at older Omani and Bahraini facilities originally built to superseded standards. Stakeholders must monitor how Saudi Vision 2030 airport privatization timelines redistribute project risk between state operators and international construction consortia.
Market Dynamics
Biometric passenger processing systems are compressing terminal redesign cycles across Gulf airports, forcing contractors to integrate digital identity infrastructure into concrete-and-steel construction timelines.
Growth Catalysts
- GCAA Smart-Gate Mandates:The UAE's General Civil Aviation Authority requires biometric boarding corridors in all new terminal builds, pulling facial recognition hardware into base construction contracts rather than retrofit add-ons.
- Saudi Vision 2030 Airport Privatization:Riyadh's transfer of King Khalid International and other facilities to private operators is unlocking capital pools for greenfield airside development previously constrained by ministry budgets.
- ICAO Category III-B Upgrades:Precision approach infrastructure supporting zero-visibility landings is expanding runway contract scopes across Doha, Abu Dhabi, and Jeddah as hubs compete for premium long-haul traffic.
Market Restraints
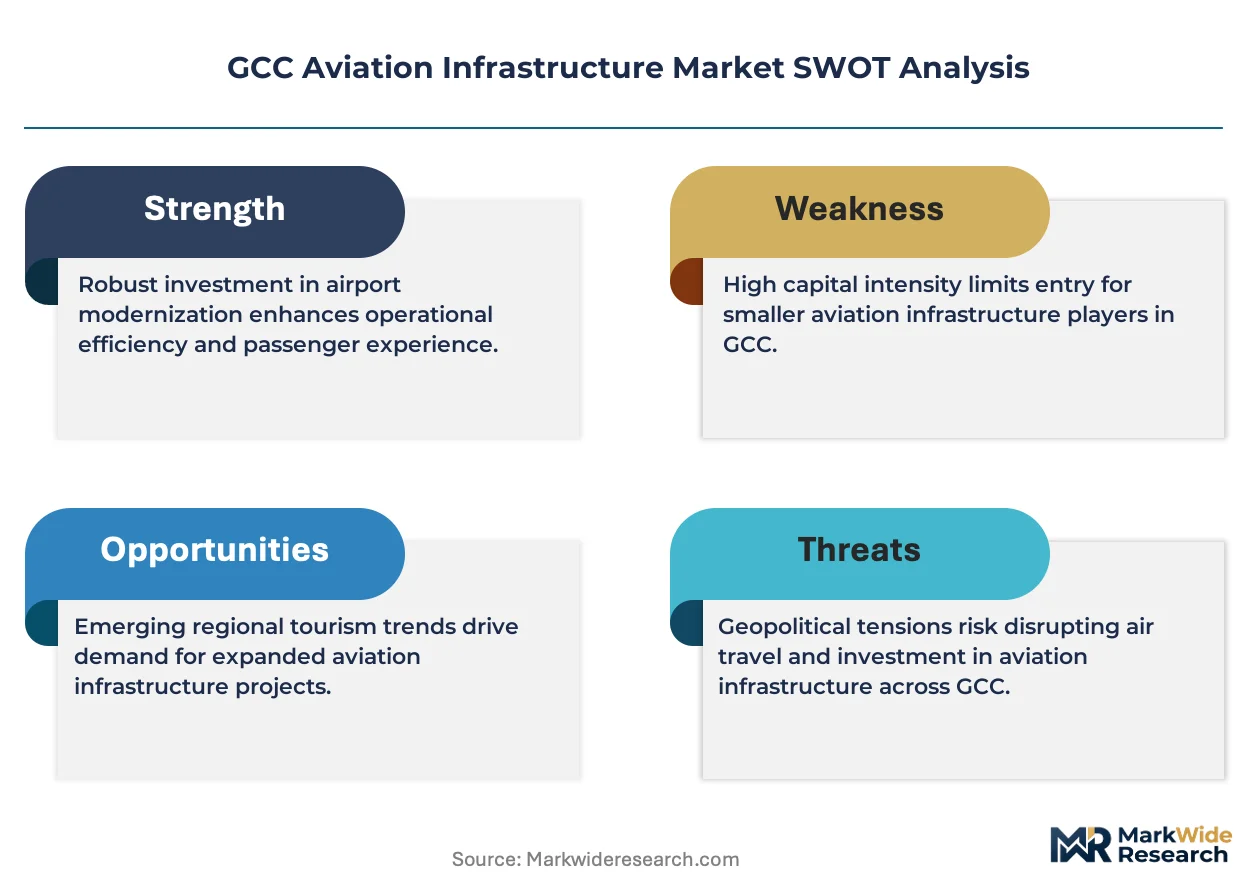
- Specialized Pavement Material Concentration:High-temperature asphalt formulations resistant to 50°C ambient heat rely on a narrow supplier base concentrated in South Korean and German chemical producers, exposing projects to input volatility.
- Airside Safety Certification Delays:Saudi GACA's extended review timelines for fuel farm separation distances and noise contour compliance are stretching project completion windows by 8-14 months.
- Skilled MEP Labor Scarcity:Gulf nationals comprise under 12% of certified airport mechanical-electrical-plumbing workforces, forcing contractors to import European and South Asian technicians at premium rates.
Strategic Opportunities
- Oman and Bahrain Retrofit Markets:Muscat International and Bahrain International airports built to pre-2010 ICAO standards face mandatory pavement strength and navigation aid upgrades, creating captive demand for specialized airside contractors.
- Solar-Integrated Terminal Roofs:Qatar's CAA renewable energy guidelines for new builds are opening design-build slots for photovoltaic canopy systems that offset cooling loads in glass-heavy passenger terminals.
- Digital Twin Convergence:The intersection of BIM platforms with real-time sensor networks is collapsing handover timelines between construction teams and airport operators, creating first-mover advantages for integrated engineering consortia.
Industry Challenges
- Legacy Radar System Interoperability:New satellite-based precision approach installations must interface with 1990s-era ground infrastructure at Dubai International and King Abdulaziz International, complicating commissioning protocols.
- Multi-Stakeholder Coordination Complexity:Terminal expansions require simultaneous alignment between sovereign wealth fund sponsors, international airline tenants, and immigration authority biometric vendors, fragmenting decision authority.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Aviation Infrastructure Market |
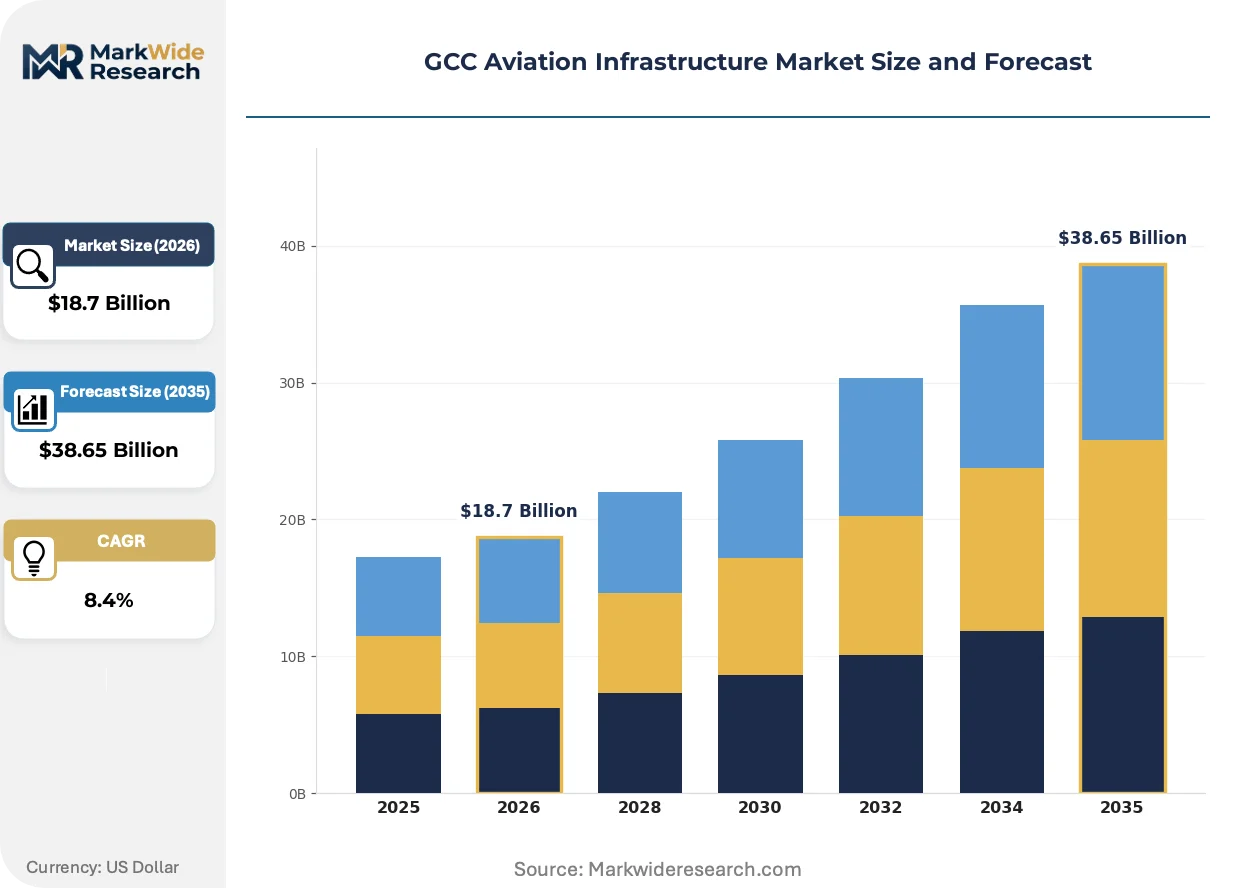
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Infrastructure Type: Airports, Runways, Hangars, Control Towers, Maintenance Facilities Stakeholder Type: Airport Operators, Ground Handling, Air Navigation Service Providers, Maintenance Organizations Technology Integration: Biometric Systems, Automated Check-in, Radar Systems, Satellite Communications, Weather Monitoring Service Offering: Passenger Handling, Cargo Management, Security Services, Facility Maintenance, Emergency Services |
| Companies Covered | TAV Construction, Dubai Aviation Engineering Projects, Binladin Contracting Group, Bechtel, AECOM, SMEC Holdings Limited, Al Jaber Group, Vinci Airports, Al Naboodah Construction, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Aviation Infrastructure Market Shifts & Advancements
Passive thermal design and predictive maintenance algorithms are displacing conventional HVAC and scheduled repair regimes across Gulf aviation infrastructure, compressing lifetime operating cost models for terminal assets.
Self-healing concrete embedded with microcapsulated repair agents is collapsing maintenance intervals for apron and taxiway surfaces exposed to thermal cycling and jet blast erosion. Dubai Airports and Abu Dhabi Airports are specifying the material in 5-year resurfacing contracts. The technology is collapsing the traditional trade-off between initial pavement thickness and lifecycle rehabilitation spend.
Saudi GACA's 2024 noise contour regulations for expanded King Abdulaziz International are forcing acoustic barrier integration into perimeter fencing and jet blast deflector redesigns. The rules affect all airside contractors bidding on Phase 4 expansions. Operators are responding by bundling noise mitigation earthworks into primary runway construction packages rather than treating them as environmental compliance add-ons.
Airline tenants at Dubai International and Hamad International are consolidating procurement authority for passenger processing infrastructure, bypassing traditional general contractor sourcing channels. The shift concentrates specification power with Emirates, Etihad, and Qatar Airways engineering divisions. Saudi Arabia's nascent Riyadh Air is replicating the model at King Salman International, creating direct vendor relationships for biometric gate hardware that sidestep airport operator intermediaries.
GCC Aviation Infrastructure Market Segmentation
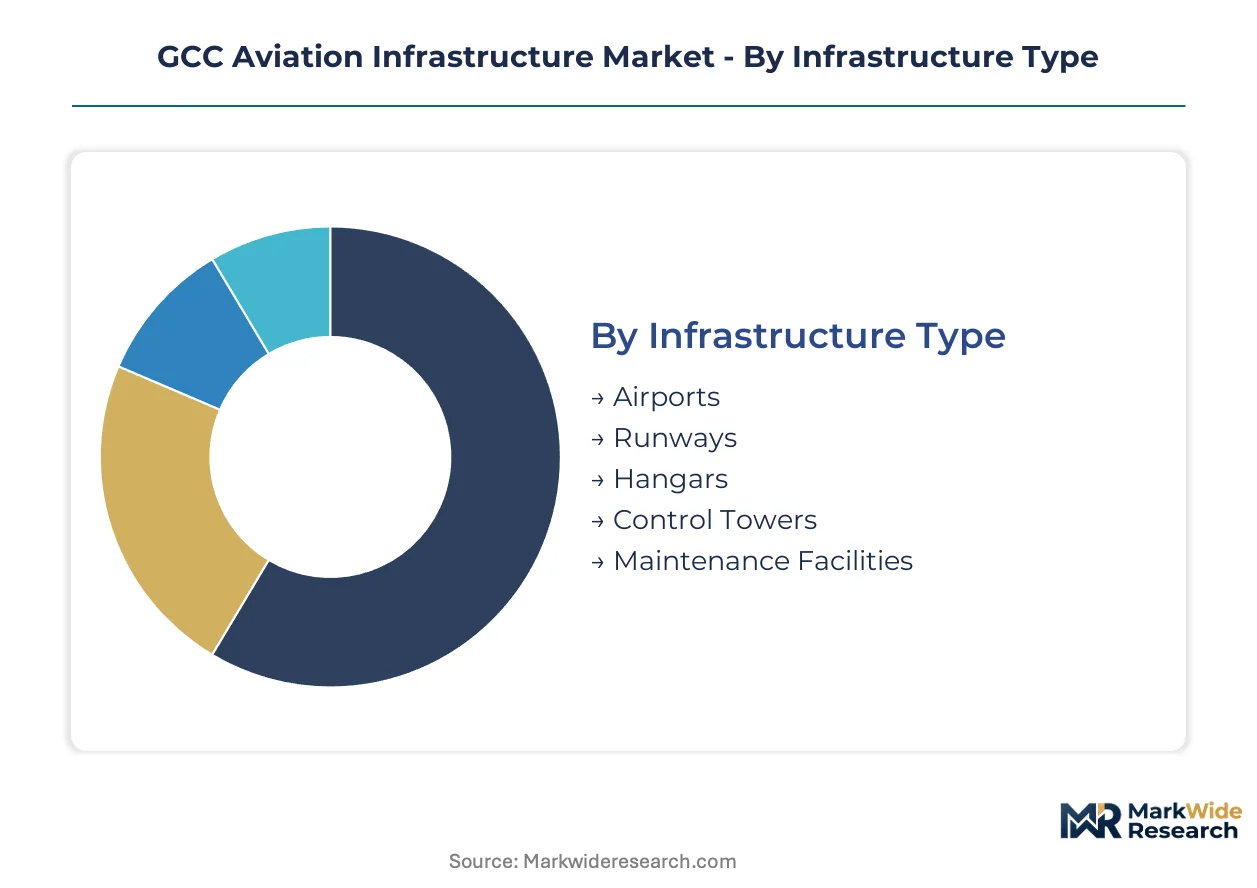
GCC aviation infrastructure segmentation reveals how capital allocation splits between physical assets and digital systems. Contract packaging strategies differ sharply across these categories, with some segments demanding design-build integration while others tolerate fragmented procurement.
Infrastructure Type:
Asset deployment spans from high-volume passenger processing hubs to specialized airside support structures, with each use-case demanding distinct engineering specifications and regulatory compliance pathways.
- Airports:Terminal complexes engineered for 30-90 million annual passenger throughput incorporate passive thermal design and biometric corridor integration. King Abdulaziz International and Dubai International absorb the majority of capital allocation as operators expand capacity to accommodate rising volumes.
- Runways:Pavement systems built to ICAO Category III-B standards support zero-visibility landings through precision approach infrastructure. Doha, Abu Dhabi, and Jeddah hubs compete for premium long-haul traffic with extended contract scopes covering satellite-based navigation aids.
- Hangars:Wide-body maintenance bays with 50°C thermal resistance specifications serve Gulf carrier fleets. Demand concentrates at Dubai South and Jeddah's King Abdullah Economic City aviation zones.
- Control Towers:Vision cab structures integrate digital surveillance feeds with legacy radar interfaces. Saudi GACA mandates are forcing replacement timelines at older Omani and Bahraini facilities.
- Maintenance Facilities:Aftermarket hangars and component shops address aging airport stock across the region. TAV Construction and Bechtel compete for these contracts through specialized MRO infrastructure expertise.
Established volume favors Airports; emerging adoption favors Maintenance Facilities.
Stakeholder Type:
Contract authority distributes across sovereign operators, privatized entities, and specialized service providers, with each stakeholder type wielding different risk allocation preferences and technical specification control.
- Airport Operators:Dubai Airports and Abu Dhabi Airports consolidate procurement for landside and airside expansions. Saudi Vision 2030 privatization timelines are redistributing project risk between state operators and international construction consortia at King Khalid International.
- Ground Handling:Apron service providers specify GSE infrastructure and cargo terminal fit-outs. Demand clusters at Emirates' Dubai hub and Qatar Airways' Doha base.
- Air Navigation Service Providers:GCAA and Saudi GACA technical divisions commission precision approach and surveillance upgrades. ICAO Annex 14 compliance requirements are forcing retrofit investments.
- Maintenance Organizations:Emirates Engineering and Saudia Technic drive hangar and component shop specifications. These entities are consolidating procurement authority for specialized infrastructure.
Procurement concentration favors Airport Operators; technical specification complexity favors Air Navigation Service Providers.
Technology Integration:
Digital infrastructure investment splits between passenger-facing processing systems and airside safety networks, with integration timelines compressing as biometric mandates tighten.
- Biometric Systems:Facial recognition corridors and smart-gate hardware now embed into base construction contracts rather than retrofit add-ons. GCAA mandates are pulling this technology into all new UAE terminal builds.
- Automated Check-in:Self-service bag drops and mobile boarding infrastructure reduce terminal footprint requirements. Qatar Airways and Etihad engineering divisions are consolidating direct vendor relationships.
- Radar Systems:Legacy ground infrastructure at Dubai International and King Abdulaziz International complicates commissioning protocols for new satellite-based precision approach installations.
- Satellite Communications:CNS/ATM infrastructure supports remote tower operations and oceanic surveillance. Saudi Arabia's greenfield airfield developments specify these systems from initial design.
- Weather Monitoring:Automated observation systems feed predictive maintenance algorithms for apron operations. Integration with digital twin platforms is collapsing handover timelines.
Regulatory pull favors Biometric Systems; interoperability challenges constrain Radar Systems.
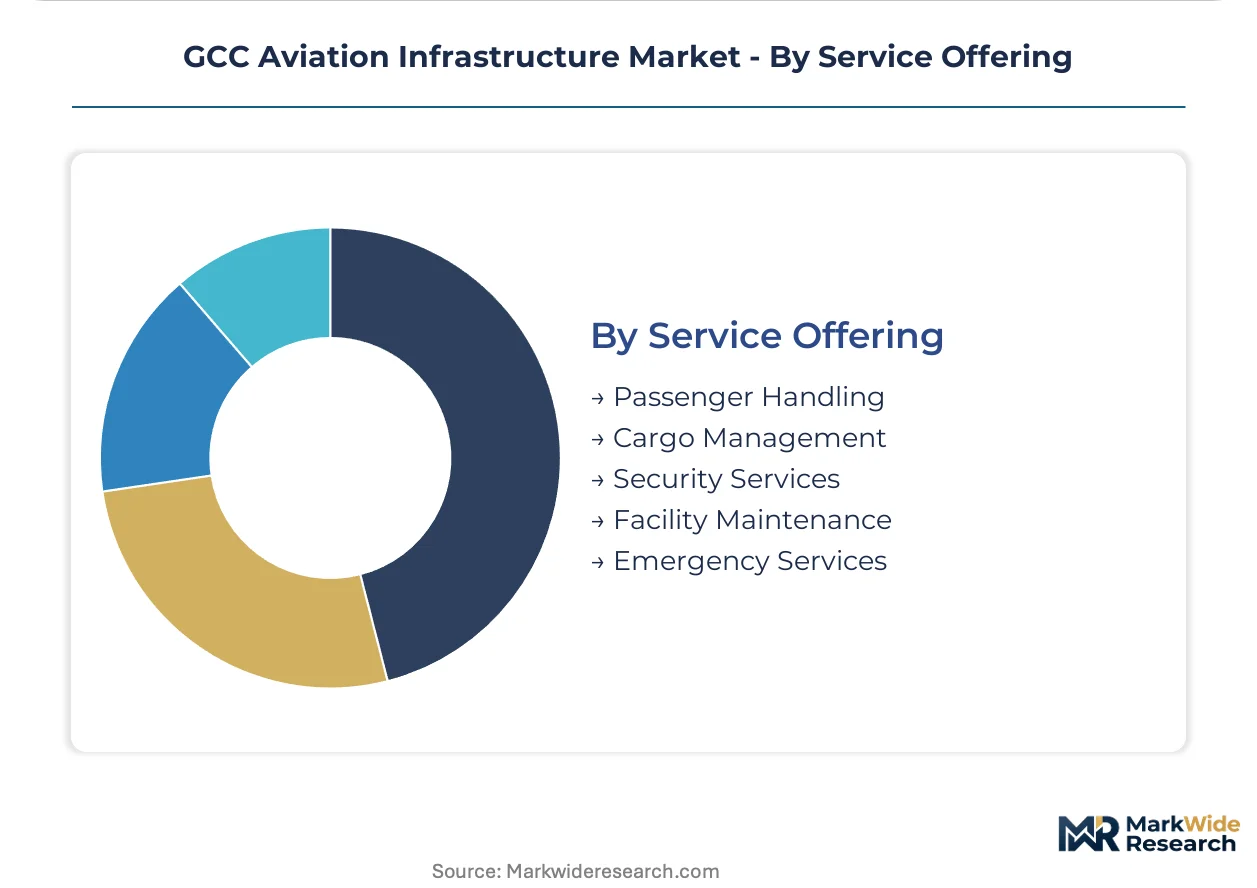
Service Offering:
Operational service segmentation determines whether infrastructure contracts bundle ongoing facility management or transfer to specialized operators post-construction.
- Passenger Handling:Terminal wayfinding, baggage systems, and lounge infrastructure serve airline tenant specifications. Emirates, Etihad, and Qatar Airways are bypassing traditional general contractor sourcing channels.
- Cargo Management:Cold chain and express freight facilities expand at Dubai World Central and Doha's Hamad International. E-commerce volume is driving dedicated freighter apron construction.
- Security Services:Hold baggage screening and access control systems integrate with biometric identity platforms. Saudi GACA extended review timelines are stretching project completion windows.
- Facility Maintenance:Predictive maintenance algorithms and self-healing concrete specifications are displacing scheduled repair regimes. Aftermarket facility maintenance revenue is rewriting profit expectations for contractors.
- Emergency Services:RFFS infrastructure and medical response facilities meet ICAO rescue and firefighting category requirements. Greenfield developments in Saudi Arabia specify these to Category 10 standards.
Airline tenant control favors Passenger Handling; lifecycle revenue potential favors Facility Maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capital allocation across the GCC splits between greenfield mega-hub development and aging facility retrofit, with Saudi Arabia and the UAE diverging sharply in procurement methodology and risk distribution models.
Saudi Arabia
King Abdulaziz International and King Khalid International drive terminal expansion contracts as passenger volumes strain 1970s-era infrastructure. GACA privatization timelines under Vision 2030 transfer project risk to international construction consortia. Riyadh anchors greenfield airfield development at King Salman International, where direct airline procurement models bypass traditional operator intermediaries.
United Arab Emirates
Dubai International and Abu Dhabi International concentrate landside and airside contract awards as hubs compete for premium long-haul traffic. GCAA smart-gate mandates embed biometric hardware into base construction rather than retrofit phases. Dubai South aviation zone absorbs wide-body hangar demand from Emirates Engineering and third-party MRO providers.
Qatar
Hamad International expansion contracts incorporate CAA renewable energy guidelines for photovoltaic canopy systems. Qatar Airways engineering divisions consolidate procurement authority for passenger processing infrastructure. Doha maintains precision approach infrastructure competition with Abu Dhabi and Jeddah through satellite-based navigation aid deployments.
Oman
Muscat International faces mandatory ICAO Annex 14 compliance upgrades for pavement strength and navigation aids originally built to superseded standards. The retrofit market creates captive demand for specialized airside contractors targeting regulatory-driven rehabilitation. Sohar and Salalah secondary airports absorb smaller-scale terminal modernization packages.
Bahrain
Bahrain International Airport's pre-2010 infrastructure triggers extended GACA-aligned review timelines for fuel farm separation and noise contour compliance. The facility's constrained footprint forces vertical expansion strategies rather than greenfield alternatives. Muharraq aviation zone development lags Saudi and UAE hubs in contract scale but maintains consistent MRO facility demand.
GCC Aviation Infrastructure Market Competitive Landscape
Capability concentration sits with design-build specialists possessing Ankara-built terminal expertise; scale advantage sits with US-based engineering conglomerates anchoring greenfield airfield developments. The vendor base stratifies across three tiers: integrated digital engineering platforms, regional construction heavyweights with sovereign relationships, and specialized MRO infrastructure boutiques. Consolidation pressure operates through airline tenant procurement centralization and airport operator privatization timelines. Dominant competitive moves include backward integration into self-healing concrete supply chains and technology licensing partnerships for biometric corridor hardware.
Within the regional construction tier, TAV Construction leverages Ankara-built expertise to compete for terminal expansion tenders, while Binladin Contracting Group anchors Saudi market presence through sovereign project relationships. Bechtel occupies a position among US-based engineering conglomerates securing design-build contracts for greenfield airfield developments. AECOM exemplifies the integrated digital engineering archetype through platforms that compress construction-phase change order exposure.
| Leading Market Players |
|---|
| TAV Construction |
| Dubai Aviation Engineering Projects |
| Binladin Contracting Group |
| Bechtel |
| AECOM |
| SMEC Holdings Limited |
| Al Jaber Group |
| Vinci Airports |
| Al Naboodah Construction |
| Others |
Supply & Pricing Matrix
Undercapacity in South Korean high-temperature asphalt formulation plants drives input cost volatility and forces GCC contractors into long-term offtake commitments with German chemical producers, compressing margin flexibility across runway and apron construction packages.
Pricing Analysis
Project-based contract structures dominate GCC aviation infrastructure, with design-build tenders bundling materials, labor, and technology integration into lump-sum awards. Price differentiation hinges on ICAO certification tier and sovereign relationship depth, with GACA-preferred contractors commanding premiums over non-aligned bidders. Cost compression in terminal fit-out segments intensifies as airline tenants consolidate direct procurement authority. International construction consortia exhibit lowest price sensitivity due to balance-sheet capacity, while regional subcontractors face acute margin pressure from skilled MEP labor scarcity.
Supply Chain Analysis
South Korean and German chemical producers hold concentrated capacity for heat-resistant pavement formulations, with no regional alternatives qualified to 50°C performance specifications. Raw material dependencies center on specialized polymer modifiers, synthetic binders, and microcapsulated repair agents for self-healing concrete. Single-source vulnerability runs through the asphalt additive tier, where plant certification timelines lock in supplier relationships. Distribution runs through sovereign wealth fund procurement portals and airport operator tender platforms, with limited spot-market liquidity for specialized airside materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Emirates, Etihad, and Qatar Airways engineering divisions bypass traditional general contractor channels, fragmenting specification authority and compressing intermediary margins across passenger processing infrastructure.
For Market Incumbents: Harden sovereign relationships through early engagement with Saudi Vision 2030 privatization timelines, securing design-build slots before risk transfer to international consortia finalizes. Deepen backward integration into self-healing concrete supply chains to capture lifecycle maintenance revenue from aging Omani and Bahraini retrofit markets. Threat: Airline tenant procurement centralization erodes traditional airport operator intermediation. For New Entrants and Emerging Players: Pursue specialized MRO infrastructure contracts at Dubai South and Jeddah's King Abdullah Economic City aviation zones, where wide-body hangar demand outpaces incumbent capacity. Target Oman and Bahrain regulatory-driven rehabilitation markets for pavement strength and navigation aid upgrades, segments where ICAO Annex 14 compliance mandates create captive demand. Go-to-market angle: Digital twin integration capabilities that collapse handover timelines between construction teams and airport operators. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among facility maintenance operators deploying predictive maintenance algorithms across aging GCC airport stock, with aftermarket service contracts extending 10-15 year visibility. Acquisition target archetype: Regional construction heavyweights with sovereign project relationships and biometric corridor technology licensing partnerships. Signal to watch: Saudi GACA privatization timeline acceleration as inflection indicator for capital pool unlocking.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Self-Healing Concrete | Captures lifecycle maintenance revenue from Dubai Airports 5-year resurfacing contracts. |
| Biometric Corridor Technology Licensing | Secures specification inclusion in GCAA-mandated UAE terminal builds. |
| Digital Twin Platform Development | Compresses handover timelines for integrated engineering consortia competing for Saudi greenfield awards. |
| Solar-Integrated Terminal Roof Design-Build | Aligns with Qatar CAA renewable energy guidelines for photovoltaic canopy systems. |
| Specialized MRO Infrastructure Capacity Addition | Serves Emirates Engineering and Saudia Technic consolidation of hangar procurement authority. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with airport operators, EPC contractors, and airline engineering divisions, and secondary validation through GACA regulatory filings, GCAA safety mandate documentation, and sovereign wealth fund procurement disclosures. Stakeholder interviews encompassed terminal construction directors, airside pavement engineers, biometric systems integrators, and MRO facility planners. Secondary sources included ICAO Annex 14 compliance databases, airport authority annual reports, and customs records for specialized pavement material imports. Bottom-up project pipeline aggregation triangulated against top-down capital expenditure forecasts.
Forecast inputs considered infrastructure type deployment schedules, technology integration adoption curves, and stakeholder procurement centralization trends across the projection horizon. Segmentation dimensions modeled encompass infrastructure type, stakeholder category, technology integration level, and service offering structure. CAGRs were derived from regression analysis of historical contract award values against passenger volume trajectories and regulatory mandate implementation timelines. Industry-specific inputs included ICAO Category III-B upgrade completion schedules and Saudi Vision 2030 privatization phase transitions.
Sensitivities concentrate around GACA review timeline extensions, South Korean asphalt additive supply disruptions, and airline tenant procurement model adoption rates. Forecasts embed assumptions regarding sovereign capital commitment continuity and skilled labor import policy stability. Quarterly review of privatization milestone progress, pavement material price indices, and biometric mandate enforcement rigor is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
Airport Logistics Systems Market
Airport Infrastructure
Heliports Market
Airport Infrastructure
Aviation Infrastructure Market
Airport Infrastructure
Ground Support Equipment Market
Airport Infrastructure
Airport Lighting Market
Airport Infrastructure
Passenger Boarding Bridge Market
Airport Infrastructure
Fixed-Base Operator Market
Airport Infrastructure
North America Aviation Infrastructure Market
Airport Infrastructure
Ground Handling Systems Market
Airport Infrastructure
Aircraft Catering Vehicle Market
Airport Infrastructure
India Aviation Infrastructure Market
Airport Infrastructure
Aircraft Tow Tractors Market
Airport Infrastructure
Aircraft Cargo Handling Equipment Market
Airport Infrastructure
Airport Services Market
Airport Infrastructure
Global Commercial Airport Lighting Market
Airport Infrastructure
South-East Asia Aviation Infrastructure Market