
 Military Sensors Cybersecurity Solutions Market | 2026-2036
Military Sensors Cybersecurity Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Military Sensors Cybersecurity Solutions Market Analysis
Defense procurement channels across European Union member states is tilting toward sovereign cybersecurity vendors with classified facility clearances. L3Harris Technologies leverages its NATO-certified secure communications infrastructure to anchor multi-year sensor protection contracts. Thales Group competes through vertically integrated encryption modules that sustain domestic supply chain requirements under EU defence procurement rules.
Military sensors cybersecurity solutions encompass hardware and software architectures that protect electro-optical, radar, acoustic, and chemical-biological sensor arrays from unauthorized access, data exfiltration, and mission-degrading interference through cryptographic isolation, zero-trust network segmentation, and real-time anomaly detection operating at sub-millisecond latency thresholds. Network security and secure communication product categories lead current procurement volumes as legacy sensor networks undergo hardening against supply chain infiltration. AI Security and Threat Intelligence technologies represent the fastest-expanding technology segments where margin pools concentrate around predictive threat modeling for autonomous sensor platforms.
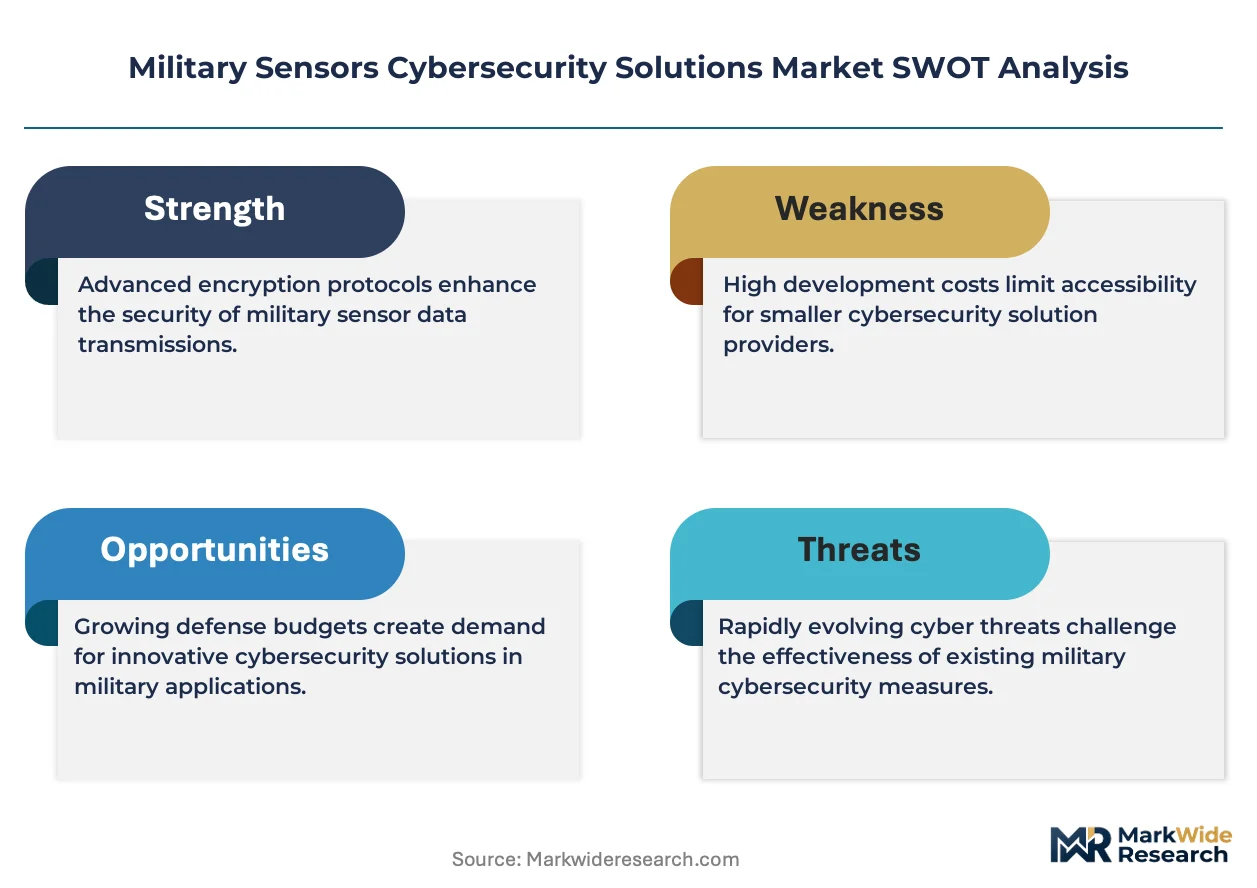
EMA, EU Cyber Defence Policy Framework, and NIS2 Directive collectively mandate baseline encryption standards and incident reporting protocols for defense-critical sensor infrastructure across European member states, directly conditioning market access on certified compliance management service capabilities. National regulators including Germany's BSI and France's ANSSI enforce supplementary technical controls that fragment certification pathways. Stakeholders must monitor divergence between EU-wide harmonization ambitions and member-state specific technical requirements when scaling sensor cybersecurity architectures.
Market Dynamics
The EU Cyber Defence Policy Framework and NIS2 Directive are compressing procurement timelines for hardened sensor architectures, forcing defense agencies to pre-qualify vendors on encryption certification before contract release rather than during execution.
Growth Catalysts
- Zero-trust network segmentation:NATO member states mandate microsegmentation for all electro-optical sensor arrays, creating pull for sub-millisecond anomaly detection systems.
- France's ANSSI technical controls:Supplementary encryption standards for radar and acoustic sensors expand addressable market for certified compliance management services.
- Autonomous platform proliferation:Unmanned aerial and ground systems require predictive threat modeling capabilities, accelerating AI Security segment expansion.
Market Restraints
- Semiconductor supply concentration:Advanced cryptographic processors depend on Taiwan and South Korea fabrication capacity, exposing sensor hardening programs to geopolitical disruption.
- BSI-ANSSI regulatory divergence:Germany and France enforce non-harmonized certification pathways, fragmenting vendor scaling economics across EU member states.
- Legacy analog sensor substitution:Older radar and chemical-biological arrays resist digital retrofitting, capping addressable upgrade volume in established NATO inventories.
Strategic Opportunities
- Poland and Baltic states:These NATO frontline members lack indigenous sensor cybersecurity capacity, opening acquisition pathways for EU-certified vendors with classified facility clearances.
- Quantum-resistant encryption:Convergence of post-quantum cryptographic standards with hardware security modules creates first-mover advantage for module suppliers.
- Direct defense agency contracting:National military cyber commands in Germany, France, and the United Kingdom now hold autonomous budgets, bypassing traditional prime contractor intermediation.
Industry Challenges
- Cryptographic engineering talent scarcity:Sub-millisecond latency requirements for real-time anomaly detection exceed current workforce supply in EU defense technology clusters.
- Cross-domain integration complexity:Electro-optical, radar, and acoustic sensor arrays use incompatible legacy protocols, multiplying system-of-systems certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Sensors Cybersecurity Solutions Market |
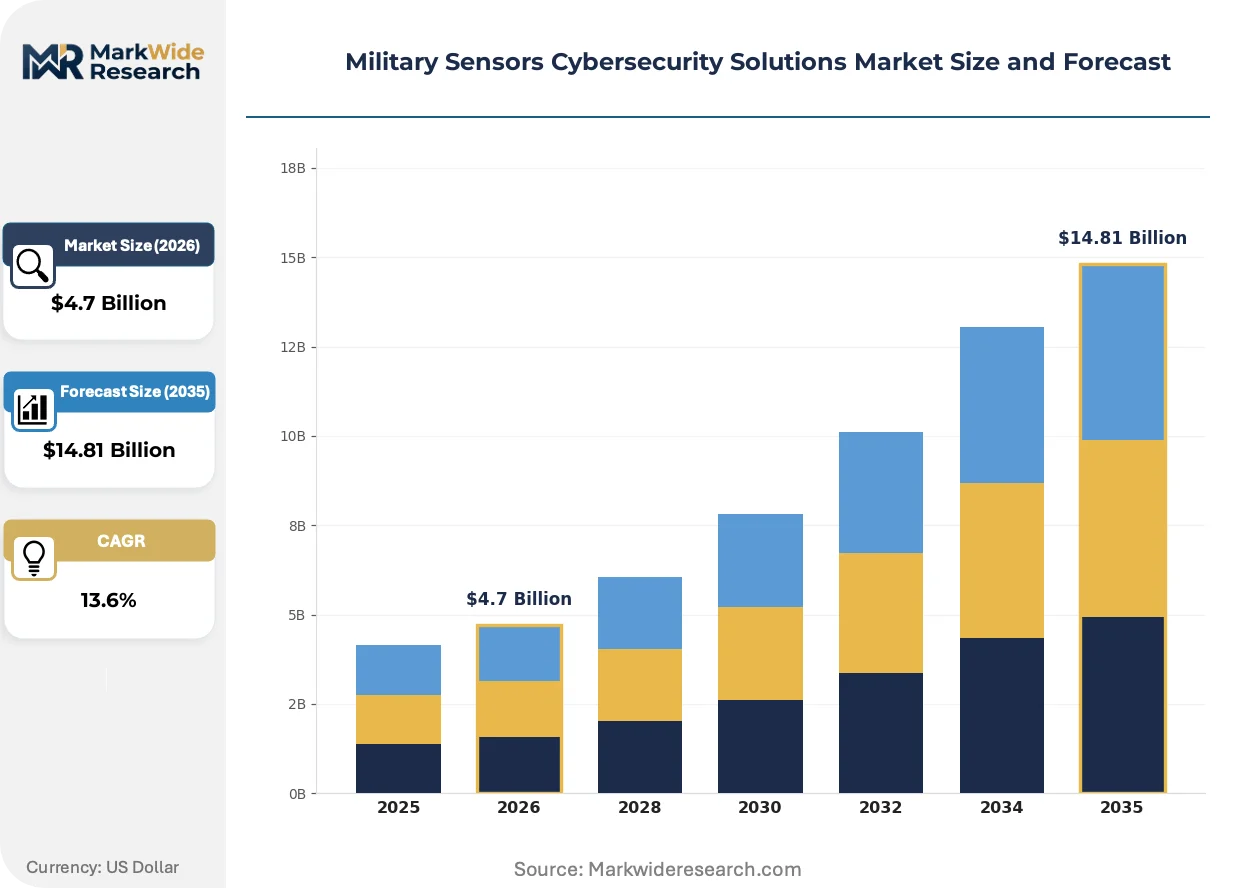
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $14.81 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Network Security, Endpoint Protection, Intrusion Detection, Secure Communication Technology: Encryption, Blockchain, AI Security, Threat Intelligence End User: Defense Agencies, Private Contractors, Government Entities, Research Institutions Service Type: Consulting, Managed Services, Incident Response, Compliance Management |
| Companies Covered | L3Harris Technologies, Thales Group, Lockheed Martin Corporation, Curtiss-Wright Corporation, General Dynamics Corporation, BAE Systems plc, Northrop Grumman Corporation, TE Connectivity Ltd., RTX Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Sensors Cybersecurity Solutions Market Emerging Trajectories
Defense procurement patterns are compressing around sovereign capability requirements, with encryption certification displacing price as the primary vendor selection criterion across European military sensor programs.
Post-quantum cryptographic algorithms are migrating from laboratory validation to field deployment in radar and electro-optical sensor arrays. Germany's BSI and France's ANSSI have accelerated pre-standardization testing timelines, compressing vendor qualification windows from thirty-six to eighteen months. This migration from theoretical security models to hardware-embedded implementations is forcing established suppliers to re-architect encryption modules around lattice-based and hash-based protocols.
The EU AI Act and NIS2 Directive collectively mandate algorithmic transparency for autonomous sensor platforms, requiring explainable anomaly detection outputs. Defense procurement officers must now document decision pathways for AI-driven threat classifications, adding compliance layers to real-time processing architectures. Network security product categories face the steepest adaptation burden, as legacy black-box detection systems require retrofitting with interpretable model structures.
Outcome-based service contracts are displacing traditional hardware-plus-maintenance agreements in UK and French sensor cybersecurity programs. Defense agencies now purchase guaranteed uptime and threat detection accuracy rather than discrete equipment, transferring operational risk to vendor balance sheets. This shift concentrates margin in predictive analytics capabilities and compresses pure hardware margins, with Germany's military cyber command piloting similar performance-based structures for acoustic sensor protection.
Military Sensors Cybersecurity Solutions Market Segmentation
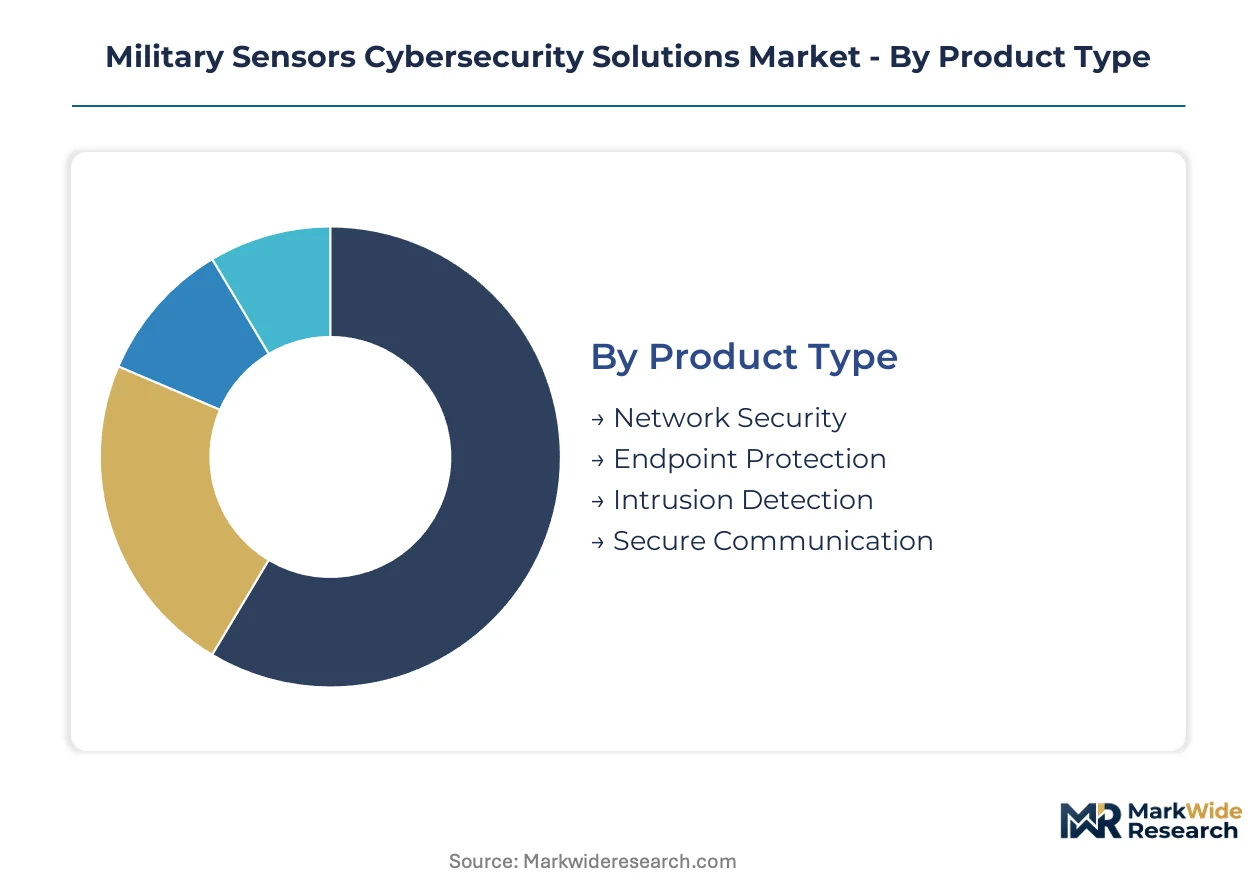
Military sensor cybersecurity architectures fragment across four critical dimensions: protective product layers, enabling technologies, contracting entities, and service delivery models. Each segmentation axis reveals distinct procurement pathways and margin concentration zones within NATO defense budgets.
Product Type:
Mature perimeter defenses dominate current procurement volumes while emerging endpoint architectures reshape investment priorities.
- Network Security:Microsegmentation appliances and zero-trust gateways isolate electro-optical and radar sensor arrays from lateral movement. Germany's military cyber command prioritizes these systems for acoustic sensor networks along Baltic borders.
- Secure Communication:NATO-certified encrypted datalinks protect sensor-to-command telemetry against interception and spoofing. France's ANSSI mandates these modules for all autonomous platform deployments, creating sovereign vendor preference.
- Endpoint Protection:Hardened firmware and runtime integrity verification for distributed sensor nodes.
- Intrusion Detection:Signature and behavioral monitoring systems for legacy analog-to-digital sensor bridges.
Network Security handles the majority of throughput; Secure Communication is the fastest mover on share.
Technology:
Cost tiers separate commodity cryptographic implementations from premium AI-driven threat modeling capabilities.
- AI Security:Sub-millisecond anomaly detection engines process sensor telemetry through explainable neural architectures. The EU AI Act mandates interpretable outputs for autonomous platform threat classifications, adding compliance engineering costs.
- Encryption:Post-quantum lattice-based and hash-based protocols migrate from BSI/ANSSI pre-standardization testing into field-deployed hardware security modules.
- Threat Intelligence:Predictive modeling platforms aggregate multi-source indicators for proactive sensor defense.
- Blockchain:Distributed ledger architectures for sensor configuration integrity and supply chain attestation.
Encryption absorbs the largest share of R&D expenditure; AI Security is climbing the fastest on procurement priority lists.
End User:
Customer type determines contracting velocity, with direct defense agency relationships accelerating fastest.
- Defense Agencies:National military cyber commands in Germany, France, and the United Kingdom hold autonomous procurement authority, bypassing traditional prime contractor structures for sensor hardening programs.
- Private Contractors:Systems integrators and platform OEMs embed cybersecurity modules into delivered sensor suites under sovereign capability requirements.
- Government Entities:Border security and critical infrastructure agencies with defense-adjacent sensor networks.
- Research Institutions:Academic and national laboratory partners developing next-generation cryptographic and AI security prototypes.
Defense Agencies command the dominant procurement volume; Private Contractors are gaining share fastest through embedded security mandates.
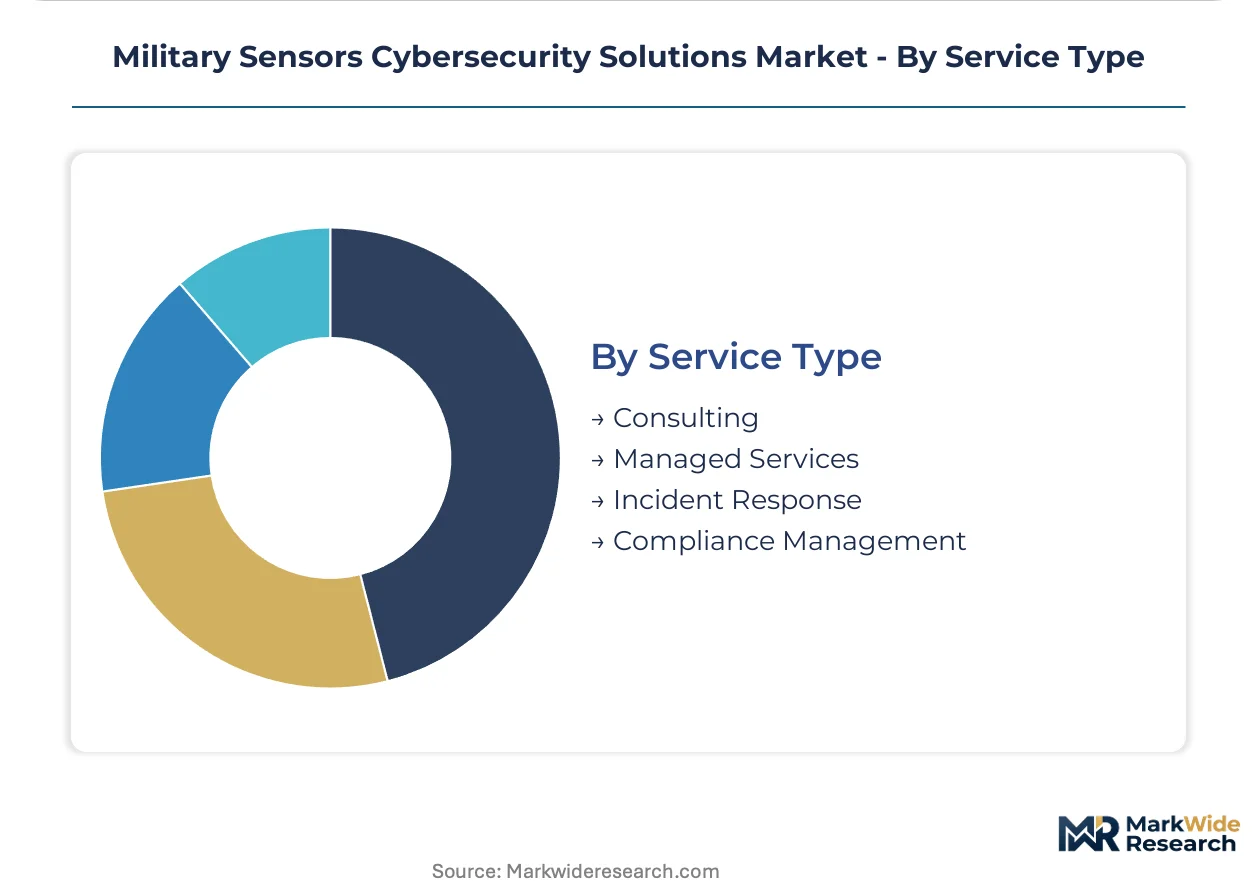
Service Type:
Margin pools concentrate in outcome-based delivery models displacing traditional hardware-plus-maintenance agreements.
- Compliance Management:Certification pathway navigation across BSI, ANSSI, and NATO harmonization frameworks. Vendors with classified facility clearances capture premium pricing for EU defence procurement rule adherence.
- Managed Services:Guaranteed uptime and threat detection accuracy contracts transfer operational risk to vendor balance sheets. The United Kingdom and France pilot these structures for sensor cybersecurity.
- Incident Response:Rapid deployment teams for sensor network breach containment and forensic recovery.
- Consulting:Architecture design and zero-trust migration planning for legacy sensor hardening.
Compliance Management carries the heaviest margin concentration; Managed Services is expanding most quickly as performance-based contracting spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Cyber Defence Policy Framework and NIS2 Directive are compressing procurement timelines for hardened sensor architectures across NATO member states. Defense agencies now pre-qualify vendors on encryption certification before contract release.
Germany
Berlin's military cyber command holds autonomous procurement authority for acoustic sensor networks along Baltic borders. The BSI enforces supplementary technical controls that mandate post-quantum cryptographic testing timelines. Munich and Stuttgart host concentrated clusters of sensor hardening specialists serving Bundeswehr modernization programs.
France
ANSSI mandates encrypted datalinks for all autonomous platform deployments, creating sovereign vendor preference in defense procurement. The country's national cyber defense regulator accelerates pre-standardization testing for lattice-based protocols. Paris and Toulouse industrial clusters concentrate encryption module development for radar and electro-optical arrays.
United Kingdom
British military cyber commands pilot outcome-based service contracts for sensor cybersecurity, purchasing guaranteed uptime rather than discrete equipment. The UK Ministry of Defence embeds sovereign capability requirements into platform OEM specifications. Bristol and Greater London house specialist vendors supplying hardened communications infrastructure.
Poland
Warsaw accelerates procurement of hardened sensor protection systems as a NATO frontline member lacking indigenous cybersecurity capacity. The country's national defense procurement agency prioritizes EU-certified vendors with classified facility clearances. Poznan and Wroclaw emerging technology clusters attract compliance management service providers.
United States
The Department of Defense drives demand for sub-millisecond anomaly detection systems protecting electro-optical sensor arrays on autonomous platforms. NSA and DOD cyber commands mandate zero-trust network segmentation across classified sensor networks. Maryland and Virginia defense corridors concentrate prime contractor operations for NATO-interoperable systems.
Military Sensors Cybersecurity Solutions Market Vendor Landscape
On the supply side, the industry is consolidating around sovereign capability requirements with encryption certification displacing price as the primary vendor selection criterion. Three strategic archetypes dominate: NATO-certified secure communications infrastructure providers, vertically integrated encryption module suppliers, and AI-driven threat modeling specialists. Competitive moves concentrate on strategic partnerships for quantum-resistant cryptographic development and direct defense agency contracting that bypasses traditional prime intermediation.
Among established defense contractors, L3Harris Technologies and Thales Group exemplify the sovereign vendor archetype with classified facility clearances anchoring multi-year sensor protection contracts. Lockheed Martin Corporation occupies a position representing the prime contractor tier adapting to direct agency contracting trends. These three entities illustrate the market's gravitational pull toward vendors capable of navigating fragmented BSI-ANSSI certification pathways while delivering NATO-interoperable hardened architectures.
| Leading Market Players |
|---|
| L3Harris Technologies |
| Thales Group |
| Lockheed Martin Corporation |
| Curtiss-Wright Corporation |
| General Dynamics Corporation |
| BAE Systems plc |
| Northrop Grumman Corporation |
| TE Connectivity Ltd. |
| RTX Corporation |
| Others |
Supply Flow & Price Mechanics
Taiwan and South Korea fabrication capacity for advanced cryptographic processors anchors margin concentration in hardware security module suppliers, with NATO certification premiums capturing value downstream from semiconductor chokepoints.
Pricing Analysis
Volume-discount tiering structures separate prime contractor embedded security bundles from direct defense agency procurement. Three-tier pricing stratifies across NATO-certified premium modules, standard EU-compliant configurations, and economy-grade retrofit kits for legacy analog arrays. Price differentiation hinges on BSI/ANSSI certification grade and sovereign facility clearance status. Cost compression in economy tiers intensifies as Polish and Baltic defense agencies consolidate orders. Direct defense agency buyers in Germany, France, and the United Kingdom exhibit lowest price sensitivity due to autonomous budget authority.
Supply Chain Analysis
Export-control regimes under EU dual-use technology regulations and US ITAR restrictions limit cryptographic processor flows to certified facility vendors. Taiwan, South Korea, and the United States concentrate advanced semiconductor fabrication for lattice-based encryption engines. Hardware security modules draw from gallium nitride substrates, tamper-resistant enclosures, and post-quantum algorithm IP licensed from BSI/ANSSI pre-standardization programs. Single-source vulnerability in Taiwan fabrication exposes sensor hardening timelines to geopolitical disruption. Distribution runs through sovereign-cleared systems integrators and direct national military cyber command contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as NATO interoperability standards and EU NIS2 Directive compliance create ecosystem lock-in around certified encryption modules, with sensor-to-command datalink standardization consolidating vendor positions.
For Market Incumbents: Entrench certification moats by accelerating post-quantum cryptographic module re-architecture ahead of BSI-ANSSI harmonization deadlines. Deepen backward integration into hardware security module fabrication to offset Taiwan semiconductor concentration risk. Lock in multi-year direct defense agency contracts in Germany, France, and the United Kingdom before prime contractor intermediation revives. For New Entrants and Emerging Players: Poland and Baltic states' absence of indigenous sensor cybersecurity capacity represents the most penetrable entry point for EU-certified vendors with classified facility clearances. AI-driven explainable anomaly detection for autonomous platforms offers uncaptured margin pools as legacy black-box systems face EU AI Act retrofit mandates. Partner with national research institutions for BSI/ANSSI pre-standardization testing access. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across post-quantum cryptographic hardware development, favoring asset-light AI security software specialists with predictable R&D conversion. Acquisition targets should demonstrate NATO-certified secure communications infrastructure or direct defense agency contracting relationships. Monitor BSI-ANSSI regulatory convergence timelines as signal for vendor scaling economics inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptographic Module Development | BSI and ANSSI pre-standardization testing compresses eighteen-month vendor qualification windows for lattice-based protocol deployment. |
| Direct Defense Agency Contracting | Germany's military cyber command and France's ANSSI bypass prime intermediaries for sensor hardening procurement autonomy. |
| AI Security Platform Integration | EU AI Act mandates explainable anomaly detection outputs for autonomous sensor platform threat classifications. |
| Strategic Partnership for Semiconductor Supply | Taiwan and South Korea fabrication concentration demands sovereign-cleared vendor alliances for cryptographic processor security. |
| Compliance Management Service Expansion | EU NIS2 Directive and Cyber Defence Policy Framework mandate certified incident reporting for defense-critical sensor infrastructure. |
Methodological Framework
A spread of perspectives from defense procurement officers at national military cyber commands, cryptographic engineering leads at hardware security module suppliers, compliance managers navigating BSI-ANSSI certification pathways, and platform OEM integration specialists converged on the working assumptions. Primary interview insights triangulated against NATO procurement databases, EU NIS2 Directive implementation filings, BSI technical guideline releases, ANSSI certification registries, and defense agency budget appropriation documents. Bottom-up sensor deployment forecasts reconciled with top-down NATO member state cybersecurity expenditure allocations.
Demand-supply balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled encompass protective product layers, enabling technologies, contracting entity types, and service delivery models, with additional granularity on certification pathway complexity. CAGRs derived from defense budget trajectory analysis and technology substitution curves for legacy analog sensor retrofit cycles. Forecast inputs incorporated EU AI Act compliance engineering cost burdens and post-quantum cryptographic hardware refresh timelines.
Practitioners should monitor BSI-ANSSI regulatory harmonization progress, Taiwan semiconductor supply disruptions, and NATO autonomous platform deployment acceleration for early signals. Forecasts reflect assumptions on certification pathway stability and sovereign vendor preference durability. Material shifts in EU-wide encryption standard centralization or export-control regime expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense Cybersecurity
Electronic Warfare Market
Defense Cybersecurity
Blockchain Technology in Aerospace and Defense Market
Defense Cybersecurity
Electronic Countermeasures Market
Defense Cybersecurity
Automotive Cyber Security Market
Defense Cybersecurity
Military Cybersecurity Market
Defense Cybersecurity
Europe Automotive Cybersecurity Market
Defense Cybersecurity
Global Handheld Counter IED Market
Defense Cybersecurity
Global C4I Systems Market
Defense Cybersecurity
Maritime Cybersecurity Market
Defense Cybersecurity
Defence Cybersecurity Market
Defense Cybersecurity
Railway Cyber Security Market
Defense Cybersecurity
Automotive Cybersecurity Service Market
Defense Cybersecurity
Anti-Drone Defense System Market
Defense Cybersecurity
High Energy Lasers Market
Defense Cybersecurity
Vehicle Cybersecurity Market
Defense Cybersecurity
Ballistics Targeting Software Market