
 Aerospace Sealants Market | 2026-2036
Aerospace Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Sealants Market Analysis
The shift from single-source to multi-source procurement for polysulfide and silicone aerospace sealants is broadening supplier access across tiered vendor bases. PPG Industries leverages captive resin synthesis to sustain margin control across fuel tank sealing applications. Henkel anchors European MRO channels through qualified distributor networks. Huntsman Corporation differentiates via specialized epoxy formulations for composite bonding in next-generation airframes.
Aerospace sealants are polymeric compounds engineered to withstand temperature extremes from minus sixty-five to plus four hundred degrees Fahrenheit while maintaining adhesion to aluminum, titanium, and composite substrates; their primary purpose is to prevent fluid ingress, maintain pressurized cabin environments, and inhibit corrosion across airframe joints and seams. Silicone formulations lead the product type category due to established qualification heritage on commercial transport programs, while polyurethane sealants represent the fastest-expanding segment driven by weight-reduction targets on narrowbody platforms. Within end user channels, OEMs concentrate the highest value per airframe, though MROs extend the recurring revenue pool as fleet operating hours accumulate.
The Federal Aviation Administration mandates flammability resistance under FAR 25.853, while the European Union Aviation Safety Agency enforces EASA Part 21 design standards that shape sealant qualification protocols for European-registered aircraft. EPA regulations on hexavalent chromium content are forcing reformulation timelines for legacy polysulfide products used in military and commercial maintenance. Stakeholders must monitor evolving OEM specifications for out-of-autoclave composite manufacturing, as these processes demand cure-compatible sealant chemistries that depart from traditional autoclave-tolerant formulations.
Market Dynamics
REACH chemical restrictions and the EU Green Deal are forcing immediate reformulation of legacy polysulfide sealants, compressing qualification timelines while OEMs simultaneously demand cure-compatible chemistries for out-of-autoclave composite manufacturing.
Growth Catalysts
- Commercial aviation fleet expansion:Narrowbody and widebody production rate increases at Boeing and Airbus facilities are accelerating sealant consumption for fuel tank integrity and cabin pressure sealing applications.
- FAR 25.853 flammability mandates:FAA regulations governing fire resistance in aircraft interiors are sustaining qualified silicone sealant demand across OEM and MRO channels.
- Chromate-free chemistry transition:EPA restrictions on hexavalent chromium content in maintenance compounds are pulling demand toward reformulated polysulfide alternatives with equivalent corrosion inhibition performance.
Market Restraints
- Specialty polymer feedstock concentration:Key silicone and polysulfide resin precursors originate from concentrated petrochemical complexes in the United States and Germany, exposing formulators to input cost volatility and supply interruption risk.
- Qualification heritage lock-in:Decades-long airframe certification histories create switching friction that protects incumbent sealant specifications and delays competitive entry for novel chemistries.
- Two-part formulation complexity:Precision mixing requirements for aerospace-grade sealants demand specialized application equipment and trained technicians, constraining deployment flexibility in field maintenance environments.
Strategic Opportunities
- India defense aviation modernization:Indigenous fighter and transport aircraft programs under the Ministry of Defence are creating qualification pathways for sealant suppliers willing to establish local technical support infrastructure.
- Battery thermal management sealing:Electric and hybrid-electric propulsion prototypes require dielectric, flame-resistant sealant formulations for high-voltage battery enclosures and power distribution systems.
- Urban air mobility airframe assembly:Emerging eVTOL manufacturers in the United States and Germany are specifying rapid-cure sealants compatible with automated dispensing and reduced touch-labor assembly lines.
Industry Challenges
- Application technician certification scarcity:Qualified sealant applicators with airframe-specific training credentials are concentrated at major MRO hubs, creating bottlenecks for regional maintenance expansion.
- Dual qualification burden:Suppliers must simultaneously satisfy FAA and EASA certification protocols for global airframe programs, duplicating testing expenditure and extending time-to-revenue for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Sealants Market |
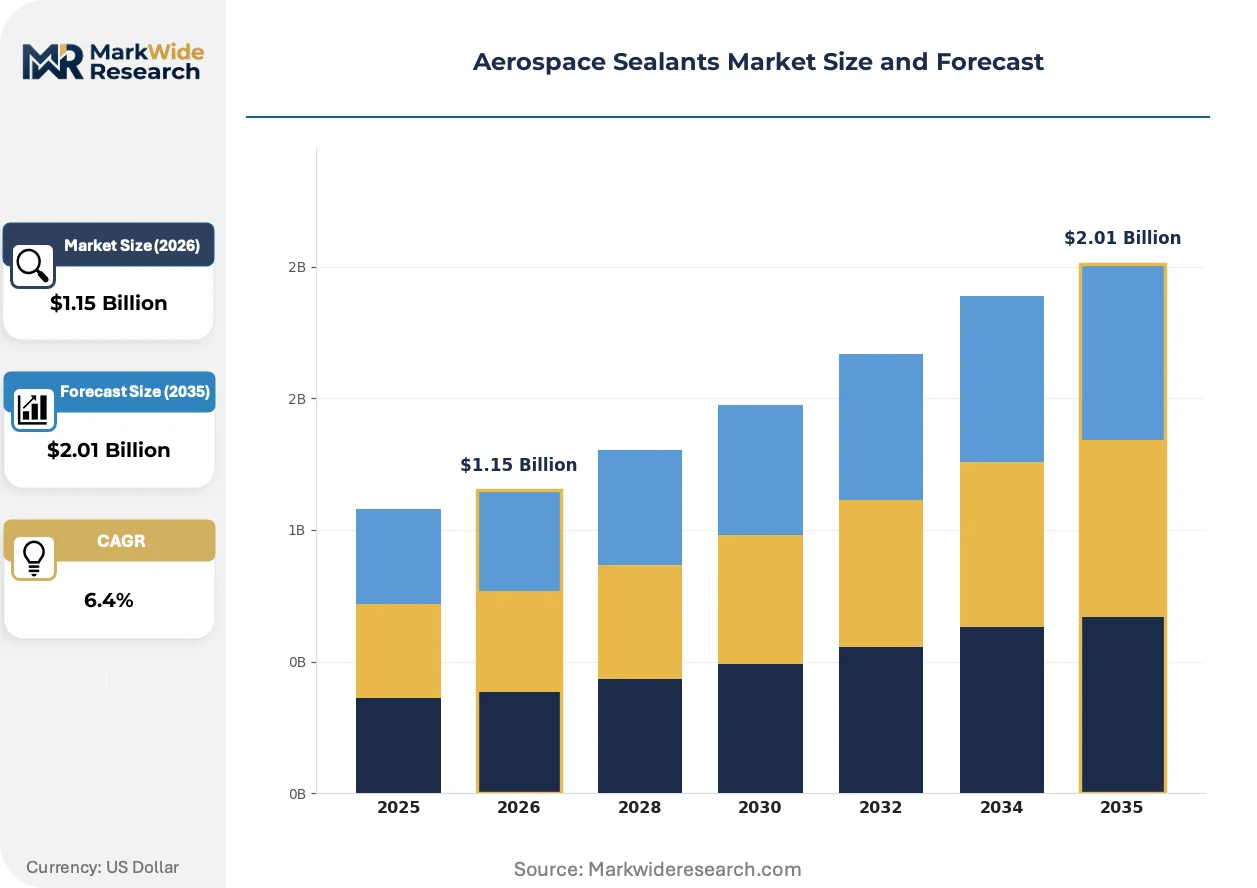
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $2.01 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Silicone, Polyurethane, Epoxy Application: Aerospace, Military, Commercial, General Aviation Technology: Curing, Adhesive Bonding, Surface Treatment, Coating End User: OEMs, MROs, Tier-1 Suppliers, Aftermarket Providers |
| Companies Covered | PPG Industries, Henkel, 3M, Solvay, Flamemaster, H.B. Fuller Company, Chemetall, Dow, Huntsman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Sealants Market Emerging Trajectories
Reformulation chemistry, regulatory compliance automation, and procurement digitization are converging to reshape how sealant specifications propagate from OEM engineering offices through tiered supply chains to point-of-use application.
Room-temperature vulcanizing silicone formulations with self-leveling characteristics are rewriting application economics for fuel tank sealing. MRO operators at Dallas-Fort Worth and Frankfurt maintenance hubs are adopting these materials to reduce cure-cycle downtime during C-check intervals. The technology is compressing labor-hour requirements per sealant application while maintaining the temperature and fluid resistance specifications demanded by engine nacelle and wing box assemblies.
EASA Part 21 design standards are tightening documentation requirements for sealant traceability across European-registered aircraft. Manufacturers must now maintain digital records linking batch numbers to specific airframe serial numbers, with audit protocols enforced by national aviation authorities in France, Germany, and Italy. This regulatory shift is accelerating investment in blockchain-enabled supply chain tracking systems among sealant distributors serving the European MRO channel.
Airframe OEMs are consolidating approved supplier lists and demanding direct electronic data interchange for inventory replenishment. Tier-1 aerostructures manufacturers at Boeing's Charleston and Airbus's Hamburg facilities are replacing phone-and-fax procurement with vendor-managed inventory systems. This behavioral shift is most visible in the United States, where supplier reduction programs are concentrating sealant purchasing power among distributors capable of integrating with OEM enterprise resource planning platforms.
Aerospace Sealants Market Segmentation
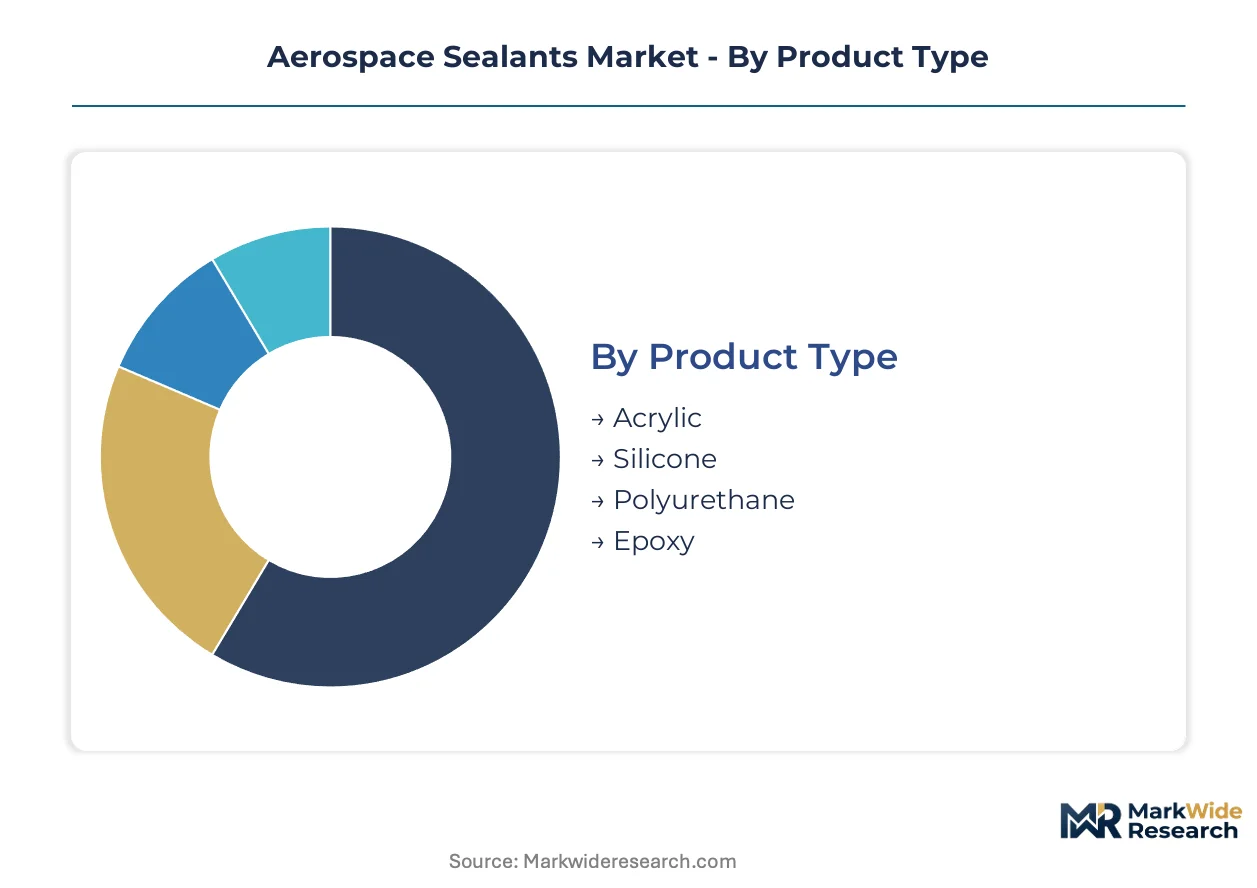
Aerospace sealant specifications propagate through four intersecting dimensions that determine qualification pathways, pricing tiers, and procurement protocols. Product chemistry dictates thermal and fluid resistance profiles. Application context shapes regulatory burden and volume scale. Technology selection governs cure cycles and automation compatibility. End-user channel determines contract structure and margin capture.
Product Type:
Silicone and polysulfide resin supply concentrates among petrochemical complexes in the United States and Germany, exposing formulators to input cost volatility and qualification heritage lock-in.
- Silicone:Formulated from polydimethylsiloxane backbones with filler reinforcement, silicone sealants maintain elasticity across minus sixty-five to plus four hundred degrees Fahrenheit. Boeing 737 and Airbus A320 fuel tank sealing specifications anchor demand at OEM facilities in Renton and Hamburg, though REACH chemical restrictions are compressing reformulation timelines for European-qualified grades.
- Polyurethane:Two-part aliphatic and aromatic polyurethane systems deliver weight reduction advantages on narrowbody platforms through lower specific gravity than polysulfide alternatives. Airbus A220 wing box assemblies and emerging eVTOL airframes in Germany and the United States are specifying these materials for automated dispensing compatibility.
- Acrylic:UV-curable acrylic formulations serve interior cabin sealing applications where rapid tack-free handling accelerates final assembly line throughput.
- Epoxy:High-modulus epoxy sealants provide structural bonding for composite laminate edges and metal-to-composite transitions in next-generation airframes.
Today's leader: Silicone. Tomorrow's challenger: Polyurethane.
Application:
Cost tier differentiation separates military programs with decade-long qualification cycles from commercial aviation's volume-driven procurement.
- Commercial:Narrowbody and widebody production at Boeing and Airbus facilities generates the highest sealant consumption per airframe, with fuel tank integrity and cabin pressure sealing commanding premium pricing for qualified materials.
- Military:Fighter and transport programs under the U.S. Department of Defense and India's Ministry of Defence demand chromate-free polysulfide reformulations under EPA and indigenous procurement mandates, extending qualification timelines while sustaining margin premiums.
- Aerospace:Space launch vehicle applications require outgassing-tested sealants for vacuum exposure, with suppliers in the United States serving SpaceX and United Launch Alliance programs.
- General Aviation:Cessna and Cirrus aircraft manufacturing in Wichita and Duluth operates on shorter procurement cycles with reduced specification stringency, enabling distributor-tier competition.
Commercial commands volume. Military commands margin. General aviation commands access.
Technology:
Volume concentration in curing technologies reflects the dominance of two-part polysulfide and silicone systems across OEM assembly lines.
- Curing:Room-temperature vulcanizing and heat-accelerated cure chemistries accommodate both field MRO deployment and factory-controlled autoclave processing, with cure-cycle duration directly impacting labor economics at Dallas-Fort Worth and Frankfurt maintenance hubs.
- Adhesive Bonding:Structural epoxy formulations for composite bonding are gaining share fastest as out-of-autoclave manufacturing processes at Boeing Charleston and Airbus Hamburg demand cure-compatible alternatives to traditional autoclave-tolerant sealants.
- Surface Treatment:Primer and adhesion promoter systems prepare aluminum, titanium, and composite substrates for sealant application, with chromate-free alternatives displacing legacy hexavalent chromium formulations under EPA regulations.
- Coating:Film-forming sealant coatings provide secondary corrosion protection for fastener heads and lap joints in harsh-service environments.
Curing dominates factory floors. Adhesive bonding climbs fastest in composite-intensive programs.
End User:
Customer type determines contract structure, with OEMs demanding direct electronic data interchange and MROs prioritizing distributor availability.
- OEMs:Boeing and Airbus engineering offices specify qualified sealants through approved supplier lists, consolidating purchasing power among distributors capable of vendor-managed inventory integration with enterprise resource planning platforms.
- MROs:Maintenance, repair, and overhaul operators at Atlanta, Singapore, and London Heathrow extend recurring revenue pools as fleet operating hours accumulate, though qualified technician scarcity constrains regional expansion.
- Tier-1 Suppliers:Spirit AeroSystems and GKN Aerospace facilities purchase to OEM-directed specifications with limited formulation discretion, functioning as pass-through demand channels.
- Aftermarket Providers:Independent distributors serve non-scheduled maintenance and aging fleet support, competing on availability rather than technical specification development.
OEMs dictate specifications. MROs dictate volume sustainability. Aftermarket dictates fill-rate performance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boeing's supplier base in the United States anchors OEM sealant procurement, while Airbus production at Hamburg and Toulouse drives European formulation demand. Regulatory divergence between FAA and EASA protocols shapes regional qualification requirements.
United States
Commercial aviation production at Boeing's Renton and Charleston facilities sustains polysulfide and silicone sealant demand for fuel tank integrity applications. EPA restrictions on hexavalent chromium content force reformulation timelines for legacy maintenance compounds. Dallas-Fort Worth and Atlanta MRO hubs concentrate qualified technician pools for C-check sealant applications.
Germany
Airbus Hamburg final assembly lines and Hamburg MRO infrastructure generate concentrated demand for REACH-compliant sealant grades. EASA Part 21 design standards enforce batch-to-airframe traceability documentation across European-registered aircraft. Frankfurt maintenance hubs adopt room-temperature vulcanizing formulations to compress cure-cycle downtime.
France
Toulouse Airbus manufacturing and Safran aerostructures operations specify qualified sealants for composite-intensive wing box assemblies. ANSM enforces chemical substance reporting under REACH Article 33 for imported sealant components. The Occitanie aerospace cluster sustains distributor networks serving both OEM and aftermarket channels.
India
Indigenous fighter and transport programs under the Ministry of Defence create qualification pathways for chromate-free polysulfide alternatives. BIS certification requirements and DGFT import substitution mandates shape local procurement protocols. Bangalore and Hyderabad defense aviation clusters demand established technical support infrastructure from sealant suppliers.
United Kingdom
GKN Aerospace and BAE Systems facilities purchase to OEM-directed specifications with limited formulation discretion. The Civil Aviation Authority enforces flammability resistance standards aligned with FAR 25.853 for UK-registered commercial fleets. Bristol and Lancashire aerostructures manufacturing sustain distributor-tier competition for general aviation applications.
Aerospace Sealants Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue rapid-cure formulations for automated eVTOL assembly lines. The supplier base concentrates among diversified chemical conglomerates with captive resin synthesis capabilities and specialized aerospace formulators with qualification heritage. Three archetypes dominate: petrochemical-integrated conglomerates controlling upstream polymer supply, European MRO-focused distributors with EASA qualification depth, and composite-bonding specialists serving out-of-autoclave manufacturing programs. Competitive moves center on backward integration into resin precursors and strategic partnerships with eVTOL manufacturers seeking rapid-cure dispensing compatibility.
Among diversified chemical conglomerates, PPG Industries and Dow occupy positions anchored by captive silicone and polysulfide resin production. Henkel exemplifies the European distributor archetype with qualified network coverage across EASA-regulated MRO channels. Huntsman Corporation represents the structural bonding specialist tier with epoxy formulations aligned to composite-intensive airframe programs.
| Leading Market Players |
|---|
| PPG Industries |
| Henkel |
| 3M |
| Solvay |
| Flamemaster |
| H.B. Fuller Company |
| Chemetall |
| Dow |
| Huntsman Corporation |
| Others |
Supply Flow & Price Mechanics
Polydimethylsiloxane feedstock indices from United States and German petrochemical complexes cascade through formulation tiers, compressing margins for non-integrated sealant producers while concentrating pricing power among resin-synthesis captives serving Boeing and Airbus procurement channels.
Pricing Analysis
Input-cost pass-through from silicone and polysulfide resin precursors anchors contract-based long-term offtake structures for OEM-direct supply, while spot-market exposure persists for MRO distributor tiers. Price differentiation separates chromate-free qualified grades from legacy formulations, with EPA-mandated reformulation timelines intensifying cost compression in the maintenance segment. OEM engineering offices exhibit lowest price sensitivity due to qualification heritage lock-in, whereas general aviation and aftermarket channels face acute margin pressure from distributor-tier competition.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Boeing Renton and Airbus Hamburg facilities, while qualified distributor networks serve fragmented MRO maintenance hubs. Raw material supply draws from concentrated petrochemical complexes in the United States, Germany, and Japan, with polysulfide resin precursors and silicone backbones constituting critical dependencies. Single-source vulnerability around chromate-free corrosion inhibitor supply creates structural risk under EPA and REACH regulatory restrictions. Distribution runs through tiered vendor-managed inventory systems integrating with OEM enterprise resource planning platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA hexavalent chromium restrictions and EASA Part 21 traceability mandates continuously reshape procurement specifications and reformulation investment requirements.
For Market Incumbents: Extend qualification heritage advantage by accelerating chromate-free polysulfide certification timelines ahead of regulatory deadlines. Backward integration into captive silicone resin synthesis defends margin position against feedstock volatility from United States and German petrochemical complexes. Channel control through vendor-managed inventory integration with Boeing and Airbus ERP platforms raises switching costs for competitive entry.
For New Entrants and Emerging Players: Capture white-space opportunity in rapid-cure polyurethane formulations for automated eVTOL assembly lines where qualification heritage barriers remain lowest. India's Ministry of Defence indigenous procurement mandates offer the most penetrable geography for chromate-free alternatives with established technical support infrastructure. Go-to-market positioning around out-of-autoclave composite compatibility differentiates against legacy autoclave-tolerant incumbents.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized epoxy formulators serving composite-intensive airframe programs where out-of-autoclave manufacturing adoption is accelerating. Long-term viability hinges on regulatory compliance automation capabilities and blockchain-enabled batch traceability infrastructure. Watch for eVTOL manufacturer qualification awards as inflection indicators for rapid-cure formulation demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Precursors | Captive silicone and polysulfide supply secures margin control against United States and German feedstock volatility. |
| Chromate-Free Formulation Certification | EPA-compliant polysulfide alternatives unlock military and commercial maintenance procurement under hexavalent chromium restrictions. |
| Blockchain Traceability Implementation | EASA Part 21 batch-to-airframe documentation requirements enforce digital supply chain investment across European MRO channels. |
| Rapid-Cure Technology Development | Automated dispensing compatibility addresses eVTOL manufacturer throughput requirements in United States and Germany assembly lines. |
| India Technical Infrastructure Establishment | DGFT import substitution mandates and BIS certification requirements demand localized support for defense aviation programs. |
Methodological Framework
Multiple input streams — primary interviews with sealant formulation chemists, OEM procurement directors, and MRO maintenance supervisors; secondary validation through FAA airworthiness directives, EASA certification databases, and EPA chemical substance filings; plus customs trade data from United States and German aerospace chemical exports — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product chemistry, application context, technology selection, and end-user channel dimensions produced volume and value outputs over the projection horizon. CAGRs were derived from airframe production rate trajectories at Boeing and Airbus facilities, fleet operating hour accumulation curves, and regulatory reformulation timeline assumptions. Industry-specific forecast inputs included OEM specification change velocity and MRO technician certification pipeline constraints.
REACH enforcement acceleration, EPA hexavalent chromium restriction expansion, and out-of-autoclave manufacturing adoption velocity are the dominant revision risks for aerospace sealant demand modeling. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerospace Fasteners Market
Aerospace and Aircraft Materials
3D Printing for Aerospace Market
Aerospace and Aircraft Materials
Global Aerospace Titanium Machining Market
Aerospace and Aircraft Materials
Aerogel Market
Aerospace and Aircraft Materials
Aerospace Lightweight Materials Market
Aerospace and Aircraft Materials
Commercial Aircraft Materials Market
Aerospace and Aircraft Materials
Aerospace Additive Manufacturing Market
Aerospace and Aircraft Materials
Aerospace and Defense Composites Market
Aerospace and Aircraft Materials
Aerographene Market
Aerospace and Aircraft Materials
Composites in United States Defense Market
Aerospace and Aircraft Materials
Global Aerospace Insulation Market
Aerospace and Aircraft Materials
Ablative Coatings Market
Aerospace and Aircraft Materials
Global Composite Materials Aluminum Alloys Aerospace Market
Aerospace and Aircraft Materials
Aramid Honeycomb Market
Aerospace and Aircraft Materials
Aerospace Composites Market
Aerospace and Aircraft Materials
Aerospace Materials Market