
 Electrical Insulation Tape Market | 2026-2036
Electrical Insulation Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical Insulation Tape Market Intelligence
A shift toward multi-source procurement from single-source supplier agreements is decoupling purchasing decisions from historical vendor relationships, forcing more competitive bidding. 3M Company leverages its global manufacturing footprint and R&D capabilities to serve diverse end-markets. Nitto Denko Corporation specializes in advanced polyimide and polyester tapes for the electronics industry. Tesa SE sustains a strong position through its extensive distribution network in European industrial markets.
Electrical insulation tape is a pressure-sensitive adhesive product designed to insulate wires and other electrically conductive components. These tapes feature a backing material, such as vinyl or polyimide, combined with an adhesive engineered for specific dielectric strength and temperature resistance. Its primary function is preventing electrical shorts, protecting against environmental factors, and ensuring operational safety. While vinyl-based tapes dominate the market by volume for general applications like wire splicing, high-performance polyimide tapes command premium pricing for use in aerospace assembly and consumer electronics.
Product formulation and market access are governed by stringent regulatory frameworks. The EU's RoHS directive restricts the use of hazardous materials, while UL standards in the United States certify safety and performance for electrical equipment. These regulations compel manufacturers to invest in compliant material science and rigorous testing protocols. Consequently, material selection decisions must continuously balance compliance costs with the evolving performance demands from industrial and electronics end-users.
Market Dynamics
The market's central dynamic is the shift from historical, relationship-based single-supplier agreements to multi-source competitive bidding. This change in procurement behavior, driven by cost-optimization initiatives in large industrial and electronics firms, is forcing manufacturers to compete more aggressively on price and technical specifications.
Growth Catalysts
- 5G Telecommunications Expansion:The global deployment of 5G infrastructure creates significant demand for specialized tapes used in base stations, antennas, and small cell networks to insulate sensitive electronic components from interference and environmental factors.
- Electric Vehicle Battery Systems:Rapid expansion in electric vehicle production necessitates high-performance insulation tapes for battery pack assembly, thermal management, and protecting high-voltage wiring, driving demand for polyimide and glass cloth tapes.
- Consumer Electronics Miniaturization:The continuous drive for smaller, more powerful devices requires specialized tapes with superior dielectric properties and thermal resistance for use in the compact internal assemblies of smartphones, tablets, and wearables.
Market Restraints
- Raw Material Price Volatility:Fluctuations in the cost of petrochemical-derived inputs, such as PVC resins, plasticizers, and acrylic adhesives, directly impact manufacturer margins and create pricing instability for end-users.
- Substitution by Alternative Solutions:In certain industrial and automotive applications, liquid conformal coatings and heat-shrink tubing present viable alternatives that can offer superior performance in high-vibration or chemically harsh environments.
- Stringent Regulatory Compliance:Adherence to material standards like the EU's RoHS directive and performance certifications like those from UL requires significant R&D investment and lengthy testing, slowing the introduction of new formulations.
Strategic Opportunities
- High-Voltage DC Applications:The expansion of data centers and electric vehicle charging infrastructure creates a market for tapes specifically engineered for high-voltage direct current (HVDC) busbar and power distribution insulation.
- Bio-Based and Recycled Materials:Developing tapes with backings and adhesives derived from renewable or recycled sources offers a path to meet corporate sustainability mandates and appeal to environmentally conscious industrial customers.
- Grid Modernization Programs:Government-led initiatives to upgrade aging electrical grids in countries like India and Brazil present a substantial opportunity for tapes used in transformer repair, cable splicing, and substation maintenance.
Industry Challenges
- Certification Bottlenecks:The lengthy and costly process of obtaining UL and IEC certifications for new product formulations creates a significant time-to-market delay, particularly for high-performance specialty tapes aimed at electronics or aerospace.
- Counterfeit Product Proliferation:The infiltration of low-cost, non-compliant counterfeit tapes into distribution channels, especially in developing markets, poses serious safety hazards and erodes pricing power for legitimate manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical Insulation Tape Market |
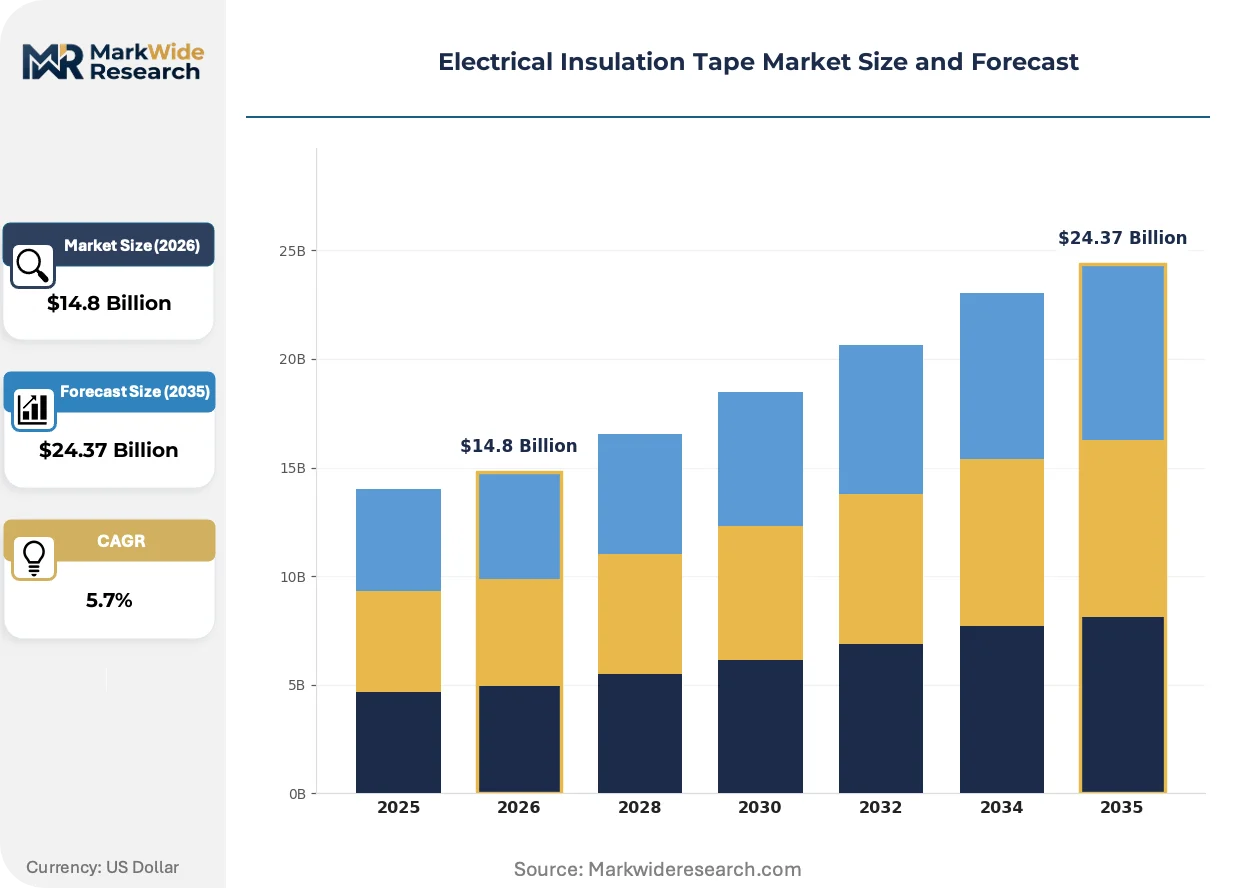
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl, Rubber, Polyester, Acrylic, Polyimide Adhesive Type: Rubber-Based, Acrylic-Based, Silicone-Based, Hot Melt, Emulsion Application: Cable Harnessing, Wire Splicing, Surface Protection, Marking, Sealing End User Industry: Telecommunications, Consumer Electronics, Electrical Equipment Manufacturing, Aerospace Assembly, Defense Systems |
| Companies Covered | Saint-Gobain, Intertape Polymer Group, 3M Company, Achem (YC Group), Scapa Group, Nitto Denko Corporation, Avery Dennison Corporation, Shurtape Technologies, Tesa SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical Insulation Tape Market Strategic Shifts & Innovations
Material science innovation is responding to the dual pressures of extreme performance requirements from the electronics sector and rising environmental regulations. This is pushing development toward multifunctional tapes that combine electrical insulation with other properties like thermal conductivity or EMI shielding.
Thermally conductive adhesive tapes are a key product evolution. These tapes incorporate ceramic or metallic fillers into the adhesive matrix to facilitate heat dissipation away from sensitive components. Electronics and electric vehicle battery manufacturers are rapidly adopting these materials, and the technology is integrating thermal management functions directly into the insulation layer, reducing component count and assembly complexity.
The EU's REACH regulation continues to scrutinize and restrict chemical substances used in adhesives and polymer backings. This regulatory pressure forces a continuous cycle of material reformulation and expensive requalification for products sold within the European Union. Manufacturers serving the medical device and aerospace sectors face the highest compliance burden, as they must validate new materials without compromising critical performance attributes.
A notable behavioral shift is occurring as large end-users consolidate their MRO (Maintenance, Repair, and Operations) purchasing. This trend favors large industrial distributors and e-commerce platforms that can offer a wide basket of products over specialized, direct-sales relationships for commodity vinyl tapes. This change in procurement is most visible within the North American and European industrial manufacturing sectors.
Electrical Insulation Tape Market Segmentation
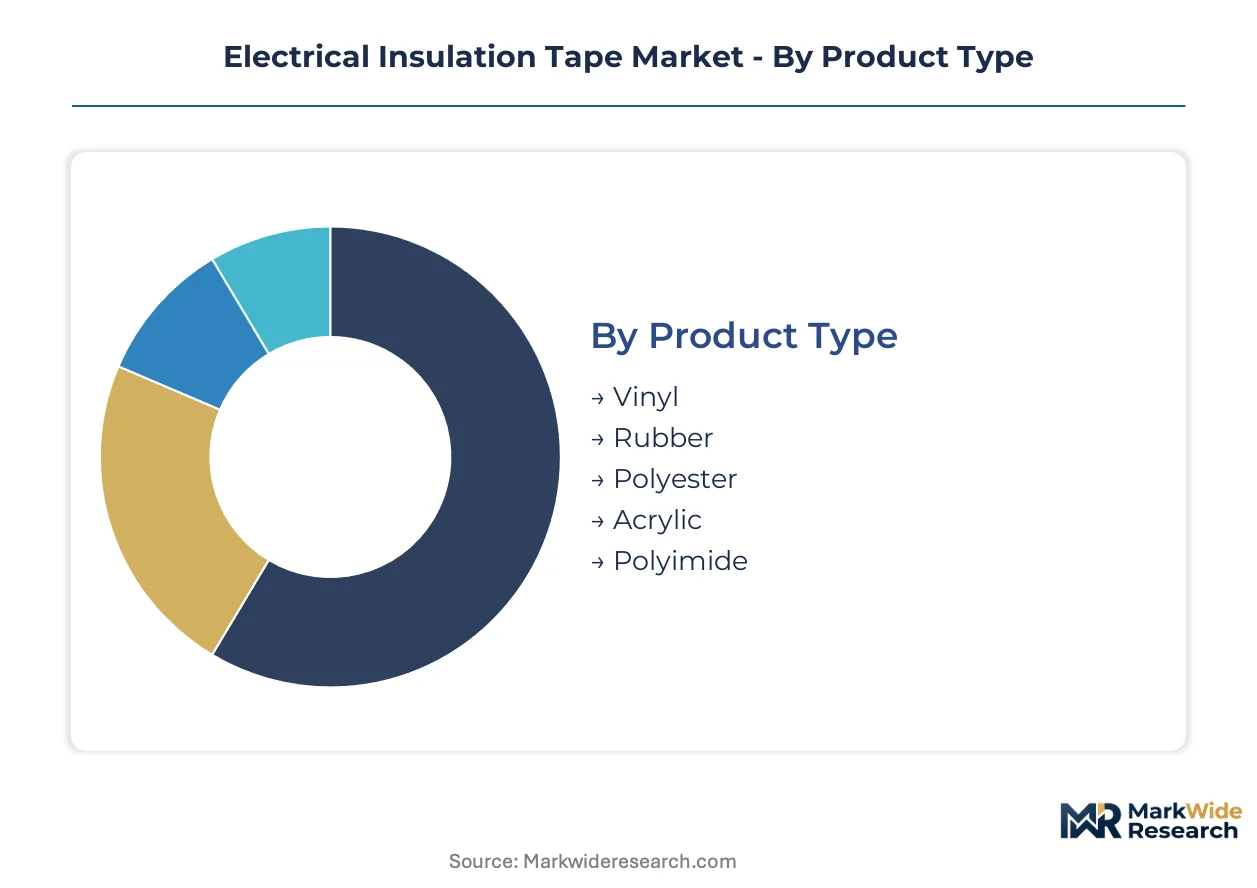
The electrical insulation tape market segmentation highlights the diverse material science and application demands across various industries. Understanding these segments clarifies specific performance requirements and regulatory compliance needs for different product formulations and end-use environments.
Product Type:
Certain product types within the electrical insulation tape market face distinct regulatory hurdles, impacting market entry and material selection.
- Vinyl:These tapes feature a flexible PVC backing combined with a rubber-based adhesive, offering good conformability and electrical insulation for general-purpose applications. High-volume demand for vinyl tapes concentrates in residential and commercial electrical wiring projects, driven by cost-effectiveness and ease of use in countries like India.
- Polyimide:Characterized by exceptional thermal stability and dielectric strength, polyimide tapes utilize a thin film backing with silicone adhesives, making them suitable for extreme temperature environments. Demand for polyimide tapes is concentrating in consumer electronics for miniaturized components and electric vehicle battery systems due to their high-performance requirements.
- Rubber:Rubber-based tapes provide excellent moisture resistance and insulation properties, often used for sealing and padding.
- Polyester:Polyester tapes offer good tensile strength and chemical resistance, finding applications in coil wrapping and transformer insulation.
- Acrylic:Acrylic tapes provide superior UV resistance and long-term adhesion, suitable for outdoor electrical installations.
Leading the category by volume: Vinyl. Growing fastest: Polyimide.
Adhesive Type:
Adhesive formulations define the tape's performance characteristics, directly influencing its suitability for specialized applications.
- Acrylic-Based:These adhesives offer strong adhesion, excellent temperature resistance, and good UV stability, often used with high-performance backings like polyimide or polyester. Electronics assembly and outdoor telecommunications infrastructure drive demand for acrylic-based adhesives due to their reliability and environmental resilience.
- Silicone-Based:Known for their high-temperature performance and chemical inertness, silicone adhesives maintain flexibility across a wide thermal range, making them ideal for demanding applications. Aerospace assembly and industrial furnace applications concentrate demand for silicone-based adhesives, requiring extreme heat resistance.
- Rubber-Based:Rubber adhesives provide quick stick and good conformability, commonly paired with vinyl backings for general electrical work.
- Hot Melt:Hot melt adhesives offer fast bonding and high initial tack, primarily used in packaging and non-critical insulation tasks.
- Emulsion:Emulsion adhesives are water-based, providing an environmentally friendly option for less demanding insulation applications.
Manufacturers prioritize adhesive types that deliver optimal thermal stability and adhesion for demanding industrial environments.
Application:
The functional application dictates specific performance requirements, driving demand for tailored electrical insulation tape solutions across diverse industries.
- Cable Harnessing:This involves bundling and securing multiple cables together, protecting them from abrasion and environmental factors while maintaining organized routing. The automotive industry and data center construction require significant volumes of tapes for cable harnessing to ensure system reliability and safety.
- Wire Splicing:Wire splicing applications involve joining two or more electrical conductors and insulating the connection to prevent short circuits and moisture ingress. Electrical utilities and residential construction projects consistently drive demand for reliable wire splicing tapes, particularly in regions with aging infrastructure.
- Surface Protection:Tapes used for surface protection shield sensitive components from physical damage, chemicals, or contaminants during manufacturing or operation.
- Marking:Marking tapes identify wires, cables, and components for easier installation, maintenance, and troubleshooting in complex electrical systems.
- Sealing:Sealing applications prevent moisture, dust, and other environmental elements from entering electrical enclosures or connections.
Core applications like cable harnessing and wire splicing continue to shape product development toward enhanced durability and ease of use.
End User Industry:
Specific end-user industries drive demand for electrical insulation tapes based on their unique operational environments and performance needs.
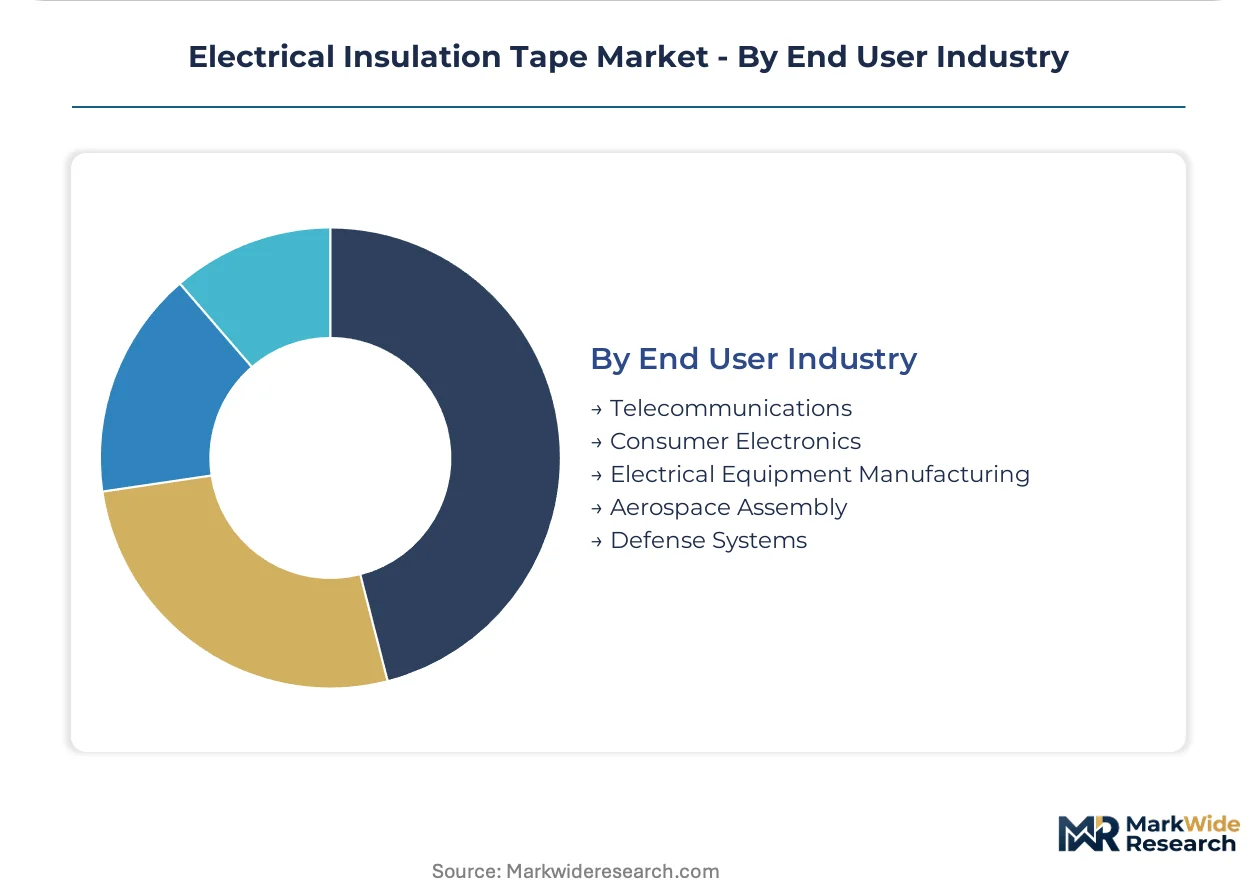
- Telecommunications:This sector utilizes specialized tapes for insulating sensitive components in 5G infrastructure, base stations, and fiber optic networks, protecting against interference and environmental exposure. Global 5G deployment, particularly in countries like China and the United States, creates significant demand for high-performance telecommunications tapes.
- Consumer Electronics:Miniaturization in smartphones, tablets, and wearables necessitates ultra-thin tapes with superior dielectric properties and thermal resistance for compact internal assemblies. The relentless product innovation cycle in consumer electronics, led by companies in South Korea and Japan, fuels demand for advanced insulation solutions.
- Electrical Equipment Manufacturing:This industry uses tapes for insulating motors, transformers, and switchgear, ensuring operational safety and longevity.
- Aerospace Assembly:High-reliability applications in aircraft and spacecraft require tapes with extreme temperature resistance and flame retardant properties.
- Defense Systems:Military applications demand rugged, durable tapes that can withstand harsh environmental conditions and provide secure electrical insulation.
The telecommunications and consumer electronics sectors demonstrate significant potential for future demand expansion due to ongoing technological advancements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for electrical insulation tape concentrates significantly in regions undergoing rapid infrastructure development and technological advancement. Countries with robust manufacturing bases and expanding telecommunications networks drive substantial material consumption. This global distribution reflects distinct end-use requirements.
China
China's substantial investment in 5G infrastructure and electric vehicle battery production fuels robust demand for specialized insulation tapes. GB standards ensure product compliance and safety across diverse electrical applications. Manufacturing hubs in the Yangtze River Delta actively integrate high-performance tapes into advanced electronics assembly.
United States
The United States sees significant demand from expanding data centers and the growing electric vehicle charging infrastructure. UL standards rigorously certify safety and performance for all electrical equipment. Technology clusters in California actively utilize advanced insulation tapes for high-voltage direct current (HVDC) power distribution systems.
Germany
Germany's advanced automotive manufacturing, especially for electric vehicle components, and its strong industrial automation sector generate substantial tape demand. The EU's RoHS directive restricts hazardous materials, compelling compliant formulation development. Industrial regions like Bavaria integrate specialized tapes into sophisticated machinery and high-performance automotive electronics.
India
India's government-led grid modernization programs and expanding residential construction drive demand for both high-performance and general-purpose tapes. BIS standards guide material quality and safety for electrical products across the country. Major infrastructure projects in Maharashtra utilize cost-effective vinyl tapes for general wiring and cable splicing.
South Korea
South Korea's leadership in consumer electronics miniaturization and advanced battery manufacturing creates specific demand for high-performance tapes. KC certification ensures product safety and electromagnetic compatibility for electronic devices. Technology parks in Gyeonggi Province integrate ultra-thin insulation tapes into compact smartphone and wearable assemblies.
Electrical Insulation Tape Market Key Industry Players
Competitive bidding dominates the current landscape, forcing manufacturers to compete aggressively on price and technical specifications. The market exhibits a tiered structure, with a few global players holding significant market share alongside numerous regional specialists. Strategic archetypes include diversified material science conglomerates, specialized electronics tape providers, and cost-focused general-purpose tape producers. Dominant competitive moves involve portfolio diversification into high-growth end-markets and geographic expansion to capture new demand.
Diversified material science conglomerates, such as 3M Company, leverage extensive global manufacturing footprints and R&D capabilities to serve diverse end-markets. Specialists in advanced electronics tapes, like Nitto Denko Corporation, exemplify expertise in polyimide and polyester formulations for high-performance applications. Tesa SE, with its strong distribution network, represents a key player sustaining a robust position within European industrial markets. These companies anchor different segments of the market, offering solutions that range from general-purpose vinyl to highly specialized, high-dielectric materials, effectively addressing varied performance and cost requirements across industries.
| Leading Market Players |
|---|
| Saint-Gobain |
| Intertape Polymer Group |
| 3M Company |
| Achem (YC Group) |
| Scapa Group |
| Nitto Denko Corporation |
| Avery Dennison Corporation |
| Shurtape Technologies |
| Tesa SE |
| Others |
Cost & Logistics Intelligence
Vertical integration into key raw material production anchors a strong supply position for major electrical insulation tape manufacturers, influencing their pricing power against smaller, less integrated competitors. These strategic choices often dictate long-term cost structures and market responsiveness.
Pricing Analysis
Warranty and service bundling often differentiate premium electrical insulation tape offerings, where post-sale support adds perceived value beyond the product itself. The dominant pricing model for high-performance polyimide tapes is contract-based long-term offtake, while general-purpose vinyl tapes use per-unit transactional pricing. Price differentiation stems from certification levels, such as UL standards, and customization capabilities for specialized applications. Pricing softness reflects intense competitive bidding, especially for commodity vinyl tapes. Residential construction projects represent the most price-sensitive segment, contrasted with aerospace assembly buyers who prioritize performance over cost.
Supply Chain Analysis
Polyimide film supply for high-performance electrical insulation tapes rests on specialized chemical producers primarily in Japan and South Korea. Raw material dependencies include petrochemical-derived PVC resins, various plasticizers, and acrylic adhesives. Supply chain risk arises from raw material price volatility, impacting manufacturer margins directly. Distribution runs through large industrial distributors and e-commerce platforms for MRO purchasing, while direct sales channels serve specialized aerospace and electronics OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electrical insulation tape market is undergoing a technology-transition phase, with advanced multifunctional tapes integrating thermal management and EMI shielding replacing traditional single-function insulation solutions. This shift necessitates strategic adjustments across the value chain.
For Market Incumbents:Lock in long-term supply agreements for critical raw materials like polyimide films to mitigate price volatility and secure input stability. Incumbents should also invest in R&D for bio-based and recycled material formulations to address evolving environmental regulations like REACH. Expanding certification investment, particularly for UL and IEC standards, strengthens market access.
For New Entrants and Emerging Players:Enter via specialized niches such as high-voltage DC applications for data centers or EV charging infrastructure, requiring specific tape formulations. The most penetrable segment involves developing bio-based or recycled material tapes to meet corporate sustainability mandates. A strong go-to-market angle involves collaborating with emerging EV battery manufacturers.
For Investors and Strategic Acquirers:Exit pathways concentrate in specialized material science firms offering advanced polyimide or thermally conductive tape technologies, demonstrating long-term viability over five to ten years. Acquisition targets should focus on companies with strong R&D capabilities in multifunctional tapes or established certification portfolios. A signal to watch is increasing strategic partnerships between tape manufacturers and major automotive or electronics OEMs.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Vietnam | Reduces manufacturing costs for general-purpose tapes, serving growing regional demand. |
| R&D in Thermally Conductive Tapes | Addresses critical heat dissipation needs in consumer electronics and EV battery systems. |
| Certification for HVDC Applications | Unlocks market access for high-voltage direct current infrastructure and data centers. |
| Bio-Based Material Development | Meets stringent EU RoHS compliance and corporate sustainability objectives for industrial customers. |
| E-commerce Channel Development | Captures a wider MRO purchasing base, particularly in North American industrial markets. |
Research Approach
Document review covered academic journals, industry reports, and regulatory filings, complemented by interviews with industry stakeholders. Primary research involved conversations with R&D directors, procurement leads at electronics OEMs, and industrial distributors. Secondary data sources included customs data, annual reports of public companies, and government statistics on infrastructure projects. This approach ensured robust bottom-up and top-down triangulation of market estimates.
Historical market data was cross-referenced with expert panel input to construct the analytical framework across the analysis window. Segmentation dimensions modeled included product type, adhesive type, application, end-user industry, and regional infrastructure development. Compound annual growth rates were derived from a comprehensive analysis of demand drivers and market restraints. Key forecast inputs included 5G deployment rates and electric vehicle production volumes.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of extreme raw material price volatility or unforeseen regulatory shifts. Forecasts reflect assumptions regarding technological adoption and global economic stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Europe Electronics Adhesives Market
Adhesives & Sealants
Global Non-Woven Adhesives Market
Adhesives & Sealants
Heat Resistant Sealant Market
Adhesives & Sealants
Flexible Packaging Adhesive Market
Adhesives & Sealants
Cold Seal Adhesives Market
Adhesives & Sealants
Asia-Pacific Acrylic Adhesives Market
Adhesives & Sealants
South Africa Adhesives Market
Adhesives & Sealants
Electric Vehicle Adhesives Market
Adhesives & Sealants
Middle-East and Africa Polyurethane (PU) Adhesives Market
Adhesives & Sealants
EV Adhesives Market
Adhesives & Sealants
Global Underfill Material Market
Adhesives & Sealants
Pvc Based Adhesive Market
Adhesives & Sealants
Australia Adhesives Market
Adhesives & Sealants
Acrylic Glue Market
Adhesives & Sealants
Lignin for Adhesives Market
Adhesives & Sealants
Animal Glue Market