
 Acrylic Glue Market | 2026-2036
Acrylic Glue Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylic Glue Market Analytics
Modular adhesive kits bundling primers with applicators is hardening buyer expectations for turnkey solutions. Henkel leverages its European manufacturing footprint to sustain supply consistency for automotive OEMs. Dow anchors its position through in-house production of acrylic monomers, while Sika competes with specialized construction-grade formulations.
Acrylic glue comprises synthetic resin adhesives formulated from acrylic or methacrylic polymers, typically curing through solvent evaporation, moisture activation, or UV-initiated polymerization at temperatures between 20°C and 80°C. Water-based formulations lead volume sales due to regulatory pressure on solvent emissions, while UV-curable adhesives represent the fastest-expanding product category in electronics assembly where rapid cure cycles reduce work-in-process inventory. Construction applications command the largest revenue pool among end-use segments, though automotive bonding is displacing welding in electric vehicle battery pack assembly.
EPA regulations in the United States limit hazardous air pollutant content in industrial adhesives, while REACH and the EU Green Deal in Europe mandate progressive reduction of volatile organic compound emissions across chemical formulations. Japan's METI enforces JIS standards for structural adhesive performance in building applications. Stakeholders must monitor evolving chemical restriction schedules and align formulation portfolios with jurisdiction-specific compliance deadlines.
Market Dynamics
Automotive electrification is forcing adhesive formulators to engineer thermally conductive acrylic systems that bond battery modules while dissipating heat, replacing mechanical fastening in electric vehicle architectures.
Growth Catalysts
- REACH VOC Phase-Down:Europe's progressive volatile organic compound limits under the EU Green Deal are redirecting industrial procurement toward water-based acrylic formulations certified for construction and transportation assembly.
- Electric Vehicle Battery Bonding:Automotive OEMs are specifying structural acrylic adhesives for lithium-ion cell-to-pack attachment, eliminating weld points and enabling thermal management integration.
- UV-Cure Electronics Assembly:Printed circuit board manufacturers are adopting photoinitiated acrylic systems that polymerize in seconds under LED arrays, compressing work-in-process inventory in smartphone and wearable production lines.
Market Restraints
- Acrylic Monomer Price Volatility:Crude oil derivative costs for methyl methacrylate feedstock create margin pressure that water-based formulators cannot fully pass to price-sensitive construction contractors.
- East Asian Supply Concentration:Specialty photoinitiator production clusters in China expose UV-curable adhesive manufacturers to export licensing disruptions and shipping bottlenecks.
- Epoxy Substitution in Heavy Structural Loads:Wind turbine blade manufacturers prefer epoxy systems for root-to-blade bonding where peel strength requirements exceed acrylic performance envelopes.
Strategic Opportunities
- India Construction Formalization:India's BIS certification mandates for structural building materials are creating compliant-product premiums in residential high-rise and infrastructure segments previously served by unformulated adhesives.
- Medical Device Wearables:Skin-contact acrylic pressure-sensitive adhesives are penetrating continuous glucose monitor and transdermal patch applications where biocompatibility ISO 10993 testing creates qualification barriers for commodity suppliers.
- Japan METI Carbon-Neutral Building Standards:Japanese construction codes rewarding low-embodied-carbon materials are accelerating specification of bio-based acrylic monomers in commercial retrofit projects.
Industry Challenges
- Formulation Chemist Talent Scarcity:Polymer synthesis expertise combining UV-cure kinetics with rheology control commands premium compensation that mid-tier adhesive blenders struggle to match.
- Multi-Jurisdiction Registration Burden:Separate EPA TSCA notifications, REACH dossier updates, and Japan CSCL compliance create 18-to-24-month lag between lab-scale validation and commercial launch for new acrylic chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrylic Glue Market |
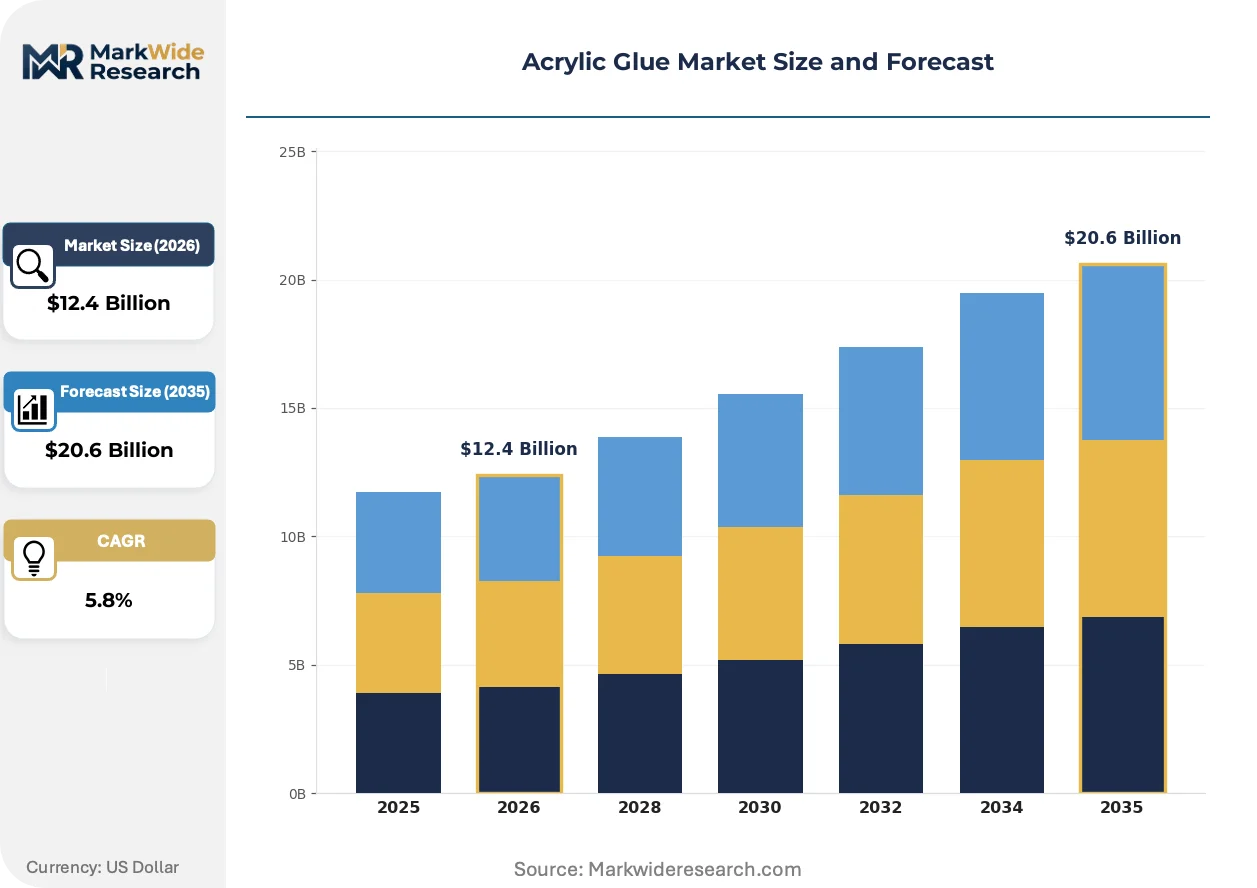
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent-Based, Water-Based, Reactive, UV-Curable Application: Construction, Automotive, Electronics, Crafts End User: Manufacturers, DIY Enthusiasts, Contractors, Hobbyists Formulation Type: Single Component, Multi Component, Adhesive Films, Paste |
| Companies Covered | 3M, Henkel, BASF, H.B. Fuller, Sika, Avery Dennison, Dow, Arkema, ITW, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylic Glue Market Evolving Landscape
Formulation science is converging with automation engineering as adhesive producers engineer systems specifically for robotic dispensing and in-line quality verification.
Dual-cure acrylic systems combining moisture-triggered and UV-initiated polymerization are expanding into automotive camera module assembly. Tier-one electronics suppliers in South Korea and Germany are specifying these hybrids to achieve handling strength at ambient conditions followed by full cure under conveyor-mounted LED arrays. The technology is compressing capital equipment requirements by eliminating thermal oven infrastructure from compact sensor production lines.
EPA hazardous air pollutant standards under the National Emission Standards for Hazardous Air Pollutants are tightening solvent content thresholds for industrial adhesive operations. Formulators serving US aerospace and furniture manufacturing are reformulating toward exempt compounds and waterborne acrylic emulsions to avoid Title V permitting complexity. The regulation is accelerating capital redeployment from solvent recovery systems toward ambient-cure dispensing equipment in Midwest manufacturing corridors.
Modular adhesive kits bundling surface primers, precision applicators, and cure-validation indicators are displacing bulk-container procurement in maintenance-repair-operations channels. Industrial distributors in Germany and Japan are consolidating supplier relationships around turnkey system providers that reduce customer technical support burden. The shift is most visible in automotive aftermarket collision repair, where shop technicians prioritize workflow integration over per-liter material cost minimization.
Acrylic Glue Market Segmentation
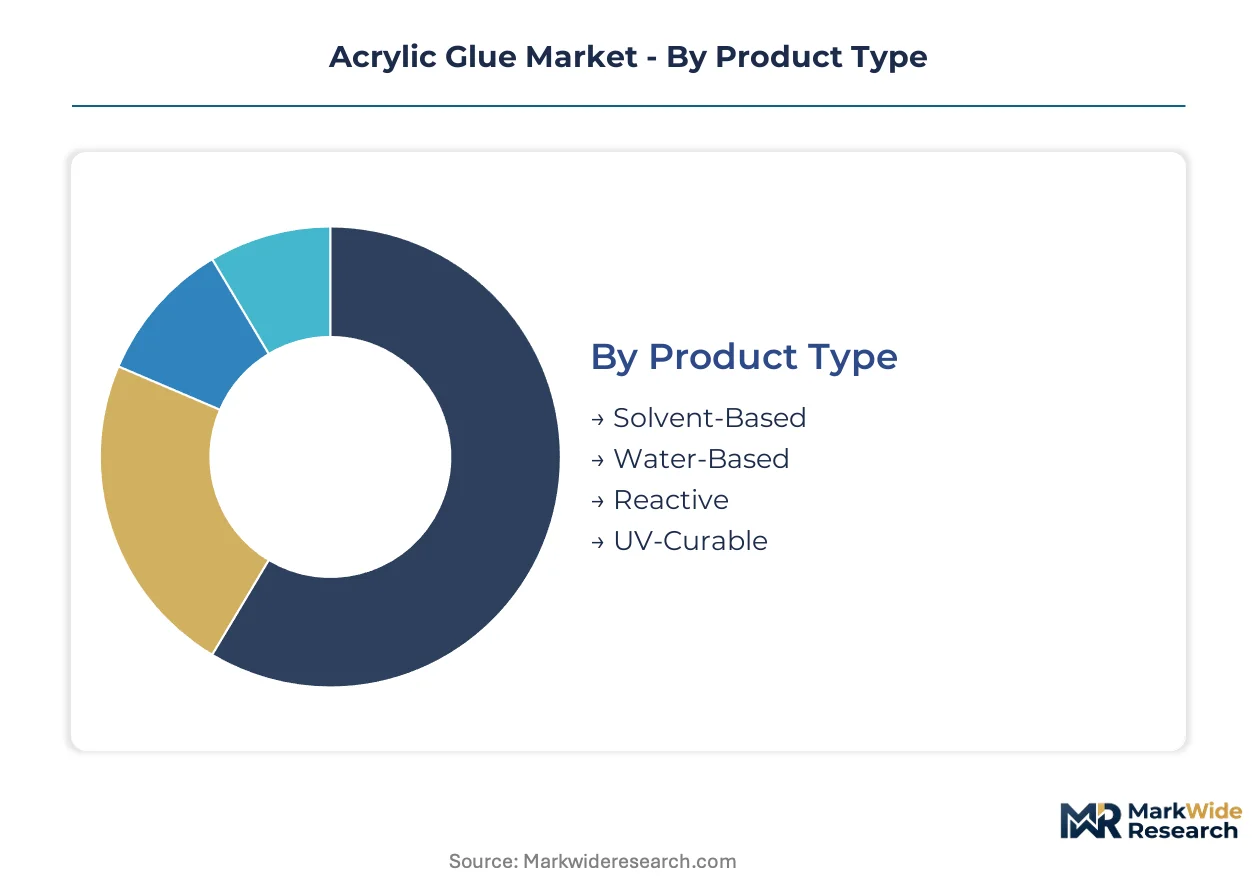
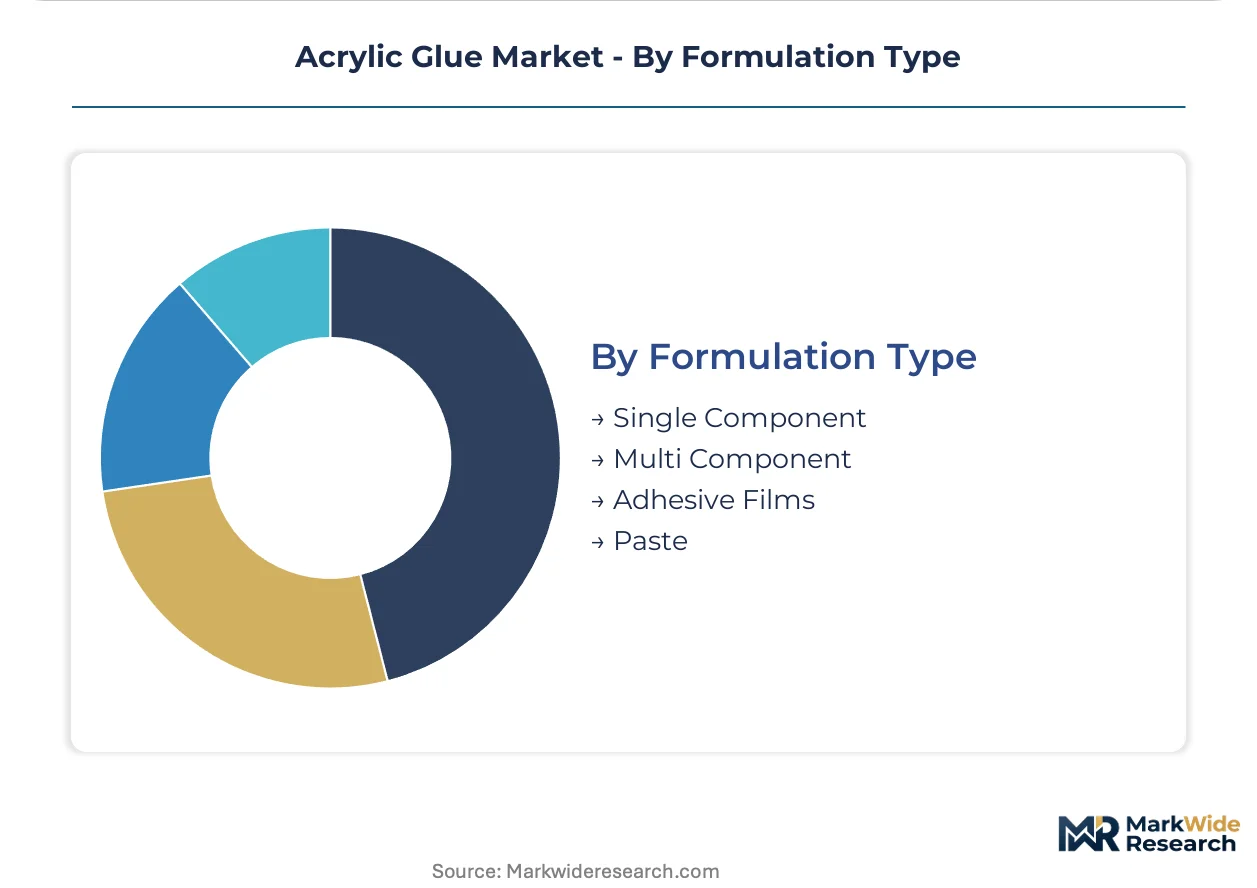
Acrylic glue segmentation reflects divergent buyer priorities across industrial procurement, regulatory compliance, and application-specific performance requirements. Formulators must align product architectures with distinct cure mechanisms, substrate compatibility demands, and end-user technical capabilities.
Product Type:
Buyers differentiate primarily by emission compliance obligations and cure speed requirements rather than bond strength alone.
- Water-Based:Acrylic emulsions disperse polymer particles in aqueous carriers, eliminating volatile organic compound emissions that trigger EPA Title V permitting in US manufacturing corridors. Construction contractors in Germany and Japan specify these formulations to satisfy REACH phase-down schedules and METI carbon-neutral building standards.
- UV-Curable:Photoinitiated systems polymerize within seconds under LED arrays, enabling work-in-process inventory compression for South Korean smartphone manufacturers and German automotive sensor suppliers. The chemistry demands precise substrate transparency and capital investment in conveyor-mounted cure equipment.
- Solvent-Based:Methyl methacrylate solutions in organic carriers deliver rapid tack and gap-filling for furniture assembly and signage fabrication where emission controls remain less stringent.
- Reactive:Two-part acrylic systems cure through chemical reaction without external energy input, serving heavy-duty transportation assembly where thermal or UV exposure is impractical.
Water-based formulations lead volumes today; UV-curable systems are gaining share fastest in electronics assembly corridors.
Application:
Segment economics hinge on specification authority concentration and contract value scales rather than unit volume.
- Construction:Structural bonding of concrete, metal, and composite panels in commercial high-rise and infrastructure projects commands the largest revenue pool. India's BIS certification mandates for structural building materials are redirecting procurement toward compliant acrylic systems in residential tower segments previously served by unformulated adhesives.
- Automotive:Electric vehicle battery pack assembly specifies thermally conductive acrylic adhesives for cell-to-pack attachment, displacing mechanical welding and enabling integrated thermal management. OEM qualification cycles spanning 24-36 months create substantial barriers for new adhesive entrants.
- Electronics:Printed circuit board and wearable device manufacturers prioritize rapid cure cycles and precision dispensing compatibility.
- Crafts:Hobbyist and artisan applications emphasize convenience packaging and retail distribution density over technical performance specifications.
Construction maintains revenue leadership; automotive electrification is climbing the fastest as weld-replacement specifications multiply across battery architectures.
End User:
Procurement sophistication separates industrial volume buyers from price-sensitive fragmented demand.
- Manufacturers:Tier-one automotive and electronics suppliers mandate lot traceability, statistical process control documentation, and multi-jurisdiction regulatory dossiers that only established formulators can sustain.
- Contractors:Professional construction crews in Germany and Japan are consolidating supplier relationships around modular adhesive kits bundling primers, applicators, and cure-validation indicators to reduce field technical support burden.
- DIY Enthusiasts:Home improvement retailers capture this segment through branded convenience packaging and instructional content rather than technical specification depth.
- Hobbyists:Craft supply channels serve this fragmented demand through small-format retail and online marketplaces with minimal formulation differentiation.
Manufacturers dominate contract values; contractor procurement consolidation is expanding fastest as turnkey system preferences harden.
Formulation Type:
Capital equipment requirements and labor skill levels determine buyer preference across format categories.
- Single Component:Pre-mixed formulations eliminate meter-mix-dispense equipment requirements and operator training burdens, suiting maintenance-repair-operations channels and field construction applications where equipment portability matters.
- Multi Component:Two-part systems deliver superior structural performance for wind turbine blade root bonding and heavy transportation assembly where peel strength requirements exceed single-component capabilities.
- Adhesive Films:Pre-cast acrylic tapes enable precise thickness control and clean handling for electronics lamination and medical device wearable applications where biocompatibility ISO 10993 testing creates qualification barriers for liquid alternatives.
- Paste:High-viscosity formulations provide gap-filling and vertical hang capabilities for overhead construction bonding and rough substrate applications.
Single-component formats lead unit volumes; adhesive films are expanding most quickly in medical device and precision electronics specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acrylic adhesive chemistry originated in German industrial laboratories during the mid-20th century, with BASF and Henkel scaling emulsion polymerization for post-war reconstruction. European regulatory leadership subsequently shaped formulation standards that now govern procurement across automotive and construction corridors worldwide.
Germany
Automotive OEMs in Stuttgart and Munich specify thermally conductive acrylic systems for electric vehicle battery bonding, displacing mechanical fastening in cell-to-pack architectures. REACH phase-down schedules under the EU Green Deal mandate progressive volatile organic compound reduction, redirecting procurement toward water-based emulsions certified for structural applications. The Rhine-Ruhr industrial corridor hosts concentrated adhesive blending capacity serving pan-European distribution networks.
United States
EPA National Emission Standards for Hazardous Air Pollutants tighten solvent content thresholds for industrial adhesive operations, particularly affecting aerospace and furniture manufacturing clusters. Midwest manufacturing corridors from Ohio to Michigan are redeploying capital from solvent recovery systems toward ambient-cure dispensing equipment. Dow maintains captive acrylic monomer production within Texas chemical complexes to insulate formulation margins from methyl methacrylate feedstock volatility.
Japan
METI carbon-neutral building standards reward low-embodied-carbon materials, accelerating specification of bio-based acrylic monomers in Tokyo and Osaka commercial retrofit projects. JIS structural adhesive performance standards govern building applications, creating qualification barriers for unformulated imports. Chubu region electronics manufacturers specify UV-curable acrylic systems for smartphone and wearable sensor assembly, compressing work-in-process inventory through LED-initiated polymerization.
China
Specialty photoinitiator production concentrates in coastal chemical clusters, exposing UV-curable adhesive manufacturers to export licensing disruptions and shipping bottlenecks. MIIT industrial standards for structural bonding are formalizing procurement in high-speed rail and renewable energy infrastructure. Yangtze River Delta electronics assemblers drive demand for rapid-cure acrylic systems in printed circuit board lamination.
India
BIS certification mandates for structural building materials redirect procurement toward compliant acrylic systems in Mumbai and Delhi residential high-rise segments previously served by unformulated adhesives. Construction formalization is creating compliant-product premiums in infrastructure projects. Gujarat and Maharashtra industrial corridors are expanding adhesive blending capacity to serve domestic automotive and wind energy OEMs.
Acrylic Glue Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory compliance depth and automotive qualification cycles. The vendor base organizes into three tiers: multinational chemical conglomerates with captive monomer supply, specialized adhesive formulators with sector-specific certifications, and regional blenders serving price-sensitive construction contractors. Consolidation pressure intensifies as OEM qualification requirements extend development timelines and concentrate procurement authority among established dossier holders. Dominant competitive moves include backward integration into acrylic monomer production and strategic partnerships with automated dispensing equipment manufacturers.
Among diversified chemical conglomerates, 3M and Henkel occupy positions spanning industrial, automotive, and consumer adhesive portfolios. Dow anchors its competitive stance through in-house production of acrylic monomers, insulating formulation operations from feedstock price volatility. Sika exemplifies the specialized construction-grade formulator archetype, with structural certification depth in European building codes. These three represent contrasting strategic postures: materials science breadth, upstream supply control, and sector-specific technical depth.
| Leading Market Players |
|---|
| 3M |
| Henkel |
| BASF |
| H.B. Fuller |
| Sika |
| Avery Dennison |
| Dow |
| Arkema |
| ITW |
| Others |
Value Network & Pricing Analysis
Tier-one automotive OEMs and construction contractors in Germany and Japan concentrate procurement authority, enabling three-tier pricing structure across premium, standard, and economy levels based on certification depth and formulation complexity. This buyer concentration feeds upstream into methyl methacrylate feedstock sourcing decisions and regional blending capacity allocation.
Pricing Analysis
Premium-mid-economy pricing differentiation separates REACH-certified structural formulations from commodity construction grades and unformulated regional alternatives. Automotive qualification cycles spanning 24-36 months create certification premiums that insulate top-tier suppliers from spot-market volatility. Cost compression in economy-tier construction adhesives is intensifying because Indian and Chinese regional blenders compete on per-liter pricing for BIS-compliant projects. DIY enthusiasts and small contractors exhibit highest price sensitivity; automotive OEMs and medical device manufacturers show lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Automotive and electronics OEM qualification protocols act as gating mechanisms that filter supplier access to premium contract tiers. Acrylic monomer production concentrates in Germany, the United States, and China, with specialty photoinitiator manufacturing anchored in Chinese coastal chemical clusters. Formulation operations draw from methyl methacrylate feedstock, UV-initiator chemicals, and bio-based monomer alternatives. Single-source vulnerability in Chinese photoinitiator supply exposes UV-curable adhesive manufacturers to export licensing disruptions. Distribution runs through industrial distributors in Germany and Japan consolidating around modular turnkey system providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acrylic glue market represents a late-cycle quality story as electric vehicle battery bonding and medical device wearable specifications displace commodity construction demand toward premium, certified formulations.
For Market Incumbents: Deepen backward integration into acrylic monomer production to insulate margins from methyl methacrylate feedstock volatility. Expand capacity in Gujarat and Maharashtra industrial corridors to capture Indian BIS-certified construction formalization. Invest in dual-cure formulation R&D to defend against epoxy substitution in heavy structural loads. For New Entrants and Emerging Players: Capture medical device wearable applications where ISO 10993 biocompatibility testing creates qualification barriers for commodity suppliers. Target Indian residential high-rise construction previously served by unformulated adhesives now requiring BIS certification. Pursue partnership-based go-to-market models with automated dispensing equipment manufacturers to reduce customer technical support burden. For Investors and Strategic Acquirers: Specialized adhesive formulators with sector-specific certifications are the most active acquirer targets in this space as OEM qualification requirements extend development timelines. The market offers 5-10 year viability for dossier-holding specialists with automotive and medical device penetration. Monitor electric vehicle platform standardization announcements as inflection indicators for thermally conductive adhesive specification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Dow's captive acrylic monomer production insulates formulation margins from feedstock volatility. |
| Green Manufacturing Transition | Japanese METI carbon-neutral building standards accelerate bio-based monomer adoption in commercial retrofits. |
| Long-term Supply Agreement | Henkel leverages European manufacturing footprint to sustain supply consistency for automotive OEMs. |
| Joint Venture | Specialized formulators partner with automated dispensing equipment manufacturers to bundle turnkey systems. |
| Capacity Expansion | Gujarat and Maharashtra industrial corridors add blending capacity to serve domestic automotive and wind energy OEMs. |
Research Methodology
Bottom-up automotive and electronics modeling reconciled against top-down acrylic monomer and formulation tracking forms the analytical core of this study. Primary interviews with adhesive formulator R&D directors, automotive OEM procurement leads, construction contractor operations managers, and industrial distribution channel partners combine with secondary validation from customs/trade data, SEC 10-K filings, and chemical industry association reports. Top-down supply-side assessment of methyl methacrylate production capacity and photoinitiator manufacturing concentration triangulates against bottom-up demand segmentation.
Input-output matrices map cure mechanism adoption rates, substrate compatibility requirements, and end-user technical capabilities across the projection horizon. Segmentation dimensions modeled include formulation chemistry, application vertical, end-user procurement sophistication, and regional regulatory cluster. CAGRs derive from regression analysis of historical adoption curves and elasticity-adjusted demand projections. Industry-specific forecast inputs incorporate REACH phase-down schedules and electric vehicle production ramp assumptions.
Crude oil derivative cost shocks, export licensing disruptions in Chinese photoinitiator supply, and accelerated epoxy substitution in wind energy applications are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in automotive OEM battery architecture specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Electrical Insulation Tape Market
Adhesives & Sealants
Epoxy Putty and Construction Chemicals Market
Adhesives & Sealants
Europe, Middle-East and Africa Hot-Melt Adhesives Market
Adhesives & Sealants
Ethylene Butyl Acrylate Market
Adhesives & Sealants
Elastic Bonding Adhesive and Sealant Market
Adhesives & Sealants
Automotive Adhesives and Sealants Market
Adhesives & Sealants
South Africa Sealants Market
Adhesives & Sealants
MS Polymer Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Adhesives and Sealants for Handheld Devices Market
Adhesives & Sealants
Die Attach Materials Market
Adhesives & Sealants
Global Tissue Sealants Market
Adhesives & Sealants
Cycloaliphatic Epoxy Market
Adhesives & Sealants
High Strength Laminated Adhesives Market
Adhesives & Sealants
EMEA Epoxy Adhesives Market
Adhesives & Sealants
Structural Adhesives Market
Adhesives & Sealants
Global Contact Adhesives Market