
 Heat Resistant Sealant Market | 2026-2036
Heat Resistant Sealant Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Resistant Sealant Market Analytics
Aerospace procurement teams are redrawing supplier priorities as commercial aviation output recovers and defense thermal protection budgets expand. Dow leverages captive silicone polymer production to control raw material quality for jet engine gaskets and exhaust seals. Henkel AG & Co. KGaA sustains dual-track R&D across automotive underhood and industrial furnace segments, balancing volume scale with specialty margins.
Heat resistant sealants are formulated elastomeric compounds—typically silicone, polyurethane, or acrylic bases cured with peroxide or condensation catalysts—that maintain adhesion and flexibility above 150°C, serving to prevent fluid ingress, thermal cycling failure, and combustion gas leakage in critical assemblies. Silicone sealants dominate high-temperature applications above 200°C due to backbone stability, while polyurethane formulations occupy the construction and automotive middle tier where cost-performance trade-offs favor elasticity over extreme thermal endurance. Industrial application demand anchors bulk pail and drum packaging, whereas aerospace and precision automotive procurement drives tube and cartridge formats requiring controlled dispensing and shelf-life assurance.
EPA oversees VOC content limits under architectural coatings rules affecting construction-grade sealants, while REACH and RoHS constrain hazardous substance thresholds in European industrial supply chains, forcing reformulation investments that favor producers with integrated regulatory laboratories. FAA material flammability standards for aircraft interiors and powerplant assemblies create additional certification barriers that filter supplier pools. Stakeholders must monitor divergence between U.S. and EU chemical hazard classifications, as misaligned substance restrictions threaten cross-Atlantic product portability and inventory pooling strategies.
Market Dynamics
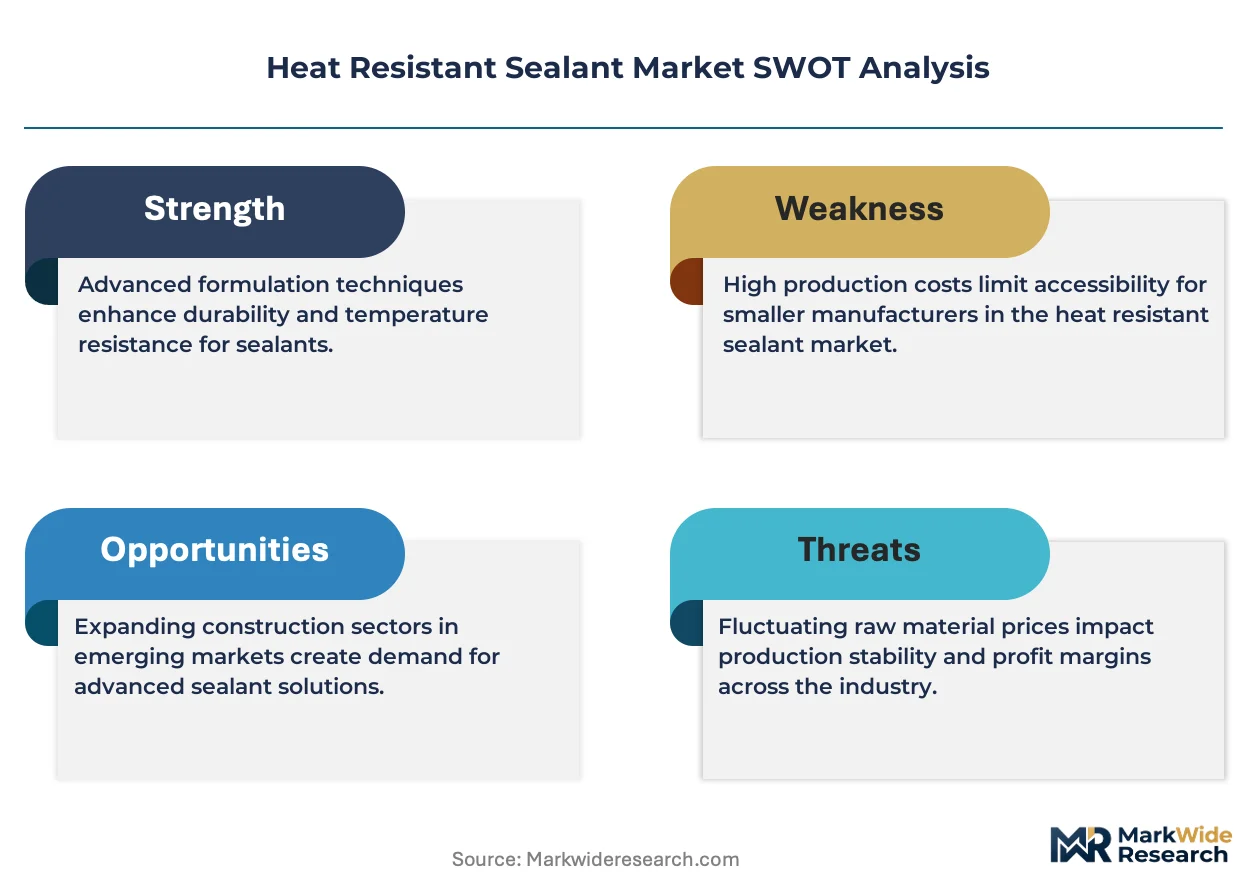
Reformulation pressure from REACH chemical compliance and EPA VOC limits is compressing supplier margins while simultaneously filtering out formulators lacking integrated regulatory laboratories. This structural force redistributes market share toward producers with captive silicone polymer supply and in-house certification capabilities.
Growth Catalysts
- REACH substance restrictions:European automotive OEMs are accelerating procurement of low-VOC silicone formulations for underhood sealing, forcing supply base consolidation that benefits compliant producers with German testing facilities.
- Jet engine thermal protection:Commercial aviation output recovery is expanding demand for FAA-certified high-temperature gaskets and exhaust seals rated above 300°C continuous operation.
- Industrial furnace maintenance cycles:Steel and glass manufacturers in the US Rust Belt are shortening replacement intervals for combustion chamber seals, driving recurring demand for drum-format silicone compounds.
Market Restraints
- Silicone monomer concentration:Four producers control over seventy percent of global dimethylsiloxane supply, creating input cost volatility that squeezes mid-tier formulator margins during energy price spikes.
- Polyurethane substitution ceiling:Automotive body sealing below 150°C is migrating toward waterborne polyurethane where thermal requirements permit, capping silicone volume growth in cost-sensitive segments.
- FAA certification timelines:New material qualification for aircraft powerplant applications requires eighteen to thirty-six months of flame-resistance and outgassing testing, delaying revenue recognition for innovative formulations.
Strategic Opportunities
- India automotive localization:PLI scheme incentives for electric vehicle manufacturing are creating demand for battery pack thermal interface materials and firestop sealants in Chennai and Pune industrial corridors.
- EU Green Deal industrial retrofit:Carbon border adjustment mechanisms are accelerating furnace efficiency upgrades across European steel plants, expanding addressable market for high-temperature joint sealants.
- Additive manufacturing convergence:Direct deposition of silicone-based conformal coatings onto 3D-printed aerospace brackets is eliminating secondary sealing operations and reducing assembly labor content.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in peroxide cure kinetics and filler dispersion for 250°C+ service conditions is concentrated among retiring technical staff at legacy silicone producers.
- Dual regulatory compliance:Product portability between EPA architectural coatings jurisdictions and REACH industrial chemical frameworks requires parallel formulation tracks that fragment R&D resources and inventory pooling.
- Legacy furnace integration:New high-performance sealants must accommodate irregular mating surfaces and thermal expansion mismatches in decades-old industrial equipment without complete rebuilds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Resistant Sealant Market |
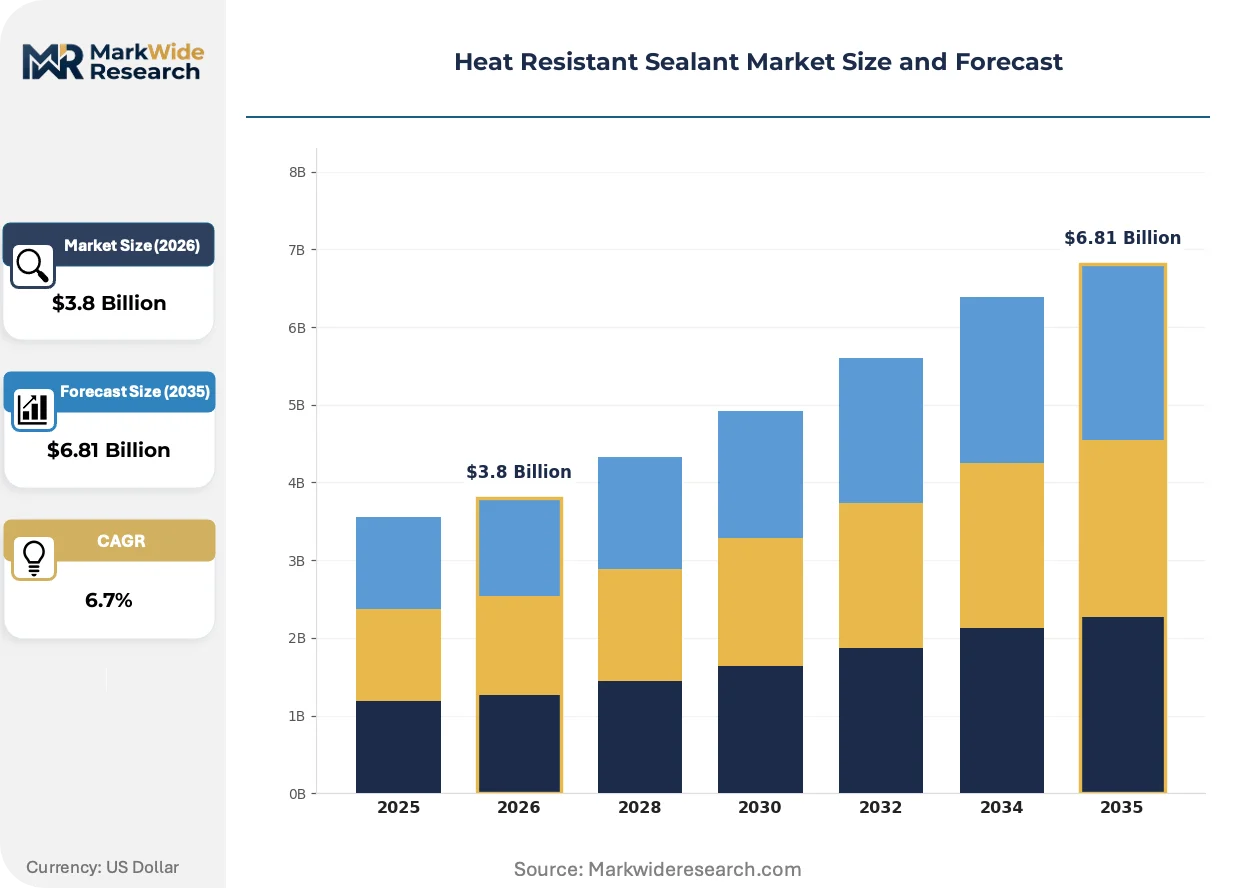
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Sealants, Polyurethane Sealants, Acrylic Sealants, Other Sealants Application: Construction, Automotive, Aerospace, Industrial End User: Manufacturers, Contractors, DIY Users, Engineers Packaging Type: Tubes, Jars, Pails, Bulk Containers |
| Companies Covered | Dow, Vitcas, Sika AG, Henkel AG & Co. KGaA, 3M, H.B. Fuller Company, Shin-Etsu Chemical, Momentive Performance Materials Inc., ACTEGA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Resistant Sealant Market Evolving Landscape
Active reformulation toward non-toxic chemistries is intersecting with precision dispensing requirements in aerospace and battery manufacturing. These pressures are compressing development cycles and elevating regulatory laboratory capabilities from cost center to competitive differentiator.
Room-temperature-vulcanizing silicone formulations with enhanced thermal conductivity fillers are miniaturizing thermal management assemblies in electric vehicle battery packs. Cell manufacturers are specifying these materials for module-to-coolant plate interfaces at volumes exceeding prior automotive sealant consumption. This technology is miniaturizing the physical footprint of thermal protection systems while maintaining dielectric strength and flame resistance ratings.
EPA architectural coatings VOC limits are constraining solvent-based construction sealant formulations and accelerating waterborne acrylic displacement in commercial building applications. Manufacturers with integrated analytical laboratories are capturing specification share by pre-certifying products across multiple state-level air quality jurisdictions. California South Coast Air Quality Management District rules are exerting outsized influence on national product portfolios due to market size and precedent-setting enforcement patterns.
Specification engineers at tier-one automotive suppliers are consolidating approved vendor lists and demanding lot-level thermal performance certification data with each delivery. Direct portal-based procurement with embedded compliance documentation is displacing distributor-mediated purchasing for high-volume programs. This concentration is most visible in Germany's automotive corridor where BMW, Mercedes-Benz, and Volkswagen procurement teams co-locate technical approval staff with sealant testing facilities.
Heat Resistant Sealant Market Segmentation
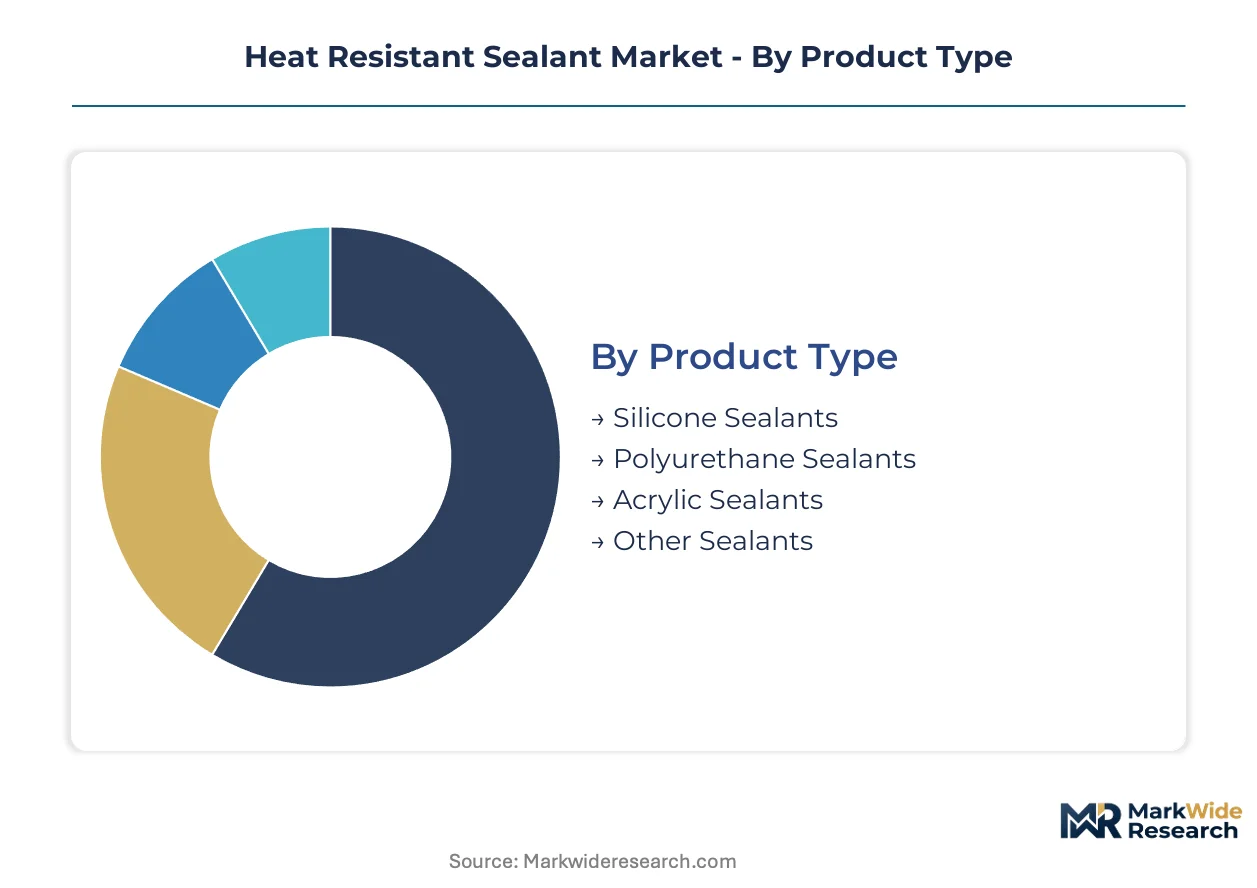
Segmentation in heat resistant sealants reveals distinct margin architectures across chemistry types and procurement channels. Aerospace and automotive OEMs drive premium pricing through certification-intensive specifications, while construction and industrial maintenance segments compete on volume scale and formulation efficiency.
Product Type:
Silicone formulations command the widest margin spreads due to raw material concentration and performance premiums above 200°C service conditions.
- Silicone Sealants:Peroxide-cured dimethylsiloxane polymers with thermal stability exceeding 300°C continuous operation anchor aerospace engine sealing and industrial furnace applications. German automotive OEMs and US jet engine manufacturers specify these formulations for exhaust gaskets and combustion chamber seals where FAA certification and REACH compliance create supplier filtering.
- Polyurethane Sealants:Two-component aliphatic and aromatic formulations dominate automotive body sealing and commercial construction below 150°C, balancing elasticity with cost efficiency. Waterborne displacement is accelerating in California and EU jurisdictions under VOC constraints, favoring producers with integrated analytical laboratories.
- Acrylic Sealants:Waterborne emulsion polymers are displacing solvent-based construction grades under EPA architectural coatings rules, with pre-certified products capturing specification share across state-level air quality districts.
- Other Sealants:Specialty hybrid and inorganic formulations address niche ceramic and glass sealing applications in steel and glass manufacturing equipment.
The dominant share belongs to Silicone Sealants, while Acrylic Sealants are closing the gap fastest.
Application:
Volume concentration diverges sharply between cyclical industrial maintenance and growth-oriented transportation electrification.
- Construction:Commercial building envelope sealing and firestop applications drive drum and pail procurement through distributor channels, with California South Coast Air Quality Management District rules exerting national portfolio influence.
- Automotive:Underhood sealing and electric vehicle battery pack thermal interface materials are expanding specification requirements for lot-level thermal performance certification data.
- Aerospace:Jet engine gaskets and exhaust seals rated above 300°C require eighteen to thirty-six month FAA qualification timelines, filtering supplier pools to producers with captive silicone polymer supply.
- Industrial:Steel and glass furnace maintenance cycles in the US Rust Belt and European steel corridors drive recurring demand for high-temperature joint sealants amid carbon border adjustment mechanisms.
Industrial applications anchor volume baselines, though Automotive is climbing the fastest on electric vehicle manufacturing localization.
End User:
Procurement sophistication separates specification engineers from price-sensitive spot buyers.
- Manufacturers:Tier-one automotive and aerospace OEMs consolidate approved vendor lists and demand embedded compliance documentation through direct portal-based procurement.
- Contractors:Commercial construction and industrial maintenance channels purchase through traditional distribution, with project-scale volume driving pricing negotiation leverage.
- DIY Users:Retail cartridge and tube formats for residential repair and improvement represent price-elastic demand with minimal specification requirements.
- Engineers:Design-phase specification authority in aerospace and battery manufacturing creates long-term lock-in effects for approved material platforms.
Manufacturers control the premium tier, while Engineers are gaining procurement influence fastest through design-phase specification authority.
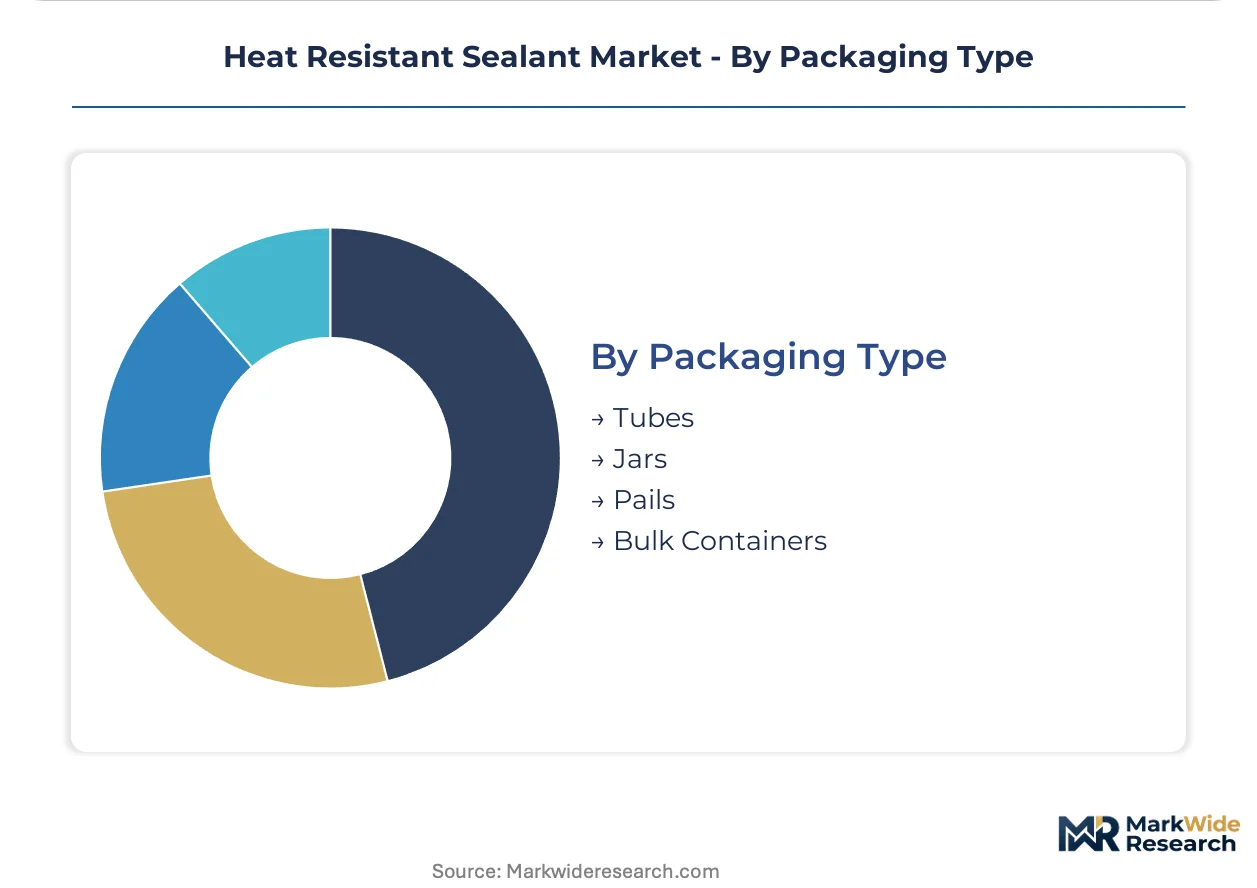
Packaging Type:
Format selection correlates directly with application precision requirements and inventory velocity.
- Tubes:Cartridge formats with controlled dispensing and shelf-life assurance serve aerospace and precision automotive procurement where lot traceability is mandatory.
- Jars:Mid-volume containers address specialty repair and maintenance applications requiring brush or spatula application methods.
- Pails:Standard industrial packaging for construction and furnace maintenance segments balances material access with handling efficiency.
- Bulk Containers:Drum and tote formats anchor steel and glass manufacturing procurement with high-volume, recurring replacement cycles.
Bulk Containers dominate industrial volume, though Tubes are expanding share fastest on aerospace and battery manufacturing precision requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports specialty silicone formulations to aerospace manufacturers in France and the United Kingdom, while the United States supplies industrial furnace sealants to steel producers across Canada and Mexico.
United States
Jet engine manufacturers in Connecticut and Ohio are expanding procurement of FAA-certified gaskets rated above 300°C. EPA VOC limits under architectural coatings rules are forcing reformulation of construction-grade sealants toward waterborne chemistries. The US Rust Belt steel corridor drives recurring drum-format demand for combustion chamber seal replacements.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg are consolidating approved vendor lists for underhood silicone formulations. REACH substance restrictions are filtering supplier pools to producers with integrated regulatory laboratories. The industrial corridor around Stuttgart and Munich co-locates testing facilities with BMW, Mercedes-Benz, and Volkswagen procurement teams.
China
Steel and glass manufacturers in Hebei and Jiangsu provinces are shortening furnace maintenance cycles amid carbon reduction mandates. MIIT industrial efficiency standards are accelerating equipment retrofit demand. The Yangtze River Delta concentration of specialty chemical producers is expanding domestic silicone polymer capacity.
India
Electric vehicle battery pack manufacturers in Chennai and Pune are specifying thermal interface materials for module-to-coolant plate applications. PLI scheme incentives for EV manufacturing are localizing demand previously served by imports. The Tamil Nadu industrial corridor is attracting sealant formulators to co-locate with cell production facilities.
Japan
Precision automotive suppliers in Aichi Prefecture are demanding lot-level thermal performance certification with each delivery. METI energy efficiency regulations are driving furnace seal upgrades across steel and ceramics sectors. The Nagoya industrial cluster maintains tight technical approval relationships between tier-one suppliers and material specification engineers.
Heat Resistant Sealant Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates with captive silicone polymer supply, creating a tiered structure where raw material control separates premium-positioned formulators from mid-tier competitors. Strategic archetypes include backward-integrated polymer producers, regulatory laboratory-equipped formulators, and regional specialists serving maintenance-heavy industrial segments. Dominant competitive moves center on certification pre-positioning for FAA and REACH compliance, plus geographic co-location with automotive OEM technical approval centers.
Among North American and European integrated producers, Dow and Henkel AG & Co. KGaA exemplify the backward-integrated archetype with in-house silicone polymer production, while Sika AG occupies a position within the construction-specialist tier. These three anchors represent distinct competitive vectors: polymer control, dual-track automotive-industrial R&D, and building chemicals scale respectively.
| Leading Market Players |
|---|
| Dow |
| Vitcas |
| Sika AG |
| Henkel AG & Co. KGaA |
| 3M |
| H.B. Fuller Company |
| Shin-Etsu Chemical |
| Momentive Performance Materials Inc. |
| ACTEGA |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between German automotive OEMs and silicone polymer producers lock in both dimethylsiloxane supply access and eighteen-month price visibility, insulating qualified formulators from spot market volatility while compressing margins for non-integrated competitors.
Pricing Analysis
Current-generation peroxide-cured silicone formulations command substantial premiums over prior-generation condensation-cure products due to FAA certification and REACH compliance requirements, while next-generation thermal-conductive grades for battery applications are resetting price benchmarks upward. Three-tier pricing structure across premium aerospace-certified, standard automotive-industrial, and economy construction tiers separates formulators by certification investment depth. Cost compression in the construction segment is intensifying because waterborne acrylic displacement under EPA VOC rules favors producers with captive analytical laboratories. Tier-one automotive OEMs exhibit lowest price sensitivity due to lot-level thermal performance certification requirements, while spot-buying industrial maintenance contractors drive the hardest volume negotiations.
Supply Chain Analysis
Inventory cycles for dimethylsiloxane monomer extend to twelve weeks at major polymer producers, creating lead-time vulnerability for non-integrated formulators during energy price spikes. Supply concentrates in Germany, the United States, and China, with German producers exporting specialty formulations to French and UK aerospace manufacturers. Raw material dependencies center on silicon metal from Norway and Brazil, methyl chloride from US Gulf Coast petrochemical complexes, and platinum-group catalysts from South African refiners. Single-source vulnerability runs through the four producers controlling seventy percent of global dimethylsiloxane capacity. Distribution runs through direct portal-based procurement for automotive and aerospace OEMs, with drum-format industrial sales flowing through regional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as tier-one automotive OEMs consolidate approved vendor lists and demand embedded compliance documentation, fragmenting pricing leverage away from mid-tier formulators toward specification-engineer-driven procurement.
For Market Incumbents: Fortify captive silicone polymer production to defend margin position against dimethylsiloxane supply volatility, while accelerating REACH and FAA certification pre-positioning to filter supplier pools before emerging Asian producers achieve qualification timelines. Backward integration into thermal-conductive filler processing addresses the battery manufacturing localization wave threatening specification share. For New Entrants and Emerging Players: Lead with electric vehicle battery pack thermal interface materials in India's Tamil Nadu and Maharashtra corridors, where PLI scheme incentives are localizing demand faster than incumbent formulators can establish technical approval relationships. A co-location strategy adjacent to cell production facilities offers the most penetrable entry vector against entrenched German automotive supply relationships. For Investors and Strategic Acquirers: Regional specialists with integrated regulatory laboratories and existing OEM technical approval relationships in Germany or Japan represent the highest-conviction acquisition archetype for long-term viability through the electrification transition. Watch for divergence between EPA and REACH substance restriction timelines as an inflection signal requiring parallel formulation tracks and inventory fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Polymer Production | Captive dimethylsiloxane supply insulates margin from energy-driven input volatility at German and US facilities. |
| Regulatory Laboratory Certification Pre-Positioning | Integrated REACH and FAA testing capabilities filter supplier pools ahead of emerging competitor qualification. |
| Battery Manufacturing Corridor Co-Location | Technical approval staff proximity to Chennai and Pune cell producers accelerates thermal interface material specification. |
| Waterborne Formulation Platform Expansion | EPA architectural coatings compliance captures construction specification share across California and state-level jurisdictions. |
| Long-Term Supply Agreement with Aerospace OEMs | Eighteen-month offtake contracts lock in jet engine gasket demand visibility through commercial aviation output recovery. |
Research Methodology
A spread of perspectives from silicone polymer plant managers, automotive OEM procurement leads, aerospace specification engineers, and industrial furnace maintenance directors converged on the working assumptions shaping this analysis. Primary fieldwork combined with secondary validation from customs trade data, ACC and Cefic chemical industry reports, SEC 10-K filings of integrated producers, and FAA material qualification databases. Bottom-up demand modeling across chemistry types and packaging formats triangulated against top-down macroeconomic indicators.
Segmentation dimensions modeled include chemistry type, application sector, end-user procurement sophistication, and packaging format across the projection horizon. CAGRs were derived from regression analysis of historical volume trajectories and forward-looking capacity announcements. Industry-specific forecast inputs incorporated jet engine production schedules from Connecticut and Ohio manufacturers, plus electric vehicle battery pack thermal management content assumptions from Tamil Nadu and Pune localization trends.
Forecasts assume regulatory continuity in EPA architectural coatings rules and REACH substance restrictions; material policy shifts would require re-modeling of waterborne displacement rates and silicone formulation portability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Europe Epoxy Adhesive Market
Adhesives & Sealants
Middle East and Africa Sealants Market
Adhesives & Sealants
Foam Adhesive Market
Adhesives & Sealants
UV Adhesives Market
Adhesives & Sealants
Elastomeric Adhesive Market
Adhesives & Sealants
Vietnam Construction Chemicals Market
Adhesives & Sealants
Canada Sealants Market
Adhesives & Sealants
Wearable Skin Adhesives Market
Adhesives & Sealants
Global Spray Adhesive Market
Adhesives & Sealants
Industrial Adhesives Market
Adhesives & Sealants
Dental Impression Tray Adhesives Market
Adhesives & Sealants
Epoxy Glue Market
Adhesives & Sealants
Wood Adhesives and Binders Market
Adhesives & Sealants
Middle-East and Africa Hot-Melt Adhesives Market
Adhesives & Sealants
Optically Clear Adhesives Market
Adhesives & Sealants
Aviation Adhesives and Sealants Market