
 Animal Glue Market | 2026-2036
Animal Glue Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Glue Market Outlook
China is tilting toward expanded gelatin extraction capacity to serve regional pharmaceutical and food packaging demand. H.B. Fuller Company leverages its adhesive formulation expertise to sustain supply relationships across woodworking and paper industry channels. Gelita AG anchors European production with specialized collagen peptide technologies for industrial and food-grade segments. Xiamen Gelken Gelatin Co Ltd. dominates domestic Chinese output, controlling raw material sourcing from regional abattoir networks.
Animal glue comprises protein-based adhesives derived from collagen hydrolysis of mammalian or fish tissues, typically exhibiting viscosities between 3,000 and 50,000 centipoise depending on extraction temperature and pH modulation. Manufacturers render connective tissues through controlled thermal degradation to produce binding agents for woodworking joinery, bookbinding restoration, and abrasive wheel fabrication. Gelatin grades command premium positioning in pharmaceutical capsule production and photographic emulsion coatings where purity thresholds exceed industrial specifications. Fish glue represents the fastest-expanding product category as marine collagen sourcing bypasses bovine-related religious dietary restrictions and BSE regulatory barriers. Blood albumin maintains niche occupancy in plywood veneer bonding where moisture resistance requirements are moderate.
REACH and the EU Green Deal impose substance disclosure obligations on European animal glue importers, while China's SAMR enforces GB standards for food-contact gelatin purity. The US FDA regulates pharmaceutical-grade collagen through drug master file requirements that constrain new supplier qualification timelines. Stakeholders must monitor evolving ECHA classification reviews for collagen hydrolysates and assess captive rendering capacity against regional livestock supply volatility.
Market Dynamics
REACH substance disclosure mandates and China's GB food-contact standards are forcing manufacturers to reconfigure rendering protocols and captive sourcing networks. The regulatory divergence between European hazard classification reviews and Asian pharmaceutical purity specifications is fragmenting production standards.
Growth Catalysts
- Pharmaceutical capsule demand:Gelatin purity requirements for drug delivery systems are tightening across multiple jurisdictions. Drug master file submissions are accelerating supplier qualification timelines.
- Fish glue substitution:Marine collagen extraction bypasses bovine spongiform encephalopathy barriers and religious dietary restrictions. Southeast Asian fisheries are expanding hydrolysis capacity.
- REACH compliance services:European importers require third-party certification for adhesive-grade animal proteins. Testing laboratories in Germany and the Netherlands are scaling analytical capacity.
Market Restraints
- Raw material volatility:Abattoir byproduct supply fluctuates with livestock culling cycles and disease outbreaks. Rendering facilities face margin compression when hide and bone prices spike.
- Substitution by synthetic adhesives:Polyvinyl acetate and polyurethane formulations capture woodworking and packaging applications. These alternatives offer consistent viscosity and moisture resistance.
- Regulatory friction:ECHA classification reviews for collagen hydrolysates create uncertainty around import documentation. European adhesive manufacturers face extended compliance verification periods.
Strategic Opportunities
- Underpenetrated pharmaceutical markets:India's CDSCO is streamlining gelatin excipient approvals for domestic generic manufacturers. Local rendering partnerships could bypass import tariff structures.
- Regulatory tailwind from EU Green Deal:Bio-based adhesive mandates in construction and furniture manufacturing favor protein binders over petrochemical alternatives. Member state procurement guidelines are incorporating circular economy criteria.
- Photographic emulsion revival:Analog photography niche markets in Japan and South Korea sustain demand for ultra-high-purity gelatin. Specialty coating applications command significant price premiums.
Industry Challenges
- Skilled rendering technician shortage:Thermal degradation process control requires expertise in pH modulation and viscosity calibration. Vocational training programs have not kept pace with retirements.
- Cross-contamination certification:Pharmaceutical-grade facilities must demonstrate complete separation from industrial adhesive production lines. Dedicated equipment investments strain mid-scale operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Glue Market |
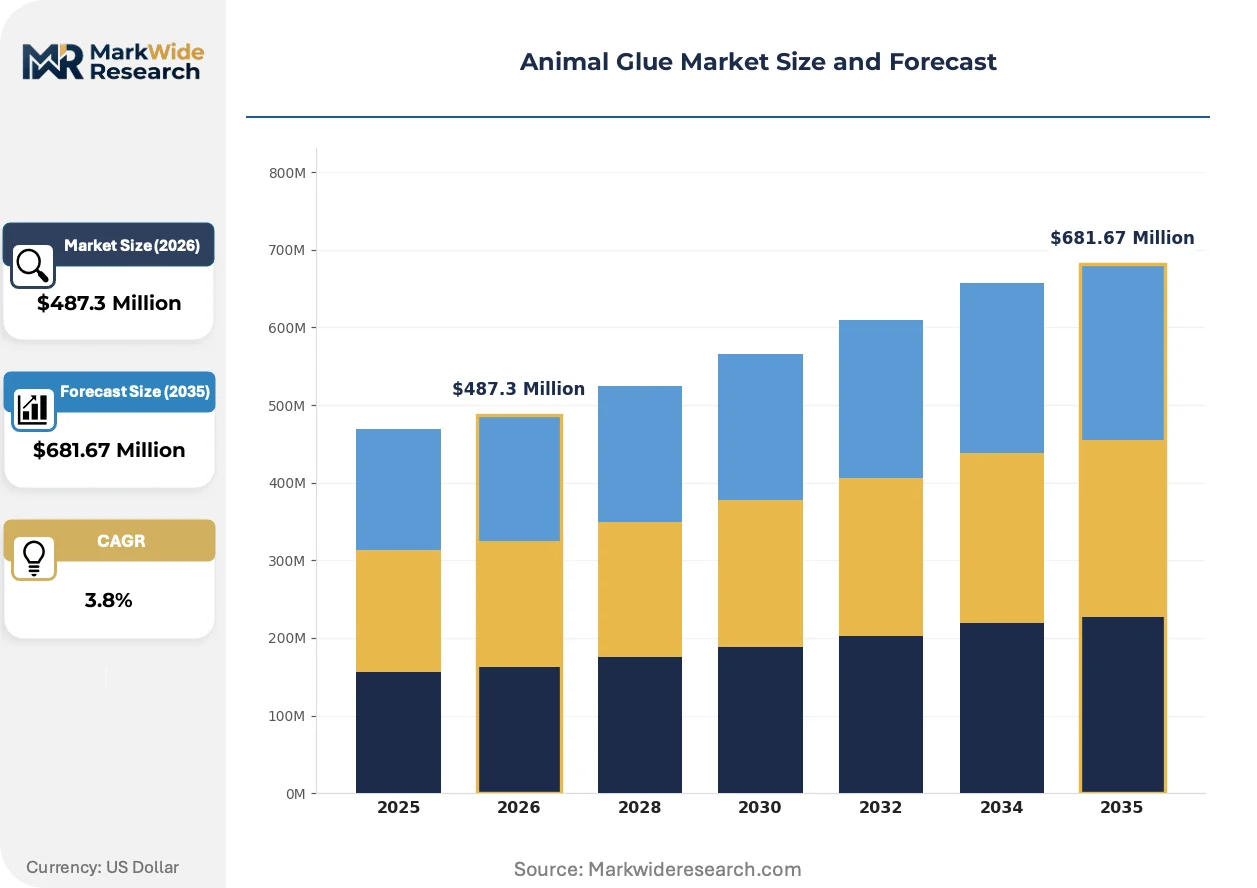
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $681.67 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, Casein, Fish Glue, Blood Albumin End User: Leather Industry, Woodworking, Paper Industry, Textile Industry Application: Adhesives, Coatings, Mold Making, Binding Grade: Industrial, Food Grade, Cosmetic Grade, Pharmaceutical Grade |
| Companies Covered | H.B. Fuller Company, Sika AG, Henkel AG & Co. KGaA, Rallis India Limited, McAdams Chemical Mfg Co., LD Davis Industries, Gelita AG, Xiamen Gelken Gelatin Co Ltd., African Glue Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Glue Market Strategic Shifts
Enzymatic extraction methods and precision fermentation alternatives are disrupting century-old thermal rendering processes. These technologies promise to decouple collagen supply from livestock processing volumes entirely.
Cold-water enzymatic hydrolysis preserves longer peptide chains and yields superior gel strength compared to traditional thermal methods. Pharmaceutical manufacturers in Switzerland and Japan are qualifying these grades for enteric coating applications. The technology is rendering obsolete batch-to-batch viscosity variation that has plagued industrial adhesive consistency.
REACH substance of very high concern candidate list expansions are capturing certain collagen hydrolysate impurities under stricter disclosure thresholds. Importers must now document supply chain provenance back to individual abattoir facilities. Adhesive-grade animal glue shipments into Rotterdam and Hamburg are facing extended customs inspection protocols.
Consolidation among bookbinding restoration specialists and fine woodworking artisans is concentrating demand among fewer, larger archival suppliers. These buyers now specify custom viscosity ranges and protein concentration certificates rather than accepting standard industrial grades. Germany's heritage conservation institutes and Japan's traditional craft associations are driving this specification escalation.
Animal Glue Market Segmentation
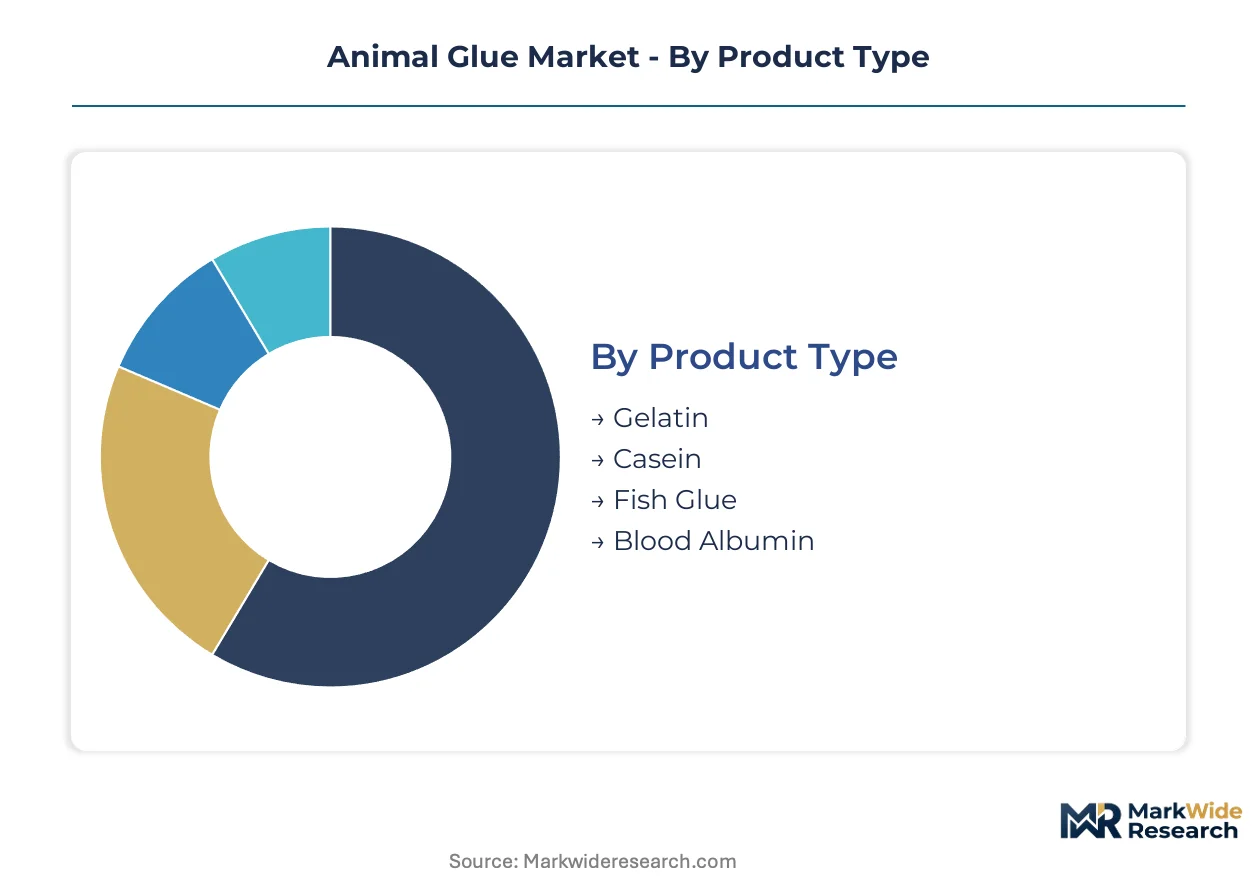
Animal glue segmentation reflects divergent purity requirements across pharmaceutical, food, and industrial channels. Each category maps distinct technical specifications to regulatory frameworks that govern formulation protocols and sourcing constraints.
Product Type:
Use-case spectrum spans pharmaceutical-grade hydrocolloids to industrial binding agents with viscosity ranges from 3,000 to 50,000 centipoise.
- Gelatin:Collagen hydrolysate derived from mammalian connective tissue through controlled thermal degradation. Pharmaceutical capsule manufacturers in Switzerland and Japan prioritize this grade for enteric coating applications where peptide chain length determines gel strength.
- Fish Glue:Marine collagen extraction bypasses bovine spongiform encephalopathy barriers and halal/kosher dietary restrictions. Southeast Asian fisheries are expanding enzymatic hydrolysis capacity to serve European adhesive importers facing REACH substance disclosure mandates.
- Casein:Milk protein precipitate binds labels and cartons in moisture-resistant packaging. German woodworking specialists specify this grade for veneer applications requiring moderate water resistance.
- Blood Albumin:Serum protein fraction from abattoir byproducts adheres plywood layers where synthetic alternatives prove cost-prohibitive. Brazilian plywood mills source this material for interior-grade panel production.
Established volume favors gelatin; emerging adoption favors fish glue.
End User:
Cost tier stratification separates premium pharmaceutical channels from commodity industrial applications.
- Leather Industry:Tanning agents and finishing binders utilize protein hydrolysates for grain stabilization. Italian tanneries in the Arzignano cluster specify custom viscosity grades for luxury footwear applications.
- Woodworking:Joinery adhesives and veneer bonding demand consistent thermal reactivation properties. Heritage restoration workshops in Germany and Japan now require batch-specific protein concentration certificates.
- Paper Industry:Sizing agents and bookbinding adhesives rely on animal glue for archival longevity. Consolidation among restoration specialists is concentrating procurement among fewer certified suppliers.
- Textile Industry:Sizing compounds prepare warp threads for weaving high-tension fabrics. Indian cotton mills represent expanding demand as domestic rendering capacity scales.
Woodworking maintains the largest installed base; leather processing shows steepest expansion trajectory.
Application:
Volume concentration clusters in adhesive formulations that displace synthetic alternatives under bio-based procurement mandates.
- Adhesives:Protein binders serve woodworking joinery, paper lamination, and abrasive wheel fabrication where EU Green Deal circular economy criteria favor renewable inputs.
- Coatings:Photographic emulsion applications in Japan and South Korea sustain demand for ultra-high-purity gelatin with price premiums reflecting impurity thresholds below 50 parts per million.
- Mold Making:Foundry binders shape sand casting molds for non-ferrous metal production. Traditional craft preservation in India maintains this niche against synthetic resin displacement.
- Binding:Pharmaceutical tablet and capsule assembly commands the most stringent purity certifications. FDA drug master file requirements constrain new supplier qualification timelines.
Adhesive applications dominate current throughput; coating applications capture the highest margin realization.
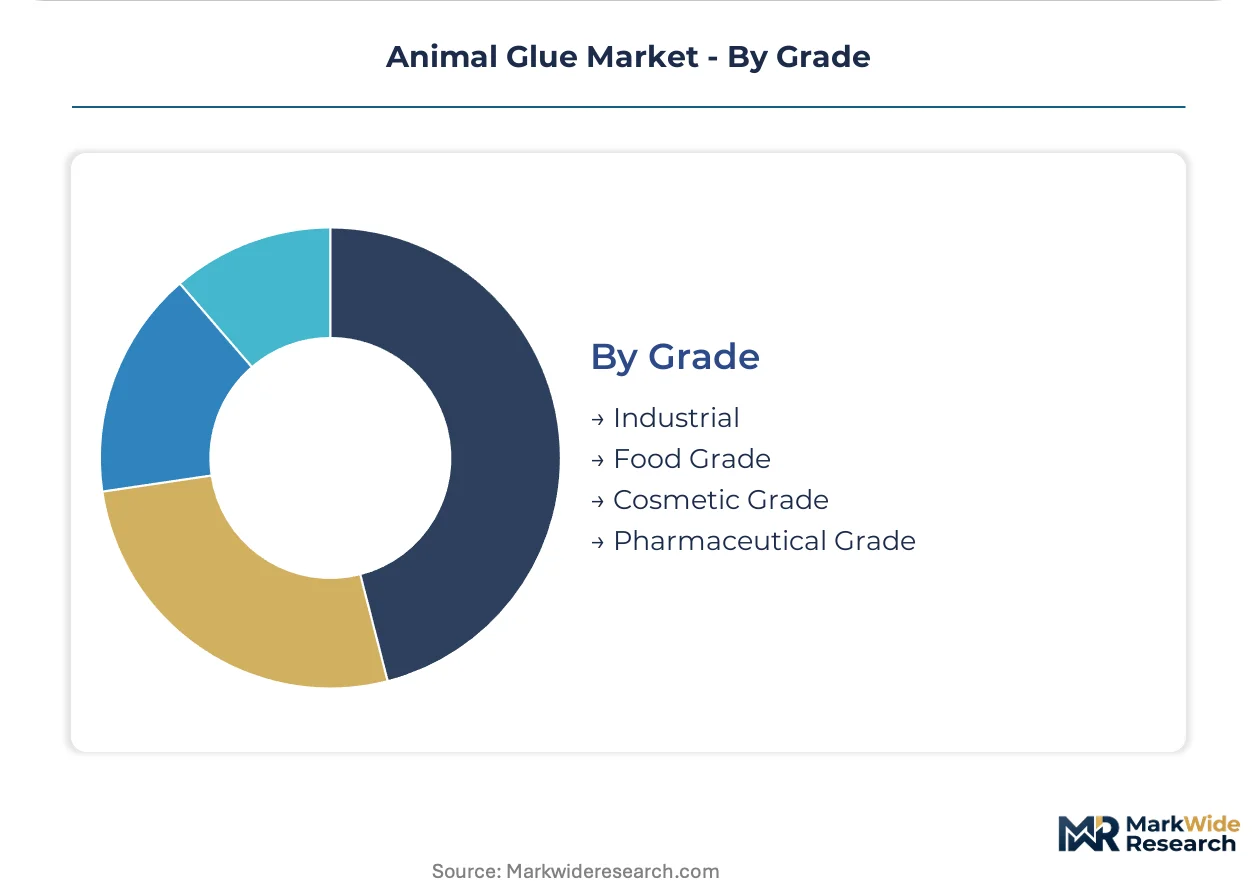
Grade:
Margin structure inverts with purity, as pharmaceutical grades command multiples of industrial pricing despite smaller batch volumes.
- Industrial:Standard viscosity adhesives for woodworking and packaging face substitution pressure from polyvinyl acetate and polyurethane formulations with consistent moisture resistance.
- Food Grade:Edible gelatin for confectionery and dairy applications complies with China's GB standards and EU EFSA purity specifications. Xiamen Gelken controls significant domestic Chinese output.
- Cosmetic Grade:Collagen peptides for topical formulations require documented absence of specific allergens. South Korean beauty manufacturers drive specification escalation.
- Pharmaceutical Grade:Excipient purity for drug delivery systems demands complete production line separation from industrial grades. Dedicated equipment investments strain mid-scale operators.
Industrial grade anchors volume throughput; pharmaceutical grade delivers margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rendering capacity clusters in China, Germany, and the United States, where established abattoir networks feed specialized collagen extraction facilities. Regional regulatory divergence is fragmenting production standards and reshaping trade flows.
China
Domestic gelatin manufacturers serve pharmaceutical capsule producers and export markets through expanded extraction facilities in Fujian and Shandong provinces. SAMR enforces GB standards for food-contact gelatin purity that exceed prior thresholds. Xiamen Gelken anchors regional output through captive sourcing from provincial abattoir networks.
Germany
Heritage conservation institutes and woodworking clusters in Bavaria and Baden-Württemberg drive specification escalation for custom viscosity grades. ECHA classification reviews for collagen hydrolysates impose extended compliance verification on adhesive importers through Rotterdam and Hamburg. Gelita AG maintains specialized collagen peptide production for industrial and food-grade segments.
United States
Woodworking joinery and bookbinding restoration channels concentrate demand among archival suppliers in the Midwest and Northeast. FDA drug master file requirements constrain pharmaceutical-grade collagen supplier qualification timelines. LD Davis Industries and McAdams Chemical Mfg Co. occupy positions within adhesive formulation and chemical manufacturing tiers.
India
CDSCO is streamlining gelatin excipient approvals for domestic generic pharmaceutical manufacturers. Cotton mills in Maharashtra and Gujarat represent expanding textile sizing demand as regional rendering capacity scales. Rallis India Limited sits within the agricultural and specialty chemicals segment with potential cross-application expertise.
Switzerland
Pharmaceutical manufacturers in Basel and Geneva qualify enzymatic extraction grades for enteric coating applications where peptide chain length determines performance. Swissmedic maintains stringent excipient certification protocols that favor established European suppliers. Precision fermentation research clusters in Zurich are advancing alternatives to thermal rendering processes.
Animal Glue Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper technical positioning. The vendor base separates into consolidated multinational adhesive formulators, mid-scale regional renderers, and niche heritage suppliers serving archival restoration markets. Three archetypes dominate: diversified chemical conglomerates with adhesive divisions, specialized collagen extraction houses with captive raw material networks, and artisan-scale producers serving conservation-grade specifications. Competitive moves concentrate on backward integration into rendering capacity and geographic expansion through distribution partnerships.
Among diversified chemical conglomerates, Henkel AG & Co. KGaA and Sika AG represent the platform integrator archetype with broad adhesive portfolios spanning construction and industrial applications. H.B. Fuller Company exemplifies the specialized formulator position with concentrated expertise in woodworking and paper industry channels. Xiamen Gelken Gelatin Co Ltd. and African Glue Industries occupy regional renderer positions with localized supply chain control. Gelita AG anchors the European specialized extraction tier with dedicated collagen peptide technologies.
| Leading Market Players |
|---|
| H.B. Fuller Company |
| Sika AG |
| Henkel AG & Co. KGaA |
| Rallis India Limited |
| McAdams Chemical Mfg Co. |
| LD Davis Industries |
| Gelita AG |
| Xiamen Gelken Gelatin Co Ltd. |
| African Glue Industries |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in European rendering facilities is intensifying competition for abattoir byproduct streams and compressing margins for adhesive-grade animal protein suppliers. This utilization squeeze simultaneously elevates input costs for industrial formulators and strengthens the bargaining position of large-scale gelatin extractors with captive sourcing networks.
Pricing Analysis
REACH substance disclosure mandates dictate the pricing tier structure across European adhesive markets, separating certified pharmaceutical-grade collagen from industrial binding agents. Three-tier pricing stratifies across premium pharmaceutical, standard food-grade, and economy industrial levels, with peptide chain length and impurity thresholds as the primary differentiation drivers. Cost compression in industrial grades is intensifying because polyvinyl acetate alternatives capture moisture-sensitive woodworking applications. Small-scale heritage restoration workshops demonstrate the least price sensitivity, while commodity packaging converters face acute margin pressure from synthetic substitution.
Supply Chain Analysis
Tariff exposure between Southeast Asian fisheries and European adhesive importers dominates supply chain risk calculus as marine collagen sourcing accelerates. Raw material procurement draws from Chinese abattoir networks, Indonesian fish processing clusters, and Brazilian bovine rendering facilities. Supply chain vulnerability centers on single-source dependency for pharmaceutical-grade gelatin extraction, where FDA drug master file requirements constrain rapid supplier switching. Distribution runs through specialized chemical distributors in Germany and the Netherlands, with direct procurement relationships dominating high-volume pharmaceutical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Animal glue markets are entering early-cycle expansion as enzymatic extraction technologies decouple collagen supply from livestock processing volatility. Pharmaceutical capsule demand and bio-based adhesive mandates under the EU Green Deal provide twin tailwinds for specialized extractors.
For Market Incumbents: Entrench position through backward integration into provincial abattoir networks and dedicated pharmaceutical-grade production line separation. Synthetic adhesive substitution in woodworking channels threatens industrial-grade volume; counter this through certification investment for heritage conservation procurement specifications. Capacity addition in Fujian and Shandong provinces strengthens raw material security against regional livestock supply fluctuations. For New Entrants and Emerging Players: Pursue white-space opportunities in Indian pharmaceutical excipient supply, where CDSCO streamlining creates entry pathways for domestic generic manufacturers. Southeast Asian fish glue extraction represents the most penetrable segment, with enzymatic hydrolysis capacity expansion bypassing bovine-related regulatory barriers. A go-to-market angle anchored in REACH compliance certification services addresses European importer documentation gaps. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade collagen peptide production as dedicated equipment requirements strain mid-scale operators. Long-term viability favors platforms with integrated rendering capacity and multi-jurisdictional regulatory qualifications. Acquisition targets should demonstrate established drug master file submissions and captive abattoir relationships. The signal to watch is ECHA classification review outcomes for collagen hydrolysate impurity thresholds, which would reshape import documentation burdens and competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rendering Capacity | Captive abattoir sourcing insulates margin structure from hide and bone price volatility in China. |
| Enzymatic Extraction Technology Deployment | Cold-water hydrolysis preserves peptide chain length for Swiss pharmaceutical enteric coating applications. |
| REACH Compliance Certification Services | Third-party testing laboratories in Germany capture extended customs inspection demand at Rotterdam and Hamburg. |
| Pharmaceutical-Grade Production Line Separation | Dedicated equipment investments satisfy FDA drug master file requirements for capsule excipient supply. |
| Marine Collagen Sourcing Partnerships | Indonesian and Vietnamese fisheries bypass bovine spongiform encephalopathy barriers for European adhesive importers. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from adhesive formulators, and ECHA substance registration databases. Rendering plant managers, pharmaceutical procurement leads at capsule manufacturers, and woodworking restoration specialists provided operational perspective. Secondary validation drew from FDA drug master file submissions, SAMR GB standard publications, and Gelita AG technical documentation. Bottom-up volume estimates triangulated against top-down market sizing from regional production capacity assessments.
Forecast inputs include grade-tier segmentation, end-use industry demand patterns, and regional regulatory framework evolution across the projection horizon. The analytical framework models pharmaceutical, food, industrial, and cosmetic grade tiers against woodworking, paper, leather, and textile end-use channels. CAGRs derive from regression analysis of historical capacity utilization and forward-looking substitution elasticity between animal proteins and synthetic adhesives. Industry-specific inputs incorporate livestock culling cycle patterns and enzymatic extraction technology adoption curves.
Macroeconomic conditions sit as an overlay; deviation in livestock commodity prices, energy costs for thermal rendering, or pharmaceutical R&D expenditure would shift the trajectory. Forecasts reflect assumptions about regulatory stability for collagen hydrolysate classifications and continued pharmaceutical capsule demand growth. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Contact Adhesives Market
Adhesives & Sealants
North America Construction Adhesives and Sealants Market
Adhesives & Sealants
Dispersion Adhesives Market
Adhesives & Sealants
Latex Binders Market
Adhesives & Sealants
South Africa Adhesives Market
Adhesives & Sealants
Dimethylaminoethyl Acrylate Market
Adhesives & Sealants
Leather Glue Market
Adhesives & Sealants
South America Acrylic Adhesives Market
Adhesives & Sealants
Asia-Pacific Epoxy Adhesive Market
Adhesives & Sealants
Global Epoxy Adhesive Market
Adhesives & Sealants
Global Footwear Adhesives Market
Adhesives & Sealants
Hydrophobic Pore-Blocking Agents for Waterproof Concrete Market
Adhesives & Sealants
Applicator Tips Market
Adhesives & Sealants
North America Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Asia-Pacific Adhesives Market
Adhesives & Sealants
Epoxy Curing Agents Market