
 Thin Insulation Market | 2026-2036
Thin Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Thin Insulation Market Outlook
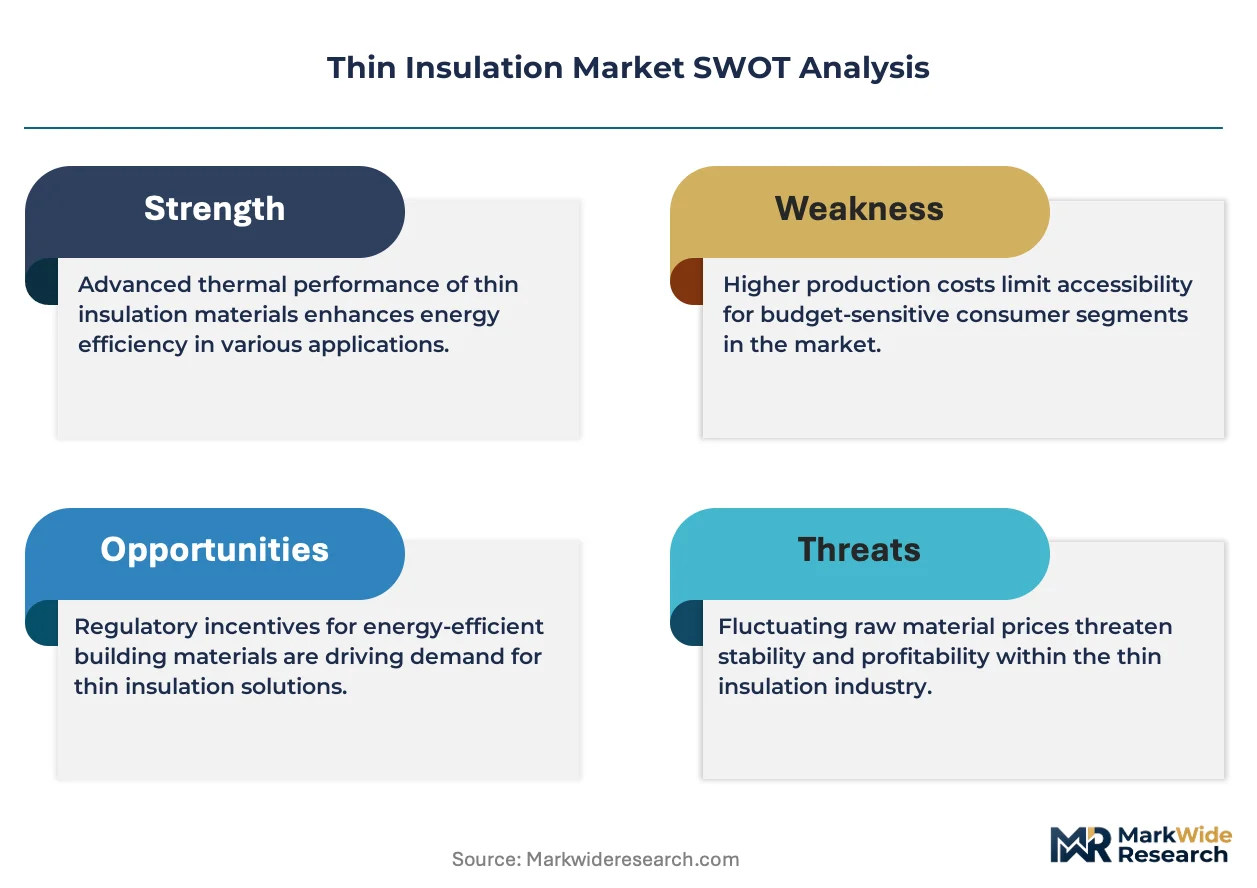
The capital-intensity divergence between thin insulation producers is collapsing as aerogel manufacturing scales down from semiconductor-grade fabs to commodity building materials. Owens Corning leverages its fiberglass infrastructure to dominate residential retrofit channels across North America. Aspen Aerogels specializes in high-performance aerogel blankets for aerospace and industrial applications where thermal efficiency commands premium positioning. BASF SE competes through integrated chemical supply chains that reduce raw material costs for polymeric insulation formulations.
Thin insulation comprises engineered thermal barriers typically measuring under fifty millimeters in installed thickness, manufactured through vacuum-sealed panel technologies, silica aerogel impregnation, or multi-layer reflective foil lamination to restrict conductive and radiant heat transfer in space-constrained envelopes. Foil-based reflective insulation leads volume in warm-climate residential construction where radiant barrier technology reduces cooling loads, while aerogel segments capture disproportionate margin pools in aerospace and cryogenic industrial applications demanding extreme thermal resistance per unit thickness. Vacuum insulation panels occupy a mature but expanding niche in commercial building retrofits where floor space constraints prohibit conventional insulation depths.
The US Department of Energy building codes and EPA energy star certification programs mandate minimum thermal performance thresholds that directly expand addressable demand for thin insulation in residential and commercial envelopes. EU REACH restrictions on formaldehyde-based binders and the F-Gas Regulation phasing out high-GWP blowing agents compel reformulation of fiberglass and spray foam products across European markets. Stakeholders must monitor evolving carbon-border adjustment mechanisms and embodied-carbon disclosure requirements that will restructure procurement criteria for insulation materials in construction supply chains.
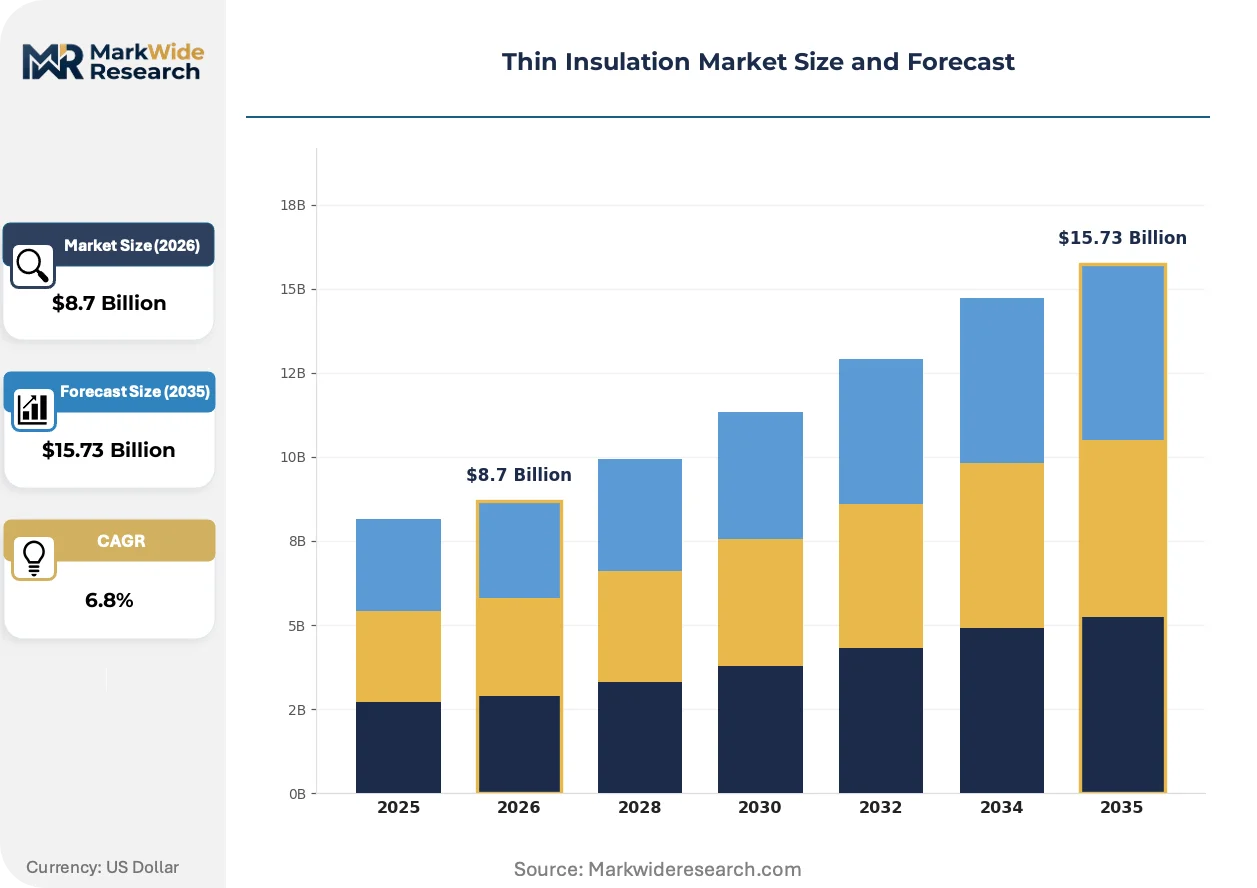
Market Dynamics
The EU Green Deal's tightening building envelope standards are compressing installation depths across commercial retrofits, forcing specification shifts toward vacuum insulation panels and aerogel blankets that deliver thermal resistance in sub-50mm profiles.
Growth Catalysts
- EU F-Gas Regulation:Phasing out high-GWP blowing agents in conventional foam insulation compels European manufacturers to reformulate toward thin-profile alternatives that eliminate hydrocarbon expanders entirely.
- Net-zero commercial retrofits:Japan's METI super-insulation subsidies for office building energy upgrades concentrate demand for vacuum insulation panels where floor-to-ceiling height constraints prohibit traditional insulation depths.
- Silica aerogel maturation:Manufacturing scale-down from semiconductor-grade production lines to commodity building material specifications collapses unit costs for high-performance thermal barriers.
Market Restraints
- Fumed silica feedstock concentration:Five chemical conglomerates control over eighty percent of precipitated silica supply for aerogel production, creating vulnerability to price volatility in construction-grade material sourcing.
- Technical thickness-performance tradeoffs:Vacuum insulation panels below twenty millimeters suffer accelerated thermal bridging at panel edges, limiting applicability in ultra-thin envelope assemblies.
- Formaldehyde binder restrictions:EU REACH limitations on urea-formaldehyde resins in fiberglass mat production force costly adhesive reformulation for reflective foil-laminated products.
Strategic Opportunities
- Cryogenic industrial expansion:LNG terminal construction across the US Gulf Coast and Qatar creates addressable demand for aerogel blankets in pipe-in-pipe insulation systems where space constraints dominate.
- US IRA commercial efficiency tax credits:Section 179D deductions for building envelope improvements accelerate payback periods for premium thin insulation in Class A office renovations.
- Smart building integration:Phase-change material microencapsulation within aerogel matrices enables thermal mass functionality in space-constrained envelopes previously limited to passive insulation.
Industry Challenges
- Vacuum seal integrity certification:Accelerated aging protocols for VIP service life prediction lack harmonization between ISO standards and national building codes, prolonging product approval timelines.
- Installation skill specialization:Aerogel blanket cutting and handling requires particulate containment protocols unfamiliar to conventional insulation contractor workforces, constraining deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thin Insulation Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foil, Aerogel, Fiberglass, Cellulose Application: Building, Automotive, Aerospace, Industrial Technology: Reflective Insulation, Vacuum Insulation, Radiant Barriers, Spray Foam End User: Contractors, OEMs, Architects, Homeowners |
| Companies Covered | Cabot Corporation, Armacell International S.A., Owens Corning, Dow Chemical Company, Johns Manville, 3M Company, BASF SE, Kingspan Insulation, Aspen Aerogels, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thin Insulation Market Strategic Shifts
Material scientists are converging thermal barrier performance with active building systems functionality, compressing the traditional separation between insulation and energy management into unified envelope solutions.
Silica aerogel composite manufacturing is miniaturizing through continuous sol-gel processing equipment scaled for roll-to-roll production rather than batch autoclave curing. Aerospace tier-one suppliers in Germany and Japan are qualifying these materials for satellite thermal protection systems where gram-level mass budgets override cost considerations. The technology is miniaturizing thermal protection into profiles previously occupied only by multi-layer insulation films, collapsing the performance gap between research-grade and commercial aerogel specifications.
REACH restrictions on substance of very high concern (SVHC) classifications are forcing polyurethane foam producers to abandon legacy amine catalysts and halogenated flame retardants. European insulation formulators are migrating toward bio-based polyols and phosphorus reactive flame retardants that maintain thin-profile compressive strength. Germany's KBA and France's ANSM are coordinating building product safety assessments that accelerate mutual recognition for reformulated materials across EU member states.
Building owners are consolidating envelope upgrade decisions with full-decarbonization pathway planning rather than isolated component replacement. Engineering-procurement-construction firms in the US Northeast are bundling thin insulation specification with heat pump HVAC retrofits and solar PV installation to capture stacked IRA incentives. This integrated procurement model concentrates buying power among national facility management platforms, compressing distributor margins and favoring direct manufacturer relationships for large commercial portfolios.
Thin Insulation Market Segmentation
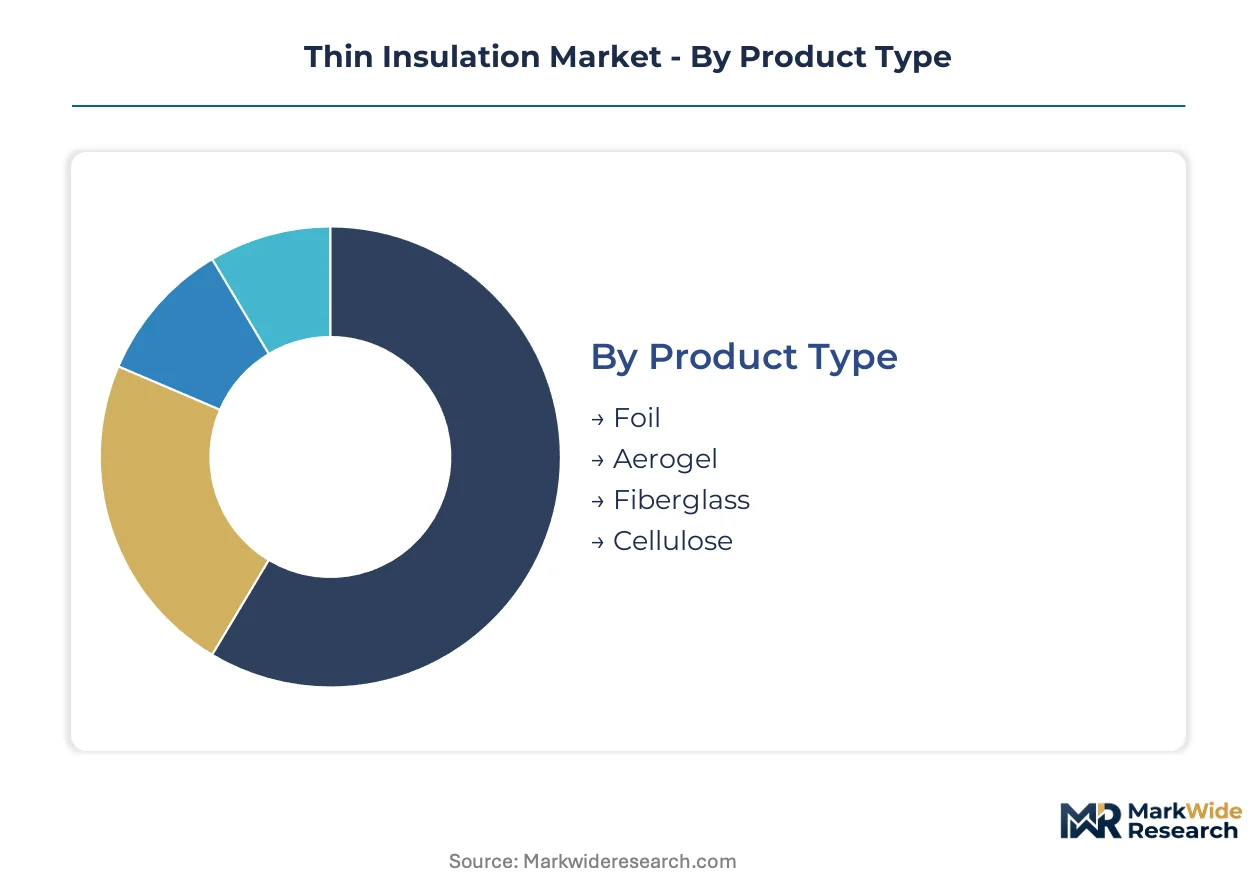
Segmentation in thin insulation reveals divergent supply chain configurations across product categories. Foil and fiberglass products serve mass-market building applications through established domestic distribution networks. Aerogel and vacuum insulation technologies concentrate in export-led aerospace and industrial channels where technical specifications command premium positioning.
Product Type:
Geographic demand patterns split sharply between commodity foils serving regional construction markets and aerogel blankets shipped globally to aerospace tier-one suppliers. Domestic production of fiberglass and cellulose feeds continental building retrofits, while vacuum panels and aerogel cross borders for specialized industrial applications.
- Foil:Multi-layer aluminum-polymer laminates engineered for radiant heat rejection in warm-climate attic assemblies. Demand clusters in US Sun Belt residential construction where cooling load reduction drives specification, constrained by installation labor availability during peak construction seasons.
- Aerogel:Silica-based nanoporous solids delivering thermal resistance at densities below 0.1 g/cm³ for space-constrained envelopes. Japan's METI super-insulation subsidies and German aerospace procurement concentrate global demand, with manufacturing scale-down from semiconductor-grade fabs collapsing unit costs for construction-grade material.
- Fiberglass:Glass fiber mat products dominate North American residential retrofit channels through established contractor distribution networks.
- Cellulose:Recycled paper-based loose-fill and dense-pack materials serve sustainability-focused building projects with lower embodied carbon profiles.
Fiberglass commands the established base. The steepest expansion runs through aerogel as manufacturing scale-down penetrates construction-grade applications.
Application:
Cost tier stratification separates mass-market building retrofits from aerospace and industrial segments where thermal performance per millimeter overrides price sensitivity. Building applications absorb volume at standard margins; aerospace and cryogenic industrial channels capture premium pricing for certified performance.
- Building:Commercial and residential envelope retrofits where floor space constraints or heritage preservation limits insulation depth. EU Green Deal building envelope standards compress installation depths across German and French commercial retrofits, forcing specification shifts toward vacuum insulation panels and aerogel blankets in sub-50mm profiles.
- Aerospace:Satellite thermal protection systems and aircraft cabin insulation where gram-level mass budgets command extreme pricing. German aerospace manufacturers expand procurement of vacuum insulation panels as the EU Green Deal tightens supply chain carbon disclosure requirements.
- Automotive:Electric vehicle battery pack thermal management and cabin comfort systems where space constraints between battery modules limit insulation thickness.
- Industrial:Cryogenic pipe-in-pipe systems and LNG terminal insulation where thermal bridging resistance dominates specification criteria.
Building applications anchor volume throughput. Aerospace and industrial segments gain share fastest as electrification and energy infrastructure expansion accelerate.
Technology:
Customer type determines channel structure: reflective insulation moves through retail and contractor networks to homeowners, while vacuum and spray foam technologies require specification by architects and direct procurement by OEMs. Maturity curves separate decades-old reflective barriers from emerging vacuum panel certification protocols.
- Reflective Insulation:Aluminum-surface radiant barriers for warm-climate residential attics and commercial roof assemblies. US Sun Belt construction markets concentrate demand where cooling load reduction delivers measurable utility savings.
- Vacuum Insulation:Fumed silica or glass fiber cores sealed in metallized polymer films achieving thermal resistance at 20-50mm installed depths. Japan's commercial retrofit sector concentrates procurement where floor-to-ceiling height constraints prohibit conventional insulation, with accelerated aging protocols for service life prediction lacking harmonization between ISO standards and national building codes.
- Radiant Barriers:Single-layer aluminum foil products for attic floor and roof deck applications in residential construction.
- Spray Foam:Polyurethane and polyisocyanurate formulations applied in-situ for complex geometries and air sealing integration.
Reflective insulation maintains the volume base. Vacuum insulation technology climbs the fastest as commercial retrofit constraints tighten across developed markets.
End User:
Supply concentration varies by procurement sophistication: contractors and homeowners access products through distribution, while OEMs and architects engage manufacturers directly for specification and certification support. Margin pools concentrate in architect-specified and OEM-integrated channels.
- Contractors:Residential and commercial insulation installers selecting products based on labor efficiency and code compliance. Installation skill specialization for aerogel blanket cutting and handling requires particulate containment protocols unfamiliar to conventional workforces, constraining deployment velocity.
- OEMs:Original equipment manufacturers in automotive, aerospace, and appliance sectors integrating thin insulation into product designs during development phases. German automotive suppliers and Japanese electronics manufacturers drive specification for vacuum panels and aerogel composites where thermal management integrates with system architecture.
- Architects:Design professionals specifying envelope assemblies for commercial and institutional projects with performance and aesthetic constraints.
- Homeowners:End consumers purchasing reflective insulation and fiberglass products through retail channels for DIY installation.
Contractors and homeowners represent the established demand base. OEM procurement expands most quickly as electrification and thermal management integration deepen across transportation and energy equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Japan and Germany accept substantial price premiums for vacuum insulation panels and aerogel blankets where floor space constraints or aerospace specifications override cost sensitivity. Price-elastic residential retrofits in the United States concentrate demand for commodity reflective foils and fiberglass where contractor labor costs dominate total project economics.
Japan
Commercial building owners in Tokyo and Osaka face severe floor-to-ceiling height limitations that prohibit conventional insulation depths. METI super-insulation subsidies for net-zero office retrofits concentrate procurement of vacuum insulation panels in sub-50mm profiles. Manufacturing clusters in Nagoya and Kobe supply fumed silica cores to domestic VIP fabricators serving the Kanto and Kansai metropolitan corridors.
Germany
Aerospace manufacturers in Bavaria and Baden-Württemberg expand procurement of vacuum insulation panels as the EU Green Deal tightens supply chain carbon disclosure requirements. KBA coordination with France's ANSM accelerates mutual recognition for reformulated insulation materials across EU member states. Industrial clusters around Munich and Stuttgart integrate thin insulation into satellite thermal protection systems where gram-level mass budgets command extreme pricing.
United States
Section 179D commercial efficiency tax credits accelerate payback periods for premium thin insulation in Class A office renovations across the Sun Belt. EPA Energy Star certification programs mandate minimum thermal performance thresholds that expand addressable demand in residential and commercial envelopes. EPC firms in the Northeast bundle thin insulation with heat pump retrofits and solar PV installation to capture stacked IRA incentives.
China
Dual carbon goals and GB standards for building energy efficiency compress installation depths in commercial retrofits across the Yangtze River Delta. MIIT promotes domestic manufacturing of silica aerogel composites for satellite and electric vehicle thermal management applications. Production clusters in Jiangsu and Zhejiang provinces scale continuous sol-gel processing equipment for roll-to-roll aerogel manufacturing.
South Korea
Electric vehicle battery pack thermal management creates specification demand for aerogel blankets where space constraints between modules limit insulation thickness. MFDS building product safety assessments align with ISO standards for vacuum panel service life prediction. Industrial concentration in the Seoul Capital Area and Busan-Ulsan corridor supplies automotive tier-one suppliers integrating thermal management into system architecture.
Thin Insulation Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where premium positioning and commodity scale operate on separate vectors. The vendor base spans integrated chemical conglomerates, specialized aerogel fabricators, and established fiberglass producers with entrenched distribution networks. Three archetypes dominate: diversified materials giants with backward integration into chemical feedstocks, aerogel specialists with semiconductor-grade manufacturing heritage, and construction-focused incumbents with contractor channel capture. Capacity expansion and strategic partnerships represent the dominant competitive moves, with chemical producers securing fumed silica supply agreements and aerogel specialists licensing continuous processing technology.
Among diversified materials conglomerates, BASF SE and Dow Chemical Company exemplify the integrated chemical supply chain archetype that reduces raw material costs for polymeric insulation formulations. Owens Corning occupies a position representing the construction-channel incumbent with established fiberglass infrastructure and residential retrofit distribution networks. Aspen Aerogels sits within the specialist tier, exemplifying the high-performance segment where thermal efficiency per unit thickness commands premium positioning in aerospace and industrial applications.
| Leading Market Players |
|---|
| Cabot Corporation |
| Armacell International S.A. |
| Owens Corning |
| Dow Chemical Company |
| Johns Manville |
| 3M Company |
| BASF SE |
| Kingspan Insulation |
| Aspen Aerogels |
| Others |
Value Chain & Pricing Dynamics
EU REACH substance-of-very-high-concern classifications gate both supplier qualification timelines and price stratification across aerogel and vacuum insulation panel tiers, compressing margins for formulators caught in extended re-registration cycles while rewarding certified incumbents with premium positioning in aerospace and cryogenic channels.
Pricing Analysis
After-sales service contracts for vacuum panel integrity monitoring and aerogel blanket replacement cycles drive lifetime value capture in commercial building portfolios. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-certified aerogel from construction-grade vacuum panels and commodity reflective foils. Pricing pressure stems from fumed silica feedstock volatility as five chemical conglomerates control precipitated silica supply. Contractors and homeowners exhibit highest price sensitivity in residential retrofit channels, while Japanese commercial developers and German aerospace OEMs accept substantial premiums for sub-50mm thermal performance.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg ports constrain just-in-time delivery of metallized polymer films for vacuum panel sealing operations. Manufacturing concentrates in Germany, Japan, and China for aerogel composites and vacuum insulation cores. Raw material dependencies center on fumed silica from Cabot Corporation and precipitated silica from Evonik, plus aluminum foil laminates from rolling mills in South Korea. Single-source vulnerability in semiconductor-grade silica purification creates supply chain risk for aerospace-qualified material. Distribution runs through direct manufacturer relationships with national facility management platforms and specialized insulation distributors serving contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin insulation is approaching a platform-economics inflection where thermal barrier performance converges with active building systems, driven by phase-change material microencapsulation within aerogel matrices that enables thermal mass functionality previously limited to passive insulation.
For Market Incumbents: Shield core margins in fiberglass residential channels by accelerating backward integration into formaldehyde-free binder chemistry ahead of EU REACH enforcement. Prioritize certification investment for vacuum panel accelerated aging protocols harmonized across ISO standards and national building codes to defend against emerging aerogel specialists capturing commercial retrofit specification. For New Entrants and Emerging Players: Anchor in cryogenic industrial expansion across US Gulf Coast LNG terminals where space constraints in pipe-in-pipe systems create specification demand for aerogel blankets with limited incumbent presence. Target automotive battery pack thermal management as the most penetrable segment, leveraging roll-to-roll sol-gel processing partnerships with Jiangsu and Zhejiang production clusters to bypass capital-intensive autoclave infrastructure. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across construction-grade aerogel manufacturing as continuous sol-gel processing displaces batch autoclave curing. Long-term viability favors acquisition targets with demonstrated qualification paths in aerospace or cryogenic certification tiers rather than undifferentiated reflective foil producers. Monitor harmonization progress between ISO vacuum panel aging protocols and national building codes as the signal for commercial retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fumed Silica Supply | Cabot Corporation's precipitated silica concentration creates captive supply advantages for aerogel fabricators facing feedstock volatility. |
| Continuous Sol-gel Processing Scale-Up | Roll-to-roll equipment licensing from Jiangsu clusters collapses unit costs for construction-grade aerogel competing with vacuum panels. |
| Phase-Change Material Microencapsulation R&D | Thermal mass functionality integration enables premium positioning in smart building envelopes previously limited to passive insulation. |
| Direct Procurement Relationships with EPC Firms | Northeast US bundled retrofit projects concentrate buying power, compressing distributor margins and favoring manufacturer-direct channels. |
| EU Green Deal Carbon Disclosure Certification | German aerospace procurement expansion ties supplier qualification to supply chain emissions transparency requirements. |
Study Parameters
The analysis maps aerogel composites, vacuum insulation panels, reflective foil laminates, and fiberglass mat products, each validated through technical directors at insulation formulators, procurement leads at German aerospace tier-one suppliers, EPC contractors in the US Northeast, and commercial facility managers in Tokyo and Osaka. Primary interview findings triangulate against secondary sources including EPA Energy Star certification databases, EU ECHA REACH registration filings, METI subsidy disbursement records, and customs trade data for fumed silica and metallized polymer film imports. Bottom-up product-level volume builds reconcile with top-down construction spending and aerospace procurement forecasts.
Consistency checks validate volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions model product type, application, technology, and end-user procurement sophistication, with regional regulatory framework clusters as an additional industry-specific dimension. CAGRs derive from installed base growth rates, replacement cycle analysis, and penetration assumptions for super-insulation retrofits. Industry-specific forecast inputs include METI subsidy allocation trajectories and EU F-Gas Regulation phase-out schedules for high-GWP blowing agents.
Material uncertainties — silica feedstock price volatility, harmonization delays in vacuum panel certification protocols, and carbon-border adjustment mechanism implementation timelines — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding manufacturing scale-down trajectories and regulatory enforcement intensity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Roofing Underlying Materials Market
Insulation Materials
Global Calcium Silicate Insulation Market
Insulation Materials
Thermal Conductive Polymer Materials Market
Insulation Materials
Fire Resistant Cable Materials Market
Insulation Materials
Asia-Pacific Insulation Materials Market
Insulation Materials
Thermal Tapes Market
Insulation Materials
UK Industrial Insulation Market
Insulation Materials
Low-Frequency Sound-Absorbing Insulation Materials Market
Insulation Materials
Hot Insulation Materials Market
Insulation Materials
Phase Change Thermal Interface Materials Market
Insulation Materials
Japan Industrial Insulation Market
Insulation Materials
North America Industrial Insulation Market
Insulation Materials
Mineral Wool Insulation Market
Insulation Materials
Low Temperature Insulation Materials Market
Insulation Materials
Global Tank Insulation Market
Insulation Materials
Rock Wool Insulation Board Market