
 Ceramic Frit Glass Market | 2026-2036
Ceramic Frit Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Frit Glass Market Outlook
China's frit manufacturing base is reshaping regional supply dynamics for ceramic frit glass. Torrecid Group leverages integrated raw material sourcing across Iberia and Asia to sustain cost competitiveness in container glass coatings. Ferro anchors its position through specialized architectural frit formulations that dominate North American specification channels. Johnson Matthey differentiates via R&D intensity in low-temperature firing systems for electronics-grade substrates.
Ceramic frit glass comprises glass substrates coated with finely ground ceramic particles (frit) that fuse during controlled heat treatment to create durable, decorative, or functional surfaces. The frit layer typically contains silica, alumina, fluxing oxides, and colorants, applied through screen printing, roller coating, or digital deposition before firing at 600–720°C to achieve chemical adhesion and scratch resistance. Flat glass commands the largest volume share as architectural glazing specifications multiply across commercial and residential envelopes, while specialty glass represents the fastest-expanding margin pool due to stringent performance requirements in semiconductor and display applications. Container glass frit demand tracks beverage and cosmetics packaging volumes, with powdered form maintaining dominance in high-throughput manufacturing settings where consistent particle size distribution proves critical.
REACH registration requirements in Europe and EPA emissions protocols in the United States constrain heavy-metal pigment formulations, redirecting R&D investment toward cadmium-free and lead-free colorant systems. China's GB standards for building glass energy performance, enforced by SAMR conformity assessment procedures, mandate minimum thermal properties that frit-coated products must satisfy for project approval. Stakeholders must monitor evolving chemical restriction schedules across major economies while calibrating product portfolios toward compliant pigment technologies and digital decoration platforms that reduce material waste.
Market Dynamics
China's domestic frit manufacturing capacity is redrawing supply geography as energy-efficiency mandates across multiple jurisdictions force architectural specification upgrades toward low-emissivity formulations.
Growth Catalysts
- REACH cadmium restrictions:European chemical registration protocols are redirecting R&D investment toward heavy-metal-free pigment systems that command specification premiums in commercial facades.
- Photovoltaic integration:Solar-control frit layers on building envelopes are gaining traction as integrated BIPV systems multiply across commercial construction pipelines.
- Shanghai construction volume:Urban development density in China's Yangtze River Delta is concentrating demand for high-performance architectural glazing with functional ceramic coatings.
Market Restraints
- Fluxing oxide volatility:Borate and lithium carbonate input costs fluctuate with battery-sector competition for finite mineral supply.
- Hebei supplier concentration:Northern China's frit production cluster creates single-source exposure for container glass coating supply chains.
- Firing temperature floor:Substrate thermal limits prevent ceramic frit adoption in temperature-sensitive polymer glazing systems.
Strategic Opportunities
- Indian building code alignment:Bureau of Indian Standards energy performance mandates for commercial envelopes are opening specification channels for solar-control frit imports.
- Digital inkjet deposition:Drop-on-demand ceramic printing is converging with architectural glass fabrication to enable mass-customization of facade patterns without screen-changeover downtime.
- US Inflation Reduction Act:Commercial building efficiency tax credits are accelerating retrofit demand for low-emissivity frit retrofits on existing curtain wall stock.
Industry Challenges
- Color matching precision:Batch-to-batch frit consistency requirements strain quality control systems in high-throughput roller coating operations.
- SAMR conformity timelines:China's market regulator certification procedures for building glass thermal performance create project approval bottlenecks for imported frit formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Frit Glass Market |
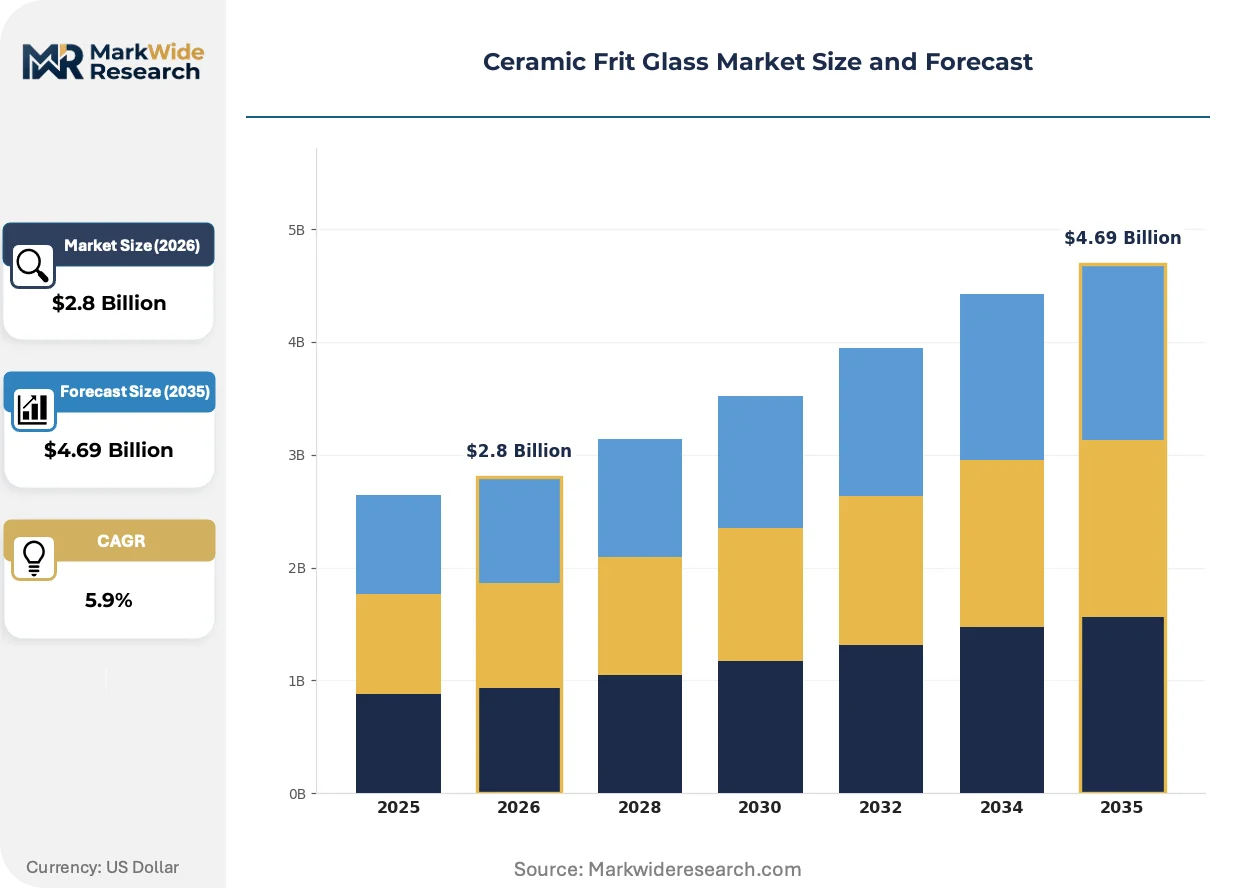
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.69 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Glass, Container Glass, Tableware, Specialty Glass Application: Architecture, Automotive, Electronics, Ceramics End User: Manufacturers, Retailers, Distributors, Artisans Form: Powdered, Granulated, Flaked, Coated |
| Companies Covered | Torrecid Group, Johnson Matthey, Ferro, Vibrantz Technologies, QuimiCer, Colorobbia, TOMATEC, Fenzi Group, Esmalglass-Itaca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Frit Glass Market Strategic Shifts
Digital decoration platforms and heavy-metal-free pigment chemistry are compressing traditional manufacturing workflows while expanding design latitude for architectural specification.
Digital inkjet deposition of ceramic frit suspensions is migrating from prototype architectural installations to volume facade production. Specifying architects in North American commercial towers are specifying pixel-scale pattern variation for branding differentiation. This technology is migrating from screen-printing dominance toward inkjet primacy by eliminating mesh inventory and enabling just-in-time pattern changes without production line reconfiguration.
EPA emissions protocols for glass manufacturing are tightening volatile organic compound thresholds in Midwest and Southeast production zones. Furnace operators are retrofitting regenerative thermal oxidizers to maintain Title V permit compliance. Container glass coating lines in Ohio and Pennsylvania are most affected, with frit suppliers reformulating organic vehicle systems to reduce solvent loading.
Specification-driven procurement now requires third-party thermal performance certification before project approval. Commercial glazing contractors in California and New York are demanding SAMR-equivalent test documentation for imported frit products. This behavioral shift is most visible in municipal and institutional building segments where public funding triggers enhanced compliance scrutiny.
Ceramic Frit Glass Market Segmentation
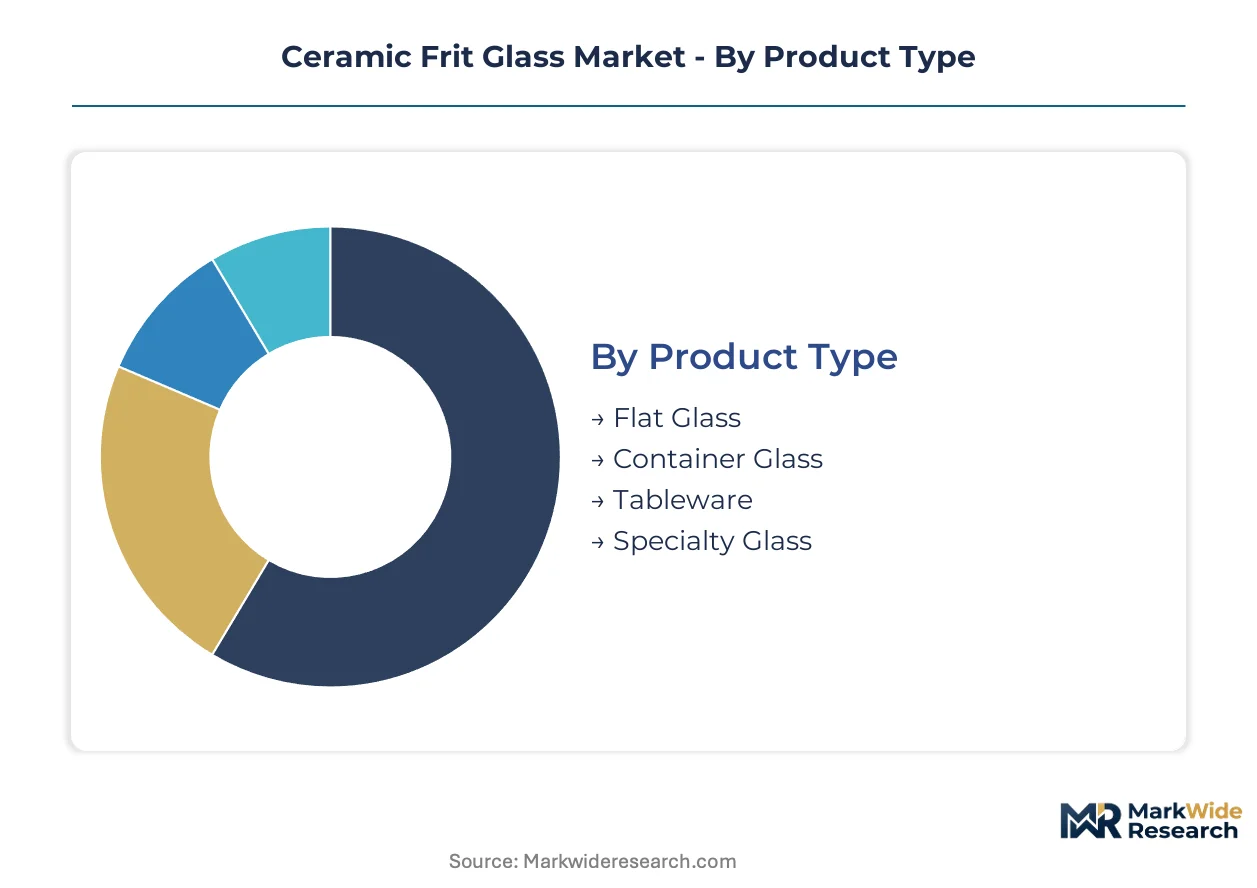
Ceramic frit glass segmentation reflects divergent technical requirements across architectural scale and precision electronics. Product form and substrate compatibility determine manufacturing investment and margin structure.
Product Type:
Maturity varies sharply across this dimension, with commodity substrates competing against emerging high-value categories.
- Flat Glass:Architectural glazing substrates dominate volume through curtain wall and facade specifications. Demand concentrates in China's Yangtze River Delta construction clusters as GB energy performance standards mandate solar-control coatings.
- Specialty Glass:Semiconductor and display-grade substrates require ultra-low particle contamination and precise thermal expansion matching. Electronics fabricators in South Korea and Taiwan are driving specification intensity for low-temperature firing formulations.
- Container Glass:Beverage and cosmetics packaging coatings track CPG volume cycles with standardized color palettes.
- Tableware:Decorative dinnerware applications serve hospitality procurement and consumer gift segments with seasonal demand patterns.
Flat glass handles the majority of throughput; specialty glass is the fastest mover on share.
Application:
End-use concentration shapes R&D allocation across thermal performance and aesthetic customization.
- Architecture:Commercial envelope specifications drive low-emissivity and solar-control frit adoption. US Inflation Reduction Act efficiency tax credits are accelerating retrofit demand across existing curtain wall stock.
- Electronics:Display substrates and semiconductor packaging require sub-micron frit deposition precision. Japanese and South Korean panel manufacturers are qualifying next-generation inkjet deposition systems for mass production.
- Automotive:Windshield and glazing applications prioritize impact resistance and optical clarity under ECE R43 regulations.
- Ceramics:Traditional pottery and tile decoration maintains steady demand through artisan and industrial channels.
Architecture commands the dominant revenue position; electronics is climbing the fastest on specification value.
End User:
Customer type determines order scale, technical service intensity, and pricing leverage.
- Manufacturers:Glass fabricators and coating line operators purchase bulk frit under annual contracts with volume-tier pricing. Chinese domestic producers are consolidating procurement through direct mill relationships.
- Distributors:Regional stocking intermediaries serve mid-scale fabricators with fragmented color-matching requirements.
- Retailers:Hobby and craft supply channels move small-batch decorative frits with premium unit economics.
- Artisans:Studio glassworkers and ceramicists drive niche demand for custom color formulations.
Manufacturers absorb the largest volume share; distributors are expanding most quickly as specification complexity fragments direct procurement.
Form:
Physical state dictates application equipment compatibility and supply chain logistics.
- Powdered:Screen printing and roller coating operations rely on tightly controlled particle size distribution for consistent deposition thickness. High-throughput architectural lines in Hebei and Shandong provinces specify this form exclusively.
- Granulated:Container glass coating lines favor free-flowing granules for automated dispensing systems.
- Flaked:Specialty decorative applications leverage metallic flake geometry for optical effects.
- Coated:Pre-treated frit particles reduce organic vehicle requirements and emissions compliance burden.
Powdered form maintains the dominant production position; coated variants are gaining share fastest under EPA emissions tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Architectural specification patterns diverge sharply across consumption centers. China deploys ceramic frit glass predominantly in high-rise commercial envelopes under mandatory energy codes, while European markets prioritize renovation retrofits and North American demand concentrates on institutional efficiency upgrades.
China
Urban construction density in the Yangtze River Delta and Pearl River Delta drives specification volume for solar-control frit formulations. SAMR conformity assessment procedures for GB standards enforce thermal performance minimums that imported products must satisfy. Hebei and Shandong provinces host concentrated frit manufacturing clusters supplying domestic glass fabricators.
United States
Commercial building retrofit activity accelerates demand for low-emissivity frit upgrades on existing curtain wall stock. EPA Title V permit requirements constrain organic vehicle formulations in Ohio and Pennsylvania coating lines. Midwest and Southeast production zones face tightening volatile organic compound thresholds under regional emissions protocols.
Germany
Facade renovation cycles in commercial building stock sustain specification demand for heavy-metal-free pigment systems. REACH cadmium restrictions redirect procurement toward compliant colorant technologies. Industrial glass fabrication concentrates in North Rhine-Westphalia and Bavaria, serving Central European export markets.
India
Bureau of Indian Standards energy performance mandates for commercial envelopes open specification channels for imported solar-control frit. CDSCO and BIS alignment procedures create compliance pathways for foreign suppliers. Construction activity concentrates in Maharashtra and Gujarat, with Delhi-NCR emerging as a secondary demand node.
South Korea
Electronics-grade substrate demand from display panel manufacturers drives specification intensity for low-temperature firing formulations. MFDS and METI-aligned quality protocols govern material purity requirements. Fabrication clusters in Gyeonggi-do and Chungcheong provinces serve Samsung and LG supply chains.
Ceramic Frit Glass Market Competitive Environment
Capability concentration sits with specialized formulation developers; scale advantage sits with integrated raw material processors. The market structures around three tiers: multinational chemical conglomerates with architectural specification relationships, regional frit specialists serving container glass and tableware segments, and electronics-focused developers of precision deposition systems. Consolidation pressure operates through backward integration into mineral sourcing and forward integration into digital printing platform partnerships.
Among Iberia-based integrated suppliers, Torrecid Group exemplifies the raw-material-anchored archetype through captive sourcing networks. Ferro Corporation occupies a position in specialized architectural formulations with established North American specification channels. Johnson Matthey represents the R&D-intensive tier focused on electronics-grade substrate applications. These three anchors illustrate divergent competitive vectors: mineral security, specification relationships, and precision manufacturing technology.
| Leading Market Players |
|---|
| Torrecid Group |
| Johnson Matthey |
| Ferro |
| Vibrantz Technologies |
| QuimiCer |
| Colorobbia |
| TOMATEC |
| Fenzi Group |
| Esmalglass-Itaca |
| Others |
Value Chain & Pricing Dynamics
Hebei and Shandong provinces concentrate China's frit manufacturing capacity, anchoring cost structures for architectural glazing supply chains while premium margin pools accumulate with European heavy-metal-free pigment specialists serving specification-driven facade projects.
Pricing Analysis
Long-term offtake contracts dominate procurement between Chinese frit mills and domestic glass fabricators, insulating volume buyers from lithium carbonate and borate volatility that strains spot-market participants. Price differentiation hinges on SAMR thermal certification tier and color-matching precision grade, with municipal project contractors least sensitive due to public-funding compliance mandates and mid-scale distributors most exposed to cost compression. Pricing pressure stems from battery-sector competition for finite mineral feedstocks, squeezing margins in standard-grade architectural formulations while solar-control and low-emissivity specialty tiers retain pricing power.
Supply Chain Analysis
Tariff exposure between China and North American specification channels dominates supply chain risk planning for architectural frit distributors. Manufacturing concentrates in China, Germany, and Spain, with raw material dependencies spanning Australian zircon, Chilean lithium, and Turkish boron. Single-source vulnerability runs through Hebei's container glass coating cluster, where concentrated output creates disruption exposure for beverage packaging lines. Distribution runs through direct mill relationships for high-volume fabricators and regional stocking intermediaries for fragmented color-matching demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digitally printed glass and thin-film photovoltaic laminates threaten substitution for conventional ceramic frit in commercial facades, forcing incumbent suppliers to defend specification relationships through performance differentiation.
For Market Incumbents: Insulate market position by deepening backward integration into lithium and zircon sourcing to offset battery-sector feedstock competition, while accelerating SAMR-equivalent certification investments for North American and European specification channels threatened by inkjet deposition technology migration. Prioritize R&D allocation toward low-temperature firing systems that exclude polymer glazing substitutes from electronics-grade applications. For New Entrants and Emerging Players: Mid-market commercial buildings in India's Maharashtra and Gujarat construction corridors represent the most penetrable entry point, with Bureau of Indian Standards energy code alignment creating first-mover advantage for solar-control frit imports. Digital decoration platform partnerships offer the strongest go-to-market angle, bypassing screen-printing capital requirements while serving architect demand for mass-customized facade patterns. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European pigment specialists holding REACH-compliant formulation libraries but lacking Asian distribution infrastructure. Five-to-ten-year viability favors acquisition targets with captive mineral sourcing and digital printing partnerships rather than legacy screen-printing equipment bases. The signal to watch is SAMR certification timeline acceleration for imported formulations, which would compress margin capture windows for non-compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Feedstocks | Battery-sector competition for Chilean and Australian lithium carbonate is forcing frit manufacturers to secure captive mineral supply. |
| Digital Inkjet Deposition Partnership | Architectural specification is migrating from screen printing toward drop-on-demand ceramic printing for pattern customization. |
| SAMR-Equivalent Certification Investment | Chinese thermal performance standards enforced by SAMR create compliance barriers for imported frit products. |
| Heavy-Metal-Free Pigment R&D Expansion | REACH cadmium restrictions redirect procurement toward compliant colorant technologies commanding specification premiums. |
| Container Glass Coating Line Modernization | EPA Title V permit requirements in Ohio and Pennsylvania are forcing organic vehicle reformulation investments. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with glass fabricator procurement directors, frit mill technical managers, architectural specification consultants, and container glass coating line supervisors. Secondary validation drew from SAMR conformity assessment databases, EPA Title V permit filings, customs trade flow records, and GB standard enforcement bulletins. Bottom-up volume estimates triangulated against top-down construction spending and glass production capacity data.
Calibration anchored volume projections to verified installation rates across the analysis window, with segmentation modeling across flat glass, specialty glass, and container glass substrates by application architecture, electronics, and automotive end-uses. CAGRs were derived from slope analysis of annual demand trajectories, incorporating photovoltaic integration rates, building code enforcement intensity, and digital decoration adoption curves as industry-specific forecast inputs.
Practitioners should monitor lithium carbonate spot price volatility, SAMR certification timeline shifts, and inkjet deposition technology cost curves for early signals of forecast revision. Forecasts reflect assumptions about mineral supply continuity, regulatory enforcement consistency, and substitution technology penetration rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Global High Performance Ceramic Coatings Market
Ceramics
Hot-Pressed Aluminum Titanate Ceramics Market
Ceramics
Feldspar and Nepheline Syenite Market
Ceramics
Carbon-Ceramic Discs Market
Ceramics
Earthenware Market
Ceramics
Aluminium Nitride Market
Ceramics
Brazil Ceramic Tiles Market
Ceramics
Mexico Ceramic Tiles Market
Ceramics
Ceramic Additives Market
Ceramics
Magnesia Carbon Bricks Market
Ceramics
Colloidal Alumina Market
Ceramics
Thailand Ceramic Tiles Market
Ceramics
Medical Ceramics Market
Ceramics
Global Alumina Trihydrate Market
Ceramics
High Temperature Ceramics Market
Ceramics
Calcium Oxide Market