
 EV Adhesives Market | 2026-2036
EV Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
EV Adhesives Market Foresight
Automotive-grade thermal management specifications are redrawing competitive boundaries in EV adhesives. Henkel AG & Co. KGaA leverages its European formulation heritage to dominate battery module bonding applications. 3M sustains technology leadership through fluoropolymer barrier expertise in cell encapsulation. Sika AG anchors its position with polyurethane structural systems tailored to OEM crashworthiness protocols.
EV adhesives comprise engineered polymer systems formulated for dielectric strength, thermal conductivity, and vibration damping in electrified vehicle architectures. These materials typically deliver shear strengths exceeding 15 MPa while maintaining operational stability across temperatures from minus 40 to 150 degrees Celsius, primarily serving to replace mechanical fasteners and enable multi-material vehicle construction. Structural adhesives command the deepest margin pools as OEMs prioritize crash-resistant battery enclosure designs, while epoxy formulations represent the fastest-expanding technology segment due to their superior chemical resistance and curing profiles for automated assembly lines. Application demand concentrates in battery systems where thermal runaway protection and cell-to-pack structural integrity have become non-negotiable design parameters.
REACH compliance in Europe, EPA toxicity guidelines in the United States, and China's GB standards for automotive materials collectively dictate formulation chemistry and market access pathways for adhesive suppliers. The EU Battery Regulation's carbon footprint disclosure requirements are forcing reformulation investments across the supplier base. Stakeholders must monitor how solid-state battery architectures reshape thermal interface and structural bonding requirements as cell chemistry evolves.
Market Dynamics
Battery pack thermal runaway protection mandates are forcing OEMs to replace mechanical fasteners with structural adhesive bonding systems, compressing assembly timelines while elevating dielectric and flame-retardant performance thresholds.
Growth Catalysts
- EU Battery Regulation carbon footprint disclosure:Tier-1 suppliers must document embodied carbon in cell-to-pack bonding materials, accelerating thermosetting epoxy qualification programs across German and French automotive corridors.
- Cell-to-pack architecture migration:Elimination of module housings concentrates structural loads directly on adhesive joints, expanding bonding surface area per vehicle by 40-60% versus conventional designs.
- China's NEV subsidy framework:Domestic OEMs must achieve 300+ kilometer range thresholds to qualify for purchase incentives, driving lightweighting investments that favor aluminum-steel dissimilar bonding with polyurethane systems.
Market Restraints
- Petrochemical feedstock volatility:Epoxy resin prices fluctuate with bisphenol-A and epichlorohydrin spot markets, squeezing formulation margins for mid-tier adhesive suppliers without captive chemical production.
- East Asian specialty chemical concentration:70%+ of high-purity anhydride curing agents originate from Japanese and South Korean chemical conglomerates, creating single-source vulnerability for European formulators.
- Fluoropolymer barrier film substitution:Cell encapsulation applications face displacement risk from laser-welded metal-polymer hybrid seals that eliminate adhesive layers entirely in prismatic cell designs.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cell manufacturing:Greenfield battery gigafactories in Gujarat and Tamil Nadu lack qualified domestic adhesive suppliers, opening technical partnership entry points for established European formulators.
- Solid-state battery interface engineering:Ceramic electrolyte-to-current collector bonding requires novel silane-modified polymer chemistries that reset competitive positioning away from incumbent liquid-cell expertise.
- Direct-to-OEM digital specification platforms:Cloud-based adhesive selection tools bypass traditional distributor networks, enabling technical sales teams to embed formulation recommendations into early-stage vehicle platform design cycles.
Industry Challenges
- Automotive electrification polymer chemist scarcity:Formulation laboratories compete for talent possessing combined expertise in dielectric materials science and high-volume manufacturing process engineering.
- UN 38.3 lithium battery transport certification:Adhesive suppliers must validate that bonded pack designs survive altitude simulation and thermal cycling tests, extending qualification timelines by 12-18 months.
- Legacy paint shop thermal compatibility:Structural adhesives must withstand e-coat bake cycles exceeding 180 degrees Celsius without degradation, limiting candidate polymer families and requiring OEM process resequencing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Adhesives Market |
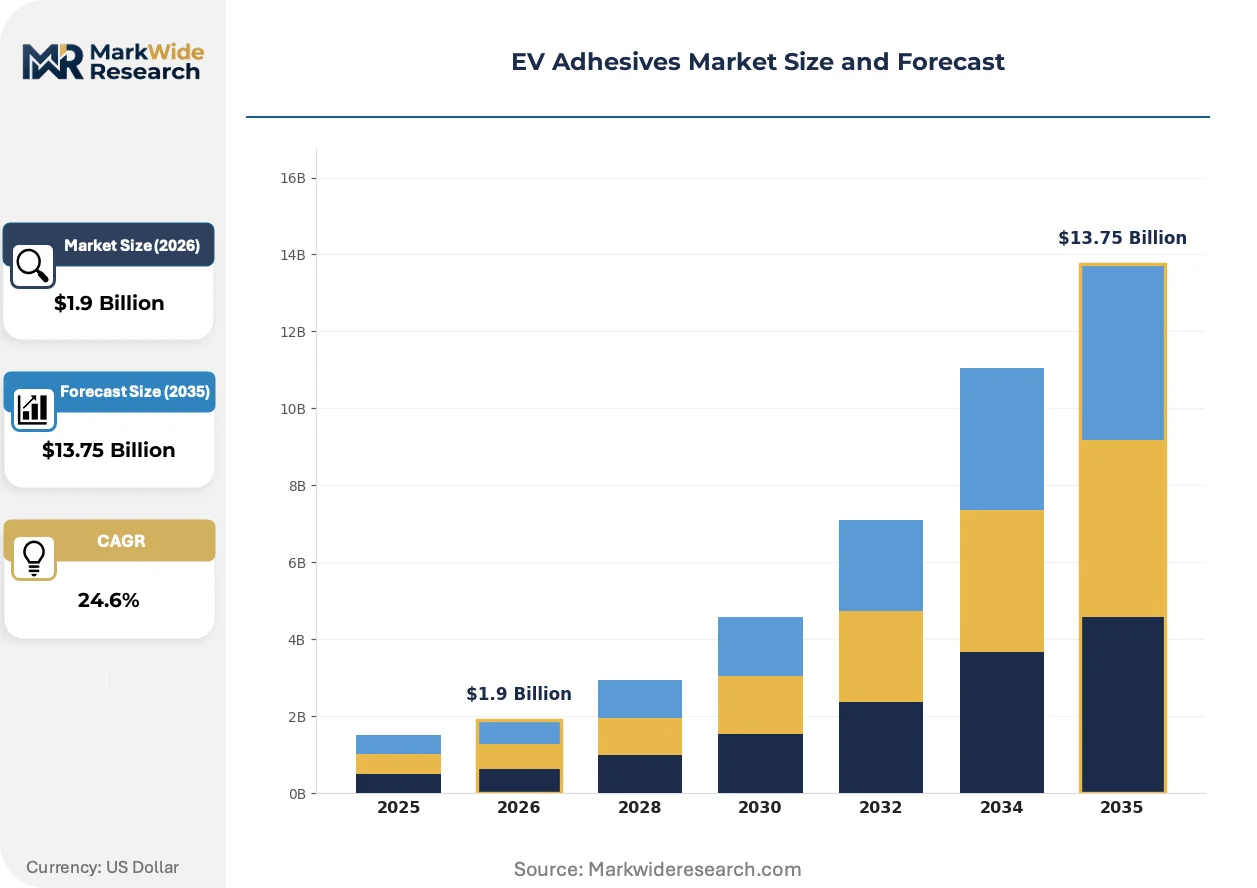
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $13.75 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural Adhesives, Sealants, Coatings, Assembly Adhesives End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Component Manufacturers Technology: Thermosetting, Thermoplastic, Epoxy, Polyurethane Application: Batteries, Chassis, Interior, Exterior |
| Companies Covered | Henkel AG & Co. KGaA, 3M, Sika AG, H.B. Fuller, Wacker Chemie AG, Arkema S.A., Dow Inc., PPG Industries, Illinois Tool Works Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Adhesives Market Shifts & Advancements
Adhesive functionality is bifurcating into dual-purpose systems that simultaneously manage thermal interface resistance and structural load transfer, collapsing previously separate material categories into unified specification sheets.
Two-part thermally conductive acrylics are miniaturizing thermal interface gap tolerances in cell-to-cell bonding applications. Korean battery manufacturers specify these materials for 4680 cylindrical cell formats where compression-set resistance must survive 10+ year vehicle lifecycles. The technology is miniaturizing heat spreader component counts by integrating thermal conductivity directly into structural joints.
REACH Annex XIV authorization requirements for diisocyanates are forcing polyurethane formulators to invest in aliphatic isocyanate alternatives or closed-loop handling systems. Industrial consequence includes 15-25% raw material cost elevation for European production facilities. German OEMs are responding by consolidating adhesive specifications to fewer qualified suppliers capable of absorbing compliance infrastructure investments.
Cell manufacturer procurement teams now mandate full supply chain disclosure for adhesive raw materials extending three tiers upstream. Tier-1 battery integrators are displacing traditional component distributors with direct technical partnerships holding ISO 14001 environmental management certification. This pattern concentrates most visibly in Sweden's Northvolt supplier ecosystem and Tesla's Nevada-Panasonic joint venture operations.
EV Adhesives Market Segmentation
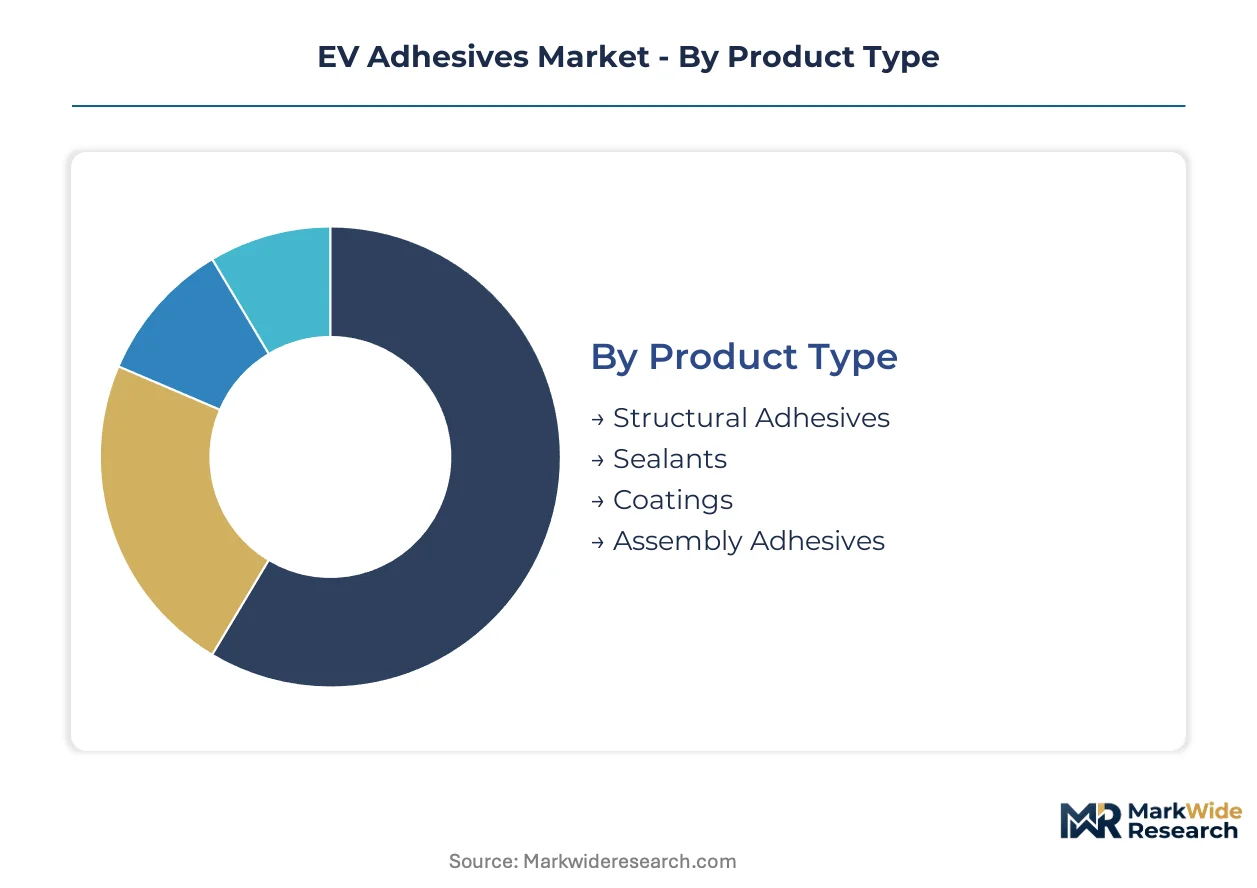
Adhesive specification in electrified vehicles diverges sharply by functional load and thermal exposure. Each segment category carries distinct qualification protocols, supply chain configurations, and margin structures that reshape competitive positioning across the value chain.
Product Type:
REACH Annex XIV authorization timelines for diisocyanates and ECHA substance of very high concern listings force reformulation roadmaps that split margin profiles across product families.
- Structural Adhesives:High-modulus thermosetting systems delivering shear strengths above 15 MPa for crash-resistant battery enclosure bonding. Demand concentrates in Germany's automotive corridor where KBA crashworthiness protocols mandate structural integrity validation for cell-to-pack architectures.
- Sealants:Elastomeric formulations providing environmental sealing and acoustic damping across multi-material body-in-white joints. European OEMs specify these for aluminum-steel dissimilar bonding to meet EU CO2 fleet targets through mass reduction.
- Coatings:Dielectric barrier films applied to cell terminals and busbar interfaces. Chinese GB standards for automotive materials drive qualification complexity for foreign suppliers entering domestic NEV supply chains.
- Assembly Adhesives:Lower-strength bonding agents for non-structural interior component fixation. Aftermarket refurbishment channels in North America absorb volume for collision repair and battery pack reconditioning.
Structural adhesives handle the majority of throughput; sealants are the fastest mover on share.
End User:
Procurement authority is shifting toward battery manufacturers as cell-to-pack architectures collapse traditional Tier-1 integration roles.
- OEMs:Direct adhesive specification for platform-level programs, particularly in Sweden where Northvolt's supplier ecosystem mandates ISO 14001 environmental management certification from all bonding material providers.
- Tier-1 Suppliers:Battery integrators and module assemblers managing qualification timelines and UN 38.3 transport certification for bonded pack designs. These stakeholders face 12-18 month validation cycles for new adhesive formulations.
- Aftermarket Providers:Collision repair networks and battery refurbishment specialists sourcing compatible bonding systems for pack disassembly and reassembly. EPA toxicity guidelines constrain available chemistries in US service channels.
- Component Manufacturers:Cell producers and thermal management subsystem suppliers specifying interface materials. Korean manufacturers of 4680 cylindrical cells drive demand for compression-set resistant acrylic formulations.
Tier-1 suppliers manage the deepest qualification pipelines; OEM direct procurement is expanding most quickly.
Technology:
Automated assembly line throughput requirements favor curing profiles that match takt time constraints without sacrificing bondline integrity.
- Thermosetting:Cross-linked polymer networks providing irreversible chemical bonds with superior chemical resistance. EU Battery Regulation carbon footprint disclosure requirements accelerate epoxy qualification programs across French and German automotive corridors.
- Thermoplastic:Reversible bonding systems enabling end-of-life disassembly and material recovery. These formulations gain traction where China's dual carbon goals incentivize circular economy compliance.
- Epoxy:Two-part systems with tunable viscosity and thermal conductivity for thermal interface applications. Japanese chemical conglomerates dominate high-purity anhydride curing agent supply, creating concentration risk for European formulators.
- Polyurethane:Flexible structural systems optimized for aluminum-steel dissimilar bonding and vibration damping. REACH diisocyanate restrictions elevate raw material costs 15-25% for European production facilities.
Thermosetting platforms carry the heaviest R&D investment; thermoplastic alternatives are gaining share fastest.
Application:
Thermal runaway protection mandates are redrawing specification boundaries between structural and functional bonding requirements.
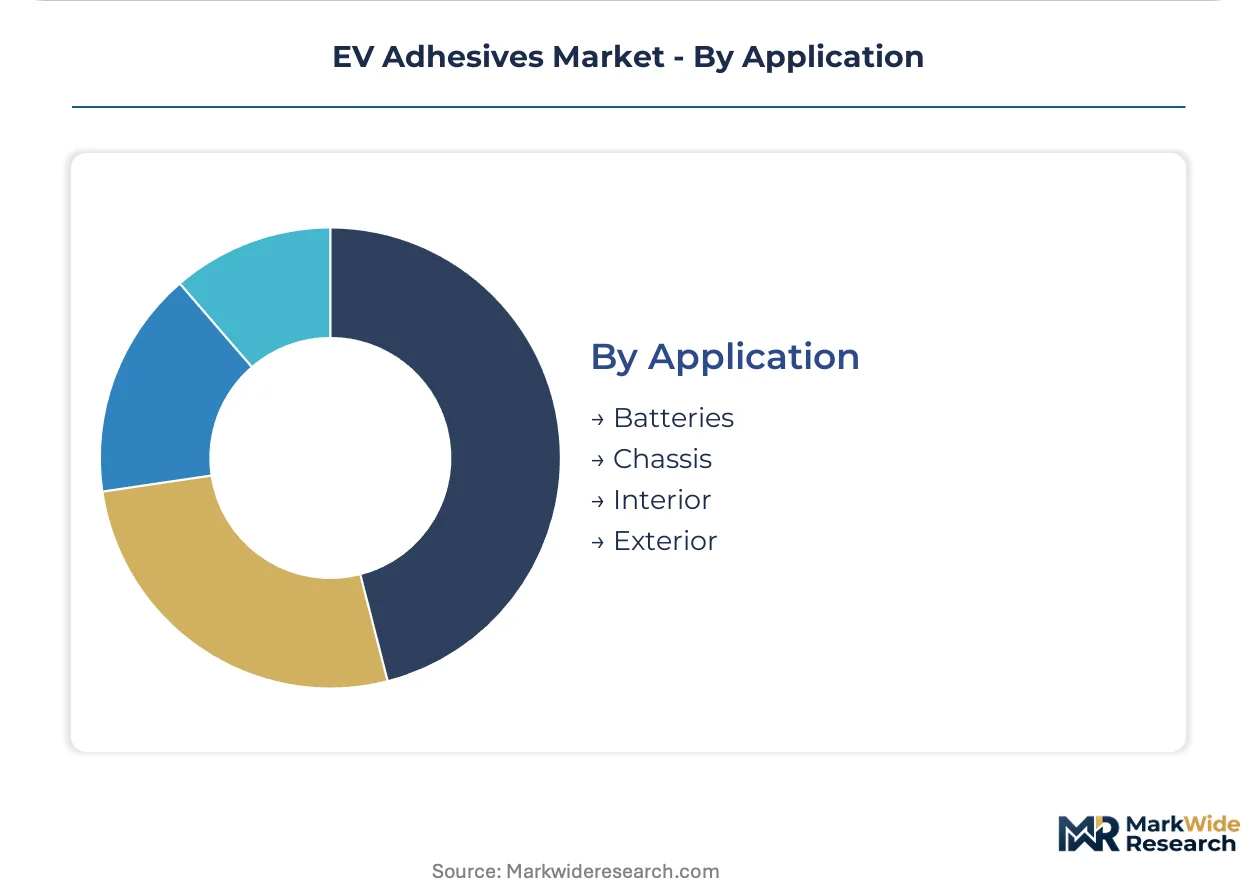
- Batteries:Cell-to-cell, cell-to-pack, and module-to-housing bonding with dielectric strength and flame-retardant performance. India's PLI scheme for advanced chemistry cell manufacturing opens technical partnership entry points for established European adhesive suppliers.
- Chassis:Multi-material structural joints replacing welded connections for mass reduction. Tesla's Nevada-Panasonic joint venture operations specify these systems for aluminum-intensive platform architectures.
- Interior:Acoustic damping and trim attachment with low-VOC emissions. Japanese OEMs drive specification through JIS standards for cabin air quality.
- Exterior:Panel bonding and sealing exposed to environmental degradation. E-coat bake cycle compatibility above 180 degrees Celsius limits viable polymer families.
Battery applications command the steepest specification thresholds; chassis bonding is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese and South Korean chemical conglomerates control over 70 percent of high-purity anhydride curing agents, forcing European formulators into single-source dependencies while Chinese NEV subsidies and EU carbon regulations reshape demand geography.
China
MIIT range mandates for NEV purchase incentives require 300-plus kilometer thresholds, compelling domestic OEMs toward aluminum-steel dissimilar bonding with polyurethane systems. GB standards for automotive materials create qualification barriers for foreign adhesive suppliers entering domestic supply chains. Battery gigafactories in Guangdong and Jiangsu provinces anchor cell-to-pack assembly lines specifying thermally conductive epoxy formulations.
Germany
KBA crashworthiness protocols mandate structural integrity validation for cell-to-pack architectures, concentrating thermosetting epoxy demand in Baden-Württemberg and Bavaria automotive corridors. REACH Annex XIV diisocyanate authorizations force polyurethane formulators into aliphatic isocyanate alternatives. Tier-1 suppliers in Stuttgart and Munich anchor next-generation EV platform programs with 12-18 month adhesive qualification cycles.
United States
EPA toxicity guidelines constrain available chemistries in aftermarket service channels while IRA domestic content provisions incentivize localized adhesive formulation. Tesla's Nevada-Panasonic joint venture operations specify structural systems for aluminum-intensive platform architectures. Midwest battery cell manufacturing investments in Michigan and Ohio lack qualified domestic adhesive suppliers, opening technical partnership entry points.
South Korea
METI-aligned battery manufacturers specify two-part thermally conductive acrylics for 4680 cylindrical cell formats requiring 10-plus year compression-set resistance. Domestic chemical conglomerates dominate high-purity anhydride curing agent supply, creating captive feedstock advantages for Korean formulators. Busan-Ulsan industrial clusters anchor cell-to-cell bonding specification development for next-generation thermal interface applications.
India
PLI scheme incentives for advanced chemistry cell manufacturing in Gujarat and Tamil Nadu lack qualified domestic adhesive suppliers, creating greenfield technical partnership opportunities. BIS automotive material standards are converging toward EU-equivalent dielectric and flame-retardant thresholds. Battery gigafactory investments in the Delhi-Mumbai industrial corridor specify structural bonding systems for initial production ramps.
EV Adhesives Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with European heritage formulators dominating qualification-intensive battery applications while Asian chemical conglomerates anchor feedstock supply. The market structure splits across three tiers: multinational diversified chemical giants with captive resin production, mid-cap adhesive specialists with OEM-direct specification relationships, and regional formulators serving aftermarket refurbishment channels. Consolidation pressure concentrates among mid-tier suppliers lacking backward integration into petrochemical feedstocks. Dominant competitive moves include strategic partnerships with battery cell manufacturers for co-development programs and geographic expansion into India's PLI-subsidized manufacturing zones.
Among European heritage formulators, Henkel AG & Co. KGaA and Sika AG occupy positions exemplifying the OEM-direct specification archetype, anchoring platform-level program relationships through crashworthiness protocol validation. 3M represents the diversified technology conglomerate tier, with fluoropolymer expertise translating into cell encapsulation positioning. These three companies illustrate how formulation heritage, regulatory compliance infrastructure, and thermal management specification depth collectively determine competitive standing in electrified vehicle architectures.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M |
| Sika AG |
| H.B. Fuller |
| Wacker Chemie AG |
| Arkema S.A. |
| Dow Inc. |
| PPG Industries |
| Illinois Tool Works Inc. |
| Others |
Supply & Pricing Matrix
Mechanical fastener substitution by structural adhesive bonding simultaneously redistributes supply geography toward German and Chinese automotive corridors while compressing margin pools for mid-tier formulators lacking captive resin production. This displacement dynamic concentrates pricing power among European heritage suppliers with REACH compliance infrastructure and Asian chemical conglomerates controlling anhydride curing agent supply.
Pricing Analysis
EU Battery Regulation carbon footprint disclosure dictates the pricing tier structure across European automotive supply chains. Three-tier pricing structure across premium, standard, and economy levels separates ISO 14001-certified formulators from qualified but uncertified suppliers and commodity aftermarket providers. Cost compression in standard-tier epoxy formulations is intensifying because bisphenol-A and epichlorohydrin spot market volatility squeezes non-integrated suppliers. Aftermarket refurbishment channels exhibit highest price sensitivity due to EPA toxicity guideline constraints on available chemistries, while OEM direct procurement demonstrates lowest sensitivity given crashworthiness protocol non-negotiability.
Supply Chain Analysis
Just-in-time inventory strategies dominate European automotive corridors where 12-18 month adhesive qualification cycles preclude speculative stockpiling, while Korean battery manufacturers maintain strategic reserves of high-purity anhydride curing agents sourced from domestic chemical conglomerates. Geographic supply concentration centers on Japan and South Korea for curing agents, Germany for formulated systems, and China for NEV platform integration. Raw material dependencies rest on petrochemical feedstocks, specialty isocyanates, and ceramic filler materials. Single-source vulnerability for European formulators creates structural supply chain risk. Distribution runs through Tier-1 battery integrators consolidating procurement authority away from traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell-to-pack architecture migration transforms adhesive specification into a platform-economics inflection where battery manufacturer procurement ecosystems displace traditional automotive supplier hierarchies. Northvolt's supplier ecosystem exemplifies this interoperability shift through ISO 14001 environmental management certification mandates that reset competitive access rules.
For Market Incumbents: Secure backward integration into anhydride curing agent supply or captive epichlorohydrin production to defend against Japanese and South Korean chemical conglomerate feedstock leverage. Consolidate formulation laboratories in Baden-Württemberg and Bavaria to absorb REACH Annex XIV diisocyanate compliance infrastructure investments, while embedding technical sales teams into early-stage OEM platform design cycles through cloud-based specification tools.
For New Entrants and Emerging Players: UN 38.3 lithium battery transport certification fast-track programs open technical partnership entry points in India's PLI-subsidized Gujarat and Tamil Nadu battery gigafactories where qualified domestic adhesive suppliers remain absent. Target solid-state battery interface engineering applications requiring novel silane-modified polymer chemistries that reset competitive positioning away from incumbent liquid-cell expertise. Pursue direct-to-OEM digital specification platform strategies bypassing traditional distributor networks.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-cap adhesive specialists possessing OEM-direct specification relationships but lacking backward integration into petrochemical feedstocks. Five-to-ten year viability hinges on consolidation plays that combine formulation heritage with carbon footprint disclosure compliance infrastructure. Watch for solid-state battery architecture commercialization timelines as inflection indicator for thermal interface and structural bonding requirement resets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Curing Agent Supply | Mitigates single-source dependency on Japanese and South Korean chemical conglomerates for European formulators. |
| REACH Annex XIV Compliance Infrastructure Investment | Enables continued polyurethane system supply to German OEMs facing diisocyanate authorization restrictions. |
| Direct-to-OEM Digital Specification Platform Launch | Bypasses traditional distributor networks to embed formulation recommendations into early-stage vehicle platform design cycles. |
| Technical Partnership in India's PLI-Subsidized Zones | Captures greenfield battery gigafactory demand in Gujarat and Tamil Nadu lacking qualified domestic adhesive suppliers. |
| Solid-State Battery Interface Co-Development Program | Positions for ceramic electrolyte-to-current collector bonding requirements that reset competitive expertise bases. |
Research Methodology
Operator-level perspectives from OEM platform engineers, Tier-1 battery integrator procurement leads, adhesive formulation laboratory directors, and aftermarket refurbishment specialists anchored the qualitative base. Primary interview data combined with secondary validation from customs and trade databases, SEC 10-K filings of diversified chemical conglomerates, IHS Markit vehicle production data, and ECHA substance registration records. Bottom-up segment sizing triangulated against top-down market envelope estimates derived from NEV production forecasts and content-per-vehicle assumptions.
Sensitivity analysis tested forecast robustness across alternative scenarios for cell-to-pack architecture adoption rates, solid-state battery commercialization timelines, and petrochemical feedstock price volatility. Segmentation dimensions modeled include adhesive product type, end-user procurement authority, curing technology platform, and application thermal exposure level. CAGRs derived from logistic growth curve fitting anchored by endpoint market size validation. Industry-specific forecast inputs incorporated UN 38.3 transport certification timeline assumptions and OEM platform program launch schedules.
Underlying assumptions cover REACH authorization timeline adherence, NEV subsidy framework continuity, and anhydride curing agent supply stability, with deviation risk concentrated in solid-state battery technology substitution and East Asian specialty chemical export restrictions. Forecasts reflect these conditions without claiming predictive certainty. Revision becomes warranted when solid-state battery pilot production volumes cross commercial viability thresholds or when EU Battery Regulation carbon footprint disclosure requirements tighten beyond current specification baselines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Joint Sealants Market
Adhesives & Sealants
Wearable Skin Adhesives Market
Adhesives & Sealants
Global Non-Woven Adhesives Market
Adhesives & Sealants
United States Sealants Market
Adhesives & Sealants
Wood Repair Epoxy Market
Adhesives & Sealants
Urea Formaldehyde Concrete Market
Adhesives & Sealants
Middle East and Africa Adhesives Market
Adhesives & Sealants
Thailand Adhesives Market
Adhesives & Sealants
Australia Sealants Market
Adhesives & Sealants
Textile Adhesives Market
Adhesives & Sealants
Russia Sealants Market
Adhesives & Sealants
Middle East & Africa Construction Adhesives & Sealants Market
Adhesives & Sealants
American Epoxy Adhesives Market
Adhesives & Sealants
Applicator Tips Market
Adhesives & Sealants
Middle East and Africa Flock Adhesives Market
Adhesives & Sealants
Global Silicone Adhesives Market