
 Electric Vehicle Adhesives Market | 2026-2036
Electric Vehicle Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Adhesives Market Intelligence
Automotive adhesive qualification under IATF 16949 is unwinding the competitive set, forcing suppliers to demonstrate continuous quality management and defect prevention. Henkel AG & Co. KGaA leverages its global footprint in structural bonding to serve premium OEM programs. Sika AG anchors its position through specialized polyurethane systems for battery encapsulation. Dow Inc. differentiates via silicone thermal management materials that address high-voltage isolation requirements.
Electric vehicle adhesives comprise formulated polymer systems—epoxies, polyurethanes, acrylics, and silicones—engineered to bond dissimilar substrates, manage thermal loads, and provide environmental sealing under operating temperatures spanning minus forty to one hundred fifty degrees Celsius. Their primary purpose is to replace welded or bolted joints, reducing vehicle weight while maintaining crash integrity and electrical isolation. Structural adhesives dominate value capture given their load-bearing function in chassis and battery pack architectures, while biobased formulations represent the fastest-growing technology category as sustainability targets harden across European and Asian OEM supply agreements. Battery assembly applications concentrate margin pools where thermal conductivity and flame-retardant specifications command formulation premiums.
The EPA oversees volatile organic compound limits affecting adhesive curing processes in US-based manufacturing, while REACH restricts hazardous substance content in European formulations, and China's SAMR enforces GB standards for EV battery safety that directly specify adhesive performance in thermal runaway containment. These frameworks collectively elevate R&D spend toward compliant chemistries and documentation systems. Stakeholders must monitor how evolving fire-safety thresholds in multiple jurisdictions will recalibrate acceptable material portfolios before the next platform design cycle locks.
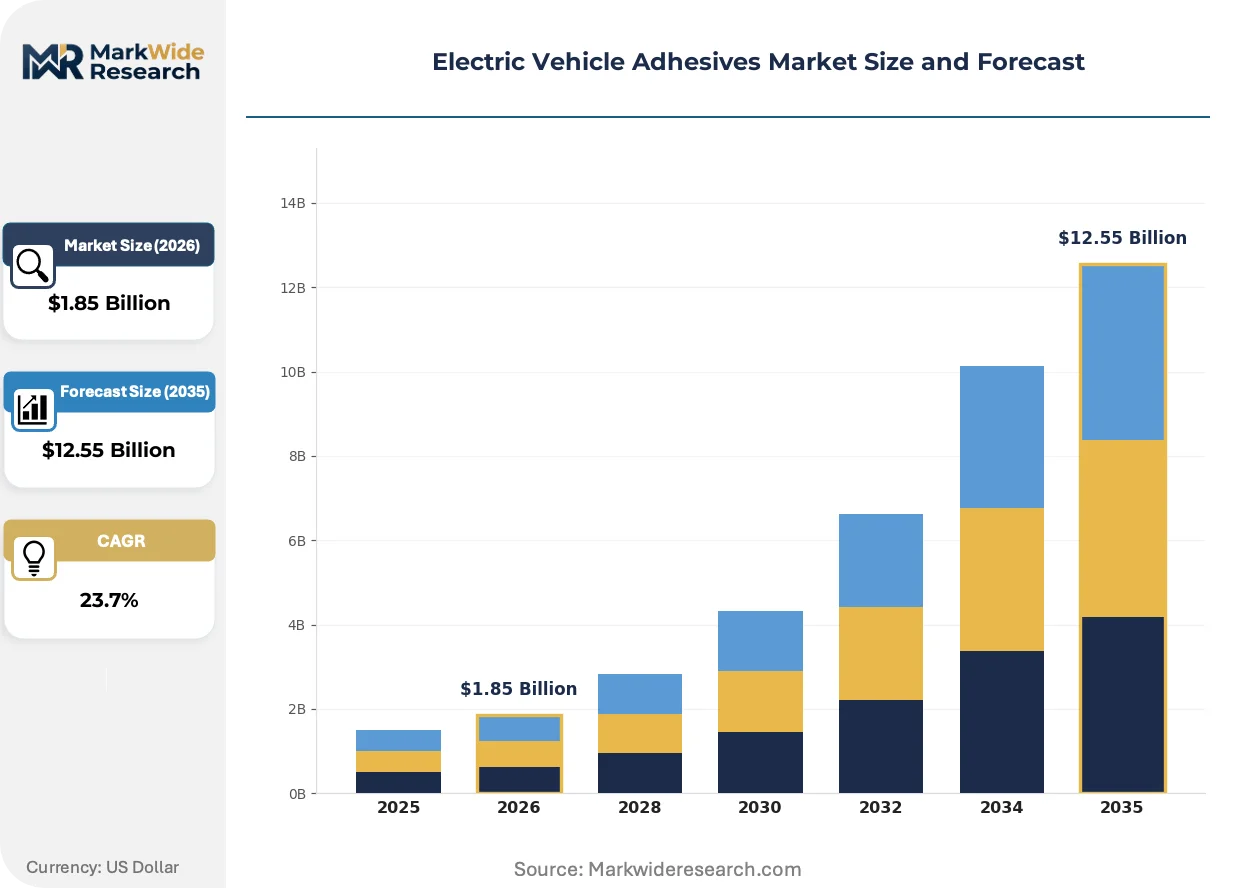
Market Dynamics
Battery pack architecture miniaturization is compressing adhesive layer tolerances while elevating thermal conductivity specifications beyond legacy automotive benchmarks. OEMs now specify materials that simultaneously bond aluminum-to-composite substrates and channel heat away from lithium-ion cells under thermal runaway conditions.
Growth Catalysts
- China's GB 38031 battery safety mandate:The SAMR-enforced standard mandates flame-retardant adhesive barriers between battery modules, forcing formulation upgrades across domestic and foreign supplier portfolios serving Chinese OEMs.
- Structural bonding in chassis-in-white:Multi-material vehicle platforms combining aluminum extrusions with carbon fiber reinforced polymers require crash-durable adhesives that maintain integrity across minus forty to one hundred fifty degree Celsius operating windows.
- Stuttgart-Munich production corridor:German automotive clusters anchor European demand concentration, with localized adhesive qualification labs accelerating OEM program integration timelines versus distant suppliers.
Market Restraints
- Petrochemical feedstock volatility:Epoxy and polyurethane resin costs fluctuate with crude oil derivatives, compressing formulation margins when OEMs lock multi-year pricing contracts.
- Specialized curing equipment concentration:Industrial oven and dispensing system suppliers cluster in Germany and Japan, creating procurement bottlenecks for regional manufacturers lacking established vendor relationships.
- Mechanical fastener residual preference:Repair network familiarity with bolted joints slows adhesive-only architectures in aftermarket-sensitive vehicle segments.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cell manufacturing:Domestic battery production incentives are attracting adhesive suppliers to establish local formulation facilities ahead of scaled OEM assembly operations.
- Biobased feedstock convergence with performance parity:Epoxy resins derived from lignin and vegetable oil precursors are achieving shear strength metrics matching petroleum-based equivalents, opening sustainability-linked procurement channels.
- Thermal interface material-battery encapsulant integration:Single-layer solutions combining structural adhesion with phase-change thermal management are displacing multi-component stackups in premium platform designs.
Industry Challenges
- IATF 16949 certification timeline compression:New entrants face eighteen-to-twenty-four month qualification periods to demonstrate defect prevention and continuous improvement systems before OEM program participation.
- Cross-functional formulation expertise scarcity:Chemists possessing simultaneous competence in polymer rheology, electrical isolation testing, and crash simulation modeling command premium compensation and limited availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Adhesives Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural Adhesives, Sealants, Coatings, Bonding Agents Technology: Synthetic Adhesives, Biobased Adhesives, Thermal Curing, Pressure Sensitive Application: Battery Assembly, Chassis Bonding, Interior Component, Body Panel End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Henkel AG & Co. KGaA, H.B. Fuller, Sika AG, 3M, Wacker Chemie AG, Arkema S.A., Dow Inc., BASF, PPG Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Adhesives Market Strategic Shifts & Innovations
Adhesive functionality is converging with thermal management and electrical safety systems, eliminating discrete component layers while complicating qualification protocols. Formulation houses now compete on integrated performance metrics rather than single-property benchmarks.
Two-part epoxy systems with embedded ceramic fillers are miniaturizing thermal interface gaps between battery cells and cooling plates. Cell manufacturers in South Korea and China specify these materials for next-generation prismatic and blade-cell architectures. The technology is compressing assembly step counts while elevating thermal conductivity thresholds beyond legacy silicone grease applications.
REACH authorization requirements for diisocyanates in polyurethane formulations are forcing European suppliers toward aliphatic alternatives with modified curing kinetics. Industrial consequence includes extended production cycle times and capital investment in UV-assisted curing lines. Battery encapsulation applications in Germany and France are most affected, with OEMs accelerating biobased epoxy trials as contingency pathways.
Specification authority is migrating from tier-one module assemblers to cell producers and OEM platform engineering teams. Long-term supply agreements now lock adhesive performance criteria at the chemistry level rather than component level, compressing supplier switching flexibility. This concentration is most visible in China, where CATL and BYD dictate formulation standards that cascade through their supplier pyramids.
Electric Vehicle Adhesives Market Segmentation
Segmentation in electric vehicle adhesives reveals how formulation chemistry, curing technology, and supply chain position determine margin capture. OEM specification authority now resides at the chemistry level, compressing supplier flexibility across all product categories.
Product Type:
Structural adhesives flow primarily through direct OEM channels with multi-year qualification timelines, while sealants and coatings route through tier-one module assemblers with shorter procurement cycles.
- Structural Adhesives:Epoxy and polyurethane systems engineered for load-bearing aluminum-to-composite joints in chassis and battery pack architectures. Demand concentrates in Stuttgart and Munich automotive clusters where crash-durable specifications command formulation premiums under IATF 16949 protocols.
- Sealants:Flexible polymer barriers providing environmental sealing across minus forty to one hundred fifty degree Celsius operating windows. Battery encapsulation applications in Germany and France drive specification authority as REACH diisocyanate restrictions force aliphatic alternatives.
- Coatings:Protective layers applied to battery module housings and cooling plates for corrosion resistance and electrical isolation.
- Bonding Agents:Specialized formulations for interior component attachment where vibration damping and weight reduction priorities dominate.
By volume, sealants lead through broad application across battery and body domains. By growth pace, structural adhesives are ahead as multi-material vehicle platforms proliferate.
Technology:
Cost tiers separate synthetic formulations serving volume production from biobased alternatives capturing sustainability-linked procurement premiums in European OEM agreements.
- Synthetic Adhesives:Petroleum-derived epoxy and polyurethane systems dominating current production scale. Petrochemical feedstock volatility compresses margins when OEMs lock multi-year pricing contracts, particularly affecting European and Asian suppliers.
- Biobased Adhesives:Epoxy resins derived from lignin and vegetable oil precursors achieving shear strength parity with petroleum equivalents. European REACH compliance and OEM sustainability targets accelerate adoption fastest in German and French battery programs.
- Thermal Curing:Heat-activated polymerization requiring industrial oven infrastructure concentrated in Germany and Japan.
- Pressure Sensitive:Room-temperature bonding systems for interior component applications with lower capital equipment requirements.
Synthetic adhesives retain volume leadership. Biobased formulations are climbing the fastest as supply agreements harden sustainability criteria.
Application:
Application concentration determines margin structure, with battery assembly commanding specification premiums and chassis bonding anchoring long-term contract value.
- Battery Assembly:Thermal interface materials and flame-retardant encapsulants managing heat dissipation and thermal runaway containment. China's GB 38031 mandate from SAMR forces formulation upgrades across domestic and foreign supplier portfolios serving CATL and BYD.
- Chassis Bonding:Crash-durable structural joints replacing welded connections in aluminum-intensive platforms. Stuttgart-Munich production corridors anchor European demand where localized qualification labs accelerate OEM program integration.
- Interior Component:Vibration-damping adhesives for dashboard, seating, and trim attachment prioritizing occupant comfort metrics.
- Body Panel:Exterior bonding and sealing applications where repair network familiarity with mechanical fasteners slows adhesive-only adoption.
Chassis bonding leads by installed volume across vehicle platforms. Battery assembly is gaining share fastest as cell architecture miniaturization elevates thermal conductivity specifications.
End User:
Customer type dictates procurement complexity, with OEMs driving chemistry-level specifications and tier-one suppliers managing formulation blending and logistics.
- OEMs:Platform engineering teams at Volkswagen, BMW, and Chinese manufacturers now lock adhesive performance criteria at the chemistry level rather than component level. This concentration compresses supplier switching flexibility and extends qualification timelines to eighteen-to-twenty-four months.
- Tier-1 Suppliers:Module assemblers purchasing qualified formulations for battery pack and chassis integration. India's PLI scheme for advanced chemistry cell manufacturing is attracting adhesive suppliers to establish local formulation facilities ahead of scaled OEM assembly.
- Aftermarket Providers:Repair network distributors where mechanical fastener residual preference slows adhesive architecture adoption.
- Vehicle Assemblers:Contract manufacturing operations with limited specification authority, procuring through tier-one channels.
Tier-1 suppliers lead by transaction volume through fragmented procurement across multiple OEM programs. OEM direct channels are expanding most quickly as specification authority migrates upstream to platform engineering teams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's GB 38031 battery safety mandate from SAMR is recalibrating formulation standards across multiple continents as OEMs harmonize supply chains. Germany anchors European qualification intensity through localized testing infrastructure. The United States and India are emerging as alternative production nodes through IRA manufacturing credits and PLI scheme incentives respectively.
China
CATL and BYD platform engineering teams dictate adhesive chemistry specifications that cascade through supplier pyramids. SAMR enforces GB 38031 flame-retardant barriers between battery modules, forcing domestic and foreign formulation upgrades. The Yangtze River Delta and Pearl River Delta clusters concentrate cell manufacturing and adhesive qualification labs.
Germany
Stuttgart and Munich automotive corridors drive crash-durable structural adhesive demand for aluminum-to-composite chassis joints. REACH diisocyanate restrictions under ECHA authorization requirements are accelerating aliphatic polyurethane trials. Bavaria hosts the densest concentration of IATF 16949 qualification facilities in Europe.
United States
IRA domestic content provisions are attracting battery cell manufacturing to Michigan and Ohio, pulling adhesive formulation capacity across the Atlantic. EPA volatile organic compound limits affect curing process design in US-based assembly plants. The Southeast corridor from Georgia to South Carolina is emerging as a secondary node through Kia and Hyundai investments.
India
PLI scheme incentives for advanced chemistry cell manufacturing are drawing adhesive suppliers to establish local formulation ahead of scaled OEM assembly. BIS certification requirements for automotive materials are extending qualification timelines for imported chemistries. Gujarat and Tamil Nadu are anchoring initial battery pack integration capacity.
South Korea
LG Energy Solution and Samsung SDI thermal interface specifications are driving ceramic-filled epoxy adoption for prismatic cell architectures. MFDS chemical safety notifications apply to imported resin systems. The Gyeonggi-do corridor surrounding Seoul concentrates both cell production and adhesive R&D partnerships.
Electric Vehicle Adhesives Market Key Industry Players
Listed leaders compete with private specialists across capital intensity and qualification timeline dimensions. The vendor set stratifies between diversified chemical conglomerates with global distribution networks and regional formulation houses serving single OEM programs. Three archetypes dominate: integrated material science conglomerates, automotive-focused adhesive specialists, and battery-specific thermal material innovators. Competitive moves center on backward integration into resin production and geographic co-location with cell manufacturing clusters.
Within the integrated material science tier, Henkel AG & Co. KGaA and Dow Inc. occupy positions exemplifying global footprint leverage for structural bonding and thermal management applications respectively. Sika AG represents the automotive-focused specialist archetype through polyurethane system concentration. These three entities anchor the competitive set through differentiated chemistry-level specification authority with OEM platform engineering teams.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| H.B. Fuller |
| Sika AG |
| 3M |
| Wacker Chemie AG |
| Arkema S.A. |
| Dow Inc. |
| BASF |
| PPG Industries |
| Others |
Cost & Logistics Intelligence
IATF 16949 certification gates both supplier qualification timelines and price differentiation in electric vehicle adhesives, compressing margins for uncertified entrants while rewarding compliant incumbents with multi-year OEM contract premiums. This regime simultaneously elevates R&D documentation costs and creates tiered pricing power anchored in quality assurance rather than commodity resin economics.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with IATF 16949-qualified suppliers commanding sustained premiums over uncertified regional blenders. Three-tier pricing structure separates OEM-direct structural formulations from tier-one module encapsulants and aftermarket repair sealants. Cost compression in synthetic epoxy tiers is intensifying because petrochemical feedstock volatility collides with locked multi-year OEM pricing, squeezing formulation margins. Tier-one module assemblers exhibit highest price sensitivity due to fragmented procurement across competing OEM programs, while OEM platform engineering teams prioritize thermal performance over unit cost.
Supply Chain Analysis
Inventory lead times for specialized curing equipment extend procurement cycles, with industrial oven and dispensing system suppliers clustering in Germany and Japan. Raw material supply concentrates in China for ceramic fillers, Germany for aliphatic polyurethane precursors, and South Korea for high-purity epoxy resins. Formulation houses draw from petroleum-derived feedstocks, lignin biobased alternatives, and imported diisocyanate chemistries. Single-source vulnerability concentrates in UV-assisted curing line equipment where Japanese vendors dominate. Distribution runs through direct OEM channels for structural adhesives and tier-one module assemblers for battery encapsulants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechanical fastener residual preference in aftermarket repair networks threatens adhesive-only architectures, forcing incumbents to defend substitution economics through total-cost-of-ownership demonstration and technician retraining investment.
For Market Incumbents: Consolidate backward integration into resin production to offset petrochemical feedstock volatility and capture margin from biobased epoxy precursors. Deepen captive supply of lignin-derived chemistries ahead of REACH diisocyanate restriction deadlines. Priority lever: co-locate formulation facilities with CATL and BYD cell manufacturing clusters in China's Yangtze River Delta to compress qualification timelines against distant European rivals. For New Entrants and Emerging Players: Anchor in India's PLI scheme corridor between Gujarat and Tamil Nadu, where domestic battery production incentives precede scaled OEM assembly and qualification timelines remain unclaimed. Target thermal interface material-battery encapsulant integration as the most penetrable white space, where single-layer solutions displace multi-component stackups in premium platforms. Go-to-market angle: partner with advanced chemistry cell manufacturers before OEM platform engineering teams lock chemistry-level specifications. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biobased adhesive manufacturing as lignin processing and UV-curing infrastructure replace conventional thermal lines. Long-term viability favors suppliers with simultaneous polymer rheology, electrical isolation testing, and crash simulation modeling capabilities—cross-functional expertise scarcity creates durable moats. Acquisition target archetype: regional formulation houses with established IATF 16949 certification and single-OEM program relationships in Germany or South Korea. Signal to watch: OEM sustainability-linked procurement clauses hardening from aspirational targets to binding supply agreement terms.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captures margin from lignin-derived epoxy precursors and insulates against petrochemical volatility. |
| Geographic Co-location with Cell Clusters | Compresses eighteen-to-twenty-four month IATF qualification timelines versus distant competitors. |
| Biobased Formulation Scale-Up | Aligns with REACH compliance deadlines and OEM sustainability-linked procurement clauses. |
| Thermal-Electrical Integration R&D | Displaces multi-component stackups with single-layer structural-phase-change solutions. |
| UV-Assisted Curing Line Investment | Responds to aliphatic polyurethane curing kinetics extended by diisocyanate restrictions. |
Research Approach
Initial hypotheses were tested against primary input from OEM platform engineers, tier-one module procurement leads, adhesive formulation chemists, and thermal management specialists, then refined through secondary validation. OEM program managers, IATF 16949 auditors, cell manufacturing operations heads, and aftermarket repair network distributors provided operational perspective. Secondary sources included customs and trade flow data for resin imports, ECHA REACH authorization filings, SAMR GB standard documentation, SEC 10-K disclosures from listed chemical conglomerates, and vehicle production databases. Bottom-up volume modeling triangulated against top-down value estimates.
Variance decomposition separated volume growth drivers from price-mix effects across the projection horizon. Segmentation dimensions spanned product chemistry, curing technology, application function, and end-user procurement channel. CAGRs derived from fitted growth curves applied to disclosed OEM platform rollout schedules and cell manufacturing capacity announcements. Industry-specific inputs included thermal conductivity specification trajectories from CATL and BYD engineering disclosures, plus REACH diisocyanate restriction implementation timelines.
Decision-makers should treat outputs as directional under assumptions of sustained OEM multi-material platform adoption and unaltered GB 38031 flame-retardant mandate enforcement; material deviation would warrant model refresh. Forecasts assume continued petrochemical feedstock volatility and incremental biobased formulation cost parity achievement. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
North America Automotive Adhesives and Sealants Market
Adhesives & Sealants
Floor Tile Adhesive Market
Adhesives & Sealants
North America Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Acrylate Market
Adhesives & Sealants
South America Waterborne Adhesives Market
Adhesives & Sealants
Asia-Pacific Waterproofing Products Market
Adhesives & Sealants
Middle-East and Africa Hot-Melt Adhesives Market
Adhesives & Sealants
South America Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Global EVA Adhesives Market
Adhesives & Sealants
North America Waterborne Adhesives Market
Adhesives & Sealants
Water-Borne Adhesives Market
Adhesives & Sealants
Cycloaliphatic Epoxy Market
Adhesives & Sealants
Japan Adhesives Market
Adhesives & Sealants
Cold Seal Adhesives Market
Adhesives & Sealants
Global Construction Silicone Sealants Market
Adhesives & Sealants
Global Slack Wax Market