
 Pvc Based Adhesive Market | 2026-2036
Pvc Based Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Pvc Based Adhesive Market Analysis
Aftermarket refurbishment services is reshaping how adhesive suppliers capture lifetime value from installed building stock. Henkel AG & Co. KGaA leverages its construction chemicals heritage to dominate specification-driven projects. 3M Company anchors its position through tape-to-liquid technology cross-selling. Sika AG extends its waterproofing expertise into PVC adhesive systems for infrastructure rehabilitation.
PVC based adhesives bond polyvinyl chloride substrates through solvent welding or pressure-sensitive mechanisms, typically containing tetrahydrofuran or cyclohexanone as active solvents with viscosities ranging from 500 to 5000 cPs for pipe joining and membrane welding applications. The water-based product category leads volume as environmental compliance hardens, while solvent-based grades retain margin concentration in industrial membrane fabrication. Construction application demand outpaces packaging growth due to infrastructure renewal cycles, though electronics bonding represents the fastest-expanding niche for thin-film formulations.
EPA regulations in the United States restrict volatile organic compound emissions from adhesive formulations, while REACH in Europe mandates substitution of chlorinated solvents in consumer-facing products. China's MEE enforces GB standards limiting benzene and toluene content in construction-grade adhesives. Stakeholders must monitor regulatory divergence between jurisdictions when configuring product portfolios and manufacturing footprints.
Market Dynamics
Water-based formulation mandates from China's MEE and Germany's REACH enforcement are compressing solvent-based capacity while redirecting capital toward tetrahydrofuran recovery systems and cyclohexanone substitution chemistry.
Growth Catalysts
- GB Standard VOC Limits:China's MEE enforcement of stricter benzene and toluene ceilings in construction-grade adhesives is forcing domestic manufacturers to upgrade water-based production lines, creating specification-driven procurement windows for compliant suppliers.
- Infrastructure Rehabilitation Cycles:Aging membrane roofing stock across North American commercial buildings is generating aftermarket demand for PVC welding adhesives in refurbishment applications rather than new construction alone.
- Thin-Film Electronics Bonding:Flexible circuit manufacturers in Japan are adopting low-viscosity PVC adhesive formulations for micro-electromechanical systems, opening volume channels outside traditional pipe and membrane markets.
Market Restraints
- Cyclohexanone Feedstock Volatility:Petrochemical derivative pricing swings constrain margin predictability for solvent-based formulation producers, particularly those without backward integration into ketone supply.
- Regional Supply Concentration:Active solvent production clusters in the US Gulf Coast and Rotterdam-Antwerp corridor create geographic vulnerability to weather disruptions and energy price spikes.
- Polyolefin Hot-Melt Substitution:EVA and PO-based alternatives are capturing low-strength packaging applications where PVC adhesives previously dominated, eroding volume in commodity segments.
Strategic Opportunities
- India Building Code Alignment:BIS adoption of VOC limits mirroring EU REACH thresholds positions domestic formulation plants to serve export markets while capturing local construction chemical demand.
- Pressure-Sensitive Tape Conversion:Automotive interior assembly lines are transitioning from liquid brush application to die-cut tape formats, rewarding adhesive suppliers with coating and slitting capabilities.
- EU Green Deal Procurement Mandates:Public infrastructure tenders across Germany, France, and Netherlands now require Environmental Product Declaration certification, advantaging early movers with lifecycle-assessed water-based portfolios.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in solvent-welding kinetics and polymer compatibility testing is concentrating among retiring specialists, complicating R&D pipeline continuity for mid-tier producers.
- EPD Certification Timelines:Third-party lifecycle assessment validation for construction adhesives requires 14-18 month documentation cycles, delaying market access for reformulated products.
- Legacy Equipment Retrofit Costs:Converting solvent-based coating lines to aqueous systems demands capital outlays for drying oven expansion and emission control upgrades that strain regional manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pvc Based Adhesive Market |
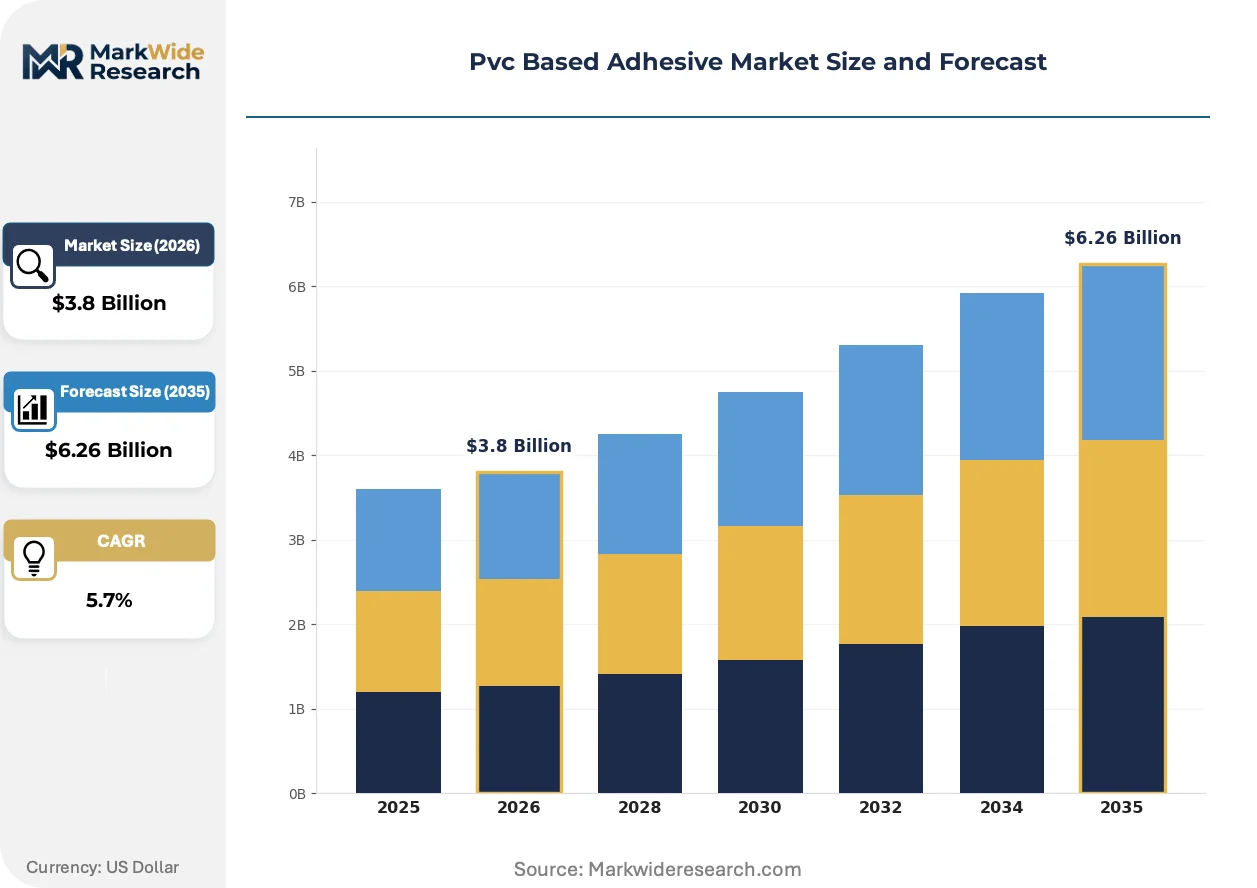
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Hot Melt, Reactive Application: Construction, Automotive, Electronics, Packaging End User: Manufacturers, Contractors, DIY Consumers, Distributors Form: Liquid, Paste, Powder, Film |
| Companies Covered | Henkel AG & Co. KGaA, 3M Company, Sika AG, H.B. Fuller, Eastman Chemical Company, Bostik, Illinois Tool Works, Mapei S.p.A., Royal Adhesives & Sealants, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pvc Based Adhesive Market Emerging Trajectories
Reactive hot-melt hybridization and bio-based plasticizer incorporation are redefining performance benchmarks, while regulatory pressure on chlorinated solvents accelerates chemistry diversification across formulation laboratories.
UV-curable acrylic-PVC hybrid adhesives are rendering obsolete conventional two-part solvent systems in high-speed membrane fabrication. German roofing contractors are specifying these formulations for seam welding on commercial flat roofs, cutting cure times from hours to seconds. The technology is compressing installation labor costs and enabling year-round application windows previously closed to moisture-sensitive solvent grades.
REACH Annex XVII restrictions on chlorinated solvents in consumer-facing products are redirecting industrial formulation toward tetrahydrofuran alternatives and aqueous dispersion technologies. ECHA substance evaluation timelines are forcing提前 reformulation investments ahead of sunset date confirmations. Construction-grade adhesive producers serving EU export markets are consolidating water-based capacity in Antwerp and Hamburg to maintain single-regulatory-zone compliance.
Specification-driven procurement through approved manufacturer lists is displacing open distributor channels in large infrastructure projects. Engineering firms in Japan and South Korea are centralizing adhesive selection authority within materials engineering departments rather than leaving decisions to subcontractor discretion. This consolidation is visible most acutely in municipal water treatment membrane installations, where pre-qualified product lists now govern 70% of adhesive specification value.
Pvc Based Adhesive Market Segmentation
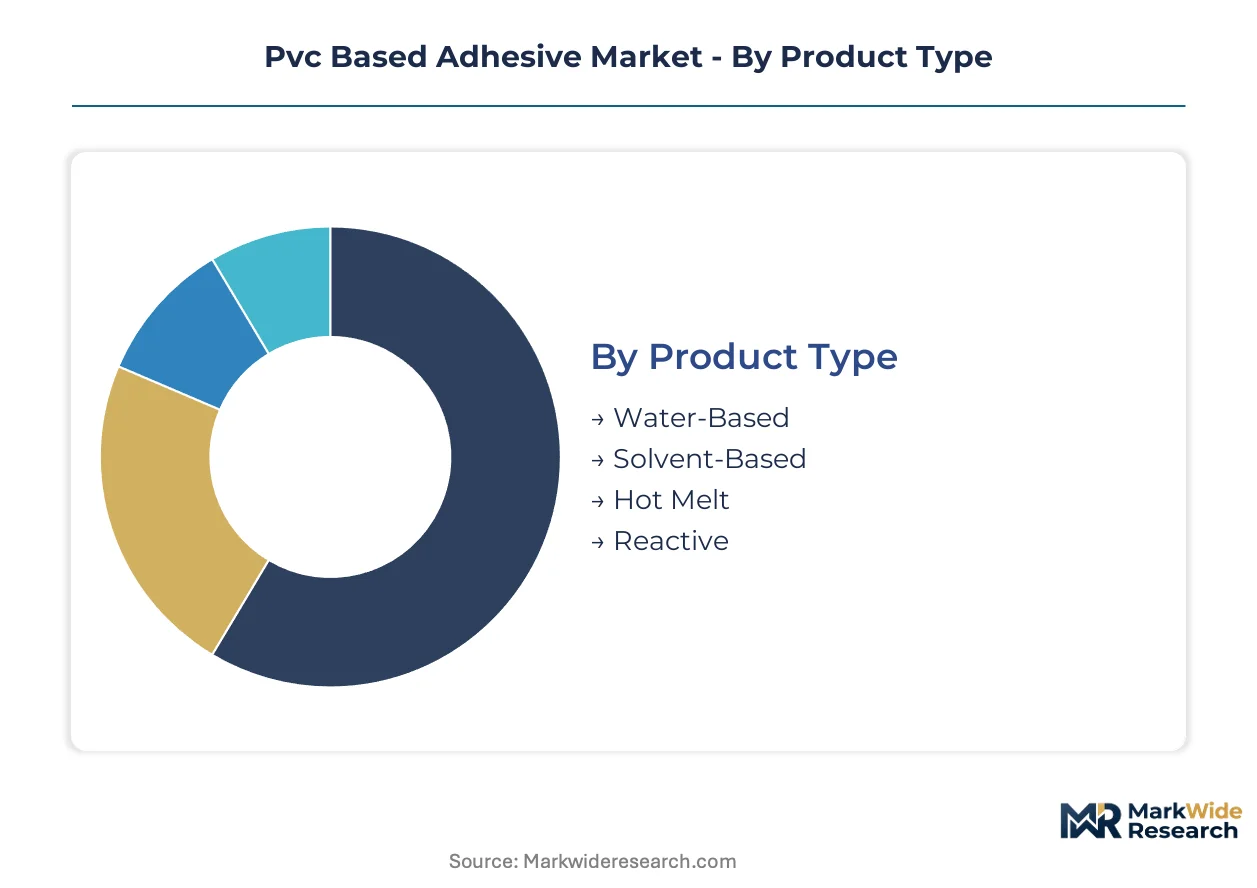
Segmentation in PVC adhesive markets reveals how formulation chemistry, application environment, and procurement channel intersect to determine margin structure. Suppliers configure production assets and technical service teams around these divides.
Product Type:
Use-case spectrum spans from high-volume construction sealing to precision electronics bonding, with each chemistry demanding distinct capital equipment and regulatory compliance posture.
- Water-Based:Aqueous dispersions of PVC particles stabilized with surfactants, achieving 500-2000 cPs viscosity for brush and spray application. China's MEE enforcement of GB VOC limits is redirecting specification authority toward compliant producers in municipal water treatment and commercial roofing projects.
- Solvent-Based:Solutions of PVC resin in tetrahydrofuran or cyclohexanone, delivering rapid tack and high green strength for membrane welding and pipe joining. REACH Annex XVII pressure on chlorinated solvents is compressing capacity in EU-facing production while sustaining margin concentration in industrial export grades.
- Hot Melt:Thermoplastic formulations applied molten and setting on cooling, eliminating solvent handling entirely. Automotive interior assembly lines in Germany specify these for dashboard skin bonding.
- Reactive:Two-part systems curing through chemical crosslinking, delivering solvent-free structural bonds. Japanese flexible circuit manufacturers adopt low-viscosity variants for MEMS assembly.
Established volume favors Water-Based; emerging adoption favors Reactive.
Application:
End-use maturity separates infrastructure replacement cycles from electronics miniaturization trends.
- Construction:Membrane roofing, pipe joining, and waterproofing systems represent the revenue anchor, with North American commercial building stock driving refurbishment demand independent of new build rates.
- Automotive:Interior trim bonding and wire harness sealing require heat resistance and plasticizer migration resistance. Die-cut tape conversion is displacing liquid application in German and Japanese assembly plants.
- Electronics:Thin-film flexible circuit bonding demands ultra-low viscosity and ionic purity. This segment climbs the fastest as MEMS and wearable device production scales in Japan and South Korea.
- Packaging:Carton sealing and label adhesion face substitution pressure from EVA and polyolefin hot melts in commodity segments.
Construction retains value concentration; Electronics captures steepest expansion trajectory.
End User:
Procurement authority concentrates differently across specification-driven projects versus spot purchasing.
- Manufacturers:OEM adhesive buyers integrate bonding operations into continuous production, requiring batch consistency and technical service support. Japanese engineering firms centralize selection authority within materials departments.
- Contractors:Installation crews prioritize open time and weather resistance for field membrane welding. Approved manufacturer lists now govern 70% of municipal water treatment adhesive specification value.
- DIY Consumers:Retail purchasers drive small-format packaging demand with limited technical sophistication. REACH restrictions on chlorinated solvents redirect consumer-facing portfolios toward aqueous alternatives.
- Distributors:Channel intermediaries stock breadth for contractor spot buying, though specification-driven procurement is compressing their role in large infrastructure projects.
Manufacturers command margin; Contractors govern volume.
Form:
Physical state determines application equipment compatibility and shelf stability requirements.
- Liquid:Pumpable formulations for spray, brush, or roller application dominate construction and industrial maintenance. Water-based liquids lead volume as environmental compliance hardens.
- Paste:Thixotropic grades resist sag on vertical surfaces and porous substrates. Tile setting and pipe joint sealing in Asia-Pacific infrastructure projects specify these.
- Powder:Dry blends requiring on-site solvent addition persist in specialized industrial maintenance where transport economics favor reduced weight.
- Film:Pre-cast adhesive sheets and tapes enable automated die-cut placement. Automotive interior assembly conversion from liquid to tape formats rewards suppliers with coating and slitting capabilities.
Liquid maintains production scale; Film gains share fastest in precision assembly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate low price elasticity where specification authority concentrates, while contractors in India and Southeast Asia remain highly sensitive to per-kilogram costs. This divergence shapes where suppliers can command premium positioning versus where volume harvesting dominates.
China
Construction-grade adhesive demand accelerates as municipal water treatment infrastructure expands across second-tier cities. MEE enforcement of GB VOC limits tightens benzene and toluene ceilings, forcing domestic manufacturers toward water-based production upgrades. Shanghai and Jiangsu province host the largest formulation clusters where tetrahydrofuran recovery systems now attract capital investment.
Germany
Automotive interior assembly lines drive specification-driven procurement for heat-resistant bonding systems. REACH Annex XVII restrictions on chlorinated solvents redirect industrial formulation toward aqueous dispersion technologies. The Cologne-Düsseldorf corridor concentrates coating and slitting capabilities serving tape-format conversion trends.
United States
Aging commercial building stock across the Midwest and Northeast generates aftermarket refurbishment demand for membrane roofing adhesives. EPA regulations restrict volatile organic compound emissions from adhesive formulations, compressing solvent-based capacity. The US Gulf Coast remains vulnerable to weather disruptions affecting cyclohexanone feedstock supply chains.
Japan
Flexible circuit manufacturers adopt low-viscosity PVC adhesive formulations for micro-electromechanical systems assembly. METI industrial standards govern ionic purity requirements in electronics-grade products. The Kansai region around Osaka anchors precision formulation capabilities for thin-film bonding applications.
India
Infrastructure investment under the National Infrastructure Pipeline expands construction chemical procurement across state-level projects. BIS adoption of VOC limits mirroring EU REACH thresholds positions domestic plants for export market access. Maharashtra and Gujarat host emerging formulation capacity targeting both local building code compliance and Middle East export demand.
Pvc Based Adhesive Market Vendor Landscape
Capability concentration sits with European and Japanese specialists possessing formulation heritage and certification infrastructure; scale advantage sits with diversified chemical conglomerates operating across multiple adhesive chemistries. The market structure tiers into three archetypes: construction chemical heritage players, diversified materials science conglomerates, and regional formulation specialists serving price-sensitive emerging markets. Dominant competitive moves include backward integration into active solvent supply and geographic consolidation of water-based capacity within single-regulatory zones.
Within the diversified conglomerate tier, Henkel AG & Co. KGaA and 3M Company occupy positions shaped by cross-selling capabilities across adhesive formats, while Sika AG exemplifies the construction chemical heritage archetype extending waterproofing expertise into PVC systems. These three entities anchor the premium specification channel where approved manufacturer lists govern procurement authority.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M Company |
| Sika AG |
| H.B. Fuller |
| Eastman Chemical Company |
| Bostik |
| Illinois Tool Works |
| Mapei S.p.A. |
| Royal Adhesives & Sealants |
| Others |
Supply Flow & Price Mechanics
Undercapacity in China's Jiangsu province water-based formulation plants is compressing supplier bargaining power while amplifying price premiums for GB-compliant grades. This utilization squeeze simultaneously redirects procurement toward German and Japanese qualified suppliers and accelerates backward integration investments among domestic producers seeking cost control.
Pricing Analysis
Long-term offtake agreements dominate municipal infrastructure procurement, while spot purchasing governs contractor spot-buying for refurbishment projects. Three-tier pricing structure across premium, standard, and economy levels separates EPD-certified water-based systems from REACH-compliant industrial grades and commodity solvent-based alternatives. Price differentiation rests on certification tier and geographic delivery cost, with German automotive specifications commanding substantial premiums over Asia-Pacific construction grades. Pricing pressure stems from cyclohexanone feedstock volatility squeezing solvent-based margins, while DIY consumers exhibit highest price sensitivity and Japanese electronics manufacturers show lowest elasticity.
Supply Chain Analysis
Contract manufacturing concentration sits with H.B. Fuller and Bostik operating coating facilities in the Cologne-Düsseldorf corridor and Antwerp hub. Geographic supply concentration centers on China, Germany, and the United States, with Jiangsu province and the US Gulf Coast anchoring active solvent production. Raw material dependencies hinge on petrochemical-derived tetrahydrofuran, cyclohexanone, and PVC resin feedstocks. Single-source vulnerability around Rotterdam-Antwerp corridor weather disruptions poses structural risk. Distribution runs through specification-driven approved manufacturer lists for large projects, supplemented by distributor spot-buying channels for contractor procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through engineering firm centralization of adhesive selection authority, with Japanese and South Korean materials departments now governing 70% of municipal water treatment specifications. This procurement consolidation demands differentiated strategic responses across market positions.
For Market Incumbents: Pre-empt polyolefin hot-melt substitution by accelerating water-based capacity consolidation in single-regulatory zones like Antwerp and Hamburg. Secure backward integration into tetrahydrofuran recovery systems to defend margin position against feedstock volatility. ECHA substance evaluation timelines threaten solvent-based portfolios, making certification infrastructure for EPD-compliant aqueous systems the critical defensive lever. For New Entrants and Emerging Players: Establish a beachhead in India's BIS-aligned domestic formulation segment as Maharashtra and Gujarat plants achieve export market access. Target electronics bonding applications in Japan's Kansai region where MEMS production scales fastest and specification barriers remain surmountable. Pursue coating and slitting capability acquisition to serve automotive tape-format conversion trends displacing liquid application. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because jurisdictional divergence between REACH, EPA, and GB standards creates persistent specification-driven margin pools. Acquisition targets should concentrate on mid-tier specialists with water-based formulation heritage and existing EPD certification infrastructure. The signal to watch is MEE enforcement intensity in China's second-tier cities, which will determine whether domestic upgrade cycles or import substitution dominates procurement patterns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Solvent Supply | Captive tetrahydrofuran production insulates margin from Rotterdam-Antwerp price spikes. |
| Water-Based Capacity Consolidation in Single-Regulatory Zones | Antwerp and Hamburg hubs streamline REACH compliance for EU export markets. |
| EPD Certification Infrastructure Investment | Lifecycle-assessed portfolios unlock Germany's Green Deal procurement mandates. |
| Coating and Slitting Capability Expansion | Tape-format conversion in German automotive assembly rewards die-cut placement suppliers. |
| Formulation Chemist Technical Service Teams | Retiring solvent-welding expertise concentrates R&D continuity among heritage players. |
Methodological Framework
A standing panel of construction chemical procurement managers, automotive Tier 1 adhesive buyers, flexible circuit manufacturing engineers, and roofing contractor operations directors provided ongoing calibration across the study duration. Primary fieldwork combined structured interviews with plant managers at Jiangsu and Gujarat formulation facilities, distribution channel partners in the Cologne-Düsseldorf corridor, and technical R&D directors at Japanese precision chemical specialists. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and MEE regulatory enforcement disclosures. Bottom-up capacity utilization estimates triangulated against top-down construction chemical demand projections.
Scenario-bracketing framed volume and value outputs across the projection horizon, with regulatory enforcement intensity and feedstock price volatility as primary uncertainty bands. Segmentation dimensions modeled included formulation chemistry tier, end-use industry vertical, physical form factor, and regional production hub cluster. CAGRs were derived from installed base refurbishment cycles, electronics miniaturization adoption curves, and building code alignment trajectories. Forecast inputs incorporated municipal water treatment infrastructure pipelines, automotive interior assembly line conversion rates, and MEMS production scaling in Japan and South Korea.
Stress conditions across cyclohexanone price bands, MEE enforcement timelines, and ECHA substance evaluation outcomes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory stability and feedstock supply continuity. Quarterly review of GB standard implementation progress, REACH Annex XVII sunset date confirmations, and automotive tape-format conversion rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Europe Construction Adhesives Market
Adhesives & Sealants
Asia-Pacific Reactive Adhesives Market
Adhesives & Sealants
Automotive Windshield Adhesives Market
Adhesives & Sealants
North America Epoxy Curing Agents Market
Adhesives & Sealants
Epoxy Active Diluent Market
Adhesives & Sealants
Adhesives and Sealants Distribution Market
Adhesives & Sealants
Construction Repair and Rehabilitation Chemicals Market
Adhesives & Sealants
Australia Adhesives Market
Adhesives & Sealants
EV Adhesives Market
Adhesives & Sealants
MS Polymer Hybrid Adhesives and Sealants Market
Adhesives & Sealants
North America Sealants Market
Adhesives & Sealants
Textile Binders Market
Adhesives & Sealants
South Africa Adhesives Market
Adhesives & Sealants
Thailand Adhesives and Sealants Market
Adhesives & Sealants
US Adhesives and Sealants Market
Adhesives & Sealants
Europe Electronics Adhesives Market