
 Middle-East and Africa Polyurethane (PU) Adhesives Market | 2026-2036
Middle-East and Africa Polyurethane (PU) Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Polyurethane (PU) Adhesives Market Foresight
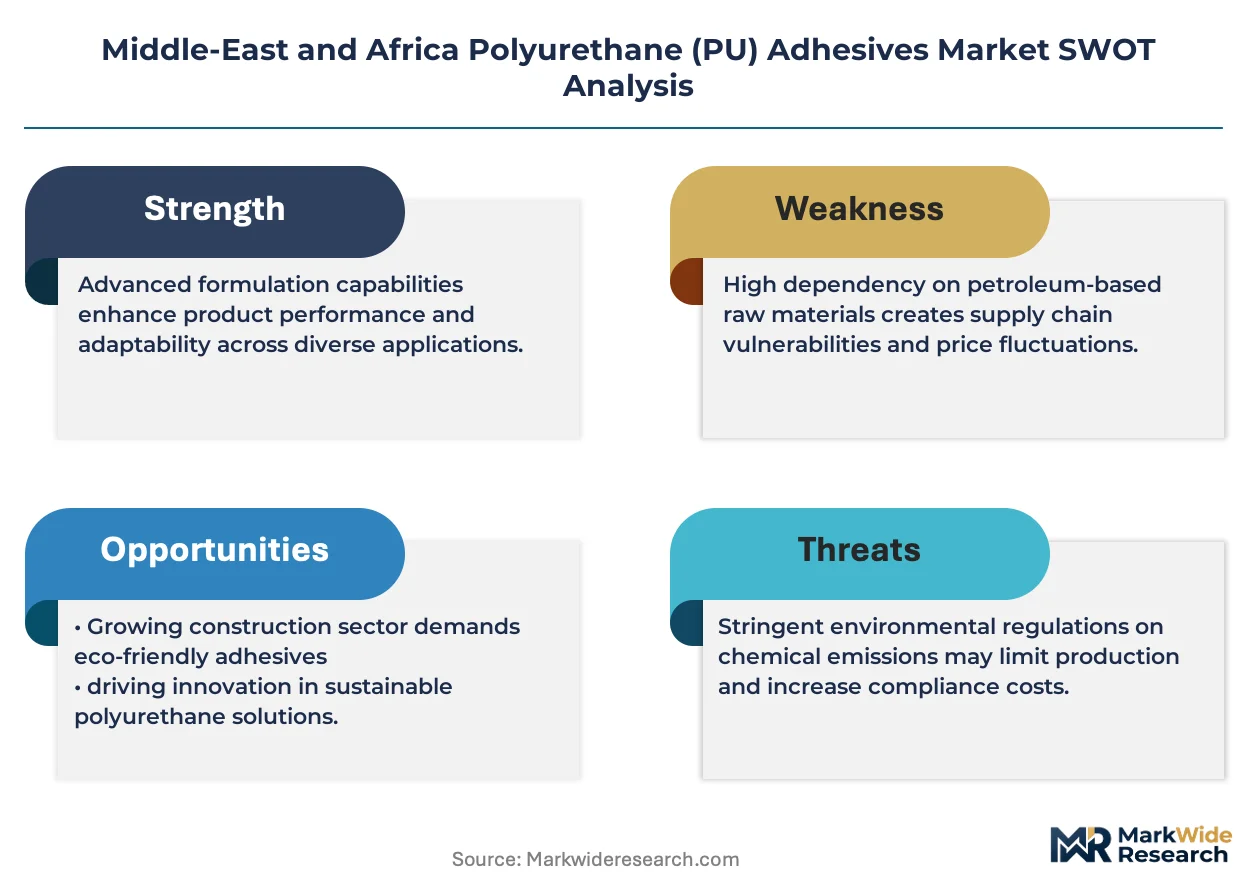
Epoxy resin is repositioning cost structures across select bonding applications, yet polyurethane chemistry retains decisive advantages in flexibility and cure-speed for Middle-East and Africa construction workflows. BASF SE leverages its Ludwigshafen-derived polymer expertise to supply tailored aliphatic prepolymers for Gulf climate exposure. SABIC anchors regional feedstock security through its Yanbu petrochemical complex, converting captive MDI and polyol streams into adhesive-grade intermediates. Henkel AG & Co. KGaA differentiates via automated dispensing systems integrated into Saudi automotive assembly lines.
Middle-East and Africa Polyurethane (PU) Adhesives are thermosetting polymers formed by reacting isocyanate-bearing compounds with hydroxyl-functional polyols, yielding cured films with Shore A hardness ranging from 20 to 90 depending on formulation architecture. These systems bond dissimilar substrates—metal to concrete, rubber to composite—through carbamate linkages that resist thermal cycling from desert peak temperatures to conditioned interiors. Flexible product types dominate volume in the region's construction expansion, where elongation properties accommodate structural movement in high-rise glazing and infrastructure joints. Hot-melt variants represent the fastest-growing application segment, driven by packaging line retrofits in South African food processing and Egyptian textile manufacturing where instant green strength eliminates clamping stages. Structural adhesives concentrate margin pools in UAE aerospace maintenance and Saudi rail fabrication, where certified load-bearing performance commands specification premiums.
Saudi Standards, Metrology and Quality Organization (SASO) building codes mandate VOC thresholds and fire-performance ratings that filter adhesive qualification lists for giga-project procurement. South African National Standards (SANS) and UAE Civil Defence certification protocols create parallel compliance tracks, with the latter requiring third-party flame-spread testing for interior applications. REACH-aligned substance restrictions emerging from Gulf Cooperation Authority technical committees are forcing reformulation of aromatic isocyanate systems ahead of anticipated harmonization. Stakeholders must monitor regulatory divergence between national standards bodies and the pace of GCC-wide chemical registration to anticipate qualification cost shifts.
Market Dynamics
Saudi giga-projects are compressing qualification timelines for adhesive suppliers, forcing simultaneous compliance with SASO fire-performance mandates and accelerated construction schedules that reward cure-speed over legacy bonding chemistries.
Growth Catalysts
- SASO VOC thresholds:Saudi building codes are filtering out solvent-based competitors and opening specification slots for low-emission polyurethane systems in Neom and Red Sea Project contracts.
- Hot-melt packaging retrofits:South African food processors are eliminating clamping stages through reactive PUR hot-melts that cut line changeover times.
- UAE aerospace maintenance:Certified structural adhesives command specification premiums in Dubai and Abu Dhabi MRO facilities serving wide-body fleets.
Market Restraints
- MDI feedstock concentration:Yanbu and Jubail petrochemical complexes control regional isocyanate supply, exposing formulators to single-source disruption risk.
- Epoxy substitution in electronics:Rigid PCB bonding is shifting toward epoxy systems where flexibility offers no performance advantage.
- REACH-aligned GCC registration:Anticipated harmonization of aromatic isocyanate restrictions is forcing costly reformulation ahead of certain demand.
Strategic Opportunities
- Egyptian textile manufacturing:Reactive hot-melt penetration remains below construction levels, offering volume expansion in Cairo and Alexandria garment assembly.
- Green building incentives:UAE Al Sa'fat and Saudi Mostadam certification programs are creating specification pull for low-carbon adhesive systems.
- Digital dispensing integration:Automated meter-mix equipment combined with IoT monitoring is enabling predictive maintenance contracts in automotive assembly.
Industry Challenges
- Formulation chemist scarcity:Gulf universities produce limited polymer science graduates, forcing reliance on expatriate talent with restricted mobility.
- SANS-SASO divergence:Parallel South African and Saudi certification tracks multiply testing costs for suppliers serving both markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Polyurethane (PU) Adhesives Market |
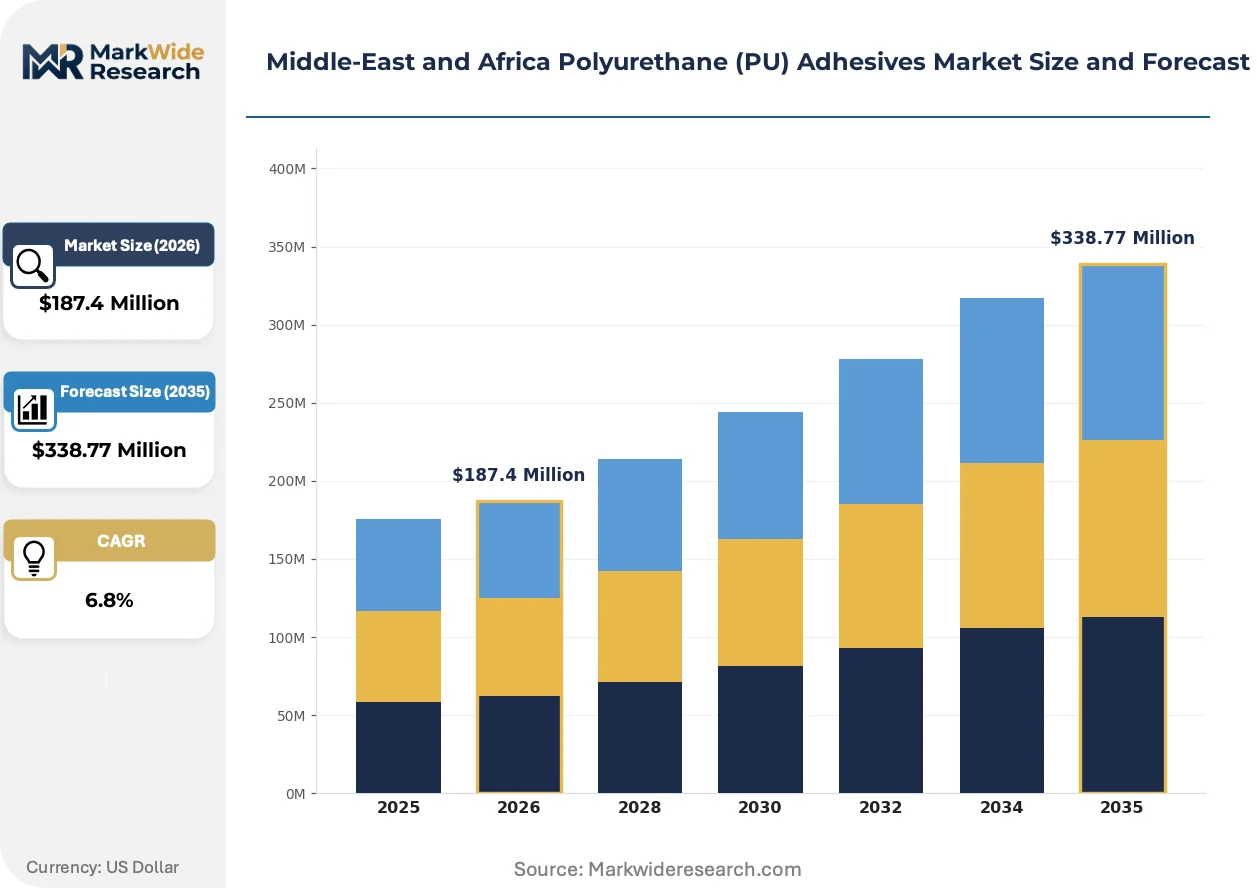
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible, Rigid, Hot-Melt, Structural Application: Construction, Automotive, Packaging, Woodworking End User: Manufacturers, Contractors, Distributors, Retailers Distribution Channel: Online, Offline, Direct Sales, Wholesalers |
| Companies Covered | BASF SE, Covestro AG, Dow Inc., Huntsman Corporation, Henkel AG & Co. KGaA, H.B. Fuller Company, Arkema, Sika AG, Saudi Basic Industries Corporation (SABIC), Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Polyurethane (PU) Adhesives Market Shifts & Advancements
Automation and regulatory convergence are compressing product development cycles while shifting competitive advantage toward integrated dispensing-chemistry systems rather than standalone adhesive supply.
Robotic dispensing paired with inline viscosity monitoring is automating adhesive application in Saudi automotive plants, where Henkel and local integrators are retrofitting assembly lines for meter-mix-deposit sequences that eliminate manual mixing errors and reduce material waste by tightening shot-size precision.
REACH-aligned substance restrictions emerging from Gulf Cooperation Authority technical committees are forcing aromatic isocyanate phaseouts ahead of formal harmonization, with formulators in Dubai and Jeddah accelerating aliphatic prepolymer development to maintain qualification status for interior applications under UAE Civil Defence flame-spread protocols.
Specification decisions are migrating from procurement departments to ESG compliance officers in UAE and Saudi commercial construction, where LEED-equivalent certifications and project finance green covenants are elevating low-VOC adhesive systems above price-competitive alternatives in giga-project bid evaluations.
Middle-East and Africa Polyurethane (PU) Adhesives Market Segmentation
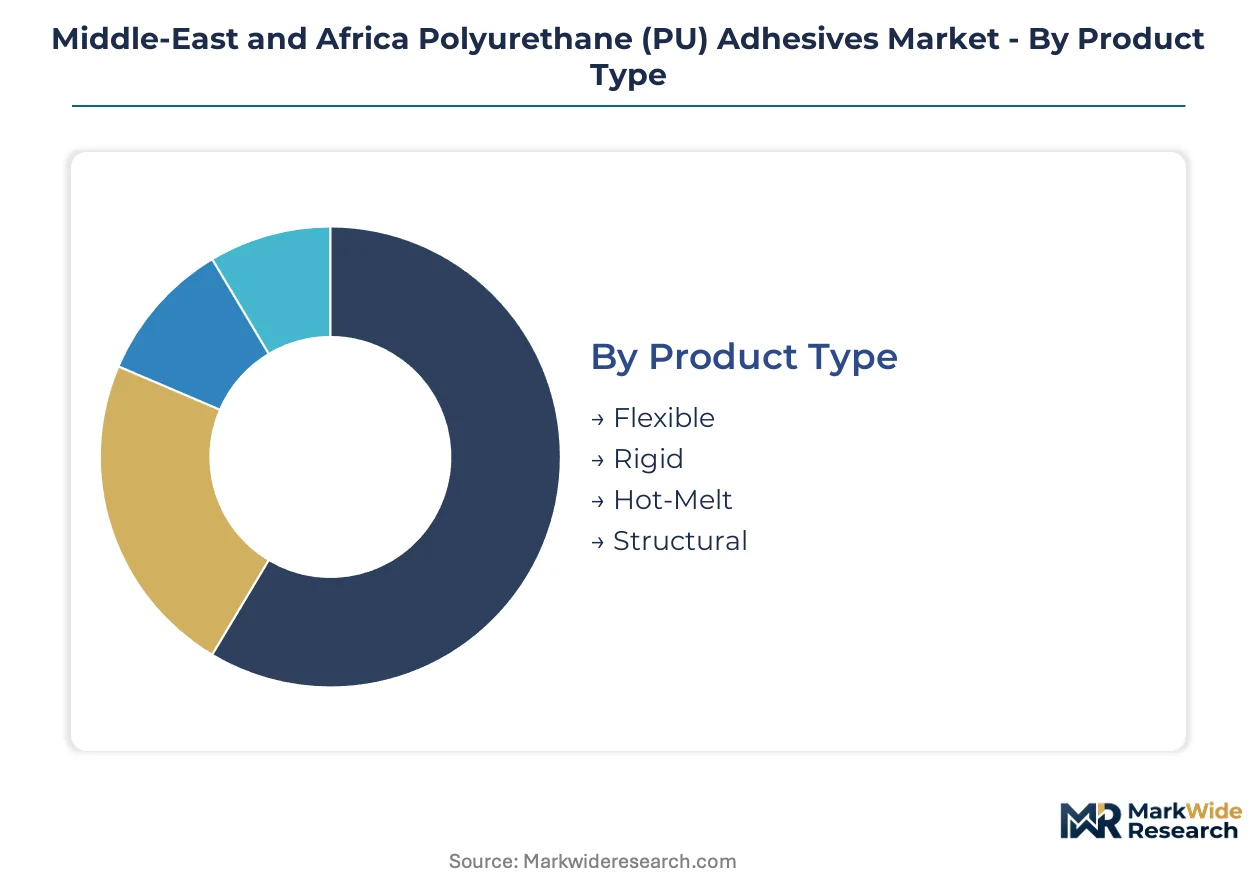
Polyurethane adhesive formulations diverge sharply across Middle-East and Africa construction workflows, with cure-speed requirements and substrate compatibility driving specification splits. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume commoditization threatens returns.
Product Type:
Supply concentration in Saudi MDI feedstock streams shapes which chemistries achieve cost-competitive scale across the region's formulator base.
- Flexible:Elongation properties exceeding 200% accommodate thermal cycling in Saudi high-rise glazing and UAE infrastructure expansion joints. Demand concentrates in Neom and Red Sea Project contracts where structural movement tolerance outweighs load-bearing requirements.
- Hot-Melt:Reactive PUR systems deliver instant green strength without clamping stages, penetrating South African food packaging lines and Egyptian textile assembly where line speed determines procurement decisions. This segment is gaining share fastest as automation retrofits accelerate.
- Rigid:Shore D hardness formulations serve concrete repair and composite panel bonding in UAE commercial construction.
- Structural:Certified load-bearing systems command specification premiums in Saudi rail fabrication and Dubai aerospace MRO facilities.
Today's leader: Flexible. Tomorrow's challenger: Hot-Melt.
Application:
Cost tier stratification separates specification-grade systems from commodity formulations across end-use verticals.
- Construction:SASO fire-performance mandates and VOC thresholds filter qualification lists for Saudi giga-projects, elevating low-emission polyurethane systems above solvent-based alternatives in Neom procurement.
- Packaging:South African food processors and Egyptian garment manufacturers drive reactive hot-melt penetration where line changeover efficiency trumps per-unit adhesive cost.
- Automotive:Henkel's automated dispensing integration in Saudi assembly lines favors meter-mix-deposit systems over manual application methods.
- Woodworking:Furniture manufacturing in Morocco and Tunisia maintains steady demand for moisture-cure systems in panel bonding applications.
Construction commands current volume. Packaging shows the steepest expansion trajectory.
End User:
Volume concentration among Saudi and UAE project owners determines formulation development priorities for regional suppliers.
- Contractors:Giga-project procurement departments in Saudi Arabia compress qualification timelines while demanding simultaneous SASO compliance and accelerated cure schedules.
- Manufacturers:South African food processors and Egyptian textile operations specify reactive hot-melts based on line integration requirements rather than standalone adhesive performance.
- Distributors:Regional stockists in Dubai and Jeddah manage inventory complexity across SANS-SASO divergence in certification requirements.
- Retailers:Hardware channels in secondary African markets serve maintenance and repair demand with general-purpose formulations.
Contractors dominate premium specification. Manufacturers drive standardization.
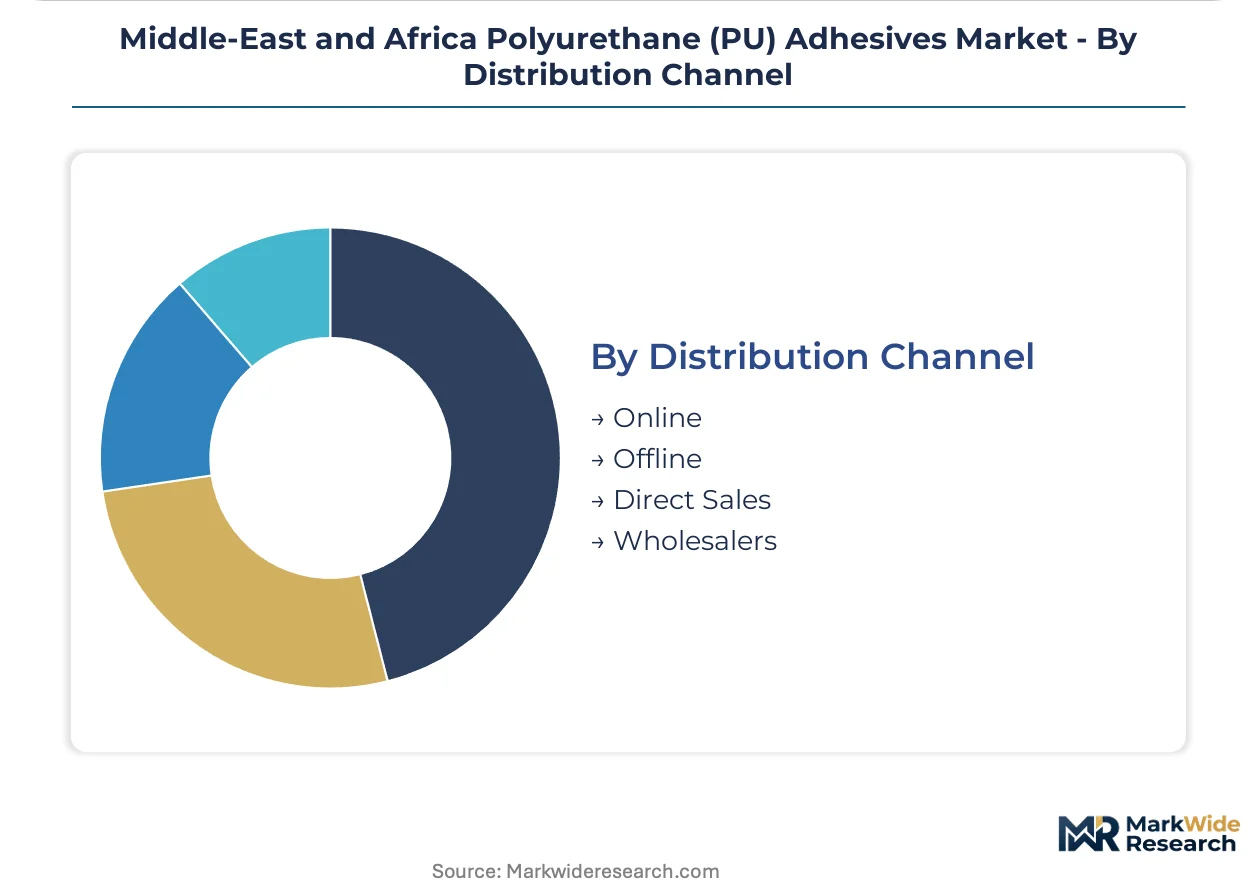
Distribution Channel:
Customer type fragmentation between project-scale procurement and maintenance/repair demand shapes channel configuration.
- Direct Sales:BASF and SABIC supply aliphatic prepolymers and adhesive-grade intermediates directly to Saudi giga-project formulators, bypassing distributor margins for high-volume contracts.
- Wholesalers:Regional stockists in Johannesburg and Cairo aggregate demand from mid-tier contractors serving SANS-compliant building activity.
- Offline:Traditional trade counters remain dominant for specification-grade construction adhesives requiring technical consultation.
- Online:E-commerce penetration lags in technical adhesive categories but gains traction in standard woodworking and packaging grades.
Direct sales capture strategic accounts. Wholesalers defend mid-market position.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yanbu petrochemical complexes anchor isocyanate supply security across the Middle-East and Africa PU adhesives landscape. National standards divergence between SASO and SANS protocols fragments qualification pathways for multi-market suppliers. Construction acceleration in Gulf giga-projects compresses procurement timelines while elevating fire-performance mandates.
Saudi Arabia
Neom and Red Sea Project contracts drive specification-grade adhesive demand for high-rise glazing and infrastructure joints. SASO building codes mandate VOC thresholds and flame-spread ratings that filter supplier qualification lists. Riyadh-based procurement departments compress vendor onboarding timelines to match accelerated construction schedules.
United Arab Emirates
Dubai and Abu Dhabi aerospace MRO facilities command certified structural adhesives for wide-body fleet maintenance. UAE Civil Defence certification requires third-party flame-spread testing for interior applications. Jebel Ali industrial zones concentrate formulator activity serving commercial construction and aviation maintenance clusters.
South Africa
Johannesburg food processors specify reactive hot-melt systems to eliminate clamping stages in packaging line retrofits. SANS building standards reshape product formulation requirements for construction adhesives serving compliant building activity. Cape Town distributors manage inventory complexity across divergent national certification tracks.
Egypt
Cairo and Alexandria garment manufacturers represent underpenetrated demand for reactive PUR hot-melts in textile assembly operations. The country's national standards body maintains parallel compliance frameworks with Gulf technical committees. Nile Delta industrial zones concentrate packaging and apparel manufacturing driving line-speed adhesive specifications.
Qatar
Lusail City development and FIFA legacy infrastructure sustain construction adhesive demand for commercial and residential building. The national civil defense authority enforces fire-performance protocols aligned with GCC harmonization trajectories. Doha-based contractors source flexible polyurethane systems for high-rise glazing accommodating thermal cycling.
Middle-East and Africa Polyurethane (PU) Adhesives Market Competitive Landscape
Global majors compete with regional champions across feedstock security and formulation specialization vectors. The vendor base splits between petrochemical-integrated suppliers controlling MDI supply chains and independent formulators competing on cure-speed customization. Three archetypes dominate: integrated petrochemical producers with captive isocyanate streams, European chemical conglomerates leveraging polymer science expertise, and regional distributors managing SANS-SASO certification complexity. Capacity expansion in Yanbu and strategic partnerships for automated dispensing integration represent the dominant competitive moves.
Within the integrated producer tier, Saudi Basic Industries Corporation anchors regional feedstock security through Yanbu petrochemical complexes. BASF SE and Henkel AG & Co. KGaA exemplify European conglomerate archetypes, with the latter representing automated dispensing-chemistry integration in Saudi automotive assembly. Covestro AG occupies a position among specialty chemical players leveraging aliphatic prepolymer development for Gulf climate exposure.
| Leading Market Players |
|---|
| BASF SE |
| Covestro AG |
| Dow Inc. |
| Huntsman Corporation |
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Arkema |
| Sika AG |
| Saudi Basic Industries Corporation (SABIC) |
| Others |
Supply & Pricing Matrix
Certification-grade stratification between SASO-compliant structural systems and general-purpose formulations splits both margin capture and sourcing strategies across Middle-East and Africa PU adhesives. This divergence channels premium procurement toward Yanbu-integrated suppliers with captive MDI streams while relegating commodity buyers to distributor-mediated supply with exposed logistics costs.
Pricing Analysis
Input-cost pass-through from MDI and polyol feedstock volatility anchors pricing dynamics for regional formulators. Project-based long-term contracts dominate Saudi giga-project procurement, insulating qualified suppliers from spot-market swings while exposing non-integrated competitors to margin compression. Price differentiation centers on SASO fire-performance certification tier and volume scale, with aerospace-grade structural adhesives commanding the widest premiums. Cost compression in flexible construction-grade formulations is intensifying as epoxy substitution pressures commodity polyurethane positioning. Contractors represent the most price-sensitive buyer archetype, whereas UAE aerospace MRO facilities exhibit minimal sensitivity due to certified-performance lock-in.
Supply Chain Analysis
Isocyanate supply rests on Saudi Arabia's Yanbu and Jubail petrochemical complexes, with secondary sourcing concentration in Germany and Belgium for specialty aliphatic prepolymers. Raw material dependencies center on MDI, polyether polyols, and catalyst packages, with formulation-grade additives drawing from Swiss and Japanese specialty chemical producers. Single-source vulnerability around Yanbu MDI output exposes regional formulators to disruption risk from feedstock concentration. Distribution runs through direct sales channels for high-volume Saudi construction contracts, while Johannesburg and Cairo wholesalers aggregate fragmented mid-tier demand across SANS-compliant markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in aliphatic prepolymer development and automated dispensing integration, as green-building certification premiums offset feedstock cost volatility through specification lock-in.
For Market Incumbents: To counter epoxy substitution in rigid bonding applications, BASF and SABIC should deepen backward integration into specialty polyol production and expand meter-mix-deposit system partnerships with Saudi automotive integrators. Certification investment in UAE Civil Defence flame-spread protocols and SASO VOC compliance represents the critical defensive lever for maintaining giga-project qualification status. For New Entrants and Emerging Players: Launch via reactive hot-melt distribution partnerships with Egyptian textile manufacturers and South African food packaging OEMs, where line-speed specifications outrank brand loyalty. Cairo and Alexandria garment assembly operations offer the most penetrable white-space target, with technical service bundling as the preferred go-to-market angle against established construction-focused incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where SANS-SASO certification divergence multiplies compliance costs for sub-scale formulators lacking integrated feedstock positions. Mid-tier distributors with established relationships across both South African and Gulf procurement channels represent the optimal acquisition archetype. Watch for REACH-aligned GCC harmonization announcements as the inflection signal triggering forced seller dynamics among aromatic isocyanate-dependent formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Polyols | SABIC's Yanbu expansion secures formulation-grade feedstock independence from European additive suppliers. |
| Automated Dispensing System Partnership | Henkel's Saudi automotive integration eliminates manual mixing errors and tightens shot-size precision. |
| Aliphatic Prepolymer Capacity Buildout | BASF's Ludwigshafen-derived chemistry addresses UAE Civil Defence interior application mandates. |
| Long-term Supply Agreement | Direct sales contracts with Neom procurement departments bypass distributor margins for volume certainty. |
| Green Certification Program | Mostadam and Al Sa'fat compliance creates specification pull for low-VOC systems in premium construction. |
Research Methodology
Multiple input streams — primary interviews with plant managers at Saudi formulators, procurement leads at UAE aerospace MRO facilities, and distribution channel partners in Johannesburg — were reconciled against customs data, SANS and SASO regulatory filings, and SEC disclosures from listed chemical conglomerates. Bottom-up volume estimates from end-use application splits were cross-validated against top-down feedstock consumption patterns reported by Yanbu petrochemical complexes.
Historical volume trajectories were cross-referenced against expert panel assessments of construction acceleration timelines and regulatory harmonization pace. Segmentation modeling incorporated product type flexibility, application vertical, end-user procurement archetype, and regional certification cluster across the projection horizon. CAGRs were derived from weighted scenario analysis incorporating MDI capacity expansion schedules and green-building incentive adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated epoxy substitution or prolonged SANS-SASO divergence. Assumptions regarding REACH-aligned GCC implementation timing and giga-project completion schedules inform the projection framework. A small set of triggers — regulatory harmonization announcements, Yanbu capacity disruption events, and aerospace MRO contract awards — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
2K Epoxy Adhesives Market
Adhesives & Sealants
Vietnam Construction Chemicals Market
Adhesives & Sealants
High Strength Laminated Adhesives Market
Adhesives & Sealants
Asia-Pacific Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Conductive Glue Market
Adhesives & Sealants
North America Flock Adhesives Market
Adhesives & Sealants
Windscreen Adhesive Market
Adhesives & Sealants
United States Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
High Temperature Adhesives Market
Adhesives & Sealants
South America Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Saudi Arabia Sealants Market
Adhesives & Sealants
Global Acrylic Adhesives Market
Adhesives & Sealants
Spain Sealants Market
Adhesives & Sealants
Construction Repair and Rehabilitation Chemicals Market
Adhesives & Sealants
Melamine Formaldehyde (MF) Market
Adhesives & Sealants
North America Human Fibrin Glue Market