
 South America Acrylic Adhesives Market | 2026-2036
South America Acrylic Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
South America Acrylic Adhesives Market Analytics
Buyer concentration across South America's packaging converters is broadening as mid-sized flexographic printers in Brazil and Argentina diversify adhesive sourcing. Henkel AG & Co. KGaA leverages its São Paulo technical center to anchor water-based formulation leadership. 3M competes through tape-grade acrylic portfolios targeted at electronics assemblers. Sika AG dominates construction-grade applications with project-specified bonding systems.
Acrylic adhesives are thermoplastic resins formulated from acrylic monomers that polymerize through free-radical mechanisms, delivering bonds with glass-transition temperatures typically spanning minus forty to plus one hundred twenty degrees Celsius. These adhesives serve primary industrial functions in structural assembly, pressure-sensitive lamination, and permanent labeling across manufacturing environments. Water-based acrylics lead volume consumption due to lower volatile organic compound profiles and compatibility with Brazil's tightening industrial emission protocols. UV-cured formulations represent the fastest-expanding type category as electronics manufacturers in São Paulo adopt rapid-cure lines for smartphone and wearable component assembly. Solvent-based acrylics retain margin concentration in specialty tape applications where immediate tack and solvent resistance justify higher formulation costs.
ANVISA regulates chemical substance notification and toxicity thresholds for adhesive formulations sold into Brazilian healthcare and consumer applications. Brazil's CONAMA resolutions and Argentina's Secretariat of Environment enforce volatile organic compound limits that push manufacturers toward water-based and hot-melt technologies. REACH-aligned standards in Mercosur trade discussions signal future convergence with European chemical disclosure frameworks. Stakeholders must monitor regulatory harmonization timelines and position formulation portfolios for cross-border certification requirements.
Market Dynamics
Water-based acrylic formulations are displacing solvent-bonding systems across Brazilian automotive assembly lines as ANVISA tightens emission disclosure thresholds, compressing formulation timelines and forcing raw-material substitution at São Paulo adhesive plants.
Growth Catalysts
- Automotive Lightweighting Mandates:Brazilian OEMs are bonding aluminum-intensive body structures with structural acrylics to meet fuel-efficiency targets, pulling volume through Minas Gerais assembly corridors.
- ANVISA Registration Harmonization:The agency's REACH-aligned toxicity notification framework is accelerating cross-border certification for Mercosur adhesive suppliers, reducing duplicate testing costs.
- UV-Cure Electronics Bonding:Smartphone assemblers in São Paulo's industrial belt are retrofitting production lines with rapid-cure acrylic systems for wearable component lamination.
Market Restraints
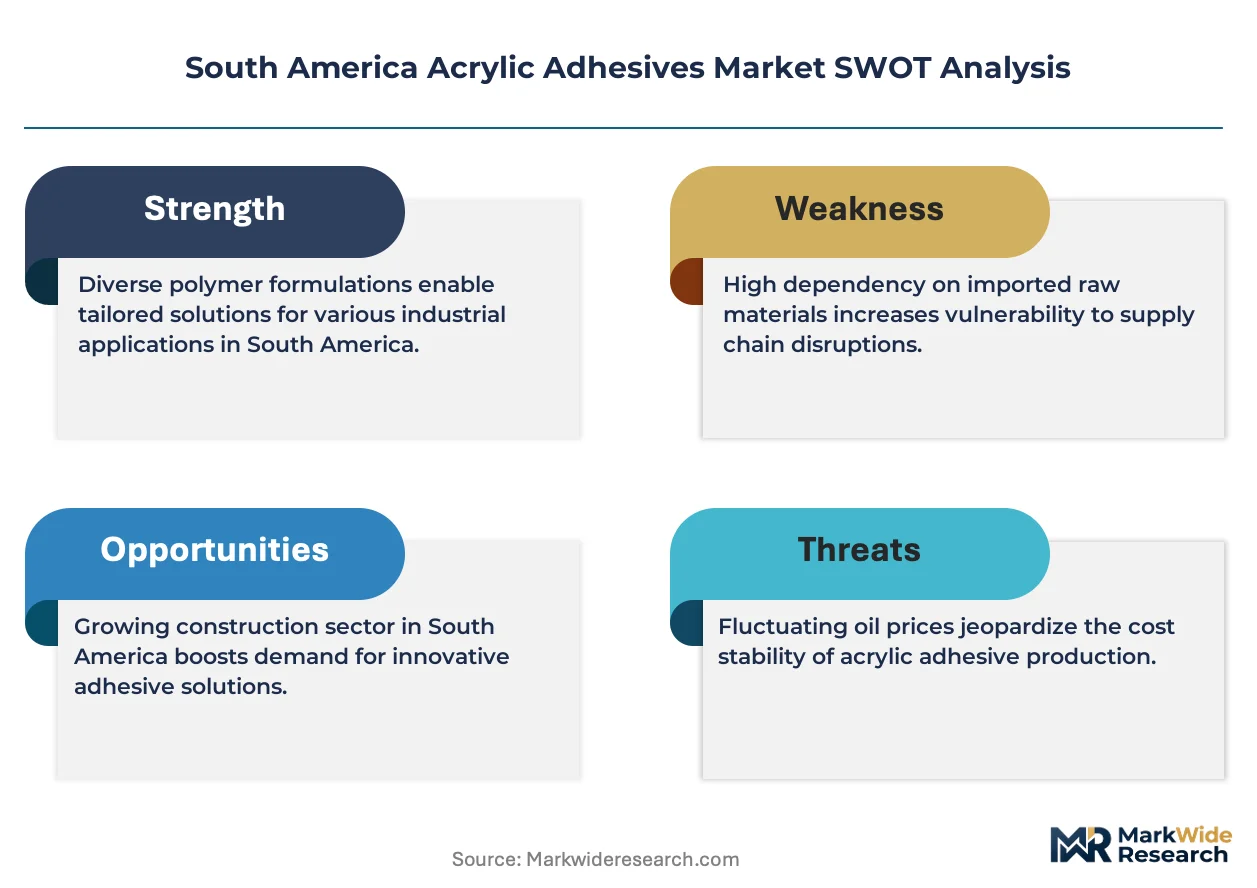
- Petrochemical Feedstock Volatility:Acrylic acid and methyl methacrylate prices track naphtha spreads at Brazilian refineries, compressing formulation margins during crude price spikes.
- Import Concentration in Specialty Monomers:High-purity functional monomers for medical-grade adhesives flow through single-port logistics at Santos, creating single-point vulnerability.
- Solvent Resistance Limitations:Water-based acrylics fail in hydrocarbon-exposure environments, preserving solvent-bonding demand in offshore equipment maintenance despite regulatory pressure.
Strategic Opportunities
- Argentine Packaging Converter Expansion:Mid-sized flexographic printers in Buenos Aires and Córdoba provinces are diversifying adhesive sourcing away from dominant Brazilian suppliers.
- Hot-Melt Formulation Convergence:Hybrid acrylic-block copolymer systems are penetrating bookbinding and woodworking applications previously served by EVA adhesives.
- CONAMA Resolution 491 Compliance Services:VOC monitoring and emission reporting consultancy represents adjacent revenue for adhesive distributors with in-house analytical capabilities.
Industry Challenges
- Formulation Chemist Scarcity:Brazilian universities graduate fewer polymer synthesis specialists than industrial demand requires, elongating R&D cycle times at adhesive plants.
- Legacy Equipment Retrofit Costs:Converting solvent-based coating lines to water-borne or UV-cure systems demands capital outlays that mid-sized Argentine converters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Acrylic Adhesives Market |
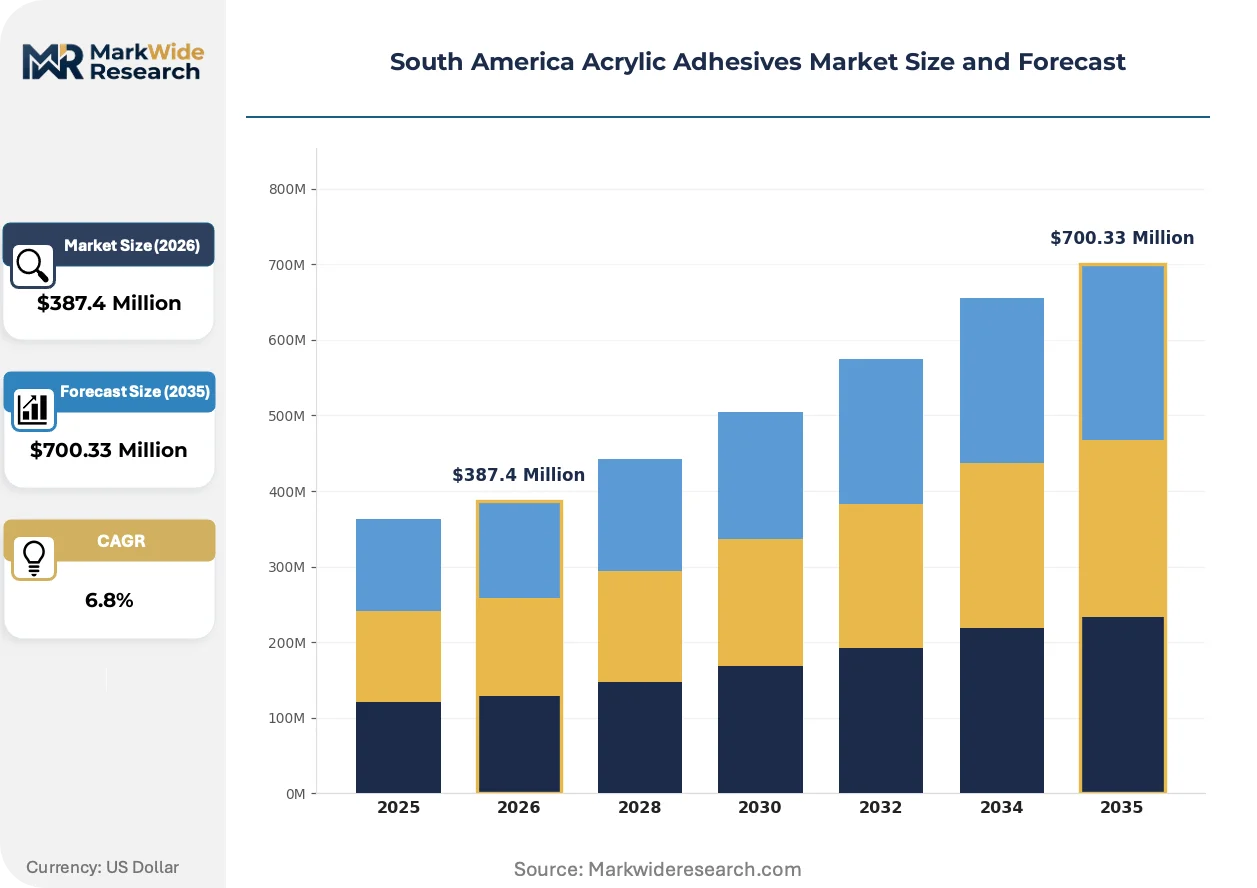
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $700.33 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Automotive, Construction, Electronics, Packaging Type: Water-Based, Solvent-Based, Hot Melts, UV-Cured End User: Manufacturing, Retail, Healthcare, Aerospace Form: Liquid, Gel, Tape, Granules |
| Companies Covered | 3M, Henkel AG & Co. KGaA, Sika AG, Arkema Group, H.B. Fuller Company, Avery Dennison Corporation, Dow, Ashland, Bostik, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Acrylic Adhesives Market Evolving Landscape
Acrylic adhesive technology is bifurcating between ultra-rapid cure systems for electronics and bio-based monomer pathways for packaging, with regulatory pressure acting as the pivot mechanism between the two trajectories.
UV-LED curable acrylic formulations are absorbing demand from thermal-cure systems in São Paulo electronics assembly plants. Smartphone and wearable manufacturers are retrofitting bonding stations with 395-nanometer LED arrays to achieve three-second tack-free cure cycles. This shift is absorbing capital that previously flowed into solvent-recovery infrastructure, compressing the installed base of conventional coating equipment.
ANVISA's chemical substance notification requirements are tightening formulation disclosure standards for adhesives sold into Brazilian healthcare applications. The agency's 2024 toxicity threshold reductions are forcing reformulation of medical-grade skin-contact tapes and wound-care products. Manufacturers are responding by pre-registering alternative monomer feedstocks to avoid supply interruption during regulatory transition periods.
Mid-sized Argentine packaging converters are consolidating adhesive procurement through distributor-managed inventory programs rather than direct mill relationships. Buenos Aires-based flexographic printers are outsourcing formulation selection and just-in-time delivery to regional chemical distributors with technical service capabilities. This pattern is most visible in the corrugated board segment, where converter margins cannot support dedicated polymer scientists.
South America Acrylic Adhesives Market Segmentation
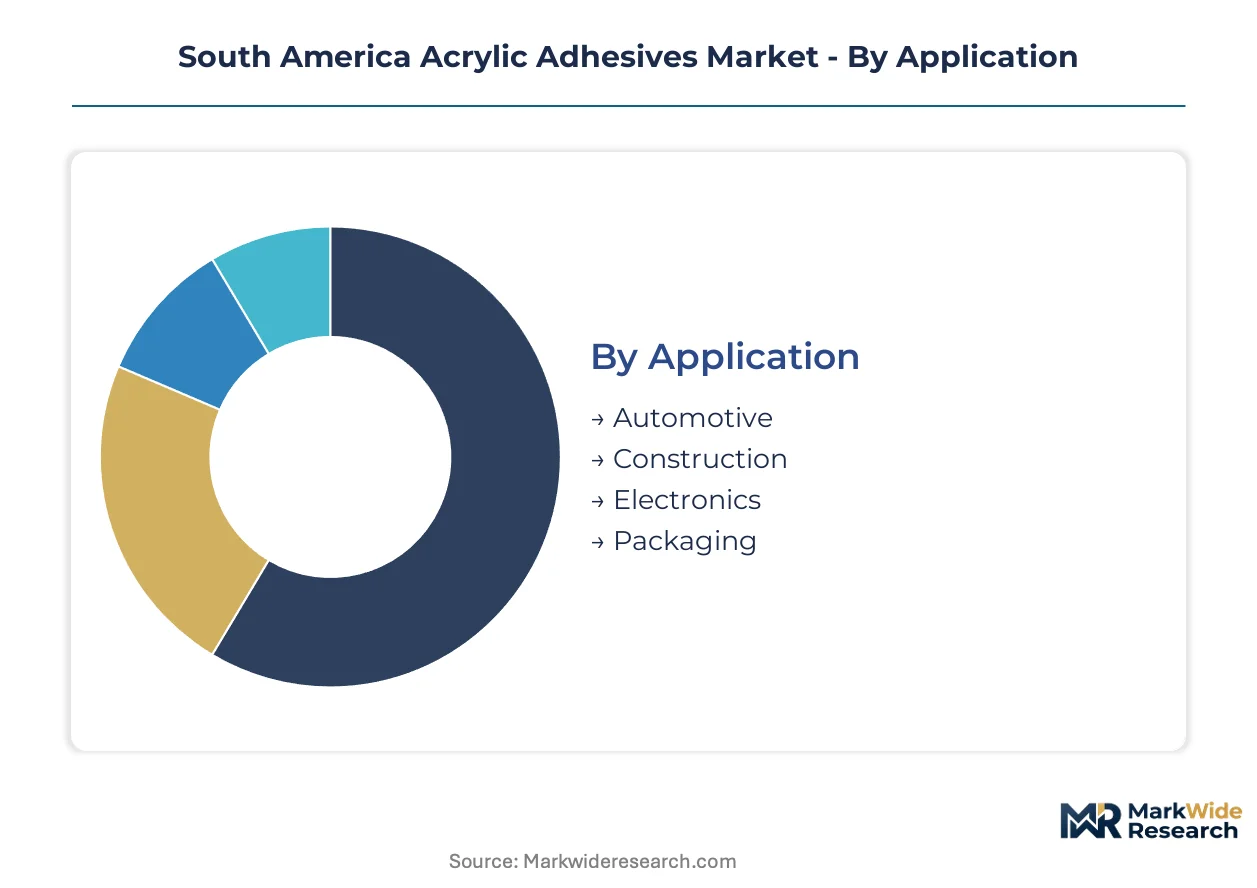
Acrylic adhesive buyers across South America fragment sharply by cure chemistry and substrate compatibility, with Brazilian automotive OEMs and São Paulo electronics assemblers driving divergent specification requirements. Segment boundaries increasingly blur as hybrid formulations penetrate cross-application demand.
Application:
Automotive and construction buyers prioritize structural shear strength and environmental durability, while electronics and packaging converters optimize for cure speed and line throughput.
- Automotive:Structural acrylics formulated for aluminum and composite bonding dominate procurement from Minas Gerais assembly corridors. Brazilian OEMs specify these adhesives for body-in-white applications to meet fuel-efficiency mandates through lightweight material substitution.
- Construction:Project-specified bonding systems from Sika AG and regional suppliers anchor demand in Brazilian commercial building and Argentine infrastructure rehabilitation. ANVISA-compliant formulations for healthcare-adjacent construction are gaining specification share.
- Electronics:Rapid-cure acrylics serve smartphone and wearable lamination in São Paulo's industrial belt, with UV-LED compatibility now a standard tender requirement.
- Packaging:Water-based pressure-sensitive adhesives convert corrugated and flexible substrates for Brazilian food exporters and Argentine flexographic printers.
Volume sits with automotive and construction; growth tilts toward electronics as UV-cure retrofit accelerates.
Type:
Cure chemistry determines capital equipment compatibility and regulatory compliance trajectory, with water-based and UV-cured formulations capturing investment displaced from solvent infrastructure.
- Water-Based:Emulsion polymers with sub-fifty grams per liter VOC profiles lead Brazilian volume consumption. São Paulo adhesive plants are expanding water-borne capacity as ANVISA tightens emission disclosure thresholds for industrial coatings.
- UV-Cured:Photoinitiator-acrylate systems achieving three-second tack-free cure are retrofitting electronics assembly lines. This chemistry is climbing the fastest as smartphone manufacturers depreciate thermal-cure equipment.
- Solvent-Based:Retains margin concentration in specialty tape applications where immediate tack and hydrocarbon resistance justify higher formulation costs despite regulatory pressure.
- Hot Melts:Acrylic-block copolymer hybrids are penetrating bookbinding and woodworking applications previously served by EVA adhesives in Argentine converter facilities.
Water-based formulations anchor current procurement volumes; UV-cured systems command the steepest expansion trajectory through the forecast window.
End User:
Manufacturing and healthcare buyers operate under divergent regulatory intensities, with ANVISA registration requirements creating formulation moats around medical-grade applications.
- Manufacturing:Industrial assembly plants across São Paulo and Minas Gerais states specify structural and pressure-sensitive acrylics for bonding, lamination, and permanent labeling operations.
- Healthcare:Skin-contact tapes and wound-care adhesives face ANVISA toxicity threshold reductions, forcing pre-registration of alternative monomer feedstocks to avoid supply interruption.
- Retail:Consumer-grade adhesive products for DIY and home improvement applications distribute through Brazilian home-center chains and Argentine hardware cooperatives.
- Aerospace:Specialty structural films and paste adhesives serve maintenance-repair-overhaul operations at Brazilian commercial aviation facilities with stringent flame-resistance specifications.
Manufacturing absorbs the greatest adhesive tonnage; healthcare commands the highest formulation premiums per kilogram.
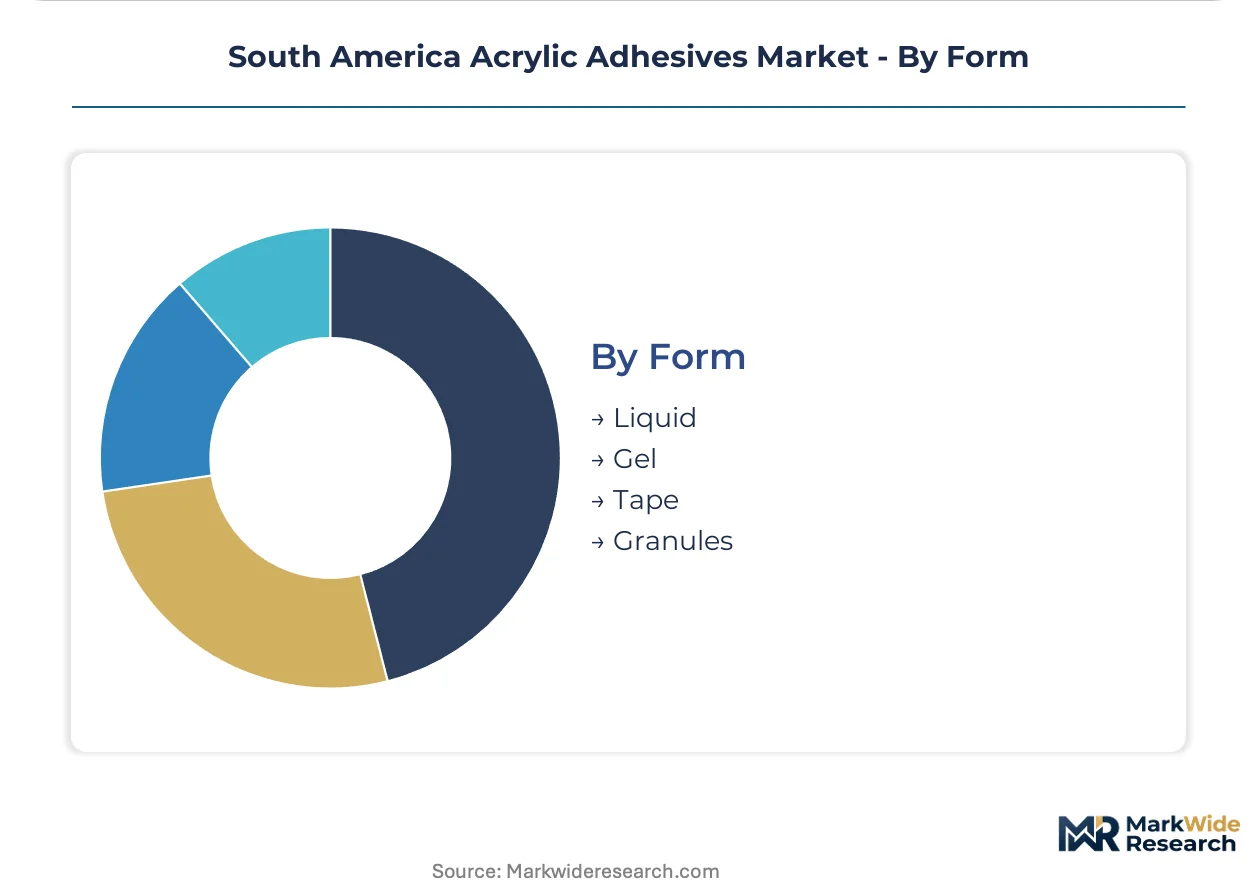
Form:
Physical delivery format determines application equipment requirements and inventory handling protocols, with liquid and tape forms dominating divergent end-use workflows.
- Liquid:Pumpable dispersions and 100-percent solids formulations feed automated dosing equipment in Brazilian automotive assembly and São Paulo electronics plants.
- Tape:Pressure-sensitive adhesive films on release liners serve electronics lamination and construction flashing applications with precise thickness control.
- Gel:Thixotropic formulations maintain position on vertical substrates for Brazilian infrastructure repair and offshore equipment maintenance.
- Granules:Solid pellet feedstocks supply hot-melt tank systems in Argentine packaging converter and woodworking facilities.
Liquid forms command the widest application breadth; tape formats generate the highest value per unit volume in electronics specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acrylic acid feedstock from Brazilian petrochemical complexes at Camaçari and Triunfo anchors South American adhesive production. Refinery naphtha spreads at these Atlantic coast facilities determine regional formulation economics. Argentine shale-gas-to-chemicals projects in Neuquén province aim to reduce import dependence for methyl methacrylate monomers.
Brazil
Minas Gerais automotive corridors absorb structural acrylics for aluminum-intensive vehicle bonding as OEMs pursue fuel-efficiency mandates. ANVISA toxicity notification requirements are tightening formulation disclosure standards for medical-grade adhesives. São Paulo's industrial belt hosts UV-cure retrofit programs at smartphone assembly plants.
Argentina
Buenos Aires flexographic printers diversify adhesive sourcing away from dominant Brazilian suppliers through distributor-managed inventory programs. The Secretariat of Environment enforces volatile organic compound limits that push converters toward water-based technologies. Córdoba province woodworking facilities adopt hybrid acrylic-block copolymer hot-melt systems.
Chile
Mining equipment maintenance operations in the Atacama Desert preserve solvent-based acrylic demand for hydrocarbon-exposure environments despite regulatory pressure. The National Environmental Commission monitors industrial emission protocols for adhesive applications in coastal manufacturing zones. Santiago packaging converters serve export-oriented fruit producers with pressure-sensitive labeling systems.
Colombia
Bogotá construction activity drives project-specified bonding systems for commercial building rehabilitation. The Ministry of Environment and Sustainable Development implements chemical substance registration frameworks aligned with regional Mercosur discussions. Medellín automotive component suppliers test structural acrylic formulations for lightweight assembly applications.
South America Acrylic Adhesives Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty formulation niches around bio-based monomers and rapid-cure electronics bonding. The South American acrylic adhesives market presents a tiered structure with multinational chemical conglomerates anchoring volume supply alongside regional distributors managing technical service relationships for mid-sized converters. Strategic archetypes include petrochemical-integrated formulators with captive monomer supply, application-focused specialists with in-house polymer synthesis capabilities, and distributor-technical service hybrids managing just-in-time inventory programs. Capacity expansion and portfolio diversification toward water-based and UV-cured formulations represent the dominant competitive moves as regulatory pressure intensifies.
Among diversified multinational suppliers, 3M, Henkel AG & Co. KGaA, and Sika AG exemplify distinct strategic positioning within this structure. 3M occupies a position emphasizing tape-grade and electronics-focused portfolios. Henkel AG & Co. KGaA represents the technical-center-driven formulation archetype with regional anchoring capabilities. Sika AG sits within the construction-grade project-specified systems tier, dominating infrastructure and commercial building applications through specification relationships with engineering firms and contractors.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| Sika AG |
| Arkema Group |
| H.B. Fuller Company |
| Avery Dennison Corporation |
| Dow |
| Ashland |
| Bostik |
| Others |
Value Network & Pricing Analysis
Captive acrylic acid production at Brazilian petrochemical complexes anchors formulation economics and insulates integrated suppliers from naphtha spread volatility. This backward integration into monomer supply concentrates pricing power among formulators with Atlantic coast production assets while forcing non-integrated competitors to absorb raw material cost swings through margin compression.
Pricing Analysis
Warranty and technical service bundling separates project-specified construction adhesives from commodity pressure-sensitive grades, with Sika AG and Henkel AG & Co. KGaA embedding application engineering into long-term supply contracts. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and ANVISA registration status, with medical-grade formulations commanding substantial premiums over industrial bonding systems. Cost compression in water-based emulsions is intensifying because São Paulo adhesive plants are expanding capacity faster than automotive demand growth. Mid-sized Argentine packaging converters exhibit the highest price sensitivity, deferring specification upgrades to preserve working capital.
Supply Chain Analysis
ANVISA's tightening domestic-content disclosure requirements for chemical registrations are reshaping sourcing patterns toward Brazilian-sourced monomer feedstocks. Acrylic acid and methyl methacrylate production concentrates in Brazil, with high-purity functional monomers for medical-grade applications drawing from specialized import channels through Santos port. Single-port logistics concentration creates vulnerability to customs delays and currency fluctuation exposure. Distribution runs through distributor-managed inventory programs for mid-sized converters, while automotive OEMs and electronics assemblers maintain direct mill relationships with technical service support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty monomer capacity constraints at Brazilian refineries prop pricing power for integrated formulators, creating a supply-constrained market structure favoring incumbent consolidation.
For Market Incumbents: Cement specification relationships with São Paulo electronics assemblers by retrofitting UV-LED cure technical service capabilities ahead of competitor capacity additions. Lock in long-term monomer offtake agreements with Camaçari and Triunfo petrochemical complexes to defend margin position against naphtha spread volatility. Prioritize ANVISA pre-registration of alternative bio-based monomer feedstocks to neutralize regulatory transition risk in medical-grade segments. For New Entrants and Emerging Players: E-commerce platform distribution routes into Argentine flexographic printer segments bypass entrenched Brazilian supplier relationships with lower customer acquisition costs. Target Córdoba province woodworking facilities with hybrid acrylic-block copolymer hot-melt formulations previously served by EVA adhesives. Pursue distributor partnership models with Buenos Aires-based technical service providers rather than direct sales force buildout. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by petrochemical-integrated conglomerates seeking downstream formulation capabilities. Long-term viability hinges on water-based and UV-cure technology portfolios aligned with CONAMA emission trajectory. Monitor ANVISA registration harmonization timelines with REACH standards as the inflection signal for cross-border consolidation activity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Captive acrylic acid production at Camaçari insulates margin from naphtha volatility. |
| UV-Cure Technical Center Expansion | São Paulo LED retrofit capabilities anchor electronics assembler specification relationships. |
| ANVISA Pre-Registration Investment | Alternative monomer feedstock registration neutralizes healthcare formulation disruption risk. |
| Distributor-Managed Inventory Programs | Just-in-time delivery partnerships penetrate Argentine mid-sized converter price sensitivity. |
| Joint Venture with Regional Petrochemicals | Triunfo complex partnerships secure methyl methacrylate supply for medical-grade expansion. |
Research Methodology
Trade databases, petrochemical industry association reports, and ANVISA chemical registration filings formed the secondary backbone for volume and value estimation. Primary interviews with adhesive plant managers, automotive OEM procurement leads, packaging converter operations directors, and distributor technical service heads validated formulation mix assumptions and capacity utilization rates. Bottom-up segment sizing triangulated against top-down petrochemical consumption data to reconcile production and demand perspectives.
Bottom-up modeling anchored forecast outputs, with top-down macroeconomic cross-checks for industrial production growth correlation. Segmentation dimensions span cure chemistry type, application end-use, physical form, and regulatory compliance tier across the analysis window. CAGRs derived from weighted average of historical trajectory and capacity expansion pipeline, with naphtha spread sensitivity and ANVISA registration timeline uncertainty incorporated as scenario variables.
Inputs from customs records and petrochemical trade flows were available through the study window; gaps in Argentine converter inventory data introduce uncertainty bands around packaging segment sizing. Forecasts reflect documented assumptions regarding regulatory harmonization pace and automotive lightweighting penetration. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Flooring Adhesive Market
Adhesives & Sealants
United Kingdom Adhesives Market
Adhesives & Sealants
Global Underfill Material Market
Adhesives & Sealants
Rubber-Based Adhesives Market
Adhesives & Sealants
Europe Bone Glue Market
Adhesives & Sealants
Malaysia Adhesives Market
Adhesives & Sealants
Restorative Materials and Bonding Agents Market
Adhesives & Sealants
Middle East and Africa Adhesives Market
Adhesives & Sealants
Nigeria Tile Adhesive Market
Adhesives & Sealants
North America Waterborne Adhesives Market
Adhesives & Sealants
Global Dental Adhesives and Sealants Market
Adhesives & Sealants
Latin America Adhesives and Sealants Market
Adhesives & Sealants
India Tile Adhesive Market
Adhesives & Sealants
China Construction Chemicals Market
Adhesives & Sealants
Emulsion Pressure Sensitive Adhesives Market
Adhesives & Sealants
Asia-Pacific Automotive Adhesives and Sealants Market