
 Europe Electronics Adhesives Market | 2026-2036
Europe Electronics Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electronics Adhesives Market Foresight
A capital-intensity divergence between integrated resin producers and formulation specialists is bifurcating competitive dynamics across the Europe Electronics Adhesives Market. Henkel AG & Co. KGaA leverages captive epoxy chemistry and European manufacturing scale to dominate automotive under-the-hood applications. Sika AG competes through silicone expertise anchored to Swiss R&D infrastructure and direct OEM relationships. Arkema SA differentiates via UV-curable acrylic platforms that reduce energy curing costs for consumer electronics assemblers.
Electronics adhesives are engineered bonding systems formulated from epoxy, silicone, acrylic, or polyurethane chemistries, designed to provide electrical insulation, thermal conductivity, or mechanical fixation at operating temperatures from minus forty to one hundred fifty degrees Celsius. These materials seal components against moisture ingress, dissipate heat from processors, and enable miniaturized device architectures where mechanical fasteners fail. Epoxy formulations command the largest volume share due to established supply chains and proven reliability in semiconductor packaging, though silicone adhesives represent the fastest-expanding category as electric vehicle inverters and battery management systems demand thermal stability beyond epoxy limits. Acrylic systems occupy a specialized niche in medical equipment where rapid UV curing supports cleanroom throughput constraints, while polyurethane paste grades sustain margin pools in industrial device repair services requiring manual application flexibility.
REACH registration requirements administered by ECHA restrict certain isocyanate and solvent constituents, compelling reformulation investments across European adhesive producers. The EU Green Deal and F-Gas Regulation progressively constrain volatile organic compound emissions and fluorinated greenhouse gas content in manufacturing processes, reshaping raw material sourcing for Dow Inc. and BASF SE operations based in Germany and the Netherlands. The Medical Device Regulation imposes biocompatibility testing burdens on adhesive suppliers to France's surgical equipment cluster. Stakeholders must monitor evolving ECHA substance restriction proposals and calibrate R&D portfolios between thermal performance and regulatory compliance before next-generation bonding specifications solidify across European automotive and medical OEM qualification programs.
Market Dynamics
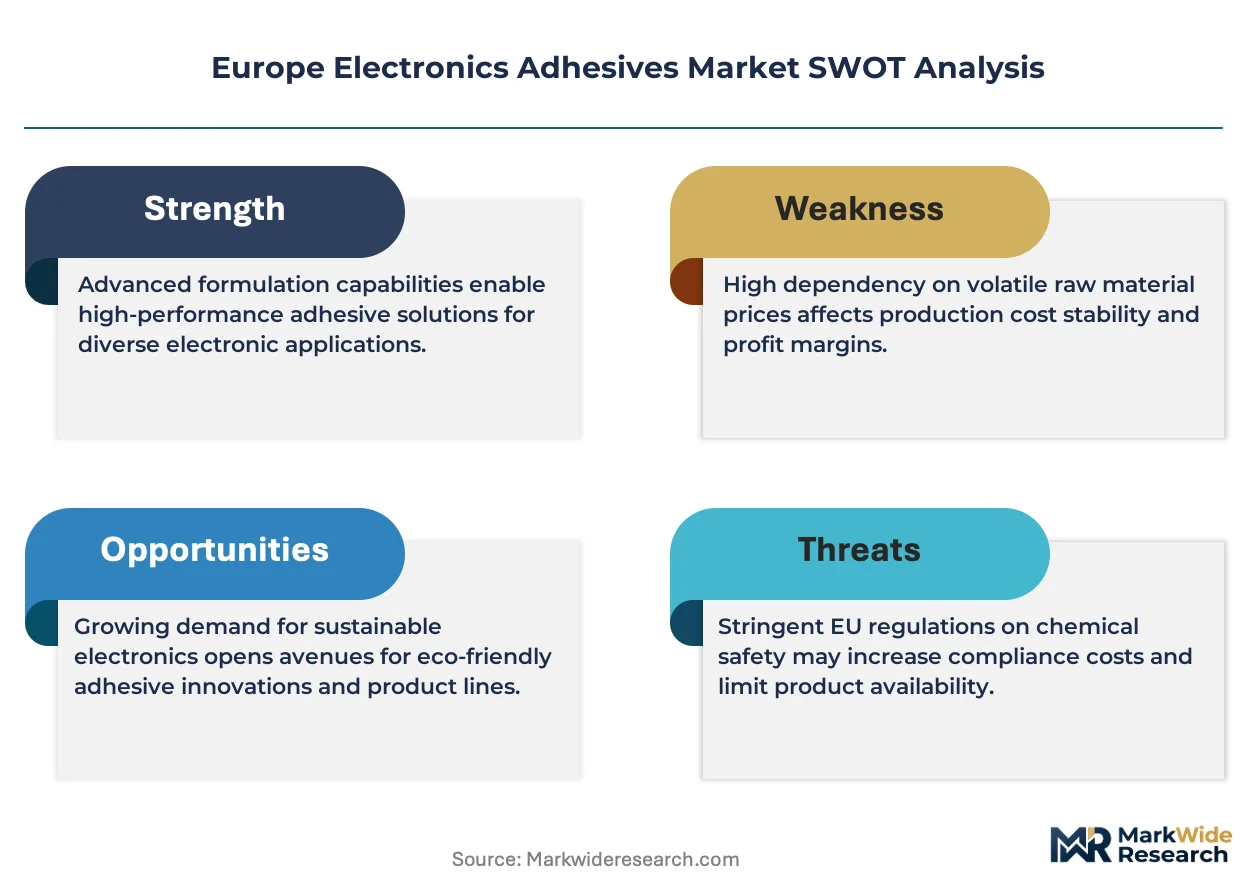
REACH substance restriction proposals and the EU Green Deal are forcing solvent-free reformulation across European adhesive producers, bifurcating capital allocation between integrated resin manufacturers and specialized formulators serving automotive and medical OEMs.
Growth Catalysts
- Electric powertrain assembly:Automotive electronics manufacturers in Germany and France are expanding adhesive procurement for battery management systems and inverter thermal management.
- REACH compliance deadlines:ECHA registration requirements are accelerating transitions to waterborne and UV-curable platforms ahead of substance restriction enforcement.
- Silicone chemistry advances:Formulators are deploying thermal-stable silicone adhesives that sustain operating temperatures beyond epoxy limits for EV power electronics.
Market Restraints
- Raw material concentration:Epoxy resin supply concentrates among integrated petrochemical producers in Germany and the Netherlands, creating input cost volatility for independent formulators.
- Technical performance ceilings:Acrylic adhesives face thermal conductivity limitations that constrain deployment in high-power semiconductor packaging applications.
- Regulatory friction:EU F-Gas Regulation compliance adds formulation complexity and extends qualification timelines for fluorinated polymer-containing products.
Strategic Opportunities
- Medical device cluster expansion:France's surgical equipment manufacturers present underpenetrated demand for biocompatible UV-curable adhesives under MDR compliance frameworks.
- Battery recycling integration:Adhesive suppliers can develop debondable chemistries that enable EU Battery Regulation-compliant end-of-life material recovery.
- Channel digitization:Direct technical sales platforms are displacing traditional distributor relationships for mid-volume electronics assemblers in Central Europe.
Industry Challenges
- Formulation chemistry expertise scarcity:European producers face recruitment gaps for polymer scientists capable of balancing thermal performance with REACH-compliant solvent elimination.
- Qualification timeline compression:Automotive OEMs are compressing adhesive validation cycles from 24 months to 12 months without relaxing reliability testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electronics Adhesives Market |
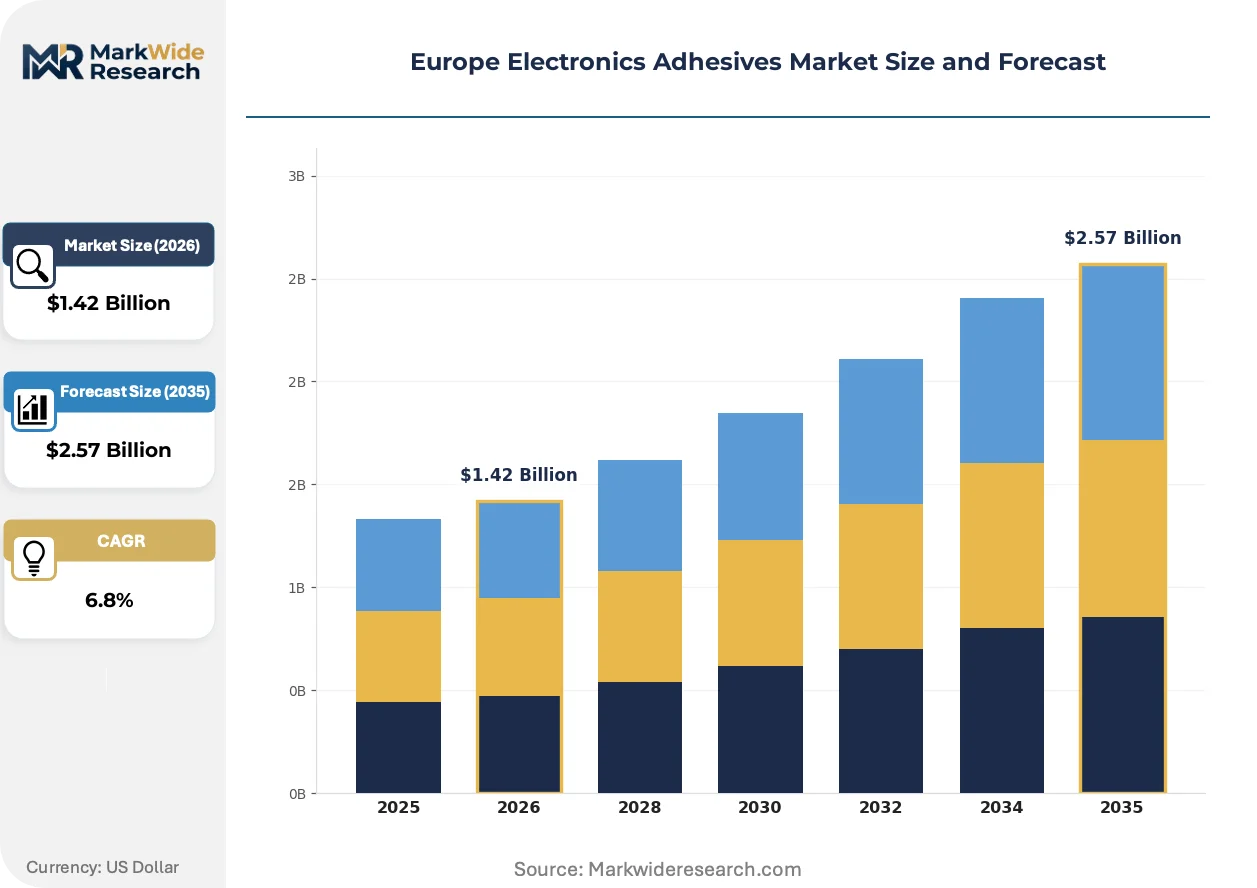
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Silicone, Acrylic, Polyurethane Application: Consumer Electronics, Automotive Components, Industrial Devices, Medical Equipment Form: Liquid, Paste, Tape, Film End User: Manufacturers, Assemblers, Repair Services, DIY Consumers |
| Companies Covered | Henkel AG & Co. KGaA, Sika AG, H.B. Fuller Company, 3M Company, BASF SE, Dow Inc., Arkema SA, Evonik Industries, Shin-Etsu Chemical, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electronics Adhesives Market Shifts & Advancements
Formulation chemistry is converging with thermal management engineering as electric vehicle power densities exceed legacy epoxy capabilities, while regulatory pressure on volatile organic compounds accelerates curing technology substitution.
Conductive die-attach adhesives are replacing solder interconnects in power semiconductor packaging to accommodate lead-free mandates and thermal cycling reliability requirements. Tier-1 automotive suppliers in Bavaria and Baden-Württemberg are qualifying silver-filled epoxy platforms at accelerated schedules. This material transition is miniaturizing bond-line thickness specifications while demanding precision dispensing automation.
EU F-Gas Regulation and REACH Annex XVII restrictions are prohibiting specific fluorinated greenhouse gases and isocyanate constituents in adhesive manufacturing processes. German and Dutch production facilities are retrofitting solvent recovery systems and migrating to UV-curable acrylic platforms. Consumer electronics assemblers in Eastern Europe are absorbing reformulation costs through energy savings from reduced curing oven throughput.
Consolidated procurement functions at European automotive OEMs are unbundling adhesive specification from mechanical component sourcing, creating direct supplier relationships with formulators. Tier-2 electronics manufacturers are bypassing regional distributors to access technical service and custom formulation development. This channel restructuring is most pronounced in Germany's industrial corridor, where OEM technical centers co-locate with adhesive R&D laboratories.
Europe Electronics Adhesives Market Segmentation
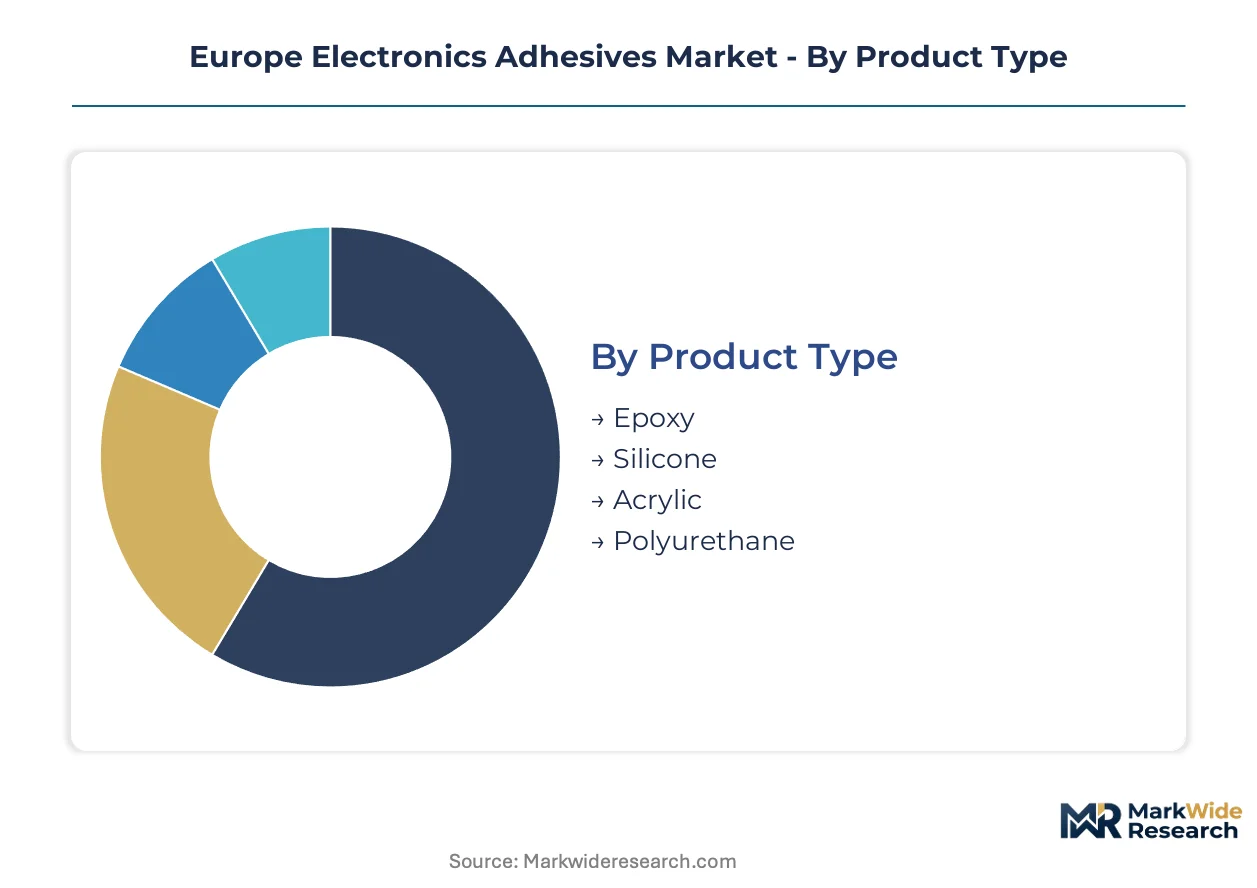
Electronics adhesives traverse distinct procurement channels depending on formulation chemistry and application criticality. Automotive OEMs negotiate direct supply agreements for thermal-grade silicones, while consumer electronics assemblers rely on distributor networks for standard epoxy platforms.
Product Type:
Channel differentiation separates bulk resin procurement by integrated manufacturers from specialized formulation sourcing by tier-2 assemblers across Germany and France.
- Epoxy:Two-part and single-component systems dominate semiconductor packaging and printed circuit board lamination due to established reliability data. Bavarian automotive electronics clusters consume high-purity grades for powertrain control modules where thermal cycling resistance is mandatory.
- Silicone:Thermal-stable formulations accommodate operating temperatures exceeding epoxy limits, making them indispensable for electric vehicle inverters and battery management systems. Baden-Württemberg OEMs are accelerating qualification timelines for these materials.
- Acrylic:UV-curable platforms serve medical equipment manufacturers in France requiring rapid cleanroom throughput.
- Polyurethane:Flexible paste grades sustain industrial repair service margins through manual application versatility.
By volume, epoxy leads. By growth pace, silicone is climbing the fastest.
Application:
Cost tier stratification separates premium-qualified automotive specifications from economy-grade consumer electronics procurement.
- Consumer Electronics:High-volume smartphone and wearable device assembly drives demand for fast-curing, thin-film epoxy systems. Eastern European contract manufacturers prioritize energy-efficient UV-acrylic platforms to reduce curing oven capital expenditure.
- Automotive Components:Under-the-hood electronics require thermal conductivity and vibration resistance beyond consumer-grade specifications. German OEMs mandate 10-year reliability testing for adhesive joints in power electronics housings.
- Industrial Devices:Field repair applications favor two-part polyurethane systems with extended working times.
- Medical Equipment:Biocompatibility testing under EU MDR frameworks restricts supplier pools for surgical device adhesives.
Automotive commands premium pricing per kilogram. Consumer electronics generates the steepest volume expansion trajectory.
Form:
Supply concentration in liquid resin production contrasts with fragmented tape and film converting operations.
- Liquid:Pumpable formulations enable automated dispensing in high-throughput PCB assembly lines. Dutch and German resin producers maintain captive supply of bisphenol-A and bisphenol-F epoxies serving this segment.
- Paste:Thixotropic grades prevent sag in vertical automotive electronics assembly applications.
- Tape:Pressure-sensitive adhesive films support temporary bonding in display lamination processes.
- Film:B-stage epoxy preforms enable precise bond-line control in semiconductor die-attach operations.
Liquid forms dominate tonnage. Film formats are gaining share fastest in advanced packaging applications.
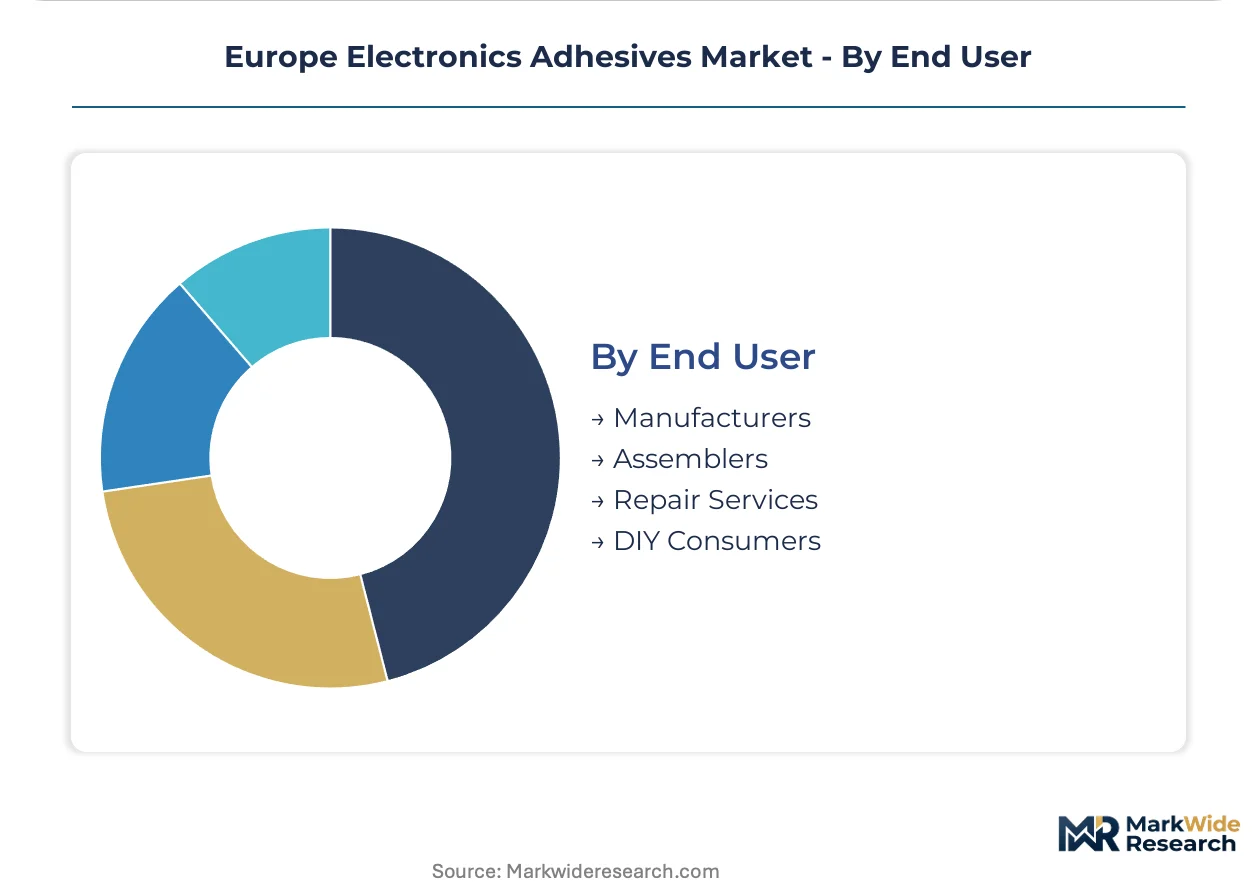
End User:
Customer type determines technical service intensity and contract structure, from embedded formulation scientists at automotive OEMs to transactional distributor relationships with repair technicians.
- Manufacturers:Tier-1 automotive and medical device producers maintain direct technical partnerships with adhesive formulators for custom specification development. Co-located R&D facilities in Germany's industrial corridor accelerate joint development cycles.
- Assemblers:Contract electronics manufacturers in Eastern Europe prioritize standardized epoxy platforms with pan-European distributor availability.
- Repair Services:Independent technicians favor two-part polyurethane kits with extended shelf stability.
- DIY Consumers:Retail-channel adhesives represent minimal revenue contribution but serve brand awareness functions.
Manufacturers capture the highest revenue per customer. Assemblers represent the fastest-expanding procurement volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across European procurement channels. German automotive OEMs absorb premium thermal-grade silicone costs without volume reduction, while Eastern European contract assemblers treat standard epoxy pricing as a primary supplier selection criterion. France's medical device cluster occupies an intermediate position where MDR compliance costs override pure price sensitivity.
Germany
Bavarian and Baden-Württemberg automotive electronics clusters drive concentrated demand for powertrain-qualified adhesives. ECHA REACH registration deadlines compel solvent-free reformulation investments across domestic resin producers. Stuttgart-based OEM technical centers co-locate with adhesive R&D laboratories to compress qualification timelines from twenty-four to twelve months.
France
Surgical equipment manufacturers in Île-de-France and Auvergne-Rhône-Alpes generate specialized demand for biocompatible UV-curable platforms. EU Medical Device Regulation testing burdens restrict supplier pools to qualified formulators. Lyon-area cleanroom assemblers prioritize rapid-curing acrylic systems that maximize throughput under contamination-controlled conditions.
Netherlands
Rotterdam-Antwerp petrochemical corridors supply captive epoxy resin feedstocks to integrated adhesive producers. F-Gas Regulation compliance requires retrofitting solvent recovery systems at Dutch manufacturing facilities. Eindhoven's semiconductor equipment cluster sources high-purity die-attach adhesives through direct technical partnerships.
Italy
Lombardy-based industrial electronics repair services sustain demand for flexible polyurethane paste grades with extended working times. CE marking requirements for machinery directive compliance shape adhesive selection criteria for domestic automation OEMs. Milan-area distributors maintain pan-European inventory positions for standard epoxy platforms serving mid-volume assemblers.
Poland
Eastern European contract manufacturers prioritize energy-efficient UV-acrylic platforms to reduce curing oven capital expenditure. EU Green Deal carbon border adjustments influence procurement decisions for imported resin formulations. Warsaw and Krakow assembly hubs consolidate volume demand for standardized epoxy systems with regional distributor availability.
Europe Electronics Adhesives Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Europe Electronics Adhesives Market. Integrated resin producers leverage captive petrochemical feedstocks and European manufacturing scale to dominate high-volume epoxy segments. Specialized formulators compete through silicone chemistry expertise and direct OEM technical relationships in automotive thermal management. Competitive dynamics center on strategic partnerships with tier-1 automotive suppliers and portfolio diversification into UV-curable medical-grade platforms.
Among German-anchored diversified chemical groups, Henkel AG & Co. KGaA and BASF SE exemplify integrated players with captive resin production and broad formulation portfolios. Swiss-based Sika AG occupies a position within the specialty silicone tier, while Arkema SA represents the UV-curable acrylic segment focused on energy-efficient curing solutions. These three companies anchor distinct competitive vectors: integrated scale, thermal-grade specialization, and regulatory-responsive curing technology.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Sika AG |
| H.B. Fuller Company |
| 3M Company |
| BASF SE |
| Dow Inc. |
| Arkema SA |
| Evonik Industries |
| Shin-Etsu Chemical |
| Others |
Supply & Pricing Matrix
Silicone chemistry substitution for epoxy in EV thermal management is redrawing procurement geography and compressing margin structures across European adhesive markets. This material transition concentrates premium pricing power with German and Swiss formulators while forcing standard epoxy producers toward volume-driven contract structures.
Pricing Analysis
After-sales technical service contracts capture lifetime value exceeding initial material sales by factors of three to five in automotive thermal-grade segments. Three-tier pricing structure across premium silicone, standard epoxy, and economy acrylic levels reflects certification intensity and volume scale. Cost compression in standard epoxy runs through Eastern European contract manufacturers absorbing reformulation expenses. German OEMs exhibit lowest price sensitivity due to reliability mandates, while Polish assemblers treat epoxy pricing as primary supplier selection criterion.
Supply Chain Analysis
Rotterdam-Antwerp petrochemical corridor chokepoints expose European formulators to feedstock disruption from integrated resin producers in Germany and the Netherlands. Bisphenol-A epoxies, silicone intermediates, and UV-curable acrylic monomers draw from concentrated petrochemical streams. Single-source vulnerability concentrates in Dutch epoxy resin output serving die-attach applications. Distribution runs through direct technical partnerships for automotive OEMs and regional distributors for mid-volume assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through consolidated procurement functions at European automotive OEMs unbundling adhesive specifications from mechanical component sourcing. Tier-1 supplier consolidation across Bavaria and Baden-Württemberg accelerates this shift.
For Market Incumbents: Secure captive silicone chemistry supply through backward integration into specialty resin production or exclusive offtake agreements with German petrochemical producers. Defend automotive thermal management positions by embedding formulation scientists at Stuttgart-based OEM technical centers. Channel control through direct technical sales platforms displaces distributor relationships at risk from consolidated procurement functions. For New Entrants and Emerging Players: Lead with biocompatible UV-curable platforms targeting France's surgical equipment cluster where MDR compliance burdens restrict incumbent supplier pools. France's medical device segment presents the most penetrable white-space opportunity due to qualification timeline compression and regulatory friction. Go-to-market execution should emphasize cleanroom throughput validation and rapid curing energy savings. For Investors and Strategic Acquirers: The market sits at a formulation-specialization phase that favors mid-cap silicone experts and UV-curable platform developers over integrated commodity resin producers. Long-term viability over the next decade hinges on regulatory-responsive curing technology and direct OEM technical relationships. Watch ECHA substance restriction enforcement timelines as the critical inflection signal for portfolio reallocation between solvent-free and legacy formulation assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Intermediates | Captive supply secures thermal-grade formulations for Baden-Württemberg EV powertrain programs. |
| REACH-Compliant UV Platform Development | Energy-efficient curing reduces oven capital burden for Eastern European contract assemblers. |
| Direct Technical Sales Channel Expansion | Bypasses distributor markups and captures consolidated procurement at German automotive OEMs. |
| Biocompatibility Certification Investment | MDR-compliant supplier status unlocks France's surgical equipment cluster with restricted competition. |
| Debondable Chemistry R&D Partnership | EU Battery Regulation alignment enables end-of-life material recovery service revenue streams. |
Research Methodology
Operator-level perspectives from adhesive formulators, automotive Tier-1 procurement leads, medical device cleanroom managers, and ECHA regulatory affairs specialists anchored the qualitative base. Primary interviews combined with secondary validation from ECHA substance restriction proposals, EU Green Deal implementation documents, Cefic chemical industry reports, and SEC filings from listed adhesive producers. Bottom-up segment sizing triangulated against top-down petrochemical feedstock demand estimates.
Sensitivity analysis tested volume and value outputs across formulation chemistry, application criticality, and regional regulatory cluster dimensions over the projection horizon. CAGRs derived from segment-level adoption curves weighted by automotive electrification investment cycles and medical device MDR transition timelines. Forecast inputs incorporated REACH registration deadline acceleration scenarios and F-Gas Regulation compliance cost pass-through assumptions.
The analysis sits within stated boundaries; outcomes outside sustained EV powertrain investment intensity or accelerated ECHA enforcement timelines would require recalibration. Forecasts reflect documented assumptions about regulatory implementation pace and OEM qualification cycle compression. Practitioners should keep alternative scenarios live as EU Green Deal carbon border adjustment mechanisms and Battery Regulation end-of-life requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Asia-Pacific Urea-Formaldehyde Glues and Resins Market
Adhesives & Sealants
Plastic Adhesives Market
Adhesives & Sealants
Southeast Asia Adhesives and Sealants Market
Adhesives & Sealants
Europe EVA Adhesives Market
Adhesives & Sealants
Electrical Insulation Tape Market
Adhesives & Sealants
North America Adhesives and Sealants Market
Adhesives & Sealants
Global Self-Adhesive Vinyl Films Market
Adhesives & Sealants
Europe Chemical Anchors Market
Adhesives & Sealants
North America Electronics Adhesives Market
Adhesives & Sealants
Middle-East and Africa Reactive Adhesives Market
Adhesives & Sealants
Textile Binders Market
Adhesives & Sealants
Carpet Adhesive Market
Adhesives & Sealants
2K Epoxy Adhesives Market
Adhesives & Sealants
Correction Fluid and Tape Market
Adhesives & Sealants
Active Metal Brazing (AMB) Paste Market
Adhesives & Sealants
Structural Adhesives Market