
 Asia-Pacific Acrylic Adhesives Market | 2026-2036
Asia-Pacific Acrylic Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Acrylic Adhesives Market Outlook
Water-based formulation technology is reconfiguring how automotive and electronics manufacturers approach bonding processes across the Asia-Pacific region. Henkel AG & Co. KGaA leverages its R&D footprint in Shanghai to develop low-VOC acrylic systems for EV battery pack assembly. Nanpao Resins Chemical Group anchors its competitive position through backward integration into acrylic monomer production at its Taiwan facilities. Hubei Huitian New Materials specializes in high-performance reactive adhesives for China's domestic electronics supply chain.
Asia-Pacific acrylic adhesives are thermoplastic or thermosetting resins formulated from acrylic monomers, typically polymerized through free-radical mechanisms to achieve peel strengths ranging from 2 to 20 N/mm depending on crosslink density. These adhesives bond dissimilar substrates including metals, plastics, and composites without surface primers in many applications. Water-based acrylics now dominate volume shipments across the region due to environmental compliance pressures and lower volatile organic compound emissions. Solvent-based formulations retain pricing premiums in automotive exterior bonding where rapid tack development and moisture resistance prove critical. Reactive acrylic systems represent the fastest-expanding product category, driven by structural bonding requirements in wind turbine blade manufacturing and aerospace component assembly across China and South Korea.
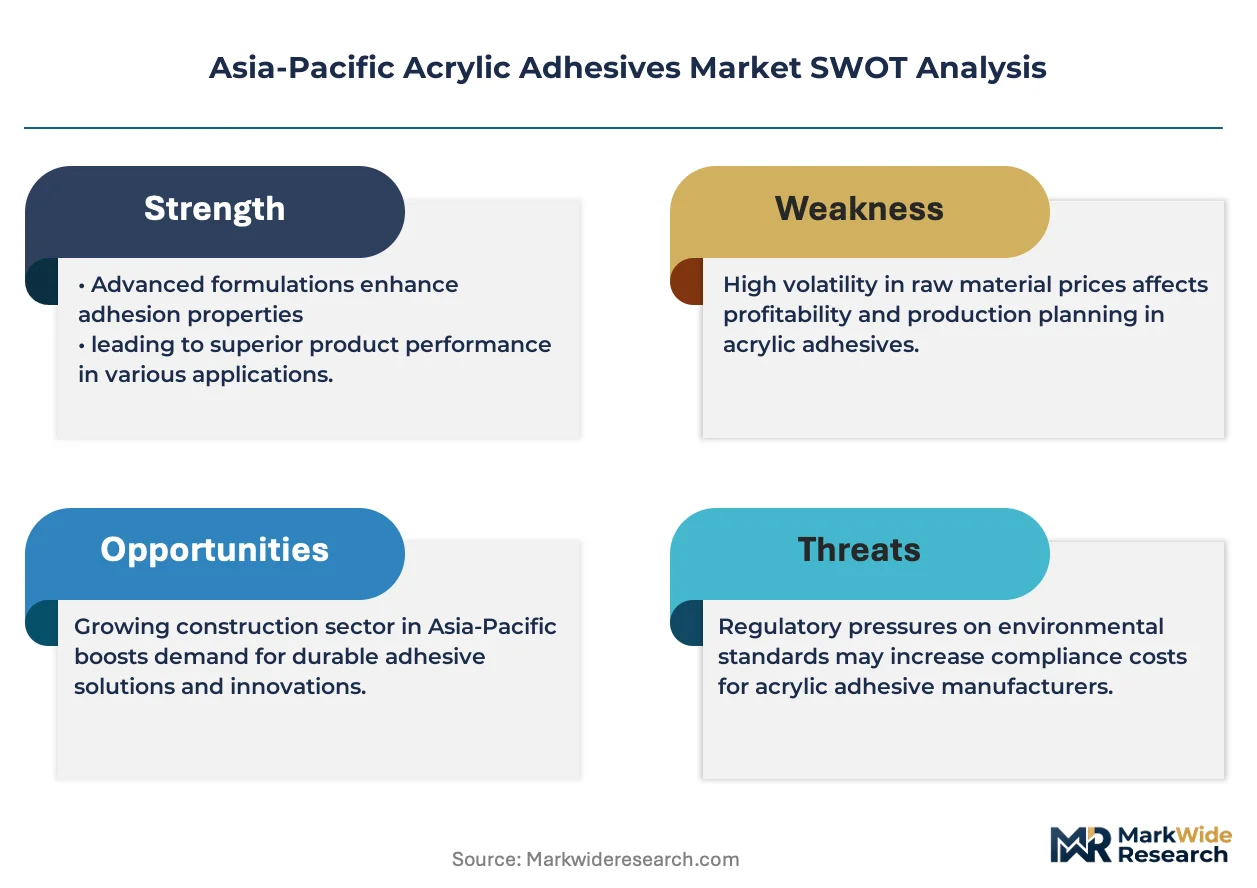
China's MEE enforces GB standards limiting VOC content in industrial adhesives, directly constraining solvent-based product formulations in manufacturing zones. Japan's METI promotes JIS-compliant low-carbon adhesive technologies through procurement guidelines affecting construction and automotive sectors. South Korea's MFDS maintains material safety requirements for healthcare applications including medical device bonding and wound closure tapes. Stakeholders must monitor how China's dual carbon goals and India's PLI scheme for advanced manufacturing reshape specification requirements and supplier qualification timelines across the region.
Market Dynamics
Water-based acrylic adhesive technology is compressing solvent-based market share as China's MEE enforces stricter GB standards on VOC emissions across manufacturing corridors. Automotive OEMs in Shanghai and Jiangsu provinces now specify low-VOC systems for EV battery bonding, forcing formulation switches at the plant level.
Growth Catalysts
- China's dual carbon goals:MEE enforcement of GB standards on industrial adhesives is eliminating high-VOC solvent formulations from eastern manufacturing zones. Automotive and electronics producers must certify water-based alternatives to maintain operating licenses.
- EV battery pack assembly:Structural bonding requirements for lithium-ion cell modules and thermal management plates are pulling reactive acrylic systems into high-volume automotive production lines.
- Taiwan's monomer supply base:Backward-integrated acrylic monomer production anchors regional raw material security, reducing import dependency for formulated adhesive manufacturers serving China and Southeast Asia.
Market Restraints
- Petrochemical feedstock volatility:Acrylic acid and ester monomer prices fluctuate with naphtha and propylene markets, compressing margin stability for non-integrated adhesive compounders.
- Moisture-cure limitations:Water-based acrylics face technical barriers in exterior automotive bonding where rapid water resistance and high-temperature performance remain critical specifications.
- South Korean supply concentration:Specialty reactive acrylic oligomer production clusters around Busan-Ulsan chemical complexes, creating geographic concentration risk for regional formulators.
Strategic Opportunities
- India's PLI scheme for advanced manufacturing:Production-linked incentives for electronics and automotive component sectors are building domestic adhesive demand that currently relies on Chinese and Taiwanese imports.
- Wind turbine blade manufacturing:Structural bonding of carbon fiber and glass fiber composites in China and South Korea represents an emerging high-performance application for reactive acrylic systems.
- Direct-to-plant technical service:Formulators are embedding application engineers at automotive and electronics OEMs to customize curing profiles and dispensing parameters, bypassing traditional distributor channels.
Industry Challenges
- Formulation chemistry expertise gap:Water-based acrylic development requires emulsion polymerization specialists scarce in regional talent pools, extending R&D cycle times for local compounders.
- Multi-jurisdiction certification complexity:Adhesives for medical device applications must secure MFDS clearance in South Korea, PMDA approval in Japan, and NMPA registration in China, creating parallel compliance tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Acrylic Adhesives Market |
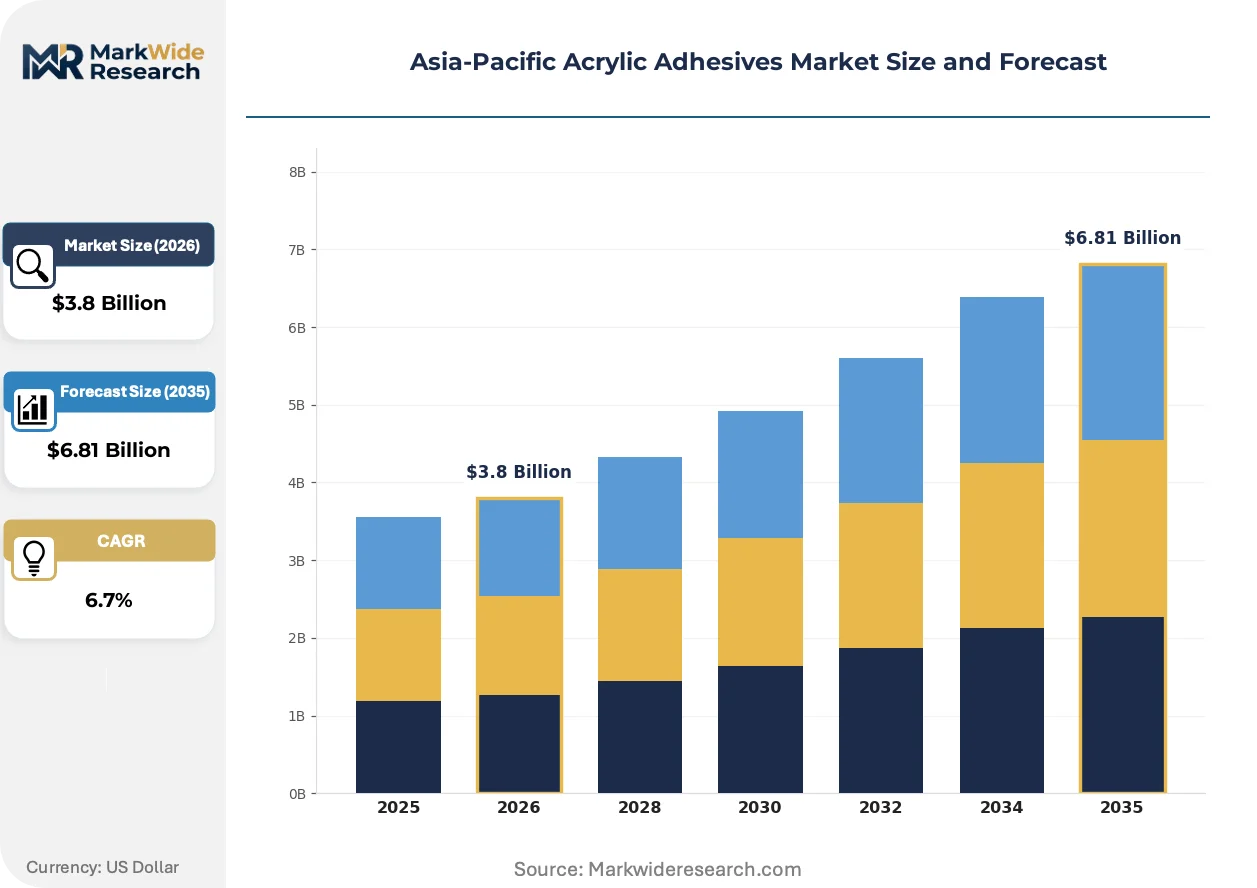
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Reactive, Hot Melt End Use Industry: Automotive, Construction, Electronics, Healthcare Form: Liquid, Paste, Film, Granule Application: Bonding, Coating, Sealing, Laminating |
| Companies Covered | 3M, Henkel AG & Co. KGaA, Avery Dennison Corporation, Hubei Huitian New Materials, Nanpao Resins Chemical Group, Arkema Group, H.B. Fuller Company, Sika AG, Bostik SA, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Acrylic Adhesives Market Strategic Shifts
Reactive acrylic chemistry is hybridizing with epoxy and polyurethane functionalities to capture structural bonding applications previously closed to single-chemistry systems. Formulators are embedding application-specific curing profiles and dispensing automation to lock in automotive and electronics OEM relationships.
Hybrid acrylic-epoxy systems are hybridizing at the molecular level through core-shell emulsion architectures that combine the rapid tack of acrylics with the structural strength of epoxies. Wind turbine blade manufacturers in Jiangsu and Guangdong provinces are piloting these systems for shear web bonding. The technology is compressing the traditional trade-off between processing speed and cured performance that has segmented the structural adhesives market.
China's GB 30982-2014 standard on VOC limits in adhesives is tightening enforcement through provincial environmental inspections, particularly in the Yangtze River Delta manufacturing cluster. Solvent-based acrylic producers face reformulation mandates or production suspensions. Electronics contract manufacturers in Shenzhen and Dongguan are accelerating water-based qualification programs to preempt supply disruptions.
Specification-driven procurement is consolidating adhesive supplier relationships at major automotive OEMs, with technical service capabilities outweighing unit price in sourcing decisions. Tier-1 suppliers in Japan and South Korea now require formulators to co-locate application engineers at assembly plants. This shift is visible in Toyota and Hyundai supply chains, where adhesive bonding process validation has become a gated milestone in new model launches.
Asia-Pacific Acrylic Adhesives Market Segmentation
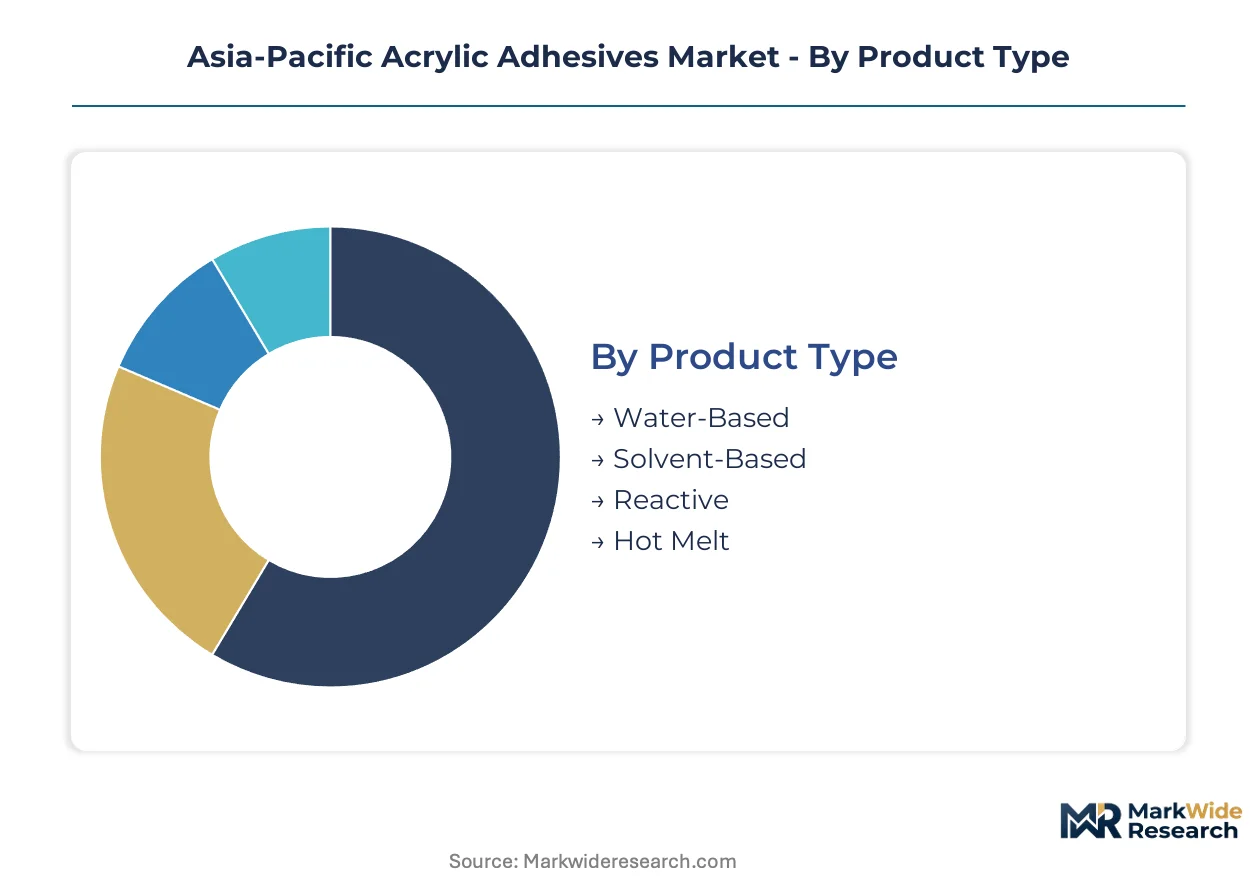
Segmentation in Asia-Pacific acrylic adhesives reveals how formulation chemistry, application requirements, and regulatory pressures fragment demand across distinct technical specifications. Manufacturers configure product portfolios around end-use performance thresholds rather than volume scale alone.
Product Type:
Water-based systems dominate interior assembly applications while solvent-based formulations retain exterior automotive specifications where moisture resistance governs selection.
- Water-Based:Emulsion polymerized acrylics with VOC content below GB 30982-2014 thresholds capture electronics and interior automotive bonding in Shanghai and Jiangsu manufacturing corridors. MEE enforcement is eliminating solvent alternatives from these zones.
- Solvent-Based:Rapid-tack formulations using acrylic ester solutions in organic carriers maintain pricing premiums for exterior automotive seam sealing where water resistance and high-temperature performance prove critical.
- Reactive:Two-part systems curing through free-radical polymerization anchor structural bonding in wind turbine blade assembly across Jiangsu and Guangdong provinces.
- Hot Melt:Thermoplastic acrylic block copolymers serve high-speed packaging and disposable product assembly where instant green strength and reprocessability matter.
The dominant share belongs to water-based formulations, while reactive systems are gaining share fastest on wind energy and EV battery demand.
End Use Industry:
Automotive OEMs now specify adhesive bonding protocols earlier in design cycles, compressing qualification timelines for compounders serving China and Japan.
- Automotive:Structural bonding of aluminum-intensive vehicle architectures and lithium-ion battery module assembly in China and South Korea pulls reactive acrylic systems into high-volume production lines. Toyota and Hyundai supply chains require co-located application engineers.
- Construction:India's BIS certification requirements for construction-grade adhesives are tightening product standards for tile bonding and panel lamination applications.
- Electronics:Shenzhen and Dongguan contract manufacturers specify low-VOC water-based systems for smartphone and tablet component assembly under MEE inspection pressure.
- Healthcare:MFDS, PMDA, and NMPA parallel compliance tracks govern medical device bonding and wound closure tape applications across South Korea, Japan, and China.
Automotive applications command the highest technical service investment, while electronics demand is expanding most quickly on water-based qualification programs.
Form:
Liquid and paste configurations align with automated dispensing infrastructure, while film and granule formats serve specialized lamination and compounding workflows.
- Liquid:Pumpable emulsions and solutions dominate high-volume automotive and electronics assembly where robotic dispensing ensures repeatability.
- Paste:Thixotropic formulations with sag resistance serve vertical construction bonding and gap-filling automotive seam sealing applications.
- Film:Supported and unsupported acrylic adhesive films enable precision lamination in electronics stack-up assembly and aerospace interior panel bonding.
- Granule:Solid thermoplastic forms feed hot melt compounding operations and specialized reactive adhesive manufacturing.
Liquid forms hold the volume lead, though film formats are climbing fastest on electronics miniaturization requirements.
Application:
Bonding functions absorb the majority of formulated adhesive volume, while coating and sealing applications command specification-driven premiums.
- Bonding:Structural and non-structural adhesion of dissimilar substrates—metals, plastics, composites—without surface primers anchors volume demand across automotive and electronics sectors.
- Coating:Pressure-sensitive adhesive coatings for tape and label stock production concentrate in Taiwan and South Korea chemical manufacturing zones.
- Sealing:Gap-filling and environmental barrier functions in automotive body assembly and construction joints favor paste-consistency solvent-based and reactive systems.
- Laminating:Film adhesive bonding of multi-layer composites serves aerospace interior components and high-performance packaging structures.
Bonding commands the dominant application share, with laminating exhibiting the steepest expansion trajectory on aerospace and advanced packaging demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwanese acrylic monomer producers supply formulated adhesive manufacturers across China's eastern seaboard and Southeast Asia, creating a north-south chemical trade corridor that underpins regional raw material security.
China
EV battery pack assembly and wind turbine blade manufacturing drive reactive acrylic system consumption in Jiangsu and Guangdong provinces. MEE enforcement of GB 30982-2014 VOC limits is eliminating solvent-based formulations from the Yangtze River Delta manufacturing cluster. Shanghai-based automotive OEMs now mandate water-based certification for supplier qualification.
Japan
Automotive lightweighting programs and aerospace component bonding sustain demand for high-performance reactive systems in Toyota and Honda supply chains. METI procurement guidelines favor JIS-compliant low-carbon adhesive technologies in construction and transportation sectors. Kanto region chemical manufacturers concentrate specialty acrylic oligomer production for domestic electronics and medical device sectors.
South Korea
Hyundai Motor Group's aluminum-intensive vehicle architectures and Samsung Electronics' smartphone assembly lines pull structural and electronics-grade adhesives into high-volume production. MFDS maintains parallel compliance tracks for medical device bonding applications. Busan-Ulsan chemical complexes anchor specialty reactive acrylic oligomer production for regional formulators.
India
Electronics manufacturing under the PLI scheme and automotive component localization are building domestic adhesive demand currently met through Chinese and Taiwanese imports. BIS certification requirements for construction-grade adhesives are tightening product standards for tile bonding and panel lamination. Maharashtra and Gujarat industrial corridors concentrate emerging formulation and application engineering capabilities.
Taiwan
Backward-integrated acrylic monomer production at Nanpao Resins Chemical Group facilities reduces import dependency for formulated adhesive manufacturers serving China and Southeast Asia. Electronics contract manufacturers in Hsinchu Science Park specify low-VOC water-based systems for semiconductor packaging and display assembly. The island's chemical sector anchors regional raw material security for emulsion polymerized acrylic supply chains.
Asia-Pacific Acrylic Adhesives Market Competitive Environment
On the supply side, the industry is consolidating around three strategic tiers: multinational chemical conglomerates with integrated monomer-to-formulation capabilities, regional specialists with backward integration into acrylic ester production, and domestic Chinese compounders serving localized electronics supply chains. Strategic moves center on co-location of application engineers at automotive OEM assembly plants and hybridization of acrylic chemistry with epoxy and polyurethane functionalities to capture structural bonding applications.
Within the multinational tier, 3M, Henkel AG & Co. KGaA, and Avery Dennison Corporation exemplify integrated players leveraging R&D footprints in Shanghai and Tokyo to develop low-VOC systems for EV battery assembly. These companies occupy positions where technical service capabilities outweigh unit price in sourcing decisions at Toyota and Hyundai supply chains. Regional specialists including Nanpao Resins Chemical Group anchor competitive positions through captive monomer supply, while Hubei Huitian New Materials represents the domestic Chinese archetype serving localized electronics contract manufacturers in Shenzhen and Dongguan.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| Avery Dennison Corporation |
| Hubei Huitian New Materials |
| Nanpao Resins Chemical Group |
| Arkema Group |
| H.B. Fuller Company |
| Sika AG |
| Bostik SA |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Taiwan's acrylic monomer production facilities is compressing feedstock costs for formulated adhesive manufacturers while simultaneously eroding margin buffers for non-integrated compounders serving China's eastern manufacturing corridor. This utilization dynamic forces suppliers to choose between absorbing price declines or ceding volume to backward-integrated competitors.
Pricing Analysis
Water-based versus solvent-based versus reactive acrylic systems define the technology-generation pricing gap across Asia-Pacific procurement channels. Three-tier pricing structure across premium reactive, standard water-based, and economy solvent-based levels reflects certification grade and volume scale differentiation. Pricing pressure stems from MEE enforcement of GB 30982-2014 VOC limits eliminating solvent-based premiums in Yangtze River Delta zones. Electronics contract manufacturers in Shenzhen exhibit highest price sensitivity while automotive OEMs in Toyota and Hyundai supply chains prioritize technical service over unit cost.
Supply Chain Analysis
Extended payment terms from automotive OEMs in Japan and South Korea are forcing working-capital restructuring among Taiwanese monomer suppliers and Chinese compounders. Raw material security draws from Taiwan's acrylic acid capacity, South Korea's specialty oligomer production, and China's domestic emulsion polymerization feedstocks. Single-source vulnerability concentrates around Busan-Ulsan chemical complexes for reactive acrylic oligomers. Distribution runs through direct technical service relationships at OEM assembly plants rather than traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. Certification requirements for automotive and medical device applications create switching costs that protect qualified supplier positions.
For Market Incumbents: Harden supplier qualification timelines by embedding application engineers at Hyundai and Toyota assembly plants before competitor technical service programs mature. Deepen backward integration into acrylic monomer production to match Nanpao Resins Chemical Group's captive supply advantage and defend against margin compression from Taiwanese feedstock volatility. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-driven electronics manufacturing corridor where domestic adhesive supply remains underdeveloped and BIS certification requirements are still stabilizing. Target wind turbine blade manufacturing in Jiangsu and Guangdong provinces with reactive acrylic systems for carbon fiber shear web bonding, leveraging direct-to-plant technical service as the primary go-to-market mechanism. For Investors and Strategic Acquirers: Capital is best deployed toward backward-integrated regional specialists with captive monomer supply and established automotive OEM relationships. Long-term viability hinges on regulatory compliance capabilities across MFDS, PMDA, and NMPA parallel tracks. Monitor MEE enforcement intensity in Yangtze River Delta manufacturing zones as the inflection signal for water-based formulation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive acrylic monomer production insulates margin stability from naphtha and propylene volatility. |
| Application Engineering Co-location | Embedded technical staff at Toyota and Hyundai plants lock in specification-driven procurement relationships. |
| Reactive Acrylic Capacity Expansion | Structural bonding demand from EV battery assembly and wind turbine manufacturing pulls capacity utilization higher. |
| Multi-Jurisdiction Certification Investment | Simultaneous MFDS, PMDA, and NMPA clearance opens medical device and automotive access across three markets. |
| Water-Based Formulation Transition | GB 30982-2014 compliance preserves operating licenses in MEE-inspected Yangtze River Delta manufacturing zones. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, ACC and Cefic chemical industry reports, and SEC 10-K filings from listed adhesive manufacturers. Technical directors at automotive OEMs, procurement leads at electronics contract manufacturers, plant managers at Taiwanese monomer facilities, and distribution channel partners across China and Southeast Asia contributed structured interviews. Bottom-up demand modeling from end-use applications triangulates against top-down supply-side capacity assessments.
Forecast inputs incorporate formulation chemistry transitions, end-use industry growth differentials, and regional regulatory enforcement trajectories across the projection horizon. Segmentation dimensions include product type, end-use industry, application function, and regional production hub. CAGRs derive from fitted growth curves applied to verified base-year estimates, with EV battery pack assembly and wind turbine blade manufacturing serving as high-weight demand drivers.
Sensitivities concentrate around MEE enforcement intensity, petrochemical feedstock volatility, and automotive platform electrification rates. Forecasts reflect documented assumptions regarding regulatory compliance timelines and technology substitution patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Construction Adhesive Tapes Market
Adhesives & Sealants
Global Bone Glue Market
Adhesives & Sealants
Light Curing Adhesives Market
Adhesives & Sealants
Polysulfide Sealants Market
Adhesives & Sealants
Die Cut Adhesive Market
Adhesives & Sealants
EV Adhesives Market
Adhesives & Sealants
North America Epoxy Adhesives Market
Adhesives & Sealants
North America Laminating Adhesives Market
Adhesives & Sealants
Global Elastic Adhesive Market
Adhesives & Sealants
Global Disposable Hygiene Adhesives Market
Adhesives & Sealants
South America Adhesives Market
Adhesives & Sealants
Nigeria Tile Adhesive Market
Adhesives & Sealants
Asia-Pacific Flock Adhesives Market
Adhesives & Sealants
North America Human Fibrin Glue Market
Adhesives & Sealants
South America Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Global Adhesive Coating Market