
 Global Non-Woven Adhesives Market | 2026-2036
Global Non-Woven Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non-Woven Adhesives Market Outlook
Modular hygiene product designs is shifting how manufacturers specify adhesive systems across baby care, adult incontinence, and feminine hygiene lines. Henkel AG leverages its global formulation network to sustain leadership in hot-melt platforms for elastic attachment and core bonding. H.B. Fuller Company anchors its position through specialized polymer expertise in breathable barrier applications. Arkema competes with bio-based raw material pathways that reduce petrochemical dependency in spunbond and meltblown laminates.
Non-woven adhesives are thermoplastic or reactive polymer systems formulated to bond synthetic or natural fiber webs without compromising porosity, flexibility, or skin-contact safety; they typically activate between 120°C and 180°C and must achieve peel strengths exceeding 2.5 N/cm for durable hygiene construction. Their primary purpose is to replace mechanical fastening in disposable products where softness, weight reduction, and manufacturing speed determine commercial viability. Hot-melt formulations dominate volume due to instant green-strength and compatibility with high-speed production lines, while water-based systems are gaining ground where volatile organic compound restrictions tighten. Reactive adhesives occupy premium niches in medical and automotive applications where thermal resistance and long-term durability justify slower curing cycles and higher material costs.
EPA industrial chemical rules, EU REACH substance restrictions, and FDA biocompatibility standards for skin-contact materials collectively shape formulation choices, testing protocols, and market access timelines for suppliers operating across multiple jurisdictions. Compliance investments are concentrating among mid-scale producers who must bridge gap analysis between regional hazard classifications and end-user certification requirements. Stakeholders should monitor evolving per- and polyfluoroalkyl substance restrictions in Europe and North America, as these will force reformulation of release liners and repellent finishes that interact with adhesive layers in finished non-woven goods.
Market Dynamics
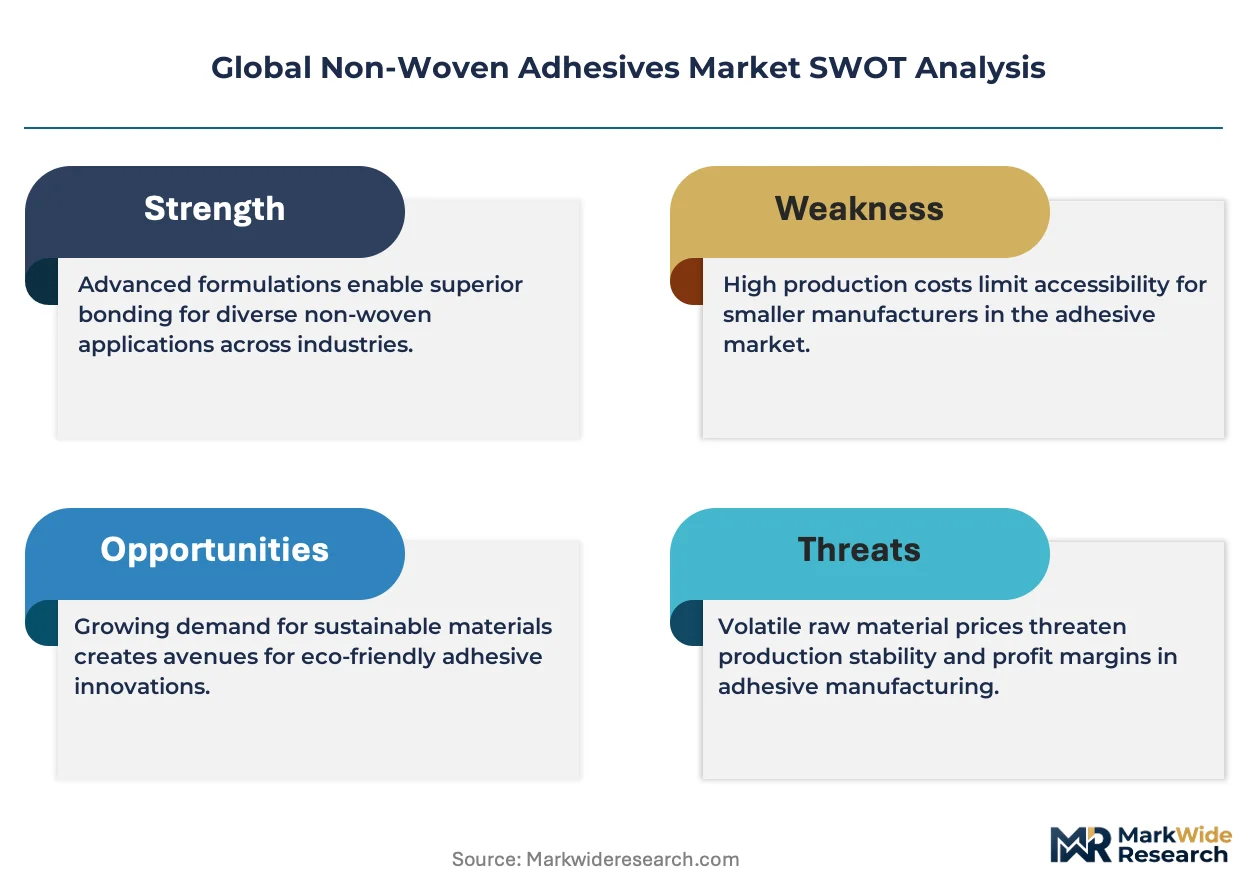
EU REACH substance restrictions are compressing formulation windows for petrochemical-based hot-melt adhesives while simultaneously accelerating bio-based polymer qualification timelines across hygiene and medical supply chains.
Growth Catalysts
- Medical-grade hygiene mandates:FDA biocompatibility standards for skin-contact materials are expanding adhesive qualification requirements in wound care and surgical drape applications.
- REACH chemical safety compliance:ECHA substance restrictions are forcing incumbent suppliers to reformulate, creating entry points for compliant bio-based alternatives in spunbond laminates.
- Automotive interior bonding:Germany's lightweighting requirements for vehicle cabin assemblies are redirecting specification authority toward adhesive suppliers with thermal resistance expertise.
Market Restraints
- Crude oil derivative volatility:Polyolefin and tackifying resin feedstock costs fluctuate with naphtha cracking margins, compressing margin stability for hot-melt formulators.
- Asian supply concentration:Specialty polymer intermediates for reactive adhesive systems concentrate among Korean and Japanese chemical producers, exposing buyers to shipping disruption risk.
- Curing speed limitations:Reactive polyurethane adhesives require 24-48 hour full cure cycles, disqualifying them from high-speed disposable hygiene lines running above 600 units per minute.
Strategic Opportunities
- Brazilian medical infrastructure:ANVISA regulatory harmonization with ISO 10993 standards is streamlining import pathways for certified skin-contact adhesives in hospital supply chains.
- PLA-bio-PU hybrid platforms:Converging polylactic acid feedstock availability with polyurethane reactivity is enabling compostable elastic attachment bonds in premium diaper lines.
- EU Green Deal procurement rules:Public healthcare tender specifications in France and Italy now weight bio-based content at 15-20% of technical scoring, favoring qualifying suppliers.
Industry Challenges
- Formulation chemist scarcity:Expertise in balancing peel strength with skin sensitization thresholds concentrates among retiring specialists at German and Swiss adhesive houses.
- Multi-jurisdiction certification timelines:Simultaneous FDA 510(k), EU MDR technical documentation, and Health Canada MDL submissions extend product launch windows by 18-24 months.
- Legacy equipment retrofit costs:Water-based adhesive conversion requires tank farm and drying tunnel investments that mid-scale hygiene producers defer amid margin pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non-Woven Adhesives Market |
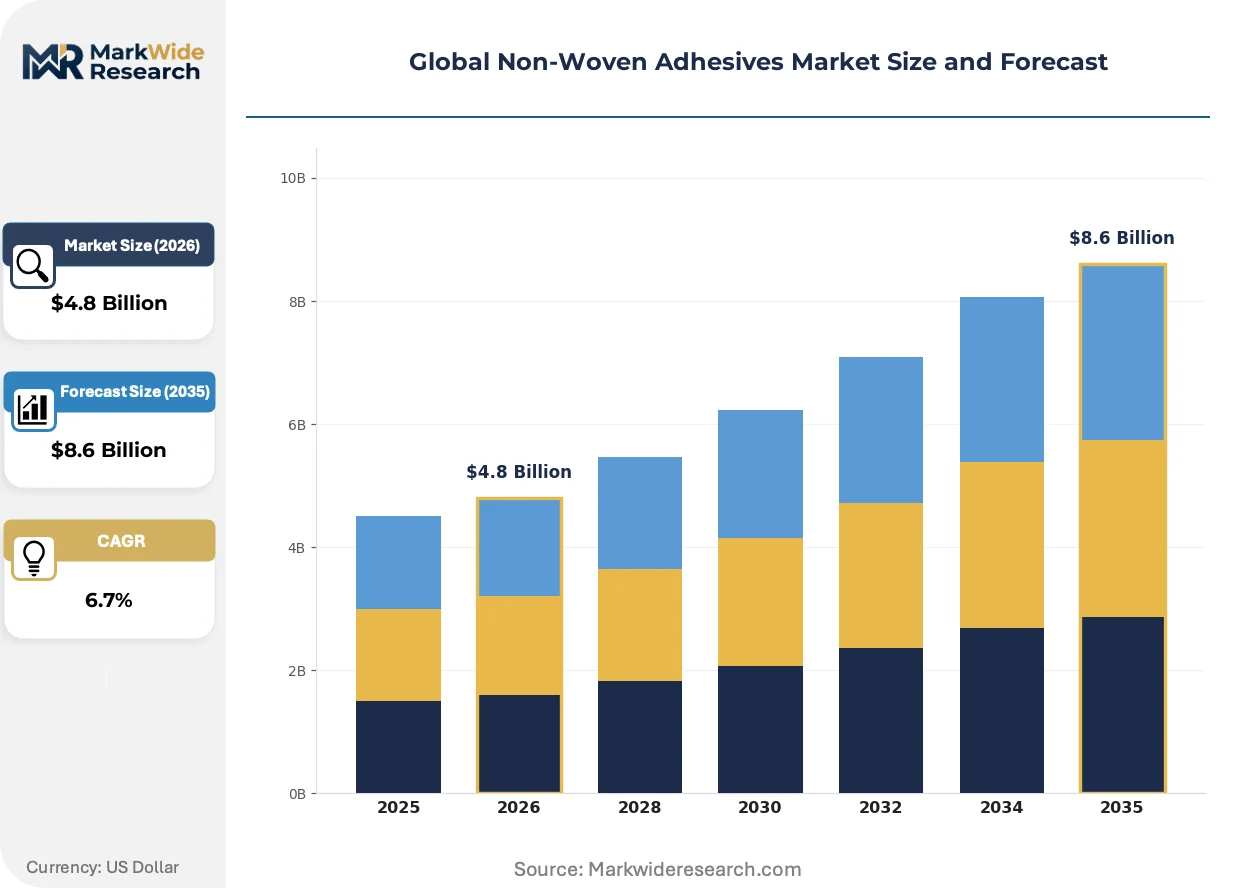
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Melt, Water-Based, Solvent-Based, Reactive Adhesives Application: Medical, Automotive, Hygiene Products, Packaging End User: Healthcare Providers, Manufacturers, Retailers, Contractors Technology: Spray, Roll Coating, Dipping, Extrusion |
| Companies Covered | Henkel AG, H.B. Fuller Company, Arkema, Bostik, MORESCO Corporation, Beardow Adams, Lohmann-Koester GmbH & Co. KG, 3M, Dow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non-Woven Adhesives Market Strategic Shifts
Bio-based raw material substitution is reconfiguring supplier qualification protocols while digital manufacturing integration is compressing batch-to-batch variance in adhesive dispensing systems.
Metallocene polyolefin hot-melt platforms deliver narrower molecular weight distribution than conventional EVA formulations, enabling precise viscosity control across temperature swings. Medical drape manufacturers in the US and Germany are adopting these systems for consistent coating weights on breathable films. This precision is expanding into automotive interior lamination where bond line aesthetics determine OEM acceptance.
EPA industrial chemical reporting under TSCA Section 8(a) now captures non-confidential production volumes for isocyanate-containing adhesives, creating transparency pressure on reactive system suppliers. Formulators are responding by accelerating aliphatic polyester prepolymer development to reduce aromatic amine exposure concerns. Medical device adhesive lines face the steepest compliance burden, with some suppliers exiting skin-contact categories rather than absorbing testing costs.
Direct adhesive purchasing from converters is displacing distributor intermediation in large hygiene accounts, with Procter & Gamble and Essity negotiating multi-year toll manufacturing agreements. This consolidation concentrates volume among three to four global adhesive houses capable of matching regional production footprints. The shift is most visible in Western Europe, where sustainability scorecard requirements favor suppliers with certified bio-based supply chains and renewable energy manufacturing.
Global Non-Woven Adhesives Market Segmentation
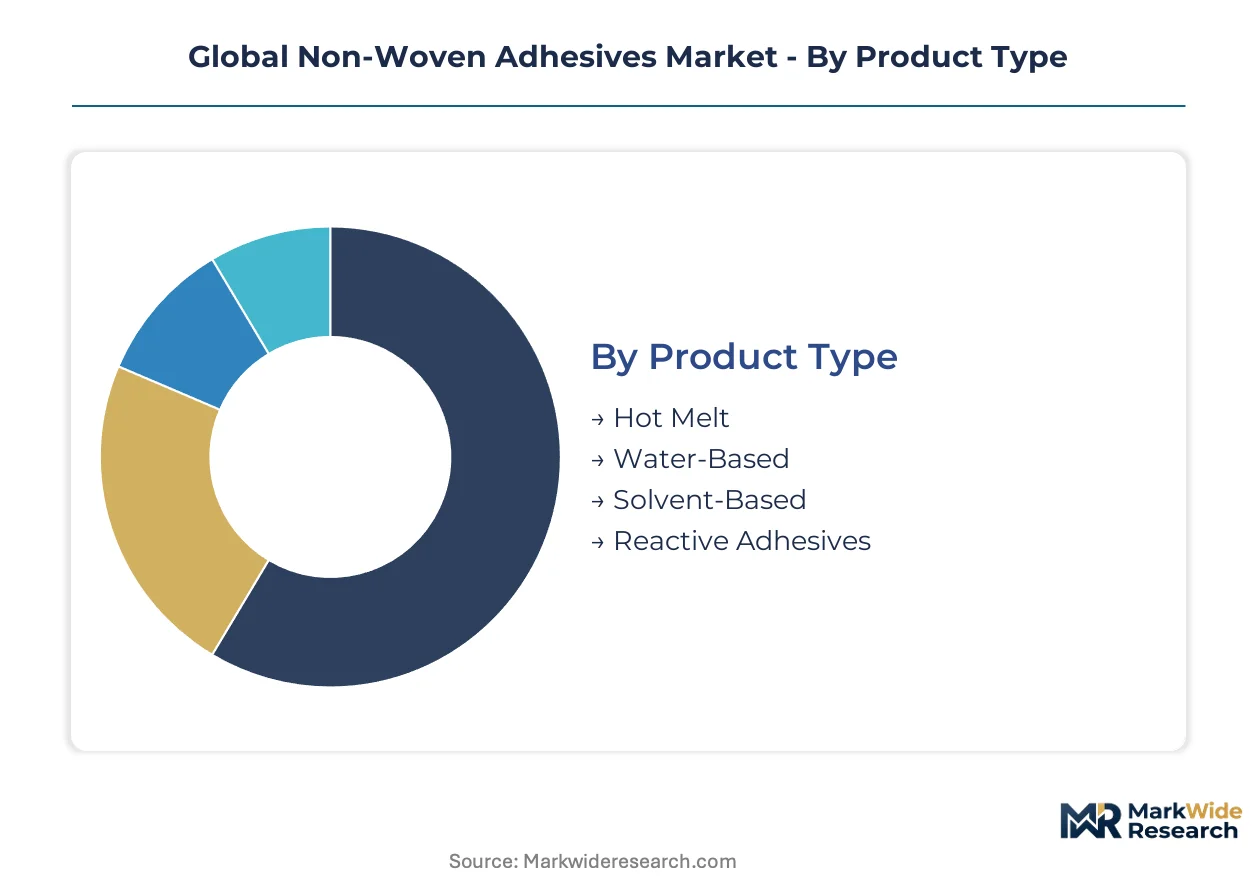
Non-woven adhesives serve divergent performance requirements across hygiene disposables, medical barriers, and automotive interiors. Specification authority varies sharply by end-use, with FDA biocompatibility mandates governing medical grades while automotive OEMs prioritize thermal resistance and acoustic damping. Understanding these segment boundaries clarifies why formulation portfolios fragment across reactive, hot-melt, and water-based chemistries rather than consolidating on single platforms.
Product Type:
Technology specifications determine activation temperature, green-strength development, and regulatory compliance pathways.
- Hot Melt:Thermoplastic formulations based on metallocene polyolefins or ethylene-vinyl acetate copolymers activate between 120°C and 180°C and deliver instant tack for high-speed hygiene lines. Demand concentrates in German automotive interior lamination where OEMs specify narrow viscosity windows for bond line aesthetics.
- Water-Based:Acrylic or polyurethane dispersions eliminate volatile organic compound exposure but require drying tunnel infrastructure. Adoption is climbing fastest in EU markets where ECHA restrictions on petrochemical feedstocks tighten formulation windows for solvent alternatives.
- Solvent-Based:Hydrocarbon or alcohol-borne systems persist in specialty medical drape applications where aggressive substrate wetting proves essential. Regulatory pressure from EPA TSCA reporting and REACH substance restrictions is compressing addressable market scope.
- Reactive Adhesives:Two-component polyurethane or epoxy systems cure through chemical crosslinking to deliver thermal resistance exceeding 150°C. Premium automotive seating and surgical drape manufacturers specify these where durability justifies 24-48 hour cure cycles.
Hot Melt leads on scale; Water-Based leads on momentum.
Application:
End-use performance thresholds reshape procurement specifications and supplier qualification protocols.
- Hygiene Products:Baby diapers, adult incontinence articles, and feminine hygiene items demand skin-contact safety certification alongside elastic attachment reliability. Procter & Gamble and Essity negotiate direct toll manufacturing agreements, bypassing distributor intermediation.
- Medical:Surgical drapes, wound dressings, and sterilization wraps require FDA 510(k) or EU MDR technical documentation for skin-contact adhesives. ANVISA harmonization with ISO 10993 standards is streamlining import pathways into Brazilian hospital supply chains.
- Automotive:Headliner lamination, seat assembly, and cabin insulation applications prioritize thermal resistance and acoustic damping. Germany's lightweighting requirements redirect specification authority toward suppliers with metallocene polyolefin expertise.
- Packaging:Flexible food and industrial packaging applications emphasize bond clarity and migration resistance. Water-based acrylics are displacing solvent systems where FDA food-contact compliance intersects with sustainability procurement mandates.
Hygiene Products commands volume concentration; Medical is climbing the fastest on regulatory tailwinds.
End User:
Procurement sophistication and certification burden vary sharply across buyer categories.
- Healthcare Providers:Hospital systems and outpatient clinics specify biocompatibility-certified adhesives for wound care and surgical applications. EU Green Deal procurement rules in France and Italy now weight bio-based content at 15-20% of technical scoring.
- Manufacturers:Non-woven converters and finished goods producers dominate volume purchasing, with multi-year supply agreements concentrating volume among adhesive houses with regional production footprints.
- Retailers:Private-label hygiene and medical product distributors specify cost-optimized formulations with reduced testing documentation. Margin pressure from retail consolidation favors hot-melt platforms with commodity feedstock exposure.
- Contractors:Construction and industrial service providers specify non-woven adhesives for geotextile and roofing membrane applications where weathering resistance determines specification.
Manufacturers lead on procurement scale; Healthcare Providers lead on qualification stringency.
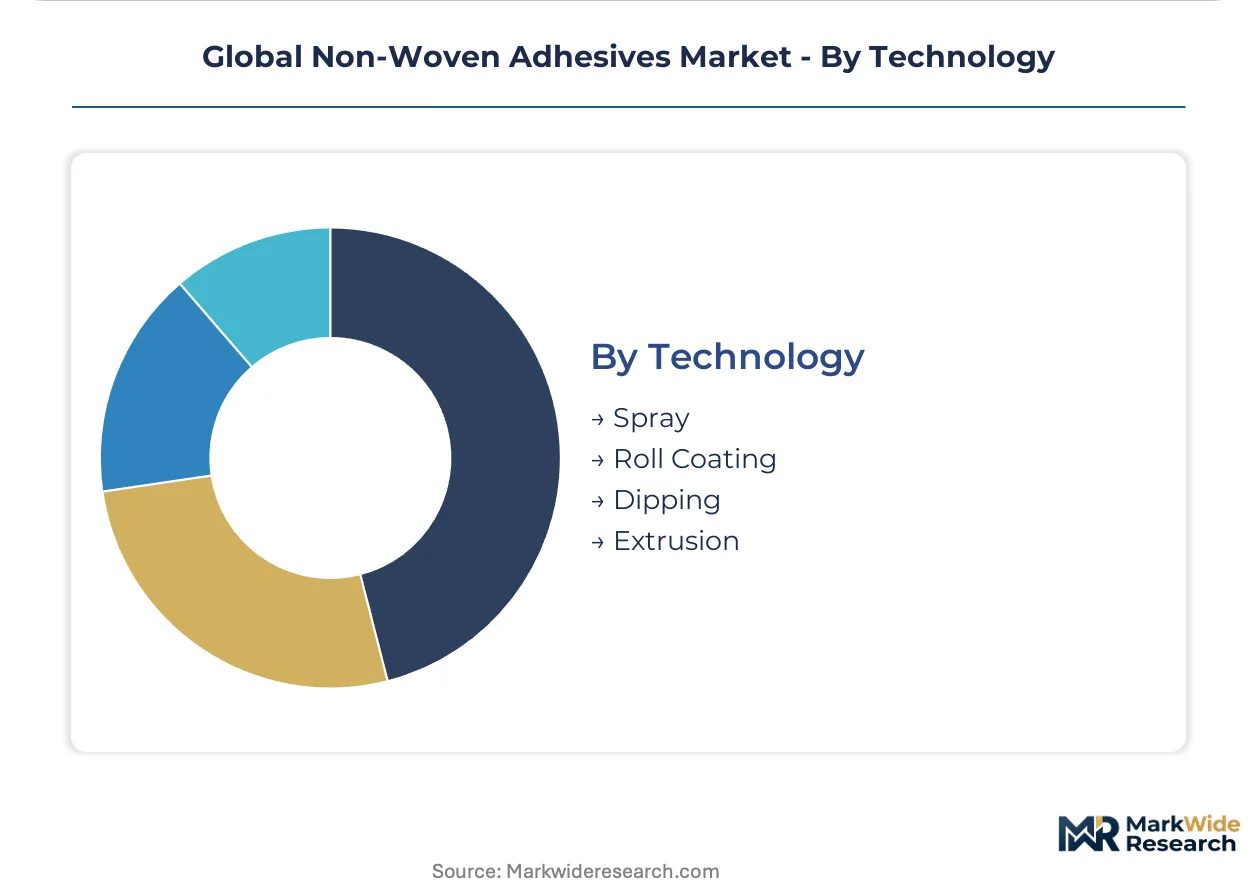
Technology:
Application method determines equipment capital requirements, coating weight precision, and production line speed compatibility.
- Spray:Atomized adhesive deposition enables targeted coverage on complex three-dimensional substrates. Medical drape manufacturers in the US adopt spray systems for consistent coating weights on breathable films.
- Roll Coating:Direct gravure or reverse roll transfer delivers uniform film thickness across flat web substrates. Hot-melt roll coaters dominate high-speed hygiene lines running above 600 units per minute.
- Dipping:Immersion coating saturates non-woven webs for saturation bonding in filtration and insulation applications. Water-based systems predominate where complete fiber encapsulation is required.
- Extrusion:Slot-die or curtain coating extrudes molten adhesive as a continuous film. Automotive interior laminators specify extrusion coating for precise bond line control in visible cabin assemblies.
Roll Coating leads on installed base; Spray leads on precision-driven replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The non-woven adhesives industry traces its modern formulation lineage to German chemical engineering clusters that pioneered hot-melt polymerization for hygiene applications in the 1970s. Industrial scaling subsequently dispersed across North American petrochemical corridors and East Asian manufacturing export zones. Today, specification authority concentrates in jurisdictions with stringent chemical safety frameworks and dense end-use manufacturing ecosystems.
Germany
Automotive interior lightweighting mandates and healthcare infrastructure investments drive adhesive procurement from suppliers with REACH-compliant bio-based portfolios. ECHA substance restrictions under EU REACH force incumbent formulators to reformulate petrochemical hot-melts, compressing formulation windows. The Rhine-Ruhr industrial corridor hosts concentrated adhesive R&D operations serving both automotive OEMs and medical device manufacturers.
United States
FDA biocompatibility standards for skin-contact materials expand adhesive qualification requirements in wound care and surgical drape segments. EPA TSCA Section 8(a) reporting now captures isocyanate-containing adhesive production volumes, creating transparency pressure on reactive system suppliers. Medical drape manufacturers in the Upper Midwest adopt metallocene polyolefin platforms for consistent coating weights on breathable films.
China
Domestic hygiene product manufacturing scales drive volume demand for hot-melt elastic attachment systems in baby diaper and adult incontinence lines. NMPA regulatory harmonization with ISO standards streamlines medical-grade adhesive import pathways for hospital supply chains. The Yangtze River Delta concentration of non-woven converters pulls adhesive formulation expertise toward Shanghai-based technical service centers.
Brazil
ANVISA regulatory harmonization with ISO 10993 standards accelerates import certification timelines for skin-contact medical adhesives. Public hospital procurement expansion under national health infrastructure programs concentrates demand in São Paulo and Rio de Janeiro metropolitan supply chains. Local converters face margin pressure from imported hot-melt platforms sourced through distributor networks.
Japan
Specialty polymer intermediate production for reactive polyurethane systems concentrates among chemical producers serving regional electronics and automotive adhesive markets. METI industrial standards for chemical substance management influence formulation disclosure requirements across supply chains. The Kansai industrial belt maintains concentrated expertise in high-performance reactive adhesives for medical and precision automotive applications.
Global Non-Woven Adhesives Market Competitive Environment
Premium-margin players sit above commodity-margin players across formulation complexity and certification burden dimensions, with medical-grade and automotive thermal-resistance specialists commanding pricing power over standard hygiene-grade suppliers. The vendor base organizes into three functional tiers: integrated chemical conglomerates with captive polymer supply, specialized adhesive houses with formulation expertise, and regional toll manufacturers serving private-label accounts. Consolidation pressure intensifies as direct purchasing agreements from large hygiene converters displace distributor intermediation, while multi-jurisdiction certification timelines favor incumbents with established regulatory affairs infrastructure.
Among the integrated chemical and specialized adhesive houses, Henkel AG and H.B. Fuller Company exemplify the formulation-led archetype with global technical service networks, while Arkema represents the materials science pathway emphasizing bio-based raw material development. These three occupy positions spanning hot-melt platform leadership, breathable barrier specialization, and sustainable polymer innovation respectively. German and Swiss adhesive houses retain concentrated expertise in balancing peel strength with skin sensitization thresholds, though this knowledge base faces generational transfer risks as specialist chemists retire.
| Leading Market Players |
|---|
| Henkel AG |
| H.B. Fuller Company |
| Arkema |
| Bostik |
| MORESCO Corporation |
| Beardow Adams |
| Lohmann-Koester GmbH & Co. KG |
| 3M |
| Dow |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between medical-grade and standard hygiene adhesives creates divergent margin architectures across the value chain, with FDA and EU MDR compliance investments concentrating pricing power among qualified suppliers while commodity hot-melt platforms compete on feedstock arbitrage. This tier divergence manifests in procurement patterns where German automotive OEMs and US hospital systems pay premiums for thermal resistance and biocompatibility documentation, while private-label hygiene converters squeeze toll manufacturers on polyolefin resin pass-through costs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels reflects certification burden and formulation complexity gradients. Price differentiation separates REACH-compliant bio-based formulations from petrochemical hot-melts and distributor-sourced commodity grades. Pricing pressure stems from naphtha cracking margin volatility compressing formulator margins in the standard tier. Private-label hygiene converters exhibit highest price sensitivity, while medical device manufacturers prioritize qualification reliability over unit cost.
Supply Chain Analysis
Specialty polymer intermediate supply rests on German, Japanese, and South Korean chemical producers with concentrated metallocene catalyst and aliphatic isocyanate expertise. Raw material dependencies include polyolefin resins, tackifying rosins, and polyurethane prepolymers sourced through long-term offtake agreements. Single-source vulnerability concentrates in medical-grade isocyanate intermediates where qualification timelines lock buyers to incumbent suppliers. Distribution runs through direct toll manufacturing agreements with large hygiene converters, displacing distributor intermediation in high-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU REACH substance restrictions and FDA biocompatibility mandates continuously elevate qualification barriers, embedding incumbents with certified portfolios while forcing reformulation cycles that favor specialized adhesive houses over commodity suppliers.
For Market Incumbents: Acquire formulation chemist expertise pools, particularly in German and Swiss technical centers where skin sensitization threshold knowledge concentrates among retiring specialists. Backward integration into bio-based feedstock supply secures margin position against petrochemical volatility and aligns with EU Green Deal procurement scoring. Defensive patenting around PLA-bio-PU hybrid platforms blocks emerging entrant access to compostable premium diaper segments. For New Entrants and Emerging Players: Mid-scale Brazilian converters represent an underserved buyer archetype facing margin pressure from imported hot-melt distributor networks. ANVISA harmonization with ISO 10993 standards streamlines certification pathways for skin-contact medical adhesives in São Paulo and Rio de Janeiro hospital supply chains. A toll manufacturing partnership with regional non-woven converters offers the most penetrable go-to-market angle, bypassing direct qualification requirements from multinational hygiene brands. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-jurisdiction certification timelines extend product launch windows by 18-24 months, favoring targets with established FDA 510(k) and EU MDR technical documentation infrastructure. Long-term viability frames around bio-based content thresholds in public healthcare procurement, with French and Italian tender specifications already weighting sustainable sourcing at 15-20% of technical scoring. Watch ECHA per- and polyfluoroalkyl substance restrictions as the inflection signal forcing reformulation of release liners and repellent finishes that interact with adhesive layers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Secures margin stability against naphtha volatility and satisfies EU Green Deal procurement scoring in France and Italy. |
| Long-Term Toll Manufacturing Agreement | Locks volume concentration among global adhesive houses with regional production footprints serving Procter & Gamble and Essity. |
| Regulatory Affairs Infrastructure Investment | Compresses simultaneous FDA 510(k), EU MDR, and Health Canada MDL submission timelines for medical-grade lines. |
| Joint Venture with Regional Converter | Accelerates market entry in Brazil where ANVISA harmonization streamlines import pathways for certified skin-contact adhesives. |
| Green Manufacturing Transition | Aligns with ECHA substance restrictions forcing petrochemical hot-melt reformulation toward compliant bio-based alternatives. |
Study Parameters
Coverage spans Germany, the United States, China, Brazil, and Japan, with primary inputs from each market informing demand calibration and competitive positioning assessment. The research combines interviews with adhesive formulators, procurement leads at non-woven converters, regulatory affairs directors at medical device manufacturers, and distribution channel partners. Secondary validation draws from ECHA substance restriction databases, FDA 510(k) filing records, EPA TSCA Section 8(a) production volume disclosures, and customs trade data for polyolefin resin and specialty isocyanate flows. Bottom-up segment sizing triangulates against top-down chemical consumption models.
Granularity-level modeling operates at product type, application, end user, and technology dimensions, with additional disaggregation by regional regulatory cluster and certification tier. Volume and value outputs derive from elasticity-adjusted consumption forecasts across the projection horizon, with CAGRs computed from fitted growth curves rather than linear extrapolation. Industry-specific inputs include hygiene line speed compatibility thresholds, automotive OEM thermal resistance specifications, and medical device biocompatibility testing cost structures.
Underlying measurement precision varies by segment; medical-grade and automotive thermal-resistance categories carry tighter precision than commodity hygiene grades due to more concentrated supplier disclosure. Forecasts reflect documented assumptions regarding REACH substance restriction implementation timing, crude oil derivative cost trajectories, and converter direct purchasing consolidation trends. A small set of regulatory triggers—ECHA PFAS restrictions, FDA biocompatibility standard revisions, and EU Green Deal procurement rule expansions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Germany Sealants Market
Adhesives & Sealants
Global Medical Adhesives and Sealants Market
Adhesives & Sealants
United States Adhesives Market
Adhesives & Sealants
Melamine Based Adhesives Market
Adhesives & Sealants
Saudi Arabia Adhesives Market
Adhesives & Sealants
South America Adhesives Market
Adhesives & Sealants
Debonding-on-Demand Adhesive Tapes for Electronics Dismantling Market
Adhesives & Sealants
Automotive Adhesives and Sealants Market
Adhesives & Sealants
Asia-Pacific EVA Adhesives Market
Adhesives & Sealants
Global Concrete Bonding Agents Market
Adhesives & Sealants
Die Attach Materials Market
Adhesives & Sealants
Gelatin Bone Glue Market
Adhesives & Sealants
Asia-Pacific Contact Adhesives Market
Adhesives & Sealants
Packaging Adhesives Market
Adhesives & Sealants
EV Adhesives Market
Adhesives & Sealants
Joint Sealants Market