
 Cold Seal Adhesives Market | 2026-2036
Cold Seal Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Seal Adhesives Market Intelligence
ISO 9001 certification cycles are reorganizing supplier eligibility across the cold seal adhesives value chain, pushing mid-tier manufacturers toward documented quality management systems. Henkel sustains broad formulation libraries spanning water-based and hot-melt platforms for European flexible packaging converters. H.B. Fuller anchors North American supply through integrated resin production and toll-coating partnerships with regional tape manufacturers. Avery Dennison specializes in pressure-sensitive cold seal technologies for medical and hygiene label applications where silicone release liners face displacement.
Cold seal adhesives are synthetic polymer coatings—typically natural rubber latex or synthetic polyisoprene dispersions—that bond to themselves under finger pressure without heat activation, functioning at 20–40°C seal initiation temperatures for heat-sensitive substrates. Their primary purpose is enabling high-speed packaging of chocolate, ice cream, and medical devices where thermal exposure would degrade product integrity. Water-based emulsion formulations occupy the largest volume share due to lower volatile organic compound profiles and compatibility with existing gravure coating lines. UV-curable technology segments are expanding fastest in electronics and pharmaceutical blister applications where instant cure rates eliminate web-handling constraints and reduce work-in-process inventory.
FDA food-contact notification requirements govern cold seal adhesive compositions for direct and indirect food packaging in the United States, while REACH restricts specific rubber additives and residual monomers across European supply chains. EPA volatile organic compound regulations for coating operations in California and the Ozone Transport Region are accelerating water-based and biobased technology transitions among domestic formulators. Stakeholders must monitor evolving state-level extended producer responsibility frameworks for packaging materials, as these policies will reshape adhesive recyclability specifications and circular-economy compliance costs.
Market Dynamics
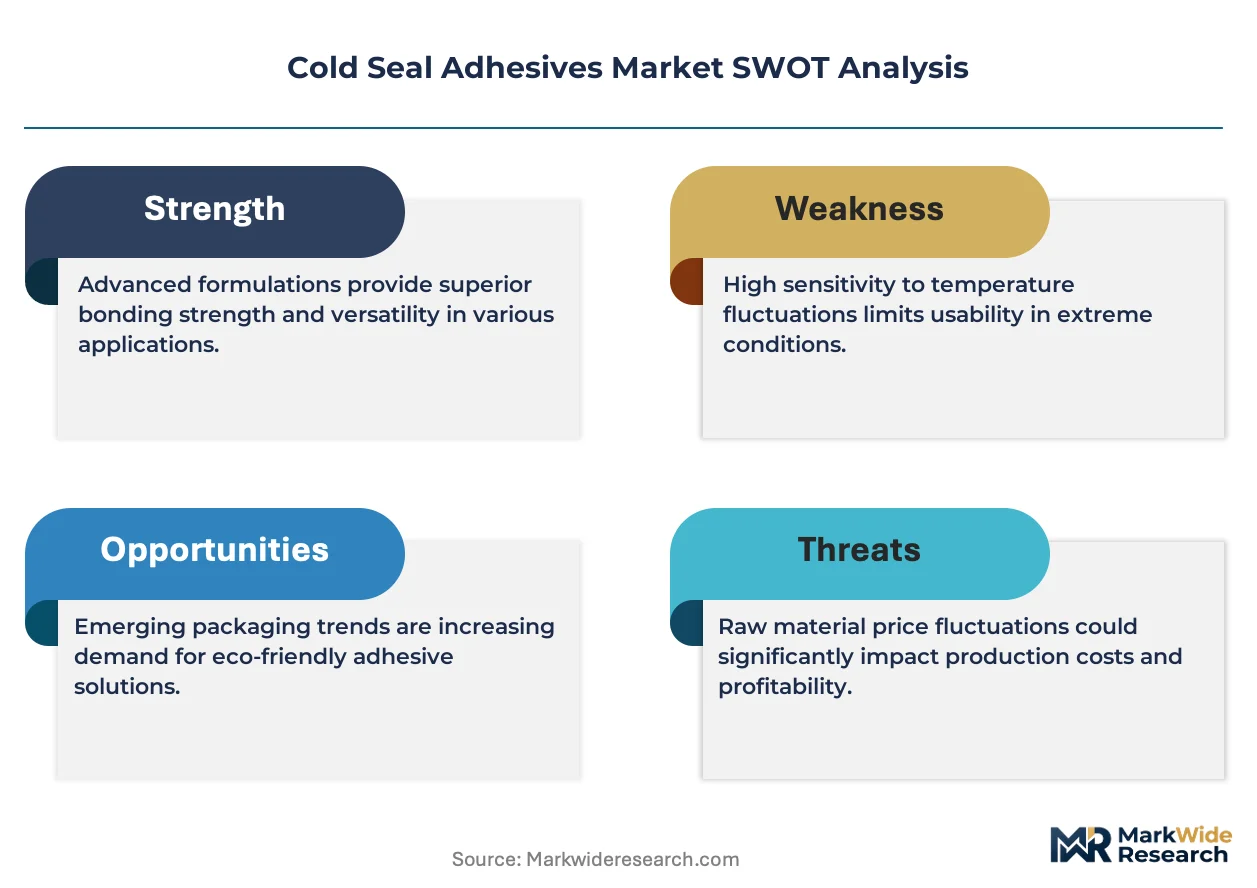
Water-based cold seal adhesive formulations are displacing solventborne systems as California Air Resources Board and Ozone Transport Region EPA limits tighten volatile organic compound ceilings, forcing converters to rebuild coating lines around emulsion chemistry.
Growth Catalysts
- Flexible packaging conversion:Chocolate and ice cream brands abandon heat-seal formats to protect temperature-sensitive contents, pulling cold seal volumes into food packaging.
- REACH additive restrictions:ECHA limits on residual monomers and rubber accelerators are filtering out low-grade suppliers, concentrating demand among REACH-compliant formulators.
- Medical device packaging:Blister and pouch manufacturers adopt cold seal for silicone-sensitive diagnostic components where thermal exposure degrades assay integrity.
Market Restraints
- Natural rubber latex price volatility:Thai and Indonesian plantation supply disruptions transmit directly into polyisoprene dispersion input costs, squeezing converter margins.
- Gravure line retrofit requirements:Water-based emulsion chemistry demands modified drying tunnel configurations and anilox specifications, creating capital barriers for mid-tier coaters.
- Heat-seal substitution in ambient-stable categories:Snack and bakery segments with non-temperature-sensitive contents retain lower-cost thermal bonding, capping cold seal addressable share.
Strategic Opportunities
- Pharmaceutical serialization compliance:EU MDR and FDA track-and-trace mandates favor cold seal blister formats that integrate with tamper-evident label systems without heat damage.
- UV-curable electronics packaging:Instant cure rates eliminate web-handling constraints for semiconductor and battery component protection films.
- Extended producer responsibility frameworks:German and French packaging waste regulations are creating specification demand for recyclable mono-material structures compatible with cold seal disassembly.
Industry Challenges
- ISO 9001 documentation gaps:Mid-tier manufacturers lack quality management system certification cycles required by multinational food and pharmaceutical brand owners.
- Gravure-to-flexo transition complexity:Converters managing hybrid coating assets face workflow inefficiencies and setup waste during format changeovers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Seal Adhesives Market |
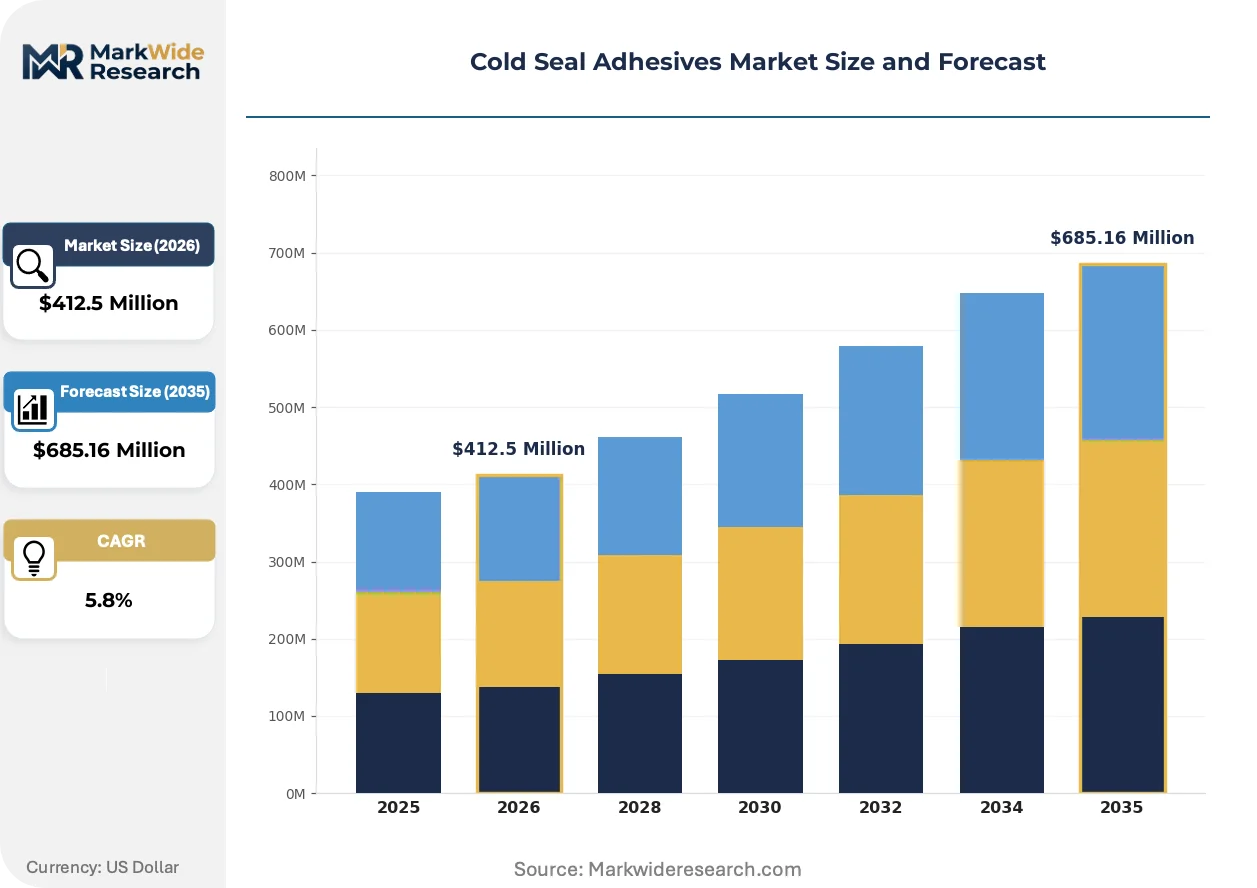
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Pressure-Sensitive, Hot-Melt End User: Packaging, Automotive, Electronics, Construction Application: Flexible Packaging, Labels, Tapes, Adhesive Bonding Technology: Biobased, UV-Curable, Emulsion, Thermoplastic |
| Companies Covered | BASF, Valpac, Henkel, DIC Corporation, ALTANA, H.B. Fuller, Avery Dennison, Sika, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Seal Adhesives Market Strategic Shifts & Innovations
Biobased feedstock integration and instant-cure chemistry platforms are restructuring formulation priorities, while regulatory compliance documentation becomes a competitive differentiator alongside technical performance.
UV-curable cold seal technology is fragmenting the electronics and pharmaceutical blister segments where instant cure eliminates work-in-process inventory and web-handling constraints. Semiconductor manufacturers and battery component suppliers are adopting these systems at accelerated procurement cycles. The technology is fragmenting traditional water-based emulsion dominance in high-value, low-volume protection film applications.
EPA volatile organic compound regulations for coating operations in California and the Ozone Transport Region are compressing solventborne adhesive viability windows. Industrial consequence includes forced capital redeployment toward water-based and biobased formulation infrastructure. Domestic formulators in affected states are responding with accelerated emulsion platform development and toll-manufacturing partnerships to maintain regional supply.
Brand-owner specification consolidation is compressing approved supplier lists as multinational food and pharmaceutical companies centralize procurement around REACH-compliant, ISO 9001-certified formulators. Regional converters and smaller coaters face displacement from qualified vendor pools. Germany and Switzerland exhibit the tightest supplier concentration, where chocolate and pharmaceutical packaging clusters demand documented compliance chains.
Cold Seal Adhesives Market Segmentation
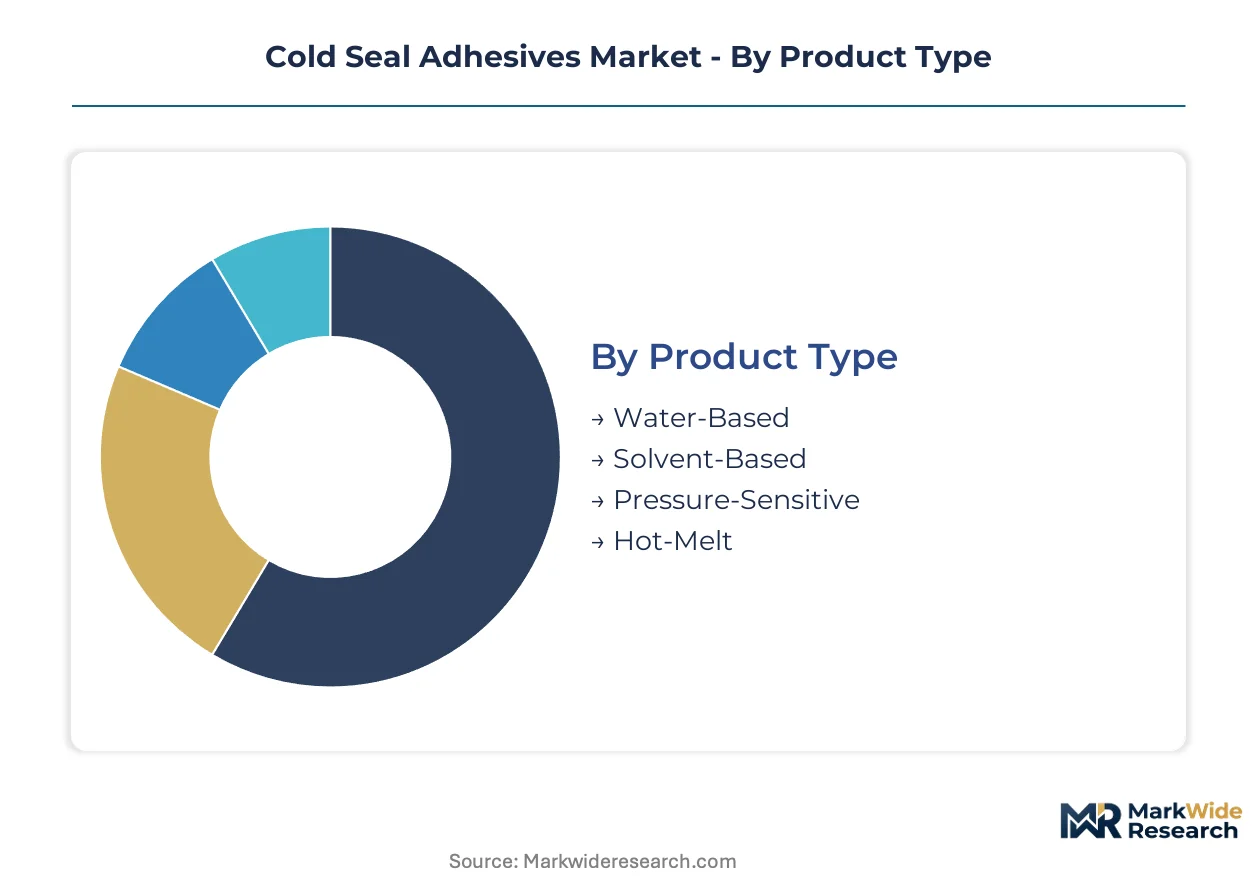
Cold seal adhesive procurement channels diverge sharply by formulation chemistry and end-use compliance requirements. Converter coating lines, pharmaceutical contract packagers, and electronics OEMs each specify distinct performance tiers that reshape supplier qualification pathways.
Product Type:
Water-based emulsions flow predominantly through gravure coating houses serving food packaging, while UV-curable systems penetrate electronics OEM direct procurement.
- Water-Based:Natural rubber latex and synthetic polyisoprene dispersions dominate flexible packaging for chocolate and ice cream. California Air Resources Board VOC limits are forcing solventborne converters to rebuild lines around emulsion chemistry.
- Pressure-Sensitive:Self-adhesive coatings bond under finger pressure without thermal activation. Medical device manufacturers in Germany and Switzerland specify these for silicone-sensitive diagnostic blister formats.
- Solvent-Based:Declining share in regulated markets; residual solvent retention conflicts with FDA food-contact notification requirements.
- Hot-Melt:Thermoplastic formulations serve ambient-stable snack segments where thermal bonding cost advantages outweigh cold seal benefits.
Established volume favors Water-Based; emerging adoption favors Pressure-Sensitive.
End User:
Cost tier stratification separates premium pharmaceutical specifications from commodity packaging volumes.
- Packaging:Flexible food and confectionery applications anchor demand. EU MDR track-and-trace mandates favor cold seal blister formats that integrate tamper-evident systems without heat damage.
- Electronics:Semiconductor and battery component protection films specify UV-curable instant-cure systems. Web-handling constraints disappear with these chemistries.
- Automotive:Interior trim and wire harness applications specify pressure-sensitive cold seals for temperature-sensitive substrates.
- Construction:Building envelope and temporary protection films represent nascent specification development.
Margin concentration sits with Electronics; volume scale concentrates in Packaging.
Application:
Geography determines application maturity, with European pharmaceutical clusters driving premium label and blister specifications.
- Flexible Packaging:Chocolate and ice cream brands abandon heat-seal formats to protect temperature-sensitive contents. German and Swiss converters lead specification density.
- Labels:Medical and hygiene applications displace silicone release liners with pressure-sensitive cold seal alternatives.
- Tapes:Regional tape manufacturers source through toll-coating partnerships with integrated resin producers.
- Adhesive Bonding:General industrial assembly represents price-sensitive spot demand.
Technology premium flows to Flexible Packaging; commoditization risk concentrates in Adhesive Bonding.
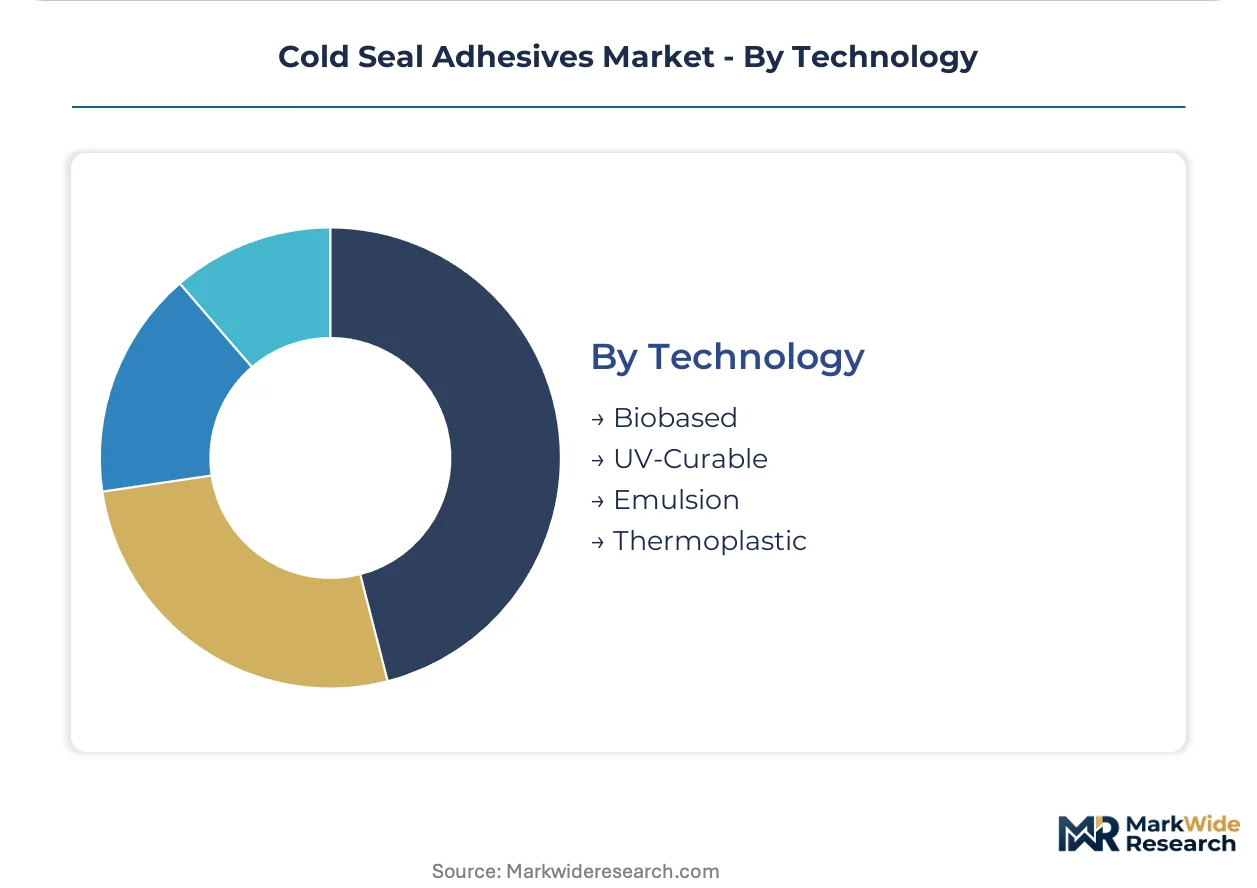
Technology:
Supply concentration among REACH-compliant formulators filters technology access for mid-tier coaters.
- Biobased:Renewable feedstock integration responds to German and French extended producer responsibility frameworks for recyclable mono-material structures.
- UV-Curable:Instant cure eliminates work-in-process inventory for semiconductor manufacturers. These systems are climbing the fastest in high-value, low-volume protection film applications.
- Emulsion:Water-based platforms compatible with existing gravure infrastructure dominate converter capital planning.
- Thermoplastic:Hot-melt chemistry serves ambient-stable categories where cold seal thermal advantages are irrelevant.
Regulatory compliance documentation favors Emulsion; patent-protected differentiation favors UV-Curable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extended producer responsibility frameworks in Germany and France are accelerating specification demand for recyclable mono-material structures compatible with cold seal disassembly. FDA food-contact notification requirements and EPA volatile organic compound regulations in the United States are compressing solventborne formulation viability. REACH compliance documentation is filtering supplier pools across European pharmaceutical and confectionery packaging clusters.
Germany
Chocolate packaging converters in Cologne and pharmaceutical blister manufacturers in Munich drive premium-grade cold seal consumption. ECHA restrictions on residual monomers and rubber accelerators are filtering out low-grade suppliers, concentrating demand among REACH-compliant formulators. The Rhine-Ruhr industrial corridor hosts the densest cluster of gravure coating houses serving flexible food packaging.
United States
California Air Resources Board VOC limits and Ozone Transport Region EPA ceilings are forcing solventborne converters to rebuild coating lines around water-based emulsion chemistry. FDA food-contact notification requirements govern adhesive compositions for direct and indirect food packaging. The Midwest packaging belt spanning Wisconsin and Illinois anchors North American converter capacity for ice cream and frozen food applications.
Switzerland
Medical device manufacturers in Basel and chocolate brands in Zurich specify pressure-sensitive cold seals for silicone-sensitive diagnostic components. Swissmedic pharmaceutical packaging standards align with EU MDR track-and-trace mandates favoring cold seal blister formats. The Swiss-German border region exhibits the tightest supplier concentration for documented compliance chains.
Japan
Electronics OEMs in Osaka and semiconductor manufacturers in Tokyo are adopting UV-curable instant-cure systems for component protection films. METI industrial standards and PMDA pharmaceutical packaging regulations shape formulation specifications. The Kansai industrial corridor leads specification density for battery component protection applications.
France
Extended producer responsibility frameworks for packaging waste are creating demand for recyclable mono-material structures compatible with cold seal disassembly. ANSM pharmaceutical regulations and EFSA food-contact standards govern adhesive selection for medical and confectionery applications. The Île-de-France region hosts contract packagers serving pan-European pharmaceutical serialization compliance.
Cold Seal Adhesives Market Key Industry Players
Listed leaders compete with private specialists across formulation platform breadth, with consolidation pressures intensifying around REACH compliance documentation and ISO 9001 certification cycles. The supplier base stratifies into three archetypes: integrated resin producers with captive coating partnerships, specialty chemical formulators with broad emulsion libraries, and pressure-sensitive technology specialists serving medical label niches. Dominant competitive moves include toll-manufacturing partnerships to maintain regional supply and accelerated emulsion platform development to satisfy state-level VOC regulations.
Among European-based chemical conglomerates, BASF and Henkel occupy positions spanning water-based and hot-melt platforms for flexible packaging converters. H.B. Fuller anchors North American supply architecture through integrated production assets. These three exemplify the scale-driven tier where formulation breadth and regulatory documentation capabilities determine multinational procurement eligibility.
| Leading Market Players |
|---|
| BASF |
| Valpac |
| Henkel |
| DIC Corporation |
| ALTANA |
| H.B. Fuller |
| Avery Dennison |
| Sika |
| 3M |
| Others |
Cost & Logistics Intelligence
REACH certification gates both supplier qualification and price differentiation simultaneously, compressing approved vendor pools while stratifying formulator margins across compliance tiers. ISO 9001 documentation requirements enforce this dual filtering mechanism, forcing mid-tier coaters to absorb certification costs or exit premium procurement channels.
Pricing Analysis
Certification level creates the primary spread between REACH-compliant premium grades and uncertified commodity formulations. Three-tier pricing structure separates pharmaceutical-grade specifications from food-contact standard grades from economy industrial tiers. Price compression runs through the natural rubber latex supply chain as Thai and Indonesian plantation disruptions transmit into polyisoprene dispersion costs. Pharmaceutical brand owners exhibit lowest price sensitivity due to assay integrity requirements, while ambient-stable snack converters retain highest elasticity.
Supply Chain Analysis
Just-in-time inventory strategies dominate among gravure coating houses serving European chocolate packaging, while strategic stockpiling persists among North American medical device manufacturers managing FDA notification lead times. Raw material supply concentrates in Thailand and Indonesia for natural rubber latex, Germany and Belgium for synthetic polyisoprene dispersions, and the United States for acrylic emulsion feedstocks. Single-source vulnerability sits with Southeast Asian plantation supply exposed to climate disruption. Distribution runs through integrated resin producers with captive toll-coating partnerships, bypassing independent merchant distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment—REACH compliance documentation creates switching costs that lock pharmaceutical and food brand owners into qualified supplier relationships. Certification barriers compound this structural advantage.
For Market Incumbents: Shield market position by deepening backward integration into synthetic polyisoprene production to offset Thai latex volatility. Expand ISO 9001 certification coverage across all production facilities before EU MDR serialization mandates tighten vendor eligibility. Prioritize toll-manufacturing partnerships in California and Ozone Transport Region states to capture solventborne converter line retrofits. For New Entrants and Emerging Players: Differentiate on biobased feedstock platforms targeting German and French extended producer responsibility frameworks. Penetrate the electronics OEM segment through UV-curable instant-cure formulations where patent landscapes remain less dense than water-based emulsions. Pursue direct procurement relationships with semiconductor manufacturers in Japan rather than converter intermediaries. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates where cold seal adhesive divisions represent non-core revenue pools with stranded REACH documentation assets. Long-term viability hinges on regulatory compliance infrastructure rather than formulation chemistry alone. Watch for ECHA additive restriction announcements as inflection indicators that will force consolidation among sub-scale formulators lacking reformulation R&D capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Polyisoprene | Captive resin production insulates margin from Thai latex price volatility. |
| REACH Compliance Documentation Investment | ECHA additive restrictions filter competitor pools to certified formulators. |
| UV-Curable Platform Development | Instant-cure chemistry captures electronics OEM direct procurement channels. |
| Toll-Coating Partnership Expansion | Regional coating capacity satisfies California CARB VOC retrofit demand. |
| Biobased Feedstock Integration | Renewable formulations align with German packaging waste regulations. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, including gravure coating line managers, pharmaceutical contract packaging procurement leads, flexible food packaging technical directors, and electronics OEM materials engineers. Secondary validation drew from ECHA regulatory filings, FDA food-contact notification databases, SEC 10-K disclosures of listed chemical conglomerates, and European flexible packaging association technical reports. Bottom-up volume estimates from converter capacity utilization were triangulated against top-down formulation consumption models.
Across the analysis window, forecasts were constructed using a segmented analytical framework spanning formulation chemistry, end-use compliance tier, application format, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections incorporating natural rubber latex price volatility assumptions and REACH enforcement intensity indices. Model inputs included gravure line retrofit capital expenditure cycles, pharmaceutical serialization mandate timelines, and electronics OEM protection film specification shifts.
Decision-makers should treat outputs as directional under base assumptions of sustained REACH enforcement and stable Thai plantation supply; material deviation would warrant model refresh. Specific revision triggers include ECHA additive blacklist expansion, California CARB threshold reductions, or sustained polyisoprene dispersion cost divergence from latex benchmarks. Revision becomes warranted when regulatory compliance cost inflation crosses converter willingness-to-pay thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Floor Adhesive Market
Adhesives & Sealants
Hot Melt Adhesives Market
Adhesives & Sealants
Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Packaging Adhesives Market
Adhesives & Sealants
Mexico Adhesives Market
Adhesives & Sealants
Temporary Bonding Adhesives Market
Adhesives & Sealants
Spain Adhesives Market
Adhesives & Sealants
South America Construction Adhesives Market
Adhesives & Sealants
Europe EVA Adhesives Market
Adhesives & Sealants
Asia-Pacific Cyanoacrylate Adhesives Market
Adhesives & Sealants
Plastic Adhesives Market
Adhesives & Sealants
Asia-Pacific Laminated Adhesives Market
Adhesives & Sealants
France Sealants Market
Adhesives & Sealants
Europe Acrylic Adhesives Market
Adhesives & Sealants
Hybrid Silane-Terminated Polymer Adhesives for EV Battery Pack Assembly Market
Adhesives & Sealants
Global Hygiene Adhesives Market