
 Electric Vehicle Supply Equipment (EVSE) Market | 2026-2036
Electric Vehicle Supply Equipment (EVSE) Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Supply Equipment (EVSE) Market Foresight
Chinese charging module manufacturers is pivoting toward higher-power liquid-cooled platforms for 350 kW and above systems. ABB leverages its industrial electrification heritage to anchor European highway corridor deployments. Tesla sustains proprietary connector dominance in North America while expanding its Supercharger network to third-party access. Schneider Electric differentiates through integrated energy management software bundled with hardware installations.
Electric Vehicle Supply Equipment encompasses the hardware, software, and communication protocols that transfer electrical energy from grid infrastructure to battery electric vehicles, with power ratings spanning from 1.4 kW residential Level 1 units to 350 kW+ liquid-cooled DC fast chargers employing silicon carbide power electronics. DC Fast Chargers command the highest capital intensity per unit and attract margin concentration from fleet operators requiring sub-30-minute turnaround times. Workplace and Fleet Depot installations are outpacing residential growth as commercial entities prioritize captive charging infrastructure for route-depot logistics. Connector standardization around CCS Combo 2 in Europe and CCS Combo 1 in North America is fragmenting aftermarket adapter demand.
The US Department of Transportation NEVI program mandates Buy America compliance for federally funded charging stations, reshaping domestic supply chain requirements. The EU F-Gas Regulation and CE marking directives enforce cooling system refrigerant standards and electrical safety protocols for public access equipment. China's GB/T standards and dual carbon goals mandate domestic interoperability while accelerating state-grid integration. Stakeholders must monitor how evolving ISO 15118 bidirectional charging standards reshape hardware-software coupling requirements and warranty liability structures.
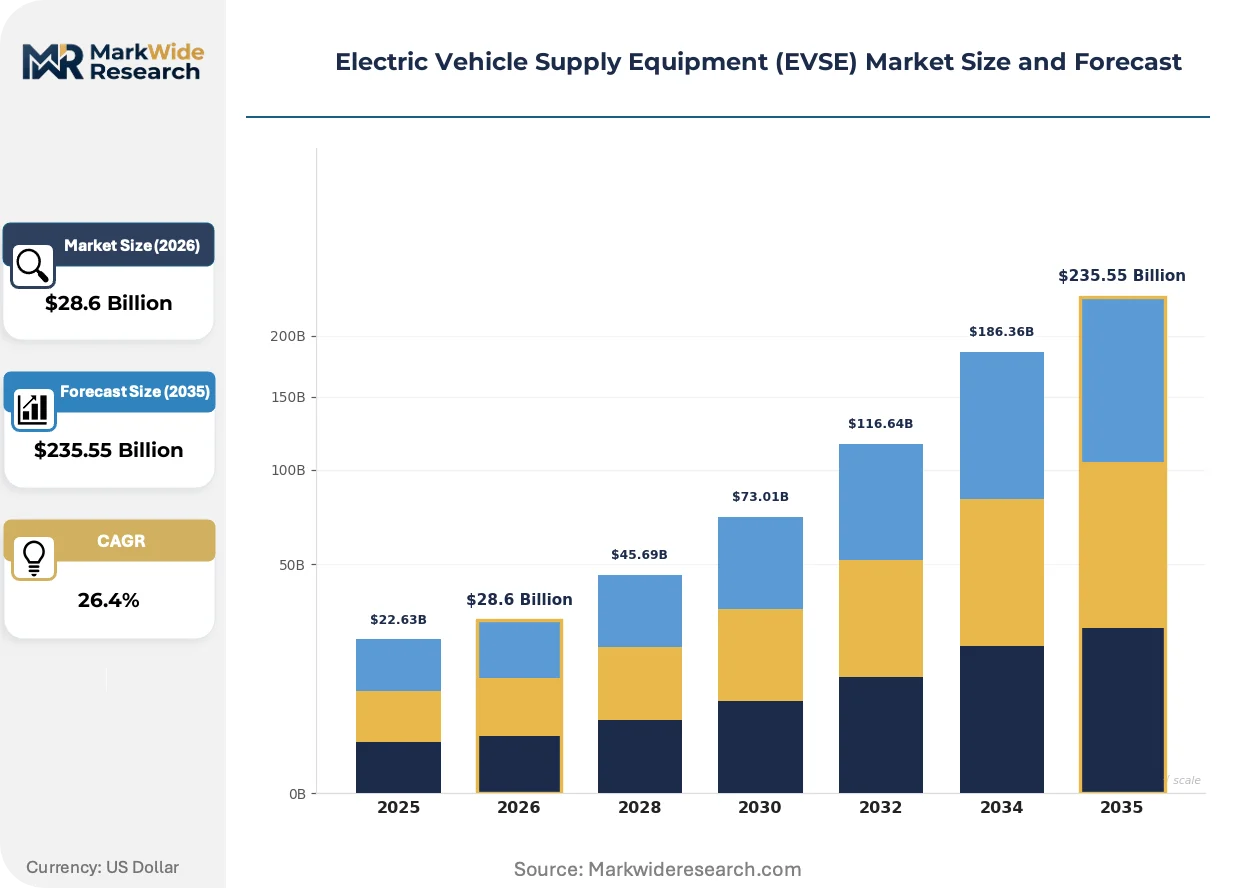
Market Dynamics
Fleet operators are consolidating charging infrastructure procurement around DC fast chargers with sub-30-minute turnaround requirements, compressing hardware replacement cycles and forcing suppliers to accelerate liquid-cooled platform development.
Growth Catalysts
- NEVI Program Mandates:The US Inflation Reduction Act and NEVI program are accelerating federally funded highway corridor deployments through Buy America compliance requirements.
- Logistics Electrification:Commercial route-depot operators are replacing overnight Level 2 installations with captive DC fast charging infrastructure to minimize vehicle downtime.
- Silicon Carbide Semiconductors:Wide-bandgap power electronics are enabling 350 kW+ systems with reduced thermal losses and smaller form factors.
Market Restraints
- Copper and Rare Earth Volatility:Charging cable conductors and permanent magnet materials face commodity price swings that compress hardware margins.
- Chinese Module Concentration:State-backed domestic capacity expansion has concentrated high-power rectifier supply within a single geography.
- ISO 15118 Implementation Gaps:Bidirectional charging standards remain incompletely harmonized across certification bodies, delaying V2G rollout.
Strategic Opportunities
- India PLI Incentives:Production-linked schemes for advanced chemistry cell manufacturing are creating localized EVSE demand from domestic automakers.
- Integrated Energy Management:Convergence of solar PV, battery storage, and charging hardware is opening bundled software-hardware contracts.
- Workplace Depot Channel:Direct sales to commercial real estate operators bypass traditional distributor markups and capture recurring service revenue.
Industry Challenges
- Power Electronics Talent Scarcity:Silicon carbide inverter design and thermal engineering expertise commands premium compensation and extends R&D timelines.
- CE Marking Certification Bottlenecks:EU F-Gas Regulation compliance for liquid-cooled systems adds 6-12 month validation periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Supply Equipment (EVSE) Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $235.55 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Level 1 Chargers, Level 2 Chargers, DC Fast Chargers, Wireless Chargers, Ultra-Fast Chargers Installation Type: Residential, Commercial, Workplace, Public Transit Stations, Fleet Depots Connector Type: Type 1 (SAE J1772), Type 2 (Mennekes), CHAdeMO, CCS Combo 1, CCS Combo 2 End User: Individual Consumers, Municipal Authorities, Commercial Fleet Operators, Retail Establishments, Hospitality Sector |
| Companies Covered | ChargePoint, ABB, Tesla, EVBox, Eaton, Schneider Electric, Wallbox, Delta Electronics, EVgo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Supply Equipment (EVSE) Market Shifts & Advancements
Hardware architectures are fragmenting into interoperable subsystems while software layers capture an expanding share of total contract value. This decoupling is redrawing competitive boundaries between component specialists and integrated platform vendors.
Silicon carbide MOSFETs are modularizing power conversion stages within DC fast chargers. Tier 1 automotive suppliers are adopting these devices for 800V architectures. This modularity is compressing thermal management costs while enabling field-upgradeable rectifier blocks.
The EU F-Gas Regulation is banning refrigerants with high global warming potential from cooling systems. Equipment manufacturers are retrofitting designs with CO2-based heat pumps. Public access chargers in Germany and France face the tightest compliance deadlines.
Commercial buyers are unbundling hardware ownership from energy management services. Fleet operators now lease charging assets while purchasing optimization software separately. This bifurcation is most pronounced in California and the Netherlands where electricity tariff complexity rewards algorithmic load management.
Electric Vehicle Supply Equipment (EVSE) Market Segmentation
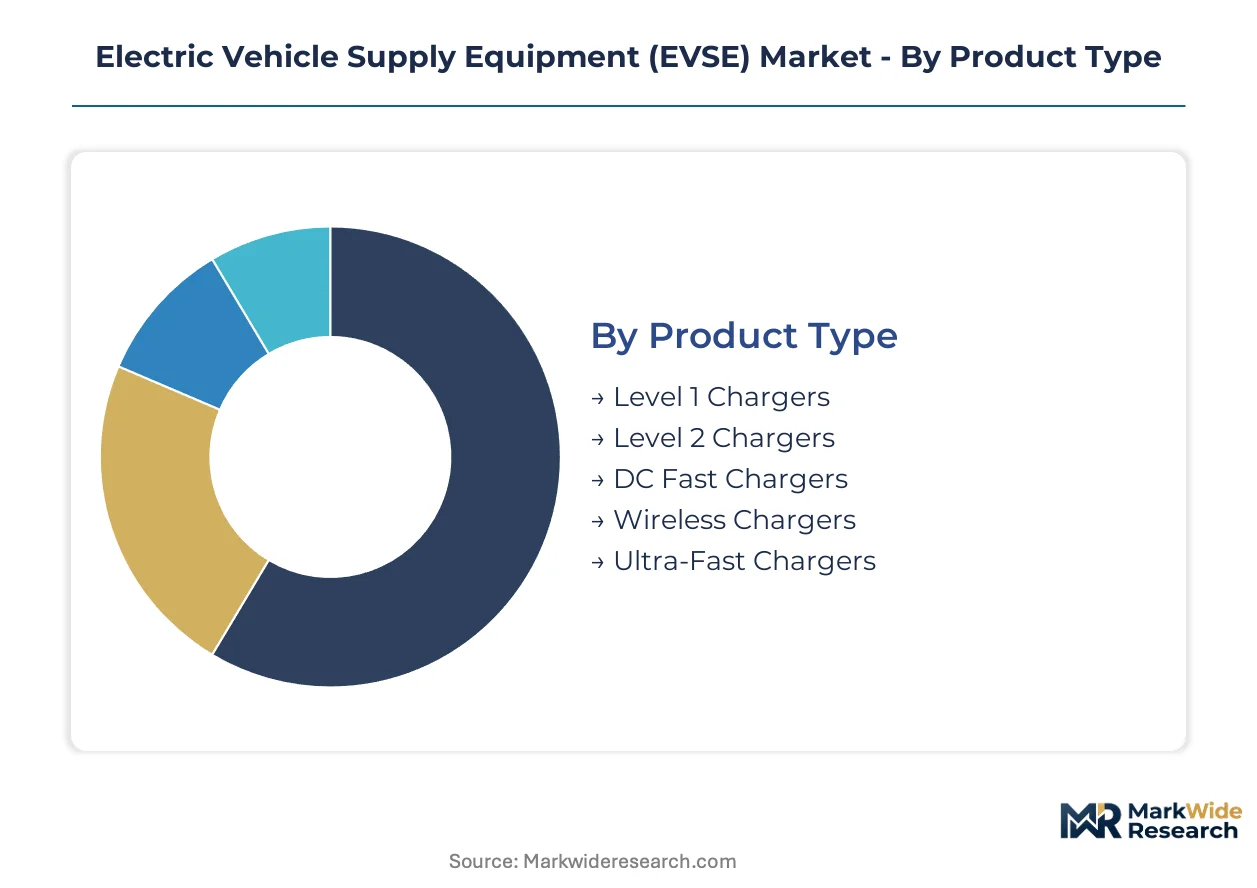
Segmentation reveals how capital intensity, deployment urgency, and regulatory compliance reshape procurement patterns across the EVSE value chain. Power rating tiers and installation contexts determine margin structures, software bundling opportunities, and warranty liability exposure for suppliers.
Product Type:
Volume concentrates in low-power residential units while premium capture clusters around liquid-cooled high-power systems for commercial deployment.
- Level 1 Chargers:These 1.4 kW units operate on standard 120V residential outlets without dedicated circuit requirements. Demand clusters in North American single-family housing where overnight dwell times accommodate slow charging cycles, constrained by utility rate structures that discourage daytime plug-in.
- Level 2 Chargers:Operating at 7-19 kW via 240V circuits, these units dominate workplace and multi-unit residential installations. Procurement concentrates in California and the Netherlands where electricity tariff complexity rewards managed charging schedules through integrated software platforms.
- DC Fast Chargers:50-350 kW systems with silicon carbide power electronics enable sub-30-minute charging cycles for highway corridor and fleet depot applications.
- Wireless Chargers:Inductive power transfer systems eliminate connector wear but face efficiency penalties and higher capital costs per kilowatt.
- Ultra-Fast Chargers:350 kW+ liquid-cooled platforms target commercial route-depot operators minimizing vehicle downtime through megawatt-scale power conversion.
Mature deployment sits with Level 1 Chargers. Newer deployment is concentrated in Ultra-Fast Chargers.
Installation Type:
Customer type determines site preparation costs, permitting complexity, and recurring service contract attach rates.
- Residential:Single-family and multi-unit dwelling installations require utility coordination for service upgrades and load management integration. Demand concentrates in suburban markets where overnight parking availability supports Level 2 adoption, though HOA restrictions and electrical panel capacity constrain penetration in older housing stock.
- Commercial:Retail, hospitality, and office property installations prioritize customer dwell-time monetization through parking fee structures. Procurement clusters in Germany and France where EU F-Gas Regulation compliance deadlines accelerate liquid-cooled system replacement cycles.
- Workplace:Employer-sponsored charging infrastructure captures captive daytime demand from commuters with limited home charging access.
- Public Transit Stations:Municipal bus and rail depot electrification requires high-availability systems with redundant power modules.
- Fleet Depots:Logistics operators consolidate procurement around DC fast chargers with route-optimized dispatch software integration.
Commercial installations anchor current revenue concentration. Fleet Depots are climbing the fastest as electrification mandates compress replacement timelines.
Connector Type:
Standardization patterns fragment procurement across regulatory jurisdictions, forcing adapter inventory costs and certification duplication.
- Type 1 (SAE J1772):This single-phase North American standard supports Level 1 and Level 2 charging up to 19.2 kW. Deployment concentrates in US residential and workplace markets where NEVI program Buy America compliance reshapes domestic supply chain requirements.
- Type 2 (Mennekes):The European three-phase standard enables 43 kW AC charging through integrated in-vehicle rectifiers. Demand clusters in German highway corridor deployments where ABB and Siemens anchor infrastructure rollouts with CE marking compliance.
- CHAdeMO:The Japanese DC fast charging standard supports bidirectional power flow for vehicle-to-grid applications.
- CCS Combo 1:North American DC fast charging extension of Type 1 with additional high-current pins for 350 kW systems.
- CCS Combo 2:European DC fast charging extension of Type 2, mandated by EU interoperability regulations for public access equipment.
Type 1 connectors dominate installed base volume. CCS Combo 2 systems are expanding most quickly through EU Green Deal infrastructure targets.
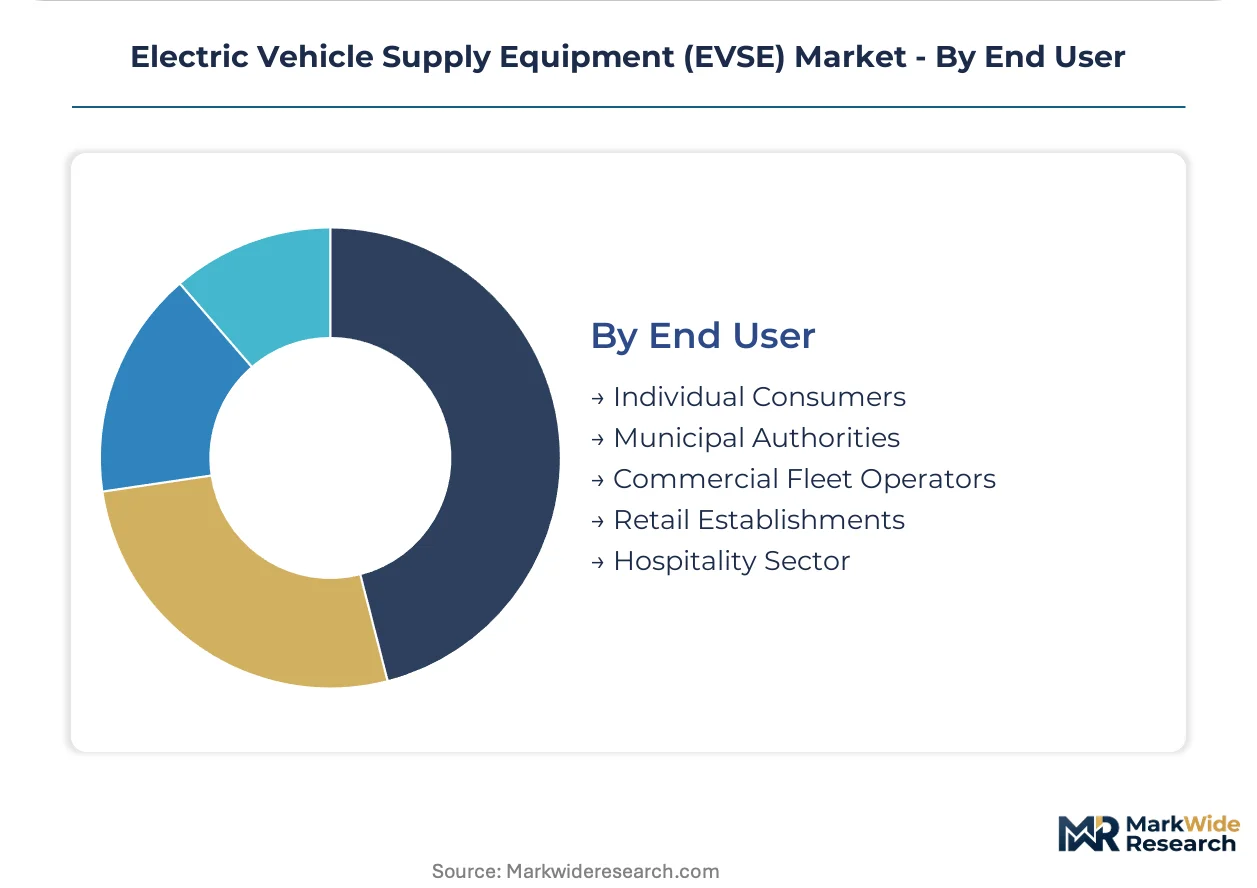
End User:
Purchasing authority and capital allocation cycles determine contract structure, financing terms, and software bundling penetration.
- Individual Consumers:Retail purchasers prioritize upfront hardware cost and installation simplicity over energy management features. Procurement concentrates in online channels and big-box retailers, constrained by electrician availability and permit processing delays in fragmented municipal jurisdictions.
- Municipal Authorities:Public transit agencies and city governments procure through competitive bidding with sustainability mandates and local content requirements. Deployment clusters in Chinese state-grid integration projects where GB/T standards mandate domestic interoperability.
- Commercial Fleet Operators:Route-depot logistics companies require sub-30-minute turnaround times and captive charging infrastructure.
- Retail Establishments:Shopping centers and convenience stores monetize charging through parking fee structures and dwell-time extension.
- Hospitality Sector:Hotels and resorts deploy charging as amenity differentiation for guest segments with EV adoption concentration.
Individual Consumers represent the largest installed base segment. Commercial Fleet Operators are gaining share fastest through consolidated procurement of high-power depot infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper concentrate from Chilean mines and rare earth deposits in China's Inner Mongolia anchor the upstream material flows feeding EVSE manufacturing clusters across three continents.
United States
Fleet electrification by Amazon, FedEx, and UPS is compressing procurement timelines for DC fast chargers along interstate corridors. The NEVI program mandates Buy America compliance for federally funded stations, reshaping domestic supply chain requirements. California's Central Valley hosts the densest concentration of depot installations, with logistics operators consolidating around captive charging infrastructure.
Germany
Automotive OEM electrification roadmaps are pulling demand for ultra-fast charging along Autobahn corridors. The EU F-Gas Regulation enforces refrigerant standards for liquid-cooled systems, adding 6-12 month certification periods. Bavaria's Munich-Stuttgart industrial corridor anchors ABB and Siemens deployments with CE marking compliance.
China
State Grid Corporation infrastructure targets dominate installation volumes through GB/T standard mandates. Dual carbon goals accelerate state-backed procurement of high-power rectifier modules. Shenzhen and Shanghai metropolitan clusters concentrate liquid-cooled platform manufacturing for 350 kW systems.
India
Domestic automaker electrification is creating localized demand through PLI scheme incentives for advanced chemistry cell manufacturing. The Central Electricity Authority issues technical standards for grid integration of public charging networks. Maharashtra's Mumbai-Pune corridor hosts the fastest-growing depot installation base.
Netherlands
Electricity tariff complexity rewards algorithmic load management, unbundling hardware ownership from energy services. EU Green Deal interoperability mandates concentrate CCS Combo 2 deployments. The Randstad conurbation leads workplace charging adoption through employer-sponsored infrastructure.
Electric Vehicle Supply Equipment (EVSE) Market Competitive Landscape
Global majors compete with regional champions across certification compliance and software-hardware bundling strategies. The vendor base stratifies into three tiers: integrated platform vendors capturing bundled contracts, component specialists supplying rectifier modules, and regional installers securing local permitting advantages. Strategic archetypes include industrial electrification incumbents pivoting from grid infrastructure, automotive-tier suppliers leveraging 800V power electronics expertise, and energy management software vendors backward integrating into hardware. Dominant competitive moves center on M&A for thermal engineering talent and strategic partnerships with fleet operators for captive depot deployments.
Within the integrated platform tier, ABB and Schneider Electric exemplify industrial electrification heritage applied to highway corridor and workplace depot segments. Tesla occupies a distinctive position through proprietary connector ecosystems and third-party network access expansion. ChargePoint represents the scale-driven archetype with direct sales channels bypassing traditional distributor markups.
| Leading Market Players |
|---|
| ChargePoint |
| ABB |
| Tesla |
| EVBox |
| Eaton |
| Schneider Electric |
| Wallbox |
| Delta Electronics |
| EVgo |
| Others |
Supply & Pricing Matrix
State-backed Chinese module producers anchor high-power rectifier supply, compressing margins for Western hardware vendors while fleet operators exploit procurement consolidation to demand extended warranty bundling. This ownership structure enforces pricing discipline through volume-scale procurement mandates and captive state-grid integration requirements.
Pricing Analysis
Warranty and service bundling now separates premium hardware vendors from commodity module suppliers, with liquid-cooled platforms commanding three-year service contracts versus one-year coverage for air-cooled systems. Price differentiation rests on CE marking tier and silicon carbide power electronics certification, with EU F-Gas Regulation compliance adding certification cost premiums. Pricing pressure stems from copper conductor volatility and rare earth magnet cost swings. Individual consumers exhibit highest price sensitivity through retail channel procurement, while commercial fleet operators prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from NEVI-funded US deployments and EU Green Deal procurement mandates force buyers to qualify rectifier modules from both Chinese and South Korean suppliers. Manufacturing concentrates in China, South Korea, and Germany for power electronics assembly. Raw material dependencies center on Chilean copper concentrate, Chinese rare earth processing, and Taiwanese silicon carbide wafer fabrication. Single-source vulnerability runs through high-power cooling system compressors. Distribution runs through direct sales channels to fleet operators and commercial real estate developers, bypassing traditional electrical distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
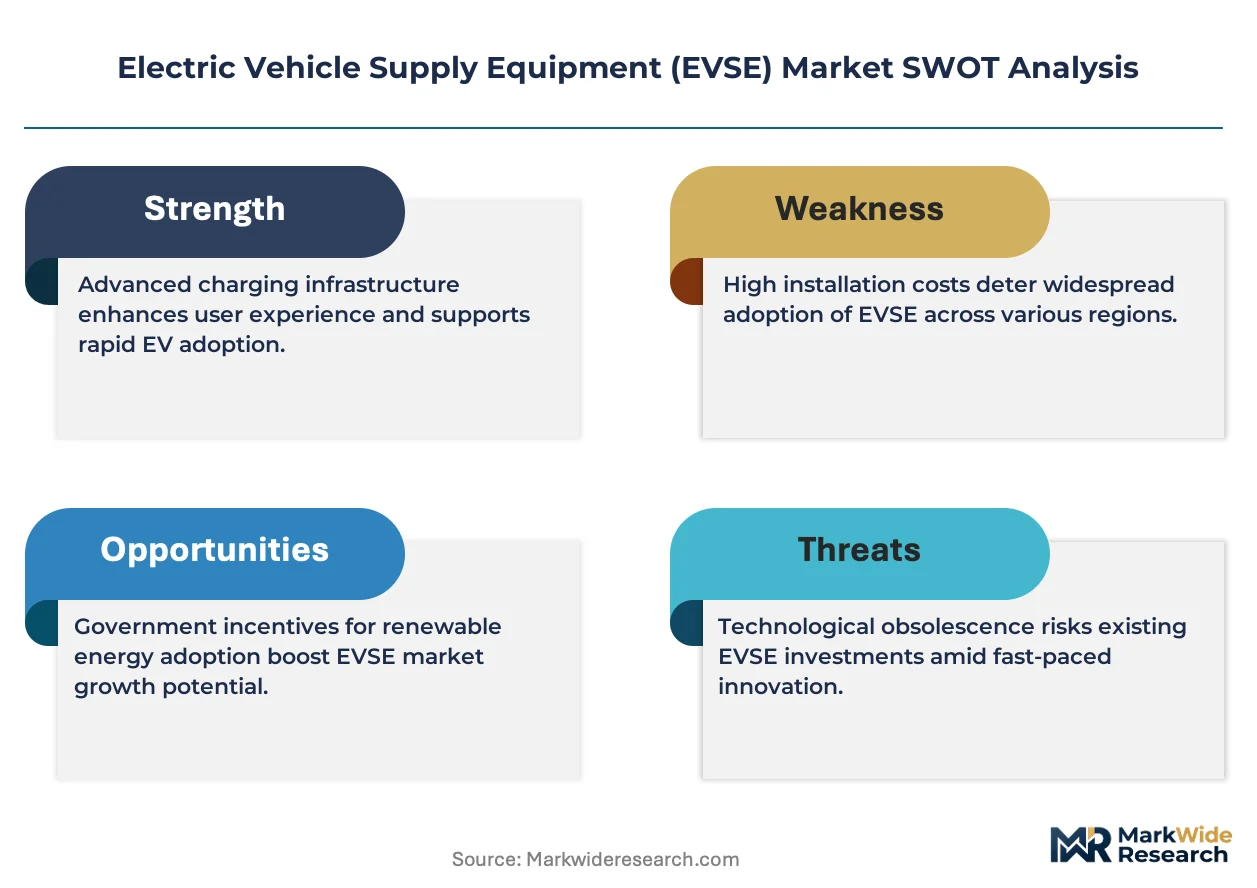
Silicon carbide MOSFET fabrication capacity constraints prop hardware pricing power, as wide-bandgap power electronics talent scarcity extends supplier lead times and limits second-source qualification.
For Market Incumbents: Anticipate margin compression from Chinese module price competition by deepening captive thermal engineering capabilities and securing NEVI-compliant domestic assembly capacity. Defensive consolidation should target liquid-cooled platform specialists with CE marking expertise to compress EU certification timelines. Priority lever sits with backward integration into silicon carbide inverter design. For New Entrants and Emerging Players: Capture white-space in India's PLI-scheme corridor through localized rectifier module assembly partnerships with domestic automakers. Workplace depot channel penetration offers lowest competitive density versus saturated highway corridor deployments. Go-to-market angle should bundle algorithmic load management software with hardware lease structures. For Investors and Strategic Acquirers: First ISO 15118 bidirectional certification completion by a Tier 1 vendor is the leading indicator that V2G revenue streams will reshape hardware-software valuation multiples. Long-term viability favors integrated platform vendors with energy management software attach rates above hardware-only specialists. Acquisition target archetype: thermal engineering boutiques with automotive 800V expertise. Signal to watch: fleet operator captive infrastructure buildout announcements exceeding threshold scale.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid-Cooled Platform Development | Enables 350 kW+ systems for fleet depot electrification under EU F-Gas Regulation deadlines. |
| Silicon Carbide Supply Agreement | Secures wide-bandgap power electronics from Taiwanese wafer fabricators for thermal efficiency gains. |
| NEVI Compliance Certification | Unlocks federally funded highway corridor deployments through Buy America domestic content verification. |
| Energy Management Software Integration | Captures recurring revenue from California and Netherlands electricity tariff optimization services. |
| Fleet Operator Partnership | Locks in captive depot infrastructure procurement with Amazon, FedEx, and UPS electrification mandates. |
Research Methodology
Document review covered SEC 10-K filings, EU F-Gas Regulation compliance databases, and NEVI program funding disclosures, complemented by interviews with charging hardware procurement directors, fleet electrification managers, and power electronics R&D leads. Secondary validation drew from IEA EV outlook reports, EIA electricity demand data, and customs trade records for copper and rare earth material flows. Bottom-up installation volume estimates triangulated against top-down infrastructure spending projections.
Segmented outputs across power rating tiers, installation contexts, connector standards, and end-user categories populated the analytical framework over the projection horizon. CAGRs derived from logistic diffusion curves fitted to fleet electrification adoption patterns and state-backed infrastructure deployment schedules. Key inputs included silicon carbide device cost decline trajectories and ISO 15118 implementation timelines across certification bodies.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare earth export restrictions and bidirectional charging standard harmonization delays. Deviation in Chinese state-grid procurement targets or NEVI funding appropriations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle Charger Operations and Maintenance Services Market
Electric Vehicle Charging
HVAC Electronically Commutated Motor (ECM) Market
Electric Vehicle Charging
Copper in Electric Vehicle Market
Electric Vehicle Charging
Germany Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
DC Chargers Market
Electric Vehicle Charging
Western Europe Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
India Battery Swapping for Electric Two-Wheelers Market
Electric Vehicle Charging
EV Charging Cables Market
Electric Vehicle Charging
Electric Vehicle Charging Plugs Market
Electric Vehicle Charging
EV Charging Point Market
Electric Vehicle Charging
Spain Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
United States Electric Vehicle Charging Systems and Equipment Market
Electric Vehicle Charging
EV Charging Station Market
Electric Vehicle Charging
Airport Charging Stations Market
Electric Vehicle Charging
Electric Vehicle Charging Station Raw Materials Market
Electric Vehicle Charging
Electric Vehicle Rapid Charger Market