
 Electric Vehicle Charging Station Raw Materials Market | 2026-2036
Electric Vehicle Charging Station Raw Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Charging Station Raw Materials Market Insights
Software-defined power management is decoupling raw material specifications from fixed hardware generations, allowing charging station OEMs to upgrade thermal performance without full enclosure replacements. BASF leverages its polymer compounding expertise to supply flame-retardant housing grades that meet evolving cable insulation standards. POSCO anchors Asia-Pacific supply security through integrated stainless steel and electrical steel output for connector and transformer cores. DuPont differentiates via high-performance resin systems that sustain dielectric integrity under repeated fast-charging thermal cycling.
Electric vehicle charging station raw materials encompass conductive metals, engineered polymers, thermal interface compounds, and protective coatings formulated to withstand sustained electrical loads, UV exposure, and temperature swings from minus 40 to plus 85 degrees Celsius. These materials enable reliable energy transfer between grid infrastructure and vehicle battery systems across residential, commercial, and fleet deployment contexts. Copper dominates conductor applications due to superior electrical conductivity, though aluminum is gaining ground in overhead charging infrastructure where weight reduction offsets resistivity trade-offs. Power control units represent a concentrated margin pool because silicon carbide and gallium nitride semiconductors demand specialized ceramic substrates and thermal management compounds. Enclosures command premium pricing when formulated with halogen-free flame retardants that satisfy EU REACH and RoHS substance restrictions.
FDA oversight of per- and polyfluoroalkyl substances is pressuring fluoropolymer alternatives in cable jacketing, while EPA lifecycle assessment protocols are reshaping supplier environmental disclosure requirements for US market access. ECHA REACH substance evaluations and EU Green Deal carbon border adjustments are tightening compliance costs for non-European polymer and metal feedstock exporters. China's SAMR national standards for EV charging interoperability are mandating specific copper purity grades and connector plating thicknesses that filter supplier eligibility. Stakeholders must monitor divergence between regional material certification regimes to avoid stranded inventory and qualification delays.
Market Dynamics
Silicon carbide power semiconductors are compressing thermal management requirements across DC fast-charging architectures, forcing raw material suppliers to reformulate ceramic substrates and interface compounds for higher cycling frequencies without degrading dielectric properties.
Growth Catalysts
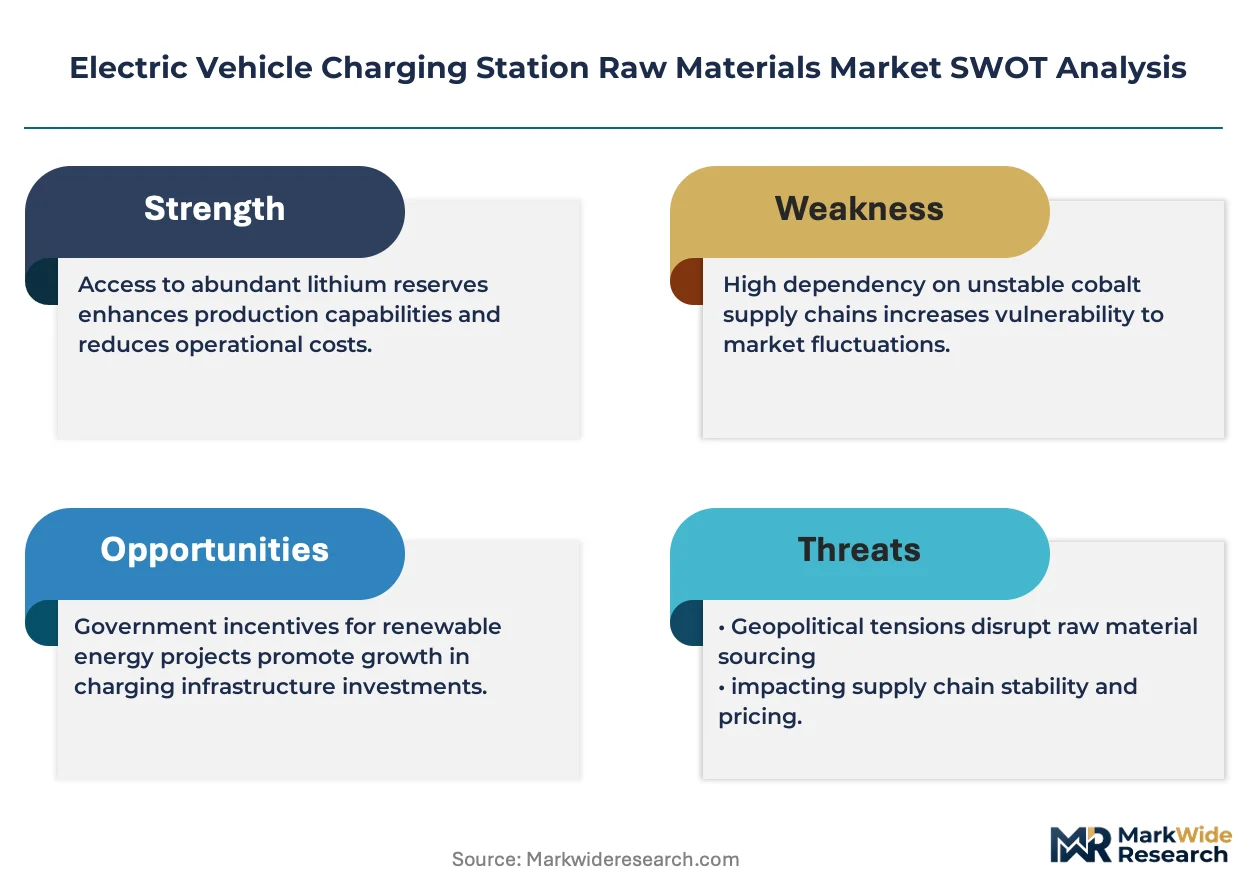
- EU Green Deal carbon border adjustments:European fleet operators are accelerating procurement of high-power charging hardware ahead of phased compliance deadlines, concentrating demand for copper and electrical steel with verified emission footprints.
- Fleet electrification mandates:Commercial vehicle operators in Germany and France face binding zero-emission procurement quotas that tighten material traceability requirements through supply chain corridors.
- Integrated battery-electric corridors:China's consolidated supply chain infrastructure is pulling refined copper and polymer feedstock into dedicated EV charging manufacturing zones.
Market Restraints
- Copper concentrate supply concentration:Smelter output from Chile and Peru dominates refined cathode availability, exposing connector and busbar manufacturers to concentrate export disruptions and treatment charge volatility.
- Fluoropolymer regulatory friction:EPA lifecycle assessment protocols and FDA per- and polyfluoroalkyl substance oversight are pressuring cable jacketing formulations, forcing reformulation investments before alternative chemistries achieve equivalent dielectric ratings.
- Aluminum resistivity trade-offs:Overhead charging infrastructure designers face structural limitations when substituting aluminum conductors for copper, requiring larger cross-sections that increase mechanical load and installation complexity.
Strategic Opportunities
- India's PLI scheme for ACC battery storage:Production-linked incentives for domestic cell manufacturing are creating captive demand for charging infrastructure raw materials as OEMs localize pack assembly.
- Software-defined power management convergence:Firmware-upgradable thermal control systems are decoupling enclosure material specifications from fixed hardware generations, enabling aftermarket upgrade revenue streams.
- Halogen-free flame retardant formulations:REACH and RoHS substance restrictions are opening premium pricing tiers for housing grades that satisfy evolving cable insulation standards without legacy brominated additives.
Industry Challenges
- Ceramic substrate qualification timelines:Silicon carbide module packaging requires specialized aluminum nitride and silicon nitride substrates with extended thermal cycling validation protocols that delay supplier onboarding.
- Cross-regional certification divergence:China's SAMR national standards for connector plating thickness and copper purity grades create stranded inventory risk for exporters serving multiple jurisdictional requirements simultaneously.
- Electrical steel grain orientation expertise:Transformer core manufacturing for high-frequency charging applications faces acute metallurgical engineering shortages that constrain capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Charging Station Raw Materials Market |
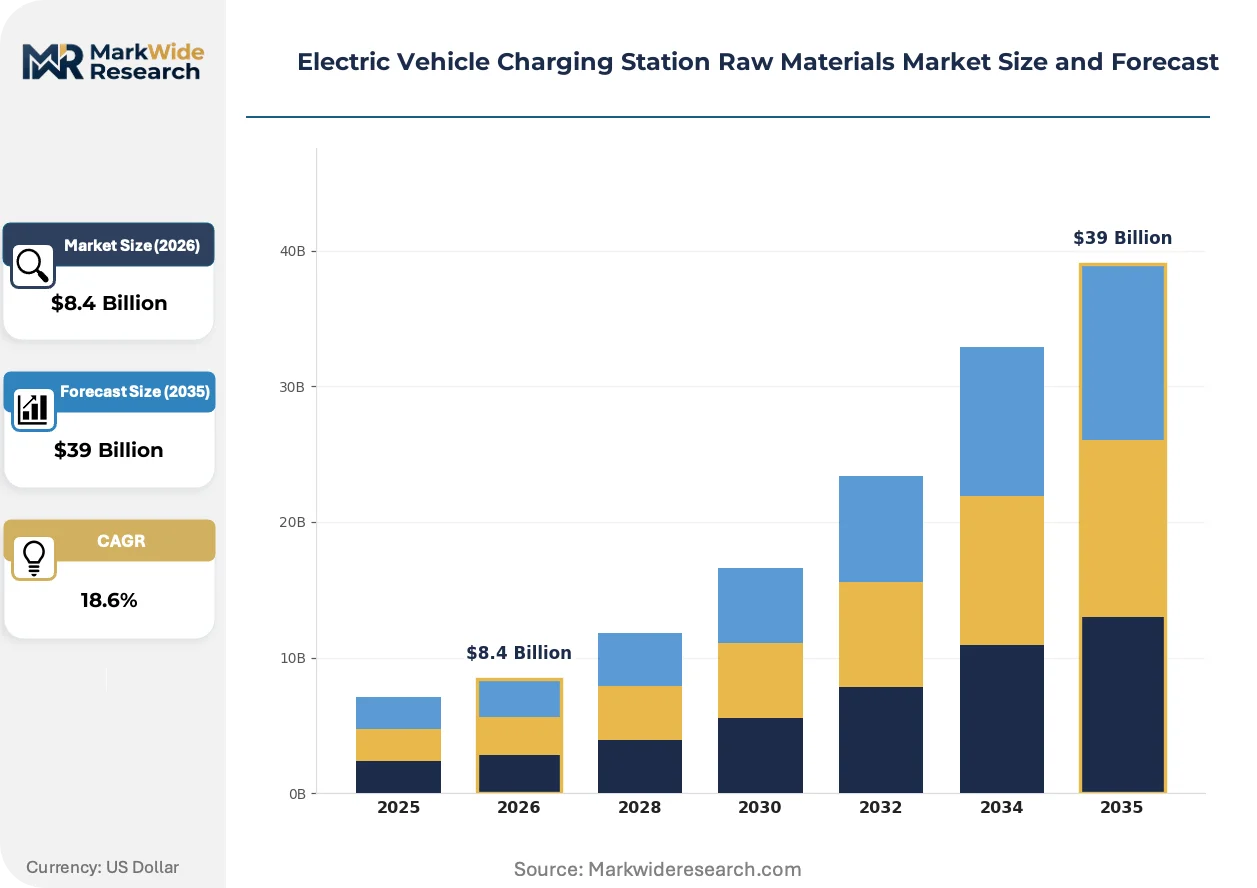
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $39 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Copper, Aluminum, Silver, Graphite Component: Charging Cables, Connectors, Power Control Units, Enclosures End User: Municipalities, Commercial Facilities, Residential Locations, Fleet Operators Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | BASF, Ryerson Holding, POSCO, thyssenkrupp AG, DOMO Chemicals, Covestro AG, SABIC, Evonik Industries, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Charging Station Raw Materials Market Trends and Innovations
Raw material specifications are decoupling from fixed hardware generations as software-defined architectures enable thermal performance upgrades without full enclosure replacements, compressing product development cycles and reformulating supplier value capture.
Silicon carbide MOSFETs are electrifying power conversion efficiency in DC fast-charging modules, cutting switching losses by half relative to silicon IGBTs. Tier 1 charging station OEMs are qualifying SiC-based designs for 350kW+ deployments ahead of fleet operator procurement waves. This semiconductor transition is electrifying demand for aluminum nitride ceramic substrates and silver-sintered die-attach materials that withstand junction temperatures above 175 degrees Celsius.
ECHA REACH substance evaluations are tightening compliance costs for non-European polymer and metal feedstock exporters seeking EU market access. The EU Green Deal's carbon border adjustment mechanism will phase in embodied emission reporting requirements for imported copper and steel by 2026. Charging station enclosure suppliers are responding by qualifying halogen-free flame-retardant grades from BASF and DuPont that preemptively satisfy substance restrictions.
Fleet operators are consolidating procurement authority into centralized technical specifications that bypass traditional distributor channels. Large logistics and transit agencies in Germany and France are issuing unified material certification requirements across multi-site charging deployments. This concentration is most visible in China's integrated battery-electric supply chain corridors, where state-owned fleet operators negotiate directly with copper smelters and polymer compounders for volume-indexed pricing.
Electric Vehicle Charging Station Raw Materials Market Segmentation
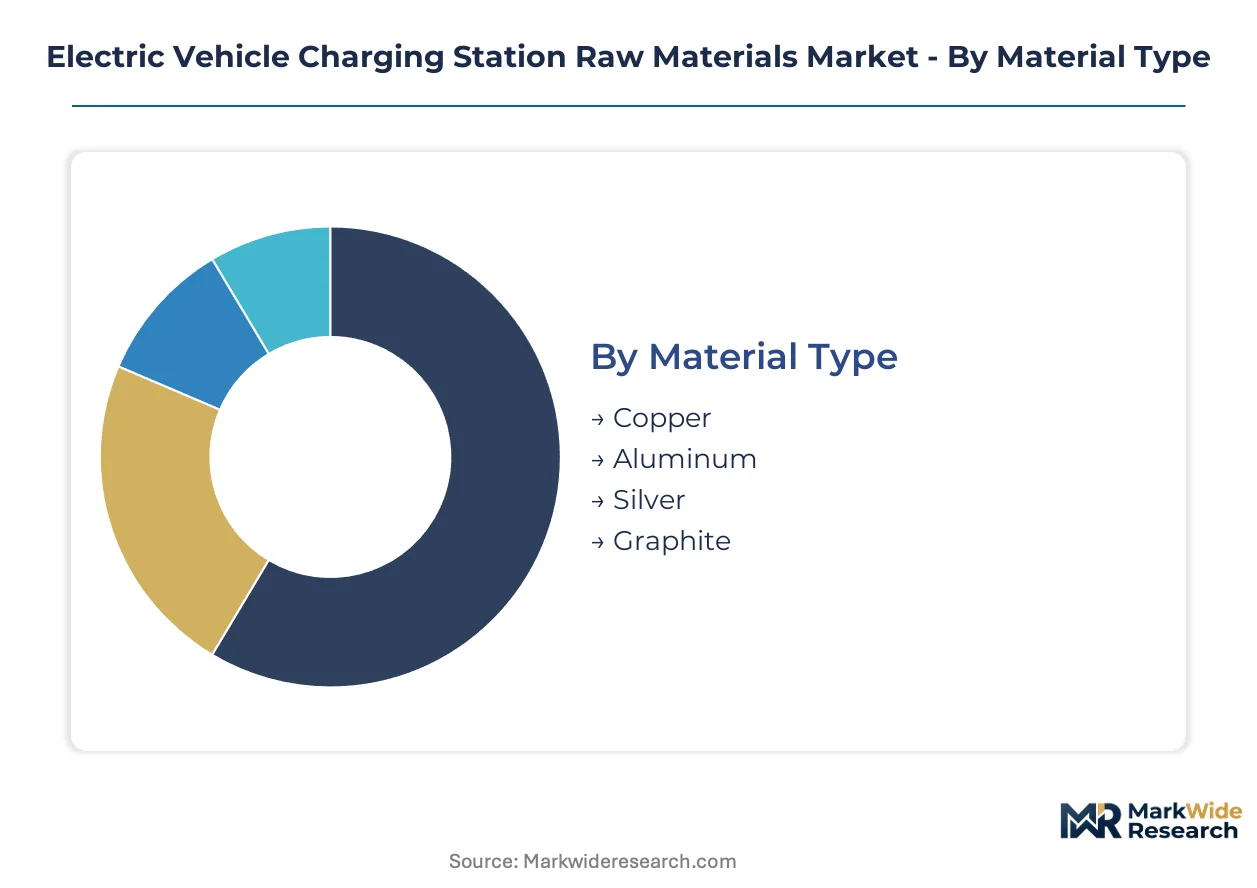
Raw material specifications diverge sharply across charging station architectures, with certification burdens clustering around high-voltage components and thermal management systems. Each segment carries distinct metallurgical and polymer requirements that filter supplier eligibility through regional compliance regimes.
Material Type:
REACH substance restrictions and SAMR purity mandates impose tiered certification burdens, with conductive metals facing emission-footprint verification and graphite suppliers navigating battery-grade qualification protocols.
- Copper:Refined cathode with conductivity exceeding 100% IACS dominates busbar and connector applications. Fleet operators in Germany and France are consolidating procurement around verified low-emission smelter output ahead of EU carbon border adjustments. Copper sits at the top of the volume ranking, with graphite climbing the fastest.
- Aluminum:6xxx-series extrusions and cast alloys reduce weight in overhead pantograph and cable support structures. China's integrated corridors are pulling secondary aluminum into enclosure manufacturing zones to offset concentrate import dependency. Aluminum trades conductivity for mechanical efficiency in structural applications.
- Silver:Electroplated finishes and sintered die-attach pastes serve high-frequency switching contacts in silicon carbide modules. SAMR plating thickness standards filter supplier eligibility for connector exports to Chinese OEMs.
- Graphite:Synthetic and natural flake grades supply thermal interface pads and battery anode precursors. India's PLI scheme for ACC storage is creating captive demand as domestic cell manufacturing scales.
Copper commands the largest procurement volumes across all charging architectures, while graphite feedstock is expanding most quickly behind battery-integrated infrastructure buildouts.
Component:
Margin structures concentrate in semiconductor-adjacent assemblies where ceramic substrate qualification timelines extend supplier onboarding cycles.
- Charging Cables:Multi-conductor assemblies with halogen-free TPU or XLPE jacketing withstand repeated flexing and UV exposure. EPA lifecycle assessment protocols are pressuring fluoropolymer alternatives before equivalent dielectric ratings mature. Cable assemblies generate recurring replacement revenue across fleet depots.
- Connectors:Silver-plated copper contacts and liquid-cooled pin configurations manage 350kW+ thermal loads. ECHA REACH substance evaluations restrict legacy brominated flame retardants in housing adjacent to high-touch surfaces. Connector qualification spans electrical, mechanical, and environmental stress testing.
- Power Control Units:Silicon carbide MOSFET modules mounted on aluminum nitride ceramic substrates convert AC grid input to DC battery voltage. Extended thermal cycling validation protocols delay second-source approval for substrate suppliers. PCUs capture concentrated value through semiconductor content.
- Enclosures:Glass-filled polyamide and polycarbonate grades integrate EMI shielding and IP67 sealing for outdoor deployment. BASF and DuPont formulations preemptively satisfy evolving EU substance restrictions. Enclosure material selection governs field serviceability and upgrade pathways.
Power control units anchor the premium pricing tier, with charging cables generating the steadiest replacement demand across installed bases.
End User:
Procurement authority concentration varies by scale, with fleet operators bypassing distributor channels and municipalities navigating fragmented approval workflows.
- Fleet Operators:Centralized technical specifications for multi-site depot charging drive volume-indexed negotiations directly with copper smelters and polymer compounders. Binding zero-emission procurement quotas in Germany and France tighten material traceability requirements through supply chain corridors.
- Municipalities:Public curb-side and transit hub installations face extended permitting cycles that delay raw material commitment timing. Budget constraints favor standardized connector interfaces over custom architectural integration.
- Commercial Facilities:Retail and workplace charging prioritizes aesthetic enclosure finishes and dual-use parking infrastructure compatibility. Property managers balance upfront hardware costs against tenant attraction and retention value.
- Residential Locations:Single-family and multi-unit dwelling installations emphasize plug-and-play simplicity and utility interconnection compliance. Homeowner associations and local electrical codes create jurisdictional fragmentation in material specification.
Fleet operators dominate procurement volume, with commercial facilities gaining share fastest behind workplace charging mandates and retail loyalty programs.
Distribution Channel:
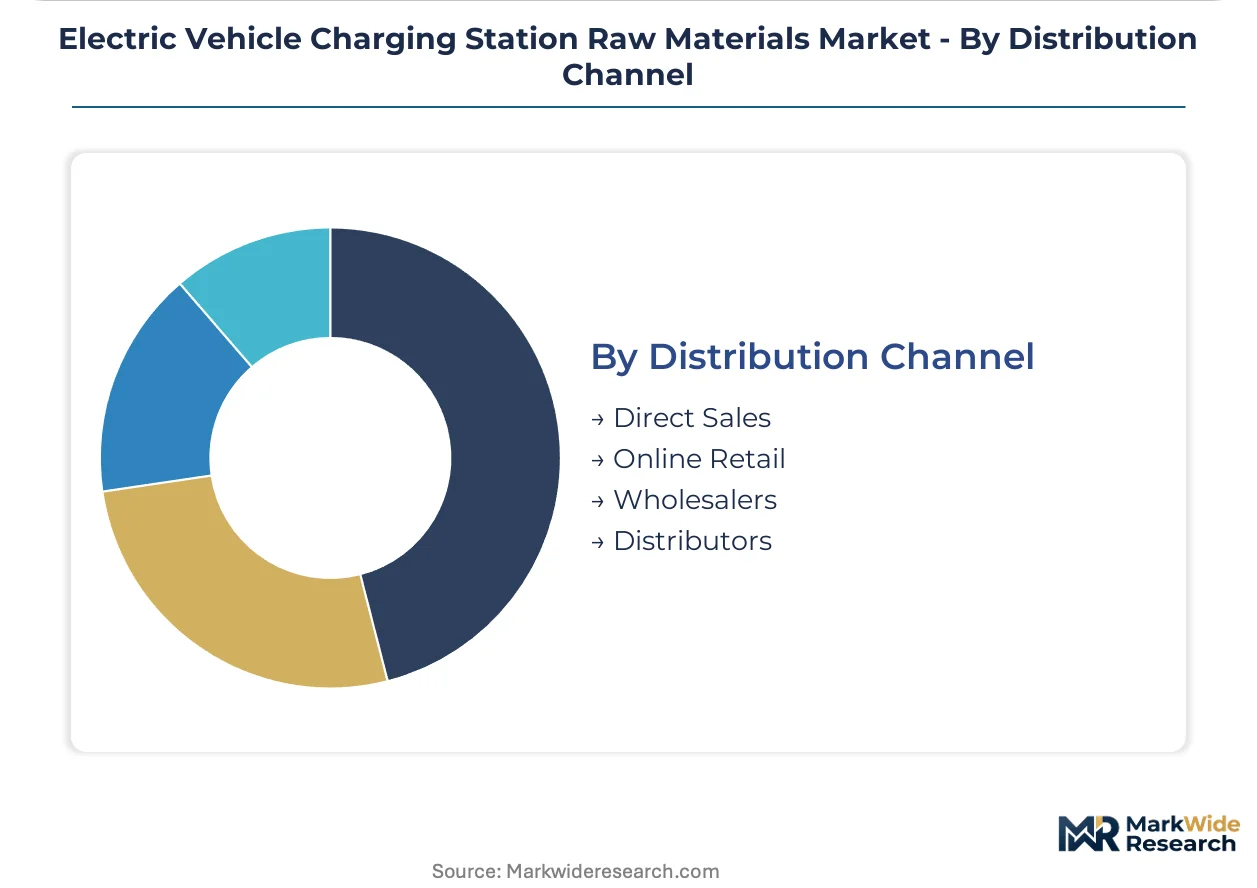
Channel selection correlates with order scale and technical specification complexity, with direct relationships commanding volume thresholds that exclude smaller installers.
- Direct Sales:Tier 1 charging station OEMs negotiate annual copper cathode and electrical steel contracts with POSCO and integrated smelters. Long-term agreements embed price adjustment clauses tied to LME benchmarks and treatment charge indices.
- Distributors:Regional electrical supply houses stock connector and cable assemblies for contractor installation networks. Inventory positioning requires balancing SAMR-certified SKUs for export orders against domestic specification variants.
- Wholesalers:Bulk polymer pellet and metal rod distributors serve enclosure fabricators and cable extrusion houses. Volume breaks and just-in-time delivery terms compete with mill-direct alternatives.
- Online Retail:E-commerce platforms capture residential replacement cable and adapter sales with limited technical consultation. Product listings emphasize safety certification badges over material composition disclosure.
Direct sales channels transact the largest individual orders, with distributor networks expanding most quickly to serve accelerating contractor installation capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's integrated battery-electric corridors pull refined copper volumes that Germany's fleet electrification mandates cannot match ton-for-ton, yet both geographies are tightening material traceability through divergent regulatory instruments.
China
State-owned fleet operators negotiate directly with copper smelters for volume-indexed pricing across Yangtze River Delta manufacturing zones. SAMR national standards mandate specific copper purity grades and connector plating thicknesses that filter supplier eligibility for domestic OEM qualification. Shenzhen and Shanghai anchor dedicated EV charging manufacturing corridors where polymer compounders co-locate with enclosure fabricators.
Germany
Binding zero-emission procurement quotas for commercial vehicle fleets concentrate demand for high-power charging hardware with verified emission footprints. KBA enforcement of EU Green Deal carbon border adjustments accelerates procurement timelines ahead of phased compliance deadlines. North Rhine-Westphalia hosts transformer core manufacturers facing acute metallurgical engineering shortages for electrical steel grain orientation expertise.
United States
FDA oversight of per- and polyfluoroalkyl substances pressures fluoropolymer alternatives in cable jacketing formulations before equivalent dielectric ratings mature. EPA lifecycle assessment protocols reshape supplier environmental disclosure requirements for market access. Michigan and Texas industrial clusters absorb silicon carbide module packaging demand despite extended ceramic substrate qualification timelines.
India
Production-linked incentives for domestic ACC battery storage under the PLI scheme create captive demand for charging infrastructure raw materials as OEMs localize pack assembly. BIS standards for EV charging interoperability filter connector and cable assembly imports. Gujarat and Tamil Nadu manufacturing zones attract copper rod and polymer pellet distributors serving enclosure fabricators.
France
ANSM coordination with EU REACH substance evaluations tightens compliance costs for polymer and metal feedstock exporters seeking market access. National zero-emission vehicle mandates bind transit agencies to unified material certification requirements across multi-site charging deployments. Auvergne-Rhône-Alpes concentrates automotive supplier engineering talent for thermal management compound formulation.
Electric Vehicle Charging Station Raw Materials Market Competitive Landscape
Top-tier vendors anchor integrated material supply, while specialized compounders occupy niche certification tiers. The vendor base stratifies across metallurgical conglomerates, polymer formulators, and semiconductor-adjacent substrate specialists. Three archetypes dominate: integrated steel and non-ferrous metal producers, halogen-free flame-retardant polymer compounders, and ceramic substrate qualification leaders. Capacity expansion into electrical steel grain orientation and backward integration into copper smelting represent the dominant competitive vectors.
Among German chemical conglomerates, BASF and Covestro AG exemplify the polymer compounding archetype with REACH-compliant formulation expertise. POSCO anchors Asia-Pacific supply security as a Korean integrated steel producer. These three entities occupy positions that span multiple certification regimes simultaneously.
| Leading Market Players |
|---|
| BASF |
| Ryerson Holding |
| POSCO |
| thyssenkrupp AG |
| DOMO Chemicals |
| Covestro AG |
| SABIC |
| Evonik Industries |
| DuPont |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide power semiconductor transitions are compressing thermal management cost economics while concentrating procurement authority among fleet operators capable of underwriting long-term copper cathode contracts. This technology shift simultaneously elevates ceramic substrate pricing tiers and filters supplier eligibility through extended qualification protocols that reshape supply chain power dynamics.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing zones are reshaping price floors for refined copper and polymer feedstock as state-owned fleet operators negotiate volume-indexed contracts directly with smelters. Three-tier pricing structure across premium, standard, and economy levels separates SAMR-certified connector grades from domestic specification variants, with certification tier and volume scale as the primary differentiation drivers. Cost compression in standard-grade aluminum extrusions is intensifying because secondary smelter expansions are loosening concentrate import dependency. Fleet operators exhibit the lowest price sensitivity due to centralized procurement authority, while residential installers through online retail channels face acute margin pressure.
Supply Chain Analysis
Acute metallurgical engineering shortages in Germany's North Rhine-Westphalia cluster and China's Shenzhen corridor are constraining electrical steel grain orientation capacity expansion for transformer core manufacturing. Supply concentrates in Chile and Peru for copper concentrate, China for refined cathode and polymer compounding, and South Korea for electrical steel output. The value chain draws from copper concentrate, ceramic substrates, and halogen-free flame-retardant resins as critical inputs. Single-source vulnerability in Chilean smelter output exposes connector manufacturers to concentrate export disruptions. Distribution runs through direct annual contracts for Tier 1 OEMs, regional electrical distributors for contractor networks, and bulk wholesalers for enclosure fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by binding zero-emission fleet procurement quotas that generate predictable raw material demand across multi-year infrastructure deployment cycles.
For Market Incumbents: Cement supply security through backward integration into copper smelting or captive electrical steel capacity in Asia-Pacific manufacturing corridors. Deepen qualification relationships with silicon carbide module packagers ahead of ceramic substrate supply bottlenecks. Prioritize halogen-free flame-retardant formulation investments to preempt EU REACH substance restrictions that threaten legacy polymer portfolios. For New Entrants and Emerging Players: Capture India's PLI scheme-driven localization wave by establishing polymer compounding or copper rod distribution in Gujarat and Tamil Nadu manufacturing zones. Target municipal procurement fragmentation in the United States where extended permitting cycles delay incumbent commitment timing and create white-space for agile suppliers. Lead with SAMR certification consulting as a differentiated service wrapper around commodity metal supply. For Investors and Strategic Acquirers: Roll-up economics work for regional electrical steel distributors with grain orientation expertise because transformer core manufacturing faces acute metallurgical engineering shortages that constrain organic expansion. Five-to-ten-year viability rests on exposure to fleet electrification mandates rather than residential charging cyclicality. Monitor EU Green Deal carbon border adjustment implementation pace as the inflection signal for low-emission copper premium pricing durability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Smelting | POSCO and integrated Asian metal producers anchor supply security through captive concentrate processing. |
| Halogen-Free Flame-Retardant Formulation Investment | BASF and DuPont preemptively satisfy ECHA REACH substance restrictions ahead of compliance deadlines. |
| SAMR Certification Consulting Services | Regional distributors differentiate commodity metal supply with Chinese regulatory navigation expertise. |
| Ceramic Substrate Qualification Partnerships | Silicon carbide module packagers extend thermal cycling validation protocols that filter second-source approval. |
| Electrical Steel Grain Orientation Capacity Expansion | German and Korean producers address acute metallurgical engineering shortages constraining transformer core output. |
Research Methodology
Direct dialogue with charging station OEM procurement directors, copper smelter sales executives, polymer compounder technical directors, and fleet operator infrastructure planners grounded qualitative findings in operational reality. Secondary validation drew from SAMR national standards filings, EU ECHA REACH substance evaluation registers, EPA lifecycle assessment protocol disclosures, and customs trade data for copper concentrate and refined cathode flows. Bottom-up material demand modeling triangulated against top-down infrastructure deployment projections from regulatory mandate analysis.
Segmented volume and value estimates emerged from modeling across material type, component category, end-user procurement authority, and distribution channel structure throughout the forecast period. CAGRs derived from regression analysis of historical copper and polymer price series against charging station deployment trajectories, with silicon carbide penetration rates and fleet electrification mandate compliance timelines as key industry-specific inputs.
Copper concentrate export disruptions, fluoropolymer regulatory bans before alternative maturation, and ceramic substrate qualification timeline extensions are the dominant revision risks that could compress or delay material demand projections. Material deviation in named triggers warrants pause and re-evaluation of supply security assumptions and pricing tier durability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
South America Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Public EV Charger Market
Electric Vehicle Charging
Electric Vehicle Charger Market
Electric Vehicle Charging
EV Charging Facilities Market
Electric Vehicle Charging
Second Life Electric Vehicle Battery Market
Electric Vehicle Charging
EV Charging Networks Market
Electric Vehicle Charging
Automotive EV Charging Adapters Market
Electric Vehicle Charging
EV Charging System Test and Certification Equipment Market
Electric Vehicle Charging
Asia-Pacific Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Electric Vehicle Coin Charging Station Market
Electric Vehicle Charging
North America Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Wireless Charging Market
Electric Vehicle Charging
Europe Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
India Battery Swapping for Electric Two-Wheelers Market
Electric Vehicle Charging
Asia-Pacific Brushless DC Motors Market
Electric Vehicle Charging
Electric Vehicle (EV) Public Charging Station Market