
 Advanced Batteries Market | 2026-2036
Advanced Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Batteries Market Analysis
Direct supply agreements between automakers and cell producers is reshaping how advanced batteries reach end users. CATL leverages long-term offtake contracts with European OEMs to secure volume commitments years ahead of production. LG Energy Solution anchors its competitive stance through in-house cathode material production in South Korea. Samsung SDI specializes in high-nickel prismatic cells for premium electric vehicle platforms, competing on energy density rather than cost.
Advanced batteries are electrochemical storage devices engineered to deliver superior energy density, cycle stability, and charge acceptance compared to conventional lead-acid or alkaline systems, typically achieving 250-300 Wh/kg in commercial lithium-ion formats and serving as the core power source for electrified transport and stationary grid applications. Lithium-ion chemistry dominates current manufacturing scale and cost curves, while solid-state designs command the fastest-growing R&D investment pool due to their promise of eliminating thermal runaway risks. Flow batteries occupy a narrower but defensible niche in grid management applications where eight-hour discharge durations outweigh energy density priorities. Energy storage systems applications are drawing margin attention as utility procurement shifts from pilot projects to multi-gigawatt-hour tenders.
The EPA tailpipe emission standards and the EU's Battery Regulation are mandating recycled content thresholds and carbon footprint declarations, forcing producers to reconfigure supply chains or face market exclusion. China's SAMR enforces GB standards on cell safety testing that effectively gate entry for foreign suppliers lacking domestic certification partnerships. Japan's METI coordinates national solid-state development consortia that concentrate intellectual property among domestic incumbents. Stakeholders must monitor which regulatory jurisdiction certifies their cells first, as that approval cascade often determines subsequent market access across multiple geographies.
Market Dynamics
Fleet electrification mandates are compressing cell qualification timelines while simultaneously forcing producers to decarbonize manufacturing footprints through dry electrode coating and renewable-powered gigafactories.
Growth Catalysts
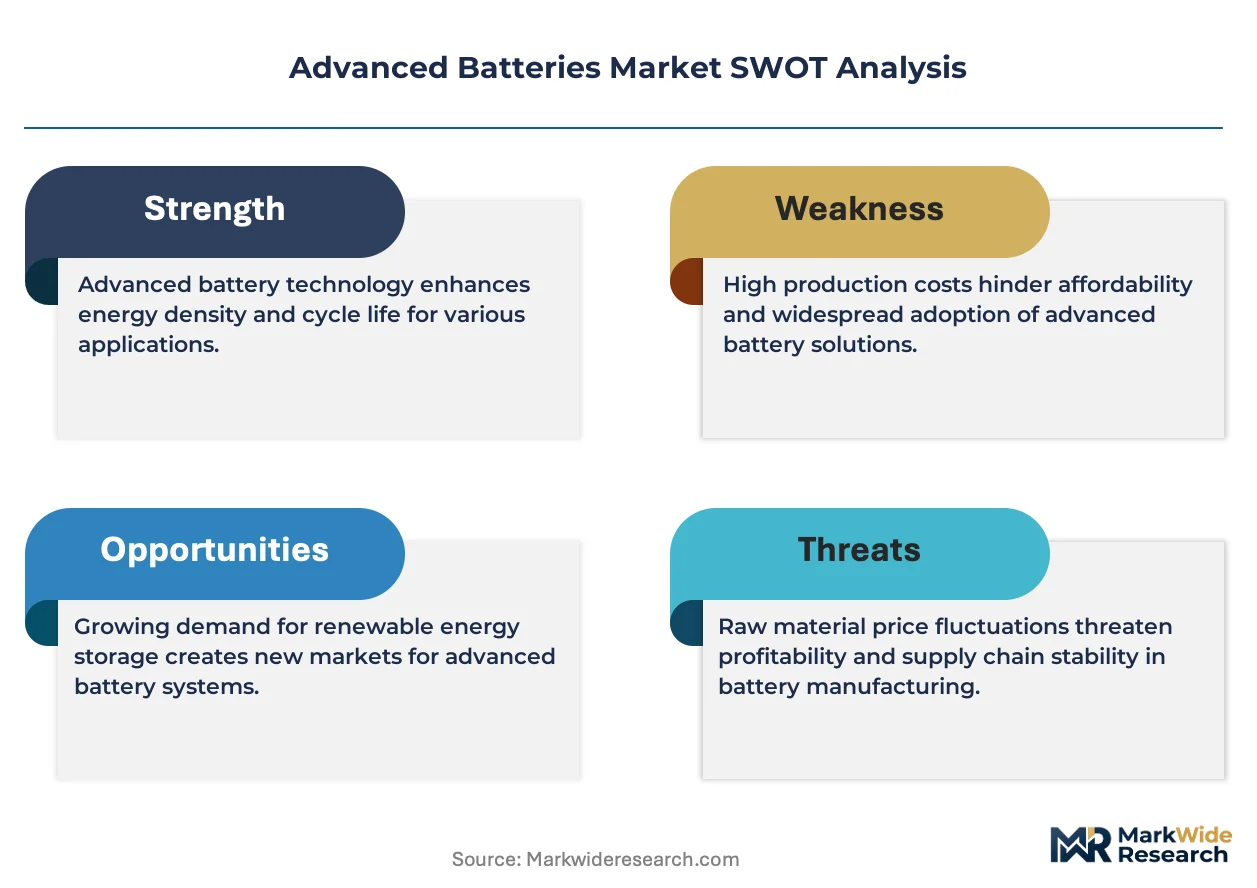
- EU Battery Regulation:Mandatory recycled content thresholds and carbon footprint declarations are accelerating closed-loop material recovery investments across European cell production corridors.
- High-nickel cathode chemistry:Energy density gains above 250 Wh/kg are enabling extended-range electric vehicle platforms without proportional pack weight penalties.
- Germany's automotive corridor:Volkswagen, BMW, and Mercedes-Benz are consolidating supplier relationships around local gigafactories, creating captive demand pools for qualified cell producers.
Market Restraints
- Lithium carbonate volatility:Raw material price swings compress margin visibility for producers locked into long-term offtake contracts with fixed pricing clauses.
- Chinese cathode supply concentration:Refining capacity geographic clustering creates single-point-of-failure exposure for non-domestic cell makers.
- Thermal runaway physics:Liquid electrolyte flammability limits pack energy density in commercial aviation and maritime applications where containment failure carries catastrophic liability.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for advanced chemistry cell manufacturing are attracting first-mover capacity commitments from international producers.
- Grid-scale flow batteries:Eight-hour discharge duration requirements in utility procurement tenders favor aqueous electrochemistry over lithium-ion for diurnal storage applications.
- Solid-state electrolyte convergence:Sulfide and oxide ceramic separator technologies promise simultaneous elimination of thermal runaway risk and dendrite penetration failure modes.
Industry Challenges
- Dry electrode coating equipment:Solvent-free manufacturing process engineering expertise remains scarce, constraining throughput scaling at new production facilities.
- Multi-jurisdiction certification sequencing:China's SAMR GB standards, EU Battery Regulation conformity assessments, and EPA tailpipe compliance create overlapping timeline dependencies that delay commercial launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Batteries Market |
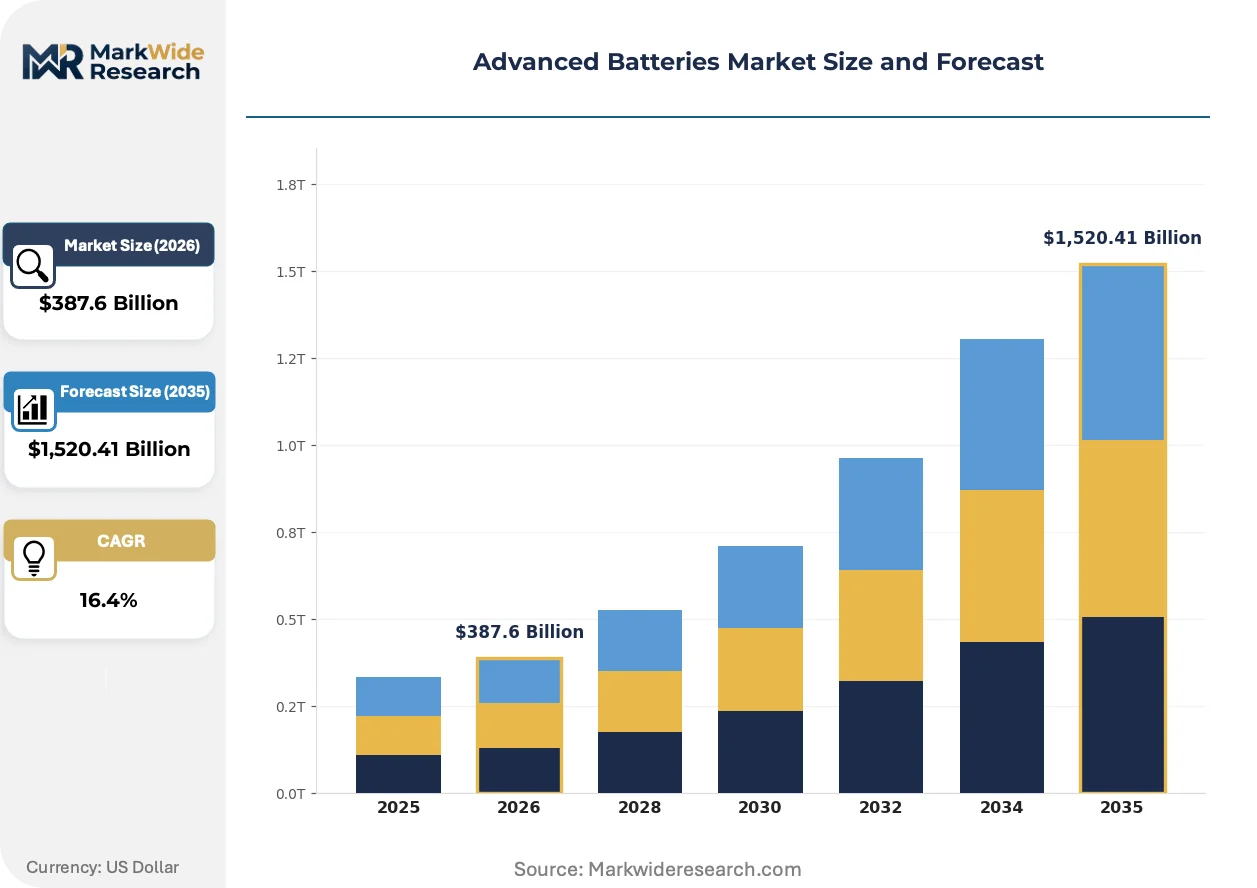
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,520.41 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Nickel-Metal Hydride, Solid-State, Flow Batteries Application: Electric Vehicles, Energy Storage Systems, Consumer Electronics, Grid Management End User: Automotive Industry, Renewable Energy Sector, Electronics Manufacturers, Telecommunication Companies Technology: Battery Management Systems, Energy Density Improvement, Fast Charging, Recyclable Materials |
| Companies Covered | Contemporary Amperex Technology Co. Limited (CATL), LG Energy Solution, Panasonic Holdings Corporation, Samsung SDI, BYD Company Limited, GS Yuasa Corporation, QuantumScape Battery Inc., Saft Groupe SA, SK On Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Batteries Market Emerging Trajectories
Electrode manufacturing processes and cell form factors are undergoing simultaneous transformation as producers balance energy density targets against manufacturing carbon intensity requirements.
Solid-state electrolyte technology is migrating from laboratory validation to pilot production lines. Automotive OEMs are qualifying sulfide-based ceramic separators for 2028 platform integration. This migration is compressing the competitive window for incumbent liquid electrolyte producers to recoup capital investments before obsolescence risk materializes.
China's dual carbon goals are forcing domestic cell makers to source renewable electricity for production facilities or face exclusion from government procurement tenders. The industrial consequence is accelerated solar-plus-storage co-location at gigafactory sites. European producers are responding by securing power purchase agreements with offshore wind developers to match carbon intensity claims.
Utility buyers are consolidating procurement into multi-gigawatt-hour tenders with integrated service obligations. Energy storage system integrators are displacing standalone cell vendors as the primary contracting party. This pattern is most visible in Germany's grid modernization programs and California's resource adequacy mandates.
Advanced Batteries Market Segmentation
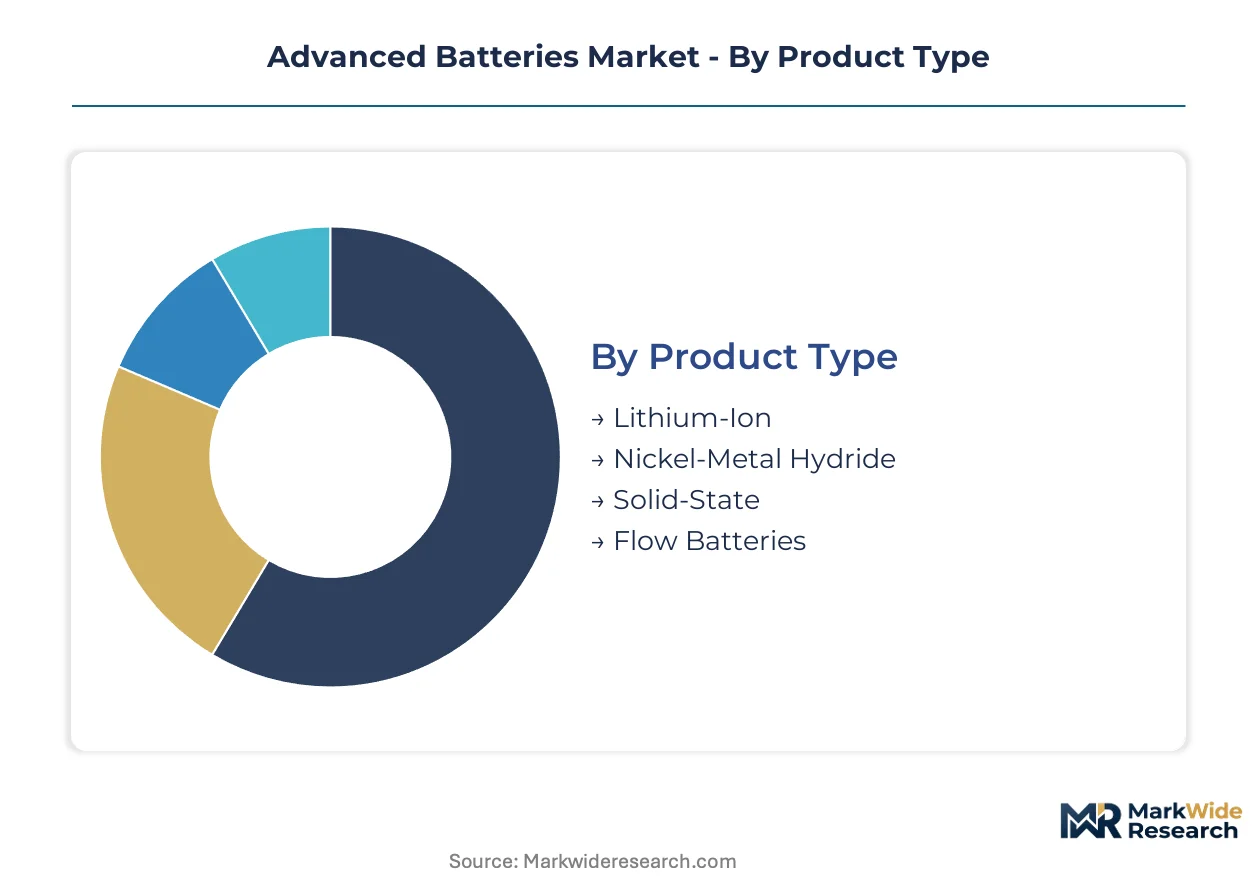
Segmentation reveals how qualification timelines, margin structures, and certification requirements diverge across electrochemistry families and end-use verticals. Understanding these fault lines helps suppliers prioritize capital allocation and anticipate which customer segments will consolidate procurement first.
Product Type:
Lithium-ion cells turn inventory fastest through automotive qualification pipelines, while flow batteries move slowest due to utility tender cycles stretching across multiple regulatory review periods.
- Lithium-Ion:Dominant commercial format achieving 250-300 Wh/kg through layered oxide cathodes and graphite-silicon anode blends. Volkswagen, BMW, and Mercedes-Benz in Germany's automotive corridor are consolidating supplier relationships around local gigafactories, compressing qualification timelines for qualified producers.
- Solid-State:Ceramic electrolyte designs eliminate thermal runaway risks while enabling lithium-metal anodes. Sulfide and oxide separator technologies are migrating from laboratory validation to pilot production lines as automotive OEMs target platform integration.
- Nickel-Metal Hydride:Mature chemistry retaining presence in hybrid electric vehicle applications where cost sensitivity outweighs energy density priorities.
- Flow Batteries:Aqueous electrochemistry utilizing vanadium or iron-chloride redox couples for stationary applications. Eight-hour discharge duration requirements in utility procurement tenders favor this format for diurnal grid storage.
Lithium-ion dominates installed base. Solid-state is where expansion concentrates.
Application:
Cost tier separation runs deepest here, with electric vehicles commanding premium pricing for qualified cells while grid management applications squeeze margins through multi-gigawatt-hour tender aggregation.
- Electric Vehicles:Battery electric and plug-in hybrid platforms requiring cells qualified to UN 38.3 and OEM-specific abuse testing protocols. Fleet electrification mandates from EPA tailpipe emission standards are compressing cell qualification timelines while forcing producers to decarbonize manufacturing footprints.
- Energy Storage Systems:Stationary installations ranging from commercial behind-the-meter to utility-scale front-of-meter deployments. Procurement is shifting from pilot projects to multi-gigawatt-hour tenders with integrated service obligations, displacing standalone cell vendors as primary contracting parties.
- Consumer Electronics:Cylindrical and pouch formats for smartphones, laptops, and power tools. Energy density requirements above 700 Wh/L drive cobalt-bearing cathode chemistries despite cost and ethical sourcing pressures.
- Grid Management:Frequency regulation, voltage support, and resource adequacy services. California's resource adequacy mandates and Germany's grid modernization programs are consolidating procurement into long-duration storage configurations.
Electric vehicles absorb the highest unit margins. Energy storage systems are climbing the fastest in absolute capacity additions.
End User:
Customer type determines contract structure, with automotive industry offtake agreements spanning five-to-ten year horizons while electronics manufacturers negotiate annual volume commitments.
- Automotive Industry:Passenger vehicle, commercial truck, and bus OEMs specifying cell performance through platform-level integration requirements. Direct supply agreements between automakers and cell producers are reshaping how advanced batteries reach end users, with CATL leveraging long-term offtake contracts to secure volume commitments years ahead of production.
- Renewable Energy Sector:Solar and wind developers pairing storage with generation assets to shift energy delivery profiles. China's dual carbon goals are forcing domestic cell makers to source renewable electricity for production facilities or face exclusion from government procurement tenders.
- Electronics Manufacturers:Device OEMs prioritizing volumetric energy density and cycle stability for portable applications.
- Telecommunication Companies:Tower operators and data center providers requiring backup power systems with fifteen-to-twenty year operational lifespans.
Automotive industry commands the steepest expansion trajectory in absolute cell demand. Renewable energy sector offers the longest contract durations.
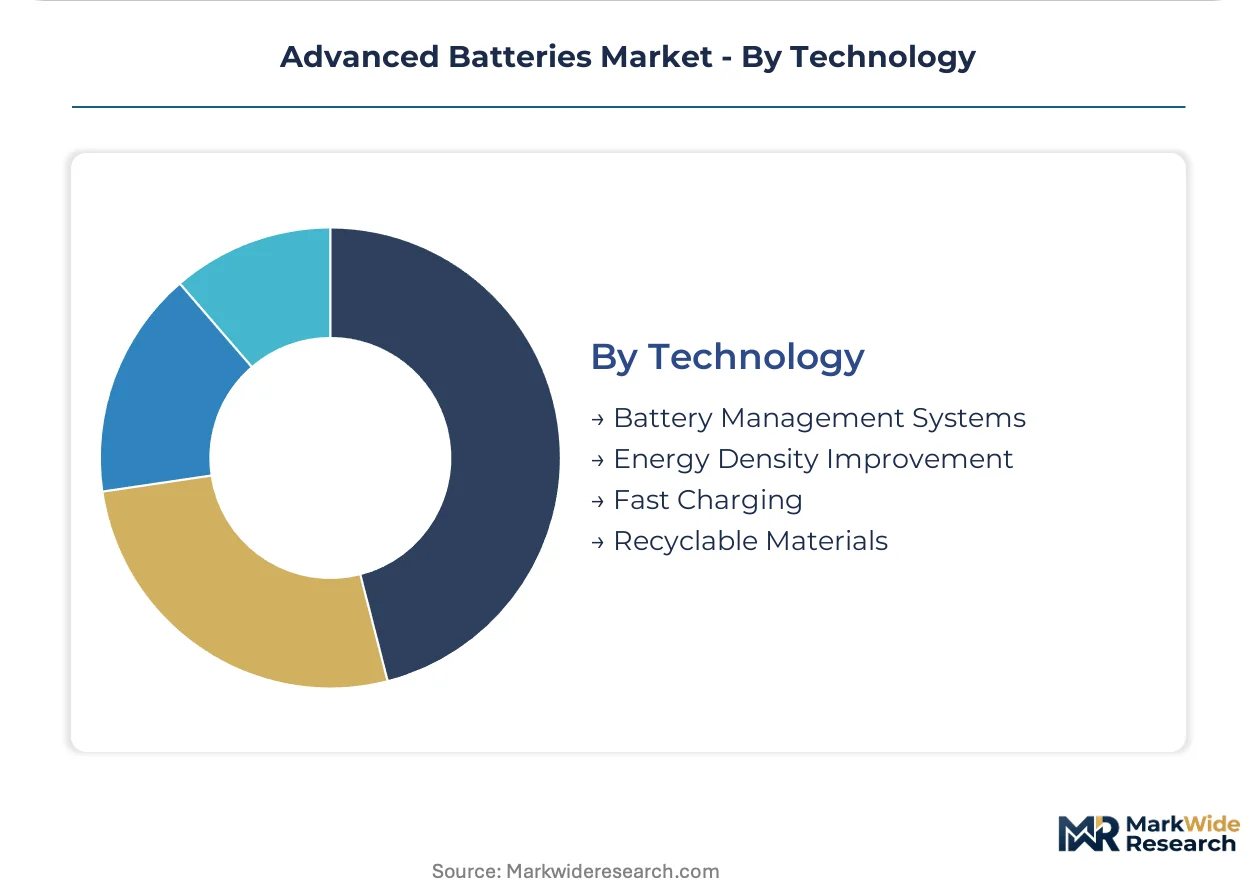
Technology:
Supply concentration varies sharply across this dimension, with battery management systems consolidating among specialized semiconductor vendors while recyclable materials expertise fragments across pyrometallurgical and hydrometallurgical process developers.
- Battery Management Systems:Electronic architectures monitoring cell voltage, temperature, and state-of-charge to prevent operational excursions. State estimation algorithms and active balancing circuits differentiate performance in premium electric vehicle platforms.
- Energy Density Improvement:High-nickel cathode chemistry and silicon anode loading protocols enabling energy density gains above 250 Wh/kg without proportional pack weight penalties. Samsung SDI specializes in high-nickel prismatic cells for premium electric vehicle platforms, competing on energy density rather than cost.
- Fast Charging:Electrode architectures and thermal management systems supporting 350 kW DC input rates. Graphite anode modifications and electrolyte additive packages reduce lithium plating risks during high-current operation.
- Recyclable Materials:Closed-loop recovery processes for lithium, cobalt, nickel, and copper from end-of-life cells. The EU Battery Regulation mandates recycled content thresholds and carbon footprint declarations, accelerating investments across European cell production corridors.
Battery management systems anchor current production. Energy density improvement is where R&D investment pools concentrate most heavily.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's automotive corridor while Chinese producers compete on volume scale. European cell makers capture premium margins through carbon-compliant production. Asian manufacturers dominate cost curves but face escalating compliance costs in export markets.
China
Domestic EV deployment and energy storage procurement drive cell demand across multiple provinces. SAMR enforces GB standards on cell safety testing that gate market entry for foreign suppliers lacking domestic certification partnerships. The Yangtze River Delta hosts concentrated gigafactory development where producers source renewable electricity to meet dual carbon goals or face exclusion from government tenders.
Germany
Volkswagen, BMW, and Mercedes-Benz consolidate supplier relationships around local production facilities. The EU Battery Regulation mandates recycled content thresholds and carbon footprint declarations that force supply chain reconfiguration. Bavaria and Lower Saxony anchor the automotive corridor where cell producers secure long-term offtake contracts spanning five-to-ten year horizons.
United States
EPA tailpipe emission standards compress cell qualification timelines for fleet electrification mandates. The Inflation Reduction Act domestic content provisions reshape procurement patterns for utility-scale storage and automotive applications. Michigan and Tennessee host expanding production corridors where producers align with offshore wind developers to match carbon intensity claims.
South Korea
Automotive OEM qualification programs and energy storage system integration contracts sustain cell demand. METI coordinates national solid-state development consortia that concentrate intellectual property among domestic incumbents. The Seoul Capital Area anchors cathode material production where LG Energy Solution maintains in-house supply capabilities.
India
Production-linked incentives for advanced chemistry cell manufacturing attract first-mover capacity commitments from international producers. BIS certification requirements and CEA grid codes create overlapping compliance timelines for storage system deployment. Gujarat and Tamil Nadu concentrate pilot manufacturing facilities where producers test localized supply chain configurations.
Advanced Batteries Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in cathode materials and separator technologies. The vendor base stratifies across three tiers: automotive-qualified cell producers with decade-long offtake relationships, utility-focused system integrators aggregating procurement, and materials specialists controlling refining and precursor supply. Dominant competitive moves include backward integration into cathode production and geographic expansion through joint venture structures in target demand corridors.
Within the automotive-qualified tier, Contemporary Amperex Technology Co. Limited, LG Energy Solution, and Samsung SDI occupy positions shaped by long-term OEM relationships. CATL exemplifies the scale-driven archetype through volume commitments secured years ahead of production. LG Energy Solution represents backward integration into precursor materials. Samsung SDI anchors the premium energy density segment. These three entities illustrate how qualification timelines and manufacturing carbon intensity requirements separate sustainable competitive position from commodity participation.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co. Limited (CATL) |
| LG Energy Solution |
| Panasonic Holdings Corporation |
| Samsung SDI |
| BYD Company Limited |
| GS Yuasa Corporation |
| QuantumScape Battery Inc. |
| Saft Groupe SA |
| SK On Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Gigafactory undercapacity in Germany's automotive corridor is compressing supplier lead times while simultaneously elevating pricing leverage for qualified cell producers serving Volkswagen, BMW, and Mercedes-Benz platform requirements. This utilization squeeze propagates through long-term offtake structures, forcing buyers to accept indexed raw material pass-through clauses that erode procurement certainty.
Pricing Analysis
The customization-premium spread between configured-to-order automotive cells and standard energy storage formats exceeds threefold, with contract structures diverging sharply across buyer archetypes. Automotive OEMs absorb premium pricing for UN 38.3-qualified and abuse-tested cells through five-to-ten year offtake agreements, while utility procurement through multi-gigawatt-hour tenders compresses margins for commodity-format suppliers. Price differentiation intensifies around carbon footprint certification tiers mandated by EU Battery Regulation conformity assessments. Cost compression runs deepest in lithium carbonate-exposed contract tiers where fixed-price clauses collide with spot market volatility. Electronics manufacturers exhibit highest price sensitivity due to annual volume renegotiation cycles, whereas automotive platform engineers prioritize qualification stability over unit cost minimization.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for cathode precursor sourcing, forcing non-domestic cell makers to reconfigure procurement geography. Raw material concentration clusters in China for lithium carbonate refining, South Korea for cathode active material production, and Indonesia for nickel laterite processing, creating interdependent vulnerability nodes. The supply chain draws from spodumene concentrates, nickel sulfate, and cobalt hydroxide as critical feedstocks where geographic concentration amplifies disruption propagation. Single-source vulnerability in Chinese GB-certified separator supply threatens qualification timelines for European market entry. Distribution runs through direct OEM supply agreements displacing traditional distributor networks, with system integrators capturing utility-scale procurement aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced batteries sit in early-cycle expansion as fleet electrification mandates from EPA tailpipe standards and EU regulatory frameworks compress adoption timelines across passenger and commercial vehicle segments.
For Market Incumbents: Harden qualification moats by accelerating SAMR GB standard certification partnerships in China while expanding in-house cathode precursor production to offset Chinese supply concentration risk. Samsung SDI's energy density specialization demonstrates how premium positioning defends margin structure against cost-driven entrants. Defensive capacity addition in Germany's automotive corridor secures captive demand from consolidating OEM supplier relationships. For New Entrants and Emerging Players: Build out India's PLI scheme manufacturing corridors where production-linked incentives reduce capital intensity for first-mover facilities. Grid-scale flow batteries for eight-hour discharge utility tenders represent the most penetrable white space, given lithium-ion thermal runaway limitations in long-duration configurations. Joint venture structures with established cathode material producers accelerate qualification timelines without full vertical integration burden. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across solid-state electrolyte pilot production lines as sulfide and oxide ceramic separator technologies approach automotive platform integration. Long-term viability over the next decade hinges on differentiation through manufacturing carbon intensity compliance rather than scale alone. Acquisition targets should demonstrate EU Battery Regulation recycled content threshold readiness and renewable-powered production footprints. The signal to watch is dry electrode coating equipment throughput scaling, where process engineering scarcity constrains viable capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | CATL leverages multi-year offtake contracts with European OEMs to secure volume commitments ahead of production ramp. |
| Backward Integration | LG Energy Solution's in-house cathode material production in South Korea reduces precursor cost volatility exposure. |
| Green Manufacturing Transition | China's dual carbon goals force renewable electricity sourcing at Yangtze River Delta gigafactory sites or government tender exclusion. |
| Technology Licensing | Solid-state electrolyte patent portfolios from METI-coordinated Japanese consortia concentrate IP among domestic incumbents. |
| Joint Venture | Germany's automotive corridor partnerships localize production for Volkswagen, BMW, and Mercedes-Benz platform qualification. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with automotive platform engineers, utility procurement officers, cathode material plant managers, and grid-scale EPC contractors. Secondary validation drew from EPA regulatory filings, EU Battery Regulation conformity assessment databases, SAMR GB standard documentation, and IEA energy storage deployment trackers. Bottom-up cell demand modeling triangulated against top-down gigafactory capacity announcements across the analysis window.
Calibration against operating reality informed the analytical framework spanning product type, application vertical, end-user category, and technology dimension across the projection horizon. CAGRs derived from segment-level demand elasticity modeling and supply-side capacity absorption rates. Key forecast inputs included fleet electrification mandate compliance timelines and utility-scale storage tender aggregation patterns.
Practitioners should monitor lithium carbonate spot price volatility, SAMR certification timeline shifts, and dry electrode coating equipment commissioning delays for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Middle-East and North Africa Rechargeable Battery Market
Batteries
Australia Battery Market
Batteries
Lithium Thionyl Chloride Battery Market
Batteries
Medical Batteries Market
Batteries
Japan Mobile Battery Market
Batteries
Bangladesh Lead Acid Battery Market
Batteries
Stationary Lead-Acid Battery Market
Batteries
India Electric Vehicle Battery Manufacturing Equipment Market
Batteries
Grid-Scale Battery Market
Batteries
Two Wheeler Lead Acid Batteries Market
Batteries
United States Household Battery Market
Batteries
Disposable Batteries Market
Batteries
Modular Battery Pack Platforms for Skateboard EVs Market
Batteries
Forklift Battery Market
Batteries
Asia Pacific Electric Vehicle Battery Electrolyte Market
Batteries
Custom Battery Pack Market