
 Airport Electric Vehicle Charging Station Market | 2026-2036
Airport Electric Vehicle Charging Station Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Electric Vehicle Charging Station Market Outlook
UL 2594 certification for electric vehicle supply equipment is collapsing the supplier pool to manufacturers with proven safety validation. ABB Ltd. leverages its power electronics heritage to dominate high-reliability DC fast charger installations at major aviation hubs. Siemens AG anchors its position through integrated grid-to-vehicle software stacks that manage airport load balancing. ChargePoint Inc. competes by extending its roaming network access to airport fleet operators seeking interoperability across multiple carrier contracts.
An airport electric vehicle charging station is a fixed or mobile power interface designed to deliver controlled electrical energy to battery-electric ground support equipment, shuttle buses, and passenger vehicles, typically operating at power ratings from 10 kW for overnight AC charging to 150 kW for rapid turnaround DC fast charging. DC Fast Chargers command the dominant share of capital deployment as airports prioritize minimizing aircraft turnaround times and ground vehicle downtime. AC Chargers retain significant installed base among long-dwell fleet parking where extended charging windows align with overnight ground equipment schedules. Wireless Chargers represent an emerging segment attracting trials for autonomous baggage tractors and automated guided vehicles where physical connector wear creates operational friction.
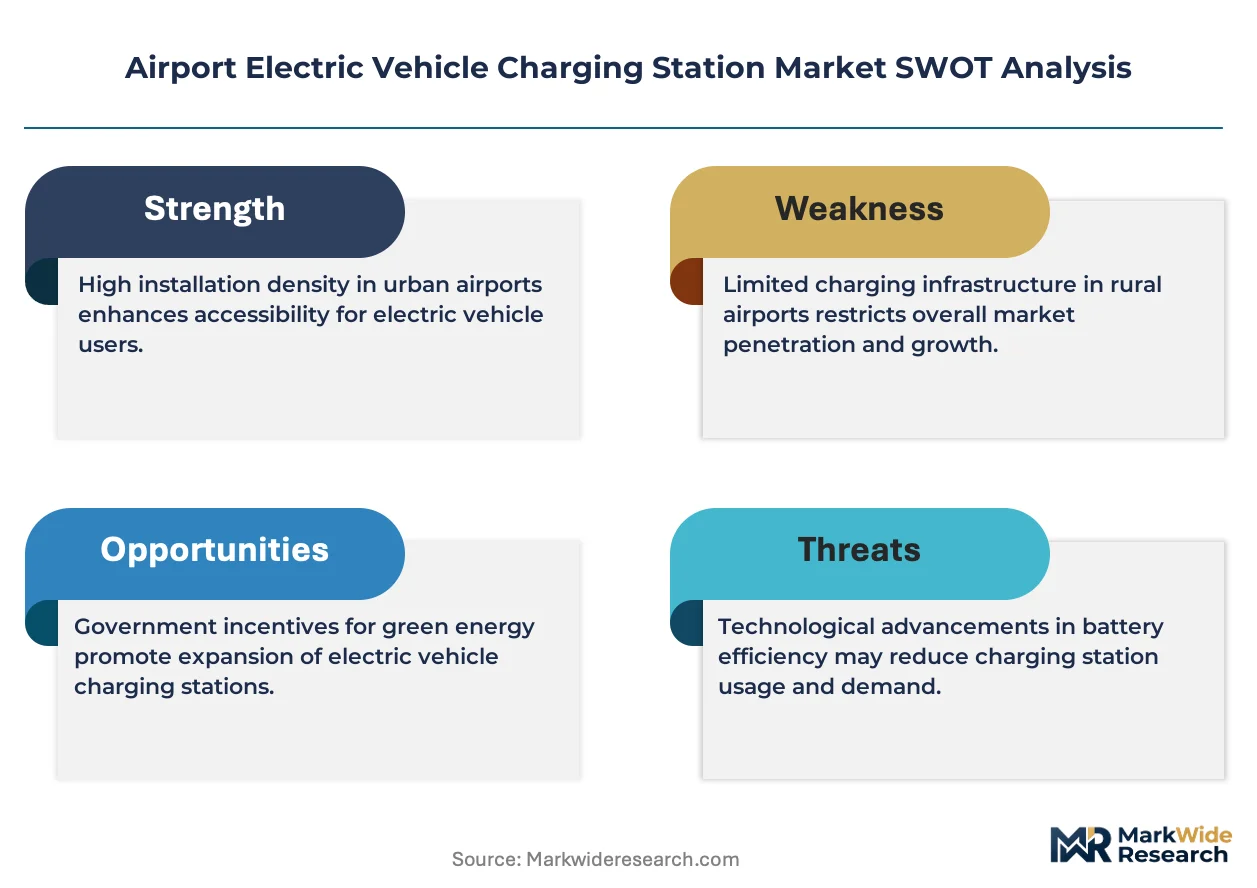
The US Federal Aviation Administration coordinates with the Department of Energy to channel IRA funding toward airport electrification projects, while the EU F-Gas Regulation indirectly shapes charger specification by accelerating the phase-out of fossil-fuel ground support equipment that EV infrastructure must replace. Airport authorities must weigh make-versus-buy decisions for charging infrastructure ownership against third-party operator models that transfer capital risk but sacrifice long-term energy revenue control.
Market Dynamics
The US Inflation Reduction Act and EU Green Deal are forcing airport authorities into accelerated electrification timelines, compressing procurement cycles from five-year planning horizons to eighteen-month deployment windows.
Growth Catalysts
- IRA Funding Channels:The US Department of Energy directs capital toward airport electrification projects, de-risking infrastructure investments for ground support fleet operators.
- EU F-Gas Regulation:This framework accelerates phase-out schedules for fossil-fuel ground equipment, mandating EV infrastructure as the replacement pathway.
- California Hub Concentration:Los Angeles International and San Francisco International anchor West Coast demand, retrofitting bus and shuttle fleets ahead of state zero-emission deadlines.
Market Restraints
- Copper and Silicon Carbide Volatility:Power electronics supply chains face input cost pressure from semiconductor substrate shortages and refined metal price swings.
- UL 2594 Certification Bottleneck:Safety validation requirements collapse the qualified supplier pool to manufacturers with proven testing records, extending lead times.
- Grid Interconnection Queues:Utility upgrade timelines for 150 kW DC fast charger installations stretch twelve to eighteen months at major aviation hubs.
Strategic Opportunities
- Autonomous Ground Equipment Convergence:Wireless inductive charging pairs with automated guided vehicles for baggage handling, eliminating connector wear points.
- Germany Hub Retrofit Wave:Frankfurt and Munich airports pursue integrated grid-to-vehicle software stacks, opening procurement for load-balancing technology providers.
- Third-Party Operator Models:Energy-as-a-service contracts transfer capital risk from airport authorities while retaining fleet interoperability across multiple carrier contracts.
Industry Challenges
- Power Electronics Talent Scarcity:Airport authorities and operators compete for electrical engineers with high-voltage DC and thermal management expertise.
- Legacy 400 Hz Aircraft Ground Power Integration:Charger installations must coexist with existing solid-state ground power units without destabilizing ramp electrical distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Electric Vehicle Charging Station Market |
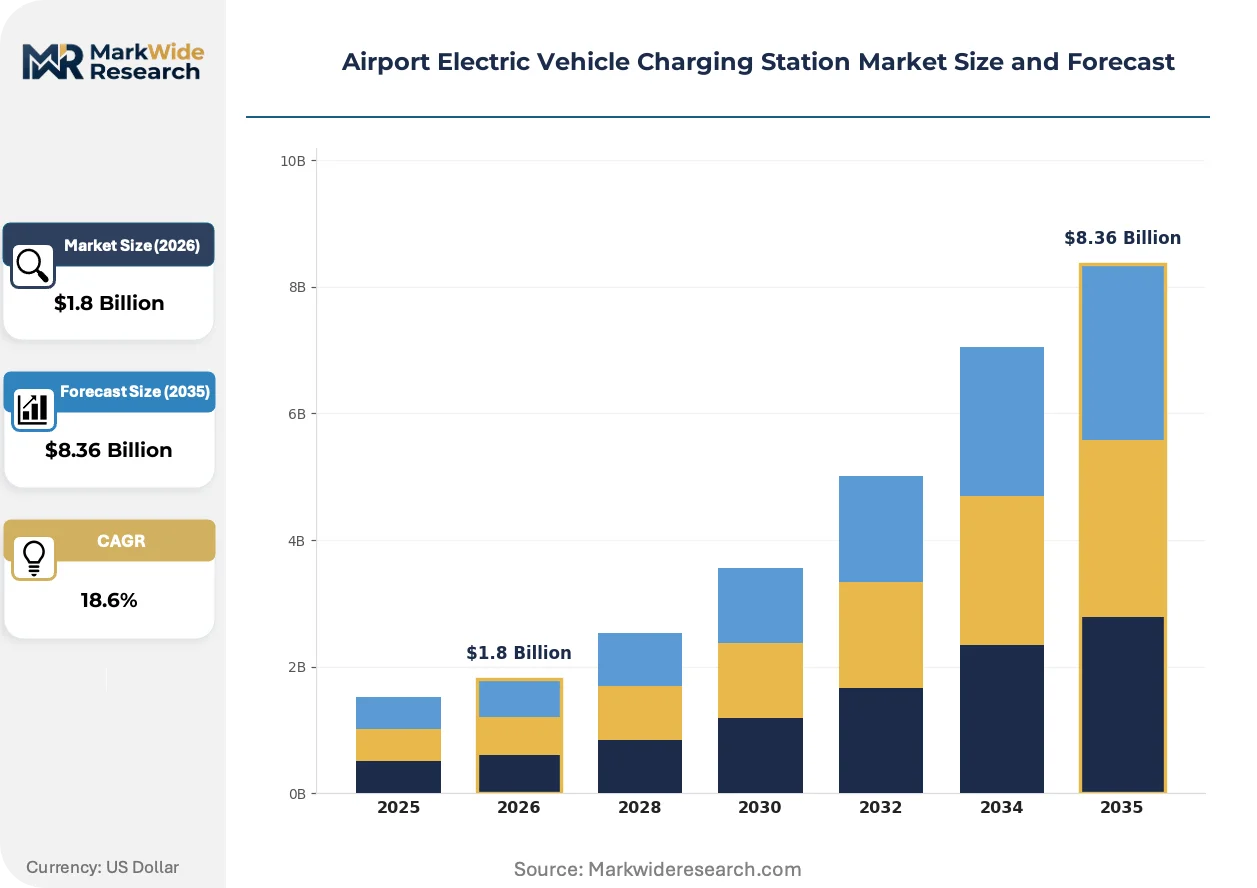
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Chargers, DC Fast Chargers, Solar Chargers, Wireless Chargers Installation Type: Ground-mounted, Wall-mounted, Garage-mounted, Portable Units Power Rating: 10 kW, 22 kW, 50 kW, 150 kW End User: Aerospace Companies, Airport Authorities, Fleet Operators, Private Users |
| Companies Covered | ABB Ltd., Blink Charging Co., Delta Electronics, Inc., Siemens AG, General Electric Company, ChargePoint Inc., Webasto Group, EVBox Group, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Electric Vehicle Charging Station Market Strategic Shifts
Power conversion topology and thermal management systems are compressing charger footprints while pushing power densities upward, enabling installation in space-constrained terminal zones and remote apron positions previously inaccessible to high-capacity equipment.
Silicon carbide MOSFET arrays replace traditional IGBT modules in DC fast charger power stages, cutting switching losses and enabling liquid-cooled architectures. Frankfurt Airport deploys these units in baggage handling areas where ambient temperature swings stress conventional cooling. The technology is miniaturizing charger enclosures to dimensions that fit within existing electrical vaults without structural expansion.
The EU F-Gas Regulation indirectly shapes charger procurement specifications by accelerating ground support equipment replacement schedules. Airport engineering departments must coordinate EV infrastructure rollout with diesel equipment retirement timelines. German and UK hub airports face the tightest compliance windows, driving bundled tenders that combine vehicle acquisition with charging hardware.
Fleet operators increasingly unbundle charging infrastructure ownership from energy supply contracts, preferring third-party operators who assume capital deployment risk. This procurement pattern displaces traditional direct-purchase models at US and European hub airports. California and the United Kingdom show the most advanced adoption, with Los Angeles International and Heathrow contracting dedicated charge-point operators under fifteen-year concession agreements.
Airport Electric Vehicle Charging Station Market Segmentation
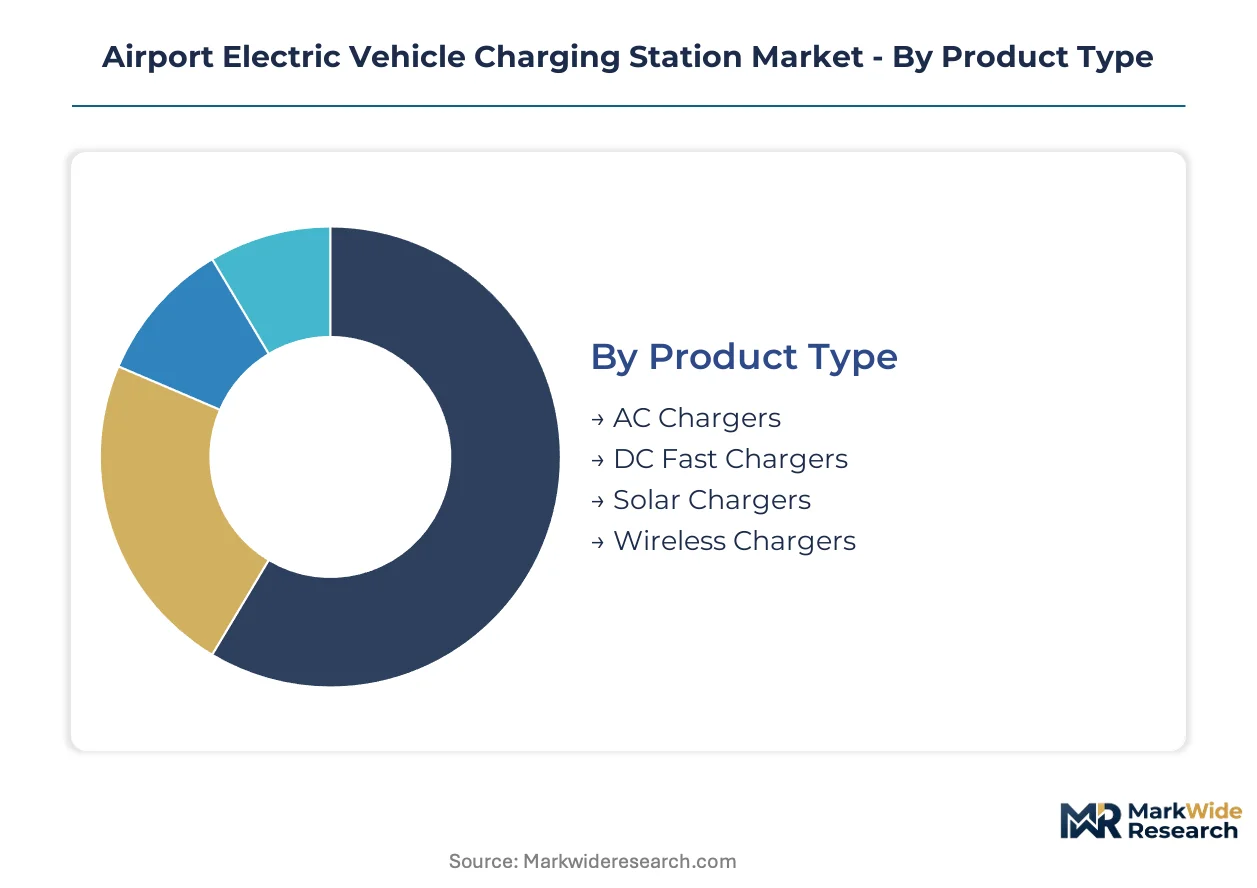
Airport EV charging infrastructure segments diverge sharply by deployment urgency and capital intensity. DC fast charging dominates retrofit budgets while wireless systems attract autonomous fleet trials. Procurement patterns cluster around hub airports in Germany, California, and the United Kingdom where regulatory deadlines compress decision timelines.
Product Type:
Domestic manufacturing concentration varies by charging technology, with DC fast charger assembly anchored in Germany and the United States while wireless charging R&D concentrates in Japan and South Korea.
- AC Chargers:These units deliver 10-22 kW through onboard vehicle rectifiers, suited for overnight ground support equipment parking at remote apron positions. Demand concentrates among fleet operators managing long-dwell baggage tractors and belt loaders at Frankfurt and Munich airports where extended charging windows align with overnight maintenance schedules.
- DC Fast Chargers:Direct current systems bypass onboard conversion to deliver 50-150 kW, slashing turnaround times for shuttle buses and passenger vehicles. California hub airports including Los Angeles International and San Francisco International prioritize these units to meet state zero-emission deadlines for ground transport fleets.
- Solar Chargers:Photovoltaic-integrated units serve remote apron positions lacking grid infrastructure at Dubai and Singapore Changi.
- Wireless Chargers:Inductive pads enable autonomous guided vehicle operation without connector wear.
DC Fast Chargers holds the largest share; momentum sits with Wireless Chargers.
Installation Type:
Cost tiers separate capital-heavy ground-mounted infrastructure from lightweight portable deployments suited to temporary gate expansions.
- Ground-mounted:Pedestal and bollard configurations anchor permanent charging hubs at terminal curbs and rental car centers. Heathrow and Schiphol deploy these for high-volume passenger vehicle turnover.
- Wall-mounted:Bracketed units maximize constrained electrical vault space in older terminals. San Francisco International retrofits these into 1970s-era infrastructure without structural expansion.
- Garage-mounted:Ceiling-suspended systems serve multi-level parking structures at Hartsfield-Jackson Atlanta.
- Portable Units:Mobile cart-based chargers support seasonal capacity surges and construction-phase fleet operations.
Ground-mounted infrastructure commands the largest share; Portable Units are climbing the fastest.
Power Rating:
Application requirements dictate power selection, with passenger shuttle operations demanding rapid turnaround while ground support equipment tolerates slower overnight cycles.
- 10 kW:Entry-level AC output serves small baggage tractors and utility vehicles with 8-12 hour dwell windows. Fleet operators at London Gatwick specify these for overnight equipment staging areas.
- 22 kW:Mid-tier AC capacity balances cost and speed for mixed ground support fleets. Amsterdam Schiphol standardizes on this rating for apron equipment renewal programs.
- 50 kW:Entry DC fast charging supports passenger shuttles with 30-45 minute turnaround requirements.
- 150 kW:High-output DC systems minimize downtime for high-frequency bus routes and emergency vehicle fleets.
22 kW holds the largest share; 150 kW shows the steepest expansion trajectory.
End User:
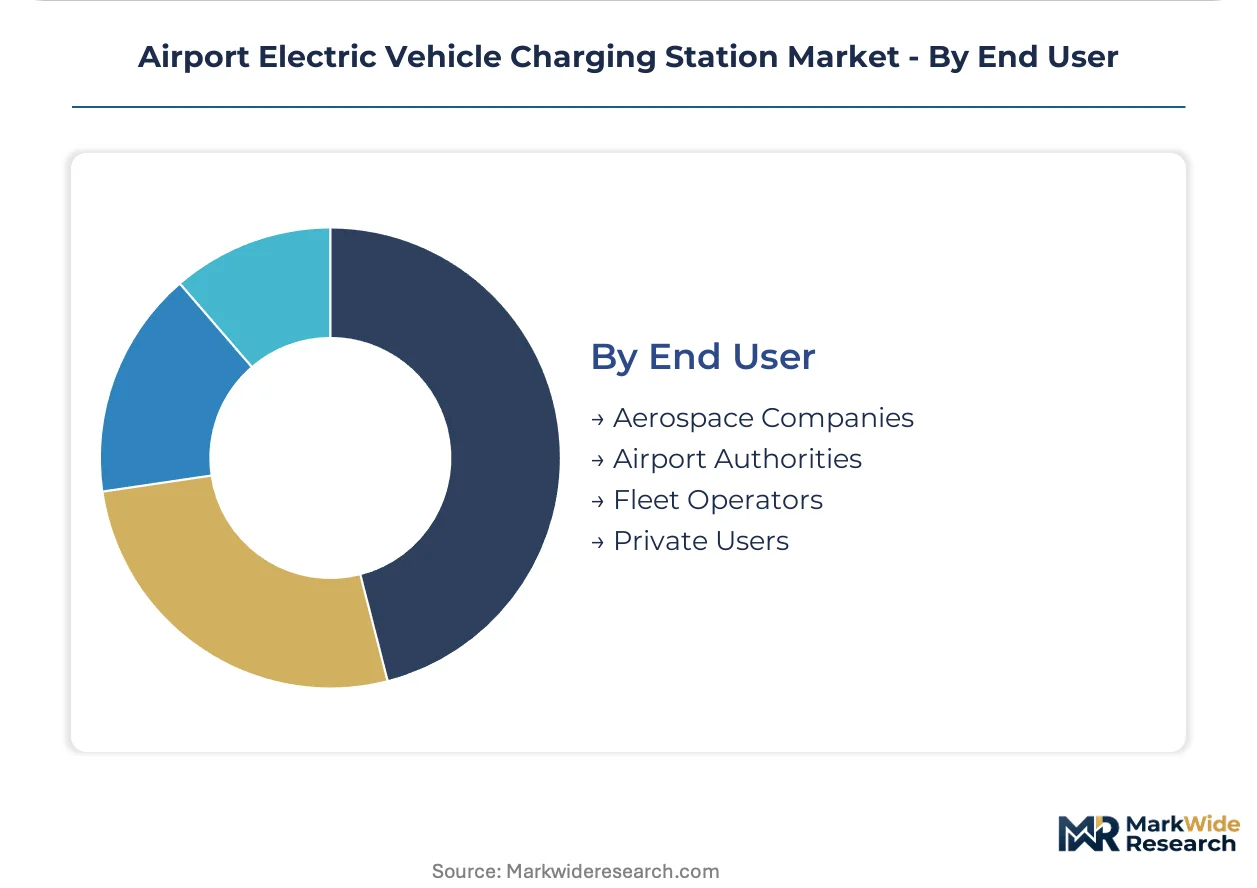
Customer type determines procurement authority and contract structure, with airport authorities retaining infrastructure ownership while fleet operators seek third-party operator arrangements.
- Aerospace Companies:Airlines and ground handlers contract dedicated charging for proprietary equipment. Lufthansa Technik operates captive infrastructure at Frankfurt and Munich under 15-year energy-as-a-service agreements.
- Airport Authorities:Municipal and regional airport operators specify system-wide electrification master plans. The Port Authority of New York and New Jersey channels IRA funding toward consolidated charging hubs serving multiple carriers.
- Fleet Operators:Third-party ground transport providers prioritize interoperability across carrier contracts.
- Private Users:Employee and passenger charging operates on commercial retail terms.
Airport Authorities hold the largest share; Fleet Operators are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The IRA and EU Green Deal compress procurement cycles to eighteen-month windows. Germany, California, and the United Kingdom anchor retrofit demand. Hub airports in these jurisdictions face the tightest compliance deadlines.
United States
Los Angeles International and San Francisco International anchor West Coast retrofit demand. The FAA channels IRA funding toward consolidated charging hubs serving multiple carriers. The Port Authority of New York and New Jersey deploys ground-mounted infrastructure at JFK and Newark under fifteen-year concession agreements.
Germany
Frankfurt and Munich airports pursue integrated grid-to-vehicle software stacks for load balancing. The EU F-Gas Regulation accelerates diesel equipment phase-out schedules. Lufthansa Technik operates captive infrastructure at both hubs under long-term energy-as-a-service contracts.
United Kingdom
Heathrow contracts dedicated charge-point operators for high-volume passenger vehicle turnover. The UK zero-emission vehicle mandate shapes ground transport fleet procurement timelines. London Gatwick specifies 10 kW AC units for overnight ground support equipment staging areas.
Netherlands
Amsterdam Schiphol standardizes on 22 kW AC capacity for apron equipment renewal programs. The EU Green Deal emissions targets compress infrastructure deployment schedules. Rotterdam The Hague Airport trials wireless inductive pads for autonomous baggage tractors.
Japan
Tokyo Haneda and Narita International retrofit electrical vaults with liquid-cooled silicon carbide architectures. METI efficiency standards drive power electronics procurement specifications. Osaka Kansai International tests ceiling-suspended garage-mounted systems in multi-level parking structures.
Airport Electric Vehicle Charging Station Market Competitive Environment
Listed leaders compete with private specialists across certification capability and power electronics heritage. The qualified supplier pool collapses to manufacturers with proven UL 2594 safety validation records. Three archetypes dominate: diversified industrial conglomerates with grid integration expertise, pure-play charging network operators, and automotive-tier suppliers extending into airport infrastructure. Competitive moves concentrate on strategic partnerships for load-balancing software and geographic expansion through concession agreements.
Within the industrial conglomerate tier, ABB Ltd. and Siemens AG exemplify players leveraging power electronics heritage for high-reliability installations. ChargePoint Inc. represents the network-operator archetype competing through roaming access and interoperability across carrier contracts. These three occupy distinct positioning vectors without overlapping core competencies.
| Leading Market Players |
|---|
| ABB Ltd. |
| Blink Charging Co. |
| Delta Electronics, Inc. |
| Siemens AG |
| General Electric Company |
| ChargePoint Inc. |
| Webasto Group |
| EVBox Group |
| Schneider Electric |
| Others |
Value Chain & Pricing Dynamics
Silicon carbide MOSFET arrays replacing conventional IGBT modules are simultaneously shifting power electronics sourcing toward Germany and Japan while compressing charger price premiums at the 150 kW tier. This substitution dynamic redistributes supplier leverage from legacy semiconductor foundries to SiC substrate specialists, tightening margins for mid-tier charger assemblers dependent on commoditized silicon components.
Pricing Analysis
Certification level (UL 2594-grade) creates the primary spread between qualified and unqualified supplier tiers, with safety-validated manufacturers commanding project-based contract premiums for hub airport deployments. Price differentiation separates CE-marked European units from economy-tier alternatives through thermal management specifications and grid-integration software bundling. Cost compression in the 22 kW AC segment is intensifying because Chinese manufacturers are flooding fleet operator tenders with unbundled hardware. Airport authorities prove least price-sensitive due to IRA funding de-risking capital outlays, while third-party fleet operators exhibit acute sensitivity to per-kWh energy margins.
Supply Chain Analysis
Strait of Malacca transit exposure concentrates refined copper sourcing from Chile and Indonesia, with semiconductor substrate fabrication anchored in Germany, Japan, and the United States. Power electronics assembly draws from silicon carbide wafers, liquid-cooled thermal management subsystems, and high-voltage connector assemblies. Single-source vulnerability sits with SiC substrate suppliers qualified for aviation-grade reliability standards. Distribution runs through EPC contractors specializing in airport electrical infrastructure, who bundle charger procurement with utility intercoordination services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as IRA and EU Green Deal funding compress procurement cycles from multi-year planning to sub-two-year deployment windows, accelerating penetration beyond historical infrastructure replacement rates.
For Market Incumbents: Secure UL 2594 certification moats through accelerated testing investments before the qualified supplier pool collapses further. Anchor backward integration into SiC substrate supply through offtake agreements with German and Japanese wafer foundries, neutralizing emerging Chinese power electronics entrants competing on unvalidated silicon platforms. For New Entrants and Emerging Players: Anchor in wireless inductive charging trials for autonomous ground equipment, the most penetrable white-space segment with minimal incumbent lock-in at Rotterdam The Hague and Dubai. Target California and United Kingdom hub airports where third-party operator models transfer capital risk and lower barriers to fleet interoperability contracts. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed charging network operators holding fifteen-year concession agreements at Los Angeles International and Heathrow. Long-term viability hinges on energy-as-a-service contract renewals and software stack retention. The signal to watch is bundled tender proliferation combining vehicle acquisition with charging hardware procurement, indicating vertical integration pressure from fleet operators.| Strategic Initiative | Industry Significance |
|---|---|
| Load-Balancing Software Acquisition | Siemens AG and ABB Ltd. compete for integrated grid-to-vehicle stacks managing airport ramp electrical distribution. |
| Silicon Carbide Supply Agreement | Charger manufacturers secure substrate offtake from German and Japanese wafer foundries to qualify for aviation-grade reliability. |
| Third-Party Operator Concession | Heathrow and Los Angeles International contract dedicated charge-point operators under fifteen-year energy-as-a-service structures. |
| Wireless Charging Pilot Deployment | Frankfurt and Dubai trial inductive pads for autonomous baggage tractors eliminating connector wear points. |
| IRA Funding Channel Access | The FAA coordinates Department of Energy capital toward consolidated charging hubs serving multiple carrier ground fleets. |
Study Parameters
The analysis maps DC fast charger, AC charger, and wireless inductive segments, each validated through airport engineering directors, fleet procurement managers, EPC contractors, and utility interconnection planners. Primary interviews with these stakeholders triangulate against FAA funding disclosure records, EU Green Deal implementation reports, SEC 10-K filings from listed charging infrastructure providers, and customs data tracking power electronics imports. Bottom-up installation counts at Frankfurt, Los Angeles International, Heathrow, and Singapore Changi cross-validate against top-down IRA and EU funding allocation estimates.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models product type, installation configuration, power rating tier, and end-user procurement authority dimensions. CAGRs derive from segment-level deployment trajectories calibrated to regulatory deadline compression and fleet replacement schedules. Forecast inputs incorporate utility interconnection queue timelines and SiC substrate supply expansion curves from German and Japanese foundry disclosures.
Decision-makers should treat outputs as directional under sustained IRA funding continuity and EU F-Gas Regulation enforcement; material deviation in either policy framework would warrant model refresh. Practitioners should keep alternative scenarios live as copper and silicon carbide price volatility, grid upgrade delays, and autonomous ground equipment adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
High-Thermal-Conductivity Gap-Fill Adhesives for EV Battery Cooling Plates Market
Electric Vehicle Charging
South Korea Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
EV Charging Cables Market
Electric Vehicle Charging
Integrated EV Chargers Market
Electric Vehicle Charging
EV Charge Controller Market
Electric Vehicle Charging
Electric Vehicle Charging Station Raw Materials Market
Electric Vehicle Charging
Western Europe Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
APAC Electric Vehicle Charging Station Market
Electric Vehicle Charging
Micro Mobility Charging Infrastructure Market
Electric Vehicle Charging
Home Charging Piles Market
Electric Vehicle Charging
Europe Electric Vehicle Charging Cable Market
Electric Vehicle Charging
Electric Vehicle Supply Equipment (EVSE) Market
Electric Vehicle Charging
Electric Vehicle Charging Facilities Market
Electric Vehicle Charging
Electric Vehicle Charging Adapter Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station and Pile Operation and Management Market
Electric Vehicle Charging
Two Wheel Electric Vehicle Charger Market