
 Battery Swapping Charging Infrastructure Market | 2026-2036
Battery Swapping Charging Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Swapping Charging Infrastructure Market Intelligence
Subscription-based battery rental is repositioning the core revenue model away from hardware sales toward recurring service contracts. NIO Inc. leverages its proprietary swap station network to anchor customer retention in China's premium electric vehicle segment. Gogoro Inc. sustains leadership in two-wheeler swapping through dense urban station deployment and energy management software. Ample Inc. differentiates via modular automated systems designed for rapid retrofit across multiple vehicle platforms.
Battery swapping charging infrastructure comprises automated exchange stations that replace depleted battery packs with charged units, typically completing the cycle in under five minutes for compatible electric vehicles. The primary purpose is eliminating range anxiety and charging downtime for commercial fleets and individual drivers operating in high-utilization environments. Fleet Solutions under the Deployment Model dimension dominate margin pools due to guaranteed volume commitments and predictable utilization rates. Automated Systems within the Technology segment represent the fastest-growing category as operators seek to reduce labor costs and standardize swap times across station networks.
China's MIIT enforces GB standards for battery dimensions and communication interfaces, effectively mandating interoperability as a condition of market access for station operators and vehicle manufacturers. India's BIS and CEA are developing certification requirements for swap station electrical safety and grid connection protocols, shaping how infrastructure providers design for metropolitan deployment. The EU's F-Gas Regulation and emerging battery passport frameworks under the EU Green Deal will influence thermal management specifications and lifecycle traceability requirements for equipment sold in European markets. Stakeholders must monitor how regulatory divergence across these jurisdictions affects platform standardization decisions and cross-border equipment sourcing strategies.
Market Dynamics
Interoperability mandates from China's MIIT are forcing station operators and vehicle manufacturers toward standardized battery pack dimensions and communication protocols, eliminating proprietary lock-in strategies that previously defined competitive positioning.
Growth Catalysts
- Commercial Fleet Electrification:Ride-hailing operators across Southeast Asian urban corridors are prioritizing swap-to-go models to minimize vehicle downtime during peak demand hours.
- GB Standards Enforcement:China's MIIT interoperability mandates are accelerating cross-manufacturer compatibility, expanding addressable station utilization rates beyond single-brand captive networks.
- Automated Robotics Deployment:Robotic battery handling systems are reducing swap cycle times below three minutes while cutting labor costs at high-throughput metropolitan stations.
Market Restraints
- Lithium Price Volatility:Battery pack asset costs fluctuate with lithium carbonate spot markets, compressing rental model margins for infrastructure operators holding inventory.
- Grid Connection Bottlenecks:India's CEA certification timelines for high-capacity electrical installations delay station commissioning in dense urban corridors where demand concentrates.
- Proprietary Form Factor Lock-in:Early-mover OEMs designed non-interchangeable battery geometries, creating stranded asset risk for stations before MIIT standardization took effect.
Strategic Opportunities
- India Metropolitan Expansion:Dense two- and three-wheeler commercial fleets in Bengaluru, Delhi, and Mumbai present underpenetrated addressable markets for subscription-based battery rental networks.
- EU Battery Passport Integration:Emerging traceability requirements under the EU Green Deal create first-mover advantage for operators deploying lifecycle monitoring software from station deployment.
- Renewable Coupling:Solar-plus-storage configurations at swap stations enable grid-independent operation during peak demand pricing periods, reducing opex exposure to utility rate structures.
Industry Challenges
- Certification Backlogs:India's BIS electrical safety testing queues extend station deployment timelines by four to eight months in high-priority metropolitan zones.
- Interoperability Testing Complexity:Multi-manufacturer battery compatibility validation requires expensive test mule fleets and protocol debugging resources that strain mid-capitalization operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Swapping Charging Infrastructure Market |
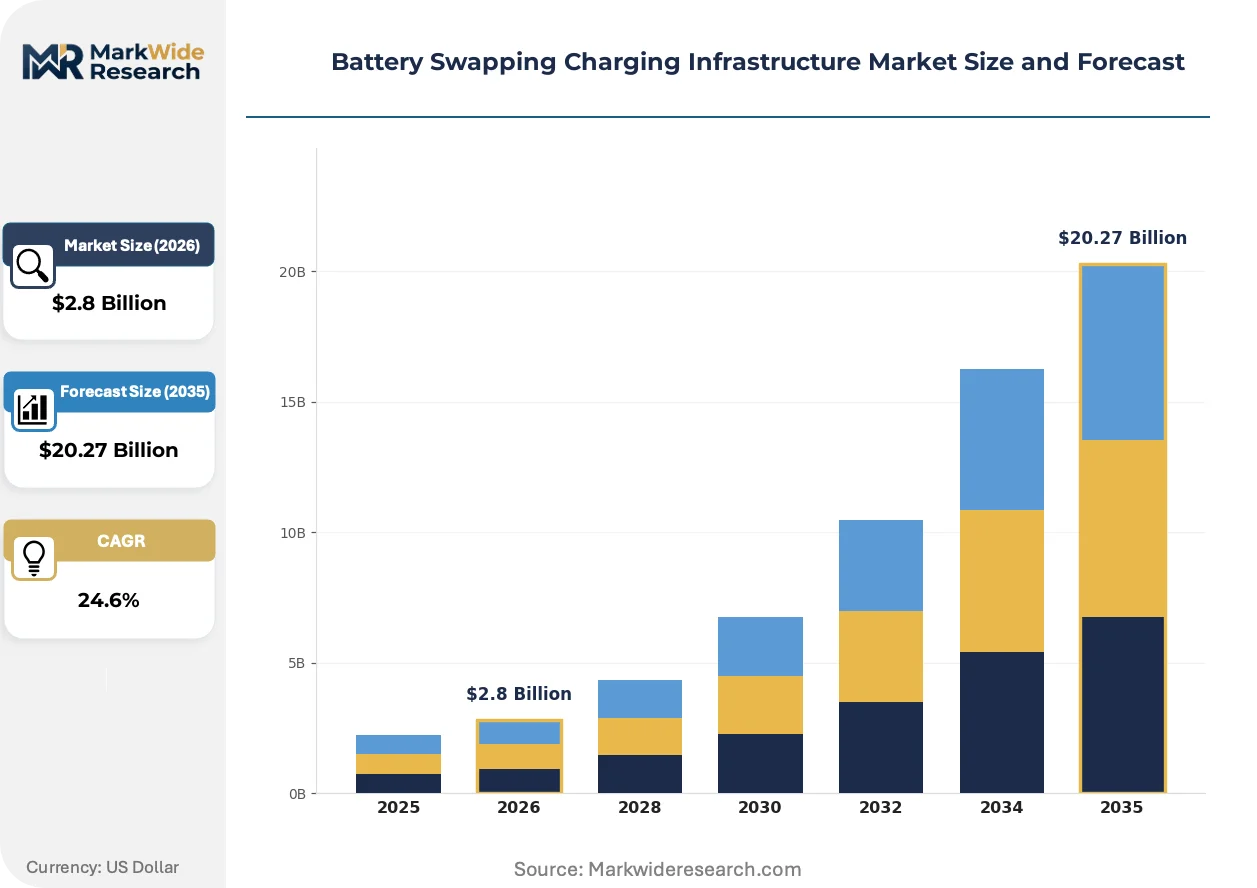
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $20.27 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Battery Rental, Subscription Model, Pay-Per-Use, Ownership Technology: Fast Charge, Automated Systems, Smart Grid Integration, Wireless Charging Deployment Model: Public Stations, Private Networks, Fleet Solutions, Urban Centers End User: Ride-Hailing Services, Delivery Fleets, Personal Vehicles, Commercial Transport |
| Companies Covered | NIO Inc., Gogoro Inc., SUN Mobility Pvt. Ltd., Ample Inc., Aulton New Energy Automotive Technology Co., Ltd., BYD Co. Ltd., Contemporary Amperex Technology Co., Limited, EVgo Inc., ChargePoint Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Swapping Charging Infrastructure Market Strategic Shifts & Innovations
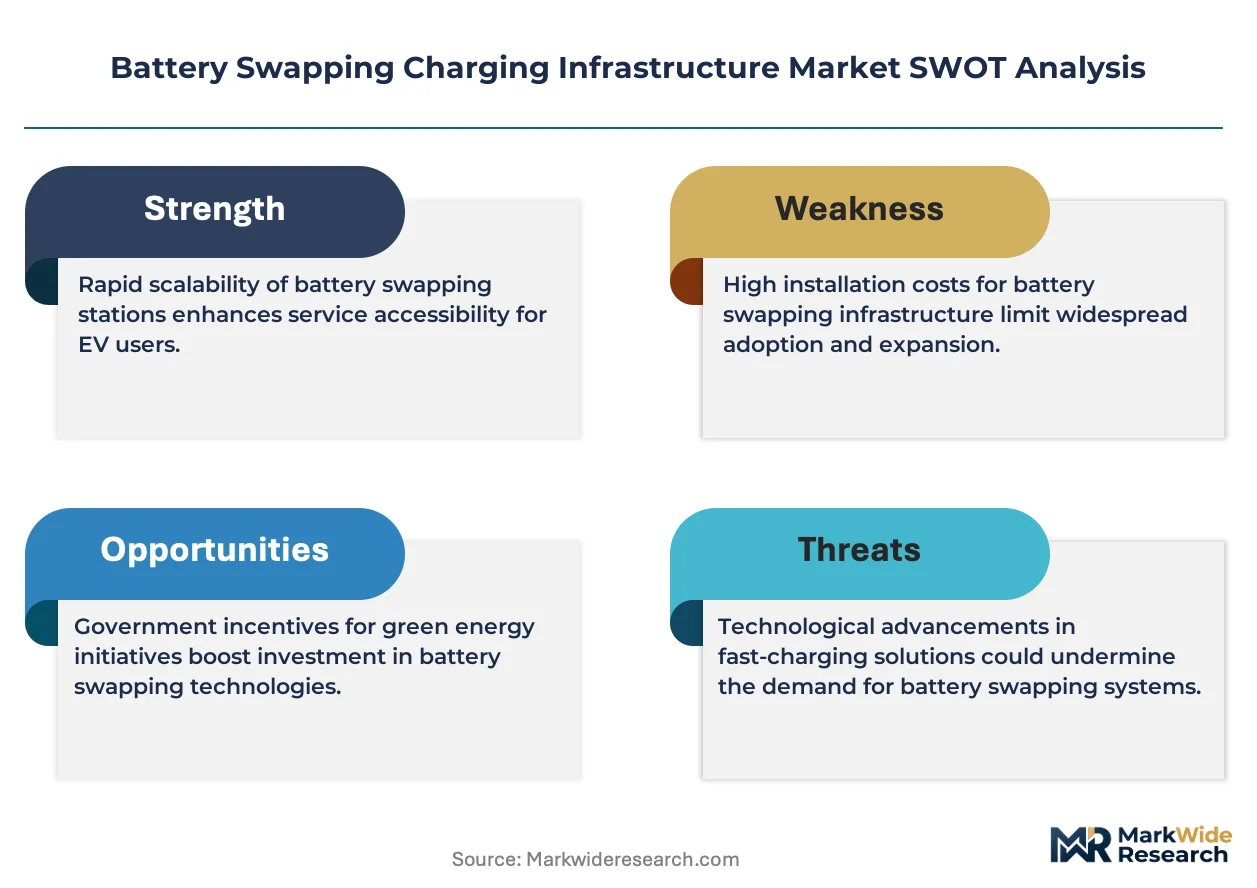
Three converging forces are restructuring how battery swapping infrastructure is deployed, financed, and integrated into urban energy systems. Technology maturation, regulatory harmonization, and service model evolution are compressing the timeline from pilot to scaled network operation.
Automated guided vehicle systems for battery transport within swap stations are integrating computer vision and force-feedback robotics to eliminate human handling errors during pack exchange cycles. Fleet operators with 24-hour utilization requirements are adopting these systems fastest, particularly in high-density Asian metropolitan markets. The technology is integrating predictive maintenance algorithms that flag cell degradation patterns before safety thresholds trigger pack retirement.
China's MIIT GB/T standards for battery dimensions and CAN bus communication protocols are mandating cross-brand compatibility as a market access condition, forcing previously proprietary networks toward open architecture. The regulation eliminates single-OEM station economics and compels infrastructure providers to design for multi-manufacturer utilization. European operators are monitoring this framework as a template for potential EU standardization under the Alternative Fuels Infrastructure Regulation.
Commercial fleet managers are unbundling battery ownership from vehicle acquisition, treating energy storage as a subscription service with per-kilometer or per-swap pricing. This procurement pattern shift displaces capital-intensive battery purchases from balance sheets and transfers residual value risk to infrastructure operators. The model is concentrating fastest among ride-hailing and last-mile delivery fleets in Indian and Southeast Asian urban corridors where vehicle utilization rates exceed 18 hours daily.
Battery Swapping Charging Infrastructure Market Segmentation
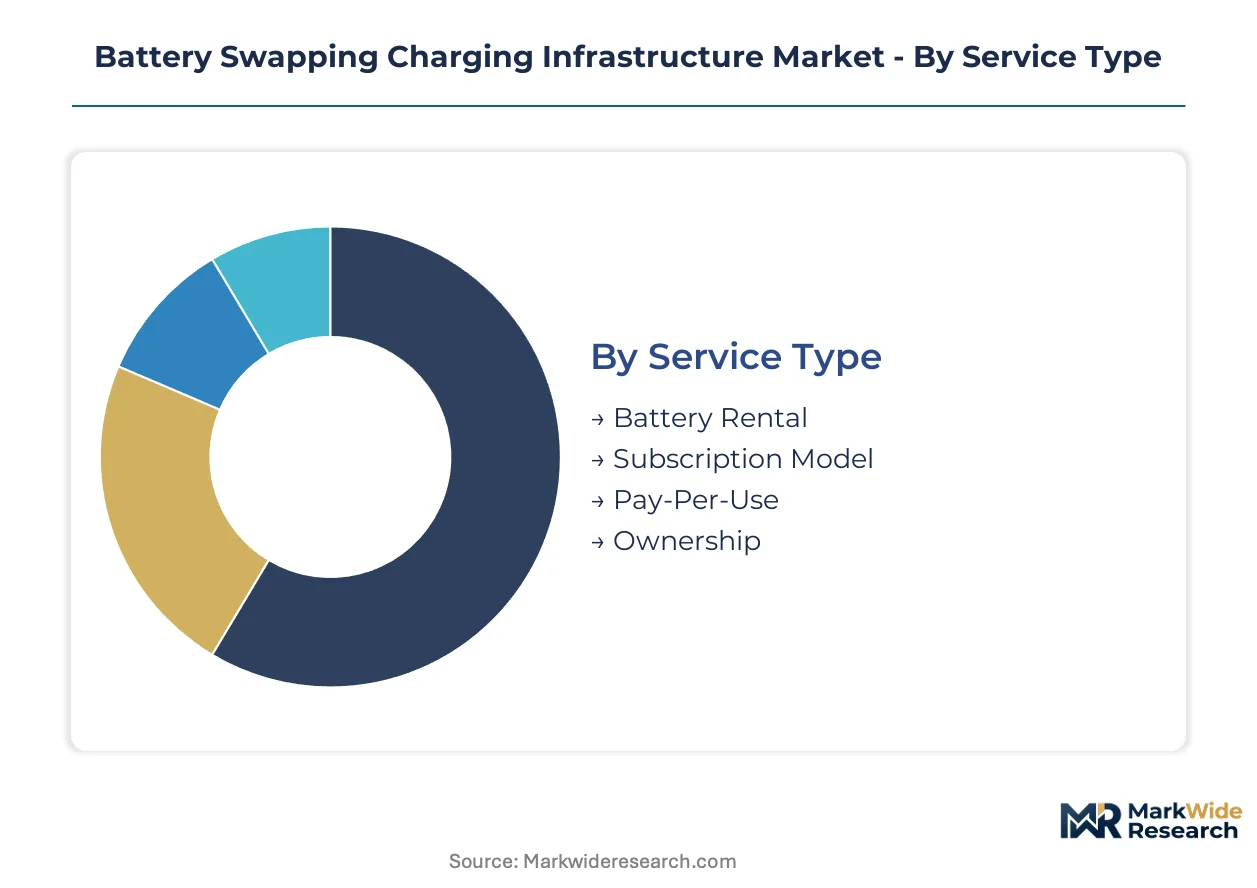
Segmentation in battery swapping infrastructure reveals how certification burdens, utilization economics, and customer procurement patterns concentrate margin pools across distinct operational models. Each dimension carries specific regulatory and capital requirements that determine competitive positioning.
Service Type:
BIS electrical safety certification applies to rental inventory management systems, while CEA grid-connection approvals dominate ownership-model installations requiring permanent electrical infrastructure.
- Battery Rental:Operators retain battery asset ownership and charge per-swap or per-kilometer fees. Demand concentrates among Indian two-wheeler delivery fleets in Bengaluru and Delhi, where SUN Mobility eliminates upfront capital barriers for gig-economy drivers.
- Subscription Model:Fixed monthly fees bundle unlimited swaps with predictive maintenance. NIO Inc. anchors customer retention in China's premium EV segment through locked-in service contracts that reduce churn.
- Pay-Per-Use:Transactional pricing suits irregular utilization patterns. Southeast Asian ride-hailing operators favor this flexibility during demand fluctuations.
- Ownership:Customers purchase battery packs outright, requiring minimal operator certification beyond station safety compliance. Personal vehicle segments in mature markets show residual preference here.
Leading the category by volume: Battery Rental. Growing fastest: Subscription Model.
Technology:
Cost tiering separates high-automation deployments from basic fast-charge retrofits, with capital intensity determining viable station economics across metropolitan density gradients.
- Automated Systems:Robotic battery handling with computer vision and force-feedback mechanics eliminates human error. Ample Inc. deploys these for sub-three-minute swaps across multi-manufacturer vehicle platforms, reducing labor costs at high-throughput urban stations.
- Fast Charge:Stationary rapid charging complements swap operations during battery inventory shortages. Deployment concentrates where grid capacity constraints limit full automation rollout.
- Smart Grid Integration:Bidirectional power flow enables peak-shaving and demand response revenue streams. MIIT GB/T communication protocols mandate this interoperability for grid-connected stations in China.
- Wireless Charging:Inductive pad systems for stationary fleet depots eliminate connector wear. Commercial transport segments in Japan test this for bus depot overnight charging.
Highest margin concentration: Automated Systems. Steepest expansion trajectory: Smart Grid Integration.
Deployment Model:
Customer type determines site selection, with fleet managers demanding guaranteed throughput commitments that public stations cannot match.
- Fleet Solutions:Captive networks serving single-operator vehicle pools with dedicated battery inventory. Gogoro Inc. builds these for 24-hour utilization ride-hailing fleets in Taipei and Southeast Asian corridors, securing predictable revenue through volume contracts.
- Urban Centers:Dense station placement targets high-frequency commercial users. Indian metropolitan expansion prioritizes Bengaluru, Delhi, and Mumbai for two- and three-wheeler density.
- Public Stations:Open-access infrastructure serving mixed vehicle bases. China's MIIT interoperability mandates now enable multi-manufacturer utilization, improving station economics.
- Private Networks:Corporate or institutional installations with restricted access. Last-mile delivery hubs in Southeast Asia deploy these for security and queue management.
Margin leadership: Fleet Solutions. Fastest network expansion: Urban Centers.
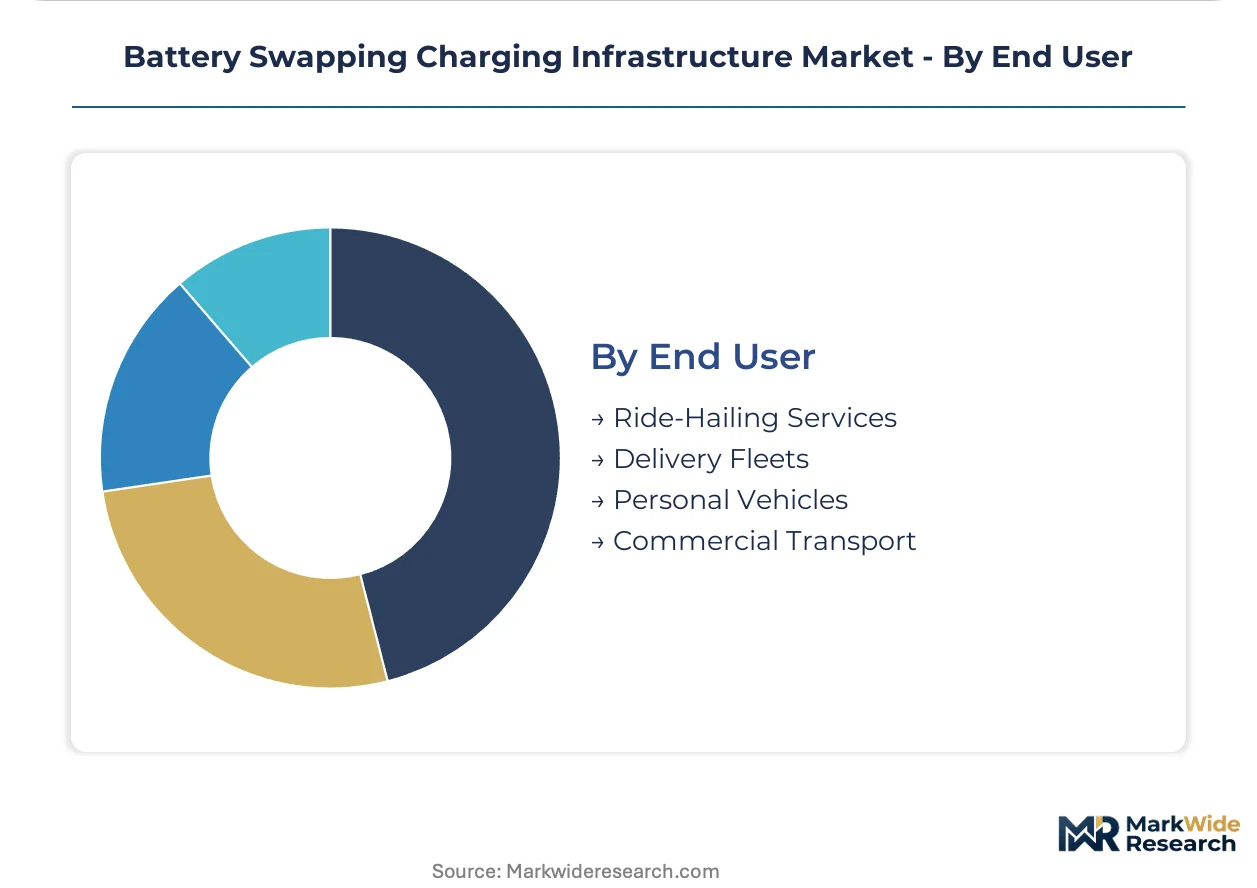
End User:
Application urgency separates commercial operators with downtime costs from personal drivers with flexible charging schedules.
- Ride-Hailing Services:Drivers face immediate revenue loss during charging downtime. Southeast Asian operators adopt swap-to-go models to maintain vehicle availability during peak demand windows.
- Delivery Fleets:Scheduled route completion depends on predictable energy access. Indian e-commerce logistics providers prioritize subscription models for three-wheeler cargo vehicles.
- Commercial Transport:Bus and light truck operators with fixed depot requirements. Japan's METI evaluates standardization for this segment.
- Personal Vehicles:Individual owners with lower utilization intensity and charging flexibility. China's NIO Inc. targets premium segment buyers with swap-station convenience as a differentiator.
Volume concentration: Ride-Hailing Services. Fastest adoption velocity: Delivery Fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bengaluru's dense two-wheeler commercial corridors anchor India's battery swapping expansion, with station networks multiplying across metropolitan India, China, and Southeast Asian urban centers where fleet electrification accelerates.
China
MIIT's GB/T interoperability mandates force cross-manufacturer battery compatibility, eliminating proprietary lock-in. GB standards for dimensions and CAN bus protocols now condition market access for station operators. Shanghai and Shenzhen station networks absorb multi-brand utilization, improving asset turns for infrastructure providers.
India
BIS electrical safety certification and CEA grid-connection approvals shape deployment timelines for metropolitan station networks. The PLI scheme for advanced chemistry cell manufacturing reduces battery import dependency. Delhi-NCR and Mumbai corridors see densest two- and three-wheeler fleet adoption of subscription rental models.
Indonesia
Jakarta's ride-hailing corridors drive swap-to-go model trials among two-wheeler taxi fleets seeking minimized downtime. The national energy ministry coordinates standardization discussions with regional counterparts. Surabaya and Bandung emerge as secondary deployment zones for commercial fleet infrastructure.
Thailand
Bangkok's motorcycle taxi density creates addressable demand for sub-three-minute battery exchange cycles. Board of Investment incentives target EV infrastructure manufacturing localization. Eastern Economic Corridor industrial zones attract station equipment assembly investments from regional suppliers.
Germany
The EU's F-Gas Regulation and emerging battery passport frameworks under the EU Green Deal influence thermal management specifications for European market entry. KBA type-approval processes evaluate automated swap station safety systems. Stuttgart and Munich automotive clusters test interoperability protocols for multi-manufacturer compatibility.
Battery Swapping Charging Infrastructure Market Key Industry Players
Capital-heavy station operators compete with asset-light technology licensors across divergent margin structures. The vendor base clusters around three strategic archetypes: integrated automotive OEMs with captive networks, pure-play infrastructure specialists deploying dense urban stations, and technology licensors supplying modular automation systems. Competitive positioning hardens through M&A consolidation of regional station portfolios and strategic partnerships between battery manufacturers and grid operators securing preferential electricity tariffs.
Within the pure-play infrastructure tier, NIO Inc. and Gogoro Inc. exemplify divergent geographic specialization strategies, with the former anchoring premium passenger vehicle networks and the latter concentrating on high-utilization two-wheeler commercial fleets. SUN Mobility Pvt. Ltd. occupies a position representing Indian market-focused subscription rental models for last-mile logistics. These three entities collectively illustrate how capital deployment intensity and local regulatory navigation determine viable station economics across divergent metropolitan densities.
| Leading Market Players |
|---|
| NIO Inc. |
| Gogoro Inc. |
| SUN Mobility Pvt. Ltd. |
| Ample Inc. |
| Aulton New Energy Automotive Technology Co., Ltd. |
| BYD Co. Ltd. |
| Contemporary Amperex Technology Co., Limited |
| EVgo Inc. |
| ChargePoint Holdings, Inc. |
| Others |
Cost & Logistics Intelligence
Sovereign-backed infrastructure operators in China and India anchor supply discipline through state-coordinated station rollouts, compressing margin variability for private capital while enforcing standardized pricing tiers across metropolitan deployment zones. Battery pack asset ownership concentrates pricing power with station operators who absorb lithium carbonate volatility into subscription contracts, transferring cost risk from fleet buyers.
Pricing Analysis
Outcome-based pricing anchored to vehicle uptime and swap throughput dominates fleet contracts, with per-kilometer fees displacing capital-intensive battery purchases. Price differentiation rests on automation tier and BIS/CEA certification status, with robotic stations commanding premiums over manual configurations. Pricing pressure stems from lithium carbonate spot market swings that compress rental model margins. Ride-hailing operators in Southeast Asia exhibit highest price sensitivity due to thin per-trip economics, while premium passenger segments in China show lowest sensitivity.
Supply Chain Analysis
Dual-sourcing requirements from Indian CEA and Chinese MIIT compel station operators to qualify multiple battery cell suppliers, fragmenting procurement concentration. Manufacturing concentrates in China, South Korea, and Japan for lithium-ion cells, with automated robotics sourced from Germany and Japan. Raw material dependencies center on lithium carbonate, nickel sulfate, and copper busbars. Single-source vulnerability in precision robotics creates bottleneck risk. Distribution runs through regional equipment integrators who bundle station hardware with local certification support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery swapping infrastructure occupies a technology-transition phase where automated robotics and standardized communication protocols displace manual swap systems and proprietary lock-in architectures. This shift restructures competitive positioning toward capital-intensive automation specialists.
For Market Incumbents: To counter interoperability mandates from China's MIIT, deepen backward integration into battery cell supply through joint ventures with CATL and BYD, while accelerating certification investments for BIS and CEA compliance in Indian metropolitan corridors. Channel control through exclusive fleet partnerships secures utilization rates against open-network competitors.
For New Entrants and Emerging Players: Begin with underpenetrated three-wheeler cargo segments in Bengaluru and Delhi, where subscription rental models eliminate upfront capital barriers for last-mile logistics providers. A licensing-based go-to-market angle supplying modular automation kits to regional station operators reduces capital intensity versus full vertical integration.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap automation specialists with proven MIIT GB/T compliance in China, where regulatory consolidation eliminates sub-scale competitors. Long-term viability hinges on software-defined energy management platforms that monetize grid services beyond swap fees. The signal to watch is CEA certification queue clearance rates in Indian metropolitan zones as inflection indicator for deployable capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | MIIT GB/T interoperability mandates force cross-manufacturer battery compatibility, eliminating proprietary lock-in. |
| Battery Supply Agreement | Long-term offtake contracts with CATL and BYD secure lithium cell availability amid spot price volatility. |
| Software-Defined Energy Management | Predictive maintenance algorithms flag cell degradation before safety thresholds trigger pack retirement. |
| Geographic Manufacturing Footprint | Eastern Economic Corridor localization in Thailand attracts regional station equipment assembly investments. |
| Charging Infrastructure Partnership | Solar-plus-storage configurations at swap stations enable grid-independent operation during peak pricing periods. |
Research Approach
Multi-period observation of station deployment rates, battery pack inventory turns, and certification queue lengths anchored the trend analysis, supplemented by interviews with infrastructure operators, fleet procurement managers, and grid planning officers. Secondary validation drew from MIIT GB standard filings, CEA grid-connection approval databases, BIS electrical safety certification records, and customs trade data for lithium cell imports. Bottom-up station economics modeling triangulated against top-down market sizing across deployment models.
Input-output matrices mapped battery pack throughput, station utilization rates, and subscription pricing tiers to derive volume and value trajectories across the projection horizon. Segmentation dimensions modeled include service type, automation technology tier, deployment model, and end-user application. CAGRs were synthesized from deployment pipeline analysis and fleet electrification commitments. Industry-specific inputs incorporated lithium carbonate price elasticity and CEA certification timeline distributions.
Underlying measurement precision varies by segment; automated systems and fleet solutions carry tighter precision than public stations and pay-per-use models due to disclosed contract volumes. Forecasts reflect assumptions on regulatory harmonization pace and battery cost curves. Deviation in CEA certification processing speeds or lithium supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle (EV) Public Charging Station Market
Electric Vehicle Charging
Micro Mobility Charging Infrastructure Market
Electric Vehicle Charging
China Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Solar Carport Charging Station Market
Electric Vehicle Charging
Electric Vehicle Charging Management Software Market
Electric Vehicle Charging
Stationary Electric Vehicle Charging Gun Market
Electric Vehicle Charging
EV Charge Management Software Market
Electric Vehicle Charging
Electric Vehicle Charger and Charging Station Market
Electric Vehicle Charging
Portable Charging Units Market
Electric Vehicle Charging
Solar Charge Controller Market
Electric Vehicle Charging
Bidirectional Charging Units Market
Electric Vehicle Charging
APAC Electric Vehicle Charging Station Market
Electric Vehicle Charging
Electric Vehicle Charging Adapter Market
Electric Vehicle Charging
Germany Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
AC Electric Vehicle Charging Station Market
Electric Vehicle Charging
EV Charging Software Market