
 Electric Vehicle Charging Products Market | 2026-2036
Electric Vehicle Charging Products Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Charging Products Market Insights
Commercial fleet electrification is consolidating as the dominant demand vector for charging hardware. ABB leverages its grid-integration expertise to anchor utility-scale depot installations across European logistics hubs. Tesla sustains vertical control over its Supercharger network while licensing connector standards to third-party operators. Siemens competes on industrial power electronics, extending its factory automation footprint into heavy-duty fleet charging systems.
Electric vehicle charging products comprise power conversion hardware, cable assemblies, and network management systems engineered to deliver controlled electrical energy from grid or distributed sources to onboard battery packs, typically operating across voltage classes from 120V residential AC to 1000V+ DC fast-charging architectures. Fast chargers and DC charging technology command the deepest margin pools as fleet operators prioritize throughput density over unit economics, while smart charging systems are capturing disproportionate R&D allocation as grid operators impose dynamic load-management requirements. Home chargers retain volume leadership but face commoditization pressure from utility-sponsored deployment programs.
The US Inflation Reduction Act and the EU Green Deal's transport decarbonization mandates are reshaping procurement standards, with the EPA and EMA frameworks now requiring interoperability certification and cybersecurity hardening for network-connected units. China's MIIT enforces GB/T connector and communication protocols that condition market access for foreign suppliers. Stakeholders must monitor evolving grid codes and subsidy eligibility rules as sovereign industrial policy becomes inseparable from product design decisions.
Market Dynamics
Fleet electrification timelines are compressing as commercial operators face Scope 3 emissions disclosure mandates and total cost of ownership parity with diesel vehicles. This demand surge is straining transformer capacity and forcing utilities to accelerate grid-edge infrastructure investments ahead of hardware deployment.
Growth Catalysts
- US Inflation Reduction Act Section 30C:Tax credits covering 30% of charging equipment costs are accelerating hardware procurement across logistics depots and multi-unit dwellings.
- EU Green Deal transport decarbonization mandates:Binding CO2 standards for heavy-duty vehicles are compelling fleet operators to electrify terminal operations and secure charging infrastructure.
- China's coastal manufacturing clusters:Concentrated OEM production in Guangdong and Jiangsu provinces is generating captive demand for high-power charging systems at assembly plants and test facilities.
Market Restraints
- Copper and silicon carbide supply concentration:Power semiconductor fabrication capacity bottlenecks in Taiwan and South Korea are extending lead times for DC fast-charger power modules.
- Utility interconnection queues:Distribution network upgrade approvals in Germany and California are delaying commercial depot energization by 18-24 months beyond equipment delivery.
- GB/T protocol fragmentation:China's MIIT-mandated connector standards create certification barriers for foreign suppliers seeking access to domestic procurement tenders.
Strategic Opportunities
- India's PLI scheme for automotive:Production-linked incentives for EV manufacturing are stimulating demand for charging infrastructure in Maharashtra and Tamil Nadu industrial corridors.
- Vehicle-to-grid integration:Bidirectional charging capability convergence with home energy management systems opens residential stationary storage revenue streams for hardware suppliers.
- Third-party network roaming:Interoperability platform providers are creating new channel access for smaller hardware manufacturers excluded from closed OEM ecosystems.
Industry Challenges
- Power electronics engineering talent scarcity:Specialized expertise in high-frequency magnetics and thermal management for 350kW+ systems concentrates at a handful of research institutions and incumbent suppliers.
- Cybersecurity certification complexity:EPA and EMA frameworks now require ISO/SAE 21434 compliance for network-connected units, extending product validation cycles by 6-9 months.
- Legacy fleet integration:Retrofitting charging infrastructure into existing depots with constrained electrical service capacity requires costly civil and utility coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Charging Products Market |
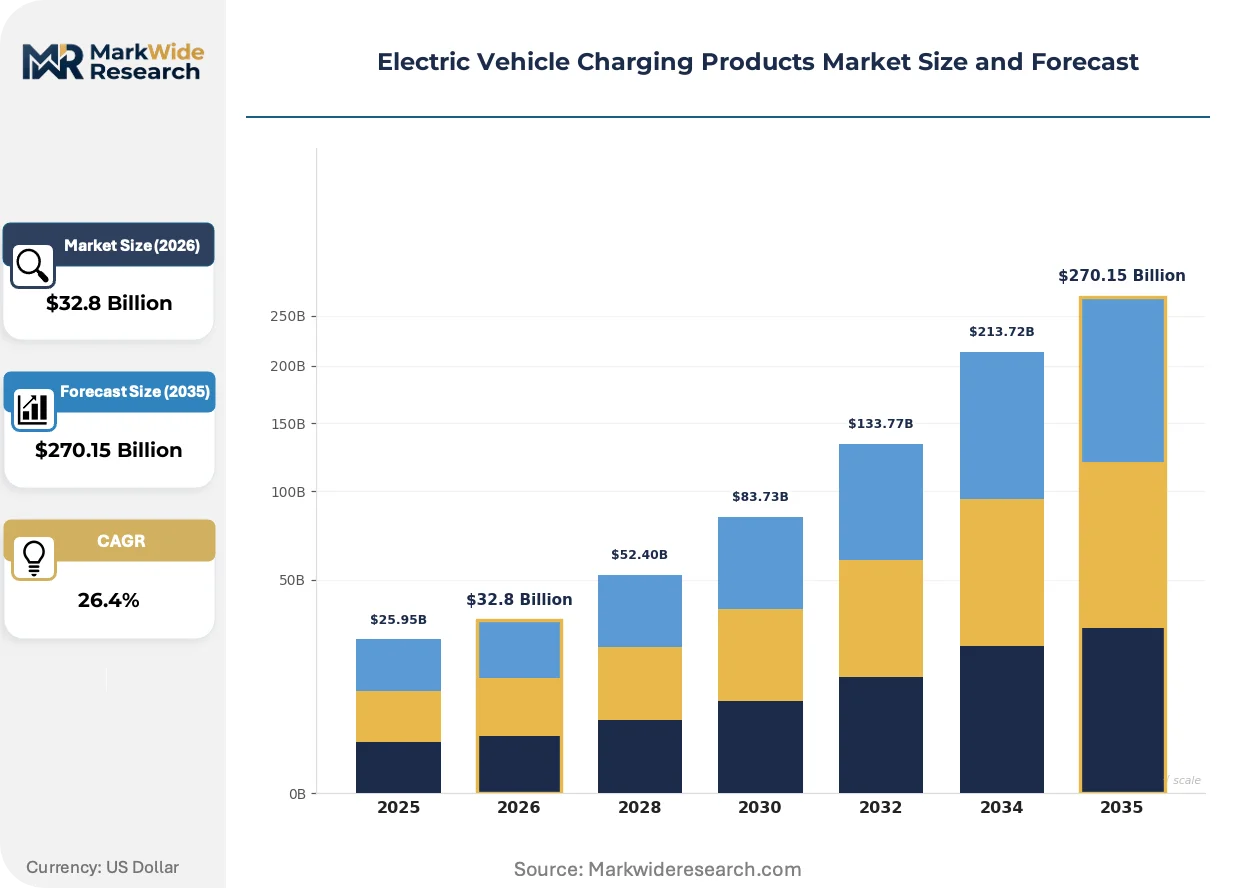
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $270.15 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Home Chargers, Public Chargers, Fast Chargers, Wireless Chargers Technology: AC Charging, DC Charging, Smart Charging, Solar Charging End User: Residential Users, Commercial Fleets, Government, Charging Networks Installation: On-Street, Off-Street, Fast Charging Stations, Integrated Solutions |
| Companies Covered | ChargePoint, ABB, Tesla, Siemens, EVBox, Wallbox, Eaton, Blink Charging, Kempower, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Charging Products Market Trends and Innovations
Hardware architectures are fragmenting across power classes as application-specific requirements diverge between residential, commercial fleet, and public corridor deployments. This specialization is driving divergent R&D investment patterns and supplier capability development.
Dynamic load management software is decentralizing charging control from centralized depot servers to edge-computing nodes embedded in individual dispensers. Fleet operators with 50+ vehicle deployments are adopting these systems to minimize demand charges and avoid utility peak pricing windows. The shift is compressing hardware margins for pure power-conversion suppliers while expanding recurring revenue pools for integrated software-hardware vendors.
EU F-Gas Regulation phase-down schedules are accelerating adoption of natural refrigerant thermal management systems in liquid-cooled charging cables and power cabinets. Equipment manufacturers must redesign cooling architectures to accommodate CO2 or propane circuits, affecting supplier qualification and component sourcing strategies. German KBA type-approval processes now prioritize refrigerant containment testing, extending certification timelines for imported systems.
Hardware-as-a-service contracting is displacing capital purchase models among mid-sized fleet operators seeking to preserve balance sheet capacity. Leasing providers bundle installation, maintenance, and energy optimization into per-mile or per-kWh tariffs. This model concentrates most visibly in California and the Netherlands where electricity market structures enable transparent pass-through of time-of-use savings to end customers.
Electric Vehicle Charging Products Market Segmentation
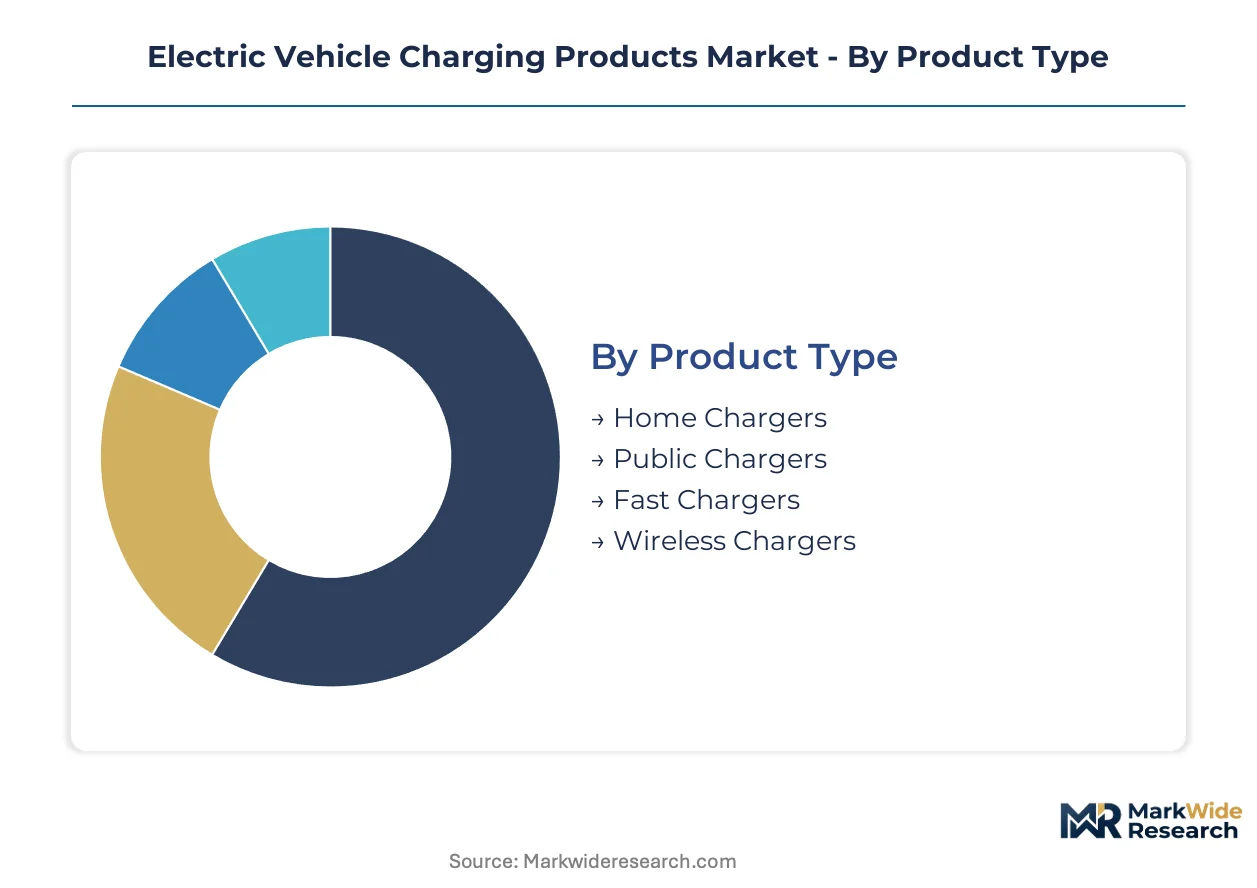
Charging hardware segmentation reveals divergent capital requirements across power classes and deployment contexts. Fleet operators prioritize throughput density while residential installations emphasize network integration and utility coordination.
Product Type:
Capital intensity escalates sharply with power output and grid interconnection complexity. DC fast-charging systems demand transformer upgrades and civil infrastructure that dwarf residential installation costs.
- Home Chargers:Level 1 and Level 2 AC units operating at 120V-240V with 3-19kW output. Demand concentrates in California and Texas where utility-sponsored deployment programs offset hardware costs for single-family dwellings. Volume leadership masks thin margins as procurement shifts toward subsidized bulk purchasing.
- Fast Chargers:DC systems delivering 50kW-350kW+ through liquid-cooled cables and high-frequency power electronics. Fleet depots in Germany and the Netherlands anchor demand as logistics operators electrify terminal operations. Grid-edge infrastructure bottlenecks constrain deployment velocity despite hardware availability.
- Public Chargers:Curbside and destination installations serving opportunistic charging patterns. Municipal procurement in France and the UK drives standardization toward CCS2 connectors.
- Wireless Chargers:Inductive pad systems eliminating physical connector wear. Pilot deployments target automated guided vehicles in controlled environments.
Most installed capacity flows through Home Chargers. Expansion is steepest in Fast Chargers.
Technology:
Technology selection tracks application power requirements and grid interaction depth. Bidirectional capability is becoming a procurement differentiator across all tiers.
- DC Charging:Direct current systems bypassing onboard rectifiers to deliver 400V-1000V to battery packs. China's coastal manufacturing clusters generate captive demand at assembly plants and test facilities where OEMs validate high-voltage architectures. Taiwan and South Korean semiconductor fabrication constraints extend power module lead times.
- Smart Charging:Network-connected systems with dynamic load management and demand response integration. California utilities mandate OpenADR protocol compliance for rebate eligibility, concentrating R&D investment among integrated software-hardware vendors.
- AC Charging:Alternating current systems relying on vehicle-mounted rectification. Residential and workplace deployments dominate volume.
- Solar Charging:PV-coupled systems with DC-DC conversion eliminating grid round-trip losses. Off-grid and remote installations in Australia and the southwestern US exploit high insolation zones.
AC Charging retains volume dominance. DC Charging is climbing the fastest as fleet electrification accelerates.
End User:
Customer type determines procurement scale, financing structure, and operational intensity. Fleet operators negotiate multi-year service contracts while residential users prioritize plug-and-play simplicity.
- Commercial Fleets:Logistics operators, delivery services, and municipal transport authorities with 10-500+ vehicle deployments. Binding EU CO2 standards for heavy-duty vehicles compel terminal electrification across German and Dutch logistics hubs. Hardware-as-a-service contracting preserves balance sheet capacity for mid-sized operators.
- Charging Networks:Third-party operators building corridor and urban fast-charging infrastructure. Interoperability platform providers create channel access for hardware manufacturers excluded from closed OEM ecosystems.
- Residential Users:Single-family homeowners and multi-unit dwelling residents. Utility interconnection queues in California delay energization beyond equipment delivery.
- Government:Municipal, state, and federal procurement for public transit and fleet electrification. US Inflation Reduction Act Section 30C tax credits accelerate hardware deployment timelines.
Commercial Fleets command the deepest margin pools. Charging Networks are expanding most quickly as roaming interoperability matures.
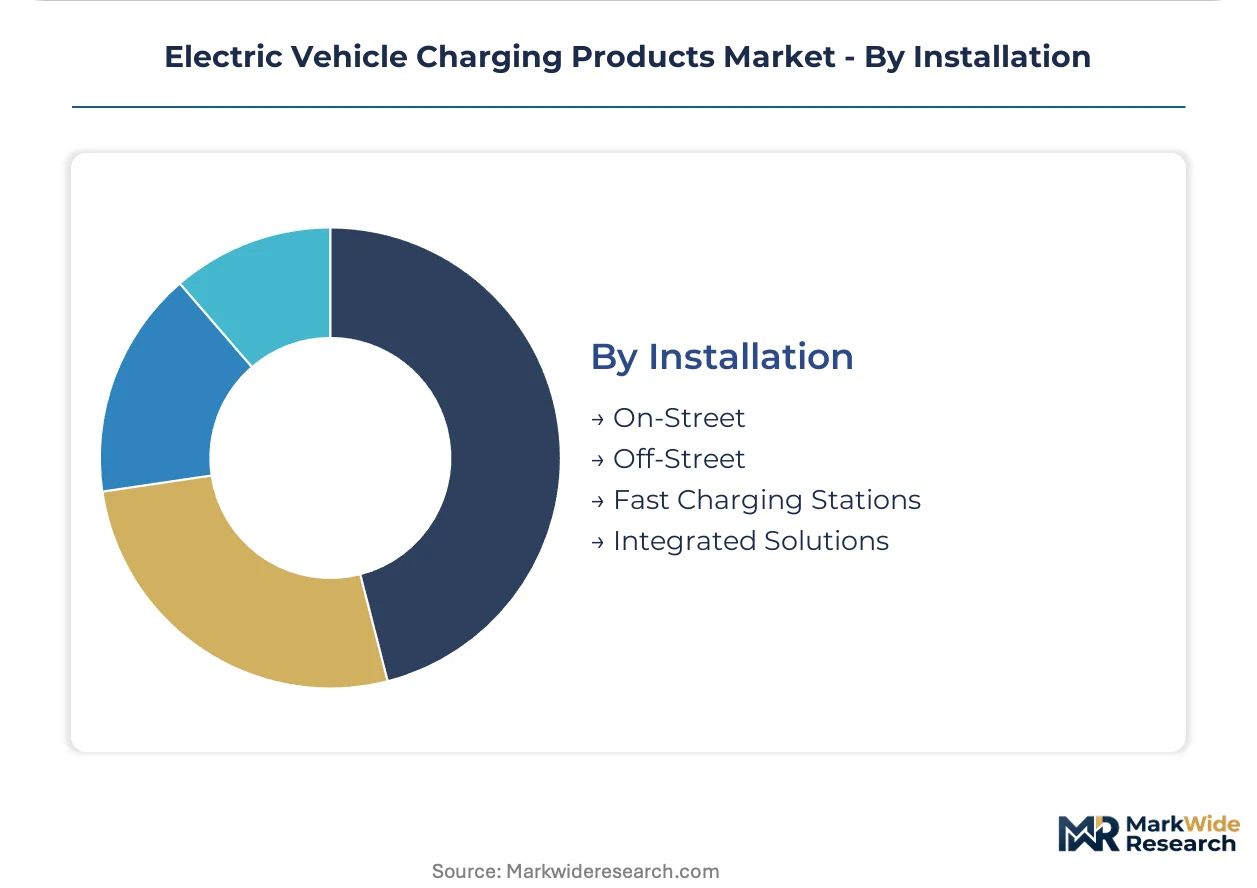
Installation:
Physical deployment context shapes civil engineering requirements, permitting complexity, and grid upgrade coordination. On-street installations face right-of-way constraints that off-street depots avoid.
- Off-Street:Depot, workplace, and residential garage installations with dedicated electrical service. Retrofitting existing facilities with constrained capacity requires costly civil and utility coordination in legacy industrial zones.
- Fast Charging Stations:Purpose-built high-power sites with dedicated substations and liquid-cooled cable systems. Utility interconnection queues in Germany extend energization delays.
- On-Street:Curbside deployments in urban rights-of-way requiring municipal permitting and trenching coordination. London and Paris accelerate lamp-post conversion programs.
- Integrated Solutions:Bundled hardware-software-energy offerings with performance guarantees. Dutch electricity market structures enable transparent time-of-use savings pass-through.
Off-Street locations host most installed capacity. Fast Charging Stations are gaining share fastest as corridor infrastructure gaps close.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as suppliers migrate production to jurisdictions with streamlined certification pathways and concentrated incentive pools. Cost-of-compliance gaps between the US Inflation Reduction Act, EU Green Deal frameworks, and China's MIIT protocols are redirecting capital toward coastal manufacturing clusters with integrated supply chains.
United States
Commercial fleet electrification and multi-unit dwelling retrofits drive hardware procurement across California and Texas logistics corridors. The Inflation Reduction Act's Section 30C tax credits accelerate deployment timelines for depot charging systems. Detroit-area automotive engineering clusters anchor power electronics R&D for 350kW+ DC architectures.
Germany
Binding EU CO2 standards for heavy-duty vehicles compel terminal electrification across North Rhine-Westphalia logistics hubs. The KBA type-approval process prioritizes refrigerant containment testing for liquid-cooled charging cables. Munich and Stuttgart engineering centers concentrate high-frequency magnetics expertise for next-generation power modules.
China
Guangdong and Jiangsu coastal manufacturing provinces generate captive demand for high-power charging systems at OEM assembly plants and test facilities. MIIT-mandated GB/T connector standards condition market access for foreign suppliers seeking domestic procurement tenders. Shenzhen power electronics clusters dominate silicon carbide device packaging.
India
Maharashtra and Tamil Nadu industrial corridors stimulate charging infrastructure demand under the PLI scheme for automotive manufacturing. The Bureau of Indian Standards enforces interoperability certification for network-connected units. Bangalore engineering centers develop thermal management systems adapted to tropical operating conditions.
Netherlands
Electricity market structures enabling transparent time-of-use savings pass-through accelerate hardware-as-a-service contracting among mid-sized fleet operators. The EU F-Gas Regulation phase-down accelerates natural refrigerant adoption in liquid-cooled systems. Eindhoven's high-tech systems cluster anchors smart charging software development.
Electric Vehicle Charging Products Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated software-hardware vendors capturing recurring revenue pools while pure power-conversion suppliers face margin compression. The vendor base concentrates around three strategic archetypes: grid-integration specialists leveraging utility relationships, automotive OEMs with captive charging ecosystems, and industrial power electronics firms extending factory automation expertise. Dominant competitive moves include strategic partnerships with fleet operators for depot-scale deployments and technology licensing agreements that open closed connector standards to third-party networks.
Within the integrated systems tier, ABB and Siemens represent European engineering-centric positioning anchored in industrial power electronics heritage. Tesla occupies a distinctive vertical-control archetype, sustaining proprietary network infrastructure while licensing connector standards to expand addressable market coverage. ChargePoint exemplifies the branded specialist model, concentrating on software-hardware integration for commercial and fleet deployments without upstream manufacturing integration.
| Leading Market Players |
|---|
| ChargePoint |
| ABB |
| Tesla |
| Siemens |
| EVBox |
| Wallbox |
| Eaton |
| Blink Charging |
| Kempower |
| Others |
Pricing and Supply Chain Analysis
Commercial fleet operators with multi-depot electrification mandates anchor procurement volume and compress vendor margins through hardware-as-a-service contracting. This buyer concentration shifts pricing power toward integrated software-hardware vendors who capture recurring revenue streams while pure power-conversion suppliers face commoditization pressure from utility-sponsored deployment programs.
Pricing Analysis
Distributor margins for DC fast-charging systems range from 15-25% before installation services, with direct-to-fleet contracts commanding 8-12% discounts for volume commitments above 50 units. Three-tier pricing structure across premium liquid-cooled architectures, standard air-cooled systems, and economy AC residential units tracks certification grade and thermal management complexity. Cost compression in residential Level 2 units intensifies because utility bulk purchasing programs aggregate demand and eliminate brand premium. Mid-sized fleet operators exhibit highest price sensitivity as they balance electrification timelines against balance sheet constraints, while charging network operators prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Dual-sourcing requirements for silicon carbide power modules are now standard among Tier 1 charging system integrators, with buyers mandating qualification across Taiwan, South Korea, and emerging domestic packaging facilities. Power semiconductor fabrication draws from Taiwanese foundry capacity, South Korean memory integration, and Chinese substrate processing. Raw material dependencies center on copper busbar stock, liquid-cooled cable assemblies, and natural refrigerant thermal management circuits. Single-source vulnerability concentrates in 350kW+ liquid-cooled cable systems where German KBA certification creates 18-month qualification barriers for alternative suppliers. Distribution runs through electrical wholesale channels for residential units and direct OEM-fleet relationships for depot-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Electric Vehicle Charging Products Market functions as a stable compounder where sovereign industrial policy creates durable demand visibility through binding fleet electrification mandates and infrastructure subsidy programs.
For Market Incumbents: Extend software-hardware integration depth to capture recurring revenue pools as dynamic load management requirements intensify. Defend margin position by securing exclusive fleet operator partnerships for depot-scale deployments before emerging entrants achieve KBA or EPA certification. Vertical integration into silicon carbide power module packaging reduces exposure to Taiwanese foundry lead time volatility. Prioritize ISO/SAE 21434 cybersecurity certification investment to compress validation cycles and accelerate procurement eligibility under federal frameworks. For New Entrants and Emerging Players: Bidirectional charging capability convergence with home energy management systems offers a technology-first wedge against incumbent hardware suppliers focused on unidirectional architectures. Target India's Maharashtra and Tamil Nadu industrial corridors where PLI scheme stimulus creates procurement windows before established vendors achieve BIS interoperability certification. Pursue third-party network roaming platform partnerships as the most penetrable channel for hardware manufacturers excluded from closed OEM ecosystems. Emphasize tropical-adapted thermal management systems developed for high-ambient operating conditions as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Electrical equipment conglomerates with existing utility relationships represent the most active acquirer category in this space, seeking charging infrastructure capabilities to complement grid-edge hardware portfolios. The acquisition target archetype comprises integrated software-hardware vendors with validated fleet operator relationships and recurring revenue contracts exceeding three-year terms. Monitor utility interconnection queue clearance velocity in California and Germany as the critical inflection indicator for hardware deployment acceleration or delay.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Power Module Integration | Reduces thermal losses in 350kW+ systems and extends operational lifespan under continuous duty cycles. |
| Dynamic Load Management Platform Deployment | Enables fleet operators to minimize demand charges through OpenADR-compliant demand response integration. |
| Natural Refrigerant Thermal System Transition | Anticipates EU F-Gas Regulation phase-down schedules and accelerates German KBA type-approval processes. |
| Hardware-as-a-Service Contracting Model | Preserves balance sheet capacity for mid-sized fleet operators in California and Netherlands electricity markets. |
| GB/T Protocol Localization Partnership | Unlocks access to China's coastal manufacturing province procurement tenders under MIIT-mandated standards. |
Research Methodology
Multiple input streams — executive interviews with charging network procurement directors, technical discussions with power electronics engineering leads, and regulatory consultations with EPA and EMA framework specialists — were reconciled against secondary validation from SEC equipment supplier filings, FERC interconnection queue databases, and IEA transport electrification tracking data. Primary engagement encompassed fleet operator sustainability officers, utility demand-side management planners, and semiconductor distribution channel managers. Bottom-up unit deployment estimates across residential, commercial fleet, and public corridor segments were triangulated against top-down infrastructure investment flows from sovereign incentive programs.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with segmentation modeling spanning power class architecture, end-user procurement scale, installation context, and regional regulatory cluster. CAGRs were derived from installed capacity buildout trajectories and hardware replacement cycles rather than revenue aggregation. Forecast inputs incorporated utility interconnection approval timelines, power semiconductor fabrication capacity expansion announcements, and evolving cybersecurity certification requirements under ISO/SAE 21434 protocols.
The model holds under sustained sovereign subsidy commitment and stable copper-silicon carbide supply availability; deviation in tariff exposure or single-source component disruption would shift deployment velocity materially. Deviation in utility interconnection queue clearance rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
EV Charging Cables Market
Electric Vehicle Charging
Electric Vehicle Supply Equipment (EVSE) Market
Electric Vehicle Charging
AC Electric Vehicle Charging Station Market
Electric Vehicle Charging
Germany Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Charging Station Raw Materials Market
Electric Vehicle Charging
Public EV Charger Market
Electric Vehicle Charging
Copper in Electric Vehicle Market
Electric Vehicle Charging
Stationary Electric Vehicle Charging Gun Market
Electric Vehicle Charging
APAC Electric Vehicle Charging Station Market
Electric Vehicle Charging
Solar Charging Station Market
Electric Vehicle Charging
Electric Vehicle Grid Integration Solutions Market
Electric Vehicle Charging
Europe Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Airport Charging Stations Market
Electric Vehicle Charging
Japan Electric Vehicle Charging Station Market
Electric Vehicle Charging
Electric Vehicle Charger Market
Electric Vehicle Charging
India Electric Vehicle Charging Station Market