
 Spain Electric Vehicle (EV) Charging Equipment Market | 2026-2036
Spain Electric Vehicle (EV) Charging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Electric Vehicle (EV) Charging Equipment Market Insights
CE marking under the EU's Low Voltage Directive and EMC standards is redrawing competitive entry barriers for equipment suppliers. ABB Ltd leverages its industrial automation heritage to anchor large-scale DC fast charger deployments across Iberian highway corridors. Wallbox Chargers sustains product specialization in compact residential units that dominate Spanish multi-dwelling installations. Iberdrola competes through vertical control of generation-to-charging value chains, extending its utility footprint into mobility services.
Spain Electric Vehicle (EV) Charging Equipment encompasses conductive power transfer systems rated from 3.7 kW residential AC through 350 kW ultra-fast DC configurations, incorporating power electronics, cooling subsystems, and communications protocols for grid interaction. These installations enable battery replenishment across passenger, commercial, and public transit fleets while supporting vehicle-to-grid bidirectional energy flows. DC Fast Chargers capture premium margin pools along trans-European transport corridors where dwell-time minimization commands tariff premiums. Smart Charging deployment models are displacing standalone units as distribution network operators mandate load-balancing interoperability. Residential Customers represent the volume foundation, though Fleet Operators generate higher per-site revenue intensity through centralized depot configurations.
Spain's Ministry for Ecological Transition administers MOVES III incentive frameworks that condition subsidy eligibility on minimum 22 kW AC or 50 kW DC output thresholds. The Spanish National Securities Market Commission oversees green bond issuances that finance charging infrastructure rollouts under EU taxonomy alignment rules. Stakeholders must monitor how proposed EU Battery Regulation due diligence requirements propagate into charger supply chain sourcing obligations.
Market Dynamics
The MOVES III subsidy framework is compressing deployment timelines while redrawing competitive entry barriers through CE marking mandates under EU Low Voltage Directive and EMC standards.
Growth Catalysts
- MOVES III subsidy thresholds:Spain's Ministry for Ecological Transition conditions eligibility on minimum 22 kW AC or 50 kW DC outputs, accelerating infrastructure rollouts across metropolitan corridors.
- Fleet electrification:Logistics operators are expanding depot-based charging configurations at centralized hubs, generating higher per-site revenue intensity than residential deployments.
- Smart charging interoperability:Distribution network operators in Madrid, Barcelona, and Valencia are mandating load-balancing protocols that displace standalone unit installations.
Market Restraints
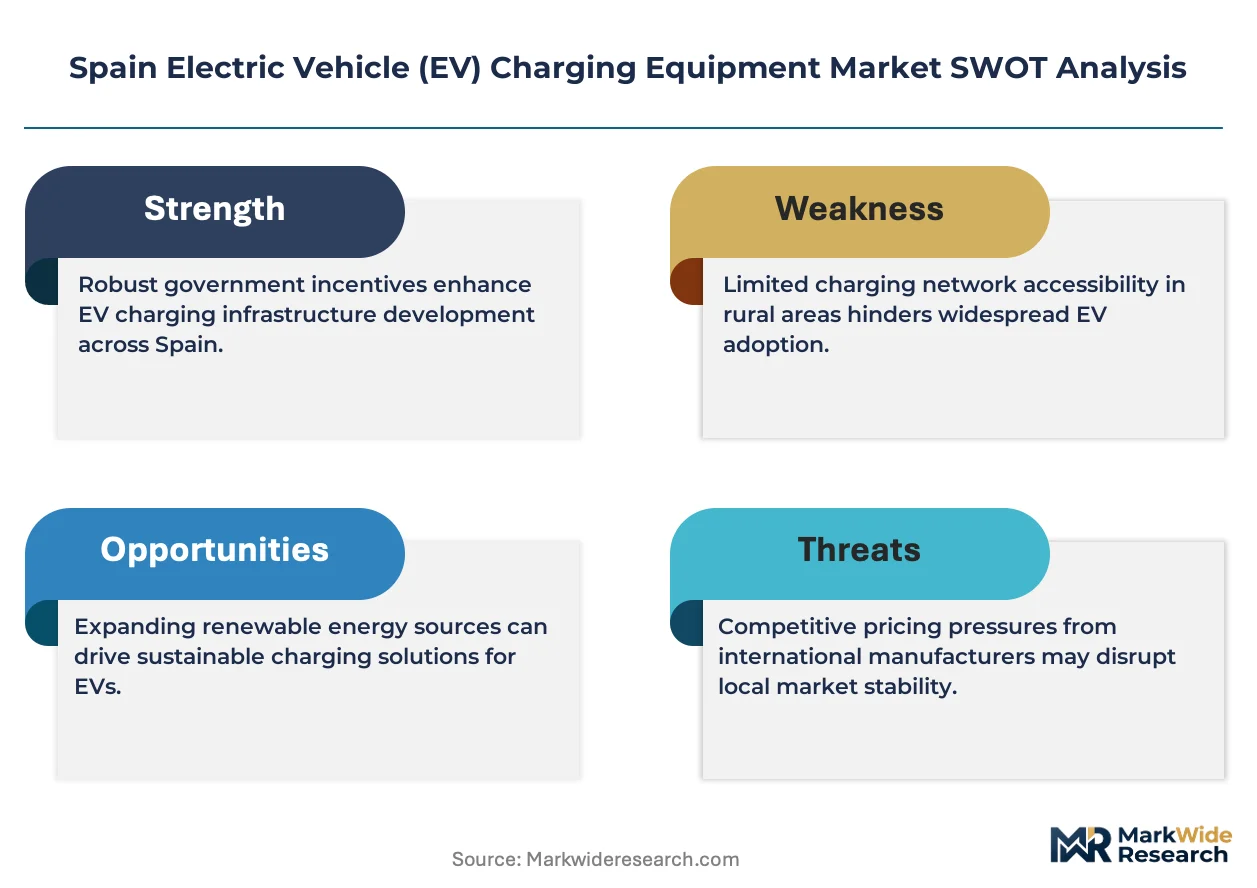
- Power electronics supply concentration:Semiconductor sourcing for 350 kW ultra-fast DC configurations faces bottlenecks from Asian foundry dependencies.
- Grid connection queuing:Spain's distribution operators impose extended technical study periods for high-capacity connections above 150 kW, delaying highway corridor deployments.
- Copper and rare earth volatility:Cooling subsystem manufacturing absorbs input cost swings from magnet and winding material markets.
Strategic Opportunities
- Vehicle-to-grid integration:Bidirectional energy flow capabilities create new revenue streams for fleet operators participating in Spanish demand-response programs.
- Andalusian corridor underpenetration:Southern Spain's logistics corridors between Seville and Málaga lack sufficient ultra-fast DC coverage relative to freight density.
- Green bond financing alignment:The Spanish National Securities Market Commission's EU taxonomy rules enable institutional capital deployment into charging infrastructure assets.
Industry Challenges
- Power electronics engineering scarcity:Specialized talent for 350 kW cooling and conversion system design remains concentrated among industrial automation veterans.
- CE marking timeline compression:EMC testing and Notified Body certification for new product variants extends market entry cycles by 8-14 months.
- Multi-dwelling installation complexity:Spanish condominium governance structures create coordination friction for shared residential charging infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Electric Vehicle (EV) Charging Equipment Market |
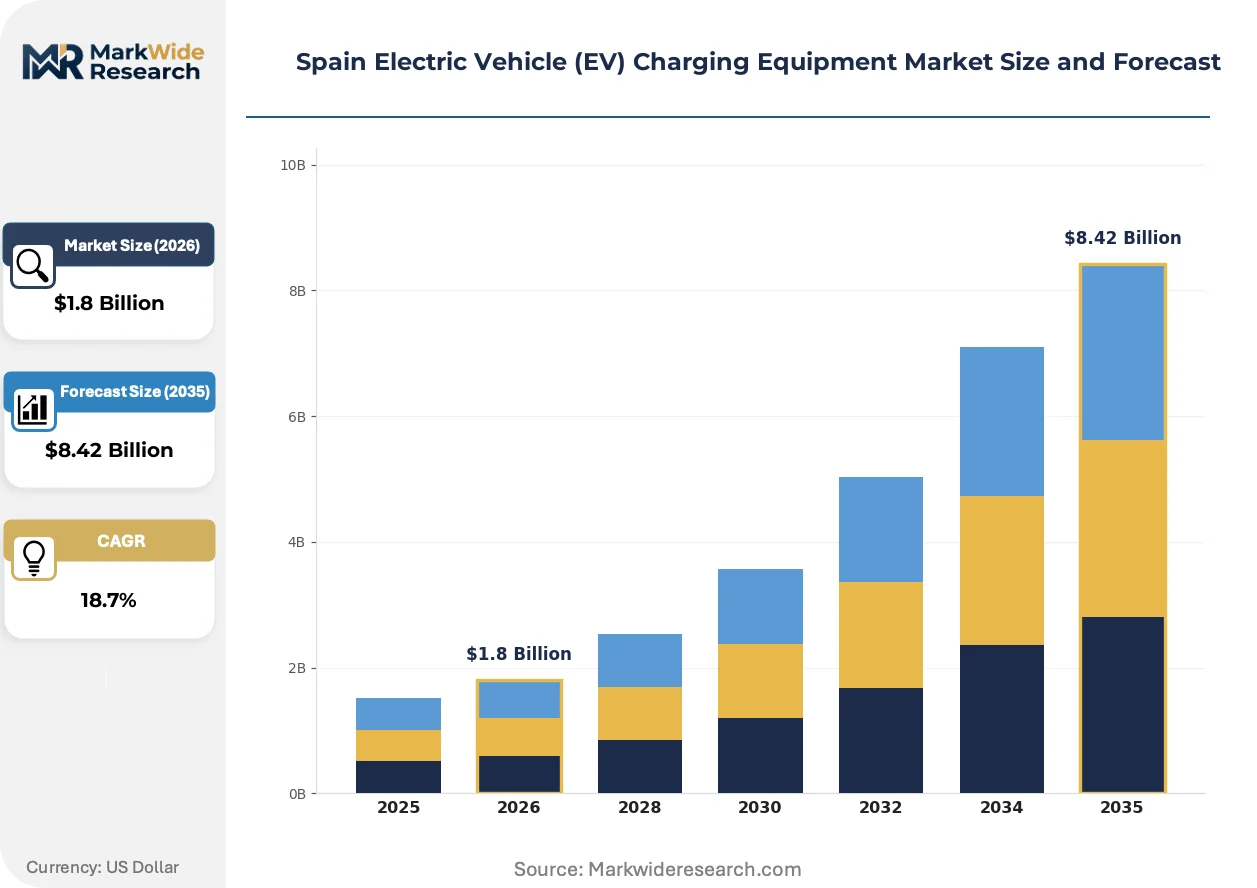
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Chargers, DC Fast Chargers, Wireless Chargers, Portable Chargers, Battery Swapping Stations Charging Connector: Type 1, Type 2, CHAdeMO, CCS Combo, Tesla Connector End User: Public Charging Points, Fleet Operators, Residential Customers, Commercial Establishments, Municipal Authorities Deployment Model: Standalone, Networked, Smart Charging, Solar Powered, Grid Connected |
| Companies Covered | ABB Ltd, Tesla Inc., Wallbox Chargers, Delta Electronics Inc., EVBox, Iberdrola, ChargePoint Inc., Kempower Charging Spain S.L.U., Endesa X Way, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Electric Vehicle (EV) Charging Equipment Market Trends and Innovations
Power electronics architectures and communications protocols are undergoing rapid specification shifts as grid-interactive capabilities become mandatory rather than optional.
Silicon carbide (SiC) power semiconductors enable higher switching frequencies and thermal efficiency in 150-350 kW DC fast charger designs. Fleet operators deploying depot-based configurations are adopting SiC-based units to minimize cooling footprint and maximize energy throughput. This technology is fragmenting supplier tiers as legacy silicon-based incumbents face displacement from specialized wide-bandgap semiconductor integrators.
The EU Battery Regulation's due diligence requirements are propagating into charger supply chain sourcing obligations for conflict minerals and carbon footprint verification. Equipment manufacturers must now document upstream material provenance to maintain CE marking validity under extended producer responsibility frameworks. Spanish suppliers with captive metal sourcing or established recycling partnerships capture preferential positioning in public procurement tenders.
Fleet procurement teams are consolidating vendor relationships around integrated hardware-software-service bundles rather than transactional equipment purchases. Large logistics operators in the Madrid-Barcelona corridor now require 10-year service level agreements encompassing predictive maintenance and guaranteed uptime thresholds. This contracting evolution compresses margins for pure-play hardware manufacturers while rewarding vertically integrated mobility service providers.
Spain Electric Vehicle (EV) Charging Equipment Market Segmentation
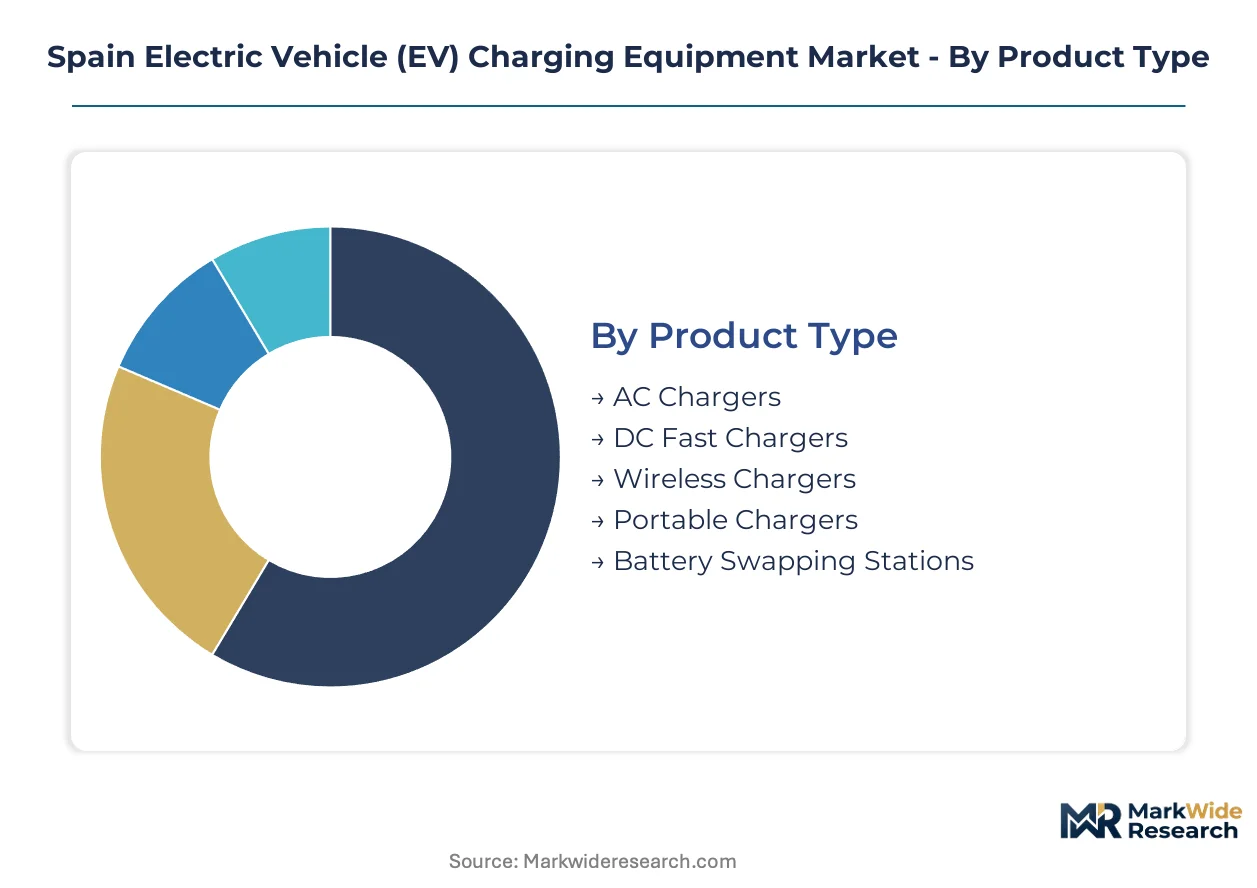
Segmentation in Spain's EV charging equipment market reveals how subsidy thresholds, grid constraints, and fleet procurement patterns concentrate demand across distinct product configurations and deployment models. Understanding these divisions exposes where MOVES III incentives reshape competitive positioning and where infrastructure gaps persist.
Product Type:
Domestic deployment dominates AC and DC categories through MOVES III-subsidized installations, while wireless and battery swapping technologies remain import-dependent with limited Spanish manufacturing presence.
- AC Chargers:These units span 3.7 kW to 22 kW single-phase and three-phase configurations, incorporating onboard power electronics and basic metering for residential and light commercial applications. Demand clusters in Madrid, Barcelona, and Valencia metropolitan corridors where multi-dwelling installations require compact wall-mounted designs. MOVES III eligibility thresholds starting at 22 kW AC are accelerating 11 kW and 22 kW unit deployment across condominium parking structures.
- DC Fast Chargers:Ranging from 50 kW to 350 kW with liquid-cooled power modules and CCS/CHAdeMO dual-cable configurations, these systems enable sub-30-minute replenishment for highway corridor and fleet depot applications. Iberian transport corridors between Madrid-Barcelona and Madrid-Valencia command premium positioning where dwell-time minimization justifies higher capital expenditure.
- Wireless Chargers:Inductive pad systems operating at 3.6 kW to 11 kW with coil alignment tolerance compensation remain nascent in Spanish deployments.
- Portable Chargers:Compact 2.3 kW to 3.7 kW emergency units with Schuko or industrial plug compatibility serve rural and secondary vehicle households.
- Battery Swapping Stations:Automated robotic exchange systems for commercial two-wheeler and three-wheeler segments see pilot activity in Barcelona logistics zones.
AC Chargers holds the largest share; momentum sits with DC Fast Chargers.
Charging Connector:
Cost tier differentiation separates premium CCS Combo deployments from legacy Type 1 retrofits, with connector selection directly tied to vehicle fleet composition and highway interoperability mandates.
- Type 1:Single-phase J1772 connectors limited to 7.4 kW serve legacy imported Japanese and early American EV models in Spanish secondary markets.
- Type 2:The European standard Mennekes connector supporting three-phase 22 kW AC dominates residential and workplace installations across Spanish distribution networks.
- CHAdeMO:This Japanese DC standard at 50 kW to 100 kW persists in early highway corridor deployments and Nissan Leaf fleet configurations.
- CCS Combo:Combined Charging System integrating Type 2 AC pins with DC fast-charging contacts supports 350 kW ultra-fast configurations. Spanish fleet operators and highway concessionaires are standardizing on CCS Combo 2 for new procurement, displacing CHAdeMO in trans-European corridor planning.
- Tesla Connector:Proprietary North American design with limited Spanish presence; Tesla Supercharger network in Spain now migrating to CCS Combo 2 compatibility.
Type 2 connectors command installed base dominance; CCS Combo is climbing the fastest in new deployment commitments.
End User:
Application-driven segmentation shows fleet operators generating highest per-site revenue intensity while residential volumes anchor total unit shipments under subsidized programs.
- Public Charging Points:Highway service areas, urban curbside installations, and retail parking facilities with 24/7 accessibility and roaming platform integration.
- Fleet Operators:Centralized depot configurations for logistics, postal, and utility vehicle pools with 50 kW to 150 kW DC hub architectures. Revenue per site exceeds residential deployments by multiples due to guaranteed utilization rates and service-level agreement structures.
- Residential Customers:Single-family and multi-dwelling installations at 3.7 kW to 11 kW AC, representing volume foundation but lower margin per unit. Spanish condominium governance creates coordination friction for shared infrastructure.
- Commercial Establishments:Workplace, hotel, and retail destination charging with dwell-time-matched power levels.
- Municipal Authorities:Public transit electrification and municipal fleet depot projects with procurement through centralized purchasing consortia.
Fleet Operators capture the steepest expansion trajectory; Residential Customers maintain volume leadership.
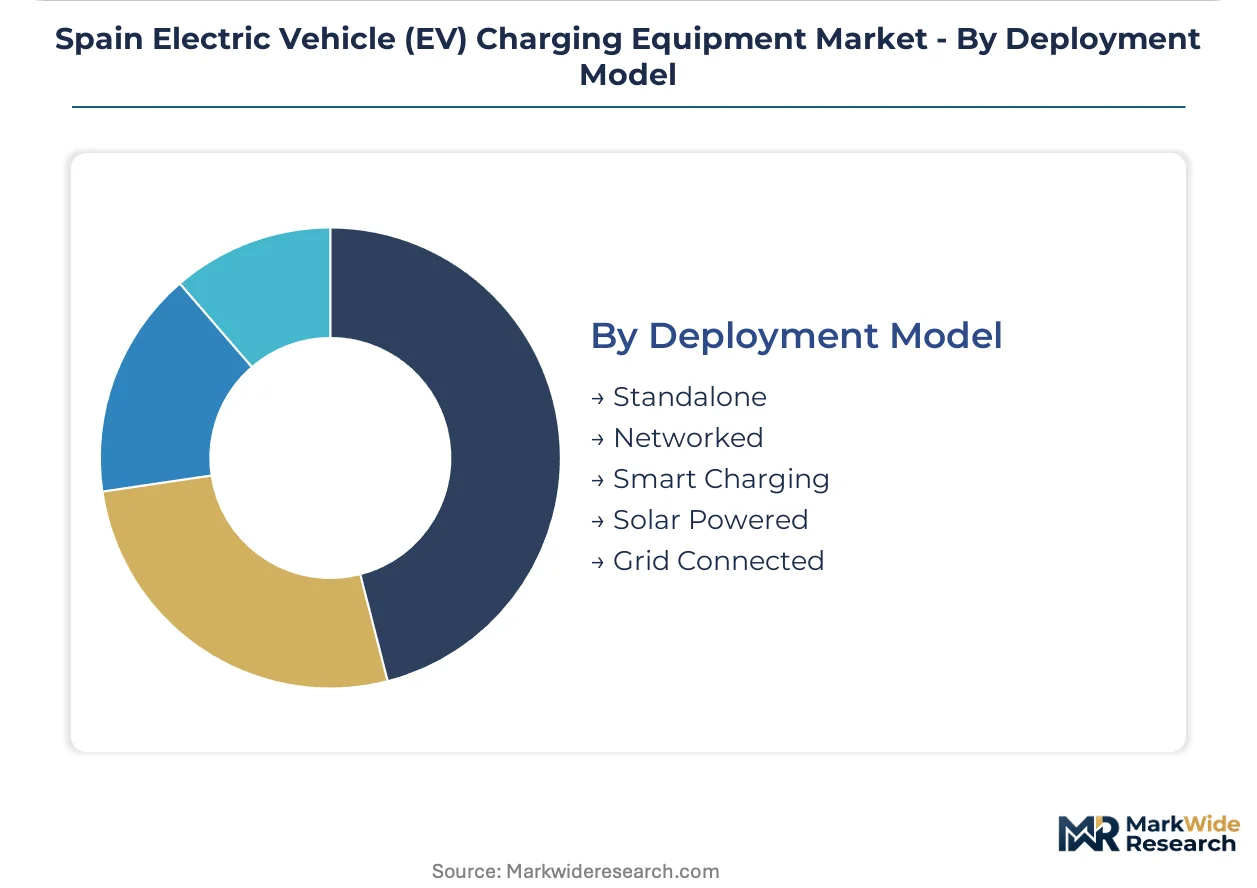
Deployment Model:
Supply concentration among grid-interactive system integrators is displacing standalone unit vendors as distribution network operators mandate interoperability protocols.
- Standalone:Basic plug-and-charge units without network connectivity, declining in Spanish deployments due to MOVES III smart charging requirements.
- Networked:Cloud-connected installations with payment platform integration and remote diagnostics, now baseline for public access points.
- Smart Charging:Load-balancing systems with dynamic power adjustment responding to grid signals and vehicle state-of-charge. Distribution network operators in Madrid, Barcelona, and Valencia are mandating these protocols for new connections above 22 kW.
- Solar Powered:DC-coupled photovoltaic integration with battery buffering for off-grid or peak-shaving configurations in Andalusian and Extremaduran rural deployments.
- Grid Connected:Bi-directional vehicle-to-grid capable systems enabling demand-response participation and frequency regulation services.
Networked deployments hold current installed base dominance; Smart Charging is gaining share fastest through regulatory mandate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MOVES III subsidy thresholds condition eligibility on minimum 22 kW AC or 50 kW DC outputs, accelerating infrastructure rollouts across Spanish metropolitan corridors while compressing deployment timelines for qualified equipment.
Madrid
Fleet electrification and logistics depot expansion drive demand for 150 kW DC hub architectures in the capital region. Spain's Ministry for Ecological Transition administers MOVES III incentive frameworks that prioritize high-capacity urban connections. The Madrid-Barcelona transport corridor commands premium positioning where dwell-time minimization justifies higher capital expenditure on ultra-fast configurations.
Catalonia
Barcelona's metropolitan density and condominium governance structures create coordination friction for shared residential charging infrastructure while generating volume demand. CE marking mandates under EU Low Voltage Directive and EMC standards redraw competitive entry barriers for equipment suppliers. The Port of Barcelona logistics zone sees pilot activity for battery swapping stations serving commercial two-wheeler segments.
Valencia
Smart charging interoperability mandates from distribution network operators are displacing standalone unit installations across the third metropolitan corridor. Load-balancing protocols with dynamic power adjustment responding to grid signals are now required for new connections above 22 kW. Valencia's automotive manufacturing heritage supports regional supplier ecosystems for power electronics integration.
Andalusia
Southern Spain's logistics corridors between Seville and Málaga lack sufficient ultra-fast DC coverage relative to freight density, creating strategic whitespace for corridor development. Solar-powered DC-coupled photovoltaic integration with battery buffering finds application in rural Extremaduran and Andalusian deployments. The region's high insolation supports off-grid or peak-shaving configurations for agricultural and secondary vehicle households.
Basque Country
Industrial automation heritage from the region's machinery sector feeds specialized talent pools for 350 kW cooling and conversion system design. Spanish National Securities Market Commission oversight of green bond issuances enables institutional capital deployment into charging infrastructure assets anchored in northern industrial zones. Bilbao-San Sebastián corridor development concentrates on fleet depot configurations for logistics and utility vehicle pools.
Spain Electric Vehicle (EV) Charging Equipment Market Competitive Landscape
Player mix skews toward industrial automation conglomerates and utility-backed mobility service providers, with pure-play hardware manufacturers facing margin compression from service-level agreement demands. Equipment supply concentrates among CE-certified system integrators capable of navigating 8-14 month EMC testing and Notified Body certification cycles. Three archetypes dominate: vertically integrated utilities controlling generation-to-charging value chains; industrial automation specialists leveraging power electronics heritage; and compact residential specialists optimized for multi-dwelling installations. Competitive moves center on strategic partnerships for software-service bundling and geographic corridor anchoring through highway concession relationships.
Within the utility-backed tier, Iberdrola and Endesa X Way occupy positions exemplifying vertical control of generation-to-charging value chains with extension into mobility services. Among industrial automation specialists, ABB Ltd anchors large-scale DC fast charger deployments across Iberian highway corridors, representing archetype concentration of power electronics engineering capability. Wallbox Chargers sits within the compact residential specialist tier, with product configurations optimized for Spanish multi-dwelling installation constraints.
| Leading Market Players |
|---|
| ABB Ltd |
| Tesla Inc. |
| Wallbox Chargers |
| Delta Electronics Inc. |
| EVBox |
| Iberdrola |
| ChargePoint Inc. |
| Kempower Charging Spain S.L.U. |
| Endesa X Way |
| Others |
Pricing and Supply Chain Analysis
CE marking compliance under the EU's Low Voltage Directive and EMC standards gates both supplier qualification and price tiering simultaneously, compressing margins for uncertified entrants while rewarding system integrators with extended Notified Body relationships. Equipment buyers face bifurcated sourcing economics where certification-validated hardware commands premium positioning against gray-market alternatives lacking grid-interoperability guarantees.
Pricing Analysis
Certification level creates the primary spread between market tiers. Three-tier pricing structure across premium CE-validated, standard EMC-tested, and economy non-networked units dominates procurement patterns. Fleet operators show lowest price sensitivity due to 10-year service agreement bundling, while residential condominium associations face acute cost pressure from governance friction and shared infrastructure coordination costs. Cost compression in the standard tier intensifies as Asian power module suppliers expand direct distribution into Iberian markets.
Supply Chain Analysis
Strait of Malacca transit routes for silicon carbide substrates and rare earth magnets concentrate vulnerability in semiconductor sourcing for 350 kW ultra-fast DC configurations. Power electronics manufacturing draws from Taiwan, China, and Germany for wide-bandgap semiconductor fabrication, with copper winding materials and liquid cooling subsystems sourcing from Chilean and Indonesian mining operations. Single-source vulnerability in SiC wafer supply creates procurement risk for Spanish system integrators lacking long-term offtake agreements. Distribution runs through Madrid and Barcelona logistics hubs for final assembly and CE certification staging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MOVES III subsidy fragmentation across metropolitan corridors, fleet depots, and rural solar-integrated deployments creates multiple niche entry points for specialized competitors. Demand-side shift toward smart charging interoperability mandates splits the vendor base between legacy standalone suppliers and grid-interactive system integrators.
For Market Incumbents: Consolidate around highway corridor anchoring through concession partnerships with Iberian transport operators, defending against utility-backed mobility service providers encroaching on fleet depot segments. Deepen backward integration into power electronics assembly through Basque Country industrial automation partnerships to secure SiC module supply against Asian foundry bottlenecks.
For New Entrants and Emerging Players: Differentiate on Andalusian corridor whitespace where Seville-Málaga freight density lacks sufficient ultra-fast DC coverage relative to logistics flow concentration. Target solar-powered DC-coupled configurations for Extremaduran agricultural and secondary vehicle households underserved by grid-connected infrastructure. Pursue municipal authority procurement channels through centralized purchasing consortia with simplified CE compliance pathways.
For Investors and Strategic Acquirers: EU Battery Regulation due diligence requirements reshaping the acquisition landscape toward suppliers with documented upstream material provenance and established recycling partnerships. Long-term viability centers on equipment manufacturers with captive metal sourcing or circular economy infrastructure spanning the analysis window. Acquisition target archetype: mid-tier system integrators with validated Notified Body relationships and existing MOVES III project pipelines. Watch for Spanish National Securities Market Commission green bond issuance velocity as inflection indicator for institutional capital deployment into charging infrastructure assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Charging Interoperability Certification | CE marking under EMC standards enables grid-connection approvals from Madrid distribution operators. |
| SiC Power Module Backward Integration | Captive semiconductor sourcing insulates margins against Asian foundry allocation constraints. |
| Highway Corridor Concession Partnership | Iberian transport route anchoring secures premium dwell-time-minimization tariff positioning. |
| Vehicle-to-Grid Capability Deployment | Bidirectional systems unlock Spanish demand-response program revenue for fleet operators. |
| Green Bond Financing Alignment | EU taxonomy compliance enables institutional capital deployment from CNMV-supervised issuances. |
Research Methodology
Operator-level perspectives from fleet electrification managers, distribution network engineers, condominium governance representatives, and MOVES III program administrators anchored the qualitative base. Primary fieldwork combined structured interviews with equipment procurement leads at logistics operators and utility mobility service divisions. Secondary validation drew from Spanish Ministry for Ecological Transition subsidy disbursement records, EU taxonomy alignment disclosures, and Iberdrola and Endesa X Way infrastructure rollout filings. Bottom-up unit deployment estimates triangulated against top-down green bond financing flow analysis.
Sensitivity analysis across power electronics cost trajectories, grid connection queuing durations, and subsidy threshold adjustments shaped the analytical framework. Segmentation dimensions modeled include product type configuration, charging connector standard, end-user application, and deployment model complexity across the projection horizon. CAGRs derived from installed base expansion rates and per-site revenue intensity differentials between residential and fleet depot configurations. Forecast inputs incorporated SiC semiconductor price elasticity and copper commodity volatility assumptions.
Material uncertainties — semiconductor supply allocation shifts, MOVES III program renewal negotiations, and distribution operator interconnection policy revisions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding subsidy continuity and CE marking timeline stability. Revision becomes warranted when grid connection queuing durations for high-capacity installations cross regulatory intervention thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Battery Liquid Cooling Plates for Electric Vehicle Market
Electric Vehicle Charging
Asia-Pacific Wireless Electric Vehicle Charging Market
Electric Vehicle Charging
EV Charging Station Market
Electric Vehicle Charging
Western Europe Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
Solar Charge Controller Market
Electric Vehicle Charging
PV BESS EV Charging Systems Market
Electric Vehicle Charging
North America Wireless Charging Market
Electric Vehicle Charging
AC Electric Vehicle Charging Station Market
Electric Vehicle Charging
Electric Vehicle Showroom Charger Market
Electric Vehicle Charging
Electric Vehicle Charging Systems Testing Market
Electric Vehicle Charging
North America Electric Vehicle Charging Station Market
Electric Vehicle Charging
Global Automotive Charging System Market
Electric Vehicle Charging
Global EV Charger Market
Electric Vehicle Charging
Electric Vehicle Charging Facilities Market
Electric Vehicle Charging
EV Charge Controller Market
Electric Vehicle Charging
Thermal Conductive Polymer Material for Electric Vehicles Market