
 EV Charging Point Market | 2026-2036
EV Charging Point Market Size, Share, and Industry Trends Forecast 2026-2036
EV Charging Point Market Insights
Commercial fleet electrification is hardening as the dominant demand vertical for EV charging point infrastructure, displacing early reliance on residential and discretionary public charging. ChargePoint leverages its software-integrated hardware platform to anchor fleet depot installations across North America. ABB sustains technology leadership in high-power DC systems above 350 kW for highway corridor applications. Tesla dominates destination charging through its proprietary connector standard and captive vehicle base, though its North American Charging Standard now faces competitive pressure from CCS alternatives.
EV charging points are electromechanical systems that convert grid alternating current into direct current matched to lithium-ion battery chemistries, with power ratings spanning 1.4 kW residential Level 1 units to 480 kW liquid-cooled DC fast chargers using silicon carbide power electronics. Their primary purpose is to replenish vehicle energy stores within time windows compatible with operator duty cycles, from overnight residential sessions to sub-30-minute highway stops. DC Fast Charging captures the majority of capital deployment as fleet operators and highway concessionaires prioritize throughput over unit economics, while Wireless Charging remains nascent with margin pools concentrated in premium autonomous shuttle pilots. Residential Use still generates the highest connector count globally but yields lower per-site revenue and installation complexity.
EPA greenhouse gas standards for light-duty and heavy-duty vehicles, NHTSA Corporate Average Fuel Economy rules, and the EU Green Deal's transport decarbonization benchmarks collectively mandate charger availability as a compliance enabler for automaker sales portfolios. China's MIIT and SAMR enforce GB/T connector standards and grid interconnection protocols that shape product design for any manufacturer serving that market. Stakeholders must monitor evolving interoperability mandates and utility rate structures, as these determine which charging business models achieve unit profitability without reliance on subsidized capital deployment.
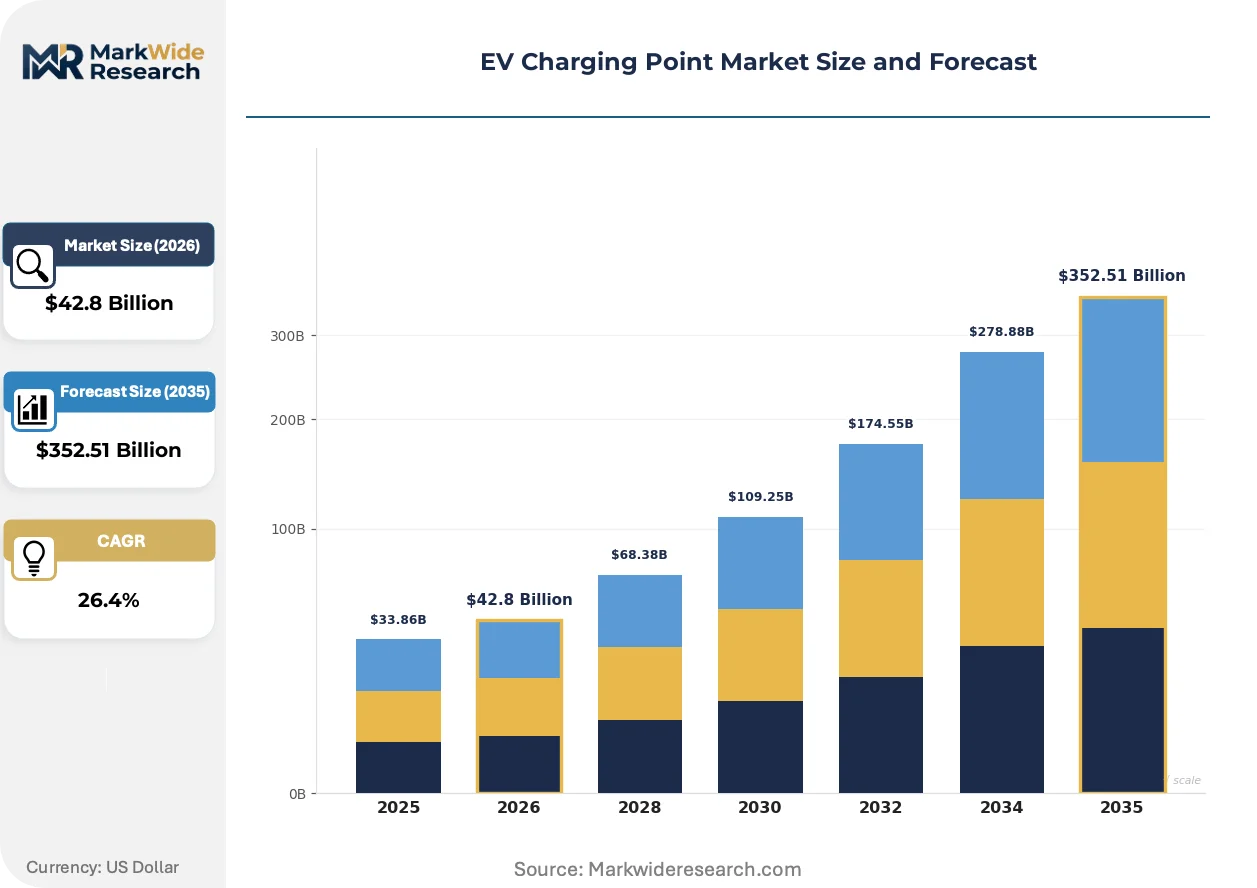
Market Dynamics
Fleet electrification mandates from EPA tailpipe rules and EU Green Deal targets are compressing charger deployment timelines, forcing infrastructure buildout ahead of vehicle availability curves.
Growth Catalysts
- Heavy-duty fleet mandates:EPA greenhouse gas standards for medium and heavy-duty vehicles require depot charging infrastructure at commercial terminals across the United States.
- Corridor electrification programs:The EU Green Deal's transport decarbonization benchmarks mandate ultra-fast charging density along European freight corridors.
- Silicon carbide power electronics:Wider bandgap semiconductors enable 350 kW+ DC systems with reduced thermal losses and smaller form factors.
Market Restraints
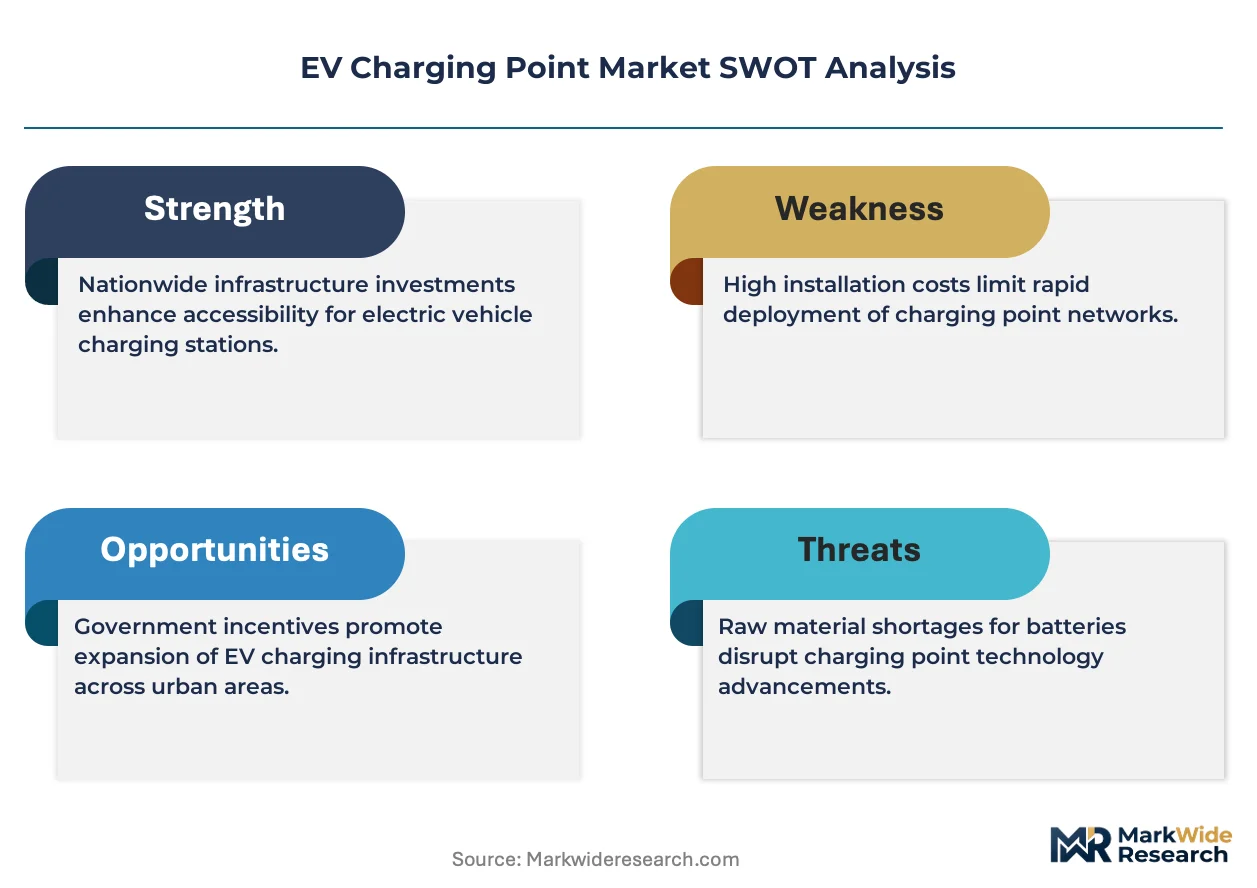
- Transformer and switchgear shortages:Utility-scale electrical equipment lead times now extend 18-24 months, constraining site energization schedules.
- Copper and rare earth price volatility:Liquid-cooled cable assemblies and permanent magnet components face input cost pressures from concentrated mining geographies.
- Grid interconnection queues:Distribution system operators in Germany and California impose multi-year approval timelines for high-capacity connections.
Strategic Opportunities
- India's PLI scheme for auto components:Domestic manufacturing incentives create localized supply chains for AC and DC charging hardware serving South Asian markets.
- Vehicle-to-grid integration:Bidirectional charging protocols enable fleet operators to monetize battery assets through frequency regulation services.
- Wireless inductive pilots:Autonomous shuttle and last-mile delivery applications in Singapore and Dubai test pad-based charging without connector wear.
Industry Challenges
- Power electronics engineering talent scarcity:Silicon carbide inverter design and thermal management expertise concentrates at a handful of specialized firms and research institutes.
- Multi-standard certification complexity:GB/T, CCS, CHAdeMO, and NACS connector variants require parallel testing regimes for any manufacturer serving multiple markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Charging Point Market |
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $352.51 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Charging Type: Level 1, Level 2, DC Fast Charging, Wireless Charging Application: Commercial Use, Residential Use, Fleet Management, Public Parking Installation Type: Wall-Mounted, Ground-Mounted, Portable, Integrated Infrastructure Provider: Utility Companies, Third-Party Providers, Automotive OEMs, Others |
| Companies Covered | ChargePoint, ABB, Tesla, EVBox, Wallbox, Eaton, Delta Electronics, Star Charge, TELD New Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Charging Point Market Trends and Innovations
Charging infrastructure is pivoting from hardware-centric deployment to software-orchestrated energy systems, with interoperability and grid integration becoming primary value drivers over connector count.
Silicon carbide MOSFETs are unifying power conversion architectures across charging tiers, replacing silicon IGBTs in modules from 22 kW AC to 480 kW liquid-cooled DC systems. Tier 1 suppliers and charging network operators are adopting these devices to reduce cooling system mass and enable higher switching frequencies. This unification is compressing development cycles for multi-standard chargers serving both passenger and commercial vehicle segments.
EPA's updated Corporate Average Fuel Economy enforcement mechanisms now treat charging accessibility as a compliance prerequisite for automaker sales credits, not merely a market enabler. The industrial consequence is pre-competitive infrastructure consortia forming between OEMs and utilities to share site development costs. Heavy-duty truck manufacturers face the tightest compliance windows, driving accelerated corridor deployment along I-10, I-75, and I-80 in the United States.
Buyer contracting patterns are fragmenting from capital purchase toward equipment-as-a-service arrangements with energy throughput guarantees. Fleet operators now prefer contracts where hardware, installation, maintenance, and electricity flow as unified operational expenditures rather than separated capital line items. This shift is most visible among North American logistics providers managing mixed diesel-electric transition fleets with unpredictable utilization patterns.
EV Charging Point Market Segmentation
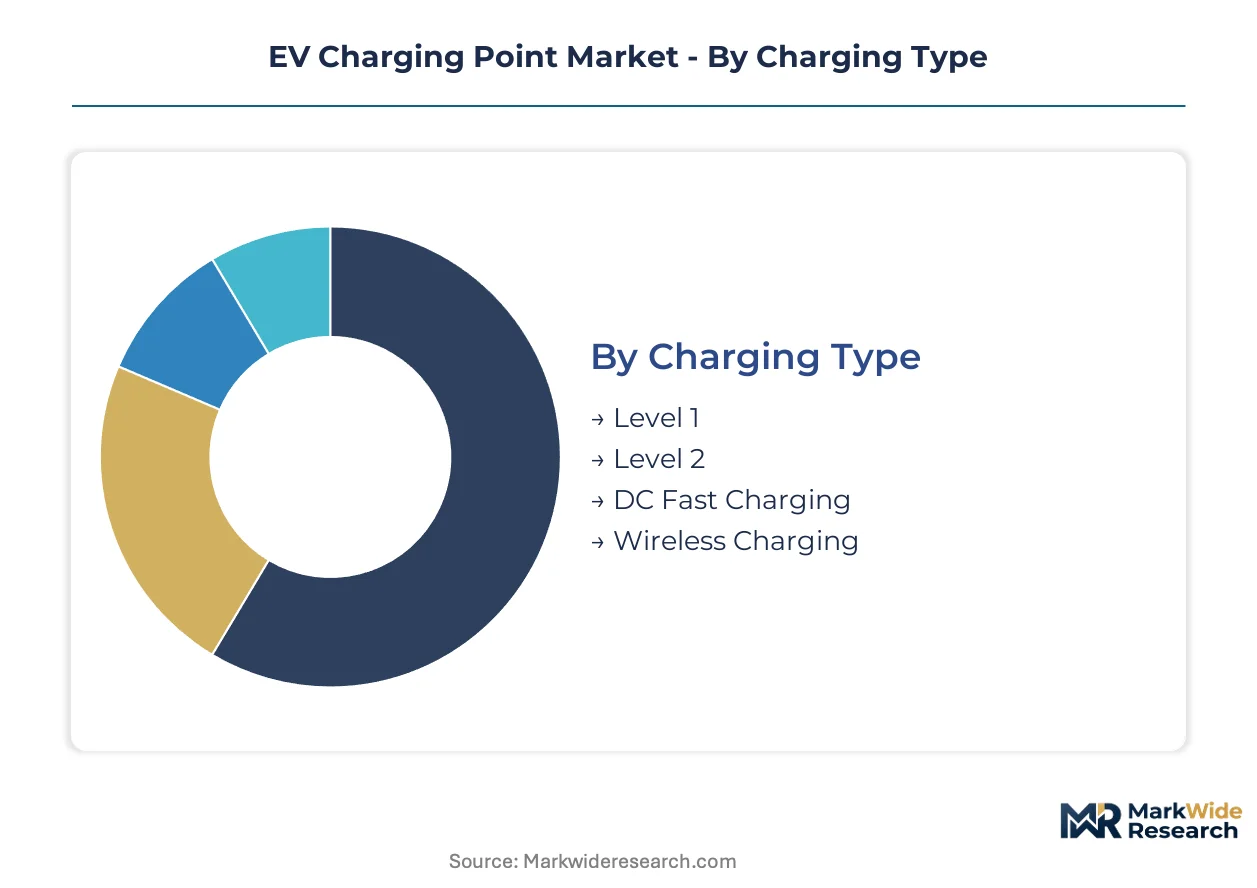
Segmentation in EV charging infrastructure reveals how power ratings, duty cycles, and ownership models fragment capital deployment across residential, commercial, and fleet applications. Each dimension shapes hardware specifications, software integration requirements, and revenue model viability for infrastructure operators.
Charging Type:
Power conversion architectures span a customization-vs-standardization spectrum, from universal AC interfaces to proprietary high-voltage DC systems with liquid-cooled cabling.
- Level 1:1.4 kW residential units using standard J1772 connectors dominate overnight charging in single-family dwellings across suburban United States. Installation requires no electrical upgrades, keeping deployment costs minimal for homeowner self-installation. Demand concentrates in legacy housing stock where panel capacity cannot support higher amperage.
- Level 2:7-19 kW AC systems with onboard vehicle rectification serve workplace and multi-unit dwelling applications. These units balance charging speed against infrastructure cost, with ClipperCreek and Enel X hardware prevalent in North American commercial parking installations. Workplace operators in Germany and California prioritize these for 6-8 hour dwell times.
- DC Fast Charging:50-480 kW off-board rectifiers with liquid-cooled CCS or NACS connectors enable sub-30-minute highway stops. Silicon carbide power electronics now standardize across 350 kW+ systems from ABB and Siemens.
- Wireless Charging:Inductive pad systems operating at 85 kHz resonance frequency pilot in autonomous shuttle deployments. Singapore and Dubai test fleets use WiTricity and Electreon hardware for connector-free operation.
Most installed capacity flows through Level 2 systems. Expansion is steepest in DC Fast Charging corridors.
Application:
End-use concentration shifts from consumer convenience toward commercial asset utilization, with fleet operators now driving procurement volume over discretionary public charging.
- Commercial Use:Retail and workplace installations prioritize dwell-time matching, with 6-22 kW AC units dominating shopping center deployments. ChargePoint and Blink networks optimize for session revenue per parking space rather than throughput.
- Residential Use:Single-family and multi-unit dwelling installations generate the highest connector count globally but yield lower per-site revenue. California Title 24 building codes now mandate EV-ready infrastructure in new construction, accelerating deployment.
- Fleet Management:Depot charging for logistics, transit, and municipal vehicles requires 150-350 kW DC systems with software-optimized load management. Amazon and UPS contract for megawatt-scale installations with guaranteed uptime SLAs.
- Public Parking:Curbside and municipal garage installations face utilization uncertainty, with many jurisdictions subsidizing capital costs to meet EPA accessibility mandates.
Fleet Management now captures the majority of new capital commitment. Public Parking remains dependent on subsidy structures for financial viability.
Installation Type:
Physical mounting configurations trade deployment flexibility against permanence, with portable and integrated systems gaining traction in temporary or space-constrained environments.
- Wall-Mounted:Bracket-attached units minimize ground footprint in parking garages and residential carports. These dominate European urban installations where space constraints favor vertical mounting.
- Ground-Mounted:Pedestal or bollard configurations withstand vandalism and vehicle impact in public environments. Highway corridor deployments favor these for accessibility and maintenance access.
- Portable:Mobile units with NEMA 14-50 or equivalent plugs serve temporary events and emergency charging. Construction and film production fleets in Los Angeles and London deploy these for location flexibility.
- Integrated:Charging hardware embedded in street furniture, luminaires, or building facades reduces visual clutter. Amsterdam and Copenhagen pilot lamp-post integrated systems for curbside charging without dedicated infrastructure.
Ground-Mounted systems absorb the largest share of highway corridor investment. Integrated configurations are gaining share fastest in dense European urban cores.
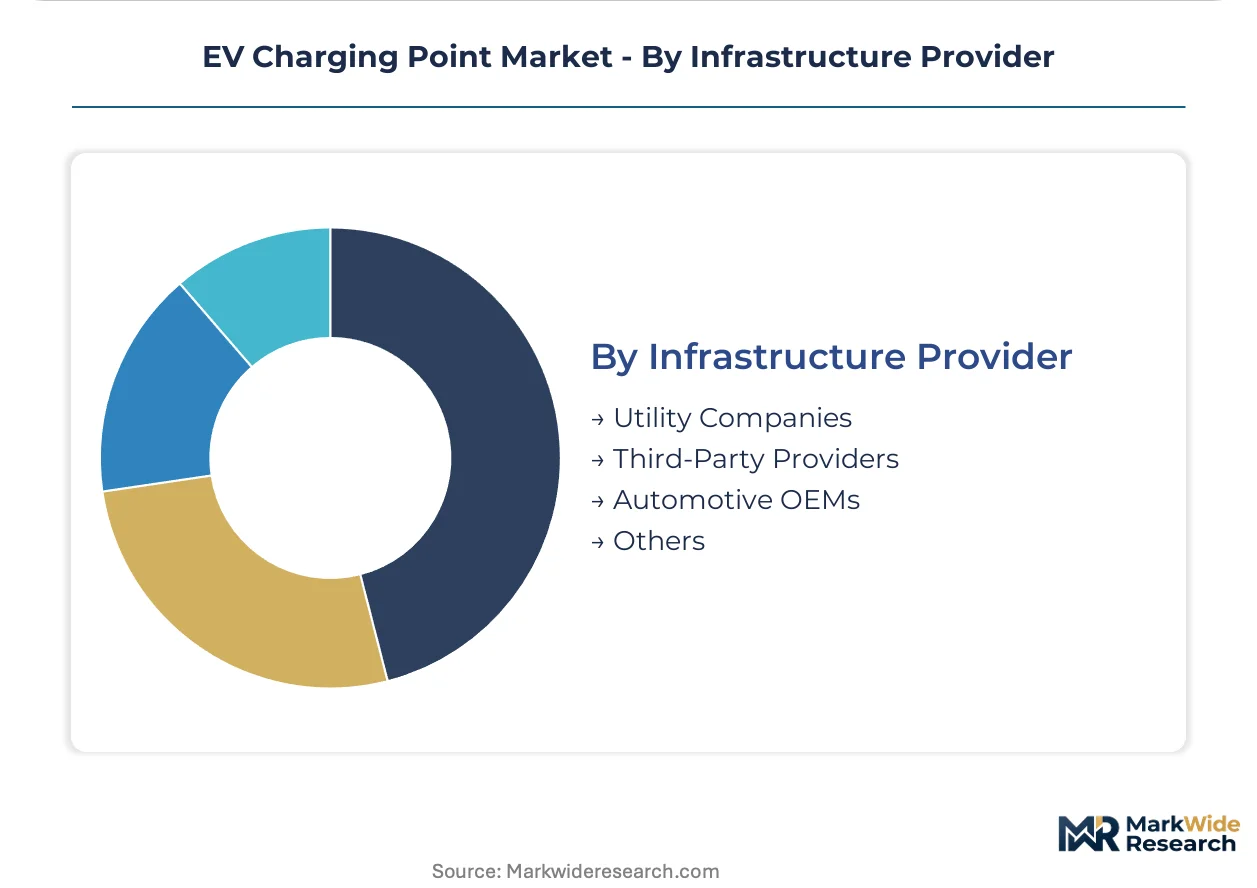
Infrastructure Provider:
Ownership models fragment across regulated utilities, competitive third-party networks, and automaker-captive systems, each with distinct capital sources and customer acquisition strategies.
- Utility Companies:State Grid, E.ON, and Southern California Edison deploy charging as grid edge infrastructure, often at regulated returns. These operators prioritize managed charging to mitigate distribution transformer loading.
- Third-Party Providers:ChargePoint, EVgo, and Ionity operate open-network DC fast charging with roaming interoperability. Their business models depend on utilization rates and energy margin capture.
- Automotive OEMs:Tesla, Rivian, and Mercedes-Benz deploy proprietary networks to support vehicle sales and brand loyalty. Tesla's NACS connector now licenses to competing networks, shifting toward revenue diversification.
- Others:Real estate investment trusts, fuel retailers, and convenience store operators install charging as amenity or traffic driver. Shell and BP integrate charging into petroleum station conversions.
Third-Party Providers operate the majority of public charging ports. Utility Companies are expanding fastest where regulatory frameworks permit rate-basing of infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting charging hardware production toward jurisdictions with streamlined certification pathways and subsidized manufacturing incentives, compressing cost-of-compliance gaps between established and emerging supply bases.
United States
Fleet depot electrification and highway corridor mandates from EPA tailpipe rules drive infrastructure deployment across California, Texas, and the Midwest. NHTSA Corporate Average Fuel Economy enforcement treats charging accessibility as a compliance prerequisite for automaker credits. Southern California Edison and Pacific Gas & Electric anchor megawatt-scale installations in Los Angeles and the San Francisco Bay Area.
Germany
Industrial automotive electrification and heavy-duty freight corridor requirements concentrate demand in Bavaria and North Rhine-Westphalia. EU Green Deal transport decarbonization benchmarks mandate ultra-fast charging density along Rhine-Alpine and Scandinavian-Mediterranean freight routes. Siemens and Ionity operate high-power DC hubs across the A3 and A9 autobahn corridors.
China
State Grid and private operators deploy ultra-fast charging hubs at scale across eastern provinces. MIIT and SAMR enforce GB/T connector standards and grid interconnection protocols that shape product design for domestic and export markets. Yangtze River Delta cities including Shanghai and Suzhou host the densest charging cluster concentrations globally.
India
Domestic manufacturing incentives under the PLI scheme for auto components create localized supply chains for AC and DC charging hardware. Central Electricity Authority protocols and state-level EV policies in Maharashtra and Gujarat accelerate deployment timelines. Delhi-NCR and Bengaluru anchor pilot corridor installations along Delhi-Mumbai and Delhi-Chennai freight routes.
United Kingdom
Corporate fleet transition programs and workplace charging mandates concentrate procurement in London and the Southeast. Office of Zero Emission Vehicles grants and local authority funding streams subsidize public infrastructure in underserved postal codes. Midlands manufacturing clusters around Birmingham and Coventry supply hardware components to European integrators.
EV Charging Point Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hardware-integrated software platforms commanding premium positioning in fleet depot applications. The vendor base organizes into three tiers: integrated energy management specialists, pure-play charging hardware fabricators, and utility-captive infrastructure operators. Consolidation pressure concentrates among mid-scale DC fast charging suppliers facing silicon carbide component sourcing constraints. Strategic moves center on M&A for power electronics engineering talent and strategic partnerships with fleet operators for guaranteed offtake volumes.
Among North American charging network operators, ChargePoint and Tesla occupy positions as archetype anchors for software-integrated hardware platforms and proprietary connector ecosystem strategies respectively. Chinese infrastructure specialists Star Charge and TELD New Energy exemplify scale-driven deployment models serving state-backed grid integration mandates. These named entities represent divergent competitive vectors rather than exhaustive market coverage.
| Leading Market Players |
|---|
| ChargePoint |
| ABB |
| Tesla |
| EVBox |
| Wallbox |
| Eaton |
| Delta Electronics |
| Star Charge |
| TELD New Energy |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal transport decarbonization benchmarks gate qualified supply for silicon carbide power modules and liquid-cooled cable assemblies, restricting premium-tier pricing access to vendors with certified grid-interconnection protocols and verified carbon-accounting documentation.
Pricing Analysis
Distributor margins on DC fast charging hardware compress as direct-to-fleet contracting expands, with project-based pricing for megawatt-scale depot installations displacing per-unit transactional models. Price differentiation hinges on UL certification tier and after-sales service bundling, with California Title 24 compliance commanding premiums over baseline hardware. Cost compression in Level 2 AC units intensifies because of commodity copper price volatility and Asian contract manufacturer competition. Fleet operators exhibit lowest price sensitivity due to operational expenditure accounting preferences, while residential buyers face highest sensitivity to upfront capital outlay.
Supply Chain Analysis
India's PLI scheme for auto components and China's MIIT domestic-content mandates reshape sourcing for power electronics and enclosure fabrication, pressuring non-compliant vendors toward joint-venture structures. Manufacturing concentrates in China, Germany, and Mexico for final assembly, with silicon carbide wafers drawing from Japan and the United States. Rare earth magnet supply for cooling system pumps rests on concentrated mining geographies, creating single-source vulnerability for liquid-cooled DC systems. Distribution runs through utility procurement channels, third-party network operators, and automotive OEM captive systems in roughly equal downstream volume splits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between India's subsidized manufacturing incentives and Germany's stringent grid-interconnection requirements creates cost and certification differentials that reward dual-footprint strategies.
For Market Incumbents: Extend silicon carbide inverter design capabilities through targeted acquisition of specialized thermal management engineering firms, defending against emerging entrants with pure-play hardware fabricator cost structures. Deepen backward integration into power semiconductor sourcing to offset commodity volatility exposure. Prioritize certification investment for GB/T, CCS, and NACS multi-standard testing regimes to maintain channel control across regulatory jurisdictions.
For New Entrants and Emerging Players: Bidirectional vehicle-to-grid integration protocols offer technology-first wedge positioning against incumbent hardware-centric vendors, with fleet management software presenting the most penetrable segment for unbundled energy-management solutions. Target India's PLI-subsidized manufacturing corridor for cost-competitive AC and mid-power DC hardware production. Pursue strategic partnership routes with state-backed utilities seeking localized grid-edge infrastructure deployment.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale DC fast charging suppliers facing silicon carbide component sourcing constraints and engineering talent scarcity. Long-term viability over the coming decade favors integrated energy management specialists with software-anchored platform architecture over pure-play hardware fabricators. Monitor EPA enforcement mechanism adjustments and EU Green Deal corridor funding disbursement timelines as inflection indicators for capital deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Power Electronics Transition | Enables 350 kW+ DC systems with reduced thermal losses for ABB and Siemens highway corridor deployments. |
| Fleet Depot Charging Partnership | Secures guaranteed offtake volumes from Amazon and UPS through megawatt-scale installation contracts with uptime SLAs. |
| Multi-Standard Certification Investment | Unlocks parallel market access across GB/T, CCS, CHAdeMO, and NACS connector variants for Chinese export manufacturers. |
| Vehicle-to-Grid Protocol Development | Creates frequency regulation revenue streams for fleet operators using ChargePoint software-integrated hardware platforms. |
| Utility Rate-Basing Expansion | Permits Southern California Edison and State Grid to deploy charging as regulated grid edge infrastructure with guaranteed returns. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with fleet operations directors, utility planning officers, charging network procurement leads, and power electronics engineering heads alongside secondary validation from NHTSA rulemaking dockets, EPA enforcement guidance documents, EU Green Deal transport decarbonization benchmarks, and MIIT connector standard filings. Bottom-up unit deployment estimates triangulate against top-down infrastructure investment flow analysis.
Granularity-level modeling segments by charging type, application, installation configuration, and infrastructure provider ownership model, with power rating tiers and regional regulatory clusters as cross-cutting analytical dimensions. CAGRs derive from installed base expansion curves, vehicle electrification mandate compliance timelines, and utility interconnection queue progression across the projection horizon. Forecast inputs incorporate silicon carbide adoption rates in power conversion modules and fleet operator contracting pattern shifts toward equipment-as-a-service arrangements.
The model holds under stable regulatory enforcement and commodity price assumptions; deviation in transformer and switchgear availability, copper price volatility, or grid interconnection approval timelines would shift deployment velocity and vendor margin structures. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle Public Charging Pile Market
Electric Vehicle Charging
Solar-Based Electronic Vehicle Market
Electric Vehicle Charging
EV Charging Networks Market
Electric Vehicle Charging
Global EV Charger Market
Electric Vehicle Charging
EV Charging Software Market
Electric Vehicle Charging
Pantograph Charger Market
Electric Vehicle Charging
Home Charging Piles Market
Electric Vehicle Charging
Bi Directional Electric Vehicle Charger Market
Electric Vehicle Charging
North America Electric Vehicle Charging Station Market
Electric Vehicle Charging
Japan Electric Vehicle Charging Station Market
Electric Vehicle Charging
Oman EV Charging Station Market
Electric Vehicle Charging
Two Wheel Electric Vehicle Charger Market
Electric Vehicle Charging
Electric Vehicle Charger Operations and Maintenance Services Market
Electric Vehicle Charging
PV BESS EV Charging Systems Market
Electric Vehicle Charging
Public EV Charging Pile Market
Electric Vehicle Charging
Airport Electric Vehicle Charging Station Market