
 Home Charging Piles Market | 2026-2036
Home Charging Piles Market Size, Share, and Industry Trends Forecast 2026-2036
Home Charging Piles Market Insights
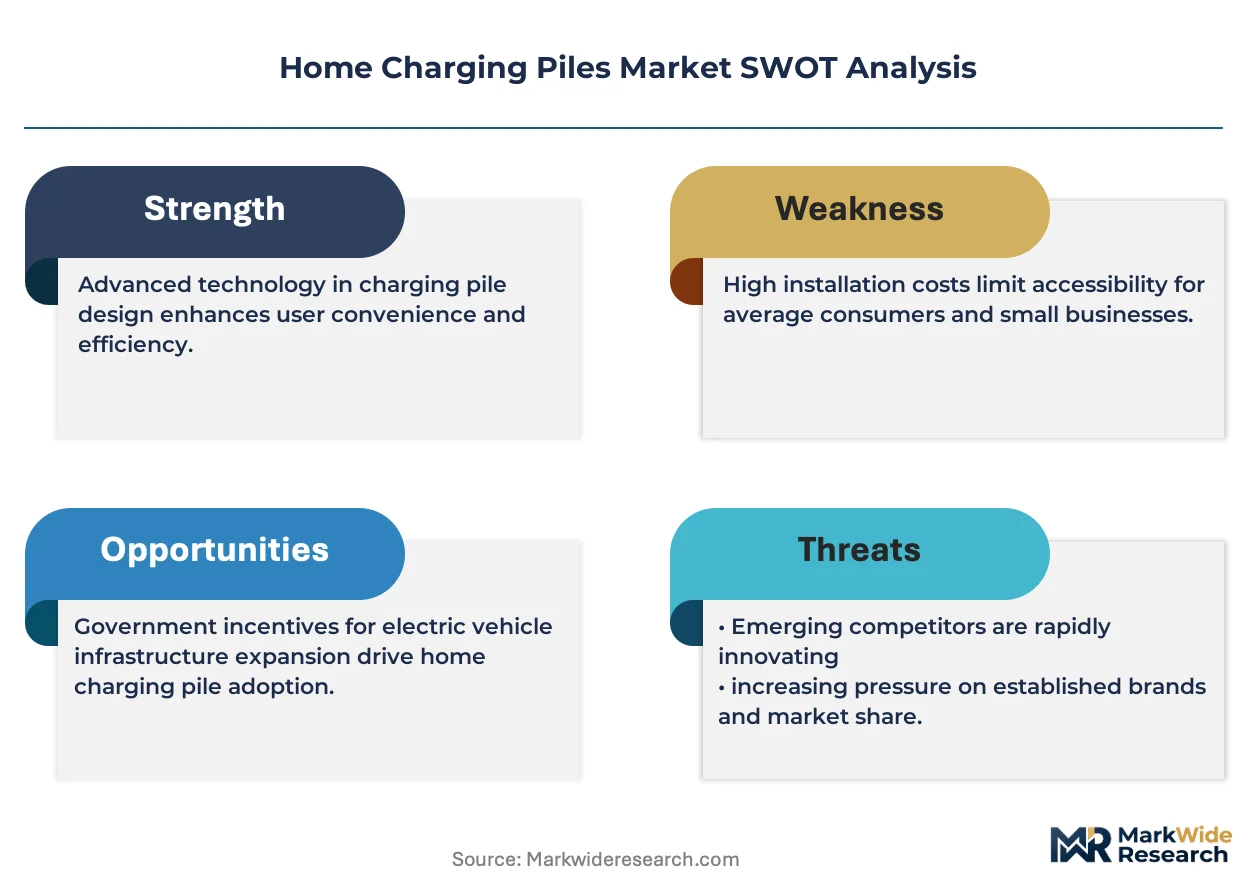
Electrician certification bottlenecks in major metros is reorganizing installation timelines and pushing manufacturers toward plug-and-play designs. Tesla leverages its proprietary connector ecosystem and supercharger brand recognition to sustain direct-to-consumer channel control. ChargePoint anchors its position through software-integrated hardware that competes on network reliability rather than hardware margins alone. ABB specializes in high-amperage residential units that dominate European three-phase home installations.
Home charging piles are permanently installed electrical supply equipment that deliver alternating current from residential panels to electric vehicles, typically operating at 240 volts and 32 to 80 amperes for Level 2 configurations, with smart variants adding load-balancing algorithms to prevent panel overload. Their primary purpose is to provide safe, convenient overnight replenishment without reliance on public infrastructure. Level 2 chargers occupy the core value pool due to their optimal balance of installation cost and charging speed for daily commuter cycles. Smart chargers with Wi-Fi connectivity are the fastest-growing product configuration as time-of-use rate optimization and solar integration become standard consumer expectations. Wireless chargers remain nascent, constrained by efficiency losses and premium pricing that limits penetration to luxury residential segments.
The US National Electrical Code through NFPA standards governs amperage ratings and ground-fault protection, while the EU F-Gas Regulation and CE marking framework shape cable insulation and enclosure material specifications for European installations. China's GB standards and grid access rules administered by the country's national energy regulator mandate communication protocols that enable demand-response participation. Stakeholders must monitor evolving building code adoption timelines and utility interconnection standards that determine whether charger hardware qualifies for rebate programs and permitted installation categories.
Market Dynamics
Electrician certification bottlenecks in major metros are compressing installation capacity and forcing manufacturers toward plug-and-play designs that reduce field wiring complexity. This structural constraint is redistributing margin from installation services toward hardware-integrated software platforms.
Growth Catalysts
- EU Green Deal building mandates:New construction across Germany, France, and the Netherlands must include charging-ready infrastructure, creating baseline demand before vehicle purchase.
- Utility rebate programs:State-level incentives in California, Texas, and New York offset hardware and installation costs for residential customers.
- Load-balancing algorithms:Smart chargers with dynamic amperage adjustment prevent panel upgrades, expanding addressable market to older housing stock.
Market Restraints
- Copper and semiconductor input volatility:Cable assemblies and power electronics face price swings that compress hardware margins.
- Installation labor concentration:Licensed electricians cluster in coastal metros, leaving interior regions with month-long project queues.
- Wireless efficiency losses:Inductive charging systems sacrifice 10-15% energy transfer, limiting penetration despite convenience appeal.
Strategic Opportunities
- Multi-unit dwelling penetration:Apartment and condominium complexes in Spain and Italy remain underserved by single-family-focused product lines.
- Solar-storage-charger convergence:DC-coupled systems that bypass grid interconnection are gaining traction among off-grid and net-zero residential builders.
- Direct-to-consumer channel expansion:E-commerce platforms and big-box retail partnerships bypass traditional electrical distributor markups.
Industry Challenges
- NFPA 70 NEC amendment cycles:Evolving ground-fault and disconnect requirements force hardware redesigns mid-product-lifecycle.
- Interoperability certification backlog:UL and CSA testing queues extend go-to-market timelines for new smart connectivity features.
- Grid interconnection standards fragmentation:Utility-specific communication protocols require regional firmware variants that complicate inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Charging Piles Market |
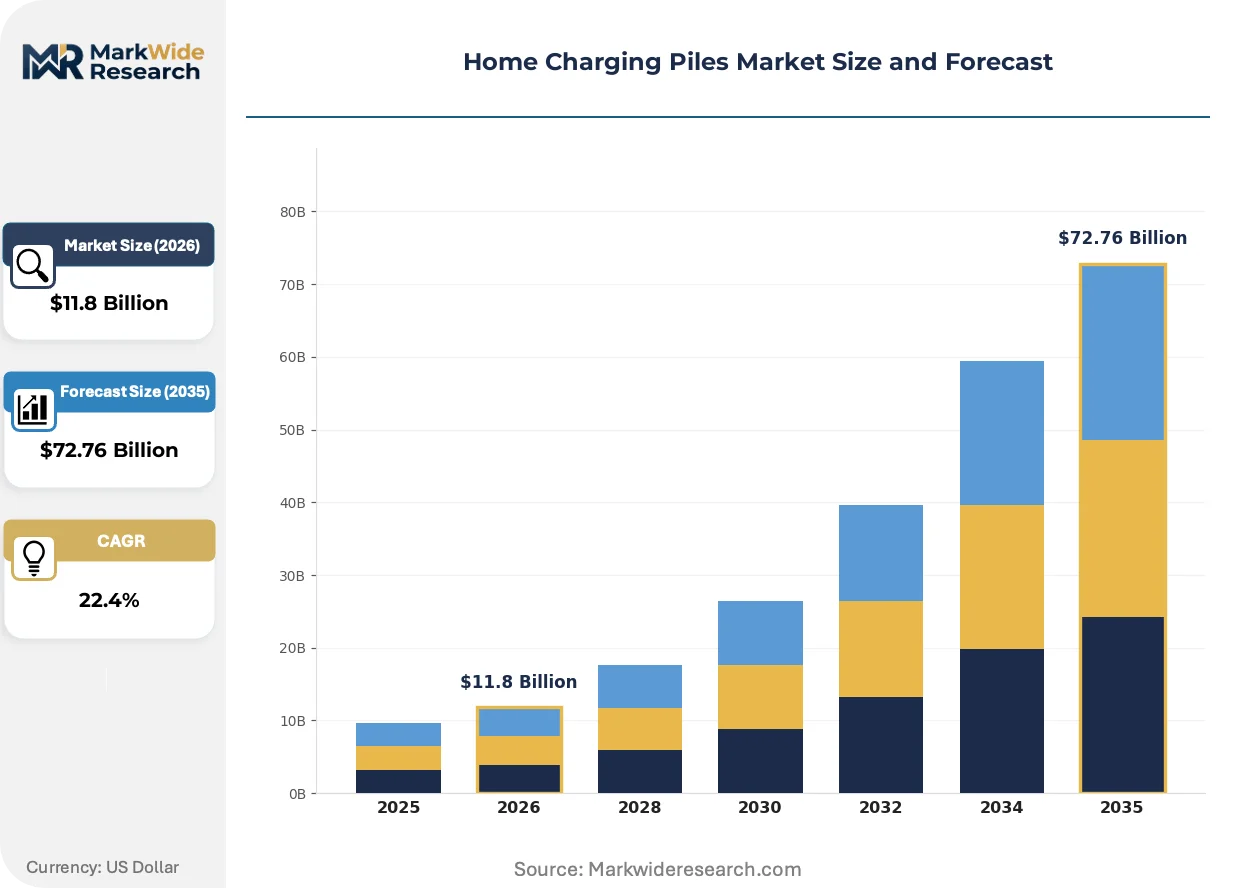
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $72.76 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Level 1 Chargers, Level 2 Chargers, Smart Chargers, Wireless Chargers Installation Type: Indoor, Outdoor, Wall-Mounted, Portable Connectivity: Wi-Fi, Bluetooth, Ethernet, Cellular End User: Residential Users, Multi-Family Dwellings, Homeowners Associations, Leasing Companies |
| Companies Covered | Tesla, ChargePoint, ABB, EVBox, Wallbox Chargers, StarCharge, Delta Electronics, Webasto, Leviton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Charging Piles Market Trends and Innovations
Modular power electronics architectures are separating control logic from power delivery, enabling faster iteration cycles and reducing recertification burdens. This decomposition is reshaping how manufacturers approach hardware-software integration and field upgradability.
Bi-directional charging capability is decomposing the boundary between vehicle and home energy systems. Early adopters with solar-plus-storage configurations in Germany and California are piloting vehicle-to-home applications. This capability is compressing the distinction between automotive and stationary battery markets, forcing charger manufacturers to certify against automotive-grade standards.
China's GB/T communication protocol mandates are tightening data localization requirements for connected chargers. The State Grid Corporation now requires real-time telemetry for demand-response aggregation. Domestic manufacturers with in-server infrastructure compliance are securing preferential grid access approvals.
Subscription-based software tiers are unbundling from hardware sales in North American markets. Buyers increasingly expect load-balancing, solar optimization, and utility rate arbitrage as ongoing services rather than one-time features. This shift concentrates recurring revenue with platform operators and erodes pure-hardware vendor margins.
Home Charging Piles Market Segmentation
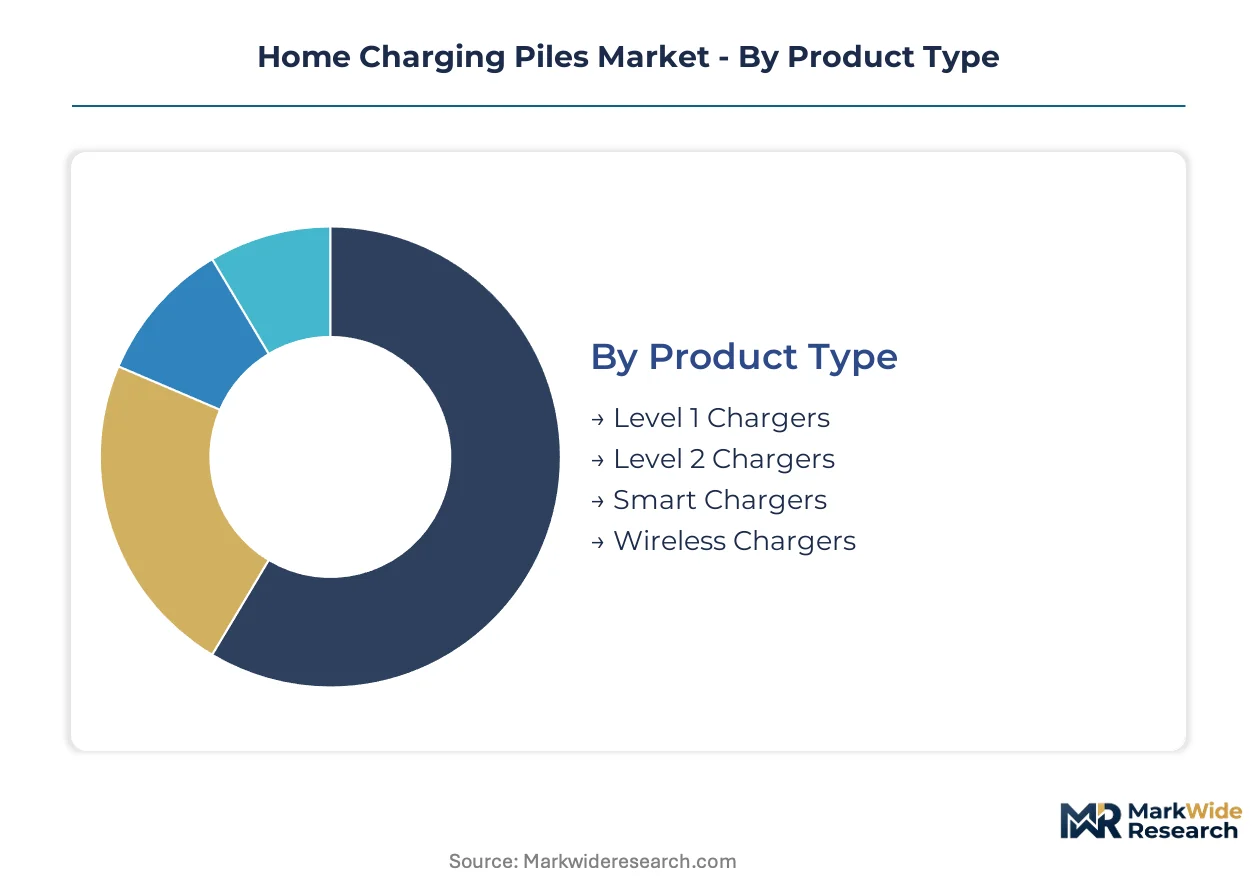
Segmentation in home charging piles determines installation complexity, software integration depth, and channel economics. Product configuration drives whether units flow through electrical distributors, direct-to-consumer platforms, or utility rebate programs.
Product Type:
Level 2 and smart chargers dominate electrical distributor and utility partnership channels, while Level 1 and wireless variants concentrate in e-commerce and specialty retail.
- Level 2 Chargers:These units deliver 240-volt alternating current at 32 to 80 amperes through hardwired or plug-in configurations. Demand concentrates in suburban single-family homes across Germany, China, and the United States where overnight replenishment cycles match daily commuter patterns. The EU Green Deal building mandates and US utility rebate programs accelerate penetration into new construction and retrofit markets.
- Smart Chargers:Wi-Fi-enabled units with load-balancing algorithms and time-of-use optimization form the fastest-expanding product tier. California and Texas homeowners with solar-plus-storage configurations drive adoption as these systems prevent panel upgrades and maximize self-consumption economics.
- Level 1 Chargers:Standard 120-volt portable units serve plug-in hybrid owners and rental property segments with minimal installation requirements.
- Wireless Chargers:Inductive systems with 10-15% efficiency losses remain confined to luxury residential segments in premium metros due to cost barriers.
By volume, Level 2 chargers lead. By growth pace, smart chargers are expanding most quickly.
Installation Type:
Cost tier stratification separates professional-installed hardwired units from consumer-deployed alternatives, reshaping margin distribution across channels.
- Wall-Mounted:Permanent bracket installations dominate Level 2 and smart charger deployments, requiring licensed electrician labor that concentrates margin in coastal metros. Germany's three-phase residential infrastructure and US suburban garages represent the core addressable base.
- Indoor:Garage and basement placements protect electronics from weather exposure and simplify NFPA 70 NEC compliance for ground-fault protection.
- Outdoor:Weather-rated enclosures with NEMA 3R or 4X ratings serve driveway and carport installations in climates with freeze-thaw cycles.
- Portable:Detachable units with NEMA 14-50 plugs bypass permanent installation, appealing to renters and multi-dwelling residents in Spain and Italy.
By revenue concentration, wall-mounted units dominate. By addressable market expansion, portable configurations are gaining share fastest.
Connectivity:
Application maturity determines whether connectivity serves basic monitoring or enables grid-interactive revenue streams.
- Wi-Fi:Dominant protocol for residential smart chargers, enabling real-time rate optimization and solar integration through cloud-based platforms. China's GB/T mandates now require State Grid Corporation telemetry compliance for demand-response aggregation.
- Cellular:Backup connectivity for rural installations outside reliable broadband coverage, particularly in interior US regions with sparse fiber deployment.
- Bluetooth:Local-only pairing for basic setup and diagnostics without persistent cloud dependency.
- Ethernet:Hardwired reliability for high-availability installations in net-zero residential builds with integrated energy management systems.
By installed base, Wi-Fi leads. By regulatory mandate penetration, cellular is climbing the fastest.
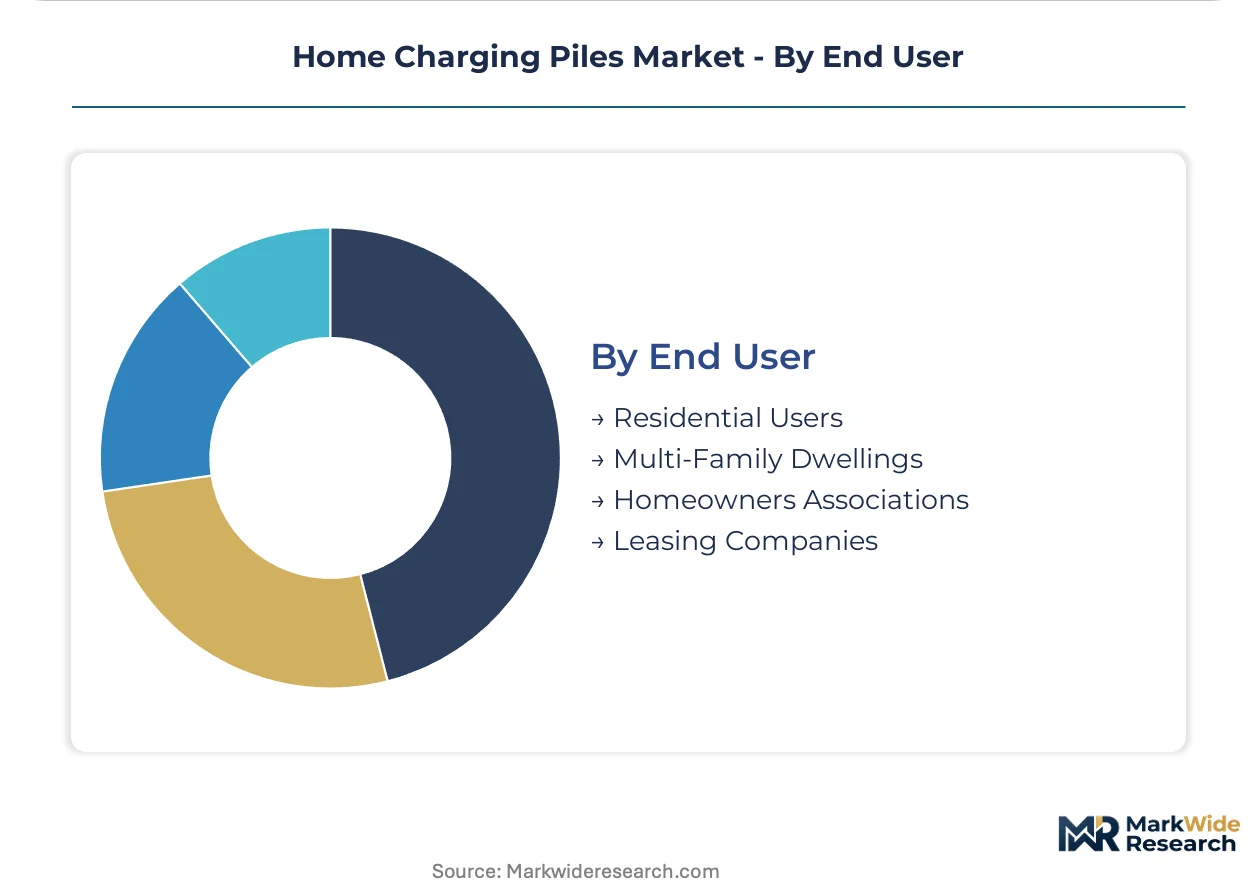
End User:
Customer type dictates whether procurement flows through homeowner direct purchase, HOA collective bargaining, or leasing company fleet standardization.
- Residential Users:Single-family homeowners in Germany, China, and the United States represent the core volume pool, with purchase decisions driven by utility rebate programs and EV manufacturer bundling. Load-balancing algorithms expand addressability to older housing stock without panel upgrades.
- Multi-Family Dwellings:Apartment and condominium complexes in Spain and Italy remain structurally underserved, creating whitespace for shared infrastructure models and sub-metering solutions.
- Homeowners Associations:Collective procurement entities in US master-planned communities negotiate bulk pricing and standardized installation specifications.
- Leasing Companies:Fleet operators standardizing charger specifications across dispersed residential rental portfolios to minimize maintenance complexity.
By current volume, residential users lead. By structural opportunity, multi-family dwellings show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German households favor three-phase hardwired installations for overnight replenishment, while US consumers gravitate toward plug-and-play NEMA 14-50 configurations that bypass electrician dependency. Chinese buyers prioritize State Grid Corporation telemetry compliance for demand-response participation.
United States
Suburban single-family homes in California and Texas drive Level 2 charger deployment through utility rebate programs administered by PG&E and ERCOT-member utilities. The National Electrical Code through NFPA standards governs ground-fault protection and amperage ratings, creating compliance hurdles for new market entrants. Installation labor concentrates in coastal metros, leaving interior regions with extended project queues.
Germany
Residential three-phase infrastructure supports high-amperage units for overnight charging cycles in suburban Munich and Stuttgart households. The EU Green Deal building mandates require charging-ready infrastructure in new construction, creating baseline demand before vehicle purchase. Bavaria and Baden-Württemberg industrial clusters supply power electronics components to domestic charger manufacturers.
China
State Grid Corporation telemetry mandates under GB standards require real-time data localization for demand-response aggregation. Yangtze River Delta and Pearl River Delta metropolitan areas concentrate smart charger manufacturing and software platform development. Domestic manufacturers with in-server infrastructure compliance secure preferential grid access approvals.
France
Île-de-France apartment complexes drive demand for shared infrastructure models and sub-metering solutions in multi-unit dwellings. National building codes aligned with EU Green Deal timelines mandate pre-wiring in new residential construction. Auvergne-Rhône-Alpes hosts automotive supplier clusters influencing charger-vehicle integration standards.
Netherlands
Randstad urban density favors compact wall-mounted units in narrow townhouse garages and carport installations. Utility-led rebate programs accelerate retrofit penetration in Amsterdam and Rotterdam housing stock. Eindhoven Region technology corridors supply semiconductor components for power management systems.
Home Charging Piles Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that competes on regional certification speed and installation simplicity. The upper tier controls proprietary connector ecosystems and software-integrated hardware platforms. Strategic archetypes include automotive-captive suppliers, electrical infrastructure incumbents, and pure-play charging network operators. Competitive moves concentrate on plug-and-play design simplification and direct-to-consumer channel expansion.
Within the integrated platform tier, Tesla and ChargePoint exemplify contrasting approaches to ecosystem control. Tesla leverages proprietary connector standards and supercharger brand recognition to sustain direct sales channel dominance. ChargePoint anchors network reliability through software-integrated hardware that competes beyond hardware margins alone. Among electrical infrastructure specialists, ABB occupies a position emphasizing high-amperage residential units for European three-phase installations.
| Leading Market Players |
|---|
| Tesla |
| ChargePoint |
| ABB |
| EVBox |
| Wallbox Chargers |
| StarCharge |
| Delta Electronics |
| Webasto |
| Leviton |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between German power electronics manufacturers and copper cable suppliers lock in both raw material access and unit cost visibility for residential charger production. These contracts insulate ABB and Wallbox from spot market volatility while compressing margin for smaller competitors forced into quarterly procurement cycles.
Pricing Analysis
Project-based contracting dominates residential installations, with electricians bundling hardware markup into fixed-scope proposals. Price differentiation rests on UL certification tier and after-sales software subscription bundling. Pricing pressure stems from semiconductor input volatility, which squeezes hardware margins faster than SaaS tiers can offset. Fleet leasing companies show highest price sensitivity, while net-zero residential builders prioritize performance over unit cost.
Supply Chain Analysis
Strategic stockpiling of power semiconductors and copper conductors characterizes Tier 1 manufacturer inventory strategy ahead of NEC amendment cycles. Manufacturing concentrates in China, Germany, and the United States. Raw material dependencies center on refined copper, silicon carbide wafers, and flame-retardant cable insulation. Single-source vulnerability in silicon carbide substrates from Wolfspeed and STMicroelectronics poses concentration risk. Distribution runs through electrical distributors and direct-to-consumer platforms in parallel channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software subscription attach rates for load-balancing and solar optimization are expanding faster than hardware unit economics, transforming charger vendors into recurring-revenue platforms. This service layer now commands higher valuation multiples than pure equipment sales.
For Market Incumbents: Fortify certification pipelines against UL and CSA testing backlogs that delay smart connectivity launches. Secure backward integration into power electronics assembly in Yangtze River Delta clusters to offset semiconductor margin compression. Channel control through utility rebate program pre-qualification remains critical for defending position against direct-to-consumer entrants. For New Entrants and Emerging Players: Differentiate on plug-and-play portability for multi-unit dwellings in Spain and Italy, where shared infrastructure models remain structurally underserved. Target condominium HOA collective procurement with sub-metering hardware bundled into standardized installation scopes. E-commerce platform partnerships bypass electrical distributor markups and accelerate customer acquisition. For Investors and Strategic Acquirers: Capital is best deployed toward software-integrated hardware platforms with demonstrated utility telemetry compliance and recurring revenue traction. Long-term viability favors vendors with in-server infrastructure meeting State Grid Corporation data localization mandates. Watch for inflection when bi-directional charging certification against automotive-grade standards becomes mandatory for grid interconnection approval.| Strategic Initiative | Industry Significance |
|---|---|
| Software Platform Integration | Load-balancing algorithms from Tesla and ChargePoint prevent panel upgrades and expand addressable housing stock. |
| Bi-directional Charging Certification | Vehicle-to-home capability requires automotive-grade standards that compress charger-battery market boundaries. |
| Direct-to-Consumer Channel Expansion | Big-box retail partnerships bypass electrical distributor markups and accelerate suburban single-family penetration. |
| Utility Rebate Program Pre-qualification | PG&E and ERCOT incentive alignment determines hardware eligibility and installation volume allocation. |
| Power Electronics Backward Integration | In-house silicon carbide assembly reduces exposure to Wolfspeed substrate supply constraints. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with charging infrastructure manufacturers, licensed electrical contractors, utility demand-response program managers, and residential solar installers; and secondary validation through NEC amendment filings, State Grid Corporation telemetry specifications, EU Green Deal implementation timelines, and customs data on power electronics trade flows. Bottom-up unit shipment estimates triangulated against top-down utility rebate redemption databases.
Across the projection horizon, the analytical framework modeled segmentation by charger intelligence tier, installation complexity class, connectivity protocol, and end-user procurement channel. CAGRs derived from utility interconnection queue growth rates and building code adoption timelines. Forecast inputs incorporated copper price futures curves and semiconductor lead time indices without year-specific anchoring.
The analysis sits within stated boundaries; outcomes outside sustained EV sales growth, stable grid interconnection standards, and intact utility rebate funding would require recalibration. Forecasts reflect documented assumptions on housing stock electrification readiness and electrician labor availability. Revision becomes warranted when NFPA 70 amendment cycles or GB/T protocol mandates cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle Charging Adapter Market
Electric Vehicle Charging
EV DC Fast Charger Market
Electric Vehicle Charging
Australia Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
United States Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
Europe EV Charging Stations Market
Electric Vehicle Charging
EV Charging Networks Market
Electric Vehicle Charging
AC Electric Vehicle Charging Station Market
Electric Vehicle Charging
Germany Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Home Charger Market
Electric Vehicle Charging
Europe Electric Vehicle Charging Cable Market
Electric Vehicle Charging
Global Electric Vehicle Charging As a Service Market
Electric Vehicle Charging
Electric Vehicle Charging Products Market
Electric Vehicle Charging
Bidirectional Charging Units Market
Electric Vehicle Charging
Electric Vehicle Coin Charging Station Market
Electric Vehicle Charging
Home EV Chargers Market
Electric Vehicle Charging
Copper in Electric Vehicle Market