
 Asia-Pacific Smart Grid Network Market | 2026-2036
Asia-Pacific Smart Grid Network Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Smart Grid Network Market Outlook
Aftermarket service revenue is narrowing toward software-defined grid management platforms as hardware commoditizes across the Asia-Pacific. ABB Ltd leverages its digital substation portfolio to capture recurring maintenance contracts in Southeast Asian markets. Siemens AG anchors its position through in-house production of industrial communication protocols tailored to utility specifications. Schneider Electric SE differentiates by integrating building energy management with utility-scale demand response systems.
A smart grid network constitutes an electricity distribution architecture incorporating two-way digital communication, automated control systems, and real-time sensing across transmission and distribution layers, typically operating at latency thresholds below 100 milliseconds for protection relay coordination. Its primary commercial purpose centers on balancing intermittent renewable generation against fluctuating load profiles while minimizing technical losses. Advanced Metering Infrastructure commands the largest installed base among technology segments, though Distributed Energy Resources integration software captures disproportionate margin pools as penetration of rooftop solar and battery storage accelerates. Within component categories, Communication Networks face the steepest upgrade cycle as utilities migrate from narrowband power-line carrier to LTE-M and fiber-optic backhaul.
China's MIIT enforces GB standards for grid-interactive inverter communications, while India's CEA mandates smart metering rollout timelines that directly shape procurement schedules for state distribution companies. Japan's METI directs R&D subsidies toward grid-forming inverter technologies that stabilize weak network areas. Stakeholders must weigh standardization commitments against the fragmentation risk of country-specific certification regimes as they scale platform deployments across the region.
Market Dynamics
Utilities across the Asia-Pacific are modernizing distribution networks to accommodate rooftop solar proliferation, with grid congestion in China's eastern coastal provinces forcing capital deployment toward two-way digital communication systems and real-time sensing infrastructure.
Growth Catalysts
- China's dual carbon goals:Beijing's net-zero targets mandate renewable integration at scale, compelling state grid operators to accelerate smart meter deployment and automated control system procurement.
- India's PLI scheme for advanced metering:The production-linked incentive framework directly shapes procurement schedules for state distribution companies, creating predictable demand pipelines for AMI hardware and software.
- LTE-M and fiber-optic backhaul:Communication network upgrades across Southeast Asian utilities enable sub-100 millisecond latency thresholds essential for protection relay coordination in high-renewable penetration zones.
Market Restraints
- Semiconductor input volatility:Power management integrated circuits and specialized analog chips for grid sensors face supply concentration risk from Taiwan-based foundries, compressing hardware margins.
- Country-specific certification regimes:Fragmentation between China's GB standards for grid-interactive inverters and India's CEA smart metering mandates forces redundant testing cycles for platform deployments.
- Narrowband power-line carrier legacy:Existing AMI infrastructure in older Japanese and Australian installations creates technical debt that slows full-stack communication network replacement timelines.
Strategic Opportunities
- Grid-forming inverter R&D subsidies:Japan's METI directs public funding toward technologies that stabilize weak network areas, opening procurement channels for advanced power electronics in rural Hokkaido and Kyushu.
- Building energy management convergence:Integration of utility-scale demand response with commercial HVAC and industrial load control creates white space for platform vendors in Singapore and South Korea's dense urban cores.
- Vietnam and Philippines distribution modernization:Underpenetrated state utility sectors in these markets present first-mover advantages for AMI and DER integration software as rural electrification expands.
Industry Challenges
- Cybersecurity certification timelines:Multi-jurisdictional security standards for critical infrastructure delay product launches as vendors navigate separate approval pathways in China, India, and Australia.
- Legacy SCADA integration complexity:Proprietary protocols in existing Japanese and South Korean utility control systems fragment vendor interoperability and extend deployment cycles.
- Grid data science talent scarcity:Shortages of power systems engineers with machine learning expertise constrain software-defined grid management platform development across the region.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Smart Grid Network Market |
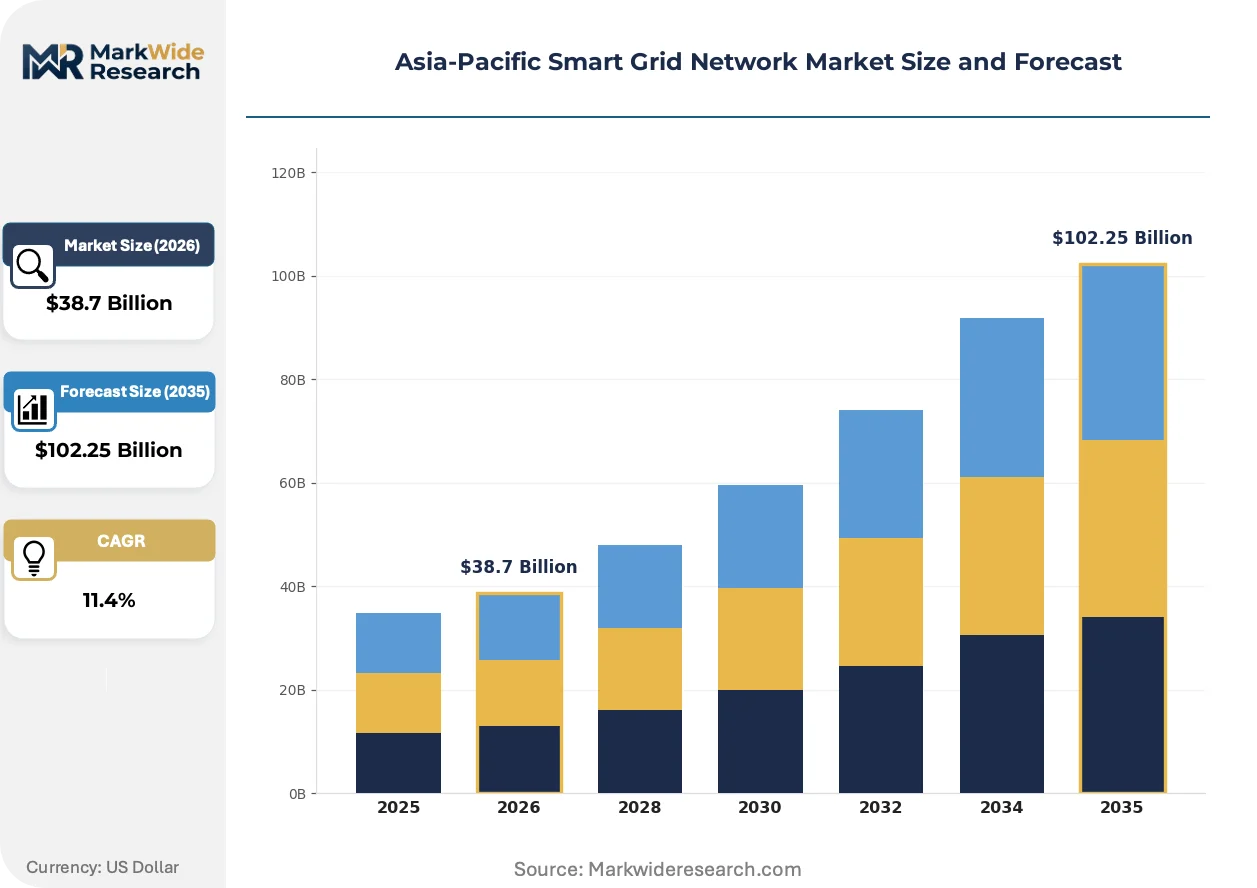
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Advanced Metering Infrastructure, Distributed Energy Resources, Demand Response, SCADA Component: Smart Meters, Communication Networks, Control Systems, Software Solutions End User: Utilities, Industrial Facilities, Commercial Buildings, Residential Consumers Installation Type: Onshore, Offsite, Retrofit, New Construction |
| Companies Covered | ABB Ltd, Siemens AG, Schneider Electric SE, Cisco Systems Inc., General Electric Company, Eaton Corporation, IBM Corporation, Honeywell International Inc., Itron Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Smart Grid Network Market Strategic Shifts
Digital substation architectures and software-defined grid management platforms are compressing hardware commoditization cycles while creating recurring revenue pools for technology vendors serving Asia-Pacific utilities.
Communication networks for smart grid applications are migrating from narrowband power-line carrier systems to LTE-M cellular and fiber-optic backhaul infrastructure. State distribution companies in India and Southeast Asian markets are prioritizing this transition to achieve latency thresholds below 100 milliseconds. The technology is migrating from legacy proprietary protocols toward standardized IP-based architectures that enable third-party application development and reduce vendor lock-in.
China's MIIT enforcement of GB standards for grid-interactive inverter communications is reshaping equipment procurement specifications across the domestic market. Manufacturers must now certify bidirectional communication capabilities for rooftop solar and battery storage systems before grid connection approval. The regulation most acutely affects inverter suppliers serving Shandong and Jiangsu provinces, where renewable penetration rates exceed network hosting capacity.
Aftermarket service contracts are unbundling from hardware sales as utilities in Australia and South Korea seek performance-based maintenance agreements for AMI and DER management platforms. Traditional equipment vendors are responding by establishing regional software support centers in Singapore and Bangalore. This shift is most visible among commercial and industrial energy users in Australia's National Electricity Market, where interval metering data drives active demand response participation.
Asia-Pacific Smart Grid Network Market Segmentation
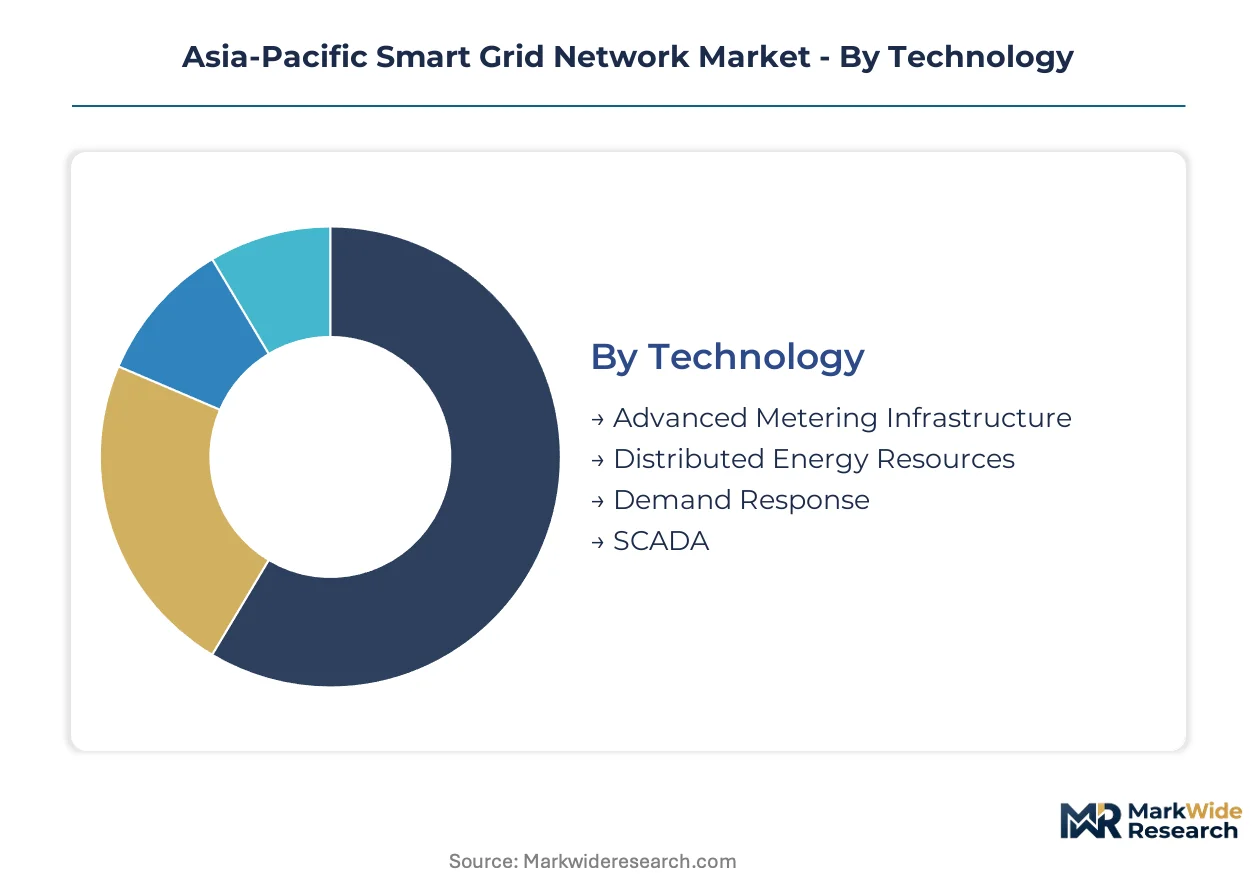
Segmentation reveals how smart grid capital flows diverge across technology maturity curves and customer sophistication levels in Asia-Pacific. Procurement patterns differ sharply between China's state grid operators and India's fragmented distribution companies, while component upgrade cycles vary by existing infrastructure vintage.
Technology:
After-sales-service intensity varies dramatically across technology segments, with software platforms demanding continuous subscription support while hardware installations require periodic calibration visits.
- Advanced Metering Infrastructure:Two-way communication endpoints and data management systems form the installed base foundation. China's eastern coastal provinces drive replacement demand as Shandong and Jiangsu exceed hosting capacity for additional rooftop solar without granular load visibility.
- Distributed Energy Resources:Aggregation software and inverter control systems manage behind-the-meter generation and storage. India's PLI scheme accelerates procurement timelines for DER management platforms as state distribution companies modernize rural networks.
- Demand Response:Load curtailment orchestration for industrial and commercial customers.
- SCADA:Supervisory control systems for transmission-level monitoring and automation.
Advanced Metering Infrastructure holds the largest share; momentum sits with Distributed Energy Resources.
Component:
Cost tier stratification separates premium fiber-optic deployments from economy-grade cellular alternatives across Southeast Asian utilities.
- Smart Meters:Interval recording devices with embedded communication modules. India's CEA mandates drive volume concentration in Maharashtra and Gujarat state distribution companies.
- Communication Networks:LTE-M cellular and fiber-optic backhaul infrastructure replacing narrowband power-line carrier systems. Japan's legacy AMI technical debt slows full replacement timelines in older Tokyo and Osaka installations.
- Control Systems:Protection relays and automated switching equipment for fault isolation.
- Software Solutions:Grid analytics and asset management platforms delivered via cloud subscription.
Communication Networks command the steepest upgrade cycle; Software Solutions expand most quickly.
End User:
Application requirements diverge between centralized utility procurement and distributed commercial-industrial deployment.
- Utilities:State grid operators and distribution companies as primary capital deployers. China's dual carbon goals mandate renewable integration at scale across State Grid and China Southern Power Grid territories.
- Industrial Facilities:Steel, cement, and chemical plants with behind-the-meter generation and process load flexibility. South Korea's KEPCO demand response programs target heavy industrial clusters in Ulsan and Yeosu.
- Commercial Buildings:Office towers and retail complexes with HVAC-integrated load control.
- Residential Consumers:Single-family and multi-unit dwellings with rooftop solar and battery storage.
Utilities dominate procurement volume; Industrial Facilities deliver the highest margin per endpoint.
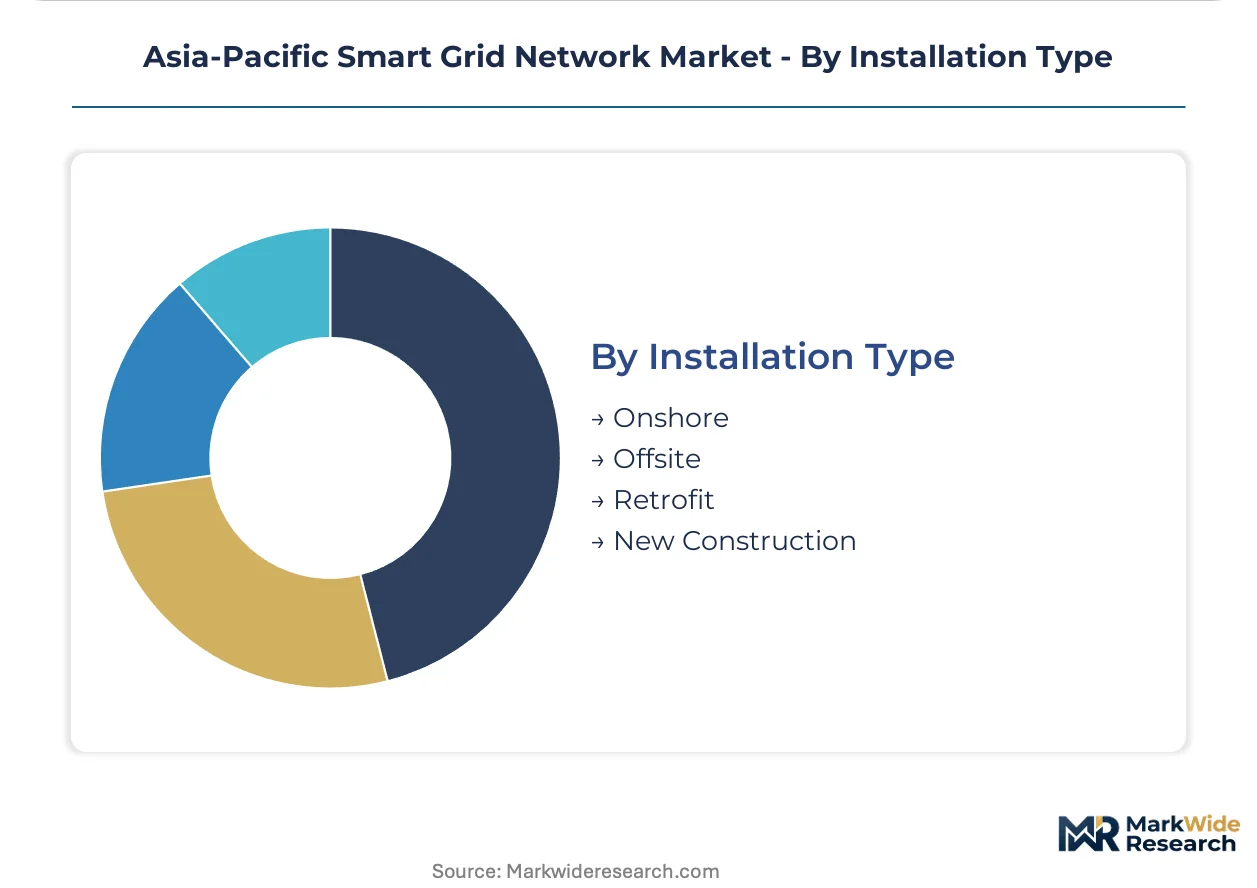
Installation Type:
Customer type determines project structure, with greenfield developments enabling integrated design versus retrofit constraints in existing substations.
- Onshore:Terrestrial grid infrastructure deployment within national boundaries. Vietnam's rural electrification expansion creates first-mover opportunities for AMI vendors in provincial distribution networks.
- Offsite:Prefabricated substation modules and containerized control systems. Australia's remote mining operations drive demand for modular digital substation architectures in Western Australia and Queensland.
- Retrofit:Upgrade of existing infrastructure with compatible communication overlays.
- New Construction:Fully integrated smart grid design in greenfield developments.
Retrofit represents the largest addressable base; New Construction offers the cleanest deployment economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity for power management integrated circuits concentrates in Taiwan, creating supply vulnerability for sensor and control hardware deployed across Asia-Pacific grid modernization programs. This concentration shapes procurement risk profiles for utilities from Seoul to Sydney.
China
Shandong and Jiangsu provinces drive replacement demand as rooftop solar penetration exceeds network hosting capacity. MIIT enforces GB standards for grid-interactive inverter communications that reshape equipment procurement specifications. State Grid Corporation deploys two-way digital communication systems across eastern coastal provinces where congestion forces real-time sensing infrastructure.
India
Maharashtra and Gujarat state distribution companies concentrate AMI procurement volume under CEA-mandated smart metering rollout timelines. The PLI scheme for advanced metering creates predictable demand pipelines for hardware and software vendors. Rural electrification expansion in Rajasthan and Madhya Pradesh accelerates capital deployment toward automated control systems.
Japan
METI directs R&D subsidies toward grid-forming inverter technologies targeting stabilization of weak network areas. Legacy narrowband power-line carrier infrastructure in older Tokyo and Osaka installations creates technical debt slowing full-stack replacement. Kyushu and Hokkaido rural utilities open procurement channels for advanced power electronics.
South Korea
KEPCO demand response programs target heavy industrial clusters in Ulsan and Yeosu with behind-the-meter generation integration. The Seoul Capital Area drives building energy management convergence with utility-scale load control systems. National smart grid standards accelerate communication network migration toward LTE-M cellular infrastructure.
Australia
The National Electricity Market drives performance-based maintenance agreements for AMI and DER management platforms among commercial and industrial energy users. Western Australia and Queensland remote mining operations demand modular digital substation architectures. Interval metering data activates demand response participation across New South Wales and Victoria.
Asia-Pacific Smart Grid Network Market Competitive Environment
Integrated industrial conglomerates and specialized power technology firms split the market between full-stack platform provision and component-level excellence. The vendor base concentrates around three strategic archetypes: diversified electrical equipment manufacturers with captive software capabilities, pure-play communication infrastructure specialists, and industrial automation groups with utility-sector heritage. Competitive dynamics center on strategic partnerships for local certification compliance and portfolio diversification into DER aggregation software.
Within the diversified equipment tier, ABB Ltd and Siemens AG exemplify integrated platform providers with regional software support centers in Singapore and Bangalore. Schneider Electric SE occupies a position bridging building energy management with utility-scale demand response systems. These European-anchored conglomerates represent the archetype of hardware-software convergence as aftermarket service contracts unbundle from equipment sales.
| Leading Market Players |
|---|
| ABB Ltd |
| Siemens AG |
| Schneider Electric SE |
| Cisco Systems Inc. |
| General Electric Company |
| Eaton Corporation |
| IBM Corporation |
| Honeywell International Inc. |
| Itron Inc. |
| Others |
Value Chain & Pricing Dynamics
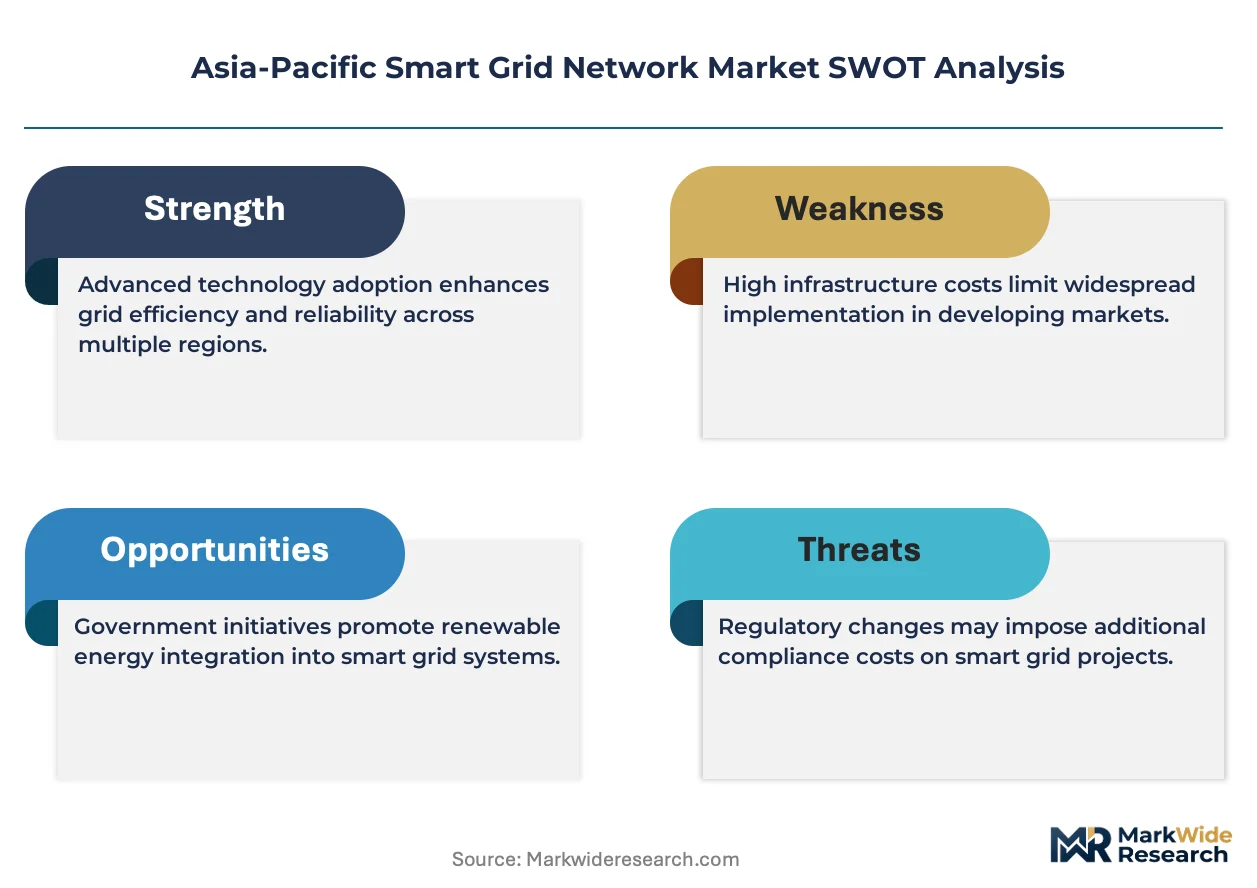
The Shanghai-Singapore maritime corridor's freight cost dynamics compress hardware margins while amplifying price differentiation between premium-certified and economy-tier smart grid components across Asia-Pacific utility procurement.
Pricing Analysis
India's CEA smart metering mandates dictate the pricing tier structure across state distribution company procurement. Three-tier pricing structure across premium, standard, and economy levels separates fiber-optic-enabled AMI from LTE-M cellular and legacy narrowband power-line carrier systems. Cost compression in economy tiers is intensifying because semiconductor input volatility from Taiwan-based foundries squeezes hardware margins. State distribution companies in Maharashtra and Gujarat exhibit highest price sensitivity; remote mining operators in Western Australia show least sensitivity due to performance-based maintenance requirements.
Supply Chain Analysis
Taiwan-based foundries and South Korean memory manufacturers hold concentrated contract-manufacturing capacity for power management integrated circuits and specialized analog chips. Geographic supply concentration centers on Taiwan, South Korea, and Japan for sensor hardware and industrial communication modules. Raw material dependencies include silicon wafers, rare earth elements for magnetic components, and copper for cabling infrastructure. Single-source vulnerability from Taiwan-based foundry concentration creates procurement risk for grid sensor deployments. Distribution runs through authorized distributor networks serving state utility procurement offices and EPC contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated state grid operators in China and India, fragmenting procurement influence among smaller Southeast Asian utilities and creating asymmetric negotiation leverage across the region.
For Market Incumbents: Build switching-cost moats through embedded software subscription platforms that lock utilities into recurring maintenance contracts. Deepen backward integration into industrial communication protocol production to reduce certification dependency on external suppliers. Threaten margin erosion from pure-play DER software vendors by bundling hardware-software performance guarantees. For New Entrants and Emerging Players: Establish a beachhead in Vietnam and Philippines provincial distribution networks where AMI penetration remains underdeveloped and first-mover advantages persist. Target grid-forming inverter technologies for Japan's rural Hokkaido utilities receiving METI R&D subsidies. Deploy cloud-native grid analytics platforms with faster deployment cycles than legacy SCADA integrators. For Investors and Strategic Acquirers: Communication infrastructure specialists with LTE-M and fiber-optic certification capabilities represent the most defensible acquisition target archetype given upgrade cycle intensity. Long-term viability hinges on software-defined platform transitions recurring revenue pools. Watch for inflection when India's PLI scheme procurement volumes cross threshold triggering consolidation among state distribution company vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Substation Architecture Deployment | State Grid Corporation's eastern coastal installations compress hardware replacement cycles while creating recurring software maintenance revenue. |
| Backward Integration into Communication Protocol Production | Siemens AG's in-house industrial protocol manufacturing reduces certification timeline exposure across India's CEA-mandated rollout schedules. |
| DER Aggregation Platform Development | Schneider Electric SE's building-utility convergence captures margin pools from Singapore's dense commercial HVAC load control market. |
| Regional Software Support Center Establishment | ABB Ltd's Singapore and Bangalore facilities unbundle aftermarket service contracts from hardware sales in Australia's National Electricity Market. |
| Grid-Forming Inverter R&D Investment | Japan's METI subsidies for rural Hokkaido and Kyushu stabilization technologies open procurement channels for advanced power electronics vendors. |
Study Parameters
Operator-level perspectives from utility planning officers, grid operators, EPC contractors, and smart meter procurement managers anchored the qualitative base for this analysis. Primary interview findings combined with secondary validation from FERC filings, IEA reports, EIA data, and project development databases. Bottom-up AMI deployment estimates triangulated against top-down capital expenditure disclosures from State Grid Corporation and China Southern Power Grid.
Scenario-bracketing framed the analytical approach across the projection horizon. Segmentation dimensions modeled include technology type, component category, end user archetype, and installation configuration. CAGRs derived from weighted average of historical deployment trajectories and policy-mandated procurement schedules. Forecast inputs incorporated India's PLI scheme volume targets and China's dual carbon goal enforcement timelines.
Stress conditions across semiconductor supply availability, regulatory certification delays, and renewable penetration hosting capacity limits were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about policy continuity and foundry capacity expansion. Quarterly review of state distribution company tender announcements and METI subsidy allocation patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
Demand Response Market
Smart Grid
South and Central America Smart Grid Market
Smart Grid
Power Grid Market
Smart Grid
Smart Grid Communications Market
Smart Grid
North America Smart Grid Market
Smart Grid
India Smart Grid Network Market
Smart Grid
Smart Grid Sensors Market
Smart Grid
Smart Demand Response Market
Smart Grid
Saudi Arabia Smart Grid Network Market
Smart Grid
North America Automated Demand Response Management System Market
Smart Grid
Saudi Arabia Smart Grid Market
Smart Grid
North America Microgrid Market
Smart Grid
China Smart Grid Network Market
Smart Grid
AC Grid Connected Microgrid Market
Smart Grid
Smart Grid Home Area Network (HAN) Market
Smart Grid
Smart Water Grid Market