

Bidirectional EV Charger and V2X Grid Integration Test Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Bidirectional EV Charger and V2X Grid Integration Test Systems Market Insights
Power electronics engineering talent is rotating from legacy inverter manufacturing toward V2X test system development, unlocking design velocity for specialized equipment. ABB leverages its grid automation heritage to anchor hardware-in-the-loop platforms for utility-scale validation. Siemens sustains R&D intensity across digital twin environments that simulate grid-edge interactions. Wallbox competes through compact residential test rigs that accelerate home energy system certification cycles.
Bidirectional EV charger and V2X grid integration test systems comprise power cycling equipment, communication protocol analyzers, and grid emulation hardware designed to validate conformance with IEC 61851, ISO 15118, and regional interconnection standards under simulated load and generation scenarios. DC charger test platforms dominate current procurement volumes due to their critical role in high-power vehicle-to-grid pathways, while wireless charger validation infrastructure represents the fastest-growing segment as inductive V2X prototypes advance toward commercialization. Application demand clusters around vehicle-to-grid configurations where margin pools deepen from recurring firmware update certification and utility interconnection re-approval workflows.
FERC interconnection rules in the United States, EU F-Gas Regulation refrigerant constraints on thermal management, and IEEE 1547-2018 grid support function requirements collectively shape product roadmaps and market access conditions for test system vendors. The EU AI Act introduces emerging conformity obligations for autonomous charge scheduling algorithms that will propagate into validation protocols. Stakeholders must monitor which standard-setting bodies harmonize V2X cybersecurity requirements first, as this convergence point will determine where capital equipment procurement accelerates next.
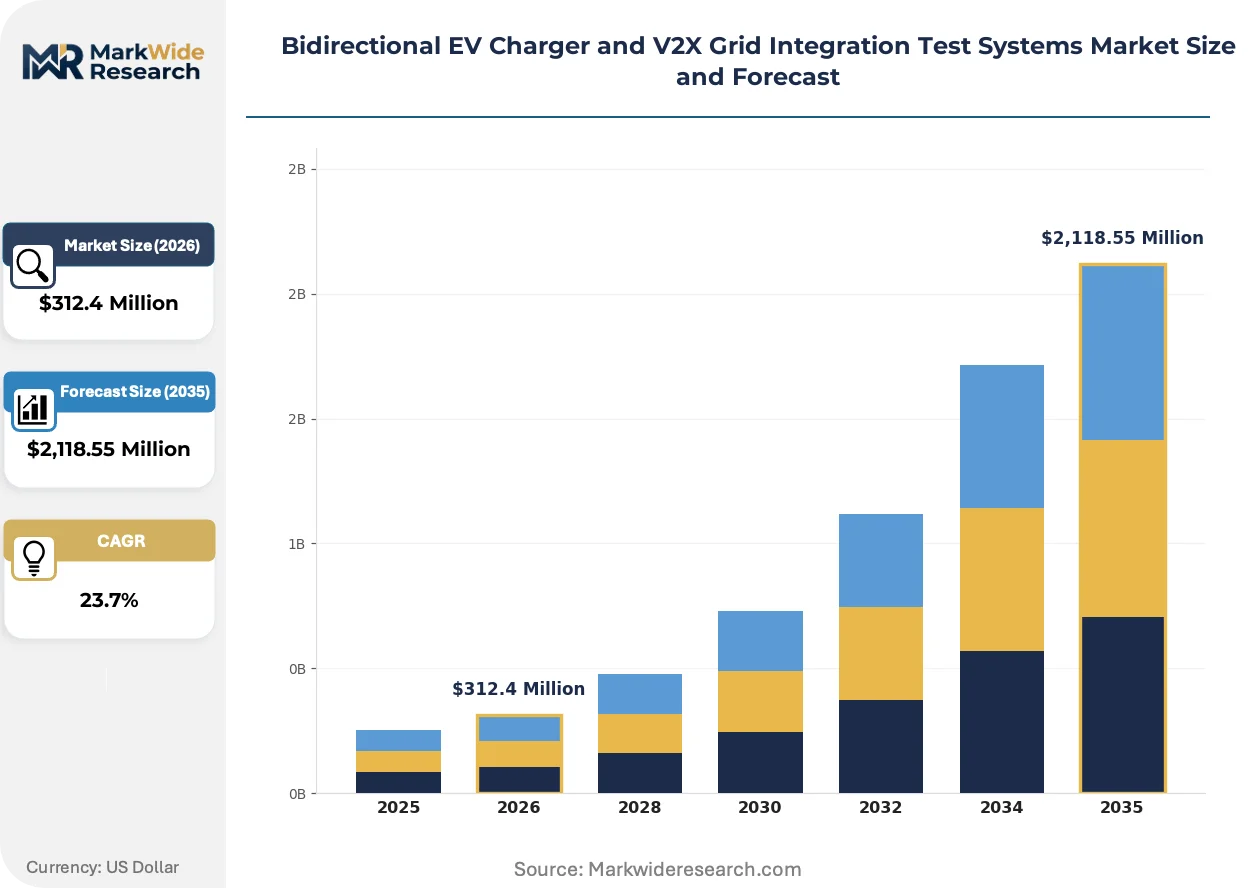
Market Dynamics
Automotive OEM validation labs are scaling test bench procurement to certify V2X interoperability under evolving grid codes, compressing equipment refresh cycles from seven years to three years as IEEE 1547 revisions and EU F-Gas Regulation tighten conformance windows.
Growth Catalysts
- Vehicle-to-grid pilot programs:German transmission and distribution system operators coordinate large-scale deployments that require certified bidirectional power electronics, creating sustained equipment procurement from TSO-DSO consortiums.
- EU F-Gas Regulation:Refrigerant constraints on thermal management systems force retesting of existing charger designs, generating recurring revenue streams for validation service providers.
- Wireless inductive prototypes:Inductive V2X systems advancing toward commercialization require specialized magnetic field emulation hardware that legacy DC test platforms cannot accommodate.
Market Restraints
- Power semiconductor supply concentration:Silicon carbide wafer fabrication concentrates in East Asian foundries, exposing test system lead times to geopolitical supply disruptions.
- IEEE 1547-2018 grid support complexity:Utility interconnection rules in the United States mandate frequency-watt and volt-watt functions that extend firmware validation timelines by months.
- Copper and rare earth magnet costs:Grid emulation hardware requires substantial copper windings and neodymium magnets, tying equipment margins to volatile commodity indexes.
Strategic Opportunities
- EU AI Act algorithmic conformity:Autonomous charge scheduling validation protocols will require new test modules for machine learning inference verification, opening adjacent revenue pools.
- Residential energy system certification:Compact home test rigs address fragmented installer networks seeking faster home energy management system approvals.
- Digital twin convergence:Hardware-in-the-loop platforms integrating real-time grid simulation software compress physical prototyping needs for OEMs.
Industry Challenges
- Power electronics engineering scarcity:Talent migration from legacy inverter manufacturing creates recruitment bottlenecks for specialized V2X test system design teams.
- Multi-protocol firmware certification:Simultaneous validation against IEC 61851, ISO 15118, and regional variants requires expensive protocol analyzer suites that strain mid-tier lab budgets.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bidirectional EV Charger and V2X Grid Integration Test Systems Market Trends and Innovations
Test system architecture is fragmenting into modular, software-defined platforms that separate power stage hardware from control layer programming, enabling faster reconfiguration across evolving certification protocols.
Silicon carbide power modules are decomposing traditional IGBT-based test bench designs by enabling higher switching frequencies at reduced thermal loads. Tier 1 automotive suppliers are retrofitting existing validation lines with SiC-equipped cycling equipment. This transition is compressing capital equipment replacement cycles as older silicon platforms lose certification relevance.
The EU AI Act introduces emerging conformity obligations for autonomous charge scheduling algorithms that will propagate into validation protocols. Equipment vendors must embed machine learning inference testing modules into existing hardware-in-the-loop architectures. European certification bodies are most affected, accelerating procurement of AI-capable test benches ahead of enforcement timelines.
Buyer concentration among utility-scale pilot programs is fragmenting certification demand across smaller residential and commercial installer networks. Traditional centralized lab services face displacement from distributed compact test rigs that accelerate local interconnection approvals. Germany and California exhibit this pattern most visibly, with DSOs and municipal utilities procuring smaller-footprint equipment for field validation.
Bidirectional EV Charger and V2X Grid Integration Test Systems Market Segmentation
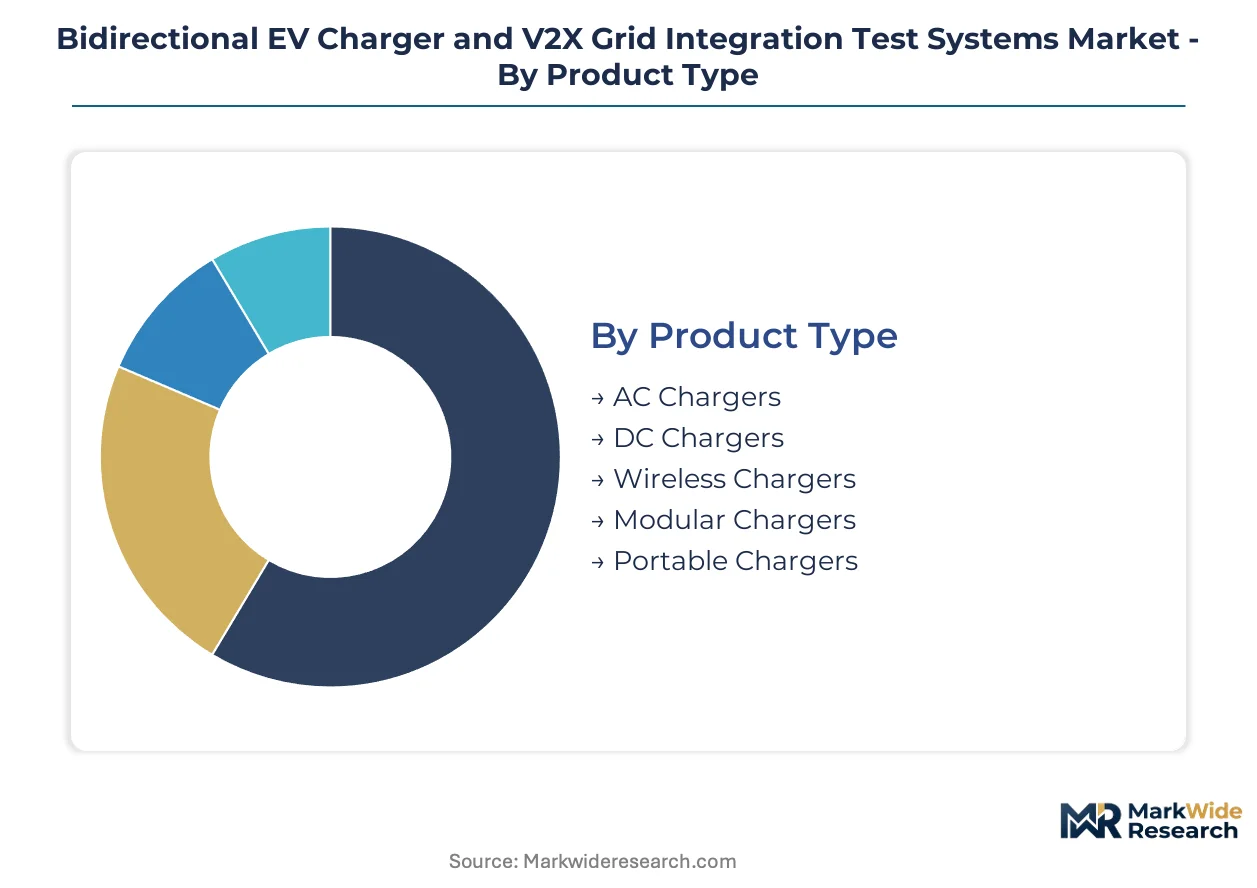
Test system procurement channels diverge sharply across segment types. OEM validation labs favor high-capacity DC platforms, while distributed installer networks drive compact AC and portable configurations. Equipment vendors must align channel strategy with segment-specific certification workflows and buyer concentration patterns.
Product Type:
Channel mix varies by power class and deployment setting, with utility-scale pilots flowing through systems integrators and residential segments fragmenting across distributor networks.
- DC Chargers:High-power cycling equipment validates bidirectional power electronics up to 350kW under IEC 61851-23. German TSO-DSO consortiums anchor procurement volumes as grid-scale V2X pilots expand.
- Wireless Chargers:Magnetic field emulation hardware tests inductive power transfer efficiency and foreign object detection. California municipal utilities and South Korean automotive OEMs concentrate early validation demand for commercialization-ready prototypes.
- AC Chargers:Residential and light commercial test rigs for lower-power bidirectional validation.
- Modular Chargers:Reconfigurable platforms that adapt to evolving protocol requirements.
- Portable Chargers:Field-deployable units for distributed installer certification needs.
By volume, DC Chargers lead. By growth pace, Wireless Chargers are climbing the fastest.
Technology:
Cost tier stratification separates premium protocol analyzers from commodity connectivity modules, with certification-grade equipment commanding substantial price premiums.
- Power Line Communication:ISO 15118-3 compliant signal integrity testing dominates European validation protocols. German certification bodies mandate PLC conformance for grid interconnection approval.
- 5G:Ultra-reliable low-latency communication testing enables autonomous charge scheduling and real-time grid balancing. Japanese METI-funded pilot programs concentrate early procurement of 5G-capable test benches.
- Cellular Network:LTE-M and NB-IoT validation for remote monitoring and firmware updates.
- Wi-Fi:Home energy system local connectivity certification.
- ZigBee:Smart home integration protocol testing.
- Dedicated Short Range Communication:Plug-and-charge authentication validation.
Power Line Communication holds the largest installed base. 5G is gaining share fastest among new procurements.
Application:
Application maturity correlates directly with margin structure, with established V2G workflows generating recurring firmware recertification revenue versus emerging applications requiring upfront platform development.
- Vehicle-to-Grid:Bidirectional power flow validation under frequency-watt and volt-watt grid support functions per IEEE 1547-2018. US FERC interconnection rules and EU F-Gas Regulation drive sustained retesting cycles across California, Texas, and German utility territories.
- Vehicle-to-Home:Residential islanding and backup power certification. Japanese residential energy system installers and German single-family housing clusters concentrate demand for compact home validation rigs.
- Vehicle-to-Load:Direct appliance power delivery testing for construction and emergency services.
- Renewable Energy Integration:Solar and storage coupling validation protocols.
- Peak Load Management:Demand response algorithm verification.
Vehicle-to-Grid dominates current revenue. Vehicle-to-Home shows the steepest expansion trajectory as residential certification networks proliferate.
End User:
Customer type determines procurement scale and decision velocity, with concentrated utility buyers negotiating multi-year frameworks versus fragmented installer networks requiring rapid-turnaround equipment.
- Electric Vehicle Manufacturers:In-house validation labs at automotive OEMs run continuous certification cycles for model-year updates. German and South Korean OEMs maintain the densest test bench concentrations.
- Charging Network Operators:Interoperability certification across multi-vendor hardware deployments. California and Netherlands-based operators face the most stringent grid code compliance timelines.
- Energy Service Companies:Third-party validation services for smaller market participants.
- Smart City Administrations:Municipal procurement for public charging infrastructure.
Electric Vehicle Manufacturers account for the largest equipment footprint. Charging Network Operators are expanding procurement most rapidly as public infrastructure scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
F-Gas Regulation enforcement by ECHA anchors European procurement intensity, while FERC interconnection mandates and METI-funded pilots concentrate validation demand across North American and Japanese utility territories.
Germany
TSO-DSO consortiums coordinate grid-scale V2X pilot programs requiring certified bidirectional power electronics. EU F-Gas Regulation refrigerant constraints force thermal management retesting of existing charger designs. The Ruhr industrial cluster and Munich engineering corridor host dense concentrations of OEM validation labs scaling test bench procurement.
United States
FERC interconnection rules mandate frequency-watt and volt-watt grid support functions that extend firmware validation timelines. California municipal utilities and Texas grid operators procure compact field-deployable rigs for distributed installer certification. Silicon Valley technology clusters and Austin energy innovation hubs concentrate pilot program coordination.
Japan
METI-funded programs concentrate early procurement of 5G-capable test benches for autonomous charge scheduling validation. Residential islanding and backup power certification drives demand for compact home validation rigs. The Kanto region around Tokyo and Nagoya's Chubu industrial corridor anchor automotive OEM test bench concentrations.
South Korea
Automotive OEMs maintain dense validation lab networks for model-year update certification cycles. Government-backed V2X commercialization initiatives accelerate inductive power transfer prototype testing. The Seoul Capital Area and Busan-Ulsan manufacturing belt concentrate wireless charger validation infrastructure deployment.
China
MIIT grid-edge interconnection standards and dual carbon goals propel utility-scale bidirectional charger deployment. Silicon carbide wafer fabrication concentration in East Asian foundries exposes test system lead times to supply chain considerations. The Yangtze River Delta and Pearl River Delta industrial zones host power electronics manufacturing clusters.
Bidirectional EV Charger and V2X Grid Integration Test Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the test system vendor base. Grid automation heritage anchors premium-tier positioning for hardware-in-the-loop platforms, while compact residential specialists compete on certification cycle acceleration. The market structures around three strategic archetypes: integrated industrial conglomerates with utility-scale validation heritage, specialized power electronics firms with SiC module expertise, and distributed energy software-hardware hybrids. Competitive moves center on digital twin convergence partnerships and modular platform architectures that separate power stages from control layers.
Within the integrated industrial tier, ABB and Siemens exemplify archetypes leveraging grid automation heritage for utility-scale hardware-in-the-loop platforms. Wallbox occupies a position representing compact residential specialists competing through distributed installer network enablement. These three anchors illustrate how vendor strategies diverge between centralized lab services and fragmented field validation equipment procurement patterns.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Wallbox |
| Schneider Electric |
| Delta Electronics |
| Fermata Energy |
| NUVVE Holding |
| dcbel |
| Virta |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with East Asian foundries lock in silicon carbide wafer access while capping price volatility for test system manufacturers serving German TSO-DSO consortiums and California municipal utilities. These arrangements tether equipment margins to commodity indexes for copper and neodymium magnets while insulating procurement timelines from geopolitical supply disruptions.
Pricing Analysis
Geographic price spreads between European certification-grade equipment and Asian commodity-tier platforms exceed threefold, driven by IEC 61851-23 conformance bundling and post-sales firmware support obligations. Three-tier pricing structure across premium, standard, and economy levels separates hardware-in-the-loop platforms with digital twin integration from basic power cycling rigs. Cost compression in the standard tier intensifies as mid-tier labs defer protocol analyzer investments. Charging network operators exhibit highest price sensitivity due to multi-vendor interoperability mandates, while automotive OEM validation labs prioritize certification velocity over unit economics.
Supply Chain Analysis
China and South Korea anchor silicon carbide wafer fabrication and power module assembly, while Germany and Japan concentrate precision magnetics and grid emulation hardware production. Test system manufacturing draws from copper windings, rare earth magnets, and high-frequency power semiconductors as critical inputs. Single-source vulnerability in SiC substrate supply exposes lead times to foundry allocation decisions. Distribution runs through systems integrators for utility-scale pilots and distributor networks for residential compact rigs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power electronics engineering talent migration from legacy inverter manufacturing has created acute design-team shortages that constrain product development velocity for specialized V2X validation equipment.
For Market Incumbents: Compound grid automation heritage into integrated hardware-in-the-loop platforms that embed machine learning inference testing ahead of EU AI Act enforcement timelines. Acquire SiC module design capabilities to secure thermal management differentiation as F-Gas refrigerant constraints force charger retesting cycles. Defend against modular software-defined entrants by tightening OEM validation lab relationships through multi-year certification service frameworks. For New Entrants and Emerging Players: Firmware update certification as a recurring revenue service represents the most penetrable white-space where incumbent equipment vendors under-serve mid-tier charging network operators. Target California and Texas municipal utilities with compact field-deployable rigs that compress distributed installer approval timelines. Pursue channel partnerships with residential energy system distributors rather than direct OEM lab sales. For Investors and Strategic Acquirers: Capital is best deployed toward specialized power electronics firms with captive SiC expertise and existing IEEE 1547-2018 validation protocols. Long-term viability hinges on positioning ahead of autonomous charge scheduling algorithm conformity requirements. Monitor which standard-setting body harmonizes V2X cybersecurity requirements first as the inflection signal for capital equipment procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | Siemens and ABB compress physical prototyping needs for German automotive OEM validation labs. |
| SiC Module Supply Agreement | Test bench manufacturers secure thermal performance advantages as IGBT platforms lose certification relevance. |
| AI Inference Testing Module Development | Equipment vendors embed machine learning validation ahead of EU AI Act enforcement timelines. |
| Residential Installer Network Partnership | Wallbox-type specialists accelerate home energy management system certification cycles. |
| Multi-Protocol Analyzer Suite Investment | Mid-tier labs address simultaneous IEC 61851 and ISO 15118 validation requirements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FERC interconnection filings, ECHA F-Gas Regulation guidance documents, and IEEE standards committee minutes. Primary interviews engaged test system product managers at industrial conglomerates, validation lab directors at German and South Korean automotive OEMs, and procurement officers at California municipal utilities. Secondary validation drew from customs trade data for power electronics equipment, SEC filings of listed charging infrastructure firms, and METI pilot program disclosures. Bottom-up equipment procurement tallies triangulate against top-down market sizing from grid-scale V2X deployment announcements.
Segmentation dimensions modeled include product type (DC, wireless, AC, modular, portable), communication technology (PLC, 5G, cellular, Wi-Fi), application configuration (V2G, V2H, V2L), and end-user category (OEM validation labs, charging network operators, energy service companies). CAGRs were derived from equipment refresh cycle compression analysis and pilot program expansion trajectories across the analysis window. Forecast inputs incorporate silicon carbide adoption curves in power cycling equipment and wireless inductive prototype commercialization timelines.
Forecasts assume regulatory continuity in EU F-Gas refrigerant constraints, IEEE 1547-2018 grid support mandates, and FERC interconnection rules; material policy shifts would require re-modeling. Supply chain disruption scenarios and standard harmonization delays represent specific revision triggers. Recalibration cycles align with material shifts in V2X cybersecurity standard convergence and autonomous charge scheduling enforcement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.