
 EV Battery Rental and Swapping Market | 2026-2036
EV Battery Rental and Swapping Market Size, Share, and Industry Trends Forecast 2026-2036
EV Battery Rental and Swapping Market Foresight
Buyer concentration is rebalancing from individual consumers toward fleet operators and ride-hailing platforms seeking asset-light electrification. NIO sustains technology leadership through its proprietary battery pack architecture and automated swap station deployment across Chinese highways. Gogoro dominates Taiwan's urban two-wheeler ecosystem with its GoStation network, leveraging dense metropolitan coverage to lock in subscriber retention. Ample competes in the commercial fleet segment with modular battery swapping for light-duty delivery vehicles, extending its platform to logistics partnerships in California and Madrid.
EV battery rental and swapping encompasses the provision of rechargeable energy storage units through lease or exchange models rather than outright purchase, typically involving standardized lithium-ion packs with 50-75 kWh capacity and automated mechanical interfaces enabling sub-three-minute exchanges. The primary purpose is to eliminate capital barriers to EV adoption while decoupling battery degradation risk from vehicle ownership. Subscription-based service models anchor recurring revenue streams and capture the largest share of contracted value, while pay-per-use structures attract occasional drivers with lower commitment thresholds. Fleet management applications generate the fastest growth trajectory as logistics operators prioritize uptime over asset ownership, with margin pools concentrating in battery lifecycle management and predictive maintenance software layers.
The US NHTSA and EPA shape product standards through crashworthiness requirements for swappable pack enclosures and emissions credits for battery-as-a-service models, while China's MIIT enforces dimensional and electrical interface standards that determine market access for station operators. India's CEA and BIS are drafting safety protocols for high-voltage swap infrastructure in tropical climates, creating compliance thresholds for foreign equipment suppliers. Stakeholders must monitor how regulatory divergence in pack standardization affects cross-border equipment economics and whether interoperability mandates emerge as a condition for public charging subsidies.
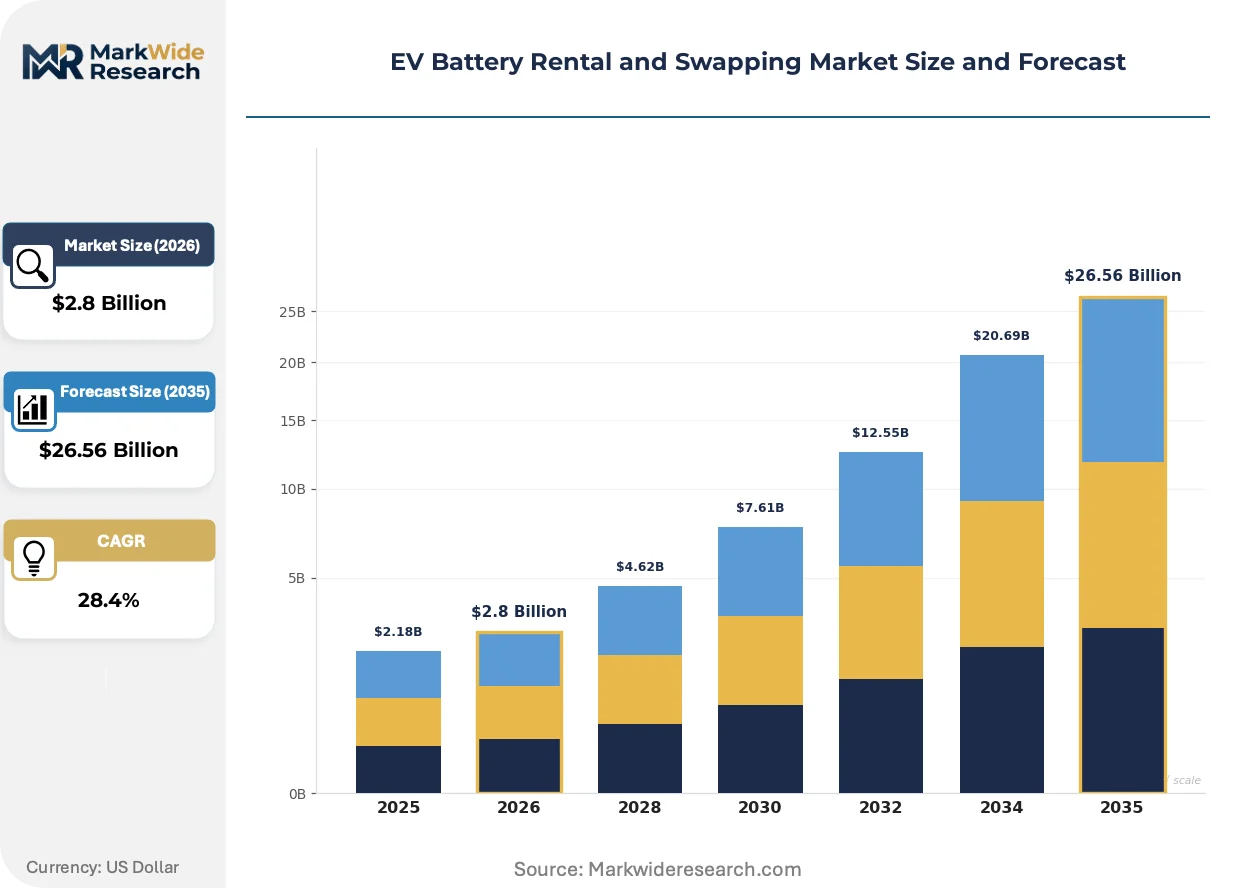
Market Dynamics
China's MIIT battery standardization mandate is compressing pack design variance and forcing station operators toward unified mechanical interfaces, reshaping equipment procurement economics across the value chain.
Growth Catalysts
- Fleet electrification mandates:Urban logistics operators in India face tightening emission norms from the CEA, accelerating battery-as-a-service adoption for commercial two- and three-wheelers.
- High-voltage swap protocols:BIS safety certifications for tropical climate infrastructure are unlocking dense station deployment in coastal Indian cities.
- Highway corridor densification:China's MIIT guidelines specify 50-kilometer maximum spacing for swap stations along national expressways, creating predictable infrastructure rollout schedules.
Market Restraints
- Lithium carbonate volatility:Raw material price swings compress rental margin structures and complicate long-term subscription pricing.
- Pack architecture lock-in:Proprietary battery form factors from dominant station operators fragment interoperability and strand capital in single-vendor networks.
- Grid interconnection delays:Distribution utility approval timelines for high-capacity swap stations extend deployment schedules in secondary Indian cities.
Strategic Opportunities
- Indonesian archipelago logistics:Island-hopping commercial fleets lack charging infrastructure, creating first-mover advantage for maritime-adapted swap networks.
- Vehicle-to-grid integration:Bidirectional power flow from swappable packs enables frequency regulation revenue streams for fleet operators.
- Second-life battery arbitrage:Retired rental packs with 70-80% state-of-health enter stationary storage applications, extending value capture beyond mobility.
Industry Challenges
- High-voltage technician scarcity:Qualified electricians certified for 400V+ live work remain concentrated in Tier-1 Indian cities, constraining station maintenance scaling.
- Multi-OEM software integration:Fleet management platforms must reconcile disparate battery state-of-health data streams across vehicle brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Battery Rental and Swapping Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $26.56 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Subscription, Pay-per-use, Long-term Lease, On-demand Battery Type: Lithium-ion, Solid State, Nickel-metal Hydride, Others Application: Ride-hailing, Personal Use, Fleet Management, Public Transport Customer Type: Individual, Business, Government, Commercial |
| Companies Covered | NIO, Gogoro, Ample, Battery Smart, Sun Mobility, CATL, Aulton New Energy, RACE Energy, Ola Electric Mobility, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Battery Rental and Swapping Market Shifts & Advancements
Standardized pack architectures and automated swap mechanisms are compressing exchange times below three minutes, while regulatory pressure on battery lifecycle accountability is forcing new service-layer monetization strategies.
Solid-state battery prototypes are absorbing thermal management complexity through inherent flame-retardant electrolyte chemistry. Logistics operators in California and Madrid pilot these packs for light-duty delivery vehicles despite manufacturing cost premiums. The technology is absorbing safety certification burdens that currently constrain lithium-ion deployment in underground parking structures.
India's CEA and BIS are finalizing tropical-climate safety protocols for high-voltage swap infrastructure, mandating IP67 enclosure ratings and enhanced humidity corrosion testing. Foreign equipment suppliers face 18-24 month certification timelines, compressing their market entry windows against domestic manufacturers. Commercial fleet operators in Chennai and Bangalore are pre-ordering certified stations to secure early-mover positioning.
Subscription fatigue among occasional drivers is fragmenting demand toward pay-per-use structures with no minimum commitment. Ride-hailing platforms in Southeast Asian cities unbundle battery costs from driver earnings, replacing vehicle financing with per-kilometer energy fees. This shift concentrates margin pools in predictive range analytics and dynamic pricing algorithms rather than hardware deployment.
EV Battery Rental and Swapping Market Segmentation
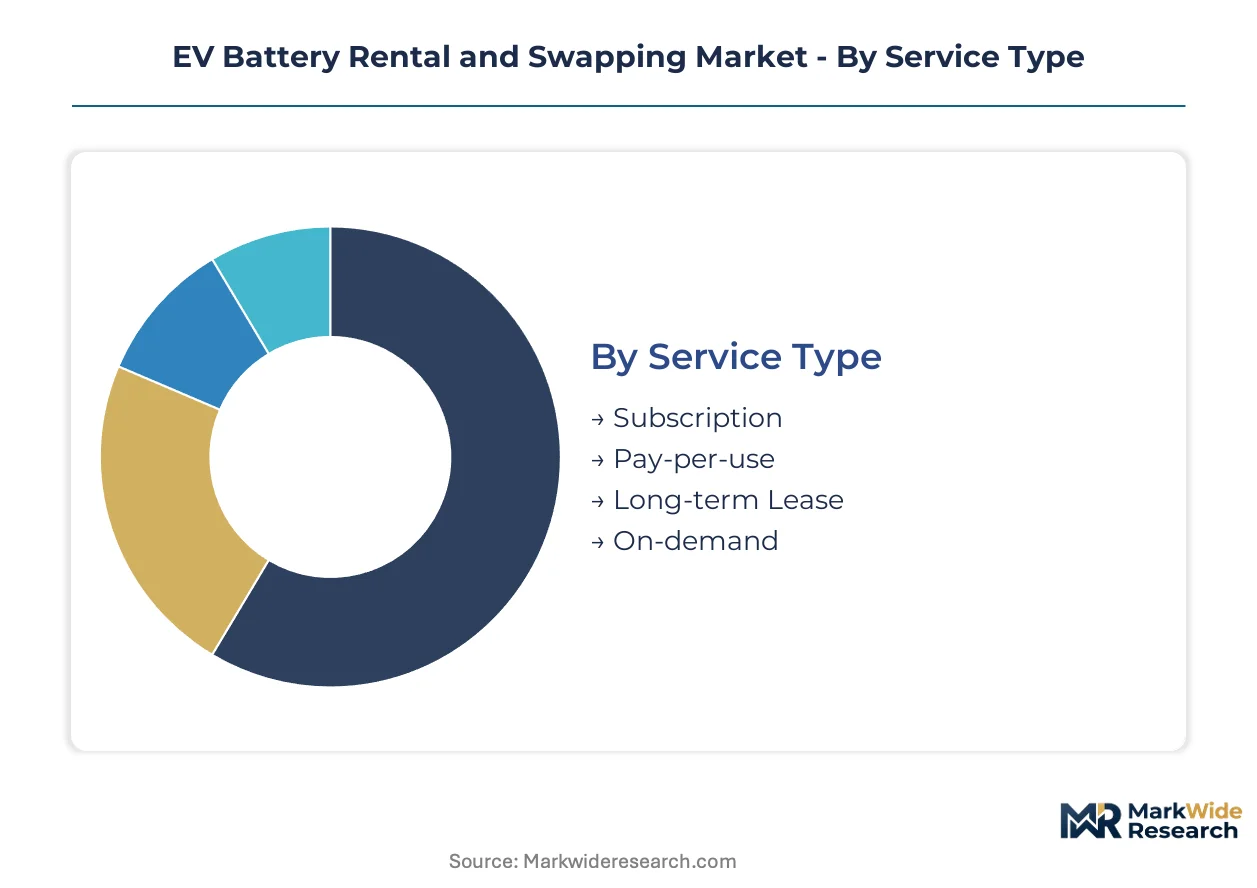
Segmentation in battery rental and swapping reveals how capital allocation, technical risk, and operational intensity fragment across use cases. Service model selection directly determines payback periods for station infrastructure, while battery chemistry choices lock in thermal management requirements and lifecycle value recovery.
Service Type:
Supply concentration in automated swap stations favors recurring-revenue contracts that amortize hardware costs across predictable utilization curves.
- Subscription:Fixed monthly fees cover unlimited battery exchanges, anchoring cash flow stability for operators deploying capital-intensive robotic swap stations. Fleet operators in India's urban corridors favor this structure to eliminate range anxiety while preserving balance sheet capacity for vehicle acquisition.
- Pay-per-use:Per-exchange or per-kilometer pricing attracts occasional drivers and seasonal commercial users with lower commitment thresholds. Ride-hailing platforms across Southeast Asian cities are unbundling battery costs from driver earnings, replacing vehicle financing with dynamic energy fees tied to actual utilization.
- Long-term Lease:Multi-year contracts transfer battery degradation risk to service providers while locking in energy costs for logistics operators with predictable route profiles.
- On-demand:Ad-hoc swapping through mobile-app dispatch serves sporadic users in emerging markets where station density remains insufficient for subscription viability.
Today's leader: Subscription. Tomorrow's challenger: Pay-per-use.
Battery Type:
Cost tier differentiation separates premium thermal performance from commoditized energy density solutions.
- Lithium-ion:NMC and LFP chemistries dominate installed capacity with mature supply chains and established recycling pathways. India's CEA and BIS certification requirements for tropical-climate operation favor LFP variants with inherent thermal stability in high-humidity coastal cities.
- Solid State:Prototype packs with flame-retardant electrolyte chemistry absorb safety certification burdens that constrain lithium-ion deployment in underground parking structures. Logistics pilots in California and Madrid test these systems for light-duty delivery despite manufacturing cost premiums.
- Nickel-metal Hydride:Legacy chemistry persists in hybrid conversions and price-sensitive retrofit markets with limited fast-charge requirements.
- Others:Sodium-ion and lithium-metal variants occupy pre-commercial niches targeting raw material diversification and specific energy density thresholds.
Cost leadership sits with lithium-ion. Technical differentiation favors solid state.
Application:
Volume concentration in commercial mobility creates divergent infrastructure requirements between high-utilization corridors and dispersed residential demand.
- Fleet Management:Centralized depot swapping with scheduled battery rotation maximizes vehicle uptime for logistics operators prioritizing asset utilization over ownership. India's commercial two- and three-wheeler segments are expanding most quickly here as CEA emission norms tighten urban logistics compliance.
- Ride-hailing:Dense urban station networks serve driver-partners with shift-based energy needs, generating the highest per-station transaction volumes in Taiwan's metropolitan cores.
- Personal Use:Residential subscribers with intermittent driving patterns require flexible pricing but generate lower station throughput economics.
- Public Transport:Bus depot swapping demands megawatt-scale grid interconnection and utility-coordinated charging windows to minimize demand charges.
Margin pools concentrate in fleet management. Mass-market scaling depends on ride-hailing penetration.
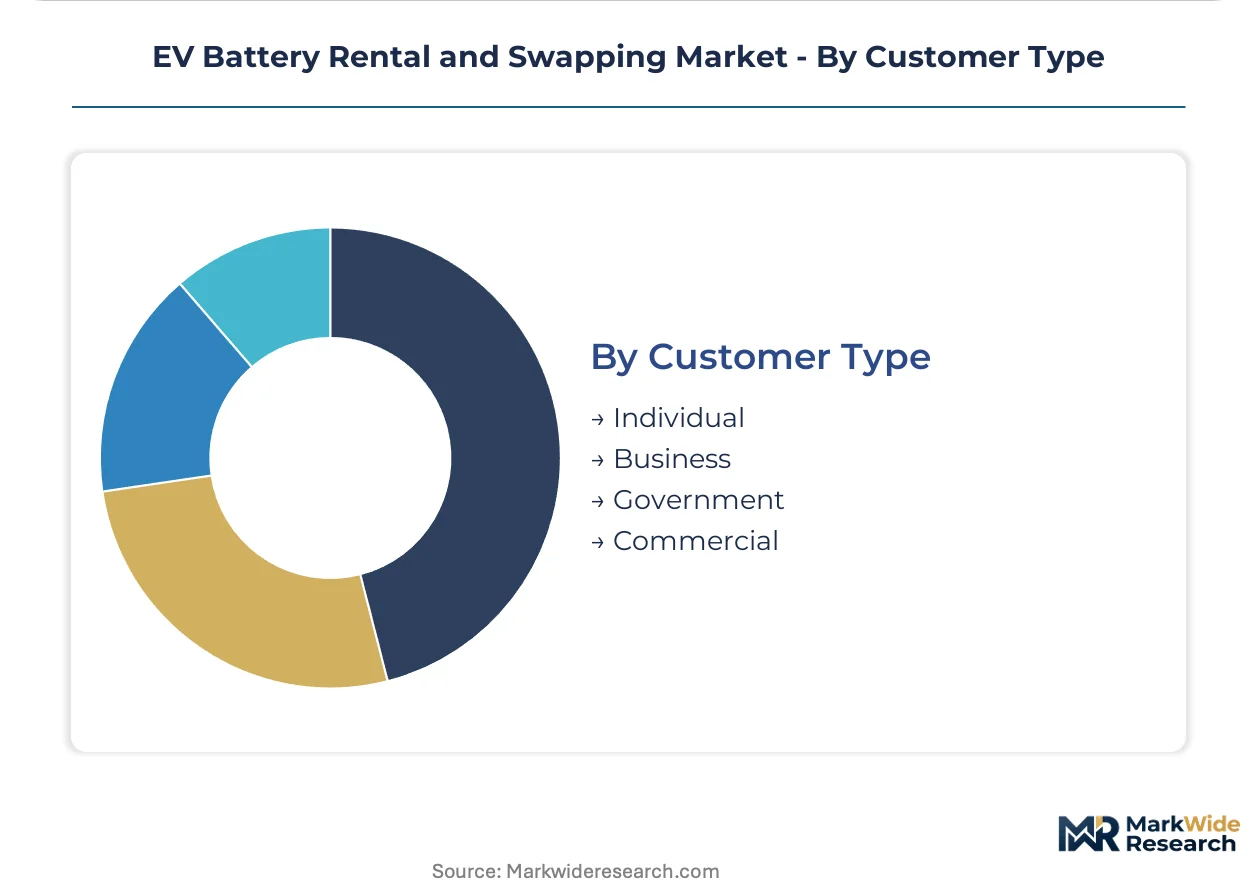
Customer Type:
Procurement authority fragmentation separates centralized fleet decisions from distributed individual choices.
- Commercial:Fleet operators and logistics platforms negotiate enterprise contracts with volume guarantees and integrated telematics, commanding preferential station access and dedicated swap bay allocation.
- Business:Small and mid-sized enterprises with mixed vehicle fleets seek hybrid service structures combining subscription baseload with pay-per-use peak coverage.
- Government:Municipal procurement mandates for public sector electrification specify interoperability requirements and domestic content thresholds that shape vendor qualification.
- Individual:Retail subscribers drive station location decisions through density-sensitive adoption patterns, with churn risk concentrated in markets lacking competitive network alternatives.
Contract value concentrates with commercial customers. Network effects depend on individual subscriber density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineers and technicians certified for high-voltage battery systems concentrate in Chinese industrial corridors and Indian metropolitan clusters, anchoring deployment capacity for automated swap infrastructure. This talent distribution shapes where station networks achieve operational scale first.
China
MIIT's mandatory dimensional and electrical interface standards compress pack design variance and accelerate highway corridor densification. The 50-kilometer maximum spacing mandate for national expressways creates predictable rollout schedules for station operators. Yangtze River Delta manufacturing hubs around Shanghai supply robotic swap mechanisms to domestic networks.
India
CEA emission tightening for urban logistics and BIS tropical-climate safety certifications unlock dense station deployment in coastal cities. Sun Mobility and Battery Smart are building networks for commercial two- and three-wheeler fleets. Chennai and Bangalore clusters pre-order certified stations to secure early positioning.
Taiwan
Metropolitan two-wheeler density and shift-based driver energy needs generate the highest per-station transaction volumes in East Asia. Gogoro's GoStation network leverages this urban concentration to lock subscriber retention through coverage depth. Taipei and Kaohsiung cores anchor the operational model.
United States
NHTSA crashworthiness requirements for swappable pack enclosures and EPA emissions credits for battery-as-a-service models shape product standards. Ample pilots modular swapping for light-duty delivery vehicles with logistics partners in California. Bay Area and Los Angeles corridors test commercial fleet viability.
Indonesia
Island-hopping commercial fleets lack charging infrastructure across the archipelago, creating first-mover openings for maritime-adapted swap networks. National logistics operators seek asset-light electrification for inter-island freight routes. Java and Sumatra port clusters represent initial deployment targets.
EV Battery Rental and Swapping Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across fragmented station infrastructure and battery lifecycle management layers. Tiered market structure separates capital-intensive hardware deployers from software-centric fleet management platforms. Three archetypes dominate: integrated automotive OEMs with proprietary pack architectures, dedicated swapping network operators with dense urban coverage, and modular technology licensors enabling third-party station deployment. Competitive moves concentrate on strategic partnerships with fleet operators and geographic licensing agreements that accelerate network scaling without direct capital deployment.
Within the integrated automotive tier, NIO represents proprietary ecosystem control through captive battery design and automated highway station deployment. Gogoro exemplifies dense urban two-wheeler network lock-in via metropolitan coverage depth and subscription retention mechanics. Ample occupies a modular licensor position, enabling third-party station deployment for commercial fleet segments without requiring direct infrastructure ownership.
| Leading Market Players |
|---|
| NIO |
| Gogoro |
| Ample |
| Battery Smart |
| Sun Mobility |
| CATL |
| Aulton New Energy |
| RACE Energy |
| Ola Electric Mobility |
| Others |
Supply & Pricing Matrix
Fleet operator procurement concentration in India's commercial two- and three-wheeler corridors anchors subscription-based pricing structures that amortize robotic station hardware across predictable utilization curves. This buyer archetype's volume guarantees compress per-swap costs below pay-per-use thresholds for individual subscribers.
Pricing Analysis
Subscription and pay-per-use service splits fragment pricing power across commitment tiers. Three-tier pricing structure across premium fleet contracts, standard commercial subscriptions, and economy pay-per-use exchanges separates contract value by utilization intensity and telematics integration depth. Cost compression in economy tiers intensifies because raw material volatility in lithium carbonate feeds through to unbundled per-kilometer fees. Fleet operators with enterprise volume guarantees exhibit lowest price sensitivity; occasional retail drivers in emerging markets show highest elasticity to minimum commitment thresholds.
Supply Chain Analysis
Single-source vulnerability sits with Chinese cathode active material suppliers dominating NMC and LFP precursor output. Manufacturing draws from concentrated cell production corridors in China, South Korea, and Japan, with robotic swap mechanisms sourcing from Yangtze River Delta industrial clusters. Tariff exposure on battery component imports complicates equipment procurement economics for station operators in India and Southeast Asia. Distribution runs through licensed technology partnerships that enable geographic scaling without direct capital deployment by original equipment vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
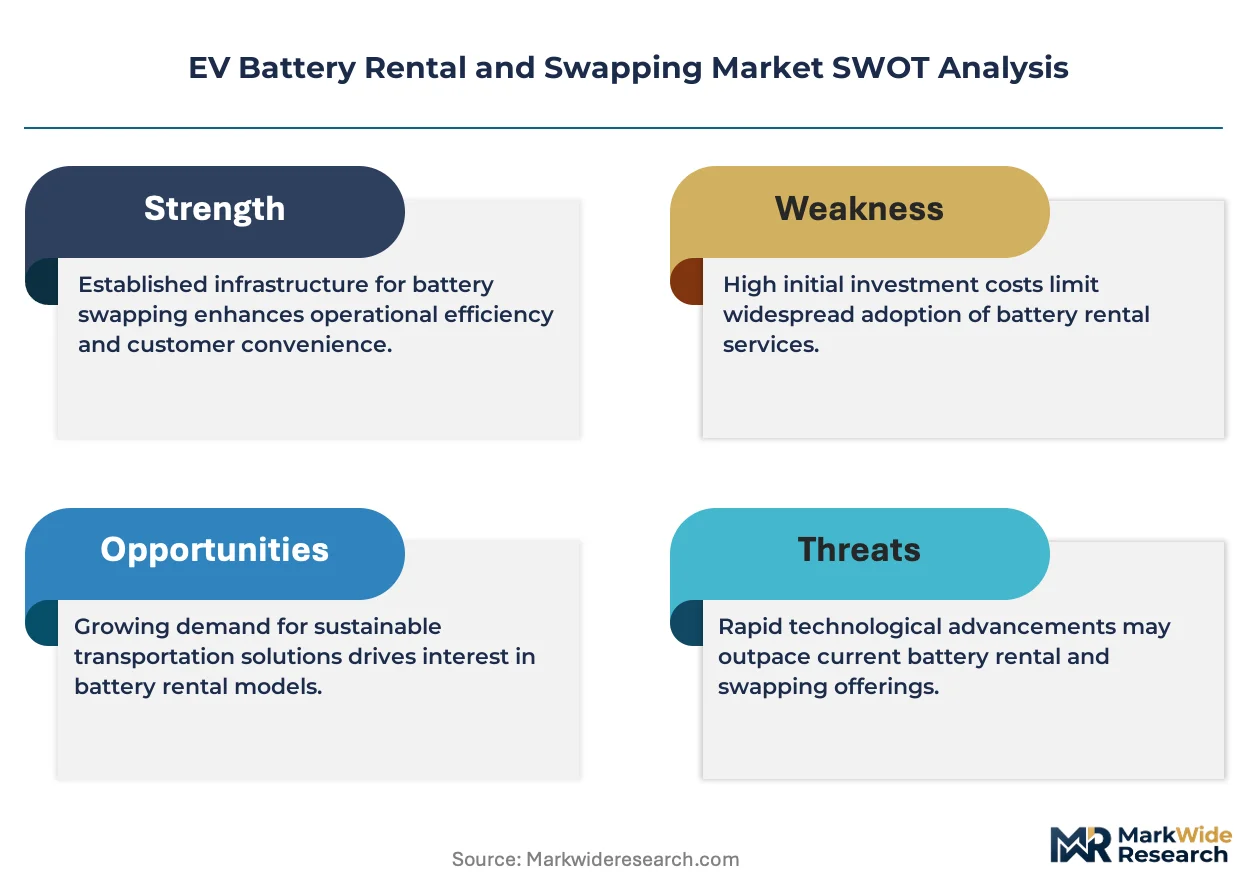
EV battery rental and swapping represents a late-cycle quality story where fleet operator procurement specifications are tightening toward IP67-certified tropical-climate enclosures and predictive maintenance software layers. This demand-shift toward premium specifications rewards operators with certified station deployments and lifecycle analytics capabilities.
For Market Incumbents: Extend proprietary pack architecture control through deeper software integration with fleet telematics platforms, locking in switching costs against modular competitors. Consolidate station maintenance networks by acquiring regional technician training programs, addressing high-voltage certification scarcity that constrains scaling in Tier-2 Indian cities. Defend margin position by backward integration into second-life battery arbitrage channels. For New Entrants and Emerging Players: Direct-to-fleet digital sales channels bypass incumbent station network density advantages in Indonesia's archipelago logistics corridors. White-space concentration in maritime-adapted swap infrastructure for inter-island commercial routes offers lowest competitive intensity. Target pay-per-use platform partnerships with ride-hailing aggregators in Southeast Asian cities where subscription fatigue has fragmented individual demand. For Investors and Strategic Acquirers: Integrated automotive OEMs are the most active acquirer in this space, seeking captive battery service revenue streams to offset vehicle margin compression. Long-term viability hinges on software-layer monetization scaling faster than hardware depreciation cycles. Acquisition target archetype: modular technology licensors with fleet management platform integration and geographic licensing agreements in place. The inflection indicator to watch is interoperability mandate adoption as a condition for public charging subsidies in major markets.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | MIIT dimensional guidelines in China compress pack variance and accelerate equipment procurement cycles. |
| Battery Supply Agreement | Long-term LFP offtake contracts with CATL insulate Indian operators from lithium carbonate spot volatility. |
| Geographic Manufacturing Footprint | Domestic station assembly in Chennai and Bangalore compresses 18-24 month BIS certification timelines. |
| Charging Infrastructure Partnership | Utility-coordinated grid interconnection agreements unlock megawatt-scale depot swapping for bus fleets. |
| Software-Defined Vehicle Investment | Predictive range analytics integration captures margin pools as ride-hailing platforms unbundle battery costs. |
Research Methodology
Bottom-up fleet operator modeling reconciled against top-down station infrastructure tracking forms the analytical core of this study. Primary interviews with swap station network operators, fleet procurement managers, high-voltage systems engineers, and BIS certification specialists combined with secondary validation against MIIT policy filings, CEA emission norm notifications, IEA EV outlook data, and customs trade records. Triangulation across supply-side capacity announcements and demand-side contract disclosures ensures volume reconciliation.
Historical trendline analysis of subscription contract growth and station deployment velocity established baseline momentum across the projection horizon. Segmentation dimensions modeled include service type, battery chemistry tier, application vertical, and customer procurement authority. CAGRs were derived from fitted growth curves adjusted for regulatory milestone timing and raw material cost trajectory assumptions. Forecast inputs incorporate fleet electrification mandate compliance deadlines and tropical-climate safety certification rollout schedules.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook by compressing thermal management infrastructure requirements and shifting safety certification burdens. Forecasts reflect assumptions regarding standardization mandate enforcement intensity and lithium supply expansion timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Two Wheel Electric Vehicle Charger Market
Electric Vehicle Charging
EV DC Fast Charger Market
Electric Vehicle Charging
Asia-Pacific Brushless DC Motors Market
Electric Vehicle Charging
Combined Charging System Market
Electric Vehicle Charging
Asia-Pacific Electric Vehicle Charging Cable Market
Electric Vehicle Charging
Micro Mobility Charging Infrastructure Market
Electric Vehicle Charging
E-Bike Charging Station Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station Infrastructure Market
Electric Vehicle Charging
Japan Electric Vehicle Charging Station Market
Electric Vehicle Charging
Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Germany EV Charging Infrastructure Market
Electric Vehicle Charging
EV Charging Point Market
Electric Vehicle Charging
Spain Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
Battery Swapping Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle DC Fast Charging Station Market
Electric Vehicle Charging
Global EV Charger Market