

High-Thermal-Conductivity Gap-Fill Adhesives for EV Battery Cooling Plates Market Size, Share, and Industry Trends Forecast 2026-2036
High-Thermal-Conductivity Gap-Fill Adhesives for EV Battery Cooling Plates Market Insights
Aftermarket thermal retrofit revenue is reconfiguring margin pools away from first-fit supply contracts. Henkel leverages its silicone chemistry heritage to dominate European OEM qualifications. Dow sustains North American battery plant proximity through localized compounding operations. Wacker Chemie anchors Asian supply chains with high-purity silicone feedstock control.
High-thermal-conductivity gap-fill adhesives are thermally conductive polymeric compounds, typically silicone or epoxy matrices loaded with boron nitride or aluminum oxide fillers achieving 3-8 W/mK, dispensed between battery cells and aluminum cooling plates to eliminate interfacial thermal resistance. Silicone-based formulations lead installed volume due to flexibility across -40°C to 150°C thermal cycling, while above 8 W/mK grades represent the fastest-expanding margin pool as 800V architectures intensify heat flux densities. Battery cooling plates capture the dominant application share, though power electronics dispersion is maturing fastest with standardization around 4-6 W/mK specifications.
EPA vehicle emissions thresholds and the EU Battery Regulation's carbon footprint declarations are tightening material traceability requirements for thermal interface materials entering US and European supply chains. China's MIIT new energy vehicle technical standards and SAMR adhesive quality certifications are synchronizing domestic formulation benchmarks with export market access rules. Stakeholders must monitor evolving thermal conductivity test methodologies under IEC standards and OEM-specific validation protocols as cell chemistry transitions multiply qualification burdens.
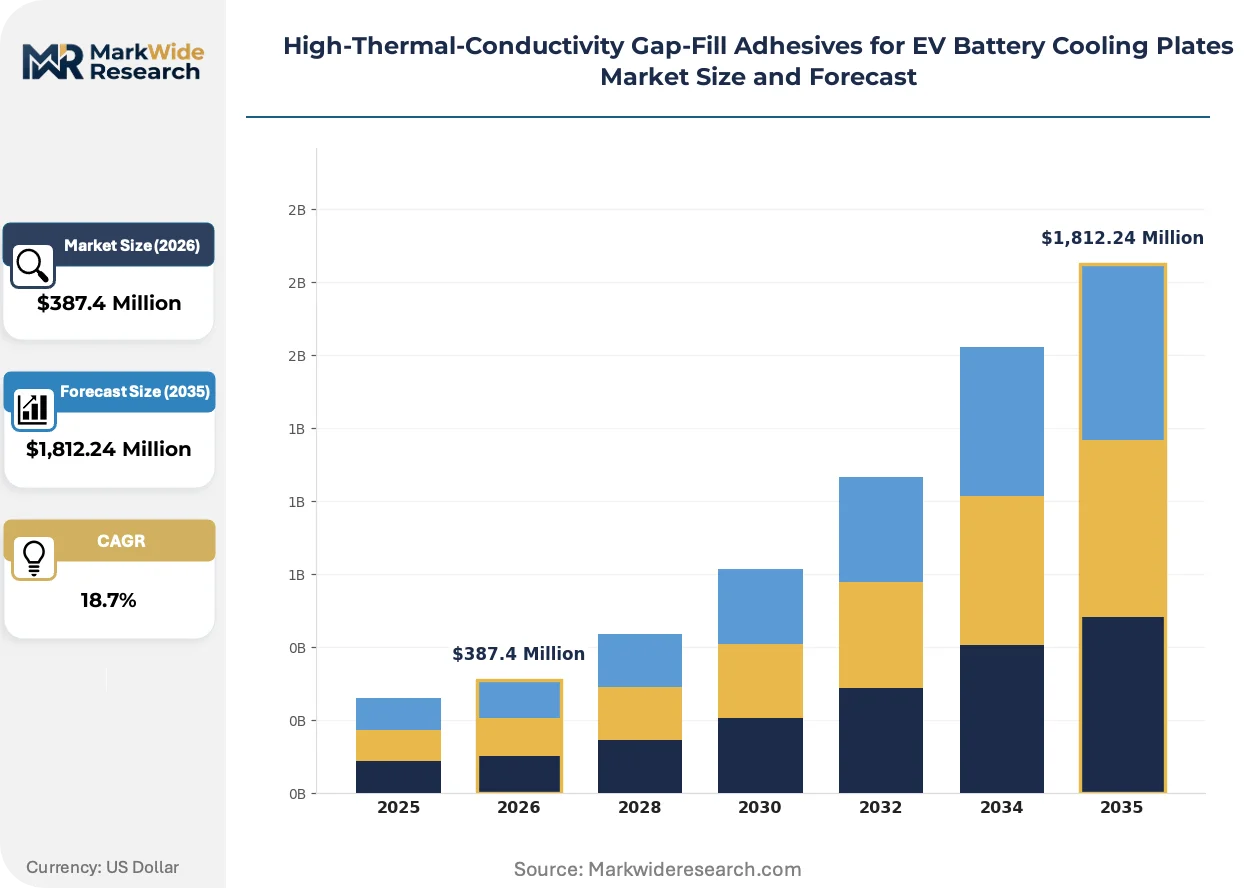
Market Dynamics
Cell-to-pack battery architectures are compressing thermal interface material specifications from module-level gaps to direct cell-to-plate bonding, forcing adhesive formulators to engineer simultaneous structural adhesion and heat dissipation in single-layer dispersions.
Growth Catalysts
- EU Battery Regulation carbon footprint declarations:Mandates under the EU Battery Regulation are forcing OEMs to document embodied carbon in thermal interface materials, advantaging suppliers with renewable energy-tinted silicone feedstock chains.
- 800V platform proliferation:Premium electric vehicle architectures operating at 800V generate heat flux densities exceeding 6 W/mK adhesive ratings, pulling demand toward boron nitride-loaded formulations above 8 W/mK.
- Stuttgart-Munich corridor concentration:Germany's automotive engineering cluster around Porsche, BMW, and Mercedes-Benz headquarters concentrates qualification activity, accelerating specification lock-in for approved suppliers.
Market Restraints
- Boron nitride supply concentration:High-purity hexagonal boron nitride synthesis capacity clusters with Chinese ceramic producers, exposing formulators to export license volatility and input cost spikes.
- Silicone feedstock energy intensity:Methyl chlorosilane production requires carbothermal reduction at 300°C+, tying adhesive margins to European natural gas pricing and carbon border adjustment exposure.
- Epoxy flexibility limitations:Rigid epoxy matrices crack under -40°C cold-start cycling prevalent in Nordic EV markets, restricting their penetration despite superior thermal conductivity.
Strategic Opportunities
- Power electronics dispersion:Inverter and onboard charger modules are standardizing around 4-6 W/mK gap-fill specifications, opening adjacent volume pools outside battery cooling plates.
- Aftermarket thermal retrofit channels:Battery degradation remediation services are creating pull-through demand for dispensed gap-fill replacement, decoupling revenue from OEM platform life cycles.
- China MIIT technical standard alignment:Domestic NEV adhesive certification benchmarks under MIIT are synchronizing with export market access rules, reducing dual-qualification burdens for compliant suppliers.
Industry Challenges
- IEC thermal conductivity test methodology divergence:Laser flash, guarded hot plate, and transient plane source methods yield inconsistent readings across OEM validation protocols, extending qualification timelines.
- Cell chemistry transition compression:LFP-to-NCM and solid-state roadmap shifts are multiplying thermal runaway simulation requirements, forcing reformulation cycles before prior generations achieve scale.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Thermal-Conductivity Gap-Fill Adhesives for EV Battery Cooling Plates Market Trends and Innovations
Formulation science is converging with dispense automation and in-line metrology, compressing the traditional separation between material specification and manufacturing process validation into unified digital twins.
Boron nitride platelet alignment through shear-controlled dispensing is digitizing thermal performance prediction. Advanced compounding operations now orient anisotropic fillers during pump-driven deposition, enabling directional conductivity tuning. Automotive thermal engineers at premium OEMs are adopting these digitally verified microstructures to eliminate over-engineering safety margins in cooling plate designs.
REACH restriction proposals on microplastic additives are tightening filler surface treatment chemistries. The European Chemicals Agency's scrutiny of silane coupling agents is forcing reformulators toward plasma-activated boron nitride surfaces. German adhesive suppliers are responding with aqueous dispersion technologies that bypass conventional solvent-based surface functionalization.
Fleet operators are consolidating thermal interface material procurement through battery leasing subsidiaries rather than OEM service networks. Commercial vehicle and energy storage buyers now contract directly with Henkel and Dow for lifecycle thermal management, bypassing tiered supply hierarchies. This disintermediation concentrates volume with formulators capable of dispensing equipment integration and predictive maintenance analytics.
High-Thermal-Conductivity Gap-Fill Adhesives for EV Battery Cooling Plates Market Segmentation
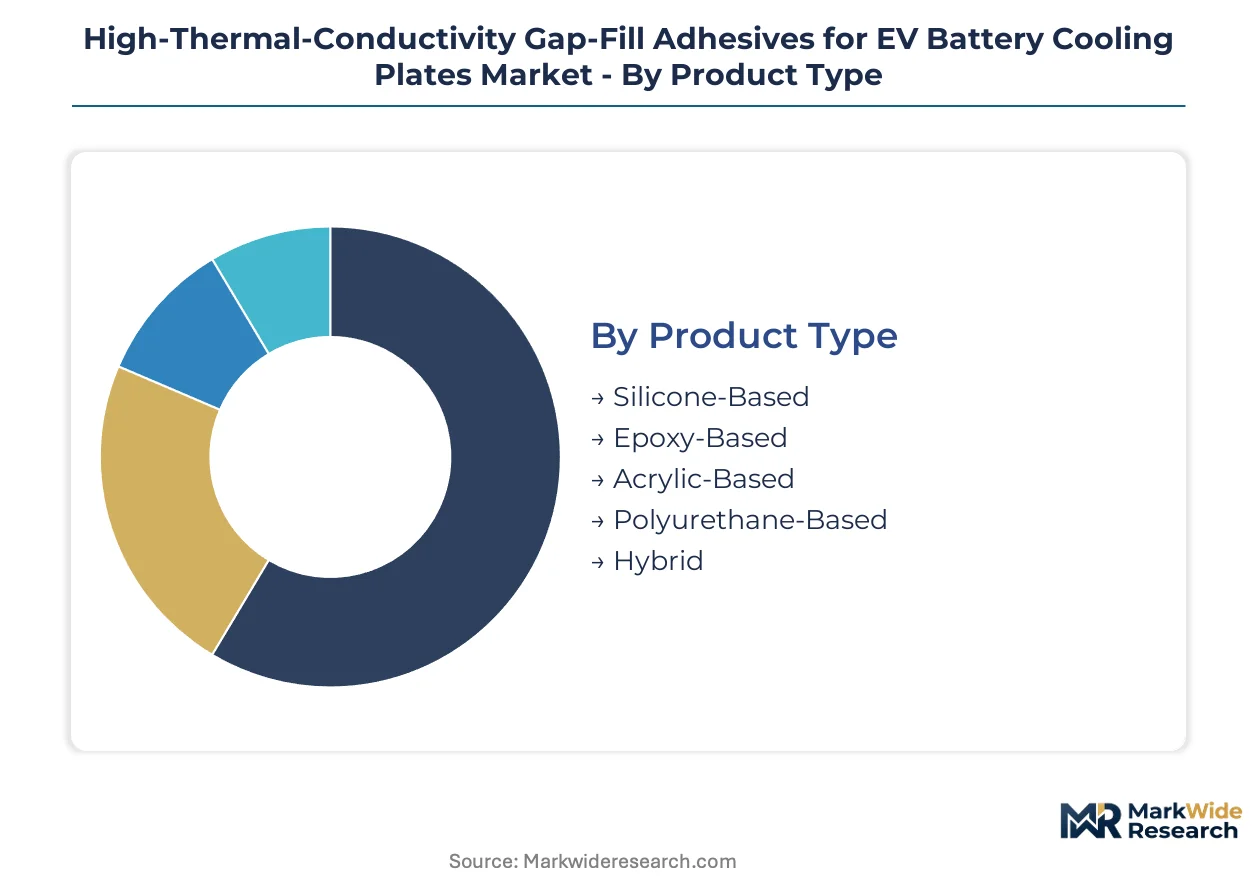
Segmentation reveals how thermal conductivity specifications, polymer chemistry choices, and customer procurement patterns fragment the gap-fill adhesive landscape. Manufacturers configure formulation portfolios around distinct performance tiers rather than pursuing universal solutions.
Product Type:
Chemistry selection determines thermal cycling resilience, processing viscosity, and filler loading capacity across battery platform specifications.
- Silicone-Based:Methyl silicone matrices loaded with aluminum oxide or boron nitride achieve 3-8 W/mK while maintaining elongation above 150%. Stuttgart-area OEMs specify these formulations for cell-to-pack architectures demanding -40°C cold-start flexibility.
- Epoxy-Based:Rigid diglycidyl ether bisphenol-A systems with metallic fillers reach 6-10 W/mK but crack under thermal shock. Nordic markets restrict epoxy penetration despite superior conductivity ratings.
- Acrylic-Based:UV-curable acrylate oligomers suit power electronics modules with lower heat flux requirements and rapid line-speed processing constraints.
- Polyurethane-Based:Two-component aliphatic systems offer moisture-cure options for repair and aftermarket retrofit channels where dispensing equipment is unavailable.
- Hybrid:Silicone-epoxy copolymer architectures attempt to bridge flexibility and conductivity gaps, though qualification timelines lag established chemistries.
Silicone-based formulations hold installed capacity. Above-8 W/mK grades are rotating up the share rankings.
Thermal Conductivity:
Performance tiering aligns adhesive specifications with heat flux densities generated by voltage architecture and cell chemistry combinations.
- 1-3 W/mK:Legacy module-level gap-fill applications with indirect cell cooling. Cost-sensitive LFP battery packs in commercial vehicles still specify this tier for non-critical thermal interfaces.
- 3-5 W/mK:Standard cell-to-pack specifications for 400V platforms with NCM chemistry. Volume concentrates with battery module manufacturers serving European premium OEMs.
- 5-8 W/mK:High-performance silicone formulations with optimized boron nitride loading. 800V architectures from Porsche and BMW pull demand toward this threshold.
- Above 8 W/mK:Anisotropic boron nitride platelet alignment through shear-controlled dispensing enables directional conductivity. Premium EV platforms operating above 800V and solid-state roadmaps drive specification migration.
3-5 W/mK captures current volume concentration. Above 8 W/mK is climbing the fastest.
End User:
Customer type determines qualification burden, contract structure, and lifecycle revenue profile for adhesive suppliers.
- Electric Vehicle OEMs:Direct platform specifications with 5-7 year qualification cycles. Cell-to-pack architecture decisions at BMW, Mercedes-Benz, and Porsche headquarters concentrate purchasing authority.
- Battery Module Manufacturers:CATL, BYD, and LG Energy Solution procure adhesives as part of integrated thermal management subsystems, with specifications dictated by OEM customers.
- Thermal Management Providers:Specialized subsystem suppliers bundle adhesives with cooling plate fabrication, compressing margins through integrated sourcing.
- Aftermarket Suppliers:Battery degradation remediation services create replacement demand outside OEM platform cycles, with dispensing equipment requirements limiting supplier participation.
Electric Vehicle OEMs retain specification authority. Aftermarket Suppliers are gaining procurement independence.
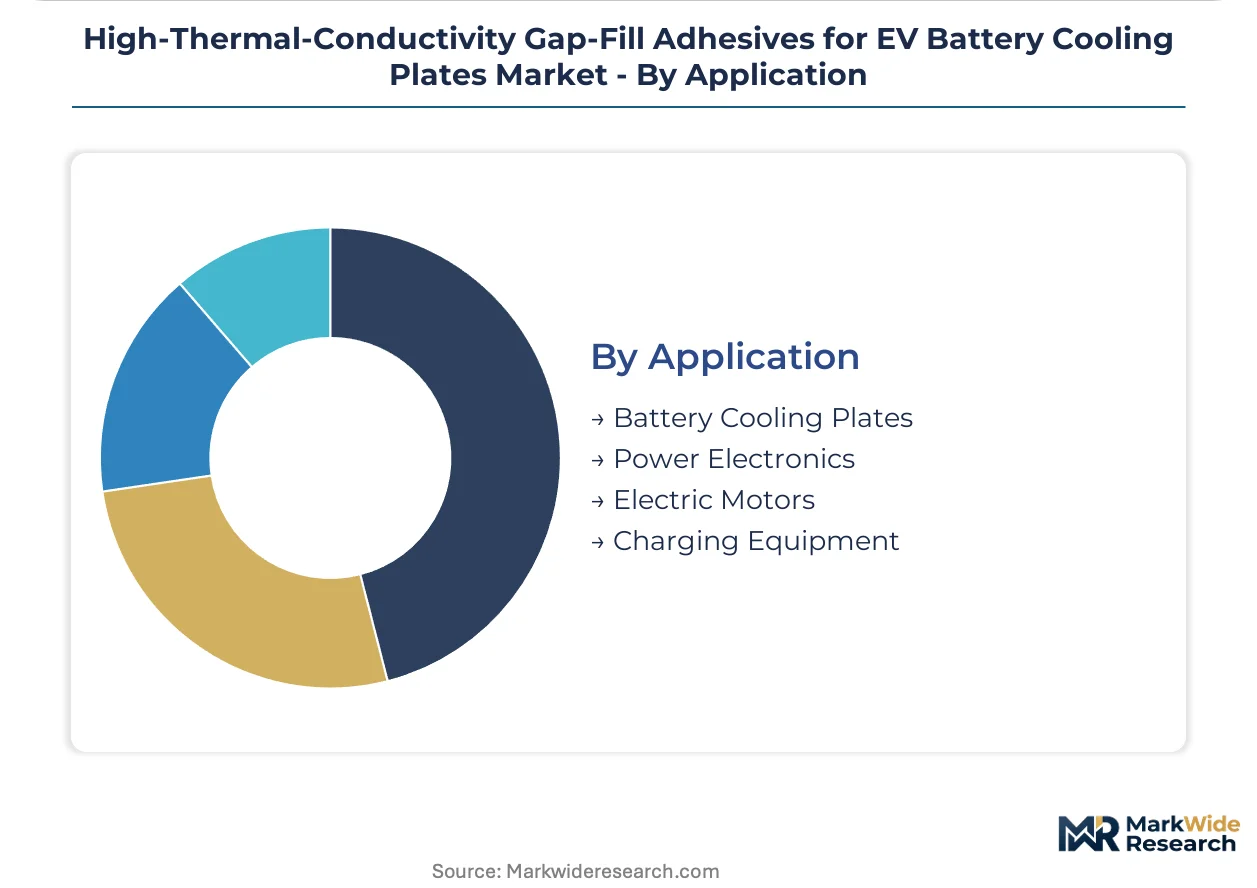
Application:
Use case diversification extends gap-fill adhesive demand beyond battery thermal management into adjacent electrification components.
- Battery Cooling Plates:Direct cell-to-plate bonding eliminates module-level thermal interfaces. Aluminum cooling plate manufacturers in Germany's automotive corridor anchor volume concentration.
- Power Electronics:Inverter and onboard charger modules standardize around 4-6 W/mK specifications. Silicon carbide switching frequencies intensify heat flux densities in this segment.
- Electric Motors:Stator winding impregnation and housing interface applications require lower conductivity grades with electrical insulation properties.
- Charging Equipment:DC fast charger power modules and cable interface sealing represent emerging volume with less stringent automotive qualification requirements.
Battery Cooling Plates dominate current procurement. Power Electronics is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exhibits the highest demand elasticity among major procurement zones, with OEMs aggressively negotiating boron nitride filler costs amid MIIT certification pressures. Germany commands premium pricing tolerance as Stuttgart-Munich corridor specifications lock in qualified suppliers for 800V platforms. The United States occupies a mid-elasticity position where EPA emissions thresholds and IRA domestic content bonuses shape sourcing trade-offs.
China
CATL and BYD drive volume concentration through integrated cell-to-pack manufacturing. SAMR adhesive quality certifications and MIIT technical standards synchronize domestic benchmarks with export access rules. Yangtze River Delta chemical clusters around Shanghai and Ningbo anchor high-purity silicone feedstock production.
Germany
Porsche, BMW, and Mercedes-Benz headquarters concentrate qualification authority for premium EV thermal specifications. EU Battery Regulation carbon footprint declarations mandate renewable-energy-tinted silicone documentation. Stuttgart automotive engineering corridors accelerate specification lock-in for approved gap-fill adhesive suppliers.
United States
Tesla, Rivian, and Lucid Motors pull demand toward localized battery plant proximity requirements. EPA vehicle emissions thresholds tighten material traceability for thermal interface materials entering domestic supply chains. Michigan and Texas battery manufacturing corridors anchor Dow's compounding operations.
South Korea
LG Energy Solution and Samsung SDI procure adhesives as integrated thermal management subsystems. MFDS chemical safety standards and METI-aligned export protocols govern formulation approvals. Seoul Capital Area battery R&D clusters concentrate qualification activity for next-generation solid-state architectures.
Japan
Toyota and Panasonic prioritize thermal cycling resilience for solid-state roadmap development. METI new energy vehicle technical standards and JIS adhesive performance benchmarks shape procurement specifications. Nagoya automotive manufacturing belts anchor precision dispensing equipment integration.
High-Thermal-Conductivity Gap-Fill Adhesives for EV Battery Cooling Plates Market Competitive Landscape
European chemical conglomerates and North American material science specialists split the market along qualification-depth versus scale-manufacturing vectors. Supplier tiers consolidate around three strategic archetypes: silicone chemistry heritage players with OEM qualification depth, diversified adhesive formulators leveraging cross-industry compounding infrastructure, and regional specialists capturing battery plant proximity premiums. Dominant competitive moves center on backward integration into high-purity boron nitride sourcing and captive dispensing equipment service bundling.
Within the heritage chemistry tier, Henkel exemplifies European OEM qualification dominance through decades of automotive adhesive supply relationships. Dow occupies a position among North American formulators emphasizing localized compounding operations near battery manufacturing corridors. Wacker Chemie anchors the feedstock-control archetype with high-purity silicone production integration. These three represent distinct strategic positions rather than direct substitutability.
| Leading Market Players |
|---|
| Henkel |
| Dow |
| Sika |
| Parker Hannifin |
| Wacker Chemie |
| Saint-Gobain |
| DuPont |
| 3M |
| H.B. Fuller |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta port congestion during boron nitride concentrate shipments feeds directly into European formulator margins, compressing the spread between Chinese feedstock procurement and Stuttgart-Munich corridor OEM price realizations. This logistics chokepoint amplifies the leverage held by suppliers with captive silicone monomer production, forcing qualification-dependent buyers toward long-term offtake structures that embed freight volatility premiums.
Pricing Analysis
Aftermarket thermal retrofit contracts capture lifetime value pools that decouple from OEM platform cycles, with battery leasing subsidiaries now contracting directly for lifecycle thermal management. Pricing stratifies across premium, standard, and economy tiers based on IEC certification grade and dispensing equipment bundling. Cost compression in the 3-5 W/mK standard tier is intensifying because CATL and BYD are consolidating procurement through integrated thermal subsystem sourcing. Fleet operators running commercial vehicle pools exhibit the highest price sensitivity, while Porsche and BMW platform engineers tolerate premium tier pricing for above-8 W/mK anisotropic formulations.
Supply Chain Analysis
High-purity hexagonal boron nitride synthesis capacity clusters with Chinese ceramic producers in Liaoning and Shandong provinces, exposing formulators to export license volatility. Methyl chlorosilane production draws from carbothermal reduction operations tied to European natural gas pricing, while aluminum oxide filler sourcing rests on Bayer process refineries in Australia and Brazil. Single-source vulnerability concentrates in boron nitride platelet surface treatment chemistries, where REACH restrictions on silane coupling agents have eliminated European alternatives. Distribution runs through battery plant co-location agreements, with Dow and Henkel operating captive compounding within 150 kilometers of major cell manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell chemistry transition compression and solid-state roadmap acceleration position this market for cyclical recovery as qualification backlogs clear and 800V platform volumes inflect. The EV battery thermal management investment cycle tracks OEM platform cadence, with adhesive specification lock-in preceding cell production ramp by 18-24 months.
For Market Incumbents: Pre-empt epoxy flexibility limitations in Nordic markets by accelerating silicone-epoxy hybrid qualification timelines before solid-state architectures mature. Secure backward integration into high-purity boron nitride sourcing through offtake agreements with Liaoning ceramic producers, insulating margins from Chinese export license volatility. Defend OEM platform positions by bundling predictive dispensing equipment analytics with formulation supply contracts.
For New Entrants and Emerging Players: Build out aqueous dispersion capabilities that bypass REACH-restricted silane coupling agents, targeting German adhesive suppliers seeking plasma-activated boron nitride surface treatments. Capture power electronics dispersion volume in the 4-6 W/mK tier, where inverter and onboard charger standardization has reduced qualification burdens relative to battery cooling plates. Lead with dispensing equipment integration partnerships rather than formulation-only supply.
For Investors and Strategic Acquirers: EU Battery Regulation carbon footprint declarations reshape the acquisition landscape by advantaging suppliers with renewable-energy-tinted silicone feedstock documentation. Target formulators with captive high-purity methyl chlorosilane production and established MIIT certification alignment for Chinese NEV market access. Monitor IEC thermal conductivity test methodology harmonization progress as the signal indicating qualification timeline compression and multiple expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Boron Nitride | Captive high-purity hexagonal boron nitride sourcing insulates Henkel and Dow from Chinese export license volatility. |
| Dispensing Equipment Service Bundling | Parker Hannifin and Sika compress customer switching costs by embedding predictive maintenance analytics with formulation supply. |
| MIIT Certification Alignment | SAMR adhesive quality synchronization reduces dual-qualification burdens for suppliers serving CATL and BYD export volumes. |
| Aqueous Dispersion Technology Transition | ECHA scrutiny of silane coupling agents forces reformulators toward plasma-activated boron nitride surfaces without solvent-based functionalization. |
| Aftermarket Thermal Retrofit Channel Development | Battery degradation remediation services create replacement demand outside OEM platform life cycles for polyurethane-based repair formulations. |
Research Methodology
A standing panel of OEM platform thermal engineers, battery module procurement leads at CATL and LG Energy Solution, dispensing equipment integration specialists, and ECHA regulatory affairs directors provided ongoing calibration across primary interview rounds. Secondary validation drew from MIIT technical standard filings, EU Battery Regulation delegated act drafts, IEC thermal conductivity test methodology working papers, and customs data tracking boron nitride concentrate trade flows. Bottom-up adhesive volume modeling by conductivity tier and chemistry type triangulated against top-down EV production forecasts by platform voltage architecture.
Scenario bracketing anchored projections across conservative, baseline, and accelerated solid-state adoption pathways, with segmentation modeling spanning polymer chemistry, thermal conductivity performance tier, end-user procurement type, and regional regulatory cluster. CAGR derivation rested on platform-level adhesive content per vehicle estimates, heat flux density requirements by voltage architecture, and cell-to-pack penetration curves. Forecast inputs incorporated SAMR certification timeline assumptions, EU carbon border adjustment implementation progress, and 800V platform launch cadence from Stuttgart-Munich corridor OEMs.
Practitioners should monitor boron nitride export license volatility, REACH restriction proposal finalization timelines, and solid-state thermal runaway simulation requirement changes for early signals of forecast revision. Cross-checking against IHS Markit EV production databases and OEM platform thermal management specification disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.