
 Electric Vehicle Charging Pile Cables Market | 2026-2036
Electric Vehicle Charging Pile Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Charging Pile Cables Market Insights
The EU Green Deal and associated national ICE phase-out mandates is realigning procurement specifications across European charging networks toward high-amperage, thermally resilient cable assemblies. Phoenix Contact leverages its interconnection technology heritage to anchor premium positioning in DC fast charging interconnect systems. Leoni AG sustains manufacturing scale across multiple conductor geometries for both AC and DC applications. TE Connectivity competes through integrated sensor-enabled cable designs that support real-time thermal monitoring.
Electric vehicle charging pile cables are specialized power transmission assemblies engineered to deliver controlled electrical energy from grid infrastructure to vehicle battery systems, typically incorporating multi-layer insulation rated for continuous operation at elevated temperatures and mechanical stress resistance. Their primary commercial purpose is to enable safe, efficient energy transfer across varying duty cycles while maintaining compliance with regional electrical safety codes. DC Fast Charging Cable occupies the highest margin pool as operators prioritize reduced dwell times and higher throughput per port. Smart Cable technology is gaining structural traction as network operators embed communication protocols for dynamic load balancing and predictive maintenance.
FCC guidelines govern electromagnetic compatibility for charging equipment deployed across the United States, while the EU AI Act and CE marking frameworks shape product certification requirements for intelligent cable systems entering European markets. China's GB standards and MIIT directives establish mandatory performance thresholds for conductive charging interfaces, directly influencing export-oriented manufacturers. Stakeholders must monitor evolving interoperability protocols between regional standards bodies as cable specification fragmentation risks complicating cross-border supply strategies.
Market Dynamics
DC fast charging infrastructure rollouts are compressing procurement cycles as fleet operators and charge point operators prioritize higher-amperage cable assemblies capable of sustaining 350kW+ continuous loads. This technical escalation is forcing rapid specification upgrades across manufacturing footprints.
Growth Catalysts
- EU Green Deal mandates:National ICE phase-out deadlines are accelerating cable specification upgrades toward thermally resilient, high-amperage designs across European charging networks.
- Fleet electrification:Logistics operators and municipal bus fleets are scaling depot charging infrastructure, pulling specialized cable orders for high-duty-cycle applications.
- Silicon carbide inverters:Wider deployment of SiC power electronics is enabling higher switching frequencies that demand improved electromagnetic shielding in cable assemblies.
Market Restraints
- Copper price volatility:Conductor material cost swings compress margin visibility for cable manufacturers locked into long-term infrastructure contracts.
- Supply concentration in China:GB standards-aligned production clusters dominate specialized conductor and insulation material supply, creating geographic dependency risk.
- Thermal management ceiling:Liquid-cooled cable architectures face reliability validation gaps that limit deployment confidence for sustained 500A+ operation.
Strategic Opportunities
- India PLI scheme:Domestic manufacturing incentives for electric vehicle components are opening localized cable production opportunities for export-oriented suppliers.
- Vehicle-to-grid integration:Bidirectional charging protocols are creating demand for communication-enabled cable assemblies with embedded powerline networking.
- Second-life battery storage:Stationary energy storage coupling with charging depots is emerging as a cable application beyond direct vehicle supply.
Industry Challenges
- Cross-standard certification:Simultaneous compliance with IEC 62893, GB/T 33594, and UL 2251 creates extended validation timelines for multi-market product launches.
- High-voltage safety training:Qualified technician scarcity for 1000V DC installation and maintenance is constraining field deployment velocity across operator networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Charging Pile Cables Market |
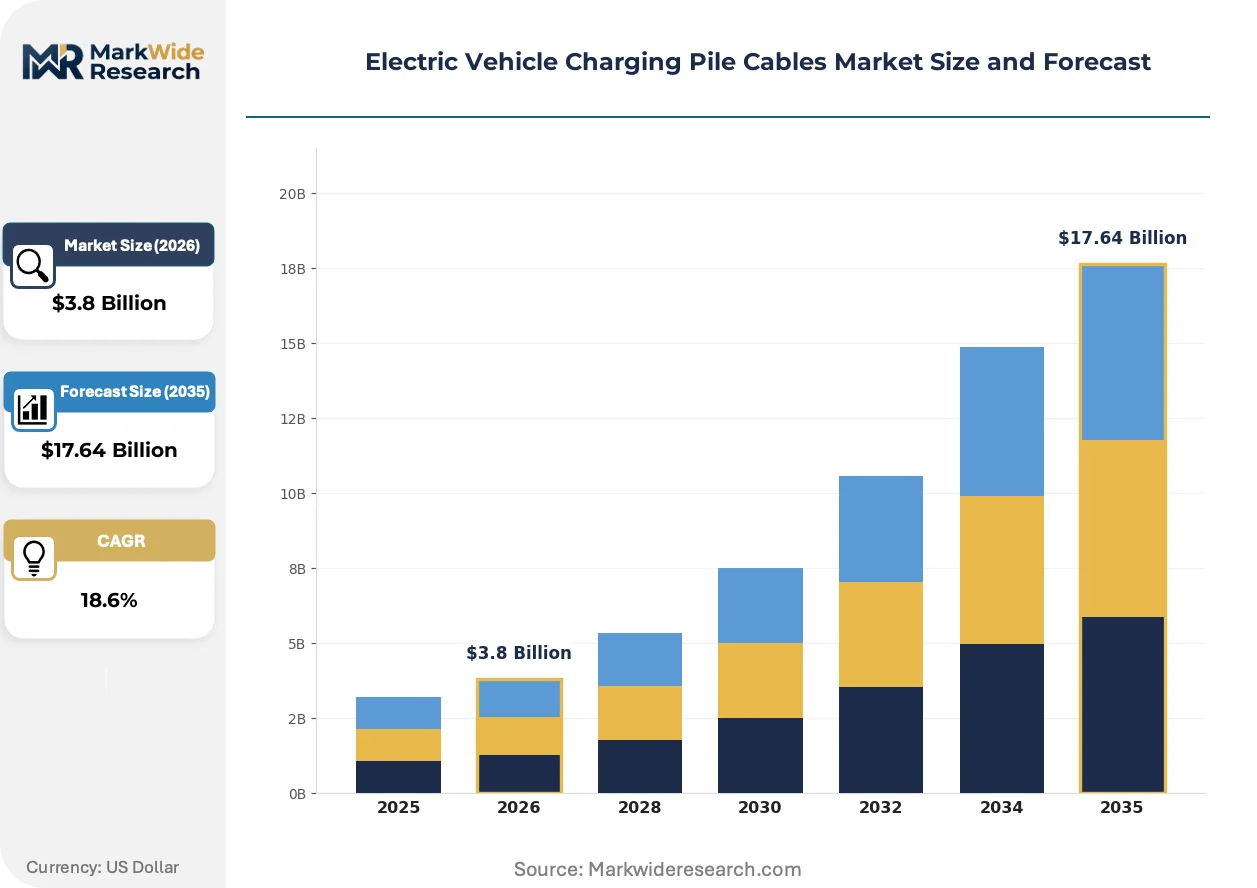
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Charging Cable, DC Fast Charging Cable, Type 1 Cable, Type 2 Cable, Combined Charging System Cable Technology: Conductive, Inductive, Wireless, Ultra-fast Charging, Smart Cable Application: Residential Charging Stations, Commercial Parking Lots, Public Charging Stations, Fleet Depots, Workplace Charging End User: EV Fleet Operators, Vehicle Dealerships, Charging Network Providers, Property Management Firms |
| Companies Covered | Phoenix Contact, Aptiv, Leoni AG, TE Connectivity, Prysmian, BESEN International Group, Sinbon Electronics, Coroplast Group, Huber+Suhner, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Charging Pile Cables Market Trends and Innovations
Charging infrastructure is fragmenting across power levels and use cases, forcing cable architectures to modularize around thermal performance tiers rather than standardized designs. This technical diversification is reshaping R&D allocation and manufacturing flexibility requirements.
Silicon carbide power semiconductors are enabling higher-efficiency energy conversion in charging inverters. Charge point operators deploying 350kW+ systems are specifying cables with enhanced electromagnetic compatibility layers. This semiconductor transition is decentralizing thermal management responsibility from centralized cooling systems toward distributed cable-integrated solutions.
The EU AI Act classification requirements are extending to intelligent cable systems with embedded diagnostics. Manufacturers must now document algorithmic transparency for thermal prediction models to secure CE marking. European network operators are prioritizing sensor-enabled cable procurement to satisfy emerging conformity assessment obligations.
Fleet procurement teams are consolidating cable sourcing through multi-year framework agreements with integrated installation services. Traditional component distributors are losing share to turnkey infrastructure providers bundling hardware, commissioning, and maintenance. This bundling concentration is most visible in Germany and the Netherlands where large fleet electrification programs are consolidating supplier relationships.
Electric Vehicle Charging Pile Cables Market Segmentation
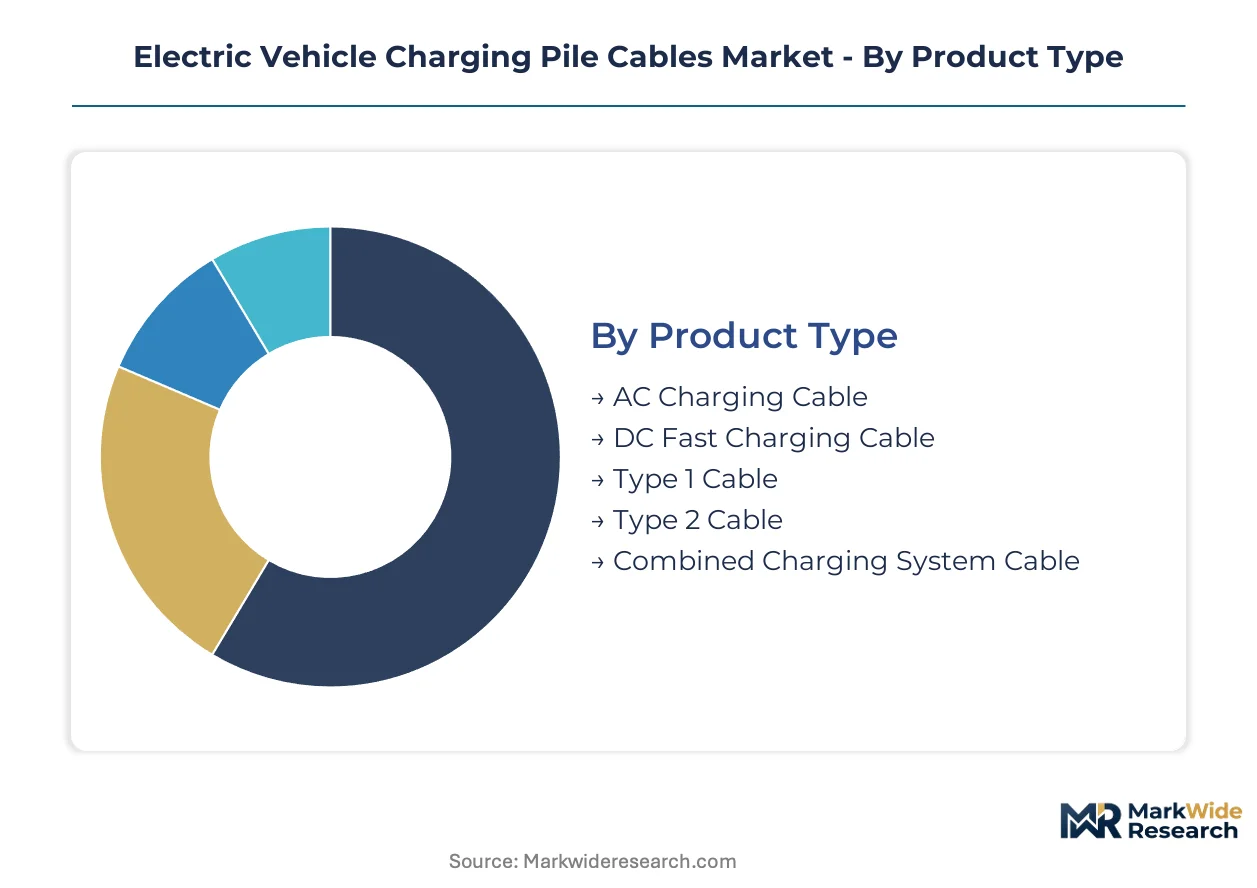
Charging pile cable procurement cycles vary sharply across power levels and use environments. Fleet operators and charge point networks prioritize different thermal specifications, insulation ratings, and connector geometries based on duty intensity and dwell time requirements.
Product Type:
Upgrade cycles accelerate as 350kW+ deployments force specification jumps across European and Chinese networks.
- AC Charging Cable:These assemblies carry single-phase or three-phase alternating current up to 22kW, incorporating thermoplastic elastomer insulation for residential and workplace durability. Demand clusters in Germany and France where overnight home charging dominates private EV ownership.
- DC Fast Charging Cable:Liquid-cooled conductor bundles rated for 500A+ continuous operation enable sub-20-minute charging sessions. Fleet depot operators in California and Guangdong province are pulling these assemblies for high-throughput logistics applications.
- Type 1 Cable:Single-phase connectors meeting SAE J1772 specifications serve legacy vehicle parcs primarily in Japan and parts of North America.
- Type 2 Cable:IEC 62196-2 compliant three-phase connectors anchor European public charging infrastructure deployment.
- Combined Charging System Cable:Integrated AC/DC connectors reduce port complexity for multi-standard vehicle compatibility across German and South Korean manufacturing.
DC Fast Charging Cable sits at the top of the volume ranking, with Combined Charging System Cable climbing the fastest.
Technology:
Cost tiers separate mature conductive architectures from emerging premium categories commanding installation premiums.
- Conductive:Physical conductor-insulation assemblies dominate installed base economics. Chinese GB/T 33594 certified production lines in Jiangsu and Zhejiang provinces supply the majority of global volume.
- Inductive:Resonant magnetic coupling eliminates connector wear for automated fleet applications. Limited deployment in controlled environments like Singapore autonomous taxi trials.
- Wireless:Dynamic charging strips embedded in roadways remain pilot-scale with regulatory validation gaps.
- Ultra-fast Charging:Cables rated for 600kW+ peak loads with active cooling loops are entering validation with Porsche and Hyundai test fleets.
- Smart Cable:Embedded powerline communication and thermal sensors enable dynamic load balancing. EU AI Act conformity requirements are accelerating procurement specifications for these assemblies in Netherlands and Denmark.
Conductive technology captures the highest absolute volume, while Smart Cable expands most quickly on network operator digitization mandates.
Application:
Customer type fragmentation separates low-utilization residential installs from high-cycle commercial duty.
- Residential Charging Stations:Lower-amperage tethered or detachable cables serve single-vehicle overnight charging. Norwegian and Swedish housing associations are standardizing Type 2 socket installations in new construction.
- Commercial Parking Lots:Retail and hospitality operators specify mid-power AC and 50kW DC cables for dwell-time charging. Shopping center deployments in France and Italy are pulling mixed AC/DC infrastructure.
- Public Charging Stations:Highway corridor operators prioritize liquid-cooled DC fast charging cables for 350kW+ hubs. Germany's Autobahn fast-charging network is consolidating procurement around CCS2 configurations.
- Fleet Depots:Municipal bus and logistics operators demand high-duty-cycle cables with predictive maintenance interfaces. Amazon's European delivery hubs in UK and Germany are specifying 150kW+ depot infrastructure.
- Workplace Charging:Employer-sponsored installations favor 11-22kW AC cables with load management for parking structure electrical capacity constraints.
Public Charging Stations lead deployment volume, with Fleet Depots gaining share fastest on electrification deadlines.
End User:
Procurement scale and technical sophistication diverge sharply across buyer categories.
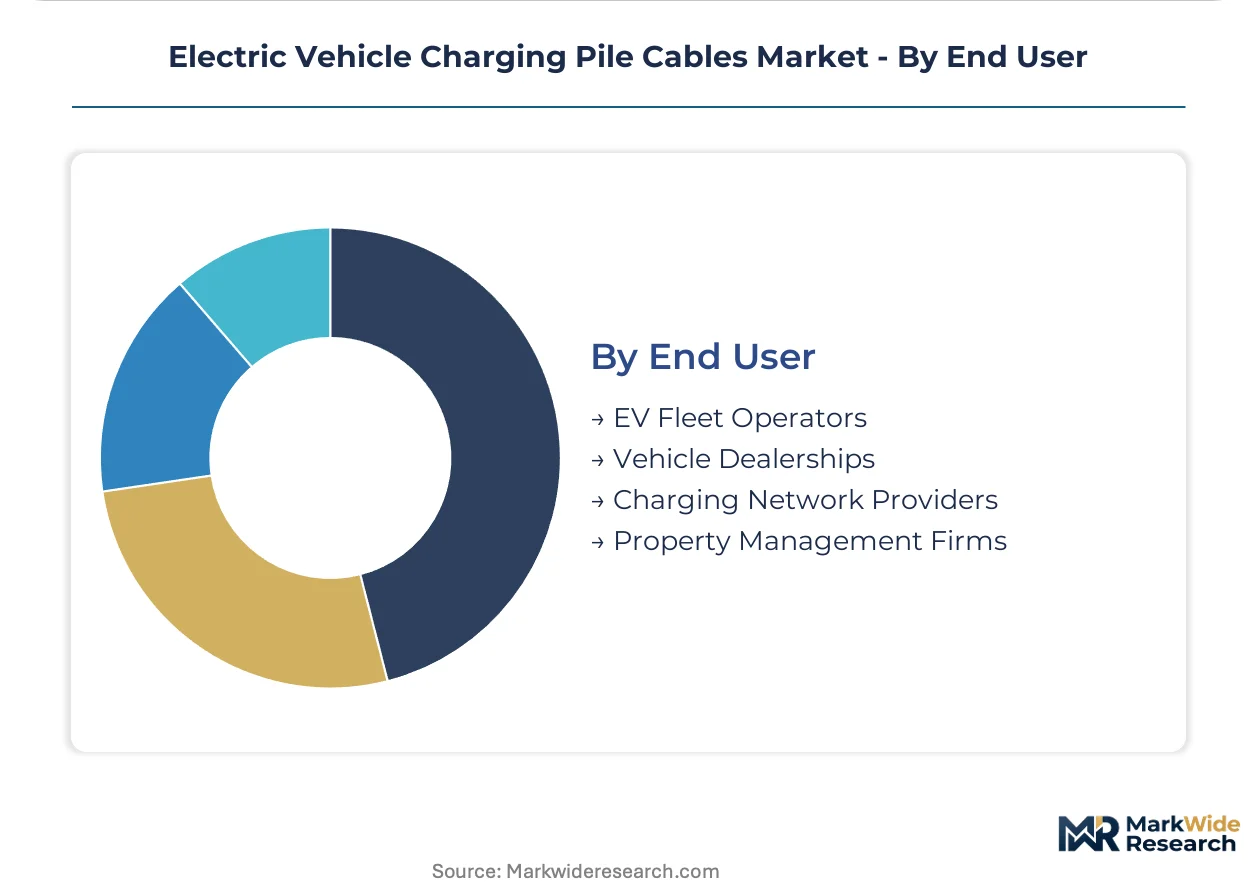
- EV Fleet Operators:Logistics and transit agencies negotiate multi-year framework agreements bundling cables, installation, and maintenance. DHL and Deutsche Post contracts in Germany are consolidating supplier relationships.
- Vehicle Dealerships:OEM-aligned retailers install demonstration and customer charging with standardized cable configurations tied to brand vehicle specifications.
- Charging Network Providers:Ionity, Fastned, and equivalent operators specify cables for 99.5%+ uptime targets with remote thermal monitoring.
- Property Management Firms:Commercial real estate owners deploy tenant-serving infrastructure with lower utilization profiles and longer payback horizons.
Charging Network Providers sit at the top of the volume ranking, with EV Fleet Operators climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The electric vehicle charging pile cables industry traces its industrial roots to Germany's automotive electrification programs of the early 2010s, where original equipment manufacturers first standardized high-voltage interconnect architectures for mass-market battery electric vehicles.
China
State Grid Corporation's ultra-high voltage transmission expansion and MIIT-mandated NEV penetration targets are pulling specialized cable orders from Jiangsu and Zhejiang production clusters. GB/T 33594 standards establish mandatory performance thresholds that directly shape export-oriented manufacturer specifications. Shenzhen and Shanghai anchor domestic demand concentration as municipal governments accelerate public charging corridor deployment.
Germany
Autobahn fast-charging network consolidation and DHL fleet electrification deadlines are compressing procurement cycles for liquid-cooled 350kW+ assemblies. EU Green Deal ICE phase-out mandates through KBA enforcement accelerate cable specification upgrades toward thermally resilient designs. Bavaria and Baden-Württemberg concentrate manufacturing scale across Leoni AG and Phoenix Contact production footprints.
United States
California Air Resources Board zero-emission vehicle mandates and Amazon's logistics depot electrification are driving high-duty-cycle cable demand. FCC electromagnetic compatibility guidelines govern charging equipment deployment across interstate highway corridors. Texas and Michigan emerging as secondary demand clusters on fleet operator infrastructure buildouts.
Netherlands
Fastned and Ionity network expansion across Randstad urban corridors prioritizes 99.5% uptime specifications with remote thermal monitoring capabilities. EU AI Act conformity assessment obligations for intelligent cable systems accelerate sensor-enabled procurement mandates. Eindhoven Region concentrates testing and validation infrastructure for next-generation communication-enabled assemblies.
India
PLI scheme domestic manufacturing incentives for electric vehicle components are opening localized cable production opportunities for export-oriented suppliers. Bureau of Indian Standards certification alignment with IEC frameworks reduces multi-market validation friction. Maharashtra and Gujarat emerging as contract manufacturing destinations on port proximity and automotive supplier ecosystem density.
Electric Vehicle Charging Pile Cables Market Competitive Landscape
Premium-margin players sit above commodity-margin players across thermal performance and certification complexity tiers, with liquid-cooled DC fast charging architectures commanding installation premiums against standard AC conductive assemblies. The vendor base stratifies between integrated interconnect specialists, diversified cable conglomerates, and regionally focused contract manufacturers. Three archetypes dominate: heritage industrial connector firms leveraging electromagnetic compatibility expertise, scaled conductor manufacturers optimizing across multiple geometries, and emerging Asia-Pacific fabricators capturing volume on state-backed infrastructure programs. Capacity expansion and backward integration into conductor and insulation material supply represent the dominant competitive moves across tier one and tier two positions.
Among heritage European interconnect specialists, Phoenix Contact and Leoni AG exemplify premium-tier positioning through decades of industrial automation and automotive cable heritage. TE Connectivity occupies a position bridging industrial connector expertise with sensor-integrated cable architectures. Huber+Suhner represents the specialized RF and high-frequency electromagnetic shielding archetype that SiC inverter deployment is elevating in procurement priority. BESEN International Group and Sinbon Electronics sit within the Asia-Pacific volume manufacturing tier, with geographic naming conventions indicating Chinese and Taiwanese origins respectively.
| Leading Market Players |
|---|
| Phoenix Contact |
| Aptiv |
| Leoni AG |
| TE Connectivity |
| Prysmian |
| BESEN International Group |
| Sinbon Electronics |
| Coroplast Group |
| Huber+Suhner |
| Others |
Pricing and Supply Chain Analysis
Specialized high-voltage cable engineering talent concentrates in Bavaria and Baden-Württemberg, where labor-cost differentials between German engineering centers and Chinese manufacturing zones drive 40-60% pricing-tier spreads across equivalent thermal performance ratings.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement negotiations, with premium tiers commanding spreads based on IEC 62893 certification grade and integrated sensor diagnostics versus commodity GB/T 33594-aligned supply. Cost compression in standard conductive assemblies is intensifying because Jiangsu and Zhejiang manufacturers are scaling capacity faster than European demand absorption. Fleet operators exhibit lowest price sensitivity due to uptime penalties, while property management firms resist premium tier migration on extended payback horizons.
Supply Chain Analysis
Single-source vulnerability sits with Chinese conductor and liquid-cooled insulation material supply, where GB standards-aligned production clusters in Jiangsu and Zhejiang feed 70% of global cable assembly demand. Raw material dependencies center on LME-grade copper cathodes, thermoplastic elastomer compounds, and liquid cooling loop components. Tariff exposure on cross-border component flows compounds geographic concentration risk. Distribution runs through integrated infrastructure providers bundling hardware, commissioning, and maintenance services, displacing traditional component distributors in Germany and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, justified by fleet procurement teams consolidating around 350kW+ liquid-cooled specifications with embedded thermal monitoring and predictive maintenance interfaces.
For Market Incumbents: Anchor premium positioning through captive supply of liquid-cooled conductor bundles and backward integration into thermoplastic elastomer compounding, defending against emerging Asia-Pacific fabricators capturing volume on state-backed infrastructure programs. Prioritize IEC 62893 and UL 2251 dual-certification investment to compress multi-market launch timelines and sustain margin tiers. For New Entrants and Emerging Players: Municipal bus fleet operators in India and Southeast Asia represent an underserved buyer archetype with limited incumbent relationship density and urgent electrification deadlines under national ICE phase-out mandates. Pursue Bureau of Indian Standards certification alignment with IEC frameworks to reduce validation friction, then leverage PLI scheme manufacturing incentives for localized production cost parity. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier conductive cable manufacturers lacking liquid-cooled architecture capabilities or sensor-integrated product pipelines. Long-term viability favors targets with demonstrated 500A+ continuous load validation and established relationships with charge point operators targeting 99.5% uptime specifications. Monitor silicon carbide inverter deployment velocity as the inflection indicator for electromagnetic shielding procurement priority shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Insulation Compounding | Captive supply of thermoplastic elastomer compounds insulates margin tiers from petrochemical feedstock volatility. |
| Dual-Certification Investment (IEC 62893 + UL 2251) | Simultaneous compliance compresses validation timelines for multi-market product launches across European and North American networks. |
| Liquid-Cooled Architecture Scale-Up | 500A+ continuous load capability addresses fleet operator dwell-time reduction mandates and commands installation premiums. |
| Sensor-Enabled Smart Cable Development | Embedded powerline communication satisfies EU AI Act conformity assessment obligations for intelligent cable systems in Netherlands and Denmark. |
| India PLI Scheme Manufacturing Localization | Maharashtra and Gujarat production footprint captures domestic manufacturing incentives and reduces tariff exposure on export-oriented supply. |
Research Methodology
Coverage spans China, Germany, the United States, the Netherlands, and India, with primary inputs from each region combining structured interviews with charge point operator procurement directors, fleet infrastructure managers, cable assembly plant engineers, and regulatory compliance officers with secondary validation from MIIT directive filings, KBA enforcement protocols, FCC electromagnetic compatibility guidelines, EU AI Act conformity assessment documentation, and Bureau of Indian Standards certification frameworks. Bottom-up and top-down triangulation cross-references production capacity announcements, import-export customs records, and infrastructure deployment databases.
Granularity-level framing models volume and value outputs at power level tier, cooling architecture type, certification standard cluster, and end-user procurement scale across the analysis window. CAGRs derive from segment-specific adoption curves weighted by fleet electrification deadlines, NEV penetration targets, and public charging corridor buildout schedules. Forecast inputs incorporate silicon carbide inverter deployment trajectories and liquid-cooled reliability validation milestones.
Underlying measurement precision varies by segment; DC fast charging cable and smart cable categories carry tighter precision than legacy AC conductive assemblies due to concentrated supplier disclosure and visible procurement contract values. Forecasts reflect documented assumptions regarding infrastructure subsidy continuity, copper price band stability, and cross-standard harmonization progress, with outcomes best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Integrated EV Chargers Market
Electric Vehicle Charging
Public EV Charging Pile Market
Electric Vehicle Charging
Electric Two Wheeler Charging Station Market
Electric Vehicle Charging
DC Chargers Market
Electric Vehicle Charging
United States Electric Vehicle Charging Systems and Equipment Market
Electric Vehicle Charging
Sweden Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Charging Plugs Market
Electric Vehicle Charging
Solar Charge Controller Market
Electric Vehicle Charging
Electric Vehicle Charger Market
Electric Vehicle Charging
Portable EV Charger Market
Electric Vehicle Charging
E-Bike Charging Station Market
Electric Vehicle Charging
APAC Electric Vehicle Charging Station Market
Electric Vehicle Charging
Electric Bus Charging Infrastructure Market
Electric Vehicle Charging
Pantograph Charger Market
Electric Vehicle Charging
Australia Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Japan Electric Vehicles (EV) Charging Equipment Market