
 Renewable Energy Inverters Market | 2026-2036
Renewable Energy Inverters Market Size, Share, and Industry Trends Forecast 2026-2036
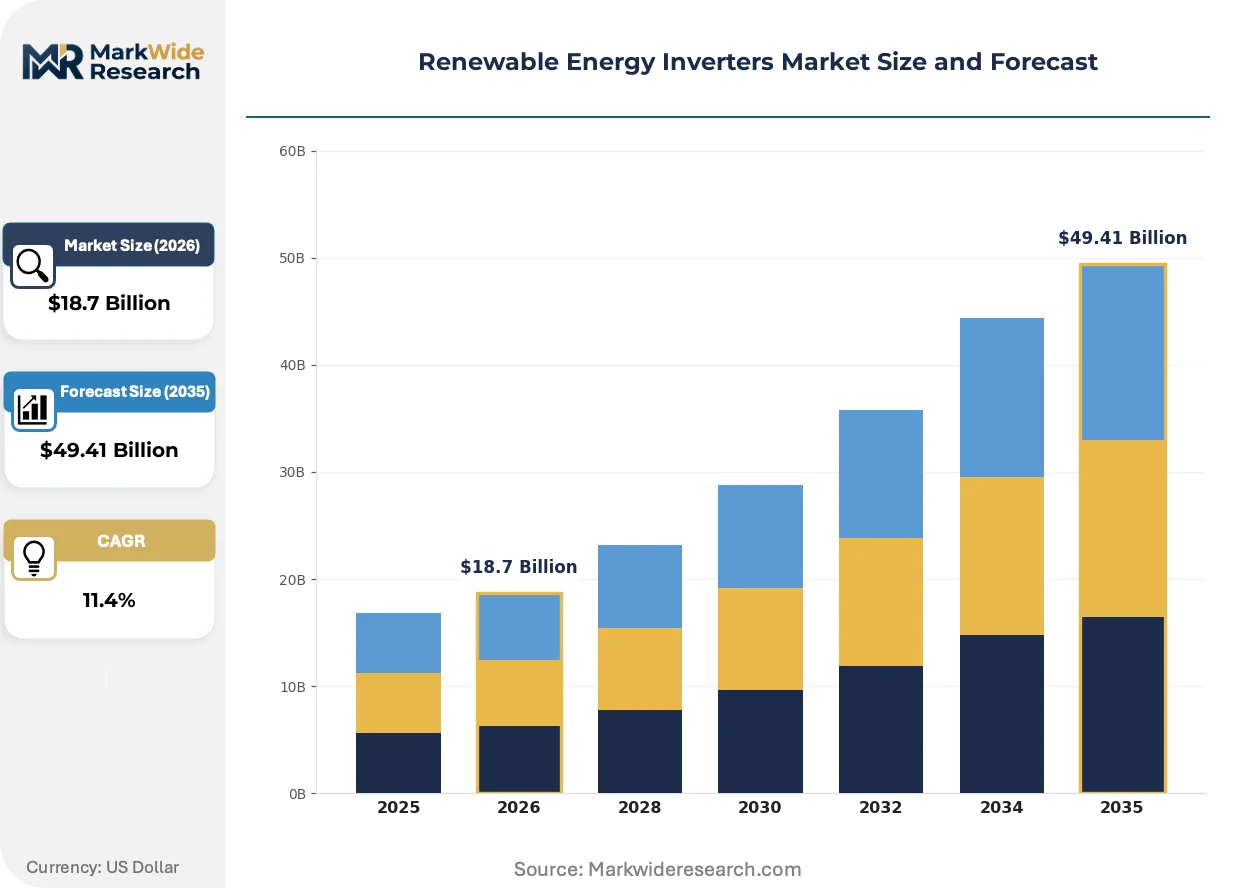
Renewable Energy Inverters Market Outlook
Aftermarket service revenue is tilting from hardware replacement toward predictive analytics and remote monitoring contracts. Huawei Technologies Co., Ltd. leverages its digital power platform to bundle inverter sales with cloud-based O&M services. Sungrow anchors its position through vertically integrated manufacturing of power semiconductors and energy storage systems. SMA Solar Technology AG competes on European brand strength and channel control through certified installer networks.
Renewable energy inverters are power electronic devices that convert direct current generated by solar panels or wind turbines into alternating current synchronized to grid frequency, typically operating at efficiency thresholds above 98% in utility-scale string and central configurations. Their primary purpose is enabling grid interconnection while providing voltage regulation, fault ride-through, and reactive power support. String inverters dominate residential and commercial rooftop segments where modularity and rapid shutdown compliance offset higher per-watt costs. Central inverters sustain margin pools in utility-scale ground-mounted installations above 100 MW where economies of scale compress balance-of-system expenses. Hybrid inverters represent the fastest-growing product category as battery-based multi-mode technology penetrates markets with time-of-use tariffs or weak grid infrastructure.
IEC 61727 and IEEE 1547 shape grid-tied inverter design through anti-islanding requirements and voltage-frequency ride-through parameters that manufacturers must certify before market access. India's CEA mandates stringent fault response standards for utility-scale solar plants, while the EU Green Deal's F-Gas Regulation indirectly pressures inverter cooling system design away from conventional refrigerants. Stakeholders must monitor how silicon carbide device costs and regional content requirements under India's PLI scheme reshape sourcing decisions and competitive positioning.
Market Dynamics
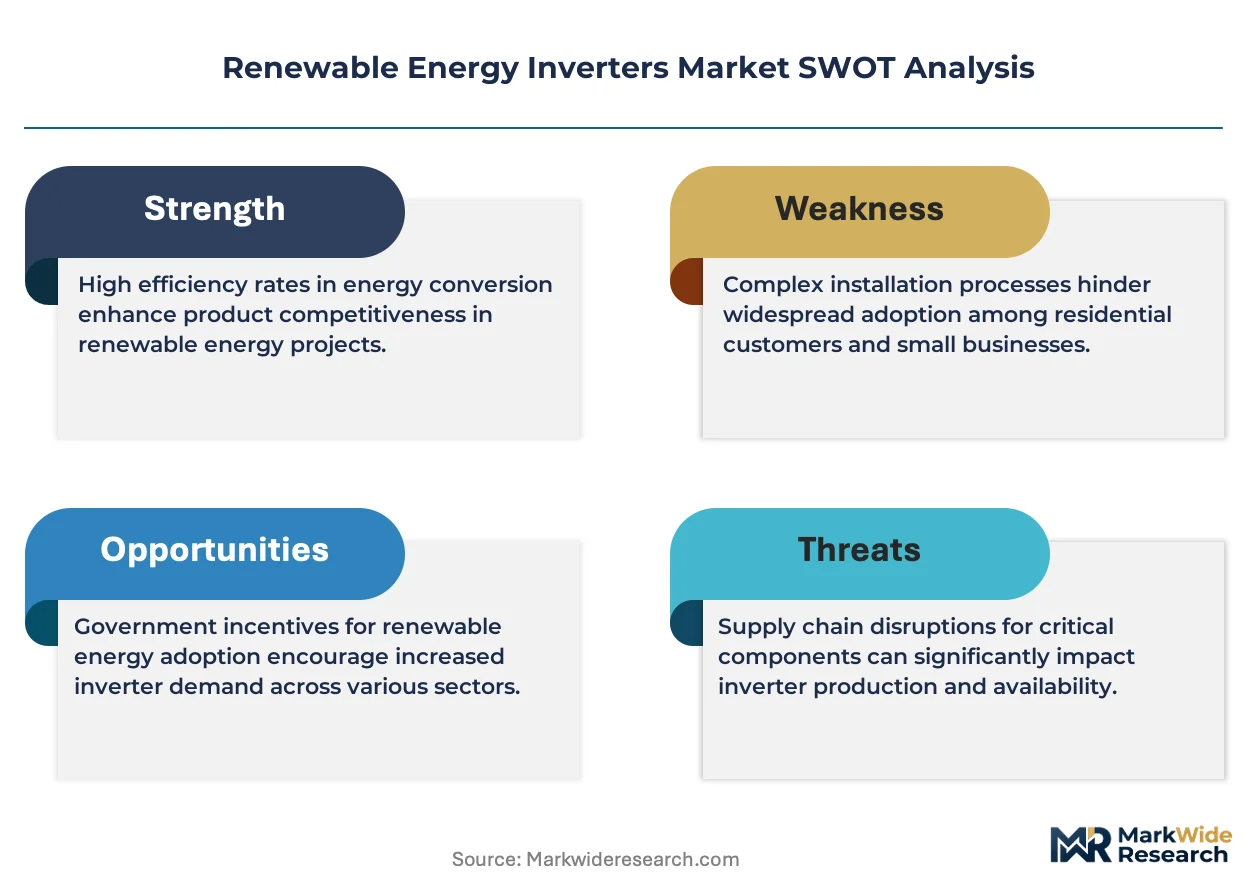
Silicon carbide power semiconductors are compressing switching losses and thermal management costs, forcing incumbent silicon-based designs into obsolescence across utility-scale procurement tenders.
Growth Catalysts
- India's PLI scheme for solar components:Domestic manufacturing incentives are redirecting inverter assembly capacity from Southeast Asian contract manufacturers to Gujarat and Tamil Nadu production clusters.
- IEC 61727 grid synchronization standards:Harmonized anti-islanding and fault ride-through requirements are unlocking cross-border equipment certification, reducing re-engineering costs for multi-market suppliers.
- Utility-scale battery co-location:Hybrid inverter architectures serving solar-plus-storage projects are capturing procurement preference in markets with evening peak demand tariffs.
Market Restraints
- Silicon carbide substrate shortage:Wolfspeed and Coherent's concentrated 6-inch SiC wafer supply creates allocation bottlenecks for inverter power module manufacturers.
- EU F-Gas Regulation compliance costs:Conventional refrigerant-based thermal management systems face phase-out timelines, forcing cooling system redesigns without mature alternative supply chains.
- Central inverter technical ceiling:Maximum power density limits and transformer coupling losses constrain efficiency gains above 99% in multi-megawatt configurations.
Strategic Opportunities
- Vietnam rooftop solar revival:Feed-in tariff restoration and net metering implementation are reactivating residential string inverter demand after 2020-2022 policy suspension.
- Digital twin integration:Cloud-based inverter performance modeling converging with SCADA systems enables predictive O&M contracts as separate revenue streams.
- US IRA domestic content bonuses:Adder incentives for projects using North American-assembled inverters are reshaping procurement evaluation criteria for utility-scale developers.
Industry Challenges
- Power electronics engineering scarcity:Specialized magnetics design and EMC compliance expertise concentrates in Germany, Japan, and China's eastern provinces, constraining talent acquisition for new market entrants.
- Multi-certification timeline compression:Simultaneous IEC, IEEE 1547, and country-specific grid code approvals extend product launch cycles by 8-14 months.
- Legacy string inverter fleet retrofit complexity:Rapid shutdown device integration with pre-2017 installed capacity requires custom engineering without standardized communication protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renewable Energy Inverters Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: String Inverters, Central Inverters, Micro Inverters, Hybrid Inverters Technology: Grid-Tied, Off-Grid, Battery-Based, Multi-Mode End User: Residential, Commercial, Industrial, Utility Installation Type: Rooftop, Ground-Mounted, Building Integrated, Floating |
| Companies Covered | Huawei Technologies Co., Ltd., Sungrow, SMA Solar Technology AG, Enphase Energy, SolarEdge Technologies, Ginlong Technologies, Power Electronics, Fimer Group, GoodWe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renewable Energy Inverters Market Strategic Shifts
Power semiconductor materials, grid interconnection standards, and procurement contracting models are simultaneously evolving, creating discontinuities in established competitive positions.
Silicon carbide MOSFETs replace silicon IGBTs in high-frequency switching applications, cutting thermal losses by one-third. Utility-scale developers in India and the US are specifying SiC-based string inverters for 1500V DC systems. The technology is migrating from premium niche deployments toward mainstream procurement specifications as device costs approach silicon parity at 100kW+ power classes.
The EU Green Deal's F-Gas Regulation mandates refrigerant phase-down in cooling systems, indirectly pressuring inverter thermal design. Manufacturers are engineering liquid-cooled and passive convection alternatives to replace conventional HVAC-dependent architectures. European utility-scale projects now prioritize inverter platforms with F-Gas-compliant thermal management to avoid retrofit liability.
Asset owners are unbundling inverter supply from long-term O&M contracts, creating separate competitive arenas. Procurement teams evaluate hardware on capex and warranty terms while operations groups select digital service providers for performance optimization. This bifurcation is most pronounced in Australia's utility-scale solar fleet, where independent power producers maintain multi-vendor inverter parks under unified monitoring platforms.
Renewable Energy Inverters Market Segmentation
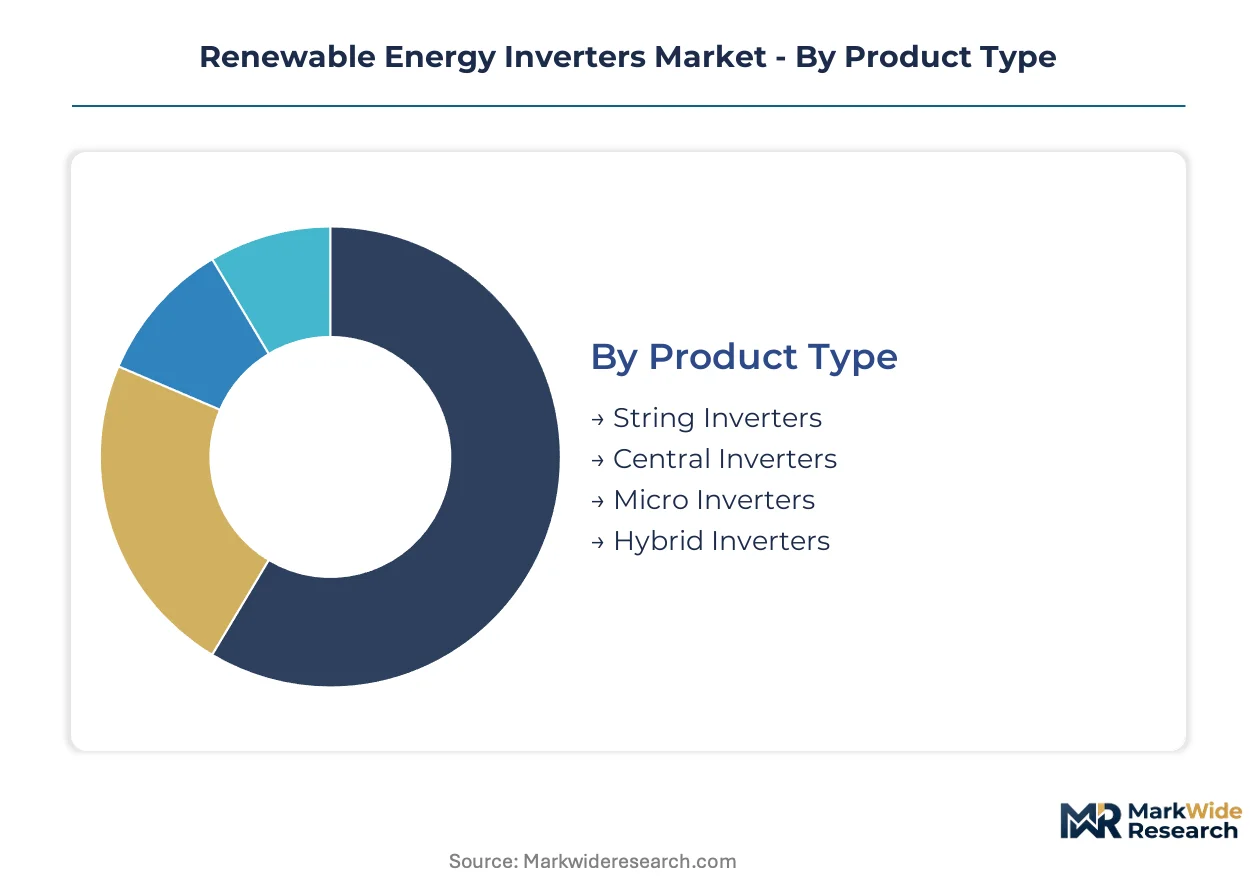
Renewable energy inverter procurement cycles vary dramatically by deployment scale, with residential string units turning over every 7-10 years while utility central inverters operate for 15-20 years. Segment-specific technology roadmaps and regulatory compliance timelines create divergent competitive dynamics across product architectures.
Product Type:
Replacement cycles compress toward string and micro inverter formats while central inverter deployments extend asset life through modular retrofit strategies.
- String Inverters:Modular DC-to-AC conversion units rated 1-150kW deploy with individual panel-level optimization and rapid shutdown compliance. India's residential rooftop programs in Gujarat and Maharashtra concentrate procurement volume under the country's net metering regulations. IEC 61727 certification requirements extend product development timelines for multi-market suppliers.
- Central Inverters:Large-scale conversion systems above 500kW serve utility ground-mounted installations with transformer-coupled output and centralized SCADA integration. India's CEA mandates stringent fault ride-through standards for plants above 5MW, favoring established European and Chinese suppliers with proven grid compliance records. Silicon carbide module adoption is compressing thermal losses below 1% in next-generation designs.
- Micro Inverters:Panel-mounted units eliminate string-level mismatch losses through independent MPPT tracking per module.
- Hybrid Inverters:Multi-mode architectures integrate battery charge control with grid-tied and off-grid operation.
String inverters anchor the volume base while hybrid inverters gain share at the steepest rate.
Technology:
Cost tiers stratify sharply between basic grid-tied functionality and premium multi-mode capabilities with islanding support.
- Grid-Tied:Synchronized inverters without energy storage interface dominate utility-scale procurement where grid stability permits direct export. India's utility solar auctions specify grid-tied architectures for projects above 100MW to minimize balance-of-system complexity.
- Battery-Based:DC-coupled storage integration enables time-shifting and backup power through shared power electronics. Australia's time-of-use tariff structures in New South Wales and Victoria concentrate residential demand for battery-ready inverter platforms.
- Off-Grid:Standalone systems with integrated battery chargers serve remote installations without grid access.
- Multi-Mode:Seamless transition between grid-tied, off-grid, and battery modes through unified control firmware.
Grid-tied technology captures the largest installed base while battery-based systems climb the fastest.
End User:
Application requirements diverge across customer types, from residential safety compliance to utility-scale grid code certification burdens.
- Utility:Multi-megawatt procurement tenders specify 1500V DC input, remote monitoring integration, and 25-year service life guarantees. India's NTPC and SECI auctions concentrate annual procurement volume under national solar mission targets.
- Residential:Single-phase and small three-phase units below 20kW prioritize rapid shutdown compliance, arc fault detection, and installer-friendly commissioning. Vietnam's restored feed-in tariff program is reactivating rooftop demand after policy suspension.
- Commercial:Three-phase string and small central inverters serve 20kW-1MW rooftop and carport installations.
- Industrial:Large commercial-grade systems with power factor correction and harmonics filtering for manufacturing loads.
Utility procurement anchors manufacturer revenue while residential demand expands most quickly.
Installation Type:
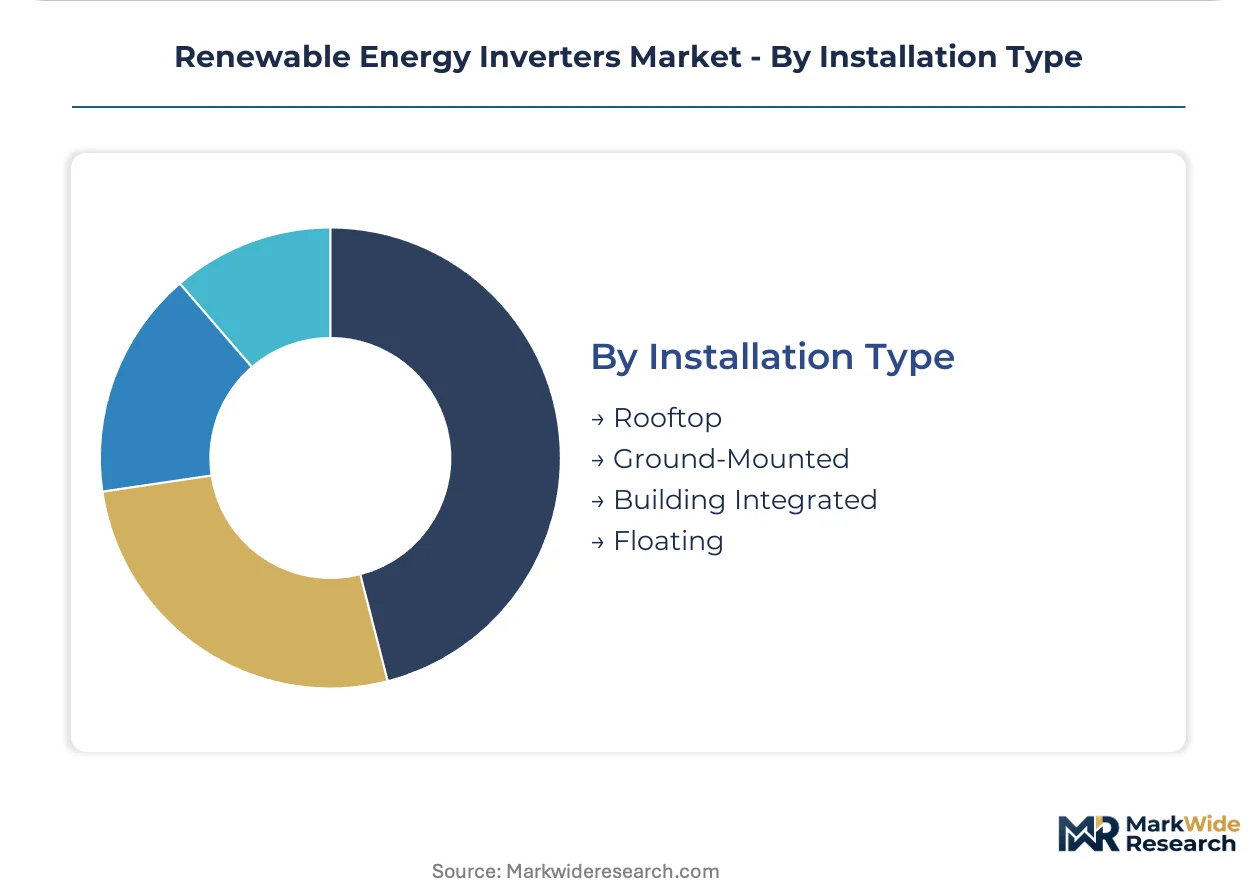
Volume concentrates in ground-mounted utility formats while emerging floating and building-integrated segments command premium positioning.
- Ground-Mounted:Utility-scale fixed-tilt and tracking arrays above 10MW dominate inverter procurement volume through standardized electrical design. India's Rajasthan and Gujarat solar parks concentrate central inverter deployment under national renewable energy targets.
- Rooftop:Residential and commercial building-mounted systems drive string inverter specifications with rapid shutdown and module-level monitoring. Australia's distributed generation market maintains multi-vendor inverter parks under unified monitoring platforms.
- Building Integrated:Architectural PV integration with custom inverter sizing for facade and skylight applications.
- Floating:Water-mounted installations requiring corrosion-resistant enclosures and elevated cooling design.
Ground-mounted deployment anchors procurement volume while floating installations gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exhibits the highest price elasticity as domestic manufacturing incentives compress procurement costs, while Germany and Japan sustain premium positioning through advanced SiC integration and grid-code certification rigor.
India
Utility-scale solar auctions under NTPC and SECI concentrate annual procurement volume above 100 MW. CEA mandates stringent fault ride-through standards for plants exceeding 5 MW. Gujarat and Tamil Nadu production clusters are capturing inverter assembly capacity redirected from Southeast Asian contract manufacturers under PLI scheme incentives.
United States
IRA domestic content bonuses are reshaping procurement evaluation criteria for utility-scale developers specifying North American-assembled hardware. FERC interconnection standards and IEEE 1547 certification requirements govern grid-tied deployment. Texas and California solar parks anchor central inverter procurement through independent power producer tenders.
Germany
EU Green Deal F-Gas Regulation compliance is pressuring thermal management redesigns away from conventional refrigerant-based cooling systems. CE marking and IEC 61727 harmonization enable cross-border equipment certification. Bavarian engineering clusters concentrate power electronics expertise for magnetics design and EMC compliance.
China
Dual carbon goals are accelerating utility-scale deployment across western provinces with high solar irradiance. GB standards and MIIT industrial policy guide domestic inverter specifications. Yangtze River Delta manufacturing bases integrate vertically from power semiconductor wafer production through final assembly.
Australia
Time-of-use tariff structures in New South Wales and Victoria concentrate residential demand for battery-ready hybrid inverter platforms. CEC certification requirements govern grid connection approval. Distributed generation markets maintain multi-vendor inverter parks under unified SCADA monitoring platforms operated by independent power producers.
Renewable Energy Inverters Market Competitive Environment
Vertically integrated conglomerates and specialized power electronics firms split the market between scale-driven cost compression and technology-differentiated premium positioning. Concentration is moderate at the top tier with fragmentation across regional specialists and emerging SiC module integrators. Three archetypes dominate: Chinese integrated technology platforms with captive semiconductor supply, European engineering specialists with certified installer channel control, and emerging pure-play SiC power module vendors. Capacity expansion into Gujarat and Tamil Nadu production clusters and strategic partnerships for cloud-based O&M service bundling represent the dominant competitive vectors.
Among Chinese integrated platforms, Huawei Technologies Co., Ltd. and Sungrow occupy positions defined by backward integration into power semiconductors and energy storage systems. SMA Solar Technology AG exemplifies the European engineering specialist archetype with channel control through certified installer networks. These three anchors illustrate the structural divide between scale-driven manufacturing efficiency and premium-tier certification strength.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| Sungrow |
| SMA Solar Technology AG |
| Enphase Energy |
| SolarEdge Technologies |
| Ginlong Technologies |
| Power Electronics |
| Fimer Group |
| GoodWe |
| Others |
Value Chain & Pricing Dynamics
Yantian-Singapore-Jebel Ali shipping corridors carry silicon carbide substrates and power semiconductor modules from Yangtze River Delta foundries to inverter assembly plants in Gujarat and Tamil Nadu, with freight cost volatility compressing margins on economy-tier string inverters while premium central inverter producers absorb logistics premiums through captive semiconductor supply.
Pricing Analysis
Extended warranty and predictive maintenance contracts now drive lifetime value beyond hardware margins. Three-tier pricing structure across premium SiC-integrated, standard silicon-based, and economy-grade string configurations stratifies procurement evaluation. Cost compression in utility-scale tenders intensifies as India's PLI scheme subsidizes domestic assembly. Residential rooftop buyers in Vietnam and Australia exhibit highest price sensitivity, while utility developers prioritize grid-code certification over per-watt economics.
Supply Chain Analysis
6-inch silicon carbide wafers from Wolfspeed's North Carolina facilities and Coherent's European foundries feed power module manufacturers in China and Germany. Magnetics cores from Japanese suppliers and aluminum enclosures from Vietnamese extruders complete bill-of-materials. Single-source vulnerability concentrates in SiC substrate allocation, where Wolfspeed and Coherent control capacity expansion timelines. Distribution runs through EPC contractors and certified installer networks rather than direct OEM-to-utility sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-moat business where CEA fault-ride-through certification and IEC 61727 harmonization create switching costs that entrench incumbents with multi-year approval timelines.
For Market Incumbents: Harden grid-code certification portfolios against emerging SiC pure-plays by accelerating IEC 61727 compliance for 1500V architectures. Expand captive power semiconductor supply through partnerships with Wolfspeed or Coherent to neutralize substrate allocation bottlenecks threatening margin compression in utility tenders.
For New Entrants and Emerging Players: Establish a beachhead in Vietnam's reactivated residential rooftop segment where feed-in tariff restoration creates demand without entrenched channel control. Target Australia's battery-ready hybrid inverter white space through CEC certification investment and cloud-based O&M bundling with independent power producers.
For Investors and Strategic Acquirers: Pure-play SiC power module integrators with proven 1500V designs represent the most defensible acquisition archetype as substrate supply constraints persist. Monitor India's PLI scheme capacity utilization rates as inflection indicator for domestic manufacturing economics versus Southeast Asian contract alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Module Integration | Wolfspeed substrate partnerships compress switching losses below 1% in utility-scale designs. |
| PLI Scheme Capacity Buildout | Gujarat and Tamil Nadu assembly clusters capture incentives redirecting from Southeast Asia. |
| Grid Code Certification Investment | CEA fault-ride-through approval unlocks NTPC and SECI auction participation above 5 MW. |
| Cloud-Based O&M Platform Launch | Huawei's digital power architecture bundles predictive analytics with hardware procurement. |
| F-Gas Compliant Thermal Redesign | Liquid-cooled architectures replace refrigerant-dependent systems for EU Green Deal compliance. |
Study Parameters
Initial hypotheses were tested against primary input from utility planning officers, IPP project developers, EPC contractors, and grid operators, and refined through secondary validation against EIA data, IEA reports, FERC filings, and project development databases. Bottom-up and top-down triangulation reconciled equipment procurement volumes with national renewable energy targets across the analysis window.
Demand-supply balance modeling segmented projections by product architecture, technology interface, end-user scale, and installation format throughout the forecast period. CAGRs derived from regression analysis of historical tender volumes and announced manufacturing capacity. Grid code harmonization timelines and SiC device cost curves served as industry-specific forecast inputs.
Stress conditions across substrate allocation bottlenecks, PLI scheme incentive duration, and F-Gas Regulation compliance deadlines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about technology substitution rates and regulatory enforcement intensity. Cross-checking against IEA renewable capacity deployment benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Israel Renewable Energy Market
Renewable Energy
North Europe Renewable Energy Market
Renewable Energy
Brazil Renewable Energy Market
Renewable Energy
East Africa Renewable Energy Market
Renewable Energy
Europe Biomethane Market
Renewable Energy
China Solar Energy Market
Renewable Energy
Turkey Renewable Energy Market
Renewable Energy
Composite Materials in Renewable Energy Market
Renewable Energy
Solar Chimney Market
Renewable Energy
Wave Energy Converter Market
Renewable Energy
West Africa Renewable Energy Market
Renewable Energy
East Asia Renewable Energy Market
Renewable Energy
Kazakhstan Renewable Energy Market
Renewable Energy
India Renewable Energy Market
Renewable Energy
Tunisia Renewable Energy Market
Renewable Energy
Solar Street Lighting Market