
 Asia-Pacific Airport Electric Vehicle Charging Station Market | 2026-2036
Asia-Pacific Airport Electric Vehicle Charging Station Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Airport Electric Vehicle Charging Station Market Analytics
Airport procurement channels for electric vehicle charging infrastructure is fragmenting as sovereign wealth funds, private operators, and municipal aviation bureaus establish separate technical specifications. ABB Ltd. leverages its high-power charging portfolio to anchor contracts across Southeast Asian hub expansions. Schneider Electric sustains competitive positioning through integrated energy management systems that bundle solar generation with charging assets. Delta Electronics Inc. specializes in compact thermal management for tropical climates, a critical parameter for outdoor installations across the region.
Asia-Pacific airport electric vehicle charging stations comprise power conversion systems, connector assemblies, and network management platforms engineered to deliver outputs from 7 kW Level 2 through 350 kW DC fast charging for commercial aviation ground fleets. Fast chargers command the dominant share of deployed capital as airlines electrify pushback tractors and baggage conveyors under narrow turnaround windows. Integrated stations represent the fastest-growing configuration, combining photovoltaic canopies with battery storage to shave peak demand charges for airport authorities operating on thin commercial margins. Wireless chargers remain nascent but attract pilot deployments from premium carriers seeking automated positioning for autonomous ground vehicles.
China's MIIT enforces GB/T connector standards and power quality requirements that shape hardware procurement for domestic airport expansions. Australia's CEA mandates grid interconnection protocols that influence inverter specifications for charging stations drawing from constrained regional substations. India's BIS certification requirements for electrical safety create compliance thresholds that filter import eligibility. Stakeholders must monitor evolving interoperability mandates between national charging standards as cross-border airline alliances pressure airports toward unified ground equipment specifications.
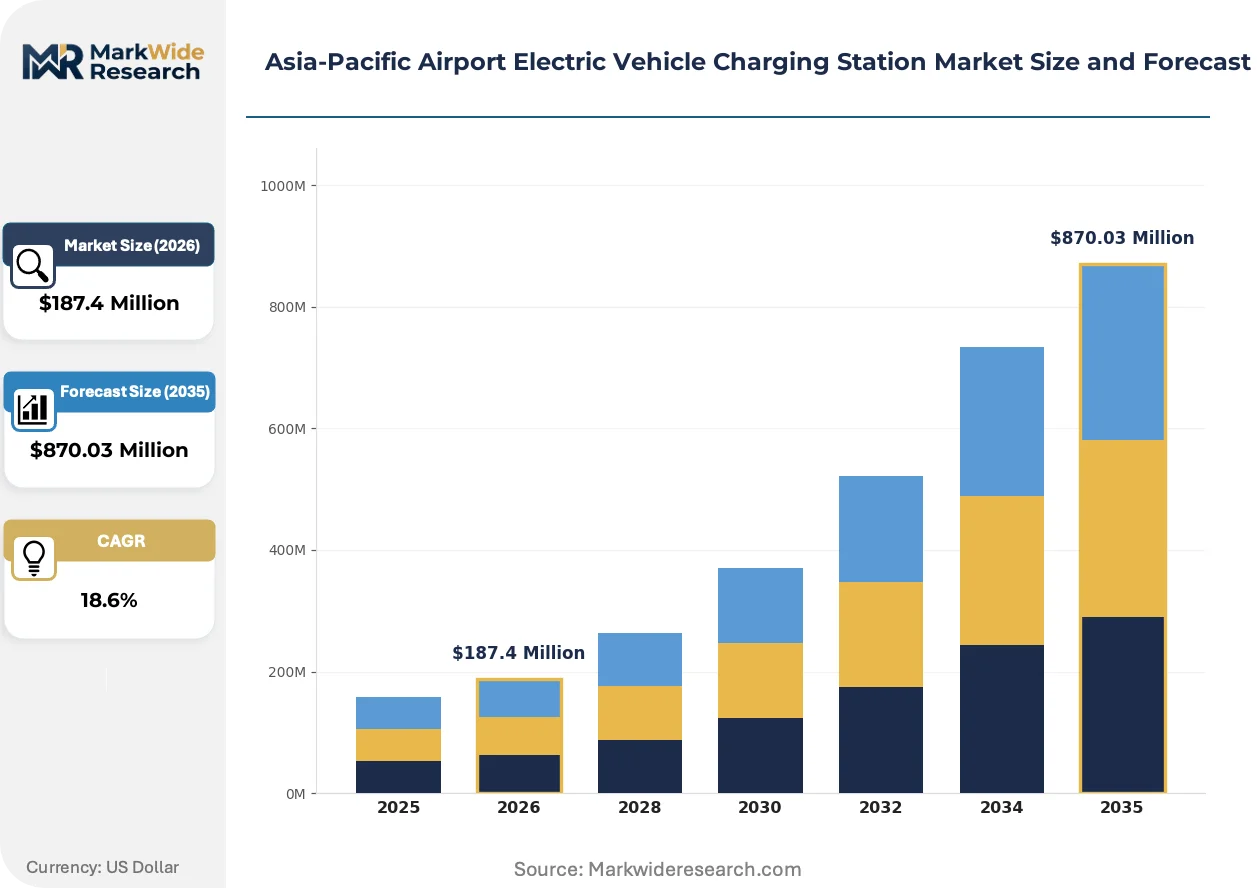
Market Dynamics
China's dual carbon goals and GB/T standard enforcement are compressing procurement timelines for airport authorities electrifying ground support equipment fleets across major aviation hubs.
Growth Catalysts
- GB/T Connector Mandates:China's MIIT enforces domestic charging interface standards that lock in hardware procurement for Beijing, Shanghai, and Guangzhou airport expansions, creating guaranteed demand pipelines for certified equipment suppliers.
- Pushback Tractor Electrification:Airlines face narrow turnaround windows that require 350 kW DC fast charging infrastructure to replace diesel ground fleets without operational disruption.
- Photovoltaic-Storage Bundling:Integrated stations combining solar canopies with battery buffers are shaving peak demand charges for airport authorities operating on thin commercial margins.
Market Restraints
- Copper and Silicon Carbide Volatility:Power conversion hardware faces input cost pressure from semiconductor substrate shortages and refined copper supply tightness concentrated in Chilean and Indonesian smelter networks.
- Regional Substation Constraints:Australia's CEA grid interconnection protocols limit charging station deployment at remote airports drawing from constrained distribution infrastructure in Western Australia and Queensland.
- Wireless Charging Technical Limits:Inductive power transfer systems suffer efficiency losses above 200 kW that prevent scaling to heavy baggage tractor applications requiring sustained high-current delivery.
Strategic Opportunities
- Vietnam and Philippines Greenfield Hubs:Emerging aviation markets lack legacy ground equipment fleets, enabling pure-electric infrastructure deployment without retrofit constraints at new Clark and Long Thanh airport developments.
- Autonomous Ground Vehicle Convergence:Premium carriers are piloting automated positioning systems that pair wireless charging pads with self-driving pushback units, eliminating connector wear and labor positioning costs.
- India PLI Scheme Tailwinds:Production-linked incentives for advanced chemistry cell manufacturing are reducing battery storage costs for integrated charging stations at Delhi and Mumbai airport expansions.
Industry Challenges
- High-Voltage Certification Bottlenecks:India's BIS electrical safety approval timelines stretch 14-18 months for imported charging hardware, delaying deployment schedules for airport operators under fleet conversion deadlines.
- Legacy Fleet Integration Complexity:Mixed-equipment airports must maintain dual diesel-electric ground support operations during transition periods, doubling maintenance training requirements and spare parts inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Airport Electric Vehicle Charging Station Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fast Chargers, Level 2 Chargers, Wireless Chargers, Portable Chargers Charging Station Type: Standalone Stations, Integrated Stations, Mobile Stations, Multi-Standard Stations End User: Airlines, Ground Handling Services, Airport Authorities, Fleet Operators Installation Type: Permanent Installations, Temporary Installations, Retrofit Installations, Future-Proof Installations |
| Companies Covered | ABB Ltd., Schneider Electric, Delta Electronics Inc., Star Charge, BYD Co. Ltd., Siemens AG, Tesla Inc., Eaton, ChargePoint, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Airport Electric Vehicle Charging Station Market Evolving Landscape
Digital twin architectures are virtualizing charging asset management, compressing maintenance response times and enabling predictive load balancing across distributed airport power networks.
High-power liquid-cooled cable systems are virtualizing thermal management in tropical installations. Southeast Asian hub operators in Singapore and Bangkok are deploying these systems to sustain 350 kW outputs without derating in 40°C ambient conditions. The technology is virtualizing site preparation requirements by eliminating external HVAC enclosures and reducing concrete pad footprints by half.
China's MIIT is tightening GB/T 20234.3 power quality requirements for harmonic distortion limits at airport charging clusters. The regulation forces inverter specification upgrades that filter voltage fluctuations from ground equipment motor startups. Domestic suppliers are responding with active front-end rectifier designs that meet the new thresholds without external power conditioning units.
Airport authorities are consolidating vendor relationships around integrated energy service contracts that bundle hardware, software, and renewable generation under single-source agreements. The model displaces fragmented procurement of separate charging, solar, and storage assets. Australia's CEA mandates are accelerating this consolidation at Adelaide and Perth airports where grid interconnection studies must demonstrate unified power management systems.
Asia-Pacific Airport Electric Vehicle Charging Station Market Segmentation
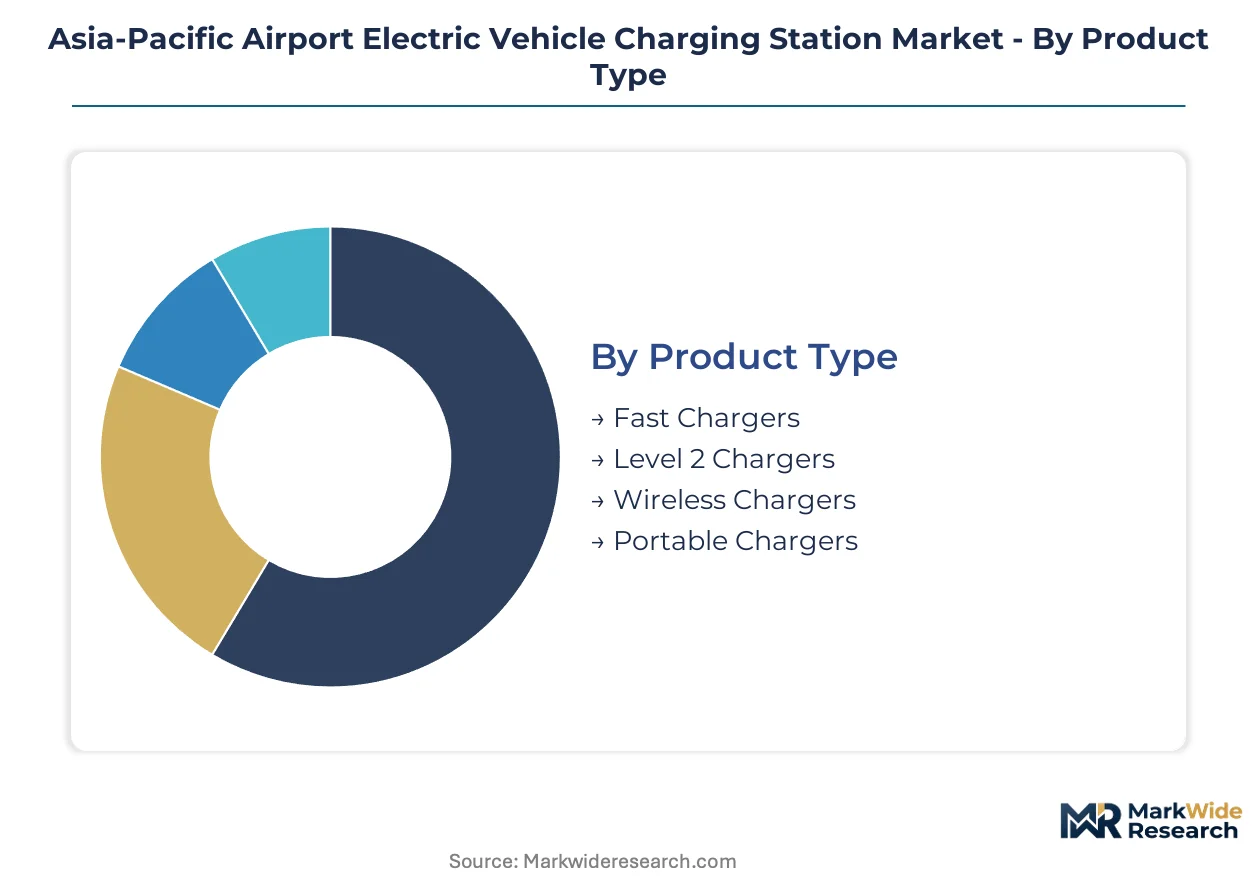
Asia-Pacific airport charging infrastructure exhibits distinct service intensity profiles across hardware categories. Procurement patterns diverge sharply between high-availability fast charging deployments and intermittent-use portable systems, shaping vendor contract structures and maintenance cadences.
Product Type:
After-sales service intensity escalates with power density and thermal management complexity across charging hardware tiers.
- Fast Chargers:High-power DC systems rated 150-350 kW dominate capital deployment for pushback tractor electrification at Beijing, Shanghai, and Guangzhou hubs. China's MIIT enforces GB/T 20234.3 power quality mandates that compress inverter replacement cycles and expand preventive maintenance contracts for harmonic filtering components.
- Level 2 Chargers:7-22 kW AC units serve auxiliary vehicle fleets and passenger shuttle operations with lower thermal stress. Australian airport operators favor these for remote terminal expansions where CEA grid interconnection protocols limit available capacity.
- Wireless Chargers:Inductive pad systems for autonomous ground vehicles require specialized coil alignment calibration and foreign object detection servicing.
- Portable Chargers:Mobile DC units address emergency ground support scenarios with minimal fixed infrastructure.
Fast chargers hold the largest share; momentum sits with wireless systems as autonomous vehicle pilots expand.
Charging Station Type:
Cost tier stratification separates premium integrated configurations from commoditized standalone hardware.
- Standalone Stations:Single-function charging assets without generation or storage bundling. These units dominate retrofit deployments at legacy airports in India and Southeast Asia where capital budgets constrain upfront investment.
- Integrated Stations:Combined photovoltaic canopy, battery buffer, and charging infrastructure. Singapore Changi and Bangkok Suvarnabhumi operators deploy these to shave peak demand charges under thin commercial margins, with solar generation offsetting 30-40% of grid draw during daylight operations.
- Mobile Stations:Trailer-mounted DC systems for temporary gate reassignments and construction-phase fleet support.
- Multi-Standard Stations:Hardware supporting GB/T, CCS, and CHAdeMO connectors for cross-border airline alliance compatibility.
Standalone stations retain volume leadership; integrated configurations are expanding most quickly as renewable bundling economics improve.
End User:
Customer type dictates procurement authority and technical specification complexity across the value chain.
- Airlines:Carriers electrifying owned pushback and baggage tractor fleets under narrow turnaround windows. Cathay Pacific and Singapore Airlines mandate 350 kW capability for sub-30-minute charging cycles between flights.
- Ground Handling Services:Third-party operators like SATS and dnata consolidate multi-airline demand through shared charging hubs, requiring flexible reservation systems and dynamic load balancing.
- Airport Authorities:Municipal aviation bureaus in China and Australia specify grid interconnection standards and site preparation requirements.
- Fleet Operators:Leasing companies managing electric ground support equipment pools across multiple airport contracts.
Ground handling services command the largest installed base; airline direct procurement is gaining share fastest as electrification timelines compress.
Installation Type:
Application maturity separates proven permanent designs from emerging future-proof specifications.
- Permanent Installations:Fixed concrete pad deployments with dedicated utility service at major hub gates. These represent the baseline for China's GB/T-mandated airport expansions.
- Temporary Installations:Rapid-deployment units for seasonal capacity surges and construction-phase operations.
- Retrofit Installations:Adaptation of existing electrical infrastructure at aging terminals, prevalent across India's metro airport upgrades where BIS certification timelines delay greenfield alternatives.
- Future-Proof Installations:Oversized conduit, cooling, and power distribution for 500+ kW next-generation charging without civil works replacement.
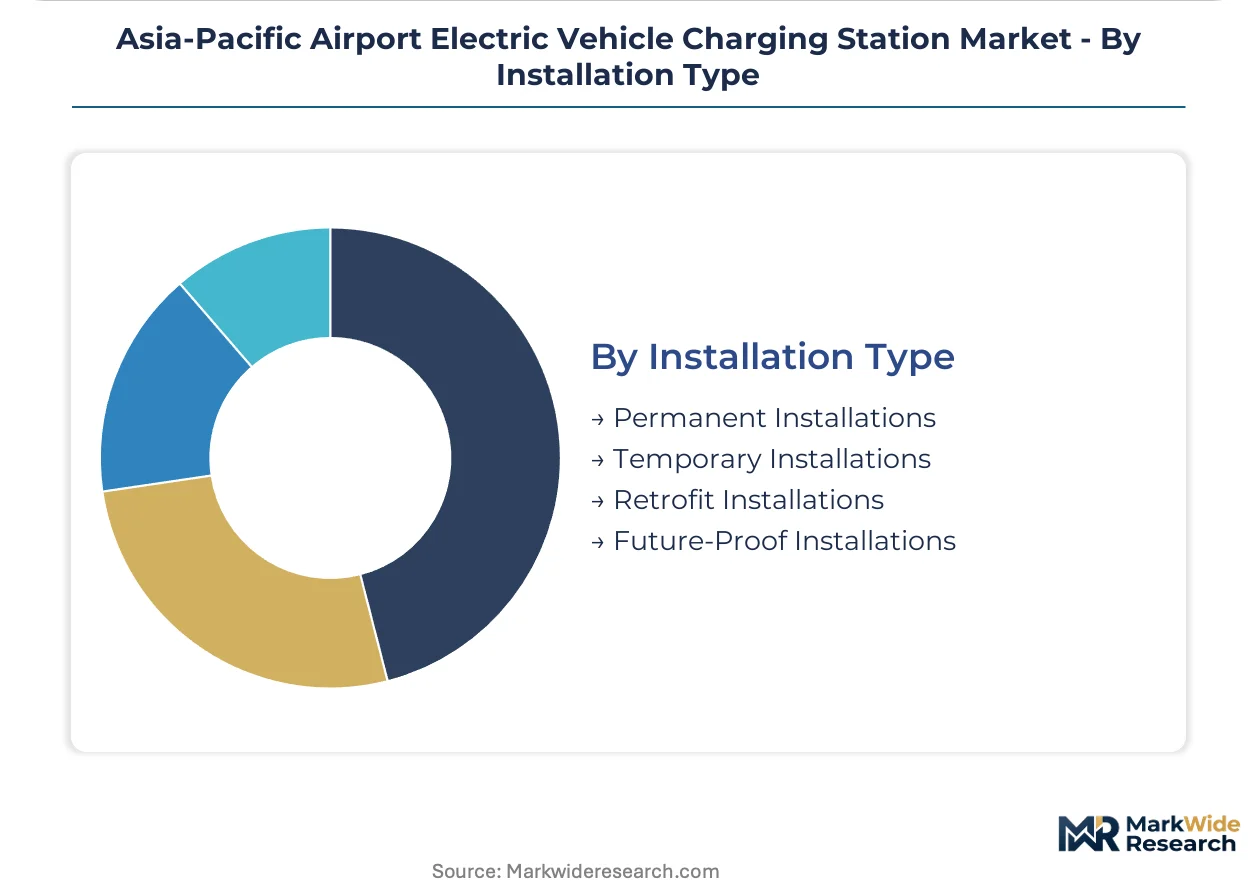
Permanent installations dominate current deployment; future-proof specifications are climbing the fastest as 2030 fleet targets harden procurement specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT enforcement of GB/T connector standards and dual carbon targets is compressing procurement timelines across Asia-Pacific airport authorities. Australia's CEA grid interconnection protocols and India's BIS certification requirements create divergent compliance pathways for equipment suppliers entering these markets.
China
Beijing Capital, Shanghai Pudong, and Guangzhou Baiyun airports are electrifying ground support equipment fleets under MIIT-mandated GB/T 20234.3 power quality standards. The dual carbon policy framework guarantees demand pipelines for certified domestic suppliers. Yangtze River Delta aviation clusters anchor the largest deployment volumes.
Australia
Adelaide and Perth airports consolidate vendor relationships under CEA-mandated unified power management systems for grid interconnection studies. Remote Western Australia and Queensland airports face substation capacity constraints that limit charging station deployment. Integrated energy service contracts bundle hardware, software, and renewable generation.
India
Delhi and Mumbai airport expansions leverage PLI scheme incentives for advanced chemistry cell manufacturing to reduce battery storage costs for integrated charging stations. BIS electrical safety approval timelines stretch 14-18 months for imported hardware, delaying deployment schedules. Metro airport upgrades concentrate in Maharashtra and Karnataka.
Vietnam
Long Thanh International Airport's greenfield development enables pure-electric infrastructure deployment without retrofit constraints. The absence of legacy ground equipment fleets allows 350 kW DC fast charging specification from initial design. Southern aviation corridor projects attract integrated station bundling.
Singapore
Changi Airport operators deploy photovoltaic-storage-integrated stations to shave peak demand charges under thin commercial margins. Solar generation offsets 30-40% of grid draw during daylight operations. High-power liquid-cooled cable systems sustain 350 kW outputs in tropical ambient conditions.
Asia-Pacific Airport Electric Vehicle Charging Station Market Competitive Landscape
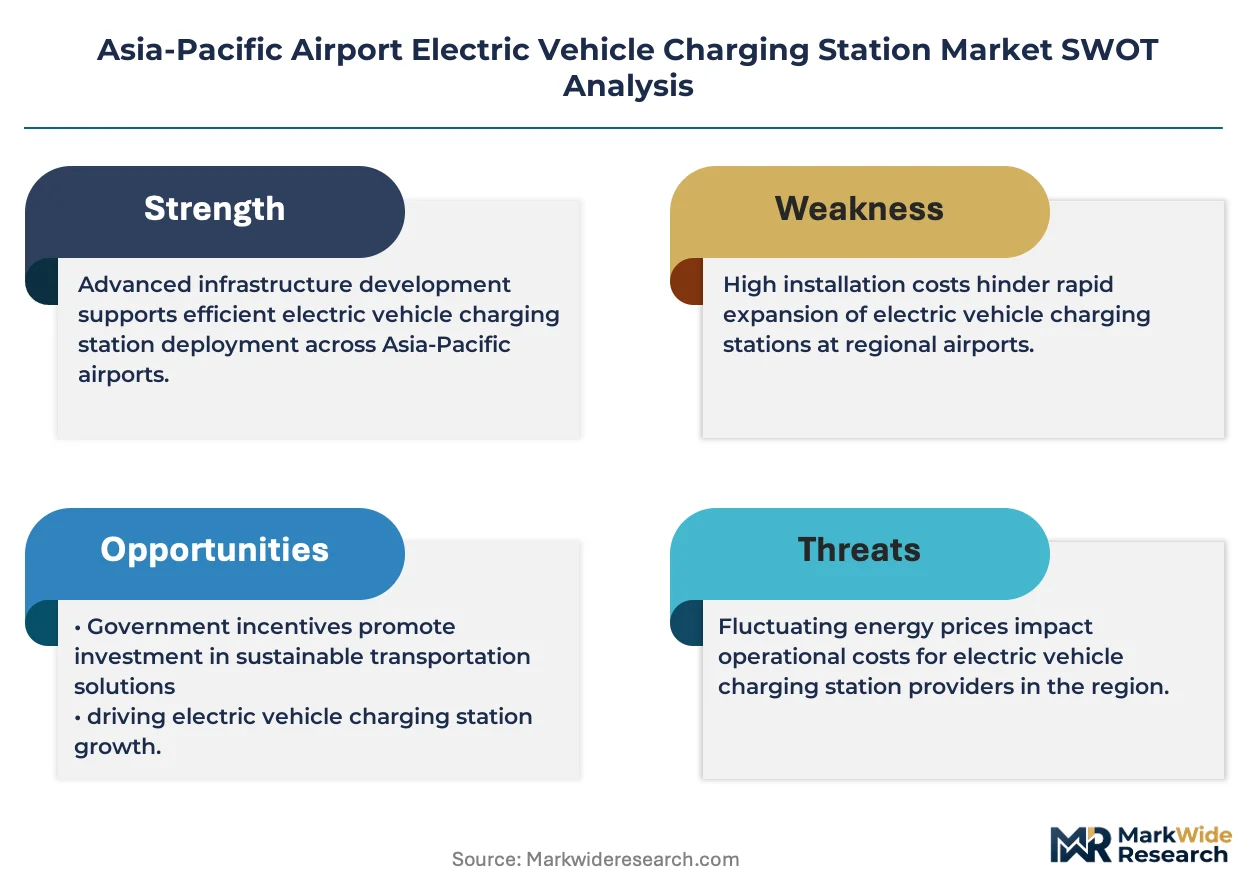
On the supply side, the industry is consolidating around three strategic tiers: multinational electrical engineering conglomerates with high-power charging portfolios, integrated energy management specialists bundling solar and storage assets, and regional fabricators with tropical climate thermal management expertise. Competitive positioning hinges on GB/T certification status for China access, CEA grid interconnection compliance for Australia, and BIS electrical safety approval for India. Dominant competitive moves include strategic partnerships with airport authorities for integrated energy service contracts and capacity expansion into Southeast Asian greenfield hub developments.
Within the multinational tier, ABB Ltd. and Schneider Electric occupy anchor positions across hub expansions, with the former representing high-power charging specialization and the latter exemplifying integrated energy system bundling. Delta Electronics Inc. sits within the regional specialist archetype, its Taiwan-based structure signaling compact thermal management capabilities for tropical outdoor installations. These three entities collectively span the certification and climate adaptation requirements that gate Asia-Pacific airport procurement.
| Leading Market Players |
|---|
| ABB Ltd. |
| Schneider Electric |
| Delta Electronics Inc. |
| Star Charge |
| BYD Co. Ltd. |
| Siemens AG |
| Tesla Inc. |
| Eaton |
| ChargePoint |
| Others |
Value Network & Pricing Analysis
Undercapacity in silicon carbide substrate fabrication across Taiwanese and South Korean foundries is compressing supplier margins while elevating pricing power for certified power electronics vendors serving China's GB/T-mandated airport expansions. This utilization squeeze propagates through inverter specification upgrades, forcing procurement officers at Beijing and Shanghai aviation hubs to accept longer lead times or premium tier positioning.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates GB/T-certified integrated stations with active harmonic filtering from basic standalone units and retrofit-compatible hardware. Price differentiation hinges on MIIT certification status and after-sales service bundling intensity. Cost compression in economy-tier standalone chargers is intensifying because Indian and Southeast Asian airport authorities prioritize capital expenditure minimization over performance reserves. Ground handling services exhibit highest price sensitivity due to thin commercial margins, while airline direct procurement shows lowest sensitivity given narrow turnaround window requirements.
Supply Chain Analysis
Copper cathode feedstock draws from Chilean smelter networks and Indonesian concentrate refining, with silicon carbide substrates sourcing from Japanese and American wafer growth facilities. Power conversion hardware rests on refined copper supply, semiconductor substrate availability, and liquid-cooled cable assemblies. Single-source vulnerability concentrates in silicon carbide epitaxy capacity controlled by Wolfspeed and Coherent operations. Distribution runs through integrated energy service contracts that bundle hardware, software, and renewable generation under single-source agreements at Adelaide, Perth, and Singapore Changi airports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific airport electric vehicle charging station market is emerging from a cyclical trough driven by China's dual carbon policy enforcement and compressed fleet electrification timelines across major aviation hubs.
For Market Incumbents: Harden GB/T certification moats through active front-end rectifier R&D investments that exceed MIIT's tightening harmonic distortion thresholds. Consolidate channel control by locking in integrated energy service contracts at Australia's CEA-mandated airports before competitor entry. Capacity addition in Vietnam's Long Thanh greenfield development represents the priority defensive geography against emerging regional fabricators.
For New Entrants and Emerging Players: Remote Western Australia and Queensland airports present white-space opportunities where CEA grid interconnection constraints have delayed incumbent deployment. The Philippines' Clark airport expansion offers pure-electric infrastructure entry without legacy diesel fleet retrofit complexity. A go-to-market angle pairing compact tropical thermal management with localized BIS certification navigation addresses India's 14-18 month approval bottleneck.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated station operators bundling photovoltaic canopies, battery buffers, and charging hardware under long-term service contracts. Long-term viability across the projection horizon favors acquisition targets with established GB/T certification and CEA compliance track records. The signal to watch is BIS approval timeline compression for imported hardware, which would unlock India's metro airport upgrade pipeline.
| Strategic Initiative | Industry Significance |
|---|---|
| GB/T Certification Investment | MIIT-mandated power quality standards lock in hardware procurement at Beijing, Shanghai, and Guangzhou hubs. |
| Integrated Energy Service Contracts | Adelaide and Perth airports consolidate vendor relationships under CEA-mandated unified power management systems. |
| Tropical Thermal Management R&D | Singapore Changi and Bangkok Suvarnabhumi deployments sustain 350 kW outputs in 40°C ambient conditions. |
| Backward Integration into Battery Storage | India's PLI scheme for advanced chemistry cells reduces integrated station costs at Delhi and Mumbai expansions. |
| Wireless Charging Pilot Expansion | Premium carriers pilot automated positioning systems pairing inductive pads with self-driving pushback units. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of MIIT regulatory filings, CEA grid interconnection protocols, and BIS certification databases. Airport authority procurement officers, ground handling fleet managers, and power electronics engineering directors provided operational perspective. SEC filings from charging infrastructure vendors, customs import records for semiconductor substrates, and airport capital expenditure disclosures furnished quantitative anchors. Bottom-up deployment tracking across Beijing, Shanghai, Guangzhou, Delhi, Mumbai, Singapore, and Australian hubs triangulates against top-down market sizing.
Forecast inputs incorporate charging station type segmentation, end-user procurement authority patterns, and installation type maturity curves across the projection horizon. Product type splits between fast chargers, Level 2 units, wireless systems, and portable configurations anchor volume modeling. CAGRs derive from fleet electrification timeline compression under China's dual carbon framework and Australia's CEA mandates. Industry-specific inputs include GB/T 20234.3 power quality threshold evolution and PLI scheme incentive trajectories for battery storage integration.
Practitioners should monitor silicon carbide substrate utilization rates and BIS approval timeline trends for early signals of supply constraint or regulatory acceleration. Forecasts reflect assumptions regarding MIIT enforcement consistency and CEA grid interconnection study completion rates. Cross-checking against IEA electric vehicle infrastructure deployment benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle AC Charging Pile Market
Electric Vehicle Charging
United Kingdom Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Portable Charging Units Market
Electric Vehicle Charging
Home Charging Piles Market
Electric Vehicle Charging
HVAC Electronically Commutated Motor (ECM) Market
Electric Vehicle Charging
India Electric Vehicle Charging Station Market
Electric Vehicle Charging
Electric Vehicle Charging Adapter Market
Electric Vehicle Charging
EV Solar Charging Wallbox Market
Electric Vehicle Charging
Bidirectional Charging Units Market
Electric Vehicle Charging
Metals in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
EV Charging Kiosk Market
Electric Vehicle Charging
High Power Charger for Electric Vehicle Market
Electric Vehicle Charging
Wireless Charging Market
Electric Vehicle Charging
Home EV Chargers Market
Electric Vehicle Charging
EV Charging Station Market
Electric Vehicle Charging
Automotive EV Charging Adapters Market