
 Thermal Conductive Polymer Material for Electric Vehicles Market | 2026-2036
Thermal Conductive Polymer Material for Electric Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Conductive Polymer Material for Electric Vehicles Market Intelligence
UL 94 V-0 flame-retardant certification is unwinding competitive access across the thermal conductive polymer landscape, raising barriers for suppliers lacking validated test data. BASF SE leverages its integrated polyamide compounding network to secure qualification slots with European OEM thermal module programs. DuPont de Nemours, Inc. anchors its position through Zytel nylon grades engineered for continuous-use temperatures above 150°C in battery housing applications. Covestro AG competes via Makrolon polycarbonate systems optimized for thin-wall power electronics enclosures where dielectric strength and thermal conductivity must coexist.
Thermal conductive polymer material for electric vehicles comprises engineered resin matrices—typically polyamide, polypropylene, or thermoplastic elastomer—loaded with ceramic fillers such as boron nitride or aluminum oxide to achieve thermal conductivities between 1-10 W/m·K while retaining injection moldability; these compounds dissipate heat from lithium-ion cells, IGBT modules, and DC-DC converters to prevent thermal runaway and extend component life. Fillers command the deepest margin pools due to raw material specialization and limited qualified supply bases, while compounds face accelerating volume pressure as tier-1 suppliers consolidate specification lists around multi-functional grades. Battery Systems applications lead absolute consumption but Charging Infrastructure represents the fastest structural expansion as high-power charging stations above 350 kW require cable jacketing and connector housings with enhanced thermal stability.
FDA maintains indirect food-contact relevance for polymers used in cabin-interior thermal pathways, while EPA tailpipe and lifecycle emissions frameworks indirectly shape material selection through OEM carbon-accounting requirements; China's MIIT NEV technical directory directly gates market access by mandating thermal propagation resistance test protocols for battery pack materials. The EU Green Deal and associated battery passport regulations are forcing traceability documentation down to filler sourcing. Stakeholders must monitor evolving flammability test protocols across NHTSA, ECHA, and SAMR jurisdictions, as diverging certification timelines threaten to fragment product qualification roadmaps and strand development investments.
Market Dynamics
Battery pack manufacturers are consolidating specification lists around multi-functional thermal conductive polymer grades that simultaneously meet flame-retardant, dielectric, and thermal conductivity requirements, compressing supplier qualification timelines and raising technical barriers to entry.
Growth Catalysts
- China's MIIT NEV Technical Directory:Mandatory thermal propagation resistance test protocols for battery pack materials are forcing OEMs to source qualified thermal conductive polymers, expanding addressable demand for certified suppliers.
- High-power charging infrastructure:Charging stations above 350 kW require cable jacketing and connector housings with enhanced thermal stability, creating new volume pools beyond battery systems.
- Cell-to-pack architectures:OEMs redesigning thermal management for higher-density cell configurations are replacing traditional gap pads with injection-moldable thermal conductive compounds.
Market Restraints
- Ceramic filler supply concentration:Boron nitride and aluminum oxide production concentrates among limited qualified suppliers, exposing compounders to input cost volatility and allocation risk.
- UL 94 V-0 certification timelines:Extended validation periods for flame-retardant grades delay revenue recognition and strain working capital for mid-scale compounders.
- Metal thermal interface materials:Sintered copper and aluminum solutions compete in power electronics applications where thermal conductivity requirements exceed 10 W/m·K.
Strategic Opportunities
- EU battery passport regulations:Traceability documentation requirements down to filler sourcing create first-mover advantages for suppliers with integrated supply chain visibility systems.
- Thermoplastic elastomer formulations:Soft-touch, thermally conductive grades for cabin-interior applications remain underpenetrated relative to battery pack and power electronics segments.
- Solid-state battery thermal management:Next-generation cell chemistries with different heat generation profiles will require redesigned polymer thermal interface architectures.
Industry Challenges
- Multi-jurisdiction flammability protocol divergence:NHTSA, ECHA, and SAMR are evolving test standards on non-aligned timelines, threatening to strand development investments in grades qualified for only one regulatory regime.
- Compounding equipment scale-up:High-shear twin-screw extrusion systems capable of dispersing high ceramic loadings without filler degradation require capital commitments that strain mid-tier compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Conductive Polymer Material for Electric Vehicles Market |
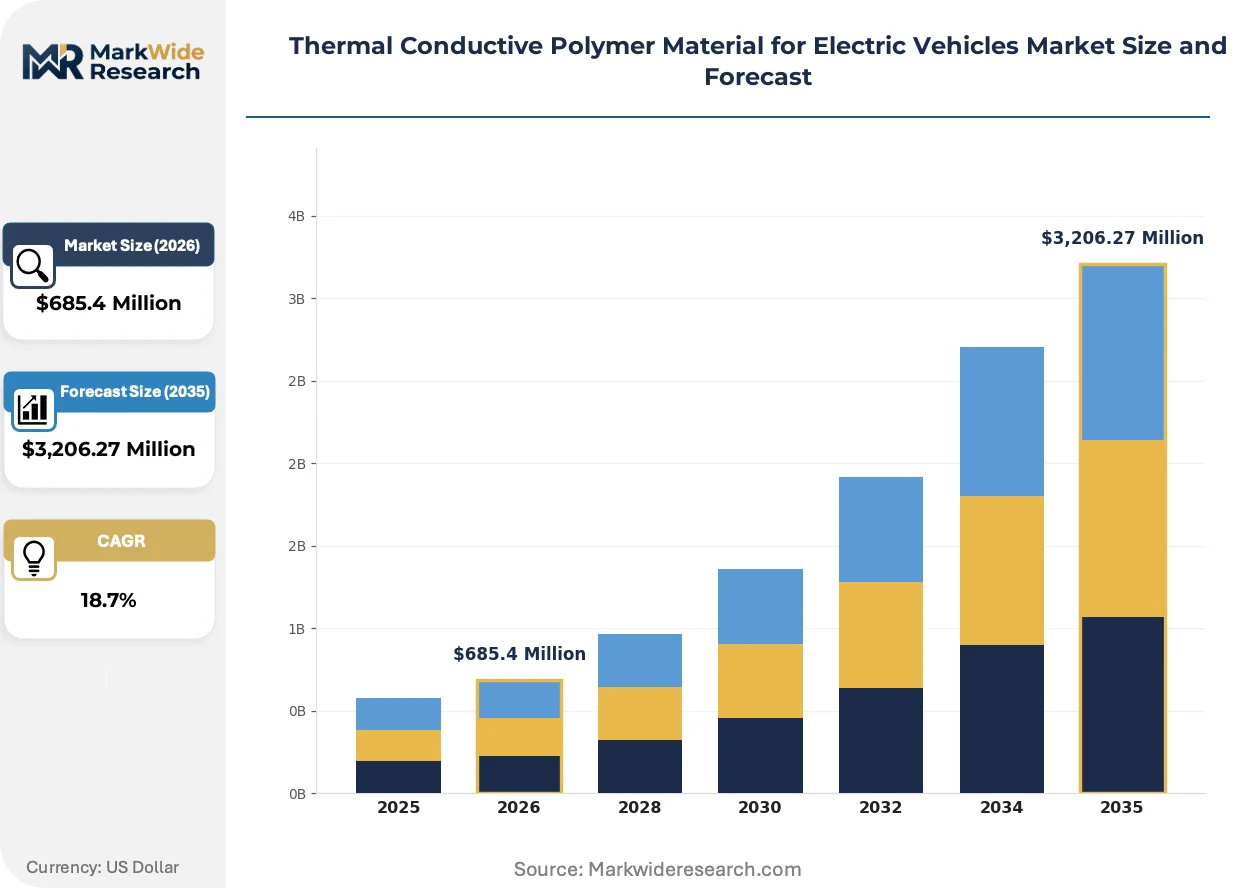
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $3,206.27 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fillers, Compounds, Coatings, Adhesives Application: Battery Systems, Power Electronics, Thermal Management, Charging Infrastructure End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Injection Molding, Extrusion, Compression Molding, 3D Printing |
| Companies Covered | Arkema, Sumitomo Chemical Co., Ltd., BASF SE, Evonik Industries AG, Asahi Kasei Corporation, DuPont de Nemours, Inc., Celanese Corporation, Lanxess AG, Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Conductive Polymer Material for Electric Vehicles Market Strategic Shifts & Innovations
Material innovation is converging on hybrid filler systems and in-situ polymerization techniques that break the traditional trade-off between thermal conductivity and mechanical processability. These advances are reshaping supplier R&D priorities and OEM qualification roadmaps.
Boron nitride platelet networks combined with spherical aluminum oxide are displacing single-filler systems in battery housing applications. Tier-1 thermal module suppliers are adopting these hybrid compounds to achieve directional thermal conductivity above 5 W/m·K while maintaining UL 94 V-0 ratings. The structural consequence is compressing development cycles for commodity-grade single-filler alternatives that cannot meet multi-property specifications.
The EU Green Deal's battery passport regulations are mandating filler provenance documentation from mine to molded part. European OEMs are responding by pre-qualifying suppliers with integrated supply chain traceability systems, shifting procurement weight toward vertically integrated compounders. Cell manufacturers with German and French assembly plants face the most acute compliance pressure.
Specification consolidation by battery pack manufacturers is compressing approved vendor lists from twenty-plus compounders to fewer than ten qualified partners. Tier-1 suppliers are replacing spot-buying with multi-year offtake agreements tied to vehicle platform lifecycles. This pattern is most visible in China's Yangtze River Delta automotive cluster, where CATL and BYD procurement teams are centralizing thermal material sourcing decisions.
Thermal Conductive Polymer Material for Electric Vehicles Market Segmentation
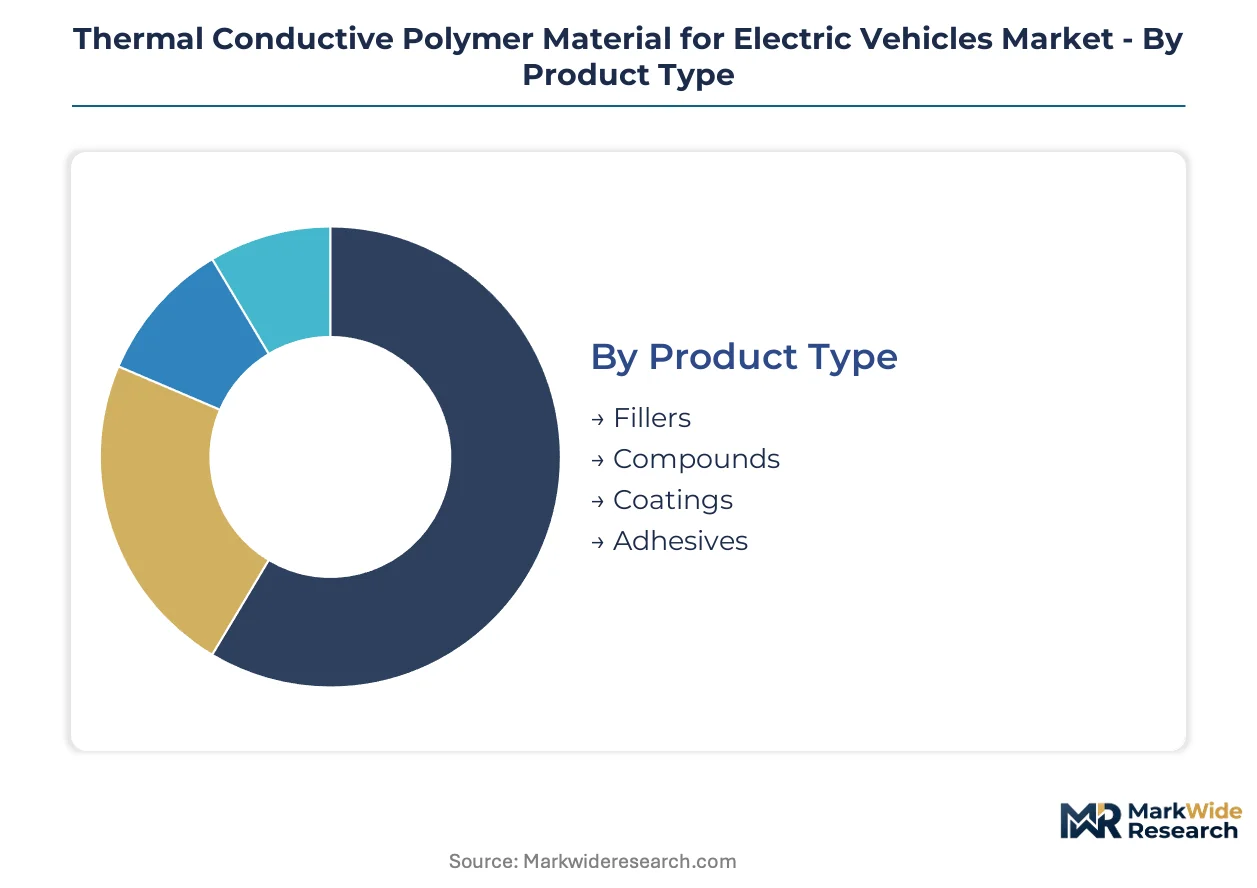
Segmentation in thermal conductive polymers determines qualification pathways, margin structures, and capital allocation priorities. Product type and application segments flow through distinct commercial channels with divergent technical barriers and pricing power.
Product Type:
Fillers and compounds dominate procurement volumes through direct supply to battery pack manufacturers, while coatings and adhesives route through tier-1 thermal module integrators serving multiple OEM programs.
- Fillers:Ceramic particles—boron nitride platelets, aluminum oxide spheres, and hybrid architectures—constitute the functional thermal conductivity phase within polymer matrices. Demand concentrates among qualified boron nitride suppliers serving CATL and BYD cell production in China's Yangtze River Delta, where thermal propagation resistance requirements under MIIT protocols are tightening purity and particle size specifications.
- Compounds:Pre-compounded resin systems—polyamide, polypropylene, or thermoplastic elastomer loaded with 30-60% ceramic filler—deliver injection-moldable thermal conductivity of 1-10 W/m·K. Procurement is consolidating around European OEM thermal module programs requiring UL 94 V-0 certification and continuous-use temperature ratings above 150°C, compressing approved vendor lists to vertically integrated compounders with validated test data.
- Coatings:Thin-film thermal interface materials applied to battery housings and power electronics enclosures. Specifications emphasize dielectric strength and flame-retardant ratings for electric vehicle platforms.
- Adhesives:Thermally conductive bonding agents for cell-to-pack architectures and module assembly. Applications prioritize thermal stability under mechanical stress and vibration resistance.
By volume, compounds lead. By growth pace, fillers are climbing the fastest as cell energy densities rise and filler loadings increase.
Application:
Cost tier segmentation separates battery systems and power electronics as premium specification segments from charging infrastructure and general thermal management as emerging volume opportunities.
- Battery Systems:Cell housings, module frames, and pack enclosures requiring simultaneous flame-retardant, dielectric, and thermal conductivity performance. Demand concentrates in OEM platform programs redesigning thermal architectures for cell-to-pack configurations, where injection-moldable compounds replace traditional gap pads.
- Charging Infrastructure:Cable jacketing, connector housings, and station enclosures for stations above 350 kW. High-power charging requirements in Germany and France are driving thermal stability specifications for continuous operation under elevated electrical loads.
- Power Electronics:IGBT modules, DC-DC converters, and inverter housings. Specifications emphasize thin-wall moldability with dielectric strength coexistence.
- Thermal Management:General heat dissipation components across vehicle thermal loops. Applications span cabin climate systems and auxiliary cooling pathways.
Battery systems command the deepest specification investment. Charging infrastructure shows the steepest expansion trajectory as deployment scales accelerate.
End User:
Customer type determines contract structure—OEMs drive multi-year platform agreements, while tier-1 suppliers consolidate specification lists and aftermarket providers serve replacement demand.
- OEMs:Vehicle manufacturers specifying thermal conductive polymers at platform design stage. Procurement teams in China's Yangtze River Delta automotive cluster are centralizing material decisions under dual carbon goals and NEV mandates.
- Tier-1 Suppliers:Thermal module and battery pack manufacturers consolidating approved vendor lists from twenty-plus compounders to fewer than ten qualified partners. Multi-year offtake agreements now tie to vehicle platform lifecycles.
- Aftermarket Providers:Replacement thermal interface materials for vehicle service and repair. Demand tracks installed base expansion rather than new vehicle production.
- Vehicle Assemblers:Contract manufacturing operations integrating thermal components into final vehicle assembly. Specifications flow down from OEM engineering teams.
Tier-1 suppliers lead procurement volume. OEMs are gaining share fastest as platform-level thermal architecture redesigns concentrate material selection authority.
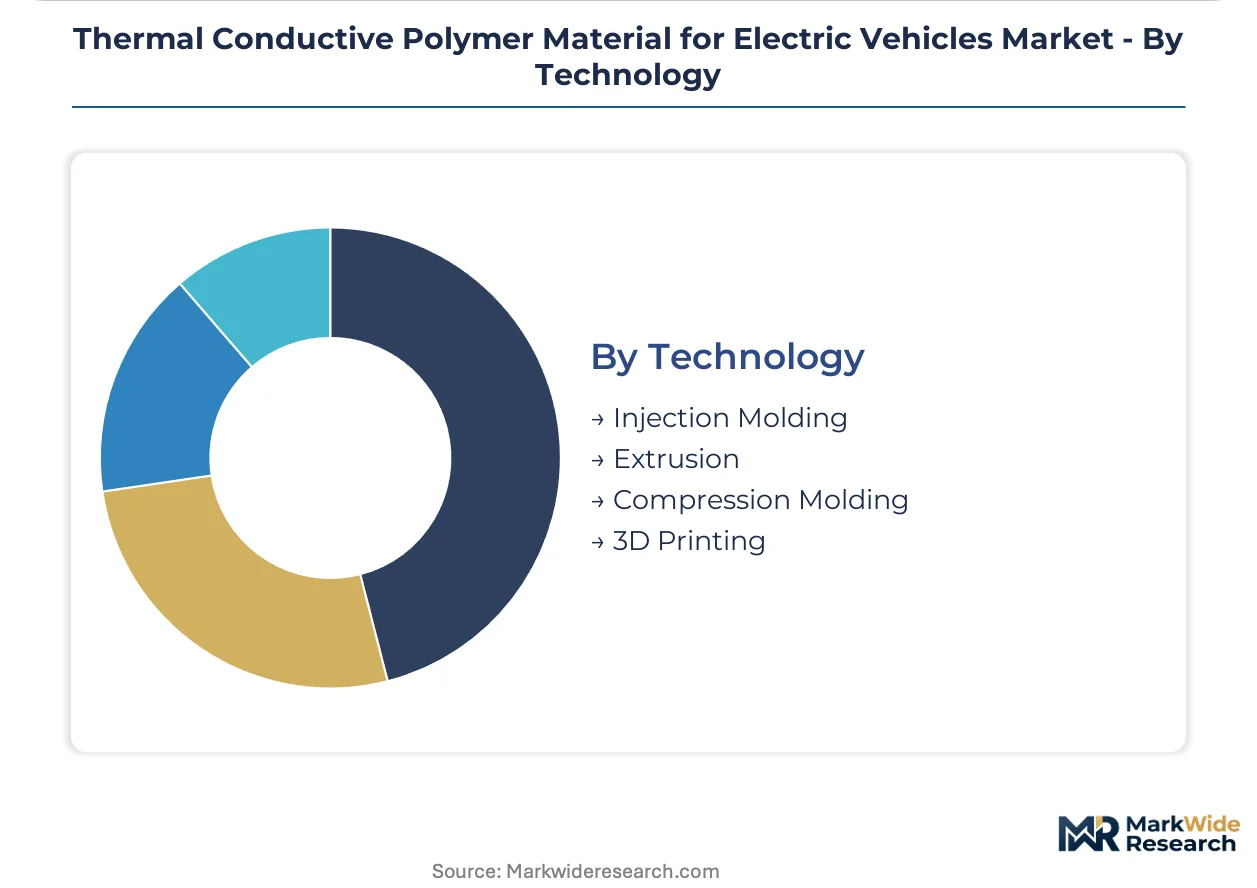
Technology:
Processing method segmentation aligns with part complexity and volume scale—injection molding dominates high-volume battery components, while 3D printing serves prototyping and low-volume thermal management geometries.
- Injection Molding:High-shear twin-screw compounding followed by precision molding for complex battery housing geometries. Equipment scale-up requirements strain mid-tier compounders seeking to disperse high ceramic loadings without filler degradation.
- Extrusion:Continuous profile production for cable jacketing and thermal interface sheet materials. Processing emphasizes consistent thermal conductivity across production runs.
- Compression Molding:Large-format part production for battery pack enclosures and thermal management plates. Applications prioritize dimensional stability under thermal cycling.
- 3D Printing:Additive manufacturing for prototyping and complex thermal management geometries. Technology enables rapid iteration of conformal cooling channels and custom thermal interface architectures.
Injection molding commands production volume. 3D printing is expanding most quickly as solid-state battery development accelerates prototyping demand for redesigned thermal interface geometries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals and NEV mandates are tightening material performance requirements across the automotive sector. Germany's EU Green Deal compliance pressure is reshaping procurement patterns for battery passport traceability. The United States IRA incentives are accelerating domestic EV manufacturing capacity buildouts.
China
CATL and BYD procurement teams are centralizing thermal material sourcing decisions in the Yangtze River Delta automotive cluster. MIIT NEV technical directory mandates thermal propagation resistance test protocols for battery pack materials. Shanghai and Jiangsu province host the densest concentration of qualified compounders serving cell-to-pack architecture redesigns.
Germany
BASF SE leverages its integrated polyamide compounding network to secure qualification slots with European OEM thermal module programs. ECHA evolving flammability test standards are compressing supplier qualification timelines. Bavaria and Baden-Württemberg anchor the premium specification segment where UL 94 V-0 certification gates market access.
United States
High-power charging infrastructure above 350 kW is driving cable jacketing demand across Texas and California corridor deployments. NHTSA evolving test protocols threaten to fragment product qualification roadmaps. Michigan and the Southeast automotive belt concentrate tier-1 thermal module supplier consolidation activity.
Japan
Solid-state battery development is accelerating prototyping demand for redesigned thermal interface geometries. METI technical standards influence material selection for export-oriented EV platforms. Kanto and Kansai industrial regions host compounders specializing in thin-wall power electronics enclosures.
South Korea
LG Energy Solution and Samsung SDI procurement patterns are converging on multi-functional thermal conductive polymer grades. MFDS regulatory frameworks indirectly shape material selection through OEM carbon-accounting requirements. Seoul Capital Area and Busan-Ulsan corridor concentrate battery system specification authority.
Thermal Conductive Polymer Material for Electric Vehicles Market Key Industry Players
Player mix skews toward diversified chemical conglomerates with integrated resin compounding networks. The supplier base compresses around vertically integrated compounders possessing validated UL 94 V-0 test data and filler sourcing traceability systems. Three archetypes dominate: resin specialists with captive polymerization capacity, ceramic filler suppliers backward integrating into compounds, and tier-1 automotive suppliers developing proprietary thermal module materials. Competitive dynamics center on multi-year offtake agreements tied to vehicle platform lifecycles and strategic partnerships for high-shear twin-screw extrusion capacity expansion.
Within the diversified chemical conglomerate tier, BASF SE, Covestro AG, and DuPont de Nemours, Inc. exemplify positioning built on integrated resin matrix production and established OEM qualification relationships. These entities occupy anchor positions in European and North American thermal module programs where continuous-use temperature ratings above 150°C and dielectric strength specifications compress approved vendor lists. Their geographic footprints span German, US, and Belgian industrial clusters where battery passport traceability requirements favor suppliers with mine-to-molded-part documentation systems.
| Leading Market Players |
|---|
| Arkema |
| Sumitomo Chemical Co., Ltd. |
| BASF SE |
| Evonik Industries AG |
| Asahi Kasei Corporation |
| DuPont de Nemours, Inc. |
| Celanese Corporation |
| Lanxess AG |
| Covestro AG |
| Others |
Cost & Logistics Intelligence
Multi-year offtake agreements tied to vehicle platform lifecycles lock in supply access and price visibility for battery pack manufacturers consolidating approved vendor lists around UL 94 V-0 certified thermal conductive polymer grades. China's MIIT NEV technical directory mandates thermal propagation resistance test protocols that compress qualification timelines and concentrate procurement authority with compounders possessing validated filler sourcing traceability systems.
Pricing Analysis
Certification level (UL 94 V-0 vs. HB-rated) creates the primary spread between premium and standard thermal conductive polymer grades. Contract-based long-term offtake structures dominate procurement as tier-1 suppliers replace spot-buying with multi-year agreements. Price differentiation hinges on continuous-use temperature ratings above 150°C and dielectric strength specifications. Cost compression in mid-tier compounds is intensifying because high-shear twin-screw extrusion equipment requirements strain capital-constrained compounders. Aftermarket providers exhibit highest price sensitivity while OEM platform engineering teams prioritize performance validation over unit economics.
Supply Chain Analysis
China and Germany anchor boron nitride and aluminum oxide ceramic filler production serving global battery pack manufacturing. Raw material dependencies rest on high-purity boron nitride platelets, spherical aluminum oxide, and engineered polyamide resin matrices. Single-source vulnerability concentrates in qualified boron nitride suppliers serving CATL and BYD cell production in the Yangtze River Delta. Distribution runs through tier-1 thermal module integrators consolidating specification lists from twenty-plus compounders to fewer than ten qualified partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal conductive polymer incumbents face substitution defense imperatives as sintered copper and aluminum thermal interface materials compete in power electronics applications exceeding 10 W/m·K conductivity requirements.
For Market Incumbents: Fortify qualification slot positions with European OEM thermal module programs by accelerating UL 94 V-0 certification investments and securing captive boron nitride supply agreements. Backward integration into high-purity ceramic filler production defends margin position against input cost volatility from concentrated qualified suppliers. Cell-to-pack architecture redesigns by OEMs threaten traditional gap pad suppliers with displacement by injection-moldable compounds. For New Entrants and Emerging Players: Anchor in thermoplastic elastomer formulations for cabin-interior thermal pathways where soft-touch, thermally conductive grades remain underpenetrated relative to battery pack segments. Target charging infrastructure cable jacketing and connector housing applications above 350 kW as high-power deployment scales accelerate in Germany and France. A go-to-market angle emphasizing EU battery passport traceability documentation from mine to molded part creates first-mover advantage with European OEM procurement teams. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated compounders with validated test data and multi-year offtake agreements tied to vehicle platform lifecycles. Long-term viability over the coming decade hinges on positioning for solid-state battery thermal management architectures requiring redesigned polymer thermal interface geometries. Acquisition target archetypes include mid-scale compounders possessing high-shear twin-screw extrusion capacity and established OEM qualification relationships. The signal to watch is divergence in NHTSA, ECHA, and SAMR flammability test protocols that could strand development investments in single-jurisdiction qualified grades.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Filler Production | Captive boron nitride supply secures margin control against allocation risk from China's Yangtze River Delta concentration. |
| UL 94 V-0 Certification Investment | Validated flame-retardant test data gates qualification slots with European OEM thermal module programs. |
| EU Battery Passport Traceability System | Mine-to-molded-part documentation creates procurement preference under ECHA evolving compliance frameworks. |
| High-Shear Twin-Screw Extrusion Capacity Expansion | Equipment scale-up enables dispersion of 30-60% ceramic loadings without filler degradation for cell-to-pack compounds. |
| Thermoplastic Elastomer Formulation Development | Soft-touch thermal conductivity addresses underpenetrated cabin-interior applications beyond battery systems. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary validation across regulatory and trade databases. Primary interviews incorporated thermal module procurement leads at tier-1 battery pack manufacturers, OEM platform engineers specifying cell-to-pack architectures, ceramic filler supply specialists, and high-shear compounding equipment operators. Secondary sources encompassed MIIT NEV technical directory filings, ECHA substance registration databases, UL certification records, customs trade data for boron nitride and aluminum oxide flows, and SEC 10-K disclosures from diversified chemical conglomerates. Bottom-up volume builds across product type and application segments triangulated against top-down OEM production forecasts.
Across the analysis window, the forecasting framework modeled thermal conductive polymer demand through segmentation by product type (fillers, compounds, coatings, adhesives), application (battery systems, charging infrastructure, power electronics, thermal management), end user (OEMs, tier-1 suppliers, aftermarket providers), and processing technology (injection molding, extrusion, compression molding, 3D printing). CAGRs derived from regression analysis of historical OEM platform deployment patterns and cell energy density trajectories. Industry-specific inputs included MIIT thermal propagation resistance test protocol adoption curves, high-power charging station deployment pipelines in Germany and France, and solid-state battery development timelines from Japanese cell manufacturers.
Material uncertainties — regulatory protocol divergence across NHTSA, ECHA, and SAMR jurisdictions, ceramic filler supply disruption from China's environmental enforcement actions, and metal thermal interface material substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions regarding OEM platform standardization timelines and tier-1 supplier consolidation trajectories. Recalibration cycles align with material shifts in NEV mandate stringency, flammability test standard harmonization, and next-generation cell chemistry thermal management requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Europe EV Charging Stations Market
Electric Vehicle Charging
Asia Pacific Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Two Wheeler Charging Station Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station Infrastructure Market
Electric Vehicle Charging
Electric Vehicle (EV) Public Charging Station Market
Electric Vehicle Charging
Electric Vehicle Charging Adapter Market
Electric Vehicle Charging
Portable Charging Units Market
Electric Vehicle Charging
Europe Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Copper in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
EV Solar Charging Wallbox Market
Electric Vehicle Charging
Second Life Electric Vehicle Battery Market
Electric Vehicle Charging
Electric Vehicle Grid Integration Solutions Market
Electric Vehicle Charging
Charging As a Service Market
Electric Vehicle Charging
Germany EV Charging Infrastructure Market
Electric Vehicle Charging
Pantograph Charger Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station Operation Market