
 Japan Electric Vehicles (EV) Charging Equipment Market | 2026-2036
Japan Electric Vehicles (EV) Charging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Electric Vehicles (EV) Charging Equipment Market Insights
Certified electrical technician shortages across Japan's prefectures is reorganizing installation timelines and forcing manufacturers to simplify deployment protocols. Sumitomo Electric Industries leverages its cable and power systems heritage to dominate high-voltage DC hardware production. TEPCO anchors its position through direct utility ownership of charging networks across the Kanto region. Nippon Charge Service specializes in interoperable payment platforms that reduce friction for multi-network fleet users.
Japan Electric Vehicles (EV) Charging Equipment encompasses conductive and inductive systems engineered to deliver alternating or direct current at outputs ranging from 3.7 kW residential Level 1 units to 350 kW ultra-fast DC dispensers, with thermal management and communication protocols ensuring safe, bidirectional energy transfer between grid and vehicle battery. DC Chargers command the steepest capital allocation from highway service operators seeking to minimize dwell times for commercial fleets. Wireless Chargers occupy a nascent but strategically watched position, with automakers evaluating inductive pad integration for premium residential and automated parking applications. AC Chargers sustain volume leadership in workplace and multi-unit dwelling deployments where overnight dwell periods accommodate slower replenishment cycles.
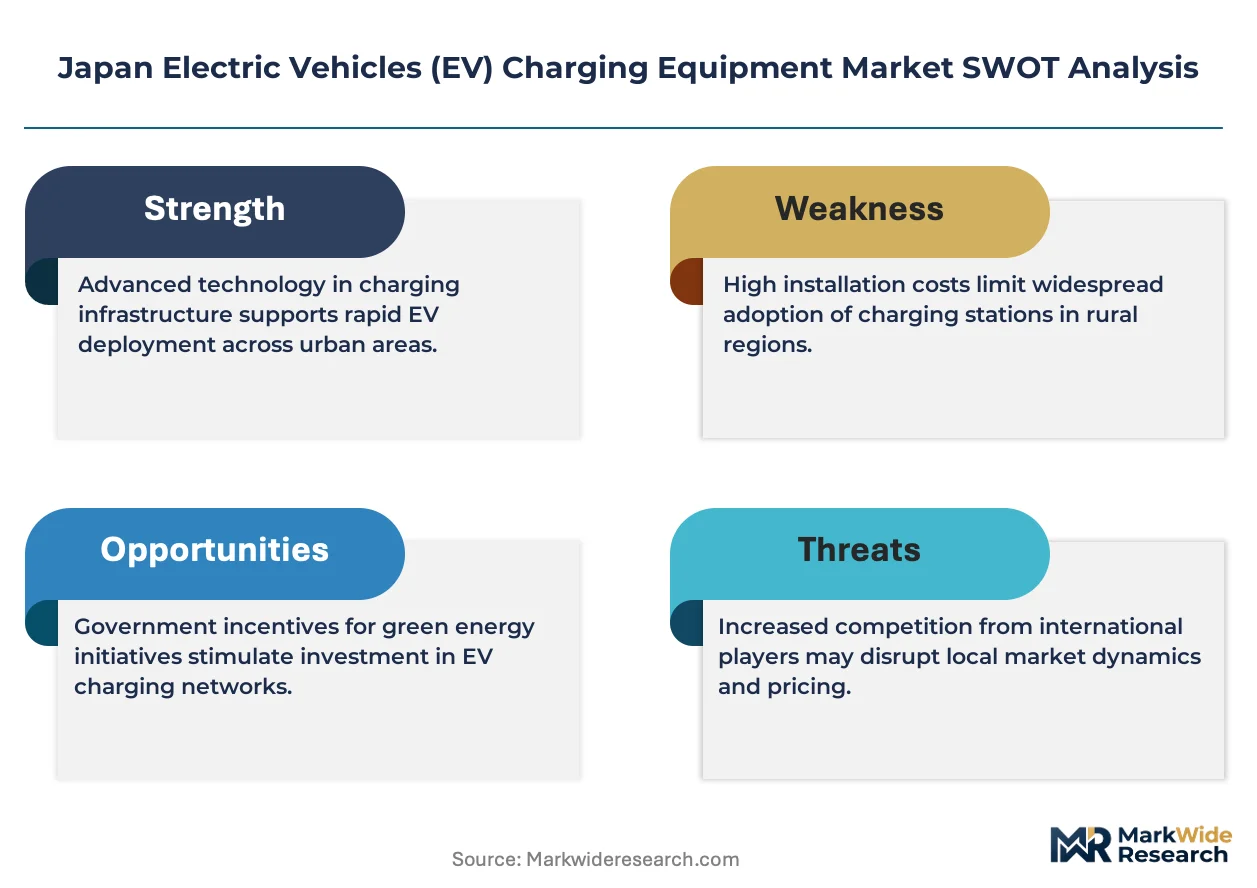
METI's Green Innovation Fund and the Ministry of Economy, Trade and Industry's charger density targets are mandating interoperability standards and accelerating subsidy disbursements for ultra-fast corridor installations. JIS standards for connector compatibility and electrical safety shape product certification requirements, creating compliance thresholds that filter lower-capability suppliers from public procurement pools. Stakeholders must monitor how amendments to Japan's Building Energy Conservation Act will mandate pre-wiring ratios in new commercial developments, as this regulatory lever stands to reshape installation economics and contractor capacity planning across prefectural construction markets.
Market Dynamics
Certified electrical technician shortages across Japan's prefectures are compressing installation capacity and forcing hardware manufacturers to redesign deployment protocols for faster commissioning with lower-skilled labor.
Growth Catalysts
- METI's Green Innovation Fund:Direct subsidy disbursements for ultra-fast corridor installations are accelerating private capital commitment from highway service operators and commercial real estate developers.
- Fleet electrification mandates:Logistics operators across the Greater Tokyo Area are expanding charging infrastructure procurement along major freight corridors to support commercial vehicle transition timelines.
- JIS interoperability standards:Unified connector compatibility and electrical safety requirements are filtering lower-capability suppliers from public procurement pools, concentrating demand on certified hardware providers.
Market Restraints
- Copper and semiconductor input volatility:Power electronics and cable assemblies face raw material cost pressure that compresses margin structures for DC fast-charging hardware manufacturers.
- Grid interconnection queues:TEPCO and regional utilities maintain lengthy approval timelines for high-capacity connections, delaying revenue recognition for corridor deployments.
- Wireless inductive substitution threat:Automakers evaluating pad-based charging for automated parking applications may defer conductive infrastructure investments in premium residential segments.
Strategic Opportunities
- Hokkaido and Tohoku corridor gaps:Northern prefectures exhibit charger density below national targets, creating first-mover positioning for ultra-fast hub developers with utility partnerships.
- Bidirectional V2G integration:Convergence of vehicle-to-grid protocols with building energy management systems opens revenue stacking for commercial real estate operators with captive fleets.
- Amended Building Energy Conservation Act:Pre-wiring mandates for new commercial developments will reshape installation economics and create captive demand for electrical contractors with EV specialization.
Industry Challenges
- Certified electrician scarcity:Prefectural licensing bottlenecks for high-voltage installation work are extending project timelines and inflating labor costs for DC fast-charger deployment.
- Multi-network payment integration:Fleet operators demand seamless roaming across TEPCO, Nippon Charge Service, and regional networks, forcing middleware investments that delay margin recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Electric Vehicles (EV) Charging Equipment Market |
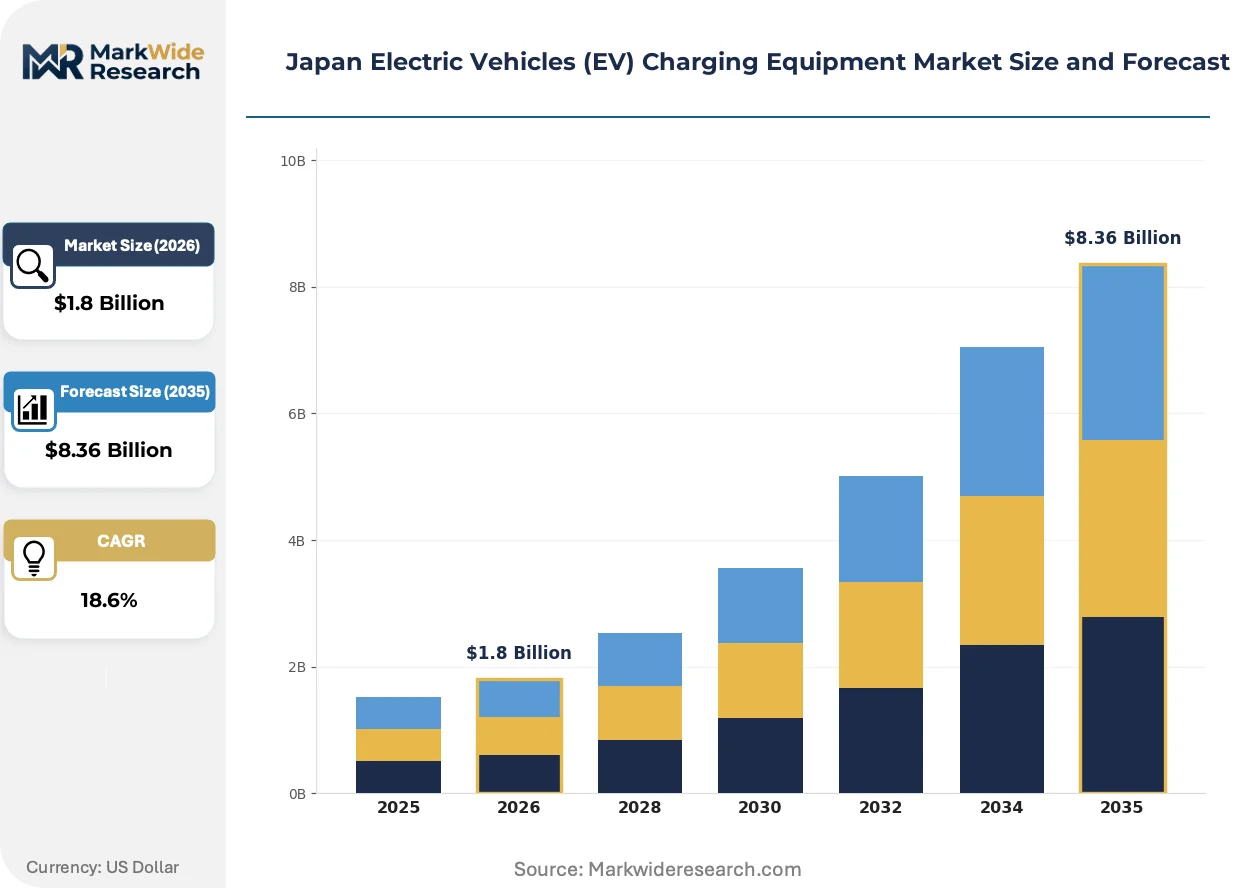
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Chargers, DC Chargers, Wireless Chargers, Fast Chargers Installation Type: Indoor, Outdoor, Public, Private Charging Speed: Level 1, Level 2, Fast Charging, Ultra-Fast Charging End User: Residential, Commercial, Fleet Operators, Government |
| Companies Covered | ENECHANGE Ltd., Sumitomo Electric Industries, ABB, Mitsubishi Corporation, TEPCO (Tokyo Electric Power Company), Delta Electronics Inc., Schneider Electric SE, Nippon Charge Service, Toyota Connected Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Electric Vehicles (EV) Charging Equipment Market Trends and Innovations
Hardware commoditization pressures and software-defined energy management are restructuring competitive advantage away from pure manufacturing scale toward integrated service orchestration.
Modular power conversion architectures are fragmenting the traditional integrated charger market. These swappable sub-10kW power blocks enable field-upgradeable capacity scaling and reduce spare parts inventory for highway service operators. Fleet managers in Osaka-Nagoya corridors are piloting these systems to match charger output to vehicle battery acceptance rates without full hardware replacement.
METI's amended subsidy frameworks now mandate OCPP 2.0.1 communication protocol compliance for all ultra-fast corridor funding eligibility. This regulatory pivot forces legacy hardware operators to retrofit or replace installed base to maintain public procurement access. Kanto region deployments are experiencing the steepest compliance-driven replacement cycles as TEPCO-owned networks modernize.
Fleet procurement committees are consolidating vendor relationships around full-lifecycle service contracts that bundle hardware, installation, maintenance, and energy management into single-source agreements. This behavior shift displaces transactional equipment sales in the commercial segment. Logistics operators with multi-prefecture footprints are driving this consolidation most aggressively in the Greater Tokyo Area and Chubu region.
Japan Electric Vehicles (EV) Charging Equipment Market Segmentation
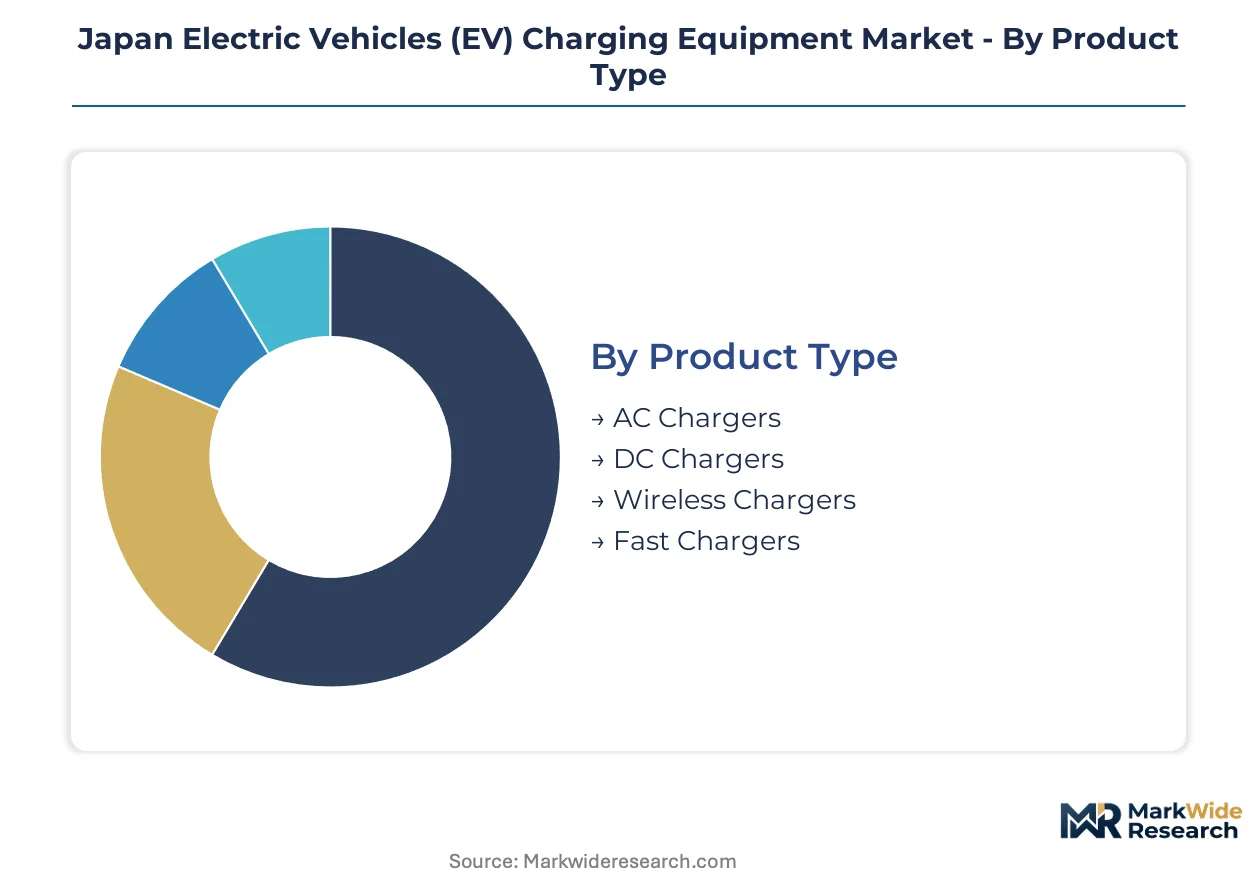
Segmentation in Japan's EV charging equipment market reveals how METI subsidy frameworks and JIS certification requirements reshape procurement patterns across hardware categories. Distinct technical specifications and installation protocols create divergent margin structures and competitive dynamics for suppliers serving each segment cluster.
Product Type:
METI's subsidy tiers differentiate funding eligibility based on power output and communication protocol compliance, concentrating capital flows toward certified high-voltage systems.
- DC Chargers:High-voltage direct current systems deliver 50 kW to 350 kW outputs through liquid-cooled cable assemblies and silicon carbide power electronics. Highway service operators across the Kanto and Chubu corridors prioritize these units to minimize commercial fleet dwell times, though copper price volatility compresses hardware margins.
- AC Chargers:Alternating current units ranging from 3.7 kW to 22 kW utilize onboard vehicle rectification and dominate workplace and multi-unit dwelling deployments. Workplace installations in the Greater Tokyo Area sustain volume leadership where overnight dwell periods accommodate slower replenishment cycles.
- Wireless Chargers:Inductive pad systems utilizing magnetic resonance coupling for automated parking applications.
- Fast Chargers:Intermediate DC systems bridging AC and ultra-fast DC categories for urban commercial deployment.
DC Chargers handles the majority of throughput; Wireless Chargers is the fastest mover on share.
Installation Type:
Cost tier differentiation separates capital-intensive utility-interconnected systems from lower-complexity residential and workplace deployments.
- Public:Street-side and highway-accessible installations requiring utility coordination, civil works, and payment network integration. TEPCO and regional utilities maintain lengthy approval queues for high-capacity connections across the Kanto region, delaying revenue recognition for corridor developers.
- Private:Captive-access systems serving single-entity fleets or residential properties with simplified commissioning protocols. Fleet operators in Osaka-Nagoya logistics corridors are consolidating procurement around full-lifecycle service contracts bundling hardware, installation, and maintenance.
- Outdoor:Weather-hardened enclosures with IP65+ ratings for exposure to coastal humidity and temperature cycling.
- Indoor:Climate-controlled deployments in parking structures and commercial facilities with reduced environmental protection requirements.
Public installations absorb the largest capital allocation; Private deployments are expanding most quickly as fleet electrification accelerates.
Charging Speed:
Application-driven segmentation aligns replenishment rates with vehicle duty cycles and dwell-time economics across passenger and commercial use cases.
- Ultra-Fast Charging:Systems exceeding 150 kW utilizing high-amperage connectors and active thermal management for commercial vehicle turnaround. METI's amended subsidy frameworks mandate OCPP 2.0.1 compliance for corridor funding eligibility, forcing legacy hardware retrofits.
- Level 2:7 kW to 22 kW AC or DC systems matching standard workplace and residential dwell periods. Multi-unit dwelling developers in the Greater Tokyo Area are integrating these units into new construction ahead of amended Building Energy Conservation Act pre-wiring mandates.
- Fast Charging:50 kW to 150 kW DC systems for urban commercial and retail location deployment.
- Level 1:Standard 3.7 kW residential outlets with minimal installation complexity and extended replenishment timelines.
Ultra-Fast Charging commands the steepest investment intensity; Level 2 sustains the broadest installation base.
End User:
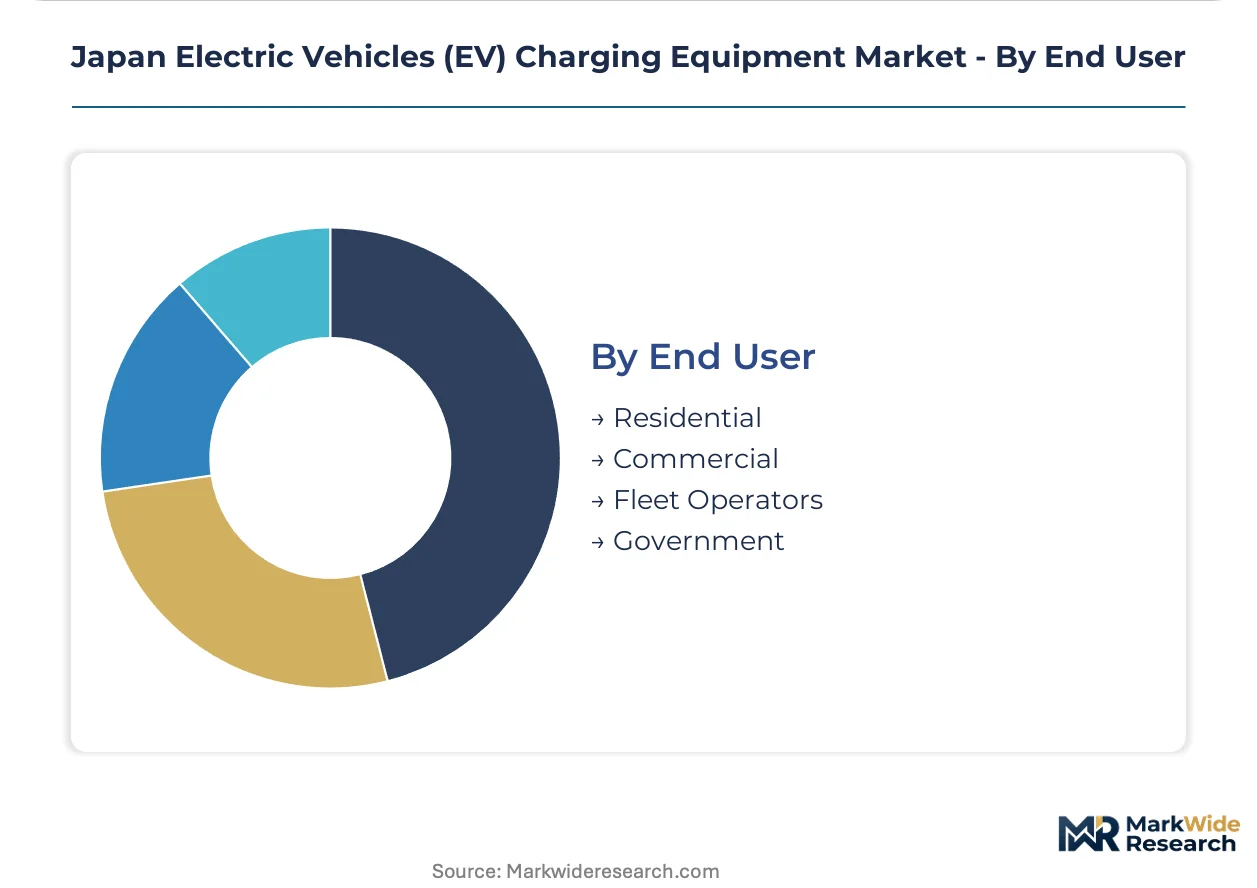
Customer-type segmentation reflects divergent procurement authority, lifecycle cost sensitivity, and network integration requirements across stakeholder categories.
- Fleet Operators:Logistics and commercial transport entities with centralized procurement authority and multi-prefecture deployment footprints. These users demand seamless roaming across TEPCO, Nippon Charge Service, and regional networks, forcing middleware investments that delay margin recovery for hardware suppliers.
- Commercial:Retail, workplace, and real estate developers integrating charging as amenity or revenue infrastructure. Commercial real estate developers in the Greater Tokyo Area are embedding charging stations into new construction to capture METI subsidy disbursements and tenant retention premiums.
- Residential:Individual vehicle owners with single-unit installations and utility rate optimization priorities.
- Government:Municipal and prefectural procurement for public access networks and fleet transition programs.
Fleet Operators drive the largest transaction values; Commercial users are gaining share fastest as real estate integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Charger deployment intensity varies sharply across Japan's prefectures, with metropolitan corridor saturation contrasting against rural infrastructure gaps that reshape procurement priorities for equipment suppliers.
Kanto
The Greater Tokyo Area concentrates Japan's densest charging network, driven by commercial real estate developers embedding stations into new construction. METI's subsidy frameworks accelerate ultra-fast corridor installations along Tomei and Tohoku Expressways. Fleet operators in Saitama and Kanagawa logistics hubs are consolidating procurement around full-lifecycle service contracts.
Kansai
Osaka-Nagoya freight corridors sustain elevated DC fast-charger demand as logistics operators electrify commercial vehicle fleets. The Ministry of Economy, Trade and Industry's interoperability mandates filter procurement toward JIS-certified hardware providers. Workplace installations in Kyoto and Hyogo prefectures dominate AC charger volume as overnight dwell periods accommodate slower replenishment cycles.
Chubu
Automotive supply chain concentration around Nagoya shapes specialized charging requirements for manufacturer captive fleets. Prefectural licensing bottlenecks for high-voltage electrical work extend installation timelines across Aichi and Shizuoka. Highway service operators along the Chuo and Higashimeihan Expressways prioritize modular power conversion architectures for field-upgradeable capacity scaling.
Kyushu
Industrial port cities including Fukuoka and Kitakyushu drive demand for heavy-duty commercial vehicle charging infrastructure. Regional utilities maintain lengthy grid interconnection queues that delay revenue recognition for corridor developers. Amended Building Energy Conservation Act pre-wiring mandates are reshaping installation economics for new commercial developments in Kumamoto and Kagoshima.
Hokkaido and Tohoku
Northern prefectures exhibit charger density below national targets, creating first-mover positioning for ultra-fast hub developers with utility partnerships. TEPCO and regional utilities face capacity constraints in extending high-voltage connections across sparsely populated territories. Sapporo and Sendai municipal governments are accelerating public procurement for fleet transition programs to close infrastructure gaps.
Japan Electric Vehicles (EV) Charging Equipment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with cable and power systems heritage conferring advantages in high-voltage DC hardware production. Utility-affiliated networks leverage direct grid ownership to anchor corridor positions across metropolitan regions. Payment platform specialists reduce friction for multi-network fleet users through interoperable roaming systems. Competitive moves concentrate on strategic partnerships with real estate developers and capacity expansion along underpenetrated northern corridors.
Within the integrated infrastructure tier, Sumitomo Electric Industries and TEPCO occupy positions shaped by captive supply chain relationships and direct utility network ownership. Nippon Charge Service exemplifies the interoperability-focused archetype, anchoring payment integration capabilities that fleet operators demand for seamless multi-network access. These three entities represent distinct competitive vectors: manufacturing heritage, grid control, and software-layer mediation.
| Leading Market Players |
|---|
| ENECHANGE Ltd. |
| Sumitomo Electric Industries |
| ABB |
| Mitsubishi Corporation |
| TEPCO (Tokyo Electric Power Company) |
| Delta Electronics Inc. |
| Schneider Electric SE |
| Nippon Charge Service |
| Toyota Connected Corporation |
| Others |
Pricing and Supply Chain Analysis
Manufacturing scale economies in silicon carbide power electronics concentrate production among Japanese and South Korean foundries, compressing price floors for DC fast-charging hardware while elevating procurement leverage for fleet operators with multi-prefecture deployment footprints.
Pricing Analysis
Long-term offtake agreements dominate procurement between highway service operators and DC hardware manufacturers, though spot purchasing persists for modular power block upgrades. Price differentiation rests on JIS certification tier and after-sales service bundling, with certified installers commanding premiums over uncertified competitors. Cost compression in copper-intensive cable assemblies is intensifying because of commodity volatility, squeezing margins for integrated hardware suppliers. Fleet operators exhibit the highest price sensitivity, while commercial real estate developers prioritize certification compliance over unit economics.
Supply Chain Analysis
Taiwan Strait transit routes for semiconductor wafers represent a critical chokepoint for silicon carbide MOSFET supply to Japanese power electronics assemblers. Hardware production draws from Japan, South Korea, and China for power conversion modules, liquid-cooled cable assemblies, and enclosure fabrications respectively. Single-source vulnerability in high-voltage connector supply creates exposure for corridor developers facing METI-mandated deployment timelines. Distribution runs through direct OEM relationships with fleet operators and utility-affiliated procurement channels for public network expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator procurement consolidation across the Greater Tokyo Area and Chubu region has shifted bargaining power toward buyers, fragmenting vendor relationships and compressing margin recovery timelines for hardware suppliers.
For Market Incumbents: Compound defensive positioning through backward integration into power electronics manufacturing and captive installation capacity in Saitama and Kanagawa prefectures. Wireless inductive substitution threats from premium automakers necessitate software-layer investments in OCPP 2.0.1 compliance to maintain METI subsidy access. Certification scarcity for high-voltage electrical work demands training academy partnerships with prefectural licensing boards. For New Entrants and Emerging Players: Differentiate on modular power conversion architectures enabling field-upgradeable capacity scaling for highway service operators in Hokkaido and Tohoku corridor gaps. White-space concentration exists in northern prefecture ultra-fast hub development where TEPCO grid interconnection queues create first-mover windows. Target full-lifecycle service contracts bundling hardware, installation, and maintenance for logistics operators with multi-prefecture footprints. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among payment platform specialists with interoperable roaming capabilities across TEPCO and regional utility networks. Long-term viability across the analysis window favors acquisition targets with JIS-certified hardware portfolios and established utility partnerships. Monitor METI subsidy amendment announcements as inflection indicators for replacement cycle acceleration in legacy installed base.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Electronics | Captive silicon carbide MOSFET supply secures margin control against Taiwan Strait transit disruptions. |
| OCPP 2.0.1 Protocol Compliance Investment | METI subsidy eligibility mandates force legacy hardware retrofits across TEPCO-owned Kanto networks. |
| Prefectural Licensing Board Partnerships | Certified electrician pipeline expansion addresses installation bottlenecks delaying corridor revenue recognition. |
| Full-Lifecycle Service Contract Bundling | Single-source agreements displace transactional equipment sales among Osaka-Nagoya logistics operators. |
| Hokkaido-Tohoku Corridor First-Mover Positioning | Sub-national charger density gaps create ultra-fast hub development opportunities with utility co-investment. |
Research Methodology
A standing panel of fleet procurement directors, METI policy officers, prefectural electrical licensing administrators, and highway service operator infrastructure heads provided ongoing calibration against secondary validation from METI subsidy disbursement records, JIS certification databases, TEPCO grid interconnection filings, and commercial real estate development permits. Bottom-up installation volume triangulation with top-down hardware shipment analysis ensured cross-verification across metropolitan and rural prefectural deployment patterns.
Consistency checks against regional utility capex disclosures and automotive OEM electrification timelines validated projection outputs across the modeling period. Segmentation dimensions incorporated product type, installation category, charging speed tier, and end-user archetype with prefectural granularity. CAGRs were derived from unit economics modeling of subsidy-eligible corridor deployments and fleet electrification mandate compliance schedules, with copper price sensitivity scenarios and grid interconnection queue duration assumptions as industry-specific forecast inputs.
Material uncertainties — METI subsidy framework amendments, JIS standard revisions, and regional utility grid capacity allocation decisions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding fleet electrification timeline adherence and certified electrician supply expansion. Practitioners should keep alternative scenarios live as wireless inductive technology maturation and Building Energy Conservation Act pre-wiring mandate enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
EV Charging System Test and Certification Equipment Market
Electric Vehicle Charging
Automotive EV Charging Adapters Market
Electric Vehicle Charging
Germany Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Supply Equipment (EVSE) Market
Electric Vehicle Charging
Global Electric Vehicle Charging As a Service Market
Electric Vehicle Charging
United States Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
Belgium Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Copper in Electric Vehicle Market
Electric Vehicle Charging
Electric Vehicle AC Charging Pile Market
Electric Vehicle Charging
Asia-Pacific Wireless Electric Vehicle Charging Market
Electric Vehicle Charging
Electric Two Wheeler Charging Station Market
Electric Vehicle Charging
US Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Battery Swap Station Market
Electric Vehicle Charging
Solar Charge Controller Market
Electric Vehicle Charging
South Korea Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Australia Electric Vehicle Charging Equipment Market