
 Europe Oil and Gas Electric Submersible Pump Market | 2026-2036
Europe Oil and Gas Electric Submersible Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Oil and Gas Electric Submersible Pump Market Foresight
Buyer concentration among North Sea offshore operators is consolidating as national oil companies and major independents pool procurement for subsea artificial lift packages. Schlumberger Limited leverages its integrated drilling and production technology portfolio to anchor long-term service contracts across Norwegian and UK assets. Baker Hughes Company competes through specialized high-temperature ESP systems designed for ultra-deep well environments. Weatherford International plc sustains regional presence through localized manufacturing and aftermarket service hubs in Aberdeen and Stavanger.
An electric submersible pump for oil and gas applications is a centrifugal pumping system comprising a submersible motor, seal section, gas separator, and multistage pump section, typically operating at depths exceeding 1,000 meters with power ratings from 100 to 1,500 horsepower to artificially lift hydrocarbons from low-pressure reservoirs. Its primary purpose is to maintain or increase production rates in wells where natural reservoir pressure proves insufficient for commercial flow. Multi-stage pumps occupy the dominant product position due to their capacity handling high-volume lift requirements in deep offshore wells, while horizontal pumps represent the fastest-growing configuration segment driven by directional drilling complexity in mature fields. Onshore installations retain the largest installation-type share, though subsea deployment is gaining traction as tieback economics improve.
The EU Green Deal, F-Gas Regulation, and REACH framework collectively mandate stricter material compliance, energy efficiency benchmarks, and restricted substance controls for ESP components deployed across European waters. ECHA substance restrictions and CE marking requirements under the Machinery Directive shape supplier qualification timelines and aftermarket parts sourcing protocols. Stakeholders must monitor evolving MEE carbon intensity thresholds for offshore equipment and assess how Norway's carbon tax regime affects brownfield ESP replacement cycles.
Market Dynamics
Offshore brownfield revitalization across the Norwegian and UK North Sea is compressing replacement cycles for subsea artificial lift systems as operators prioritize production maintenance over greenfield development.
Growth Catalysts
- F-Gas Regulation Phase-Down:The EU F-Gas Regulation mandates progressive hydrofluorocarbon reduction, forcing ESP seal system upgrades toward low-global-warming-potential alternatives across member state waters.
- Norwegian Continental Shelf Expansion:Equinor and Aker BP are sanctioning subsea tieback projects requiring high-reliability ESP packages for extended-reach wells in the Johan Sverdrup and Snøhvit fields.
- Digital Twin Integration:Real-time pump performance monitoring through subsea sensor networks is converging with predictive maintenance platforms, reducing unplanned downtime in North Sea installations.
Market Restraints
- Specialized Alloy Supply Concentration:Duplex and super-duplex stainless steel forgings for corrosion-resistant pump stages concentrate among Nordic metallurgical suppliers, creating input bottlenecks during surge demand periods.
- REACH Substance Restrictions:ECHA candidate list expansions for persistent organic pollutants complicate elastomer selection for motor lead and seal assemblies, extending qualification timelines.
- Geothermal Heat Pump Substitution:Onshore geothermal direct-use projects in the Netherlands and Germany are diverting engineering talent and electrical infrastructure investment from oilfield ESP deployment.
Strategic Opportunities
- UKCS Decommissioning Delay Projects:The UK North Sea Transition Authority's temporary cessation of production extensions creates demand for ESP refurbishment packages to sustain marginal field economics.
- Subsea Power Grid Integration:All-electric subsea production systems eliminate hydraulic umbilical complexity, enabling ESP deployment at greater distances from host platforms in Norwegian deepwater.
- EU Green Deal Industrial Funding:The European Investment Bank's sustainable energy financing windows support low-carbon brownfield optimization, including electrified artificial lift retrofits.
Industry Challenges
- Subsea Electrical Technician Scarcity:Specialized competence in high-voltage subsea connector assembly and pressure-balanced oil-filled cable termination remains concentrated among aging Aberdeen and Stavanger workforces.
- CE Marking Conformity Assessment:The Machinery Directive's harmonized standards for subsea rotating equipment lack ESP-specific guidance, forcing case-by-case notified body interpretation and documentation rework.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Oil and Gas Electric Submersible Pump Market |
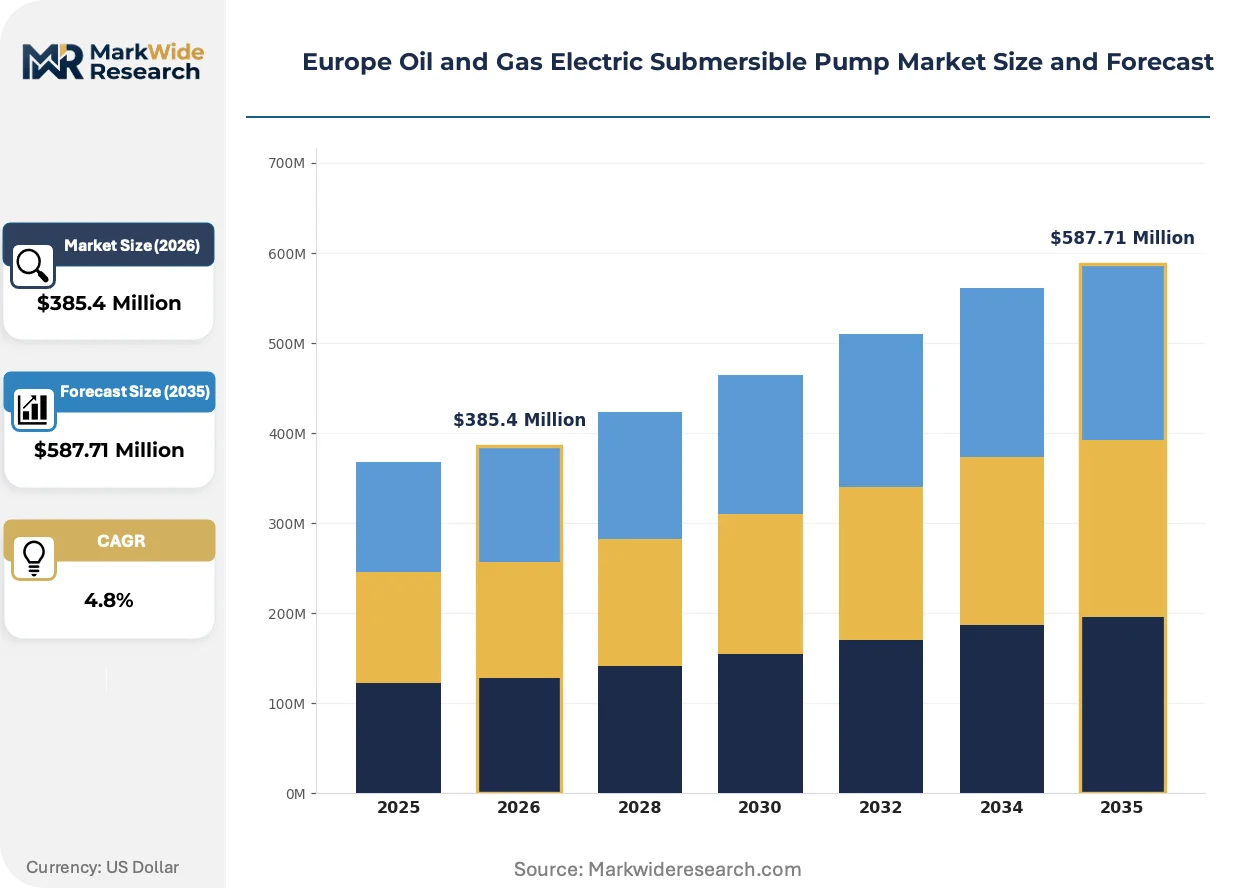
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $587.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Pumps, Horizontal Pumps, Deep Well Pumps, Multi-Stage Pumps End User: Oil Extraction, Natural Gas Production, Wastewater Management, Industrial Applications Installation Type: Onshore, Offshore, Subsea, Above Ground Power Rating: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | Weatherford International plc, National Oilwell Varco, Schlumberger Limited, DOS Canada Inc., Alkhorayef Petroleum Company, Baker Hughes Company, Borets International Limited, Novomet, Halliburton Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Oil and Gas Electric Submersible Pump Market Shifts & Advancements
Permanent magnet motor technology and subsea power electronics are compressing ESP footprint and energy intensity while enabling deeper deployment envelopes in high-pressure, high-temperature reservoirs.
Permanent magnet synchronous motor technology is replacing conventional induction designs in next-generation ESP systems, delivering 15-20 percentage point efficiency gains at partial load conditions. Norwegian operators are mandating PMM configurations for all new subsea tieback artificial lift packages. This efficiency architecture is converging with variable speed drive integration to reduce topside power consumption and carbon intensity per barrel lifted.
The EU F-Gas Regulation's 2030 phase-down targets are eliminating hydrofluorocarbon-based seal barrier fluids from approved equipment lists. ESP manufacturers are reformulating motor oil and seal chamber fluids with synthetic hydrocarbon and perfluoropolyether alternatives. Subsea system suppliers serving Norwegian and UK waters face accelerated recertification schedules to maintain compliance across installed base refurbishment programs.
Integrated service contracting is displacing discrete equipment procurement as national oil companies bundle ESP supply with installation, monitoring, and replacement liability. Major North Sea operators now specify availability-based remuneration models where vendors assume production risk. This performance transfer is most advanced in Norwegian Equinor-operated assets, where integrated drilling and production contractors bear full artificial lift lifecycle responsibility.
Europe Oil and Gas Electric Submersible Pump Market Segmentation
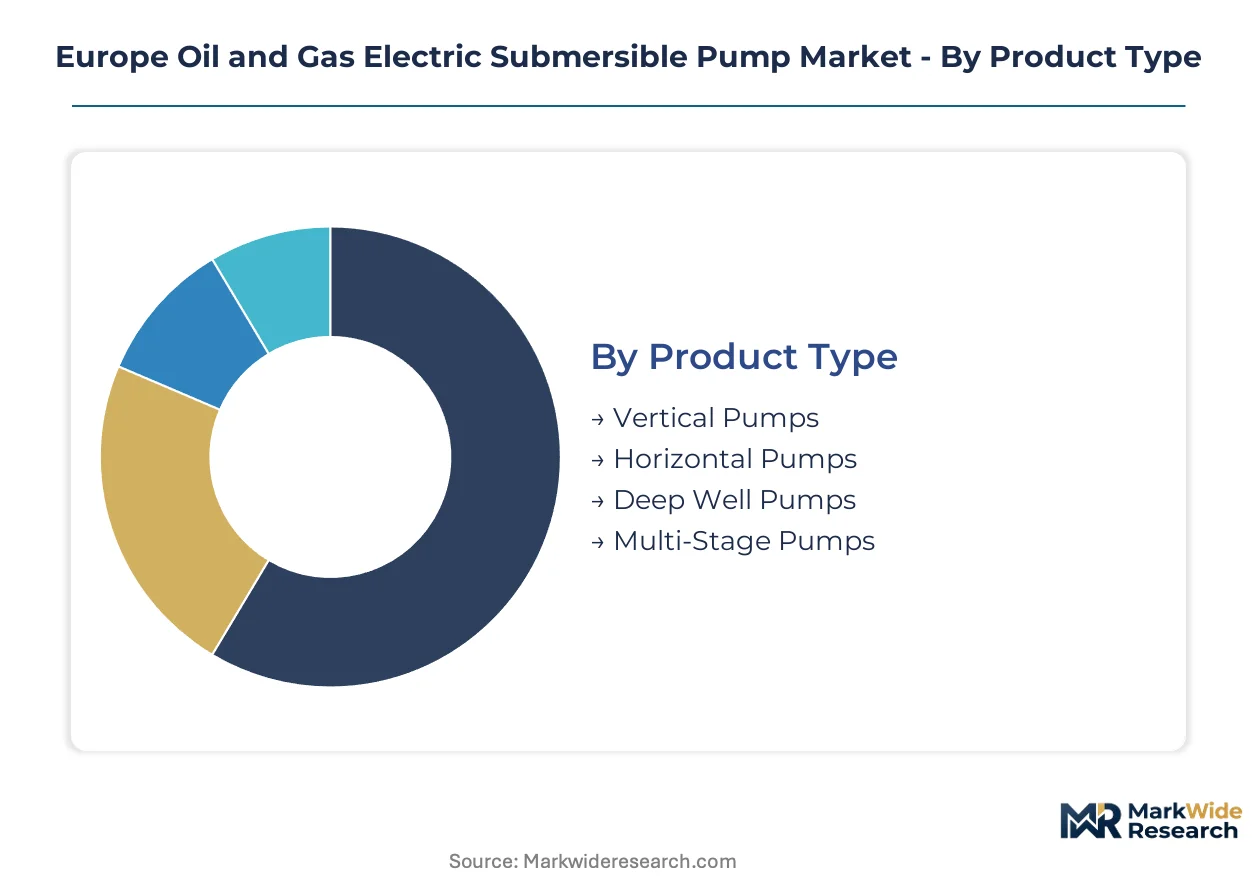
ESP procurement patterns diverge sharply across deployment environments and reservoir characteristics. Capital allocation priorities in the North Sea favor configurations that minimize platform footprint while maximizing run life in corrosive conditions.
Product Type:
Multi-stage pumps command the highest upfront capital outlay due to precision-machined impeller stacks and super-duplex metallurgy requirements.
- Multi-Stage Pumps:These systems stack 50-400 identical pump stages in series to generate pressure ratios exceeding 5,000 psi for deep offshore lift. Norwegian operators specify these for Johan Sverdrup subsea tiebacks where single-point failure costs exceed $2 million per day.
- Horizontal Pumps:Configured with side-discharge geometry to navigate deviated wellbores in mature UK North Sea fields. Demand concentrates in Shell and BP brownfield revitalization programs where sidetrack drilling angles exceed 60 degrees from vertical.
- Vertical Pumps:Standard configuration for conventional onshore installations with straight-hole completion geometry.
- Deep Well Pumps:Reinforced thrust bearing assemblies rated for 3,000+ meter true vertical depth deployments.
Most installed capacity flows through Multi-Stage Pumps. Expansion is steepest in Horizontal Pumps.
End User:
Application-driven specification requirements create distinct procurement workflows across hydrocarbon extraction versus secondary services.
- Oil Extraction:Primary revenue driver deploying high-horsepower ESP strings in low-pressure carbonate reservoirs. Equinor and Aker BP account for the majority of new subsea artificial lift packages sanctioned on the Norwegian continental shelf.
- Natural Gas Production:Dewatering applications in coalbed methane and tight gas sands require corrosion-resistant metallurgy for sour service conditions. UK North Sea gas field operators specify duplex stainless steel construction for H2S environments exceeding 100 ppm.
- Wastewater Management:Produced water reinjection and disposal well applications.
- Industrial Applications:Refinery sump drainage and tank farm transfer duties.
Oil Extraction absorbs the majority of capital deployment. Natural Gas Production is gaining share fastest as marginal gas field economics improve.
Installation Type:
Subsea tieback architectures demand integrated production system contracting rather than discrete equipment procurement.
- Subsea:Retrievable ESP modules deployed on mudline templates with flying leads to host platforms. Norwegian deepwater projects require pressure-balanced oil-filled cable systems rated for 300 bar ambient pressure and 150°C bottom-hole temperature.
- Offshore:Platform-based installations with surface-controlled variable speed drives. UK North Sea operators favor this configuration for hub-and-spoke field developments where multiple wellheads cluster around existing jacket structures.
- Onshore:Conventional land-based deployments with surface power distribution.
- Above Ground:Temporary test production and early production facilities.
Offshore infrastructure hosts the largest installed base. Subsea deployment is climbing the fastest as tieback distances extend beyond 20 kilometers.
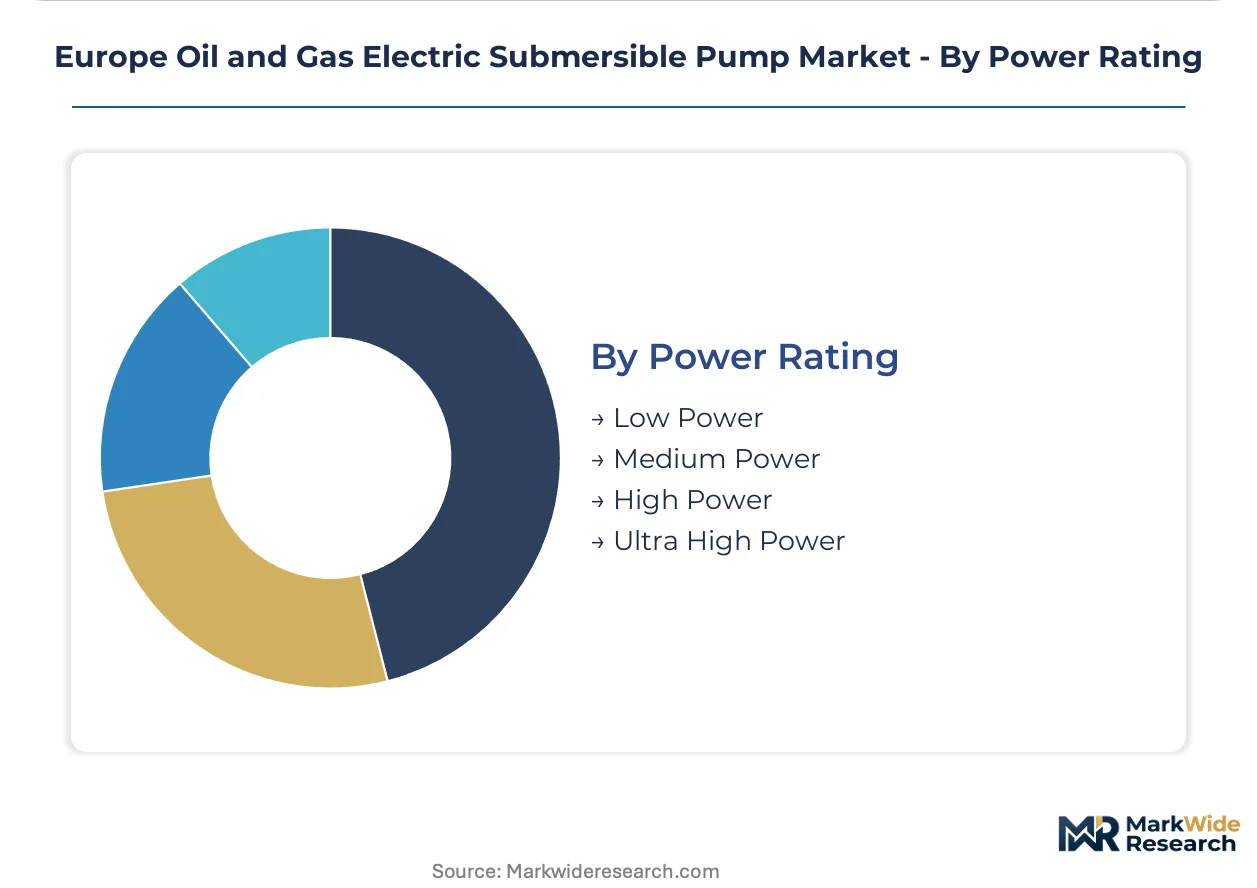
Power Rating:
Motor sizing decisions correlate directly with reservoir productivity index and required drawdown pressure.
- High Power:500-1,500 horsepower permanent magnet motor systems specified for high-volume producers in Norwegian chalk reservoirs. These configurations integrate with subsea variable speed drives to optimize power consumption across declining production profiles.
- Ultra High Power:Emerging category exceeding 1,500 horsepower for extended-reach multilateral wells. Equinor pilots these in Johan Castberg field developments where single ESP strings must lift from 2,400 meter measured depth.
- Medium Power:100-500 horsepower range for standard offshore producers.
- Low Power:Sub-100 horsepower units for stripper well and marginal field applications.
High Power systems dominate capital expenditure allocation. Ultra High Power represents the steepest expansion trajectory as well complexity increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized subsea electrical technicians concentrate in Aberdeen and Stavanger, anchoring Europe's artificial lift engineering base. These workforce clusters support brownfield ESP refurbishment and subsea tieback installations across the North Sea basin. National oil companies and major independents leverage this talent pool for integrated production system contracting.
Norway
Equinor and Aker BP drive subsea ESP demand through Johan Sverdrup and Snøhvit field developments requiring high-reliability packages for extended-reach wells. Norway's carbon tax regime compresses replacement cycles for older artificial lift systems on the continental shelf. Stavanger hosts the primary engineering cluster for pressure-balanced oil-filled cable systems rated to 300 bar.
United Kingdom
Shell and BP brownfield revitalization programs generate demand for horizontal ESP configurations navigating sidetrack drilling angles exceeding 60 degrees. The UK North Sea Transition Authority's temporary cessation of production extensions sustains marginal field economics through ESP refurbishment. Aberdeen anchors aftermarket service capacity for platform-based installations across the UKCS.
Germany
Industrial pump manufacturers supply precision-machined impeller stacks and super-duplex metallurgy components to North Sea operators. REACH substance restrictions from ECHA complicate elastomer selection for motor lead assemblies, extending supplier qualification timelines. Ruhr industrial centers concentrate forging capacity for corrosion-resistant pump stages.
Netherlands
Onshore geothermal direct-use projects divert electrical infrastructure investment from oilfield ESP deployment in Groningen and surrounding provinces. The country's national energy regulator enforces strict efficiency benchmarks for rotating equipment under EU Green Deal implementation. Rotterdam-area fabricators specialize in variable speed drive integration for topside power optimization.
Denmark
Maersk Oil legacy assets and TotalEnergies-operated fields require ESP maintenance for late-life production maintenance in the Danish North Sea. The Danish Energy Agency aligns offshore equipment standards with EU F-Gas Regulation phase-down targets for seal barrier fluids. Copenhagen technical consultancies support subsea power grid integration for all-electric production systems.
Europe Oil and Gas Electric Submersible Pump Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Europe's ESP procurement landscape. The market structure tiers around integrated service contractors, equipment-focused manufacturers, and regional aftermarket providers. Three archetypes dominate: full-lifecycle integrated drillers, high-technology system specialists, and localized service hub operators. Competitive moves concentrate on strategic partnerships for subsea tieback packages and portfolio diversification into permanent magnet motor architectures.
Within the integrated service tier, Schlumberger Limited and Baker Hughes Company exemplify full-lifecycle contractors anchoring long-term availability-based agreements. Weatherford International plc occupies a position among regional specialists leveraging localized manufacturing presence. These three entities represent the dominant competitive anchors across Norwegian and UK North Sea asset portfolios.
| Leading Market Players |
|---|
| Weatherford International plc |
| National Oilwell Varco |
| Schlumberger Limited |
| DOS Canada Inc. |
| Alkhorayef Petroleum Company |
| Baker Hughes Company |
| Borets International Limited |
| Novomet |
| Halliburton Company |
| Others |
Supply & Pricing Matrix
Super-duplex stainless steel forgings flow from Nordic metallurgical suppliers through three distinct pricing tiers before reaching North Sea offshore operators. Duplex alloy input costs cascade from German Ruhr forging centers into equipment quotations, with integrated service contractors capturing margin through bundled lifecycle contracts while standalone equipment vendors compete on unit economics.
Pricing Analysis
Bundled availability-based contracts dominate Norwegian continental shelf procurement, displacing discrete equipment purchases. Pricing stratifies across integrated service packages, standalone system sales, and refurbishment-only tiers. Cost compression in the standalone tier is intensifying because REACH compliance extends elastomer qualification timelines. National oil companies exhibit lowest price sensitivity due to production risk transfer, while marginal field operators in the UK North Sea face acute capital constraint pressure.
Supply Chain Analysis
Direct-to-operator channels handle integrated artificial lift packages from Schlumberger and Baker Hughes, while regional distributors serve aftermarket parts demand. Manufacturing concentrates in Germany, Norway, and the United Kingdom. Super-duplex forgings, permanent magnet motor assemblies, and pressure-balanced cable systems anchor component sourcing. Single-source vulnerability concentrates in specialized subsea electrical technician labor pools across Aberdeen and Stavanger. Distribution runs through platform operators, subsea installation contractors, and localized service hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Permanent magnet motor efficiency gains justify premium-tier positioning as operators face carbon tax exposure. Margin expansion hinges on converting standalone equipment sales to integrated lifecycle contracts.
For Market Incumbents: Deepen backward integration into permanent magnet motor manufacturing to capture efficiency premium value. Secure captive forging capacity for super-duplex metallurgy before Nordic supplier bottlenecks tighten. Anchor long-term availability contracts with Equinor and Aker BP before geothermal energy projects divert electrical engineering talent from oilfield services. For New Entrants and Emerging Players: Begin with subsea power electronics integration for all-electric production systems, the most penetrable white-space segment. Target UKCS decommissioning delay projects where temporary cessation extensions sustain marginal field demand. Pursue CE marking certification for subsea rotating equipment to overcome Machinery Directive interpretation barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where integrated service contractors absorb standalone equipment vendors unable to finance permanent magnet motor R&D. Long-term viability favors full-lifecycle artificial lift specialists with Norwegian continental shelf presence. Watch ECHA substance list expansions as inflection signals for elastomer-dependent motor lead manufacturers facing forced obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Motor Transition | Equinor mandates PMM configurations for all new subsea tieback packages. |
| Subsea Power Grid Integration | All-electric systems eliminate hydraulic umbilical complexity for deepwater deployment. |
| REACH Compliance Recertification | ECHA candidate list expansions force reformulation of motor seal barrier fluids. |
| Integrated Service Contracting | Availability-based remuneration transfers production risk to vendors. |
| UKCS Brownfield Refurbishment | North Sea Transition Authority extensions sustain ESP replacement demand. |
Research Methodology
Bottom-up offshore operator modeling reconciled against top-down ESP manufacturer shipment tracking forms the analytical core. Primary interviews with subsea project engineers, artificial lift procurement leads at national oil companies, aftermarket service managers in Aberdeen and Stavanger, and EPC contractors handling platform installations combined with secondary validation from Norwegian Petroleum Directorate production data, UK North Sea Transition Authority field development approvals, ECHA substance restriction databases, and EU Green Deal implementation guidance. Top-down customs data for super-duplex steel imports and bottom-up field-by-field artificial lift deployment records triangulate market sizing.
Historical trendline analysis of replacement cycle compression across the Norwegian and UK continental shelves informs projection parameters. Segmentation dimensions modeled include pump configuration, installation environment, power rating tier, and end-use application across oil extraction and gas dewatering. CAGRs derive from correlating brownfield capital allocation patterns with regulatory compliance cost trajectories. Subsea tieback sanctioning schedules and carbon tax regime adjustments feed scenario-weighted forecast outputs.
Several conditions sit outside the modeled scope, including unannounced greenfield discoveries, abrupt EU F-Gas Regulation acceleration, and geopolitical disruption to Nordic metallurgical supply. Forecasts reflect documented assumptions regarding operator capital discipline and technology adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Automation and Instrumentation Market
Oil & Gas
GCC and North Africa Coiled Tubing Market
Oil & Gas
Oil Tank Rotating Stacker Market
Oil & Gas
Intelligent Completion Sales Market
Oil & Gas
GCC Oil and Gas Separation Market
Oil & Gas
Middle-East Oilfield Services Market
Oil & Gas
Well Abandonment Services Market
Oil & Gas
Southeast Asia Oil and Gas EPC Market
Oil & Gas
Nigeria Wireline Logging Services Market
Oil & Gas
Global Completion Equipment and Services Market
Oil & Gas
Vacuum Gas Oil Market
Oil & Gas
LNG Loading Skid Market
Oil & Gas
Middle-East Enhanced Oil Recovery Market
Oil & Gas
Chad Oil and Gas Market
Oil & Gas
Oil Hose Market
Oil & Gas
Oil Country Tubular Goods (OCTG) Market