
 North America Surge Arresters Market | 2026-2036
North America Surge Arresters Market Size, Share, and Industry Trends Forecast 2026-2036
North America Surge Arresters Market Analytics
Multi-source procurement for critical surge protection components is decoupling from legacy single-vendor dependencies across major North American utilities. Eaton Corporation PLC leverages its integrated electrical portfolio to anchor utility channel relationships, while Hubbell Incorporated sustains domestic manufacturing scale for rapid-turn replacement orders. Schneider Electric SE differentiates through IEC-aligned design architectures that streamline cross-border deployment into Canadian provinces.
North America surge arresters are overvoltage protection devices typically constructed with zinc oxide disc columns housed in polymer or porcelain insulators, designed to limit transient voltage excursions on power lines and equipment terminals. Metal oxide varistors dominate product type revenue due to their non-linear voltage-current characteristics and superior energy absorption capacity relative to legacy silicon carbide alternatives. Application demand tilts toward power distribution and renewable energy segments where solar farm interconnects and offshore wind tie-ins multiply exposure to lightning-induced transients. End user procurement by utilities concentrates in transmission-grade ratings, while manufacturing and telecommunications providers drive mid-voltage indoor installation volumes.
IEEE C62.11 and NERC CIP-014 establish baseline performance and physical security standards that shape product design and testing protocols across the United States. Health Canada's PMRA and provincial electrical safety authorities enforce parallel certification tracks that vendors must navigate for full North American market access. Stakeholders should monitor evolving grid hardening mandates and state-level renewable portfolio standards that will recalibrate surge arrester specification requirements.
Market Dynamics
Utility-scale grid modernization across the United States is accelerating procurement of metal oxide varistor-based protection systems, while renewable integration strains existing infrastructure and tightens compliance thresholds under NERC reliability standards.
Growth Catalysts
- NERC CIP-014 Physical Security Mandates:Transmission owners must harden substations against physical attacks, driving replacement cycles for aging porcelain-housed arresters with polymer designs that withstand ballistic and environmental stress.
- Texas ERCOT Interconnection Strain:Record renewable capacity additions in the Texas panhandle multiply lightning exposure on collector systems, forcing wind farm developers to specify higher energy-absorption ratings for line-terminal protection.
- Silicon Carbide Displacement:Metal oxide varistor technology now dominates new installations due to superior non-linear voltage-current characteristics and reduced maintenance requirements relative to legacy silicon carbide disc assemblies.
Market Restraints
- Zinc Oxide Disc Supply Concentration:Specialty ceramic disc manufacturing concentrates among a limited supplier base in East Asia, exposing North American arrester assemblers to input cost volatility and extended lead times.
- Porcelain Insulator Fragility:Legacy porcelain-housed arresters remain susceptible to catastrophic fracture during seismic events or vandalism, creating liability exposure that slows utility adoption in earthquake-prone California corridors.
- IEEE C62.11 Testing Burden:Accelerated aging and pollution testing protocols extend product certification timelines, compressing vendor margins and delaying revenue recognition for new design introductions.
Strategic Opportunities
- Mexico CFE Grid Expansion:Comisión Federal de Electricidad transmission buildout creates demand for IEC-aligned surge protection architectures that Canadian and US vendors can supply through cross-border manufacturing footprints.
- Offshore Wind Tie-In Protection:Atlantic coast offshore wind projects require subsea cable termination arresters rated for salt-fog environments, opening specialized product tiers beyond standard transmission-grade offerings.
- State Renewable Portfolio Standards:California SB 100 and New York CLCPA mandates are recalibrating procurement specifications to favor arresters with extended service life guarantees that align with solar farm depreciation schedules.
Industry Challenges
- Polymer Housing Material Science Expertise:Compound formulation for track-resistant silicone rubber housings requires specialized polymer chemistry talent that utilities and manufacturers struggle to recruit in tight labor markets.
- Legacy Silicon Carbide System Integration:Replacing aged silicon carbide arresters with metal oxide units often requires coordinated buswork modifications and protection relay recalibration, extending project execution timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Surge Arresters Market |
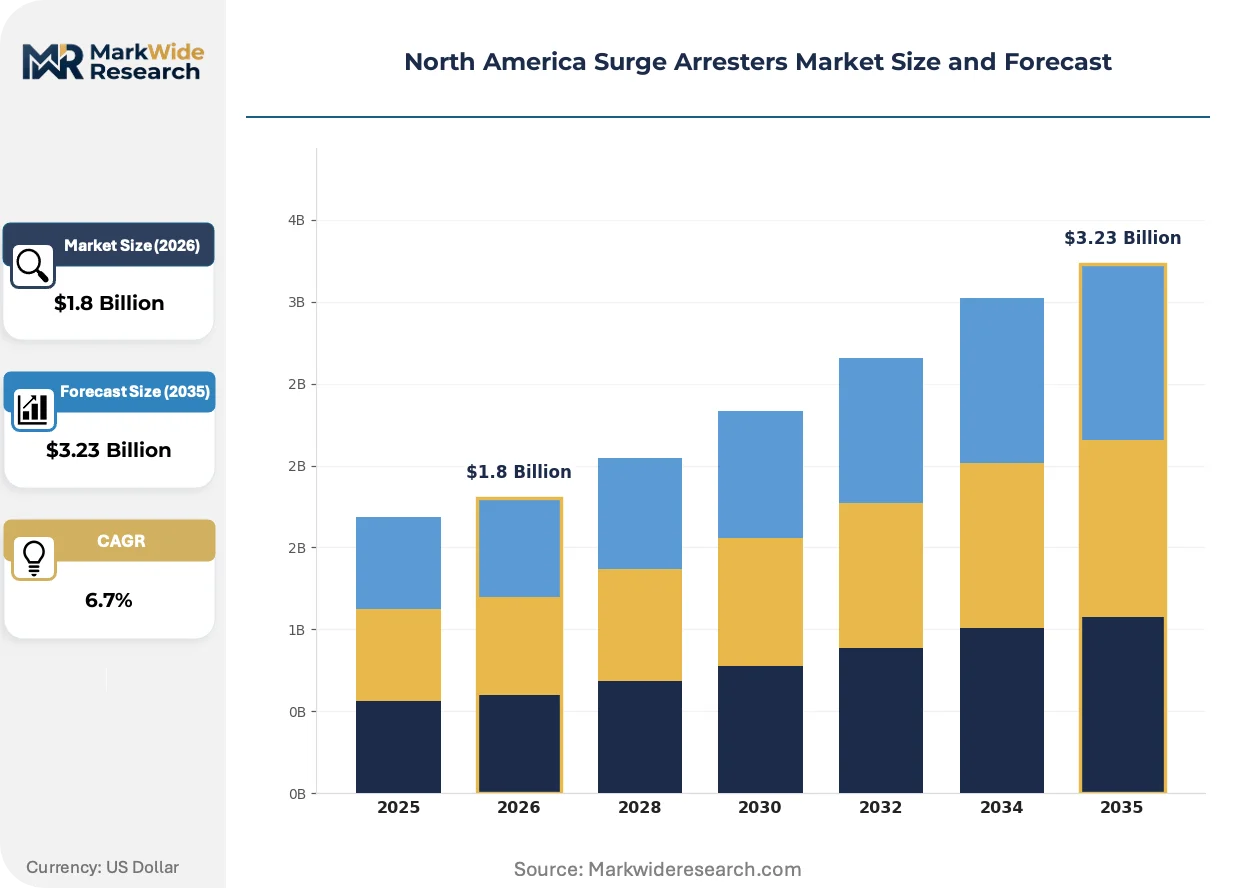
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Oxide Varistors, Gas Discharge Tubes, Transient Voltage Suppressors, Carbide Surge Arresters Application: Power Distribution, Telecommunications, Renewable Energy, Industrial Equipment End User: Utilities, Manufacturing, Telecommunications Providers, Residential Users Installation Type: Onshore, Offshore, Indoor, Outdoor |
| Companies Covered | ABB Ltd, Eaton Corporation PLC, Emerson Electric Co., Schneider Electric SE, Siemens AG, General Electric Company, Hubbell Incorporated, Mitsubishi Electric Corporation, Raycap Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Surge Arresters Market Evolving Landscape
Smart grid instrumentation is embedding monitoring capabilities directly into surge arrester housings, transforming passive protection devices into data-generating assets that enable condition-based maintenance and failure prediction.
Metal oxide varistor technology is converging with Internet-of-Things sensor architectures to create intelligent arresters capable of real-time leakage current monitoring and thermal runaway detection. Transmission operators in PJM Interconnection territory are piloting these units at critical substations. This convergence is compressing traditional inspection cycles while generating operational data streams that feed predictive analytics platforms.
Health Canada's PMRA and provincial electrical safety authorities are enforcing parallel certification tracks that vendors must navigate for full North American market access, creating dual-track compliance burdens distinct from single-jurisdiction product registrations. Manufacturers now maintain separate testing documentation for IEEE C62.11 and CSA C411.1 standards. Distribution-focused vendors serving Ontario and Quebec are responding by establishing captive Canadian certification laboratories to accelerate provincial approvals.
Buyer concentration among investor-owned utilities is consolidating procurement authority into centralized supply chain functions that negotiate multi-year framework agreements rather than project-specific purchase orders. Regional transmission organizations now specify arrester performance through master service agreements that lock in pricing and technical standards. This behavioral shift is most visible in California, where PG&E and Southern California Edison have centralized protection equipment procurement into dedicated grid modernization sourcing teams.
North America Surge Arresters Market Segmentation
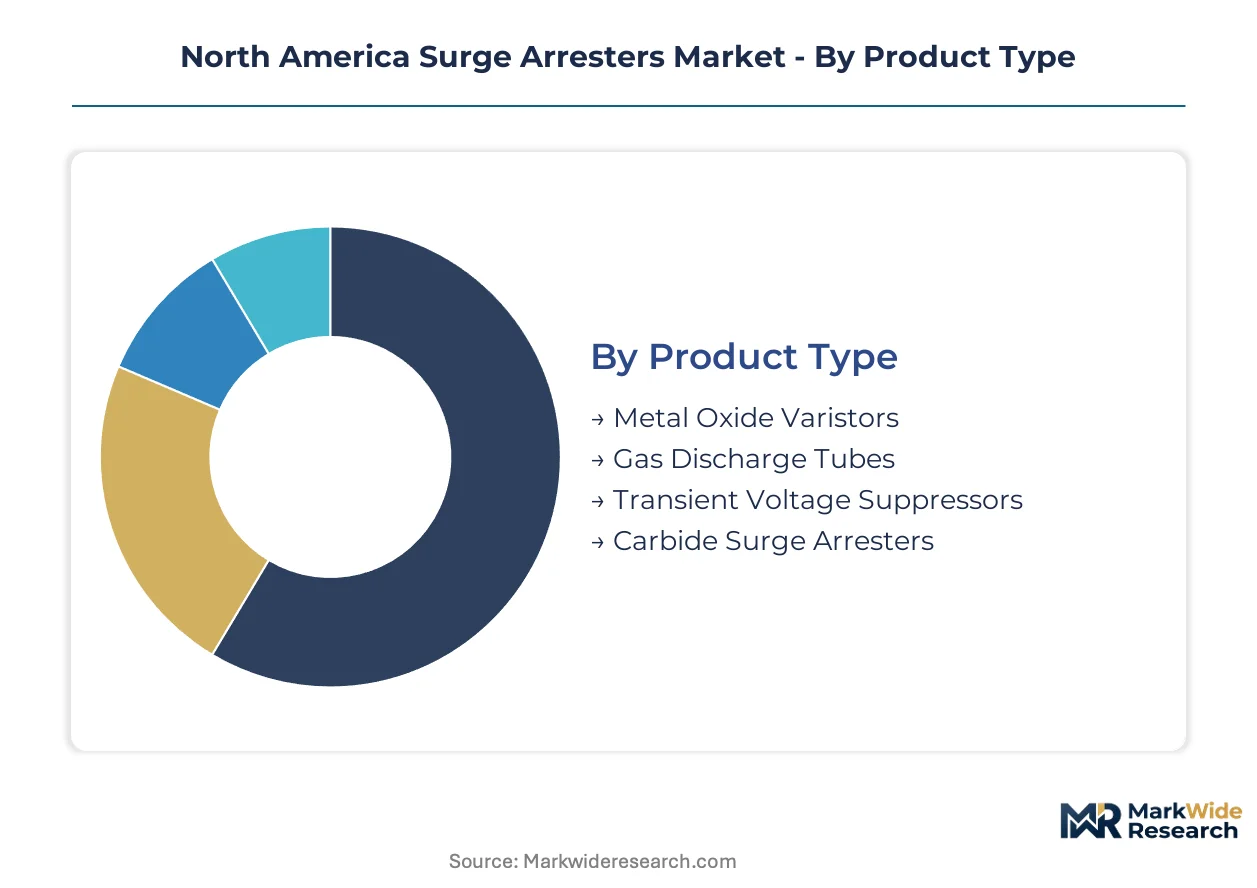
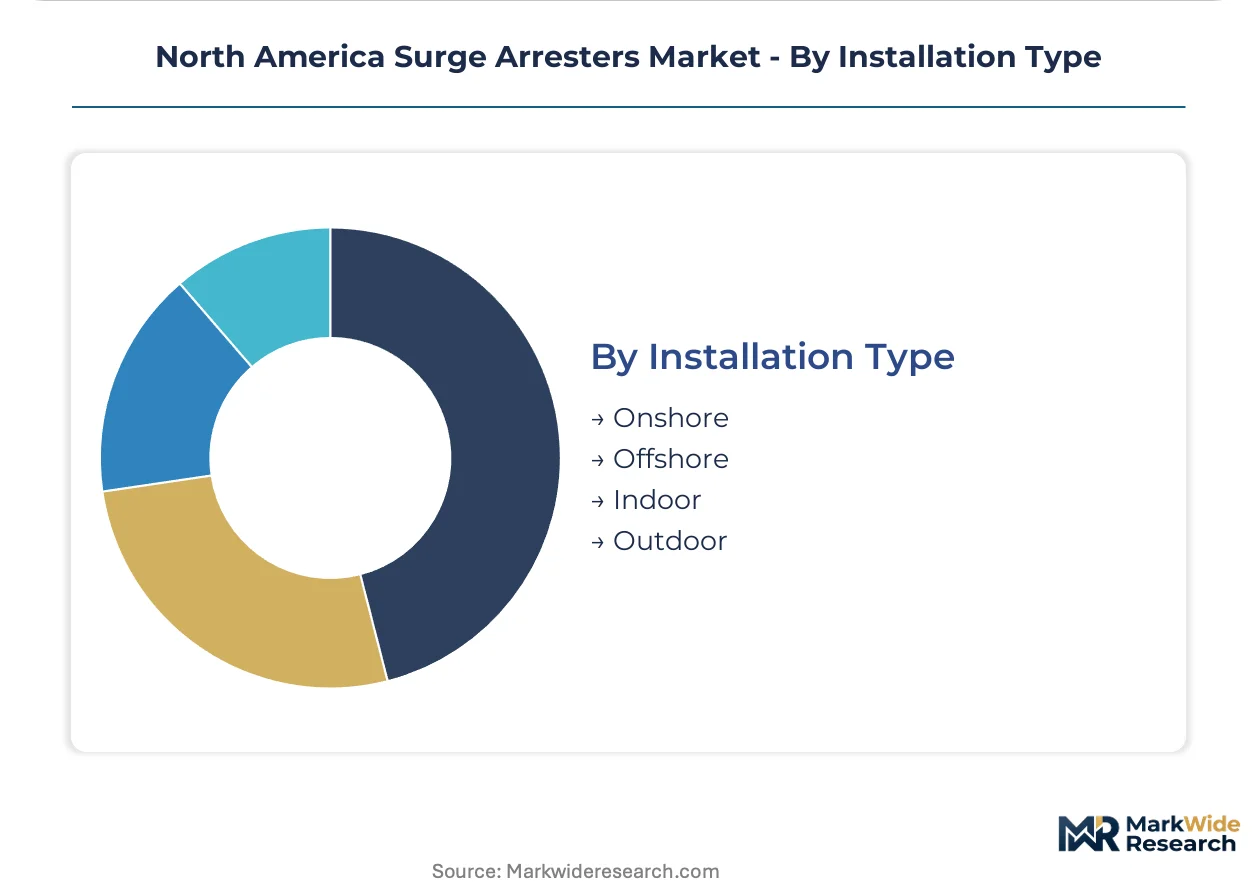
Surge arrester procurement patterns diverge sharply across product technologies and installation contexts. Utility buyers prioritize energy absorption capacity and NERC compliance, while industrial and telecom purchasers weight form factor and rapid replacement availability.
Product Type:
Metal oxide varistors command premium positioning through superior non-linear characteristics, while carbide arresters retain residual volume in legacy infrastructure replacement cycles.
- Metal Oxide Varistors:Zinc oxide disc columns deliver non-linear voltage-current response with energy absorption capacity exceeding legacy alternatives. Texas ERCOT wind farm developers specify these for collector system protection against lightning-induced transients in high-renewable penetration zones.
- Gas Discharge Tubes:Hermetically sealed noble gas chambers trigger ionization at precise breakdown voltages for telecom and signal line protection. Demand concentrates in 5G small cell deployments across California and Northeast corridor metro markets where signal integrity requirements are tightening.
- Transient Voltage Suppressors:Solid-state silicon avalanche diodes clamp overvoltages in nanosecond response windows for sensitive electronics. Manufacturing automation lines in Michigan and Ohio industrial corridors drive specification volumes.
- Carbide Surge Arresters:Silicon carbide disc assemblies with series gaps persist in aging substation installations where full system replacement economics remain unfavorable. PJM Interconnection territory retains the largest installed base requiring phased upgrade scheduling.
Mature deployment sits with carbide arresters in legacy transmission infrastructure. Newer deployment is concentrated in metal oxide varistors for renewable integration and grid hardening mandates.
Application:
Power distribution anchors absolute volume through transmission owner procurement, while renewable energy applications command specification premiums for harsh-environment durability.
- Power Distribution:Transmission-grade arresters rated for 69kV and above protect substation buses and transformer terminals across US bulk power systems. NERC CIP-014 physical security mandates are accelerating polymer housing replacement of fragile porcelain units in critical substations.
- Telecommunications:Coaxial and twisted-pair protection modules shield central office equipment and cell tower baseband units from lightning and switching transients. Tower company consolidation is standardizing procurement around multi-tenant site protection specifications.
- Renewable Energy:Solar farm DC combiner boxes and offshore wind turbine nacelles require arresters with extended temperature cycling tolerance. Atlantic coast lease area projects are driving salt-fog corrosion-resistant housing demand beyond standard transmission ratings.
- Industrial Equipment:Motor control centers and variable frequency drives deploy compact arresters for switching transient suppression. Petrochemical complexes along the US Gulf Coast specify explosion-proof enclosures for hazardous location compliance.
Power distribution represents the fastest-growing trajectory through federal grid modernization funding and state renewable portfolio standard implementation.
End User:
Utility procurement centralization is compressing vendor margins through multi-year framework agreements, while manufacturing and residential segments fragment across distributor channels.
- Utilities:Investor-owned transmission owners and municipal power departments specify IEEE C62.11 certified arresters through centralized supply chain functions. California IOUs have consolidated protection equipment procurement into dedicated grid modernization sourcing teams.
- Manufacturing:Automotive, semiconductor, and food processing facilities deploy arresters for production line continuity assurance. Mexican maquiladora operations near the US border create cross-border specification demand for IEC-aligned protection architectures.
- Telecommunications Providers:Wireless carriers and fiber network operators specify arrester arrays for central office power entry and tower grounding systems. 5G densification is multiplying small cell protection node counts across urban markets.
- Residential Users:Whole-house surge protection panels and point-of-use suppressors serve homeowner electrical service entrances and sensitive electronics. Big-box retail and electrical contractor channels dominate this price-sensitive segment.
Utility procurement maturity sits with centralized master service agreements. Residential adoption is climbing fastest through NEC code revision awareness and insurance premium incentive programs.
Installation Type:
Outdoor installations dominate transmission and distribution volume, while offshore specifications command specialized engineering for salt-fog and subsea cable termination environments.
- Onshore:Overhead line and substation installations across continental US and Canadian provinces represent standard arrester deployment. Texas panhandle wind farms and Arizona solar fields are multiplying ground-mounted collection system protection requirements.
- Offshore:Atlantic coast wind lease areas require subsea cable termination arresters with pressure-rated housings and marine-grade sealing. Specialized product tiers beyond standard transmission offerings are opening for vendors with offshore oil and gas heritage.
- Indoor:Switchgear-integrated arresters protect metal-enclosed substations and industrial control rooms. Data center power distribution units in Northern Virginia and Dallas-Fort Worth markets specify compact indoor-rated units for white space constraints.
- Outdoor:Pole-mounted and substation yard installations expose arresters to direct weather, pollution, and seismic stress. California utilities are specifying polymer housings with enhanced track resistance for coastal salt deposit and Central Valley agricultural chemical exposure.
Outdoor installation maintains the largest installed base across North American transmission networks. Offshore deployment is expanding most quickly through Atlantic coast wind lease auction awards and cable export system commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zinc oxide disc manufacturing concentrates in East Asian supply corridors, positioning North American arrester assemblers at the downstream end of extended procurement chains. Regional demand patterns diverge sharply across utility procurement maturity, renewable integration intensity, and regulatory compliance frameworks.
United States
Utility-scale grid modernization drives metal oxide varistor procurement across the PJM Interconnection territory and Texas ERCOT zone. NERC CIP-014 physical security mandates accelerate polymer housing replacement of fragile porcelain units in critical substations. California IOUs including PG&E and Southern California Edison have centralized protection equipment procurement into dedicated grid modernization sourcing teams.
Canada
Provincial electrical safety authorities enforce parallel certification tracks alongside Health Canada's PMRA oversight. Ontario and Quebec distribution-focused vendors maintain captive Canadian certification laboratories to accelerate provincial approvals under CSA C411.1 standards. Cross-border IEC-aligned deployment from US vendors streamlines into Canadian provinces through harmonized design architectures.
Mexico
Comisión Federal de Electricidad transmission buildout creates demand for surge protection architectures that US and Canadian vendors supply through cross-border manufacturing footprints. Northern border states concentrate industrial arrester deployment for maquiladora operations requiring IEC-aligned protection. CFE grid expansion in the Bajío Region and Mexico City Metro multiplies specification opportunities for polymer-housed transmission-grade units.
North America Surge Arresters Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors seek to secure zinc oxide disc supply and accelerate polymer housing material science development. The vendor base organizes around three distinct tiers: integrated electrical conglomerates with utility channel anchoring, domestic manufacturing specialists serving rapid-turn replacement demand, and cross-border deployment architects aligned with IEC standards. Consolidation pressures intensify as buyer concentration among investor-owned utilities compresses margins through multi-year framework agreements. Technology licensing and geographic expansion represent the two dominant competitive vectors as vendors position for Atlantic coast offshore wind and Mexico CFE procurement cycles.
Among integrated electrical conglomerates, Eaton Corporation PLC and Schneider Electric SE exemplify divergent standardization strategies. Eaton anchors utility channel relationships through its integrated electrical portfolio breadth, while Schneider occupies a position within the IEC-aligned deployment tier that streamlines cross-border Canadian and Mexican market access. Hubbell Incorporated represents the domestic manufacturing specialist archetype, sustaining rapid-turn replacement order capacity for utility maintenance windows. These three anchors collectively illustrate how vendor positioning stratifies across channel integration, geographic standardization, and operational responsiveness archetypes.
| Leading Market Players |
|---|
| ABB Ltd |
| Eaton Corporation PLC |
| Emerson Electric Co. |
| Schneider Electric SE |
| Siemens AG |
| General Electric Company |
| Hubbell Incorporated |
| Mitsubishi Electric Corporation |
| Raycap Inc. |
| Others |
Value Network & Pricing Analysis
California SB 100 renewable portfolio mandates gate qualified supply and premium-tier pricing access for surge arrester vendors serving utility-scale solar and wind interconnect projects. Buyers seeking extended service life guarantees must source from manufacturers with captive polymer housing material science capabilities, compressing vendor eligibility and supporting price premiums for certified suppliers.
Pricing Analysis
Warranty bundling separates premium-tier vendors offering 30-year service life guarantees from standard-tier competitors with limited coverage terms. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under IEEE C62.11 and CSA C411.1 standards, with NERC CIP-014 physical security compliance commanding additional premiums. Cost compression in the standard tier is intensifying because investor-owned utilities consolidate procurement into multi-year framework agreements. Residential end users through big-box retail channels exhibit the highest price sensitivity, while transmission owners prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Regional distribution centers in Texas, California, and Ontario anchor hub-and-spoke patterns serving utility maintenance windows and rapid-turn replacement demand. Zinc oxide disc manufacturing concentrates in China, Japan, and South Korea, exposing North American arrester assemblers to input cost volatility and extended lead times. Polymer silicone rubber compounds and porcelain insulator ceramics constitute critical raw material dependencies. Single-source vulnerability in specialty ceramic disc supply creates structural risk for vendors without backward integration into disc production. Distribution runs through authorized utility channel partners and electrical distributor networks serving industrial and residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over zinc oxide disc supply and polymer housing formulation capabilities determines margin sustainability. Players are pursuing upstream integration into specialty ceramic manufacturing to reduce East Asian supply dependency.
For Market Incumbents: Anticipate margin compression from buyer procurement centralization by securing captive zinc oxide disc supply agreements and accelerating polymer housing material science development. Eaton Corporation PLC and Hubbell Incorporated should reinforce utility channel anchoring through integrated service offerings that bundle installation support with extended warranty terms. Defensive consolidation into Canadian certification laboratory capabilities will accelerate provincial approval timelines under CSA C411.1 standards. For New Entrants and Emerging Players: Municipal power departments and electric cooperatives represent underserved buyer archetypes with fragmented procurement authority and limited framework agreement coverage. Atlantic coast offshore wind lease areas offer the most penetrable geography, with subsea cable termination arrester demand exceeding established vendor capacity. A specialized marine-grade product tier paired with offshore oil and gas heritage credentials provides viable go-to-market positioning. For Investors and Strategic Acquirers: CFE transmission buildout award announcements are the leading indicator that Mexico grid expansion procurement cycles are accelerating. Long-term viability over the five-to-ten year window hinges on exposure to renewable integration intensity and state-level renewable portfolio standard implementation. Acquisition targets should demonstrate IEC-aligned design architectures and cross-border manufacturing footprints serving Canadian and Mexican markets. The signal to monitor is polymer housing compound formulation talent scarcity in tight labor markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zinc Oxide Disc Manufacturing | Captive supply of specialty ceramic columns reduces East Asian dependency and compresses lead times for utility orders. |
| Polymer Housing Material Science Expansion | In-house silicone rubber formulation capabilities enable track-resistant designs for salt-fog and pollution environments. |
| Canadian Certification Laboratory Establishment | Captive CSA C411.1 testing accelerates provincial approvals in Ontario and Quebec distribution markets. |
| Offshore Wind Specialized Product Tier Development | Subsea cable termination arresters address Atlantic coast lease area demand beyond standard transmission offerings. |
| Utility Channel Service Integration | Bundled installation support and extended warranty terms anchor relationships with centralized procurement functions. |
Research Methodology
Document review covered IEEE C62.11 certification databases, NERC reliability standard filings, and FERC interconnection queue data, complemented by interviews with utility protection equipment procurement managers, polymer housing material scientists, and electrical distributor channel heads. Secondary validation drew from EIA grid modernization expenditure reports, state renewable portfolio standard implementation tracking, and customs import records for zinc oxide disc shipments. Bottom-up unit demand modeling and top-down utility capital expenditure triangulation anchored market size estimation.
Cross-referencing historical procurement patterns against utility planning officer panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product technology tier, application voltage class, end-user procurement maturity, and installation environment severity. CAGRs were derived from regression analysis of utility capital expenditure trajectories and renewable capacity addition correlations. Forecast inputs incorporated NERC CIP-014 implementation timelines and state-level grid hardening mandate progression.
Revisions become necessary when East Asian supply chain disruptions, seismic event frequency in California corridors, or accelerated offshore wind lease auction awards materialize outside baseline assumptions. Forecasts reflect documented expectations regarding regulatory compliance trajectory and technology substitution rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Electric Insulator Market
Electrical Power Equipment
Europe Brushless DC Motors Market
Electrical Power Equipment
Solar Combiner Boxes Market
Electrical Power Equipment
Instrument Transformers Market
Electrical Power Equipment
Train Contactor Market
Electrical Power Equipment
Overhead Power Cables Market
Electrical Power Equipment
Global Electric Power Substation Automation Market
Electrical Power Equipment
AV Power Conditioners Market
Electrical Power Equipment
Skid Mounted Unit Substations Market
Electrical Power Equipment
Residential Air Insulated Power Distribution Component Market
Electrical Power Equipment
Hollow Core Insulator Market
Electrical Power Equipment
Composite Line Post Insulators Market
Electrical Power Equipment
Gas Insulated Switchgear Sales Market
Electrical Power Equipment
Utility Poles Market
Electrical Power Equipment
Taiwan Electric Power Equipment Market
Electrical Power Equipment
Europe Electric Space Heaters Market