
 AC-DC Controller Market | 2026-2036
AC-DC Controller Market Size, Share, and Industry Trends Forecast 2026-2036
AC-DC Controller Market Outlook
Gallium nitride is pivoting AC-DC controller economics by enabling higher switching frequencies at reduced thermal losses. Texas Instruments leverages its foundry partnerships to sustain cost-competitive GaN portfolios. Infineon Technologies anchors European supply through captive silicon and wide-bandgap R&D pipelines. ON Semiconductor specializes in automotive-grade controllers that meet AEC-Q100 thresholds.
An AC-DC controller manages the conversion of alternating current to regulated direct current through feedback loops that modulate switching elements, typically operating at frequencies from 50 kHz to several megahertz depending on topology and magnetics. Its primary purpose is to deliver stable DC output with minimal ripple while maximizing conversion efficiency across varying load conditions. Switched-Mode Power Supply controllers command the largest volume share due to universal deployment in consumer and industrial equipment. Flyback Converter architectures dominate below 150W applications where transformer cost and simplicity outweigh efficiency trade-offs. Buck-Boost Converter demand is accelerating in battery-backed systems and LED drivers requiring wide input range tolerance.
EPA Energy Star specifications and EU Ecodesign regulations mandate minimum efficiency tiers that directly determine product qualification for consumer and commercial power supplies. IEC 62368-1 safety standards govern insulation and clearance requirements that shape controller pinout and packaging decisions across export-oriented manufacturing. FDA electromagnetic compatibility rules constrain medical-grade AC-DC controller designs in the United States. Stakeholders must monitor wide-bandgap material cost curves and evolving efficiency benchmarks to time process transitions and avoid stranded silicon investments.
Market Dynamics
Gallium nitride transistor adoption is compressing thermal management requirements while expanding switching frequency ceilings, forcing incumbent silicon suppliers to accelerate wide-bandgap roadmaps or cede premium sockets.
Growth Catalysts
- Data center server power supplies:Hyperscale facilities in the United States and Germany are mandating titanium-grade efficiency thresholds that only advanced controller architectures can satisfy.
- EU Ecodesign Directive:Tiered minimum efficiency requirements for external power supplies above 75W are phasing out legacy linear designs across consumer electronics exports.
- Wide-bandgap materials:Silicon carbide and gallium nitride substrates are enabling 10x switching frequency jumps that shrink magnetics and reduce passive component counts.
Market Restraints
- Wafer supply concentration:GaN-on-silicon epitaxy capacity clusters in Taiwan and China, creating single-source vulnerability for fabless controller designers.
- Copper and ferrite cost volatility:Transformer core materials and magnet wire pricing swings directly compress margins in high-volume consumer adapter segments.
- EMI suppression complexity:Megahertz-range switching generates conducted and radiated noise that demands multi-stage filtering, adding BOM cost and board area.
Strategic Opportunities
- India manufacturing incentives:PLI scheme subsidies for electronic components are attracting controller assembly investments serving domestic appliance and telecom infrastructure demand.
- Vehicle-to-grid bidirectional charging:Onboard power electronics requiring buck-boost AC-DC stages open automotive-grade controller sockets with AEC-Q100 qualification barriers.
- Digital power management convergence:Integration of telemetry, adaptive dead-time control, and PMBus communication is differentiating premium controllers from analog-only alternatives.
Industry Challenges
- Magnetics design expertise scarcity:High-frequency transformer and inductor optimization for GaN switching requires electromagnetic simulation skills that outpace university pipeline output.
- IEC 62368-1 clearance compliance:Reinforced insulation requirements for hazardous voltage separation force package redesigns and extend certification timelines by 6-12 months.
- Legacy analog controller replacement friction:Digital controller migration demands firmware competency that incumbent power supply engineering teams often lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AC-DC Controller Market |
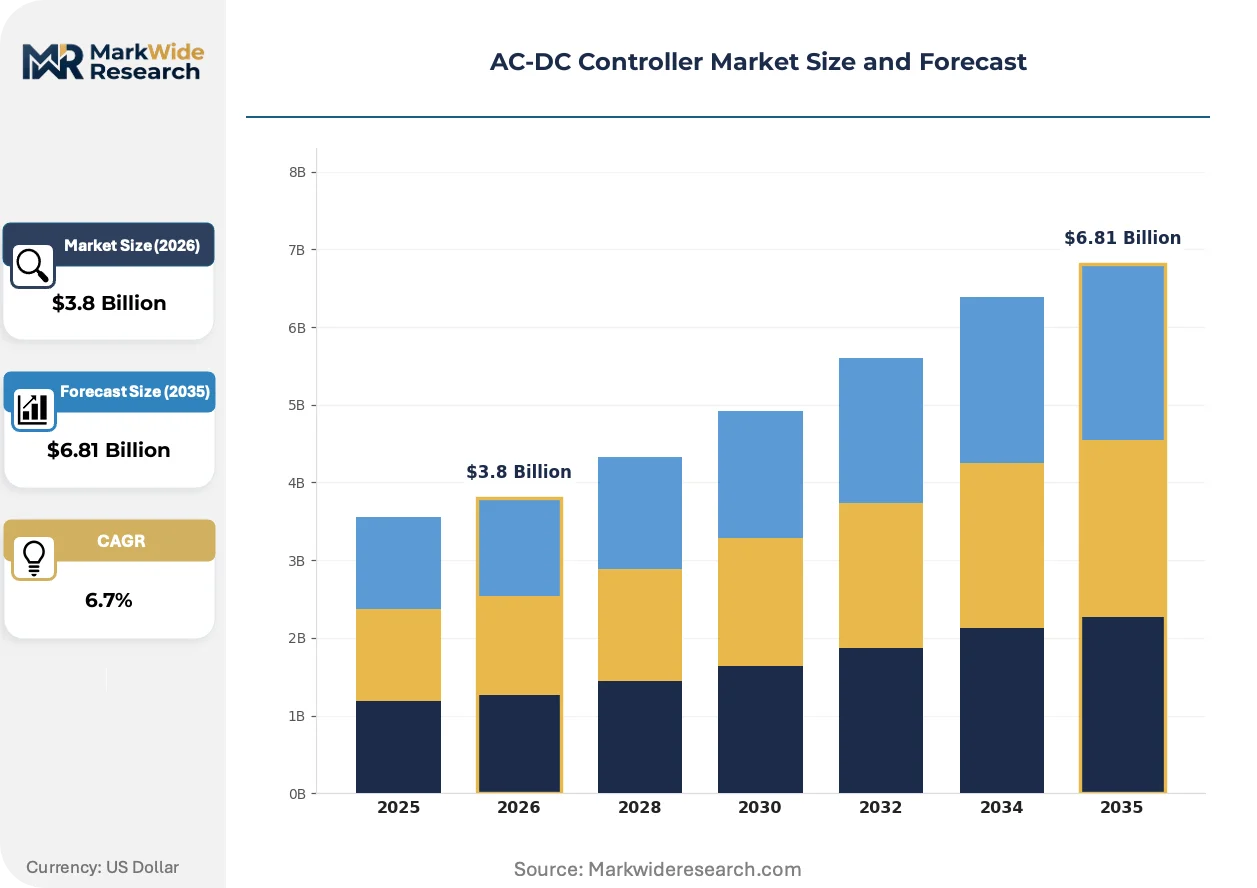
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Regulator, Switched-Mode Power Supply, AC-DC Power Adapter, Wall Mount Charger Application: Consumer Electronics, Industrial Automation, Renewable Energy Systems, Telecommunication Equipment Technology: Flyback Converter, Buck Converter, Boost Converter, Buck-Boost Converter End User: Household Appliances, Commercial Equipment, Automotive Systems, Medical Devices |
| Companies Covered | STMicroelectronics, Analog Devices, Texas Instruments, Power Integrations, Renesas Electronics, Infineon Technologies, NXP Semiconductors, ROHM Semiconductor, ON Semiconductor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AC-DC Controller Market Strategic Shifts
Active clamp and resonant topologies are displacing hard-switched alternatives as magnetics miniaturization becomes the primary competitive vector in consumer and industrial power supplies.
GaN transistors are integrating into controller reference designs at switching frequencies exceeding 1 MHz, enabling planar magnetics that eliminate traditional wire-wound transformers. Server power supply manufacturers in the United States are qualifying these architectures for 80 Plus Titanium efficiency targets. The structural consequence is a compression in passive component value capture and a shift in margin toward semiconductor and controller vendors.
EPA Energy Star Version 8.0 specifications are tightening no-load power consumption limits for external power supplies, forcing active-mode efficiency improvements at light loads. This regulatory pressure is accelerating adoption of burst-mode and frequency-foldback control techniques. Laptop and mobile device OEMs in California and the European Union are now requiring sub-100 mW standby consumption as a baseline qualification.
Modular power supply procurement is consolidating purchasing authority at hyperscale data center operators, compressing vendor counts and demanding custom controller firmware with embedded telemetry. Traditional distributor channels serving mid-tier industrial customers are losing share to direct manufacturer relationships. China-based server OEMs are most aggressive in specifying proprietary digital control loops that lock in supplier relationships.
AC-DC Controller Market Segmentation
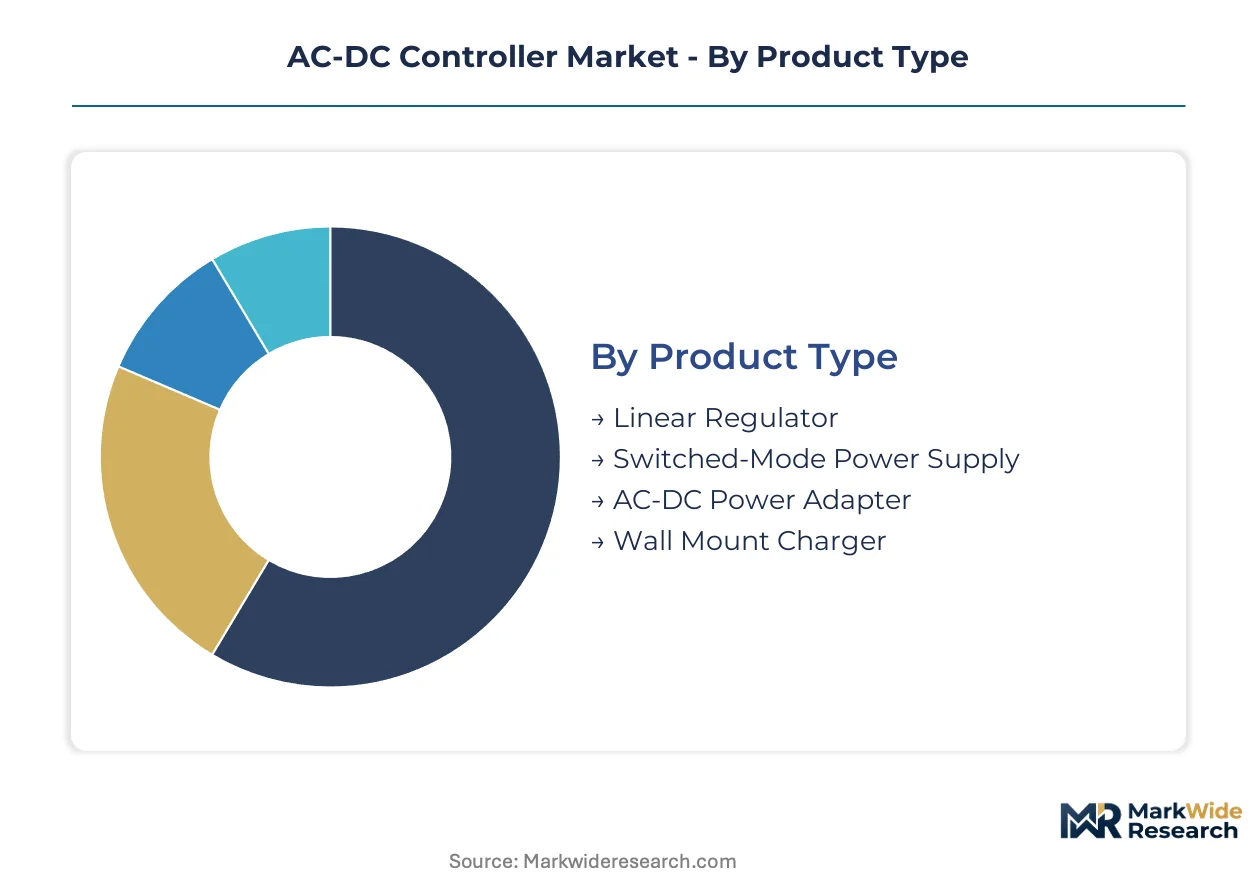
AC-DC controller architectures fragment across power levels, switching topologies, and regulatory environments that dictate silicon versus wide-bandgap material selection. Buyers prioritize efficiency certification tiers, thermal envelope constraints, and magnetics integration complexity when specifying controllers for their power supply designs.
Product Type:
Cost tier differentiation separates commodity adapters from precision-regulated industrial supplies.
- Switched-Mode Power Supply:Pulse-width modulation controllers operate at 50 kHz to several megahertz, enabling 90%+ efficiency in data center server supplies that must meet 80 Plus Titanium thresholds. Hyperscale operators in the United States and Germany specify these controllers for 96%+ efficiency at 50% load.
- Linear Regulator:Dissipative regulation through variable resistance delivers sub-1% output ripple for sensitive analog instrumentation and medical monitoring equipment. Demand concentrates in FDA-regulated medical devices where electromagnetic noise immunity outweighs efficiency penalties.
- AC-DC Power Adapter:Integrated controller-transformer assemblies serve consumer electronics with external power bricks. EU Ecodesign Directive compliance for no-load power below 75 mW drives active-mode efficiency improvements.
- Wall Mount Charger:Compact plug-in designs for smartphones and tablets prioritize power density over thermal headroom. GaN transistor integration enables 65W+ output from palm-sized enclosures.
Volume sits with Switched-Mode Power Supply; growth tilts toward Wall Mount Charger.
Application:
End-use thermal and reliability specifications determine controller topology and packaging grade.
- Consumer Electronics:Laptop, smartphone, and tablet OEMs demand sub-100 mW standby consumption under EPA Energy Star Version 8.0. Burst-mode control techniques dominate this specification-driven segment.
- Telecommunication Equipment:Base station power supplies require wide input range tolerance and holdup time compliance. Buck-boost architectures address battery-backed redundancy in 5G infrastructure deployments across China and Germany.
- Industrial Automation:Programmable logic controller power supplies prioritize surge immunity and extended temperature operation. Isolated flyback controllers with reinforced insulation meet IEC 62368-1 clearance requirements.
- Renewable Energy Systems:Solar inverters and energy storage interfaces demand bidirectional power flow capability. Vehicle-to-grid charging applications in the United States specify automotive-grade AEC-Q100 qualified controllers.
Margins concentrate in Telecommunication Equipment; expansion accelerates most quickly in Renewable Energy Systems.
Technology:
Switching frequency and magnetics complexity separate mature silicon implementations from emerging wide-bandgap designs.
- Flyback Converter:Single-switch transformer-isolated topology dominates below 150W applications where component count and cost outweigh efficiency optimization. Consumer adapter manufacturers in China deploy these controllers at multi-million unit scale.
- Buck-Boost Converter:Non-inverting and inverting variants maintain regulation across battery discharge curves and wide mains tolerance. LED driver and automotive applications in Germany specify these for input ranges spanning 9V to 36V.
- Buck Converter:Step-down switching regulators serve point-of-load applications in distributed power architectures. Digital power management integration with PMBus telemetry differentiates premium implementations.
- Boost Converter:Step-up topologies address power factor correction front-ends and battery charging stages. Active clamp variants reduce voltage stress on switching elements.
Design activity clusters around Flyback Converter; technology transition favors Buck-Boost Converter.
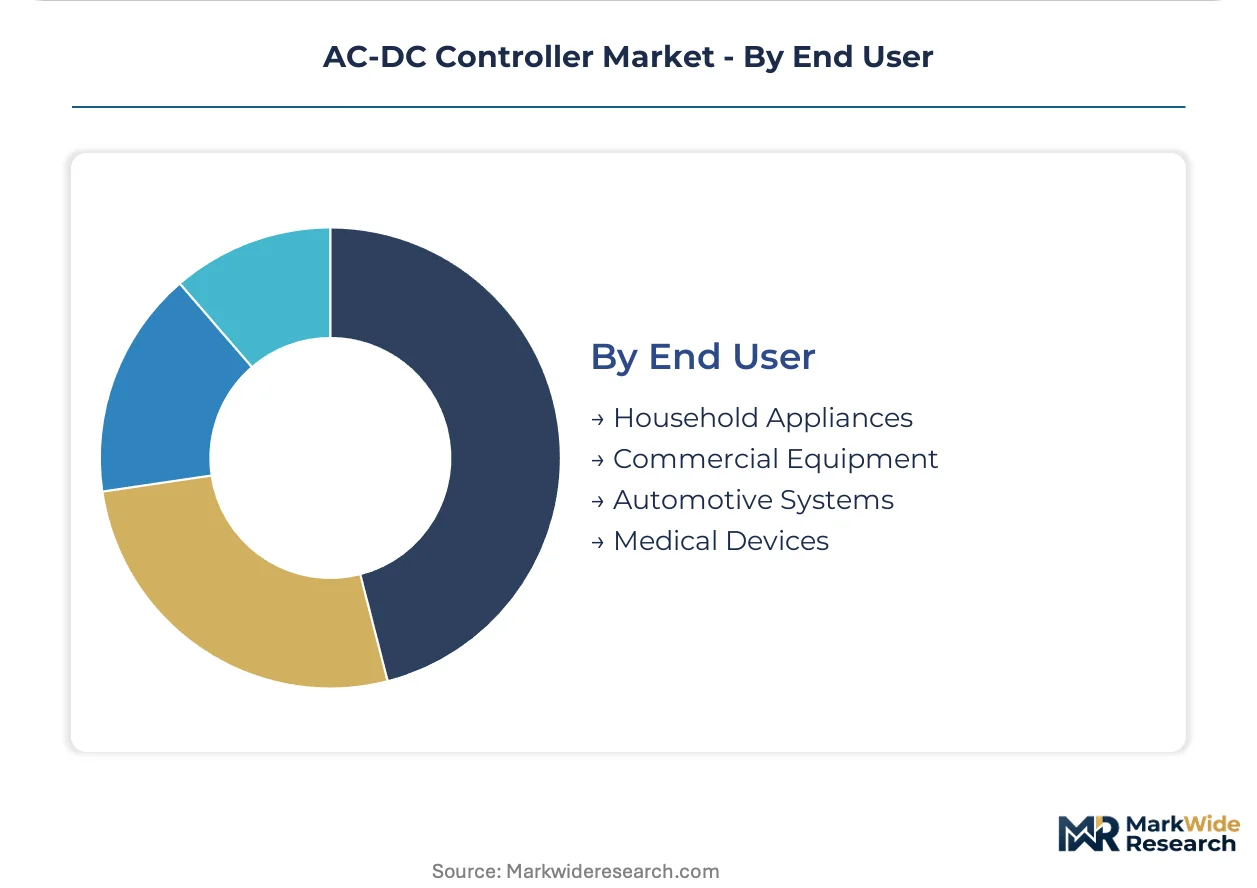
End User:
Certification grade and qualification protocol separate consumer, commercial, automotive, and medical procurement criteria.
- Automotive Systems:Onboard chargers and DC-DC converters for electric vehicles require AEC-Q100 Grade 1 qualification for -40°C to 125°C operation. Infineon and ON Semiconductor anchor European and North American supply for these sockets.
- Medical Devices:Patient-contact equipment demands 2xMOPP isolation and leakage current limits under IEC 60601-1. FDA electromagnetic compatibility rules constrain controller selection for diagnostic imaging and life support systems.
- Household Appliances:White goods manufacturers in China integrate controllers for motor drives and standby power management. Cost pressure drives discrete analog implementations over digital alternatives.
- Commercial Equipment:Server, networking, and office equipment procurement consolidates at hyperscale operators who specify custom firmware with embedded telemetry. Direct manufacturer relationships displace traditional distribution channels.
Unit volume flows through Household Appliances; value capture shifts toward Automotive Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate AC-DC controller foundry capacity serving global electronics supply chains. Germany's industrial heartland anchors European demand for high-efficiency power conversion. The United States maintains leadership in data center server power supply innovation.
United States
Hyperscale data center operators in Northern Virginia and Dallas-Fort Worth mandate titanium-grade efficiency thresholds for server power supplies. EPA Energy Star Version 8.0 specifications drive sub-100 mW standby consumption requirements across consumer electronics exports. Silicon Valley controller designers collaborate with Texas-based power supply manufacturers on GaN reference designs.
China
Consumer adapter manufacturers in Shenzhen and Dongguan deploy flyback controllers at multi-million unit scale for smartphone and laptop OEMs. MIIT efficiency regulations and GB standards enforce minimum performance tiers for domestic and export-bound power supplies. Yangtze River Delta clusters in Shanghai and Suzhou host captive GaN epitaxy capacity for wide-bandgap controller integration.
Germany
Industrial automation OEMs in Bavaria and Baden-Württemberg specify reinforced insulation controllers meeting IEC 62368-1 clearance requirements. EU Ecodesign Directive tiered efficiency mandates phase out legacy linear designs across external power supplies above 75W. Automotive suppliers in Stuttgart anchor European demand for AEC-Q100 qualified onboard charger controllers.
India
Domestic appliance manufacturers in Maharashtra and Tamil Nadu integrate controllers for motor drives and standby power management. PLI scheme subsidies for electronic components attract controller assembly investments serving telecom infrastructure and white goods demand. Bangalore-based power supply designers qualify products for BIS efficiency certification and export markets.
Japan
Precision instrumentation manufacturers in Tokyo and Osaka demand linear regulators delivering sub-1% output ripple for sensitive analog applications. METI energy efficiency standards and JIS certification requirements shape controller selection for industrial and consumer equipment. Nagoya-area automotive electronics suppliers specify wide-temperature controllers for electric vehicle powertrains.
AC-DC Controller Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with IDM-heavy portfolios commanding premium sockets and fabless designers capturing volume consumer adapter markets. The vendor base organizes around three archetypes: integrated device manufacturers with captive silicon and wide-bandgap R&D, fabless specialists leveraging foundry partnerships for cost-competitive GaN portfolios, and automotive-grade qualification leaders serving AEC-Q100 sockets. Dominant competitive moves include backward integration into epitaxy capacity and strategic partnerships for digital power management convergence.
Among European integrated device manufacturers, Infineon Technologies and STMicroelectronics exemplify the captive silicon archetype with broad industrial and automotive controller portfolios. Texas Instruments represents the fabless partnership model sustaining cost-competitive wide-bandgap offerings through foundry relationships. ON Semiconductor occupies a position within automotive-grade specialization, anchoring North American supply for AEC-Q100 qualified controllers serving electric vehicle onboard charger applications.
| Leading Market Players |
|---|
| STMicroelectronics |
| Analog Devices |
| Texas Instruments |
| Power Integrations |
| Renesas Electronics |
| Infineon Technologies |
| NXP Semiconductors |
| ROHM Semiconductor |
| ON Semiconductor |
| Others |
Value Chain & Pricing Dynamics
Captive epitaxy capacity in Taiwan and China anchors supply positions for GaN controller suppliers while simultaneously compressing pricing power for fabless competitors dependent on external foundry access. Texas Instruments and Infineon Technologies leverage in-house substrate control to sustain margin premiums against commodity silicon alternatives, whereas second-tier designers face cost pass-through vulnerability during wafer allocation cycles.
Pricing Analysis
Volume concentrates in sub-dollar flyback controllers for consumer adapters, while margins accumulate in automotive-grade and data center titanium-tier sockets. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q100 qualified automotive controllers from industrial-grade and consumer adapter implementations. Cost compression in high-volume consumer segments is intensifying because Shenzhen-based manufacturers consolidate procurement at multi-million unit scale. White goods OEMs in China exhibit highest price sensitivity; hyperscale data center operators in the United States and Germany demonstrate lowest sensitivity due to efficiency-driven total cost of ownership calculations.
Supply Chain Analysis
Reverse logistics for controller qualification failures and end-of-life power supply refurbishment flow through regional electronics recycling clusters in Guangdong and Zhejiang provinces. GaN-on-silicon epitaxy capacity concentrates in Taiwan, China, and South Korea, with silicon carbide substrate production anchored in Japan and the United States. Transformer core ferrite and copper magnet wire feed from Japanese and German specialty materials suppliers. Single-source vulnerability in GaN epitaxy creates supply chain risk during geopolitical trade restriction episodes. Distribution runs through direct manufacturer relationships with hyperscale operators, bypassing traditional component distributors for premium controller tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where IEC 62368-1 reinforced insulation requirements and AEC-Q100 automotive qualification create six-to-twelve month certification moats that protect incumbent positions from rapid competitive entry.
For Market Incumbents: To counter gallium nitride transistor commoditization threats from Chinese fabless competitors, deepen backward integration into captive epitaxy capacity in Taiwan or Yangtze River Delta zones. Prioritize firmware-locked digital power management convergence with PMBus telemetry to create switching costs that bind hyperscale data center procurement relationships. For New Entrants and Emerging Players: Capture white-space in India's PLI-subsidized controller assembly market serving domestic appliance and telecom infrastructure demand. Target vehicle-to-grid bidirectional charging applications in the United States where AEC-Q100 qualification barriers remain incomplete. Pursue partnership-based go-to-market angles with Bangalore power supply designers seeking BIS-certified components for export qualification. For Investors and Strategic Acquirers: Exit pathways concentrate in automotive-grade controller specialists with proven AEC-Q100 track records and existing Tier 1 supplier relationships. Long-term viability favors assets with demonstrated wide-bandgap material transition capabilities across the projection horizon. Watch GaN-on-silicon cost parity milestones against superjunction MOSFETs as the inflection signal for process technology obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Epitaxy Backward Integration | Captive substrate capacity insulates margin from Taiwan foundry allocation volatility. |
| Digital Power Management Convergence | PMBus telemetry integration locks in hyperscale data center procurement relationships. |
| AEC-Q100 Qualification Investment | Automotive-grade certification opens electric vehicle onboard charger controller sockets. |
| India Manufacturing Footprint Expansion | PLI scheme subsidies reduce landed cost for domestic appliance and telecom demand. |
| Active Clamp Topology Reference Design | Megahertz switching enables planar magnetics that displace wire-wound transformers. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with power supply design engineers, semiconductor procurement managers, data center infrastructure planners, and automotive Tier 1 supplier quality directors. EPA Energy Star databases, IEC certification registries, MIIT efficiency filings, and SEC semiconductor segment disclosures provided validation benchmarks. Bottom-up unit shipment estimates from controller reference design wins were triangulated against top-down power supply production forecasts.
Reconciliation of import-export statistics, foundry capacity utilization reports, and OEM bill-of-materials disclosures shaped the analytical framework across the analysis window. Segmentation modeling incorporated power level tiers, switching topology categories, certification grade requirements, and regional regulatory cluster variations. CAGRs were derived from regression analysis of historical efficiency regulation adoption curves and technology substitution patterns. GaN transistor cost curves and magnetics miniaturization trajectories served as primary forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to wide-bandgap material cost trajectories, evolving efficiency benchmark tiers, and geopolitical trade restriction severity. Forecasts reflect documented assumptions regarding regulatory phase-in schedules and technology adoption elasticity. Material deviation in EPA Energy Star specification timing, EU Ecodesign Directive enforcement intensity, or GaN epitaxy capacity expansion rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
SF6 Gas Circuit Breaker Market
Electrical Power Equipment
High Voltage Direct Current (HVDC) Cables Market
Electrical Power Equipment
Skid Mounted Unit Substations Market
Electrical Power Equipment
Substation Market
Electrical Power Equipment
Copper Ground Rod Market
Electrical Power Equipment
Utility Equipment Market
Electrical Power Equipment
Overhead Power Cables Market
Electrical Power Equipment
AC Drives Market
Electrical Power Equipment
Fault Circuit Indicator Market
Electrical Power Equipment
GCC Induction Motor Market
Electrical Power Equipment
Magnet Bearings Market
Electrical Power Equipment
Alternators Market
Electrical Power Equipment
Electric Submersible Pump Cable Market
Electrical Power Equipment
Domestic Hot Water (DHW) Tanks Market
Electrical Power Equipment
Utility Poles Market
Electrical Power Equipment
Electric Insulator Market