
 Containerized Substation Market | 2026-2036
Containerized Substation Market Size, Share, and Industry Trends Forecast 2026-2036
Containerized Substation Market Intelligence
Demand from industrial and renewable energy developers for rapid deployment is collapsing the traditional procurement cycle dominated by long-term utility planning. Siemens AG leverages its extensive portfolio in digital substation technology to serve these new buyers. Schneider Electric SE specializes in medium voltage solutions for industrial applications and microgrids. ABB Ltd sustains its market position through a global manufacturing footprint and strong channel partnerships in the utilities sector.
A containerized substation is a prefabricated, self-contained electrical substation housed within a standard ISO shipping container or similar enclosure. These units integrate key components like switchgear, transformers, and control systems, designed for rapid installation and operation. Their primary purpose is to provide a mobile, plug-and-play power distribution solution for remote or temporary sites. Within applications, renewable energy projects represent the fastest-growing segment, outpacing mature demand from the oil & gas sector. Medium voltage configurations dominate the product landscape due to their suitability for connecting distributed generation sources and industrial facilities to the main grid.
Product design and market access are governed by international standards such as those from the IEC for electrical safety and performance. In parallel, environmental regulations like the US EPA's rules on transformer fluids and the EU's F-Gas Regulation for switchgear influence component selection. Stakeholders must now decide how to balance standardization for cost reduction against customization required for specific grid codes and environmental conditions.
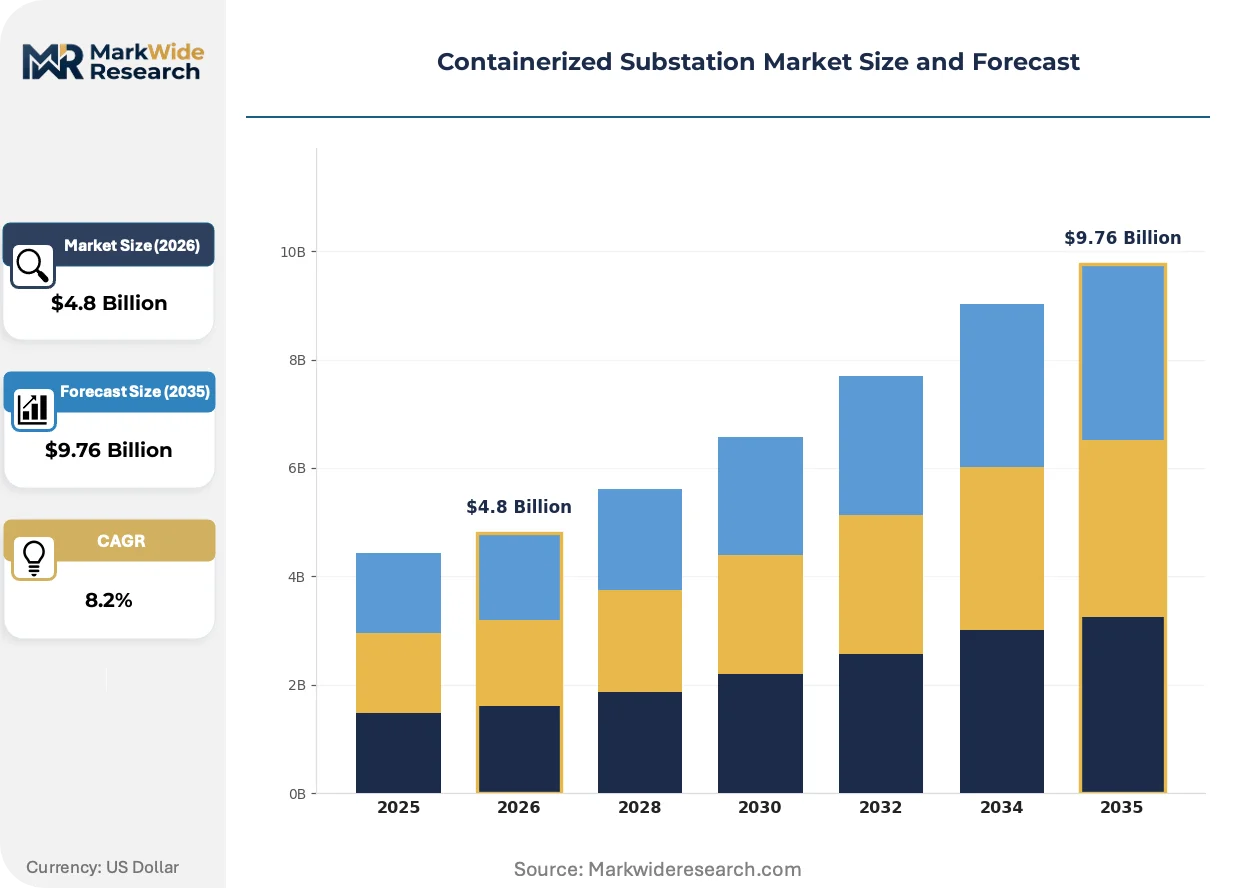
Market Dynamics
The rapid deployment timelines required by renewable energy developers and industrial users are fundamentally altering market dynamics. This shift collapses the traditional, long-term procurement cycles historically dictated by utility grid planning, creating demand for prefabricated, plug-and-play power infrastructure solutions.
Growth Catalysts
- Decentralized Energy Growth:The global expansion of distributed generation, especially solar and wind farms in remote areas, necessitates modular and rapidly deployable grid connection points that containerized substations provide.
- Supportive Government Policies:Incentives like the US Inflation Reduction Act (IRA) directly accelerate private investment in renewable energy projects, boosting ancillary demand for grid integration hardware.
- Grid Modernization Programs:National initiatives, such as China's push to meet its dual carbon goals, drive large-scale investment in new grid infrastructure that favors standardized, factory-built components for speed and quality control.
Market Restraints
- Input Cost Volatility:Fluctuating prices for essential raw materials like copper, aluminum, and electrical steel create significant margin pressure and complicate long-term project bidding for substation manufacturers.
- Grid Code Fragmentation:The lack of uniform grid interconnection standards across different countries and even within regions increases engineering complexity and costs, working against the core benefit of standardization.
- Regulatory Hurdles for Components:Environmental rules, including the EU's F-Gas Regulation restricting certain greenhouse gases in switchgear, force costly component redesigns and limit product options in key markets.
Strategic Opportunities
- Emerging Market Electrification:Underdeveloped grids in regions like Sub-Saharan Africa and parts of Southeast Asia present a significant opportunity for mobile substations to accelerate rural and industrial electrification.
- EV Charging Infrastructure:The build-out of large-scale electric vehicle fast-charging depots for commercial fleets and public highways creates a new, high-growth application for compact medium-voltage power distribution systems.
- Hybrid Power Solutions:Integrating battery energy storage systems (BESS) within the containerized unit offers a value-added product for grid stabilization, frequency regulation, and renewable energy firming.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of power systems engineers and technicians skilled in digital protection, control systems, and component integration within a compact footprint constrains production capacity. *Logistical Complexity: The transportation and installation of heavy, oversized modules to remote or challenging terrains, including offshore platforms or mountainous regions, pose significant logistical and cost-related hurdles for project execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Containerized Substation Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medium Voltage, Low Voltage, High Voltage, Compact Application: Renewable Energy, Oil & Gas, Mining, Utilities Technology: Smart Grid, Hybrid Systems, Digital Substation, Conventional End User: Industrial, Commercial, Residential, Government |
| Companies Covered | Eaton Corp plc, Larsen and Toubro Ltd., ABB Ltd, alfanar Group, CG Power and Industrial Solutions Ltd., Schneider Electric SE, General Electric Co., Hitachi Energy, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Containerized Substation Market Strategic Shifts & Innovations
Digitalization is transforming the containerized substation from a passive electrical asset into an intelligent grid node. The convergence of modular hardware with advanced communication and control software enables remote operation, predictive maintenance, and enhanced grid stability, defining the next generation of products.
Environmentally-friendly switchgear that utilizes alternative insulation gases or vacuum interrupter technology is gaining traction. Utilities and industrial operators, particularly in Europe, are adopting these systems to meet tightening environmental standards. This SF6-free technology is supplanting traditional designs to comply with the EU F-Gas Regulation and reduce the overall carbon footprint of grid infrastructure.
Standardization around the IEC 61850 protocol for substation automation is a critical enabler of market development. This global standard ensures interoperability between intelligent electronic devices from different manufacturers, facilitating the creation of truly digital substations. The control and protection system segment is most affected, as compliance becomes a mandatory purchasing requirement for utilities modernizing their networks.
Evolving procurement models are shifting from direct capital expenditure to flexible leasing or service-based contracts. This change is most pronounced for temporary power applications in sectors like mining, construction, and large-scale events, where rental companies offer short-term deployment solutions. The trend is gaining momentum in North America and Europe, providing an alternative to outright asset ownership.
Containerized Substation Market Segmentation
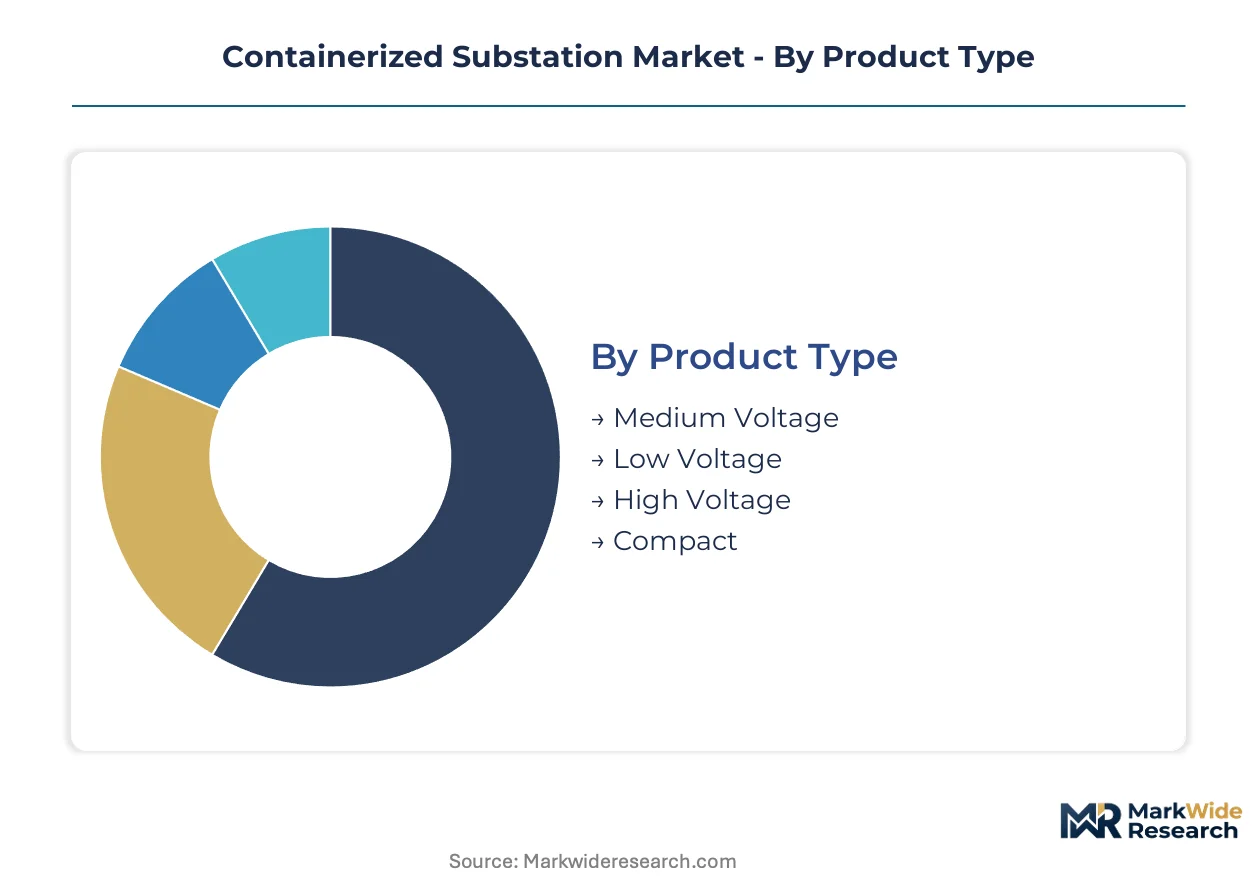
The containerized substation market's segmentation provides a detailed view of how product configurations, applications, technologies, and end-user demands shape competitive strategies. Understanding these distinct segments allows stakeholders to tailor solutions for specific operational requirements and capitalize on emerging growth vectors within the decentralized power infrastructure landscape.
Product Type:
The market for containerized substations shows a clear distinction between solutions optimized for domestic grid integration and those primarily designed for export to diverse international markets.
- Medium Voltage:These substations typically integrate switchgear, transformers, and control systems operating between 1 kV and 36 kV. Demand concentrates in connecting distributed generation sources like solar farms and industrial facilities to national grids, particularly in China and the US, driven by grid modernization.
- Compact:These units prioritize minimal footprint and rapid deployment, often integrating multiple components into a single, highly optimized enclosure. Industrial users and renewable energy developers in Europe and North America seek these compact solutions for space-constrained sites and accelerated project timelines.
- Low Voltage:Designed for power distribution below 1 kV, these units serve localized industrial processes or commercial facilities. Project developers in developing economies often deploy low voltage containerized substations for localized power needs.
- High Voltage:Operating above 36 kV, these substations are less common in containerized formats but serve specialized applications like large utility interconnections or remote mining operations. Utilities in Australia and Canada utilize these for challenging remote installations.
Medium Voltage holds the largest share; momentum sits with Compact units.
Application:
The utility of containerized substations varies significantly across different operational environments, each demanding specific technical configurations and deployment capabilities.
- Renewable Energy:This segment includes solar, wind, and other distributed generation projects requiring rapid grid connection and flexible power evacuation solutions. The US Inflation Reduction Act (IRA) directly accelerates investment in renewable energy projects, boosting demand for these substations.
- Utilities:National and regional power providers deploy containerized units for grid reinforcement, temporary power during maintenance, or rapid restoration after outages. China's grid modernization programs drive significant utility procurement for standardized, factory-built components.
- Oil & Gas:Mobile substations support exploration, production, and processing facilities in remote or hazardous locations, providing reliable power for drilling rigs and pumping stations. Companies like Saudi Aramco deploy these units for temporary power in remote desert operations.
- Mining:These applications require robust, mobile power solutions for open-pit and underground mines, often in extreme environmental conditions. Mining companies in Australia and South America depend on these for flexible power distribution across vast sites.
Renewable Energy represents the fastest-growing segment; Utilities maintain substantial foundational demand.
Technology:
The technological sophistication embedded within containerized substations determines their operational efficiency, intelligence, and adaptability to modern grid requirements.
- Digital Substation:These systems incorporate advanced communication protocols like IEC 61850 for interoperability, remote monitoring, and automated control of all substation components. Utilities in Germany and Japan are adopting digital substations for enhanced grid stability and operational efficiency.
- Hybrid Systems:These containerized units integrate multiple power technologies, often combining traditional substation components with battery energy storage systems (BESS). Developers in California and Texas utilize hybrid systems for grid stabilization and renewable energy firming.
- Smart Grid:Smart grid technology enables two-way communication and real-time data exchange, allowing for dynamic load management and improved grid resilience. European grid operators are implementing smart grid capabilities to manage distributed energy resources more effectively.
- Conventional:These substations rely on traditional electromechanical components and manual or basic remote control systems. Developing markets in Southeast Asia still rely on conventional designs for cost-effective grid expansion.
Digital Substation technology commands premium pricing; Hybrid Systems are experiencing rapid uptake.
End User:
The specific requirements of different end-user groups dictate the design, scale, and deployment model for containerized substation solutions.
- Industrial:Manufacturing plants, data centers, and large commercial facilities require reliable, scalable power infrastructure for their operations. Industrial users in the US and Germany demand rapid deployment solutions to minimize production downtime.
- Government:Public sector entities, including military bases, emergency services, and public infrastructure projects, utilize containerized substations for secure and resilient power supply. National defense agencies in the UK and France deploy these for mobile command centers and temporary base operations.
- Commercial:Shopping malls, office complexes, and temporary event venues use these units for flexible and rapid power distribution. Event organizers in major European cities frequently lease containerized substations for large-scale outdoor gatherings.
- Residential:While less common, containerized substations can support localized residential microgrids or temporary power for new housing developments. Communities in remote Canadian regions might use these for distributed power.
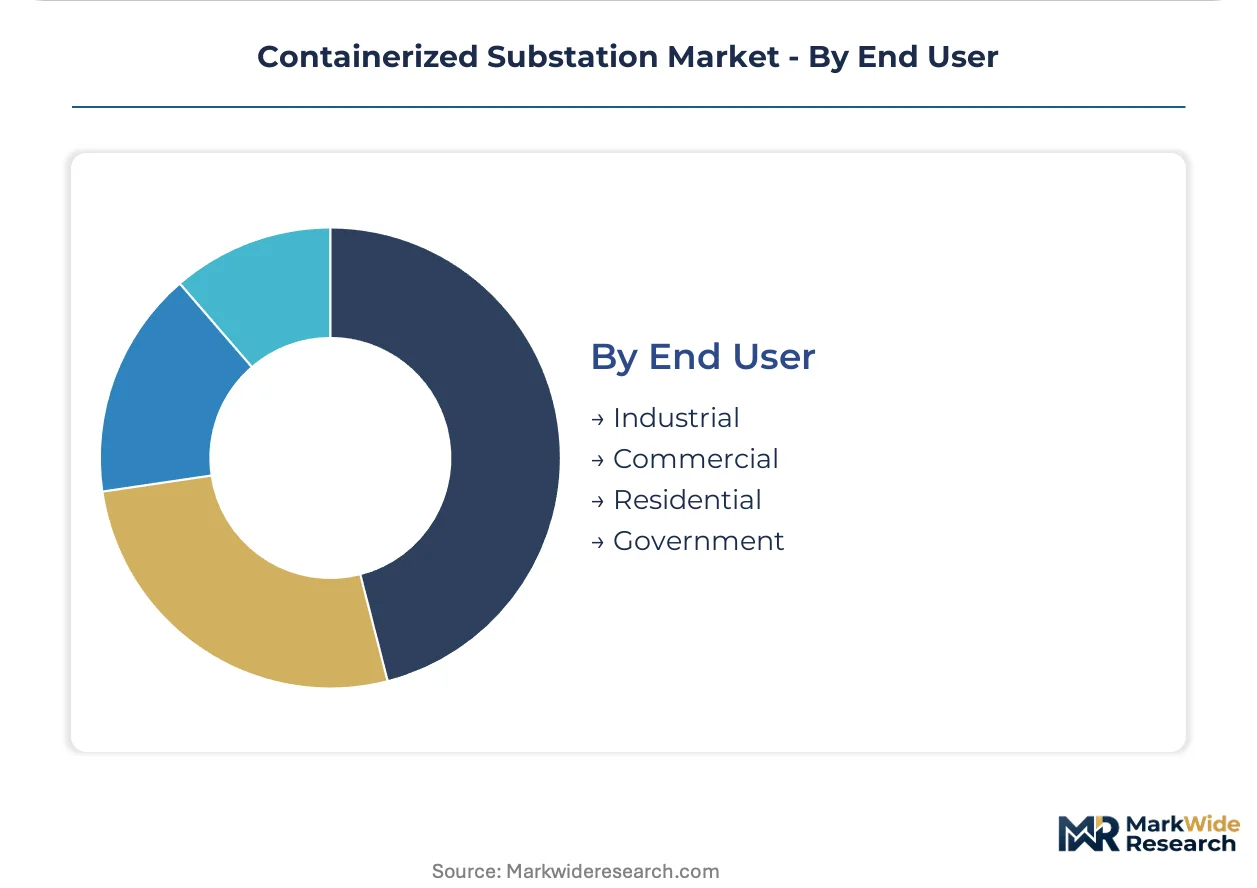
Industrial applications represent the largest volume; Government projects demonstrate consistent, high-value demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global grid interconnect network underpins regional demand for containerized substations. These modular units facilitate rapid power deployment across diverse geographic and economic landscapes. Modernization efforts and renewable energy integration drive this expansion.
China
China's rapid grid modernization programs and dual carbon goals drive significant demand for containerized substations. The country requires modular solutions to integrate vast renewable energy projects like solar and wind farms. Its national initiatives favor standardized, factory-built components for speed and quality control. The Yangtze River Delta region, a major industrial hub, drives demand for new grid infrastructure to support economic expansion.
United States
The US Inflation Reduction Act (IRA) directly accelerates investment in renewable energy projects, boosting demand for grid integration hardware. Decentralized energy growth and the build-out of EV charging infrastructure necessitate compact power distribution systems. Utilities and industrial users in the United States seek rapid deployment solutions to minimize project timelines. Texas and California developers utilize hybrid systems for grid stabilization and renewable energy firming.
Germany
German utilities are adopting digital substation technology for enhanced grid stability and operational efficiency. Environmental regulations, such as the EU F-Gas Regulation, promote environmentally-friendly switchgear in new installations. This policy shift forces costly component redesigns toward SF6-free technology. The Bavarian region exemplifies utilities adopting digital substations to manage distributed energy resources more effectively.
Australia
Australia's vast and remote territories present unique challenges for power distribution, favoring containerized substations. Mining operations and large utility interconnections in challenging environments require robust, mobile power solutions. The National Electricity Rules (NER) influence grid connection standards for new projects. Western Australia's mining sector relies on high voltage containerized units for flexible power distribution across remote sites.
India
India's ambitious rural electrification and industrial expansion initiatives create substantial demand for modular power solutions. The country's PLI scheme supports domestic manufacturing for power equipment, including substation components. Grid infrastructure development in developing economies often prioritizes cost-effective and rapidly deployable designs. Maharashtra's industrial corridors require low voltage containerized substations for localized power needs in new facilities.
Containerized Substation Market Key Industry Players
Concentration sits with large, diversified industrial conglomerates that leverage extensive portfolios and global manufacturing footprints. The market also includes specialized power technology providers focusing on specific voltage ranges or application niches. Competitive moves center on portfolio diversification to integrate digital capabilities and strategic channel partnerships to reach diverse end-users.
ABB Ltd, Siemens AG, and Schneider Electric SE exemplify large, diversified industrial conglomerates with extensive digital substation portfolios. These companies anchor market segments through global reach and comprehensive offerings for utilities and industrial clients. Their strategies involve integrating advanced communication protocols and smart grid capabilities into modular solutions. These firms sustain market positions through established channel partnerships and continuous innovation in digital substation technology.
| Leading Market Players |
|---|
| Eaton Corp plc |
| Larsen and Toubro Ltd. |
| ABB Ltd |
| alfanar Group |
| CG Power and Industrial Solutions Ltd. |
| Schneider Electric SE |
| General Electric Co. |
| Hitachi Energy |
| Siemens AG |
| Others |
Cost & Logistics Intelligence
Extended 18-month lead times for high-voltage transformers concentrate pricing power with established manufacturers, shaping procurement cycles for large-scale grid projects. This dynamic forces buyers into longer planning horizons, impacting overall project economics.
Pricing Analysis
Project-based pricing, often incorporating volume discounts for large utility orders, dominates the containerized substation market. Price differentiation stems from the customization level required for specific grid codes and the extent of integrated after-sales service and maintenance contracts. Pricing softness reflects input cost volatility for critical raw materials like copper and electrical steel, which manufacturers absorb to maintain competitive bids. Developing markets, particularly for low voltage units, exhibit the highest price sensitivity, while utilities procuring digital substations for critical infrastructure show less elasticity.
Supply Chain Analysis
Elevated container shipping costs and port congestion challenge inbound logistics for containerized substation components, particularly for intercontinental deliveries. Geographic supply concentration includes China for standardized components, Germany for specialized switchgear, and the United States for advanced control systems. Raw material dependencies include copper, aluminum, and advanced SF6-free insulating gases. Commodity price volatility for metals represents a significant structural risk for manufacturers. Distribution runs through a network of EPC contractors and direct sales channels to large utilities and industrial end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is experiencing a cyclical recovery driven by sustained global investment in renewable energy infrastructure.
For Market Incumbents: Consolidate digital capabilities by integrating advanced communication protocols like IEC 61850 across all product lines. Expand global manufacturing footprints into emerging markets to mitigate logistical complexities and reduce delivery times. This defends against specialized new entrants offering localized solutions and addresses the threat of grid code fragmentation by enabling regional customization. Invest in R&D for SF6-free switchgear technology to comply with evolving environmental regulations.
For New Entrants and Emerging Players: Anchor in niche applications requiring rapid deployment and compact footprints, such as EV charging infrastructure and temporary power for remote mining operations. Target underpenetrated geographies like Sub-Saharan Africa for rural electrification projects, offering modular low-voltage units. A viable go-to-market angle involves flexible leasing or service-based contracts, appealing to customers seeking operational expenditure models over upfront capital investment.
For Investors and Strategic Acquirers: Long-term, this sits as an infrastructure enablement play because containerized substations are fundamental to grid modernization and decentralized energy integration. Acquisition targets should be specialized power technology providers with strong intellectual property in digital protection and control systems or those with established channel partnerships in high-growth renewable energy sectors. The signal to watch is the widespread adoption of standardized grid codes across major economies, which would accelerate market scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Establishes new manufacturing hubs in high-growth regions to improve supply chain resilience. |
| Digital Integration | Enhances remote monitoring and control capabilities for predictive maintenance and grid stability. |
| SF6-Free Technology Adoption | Ensures compliance with tightening environmental regulations like the EU F-Gas Regulation. |
| Hybrid System Development | Combines substations with battery energy storage for grid stabilization and renewable energy firming. |
| Service-Based Model Expansion | Offers flexible leasing and maintenance contracts to meet evolving customer procurement preferences. |
Research Approach
Operator-level perspectives from utility planning officers, renewable energy project developers, industrial facility managers, and EPC contractors anchored the qualitative base of this analysis. This primary research was triangulated with extensive secondary data from government energy reports, company annual reports, IEC standards documents, and environmental agency publications. A robust bottom-up and top-down approach ensured comprehensive market sizing and validation.
Sensitivity analysis framed the quantitative modeling, providing volume and value projections across the analysis window. The analytical framework incorporated segmentation dimensions including product type, application, technology, end-user, and regional grid development stage. Compound annual growth rates were derived from historical trends, projected technology adoption rates, and the impact of supportive government policies. Key industry-specific forecast inputs included renewable energy deployment targets and infrastructure spending budgets.
Material uncertainties — geopolitical shifts, major commodity price shocks, and unforeseen regulatory changes — sit outside the modeled envelope. Forecasts reflect assumptions documented at the time of analysis regarding market conditions and technological trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Electrodialysis System Market
Electrical Power Equipment
Global Electric Power Substation Automation Market
Electrical Power Equipment
Residential Air Insulated Power Distribution Component Market
Electrical Power Equipment
Subsea Cables Equipment Market
Electrical Power Equipment
Global Lightning Arrester Market
Electrical Power Equipment
Substation Market
Electrical Power Equipment
Offshore Cables Market
Electrical Power Equipment
AC Residential Switchgear Market
Electrical Power Equipment
Fuse Link Market
Electrical Power Equipment
Gas Insulated Switchgears (GIS) Market
Electrical Power Equipment
Global Electrical SCADA Market
Electrical Power Equipment
Domestic Hot Water (DHW) Tanks Market
Electrical Power Equipment
Bucket Water Heater Market
Electrical Power Equipment
Magnetic Ballast Market
Electrical Power Equipment
Global Magnetic Circuit Breaker Market
Electrical Power Equipment
Solar Combiner Boxes Market