
 Energy Retrofit Systems Market | 2026-2036
Energy Retrofit Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Retrofit Systems Market Analysis
Net-zero-ready performance specifications are reorganizing procurement priorities across the energy retrofit systems value chain. Johnson Controls leverages its building automation integration capabilities to capture complex multi-system projects. Siemens anchors its position through deep manufacturing scale in HVAC and digital energy management platforms. Ameresco differentiates by specializing in performance-contracting structures that transfer efficiency risk from building owners to service providers.
Energy retrofit systems encompass integrated building upgrades—encompassing HVAC replacement, envelope insulation, lighting conversion, and control system modernization—that reduce operational energy consumption in existing structures, typically targeting thermal performance coefficients below 0.25 W/m²K and lighting power densities under 9 W/m². The application dimension tilts heavily toward commercial buildings where lease structures and corporate sustainability mandates compress payback thresholds, while residential units represent a fragmented but volume-rich segment constrained by financing access. Technology leadership clusters around energy management systems and LED technology, with solar integration gaining traction where local net-metering policies remain favorable.
The US EPA emissions disclosure requirements and the EU Green Deal renovation wave directives are tightening compliance thresholds for existing building stock, forcing capital planning cycles to incorporate retrofit sequencing. Japan's METI building energy efficiency standards and the UK's Future Homes Framework add overlapping certification demands that shape product specification and installer qualification. Stakeholders must monitor regulatory divergence across jurisdictions to avoid stranded asset exposure in multi-national building portfolios.
Market Dynamics
Stringent building emissions disclosure mandates across the United States, European Union, and Japan are compressing capital planning cycles and forcing portfolio owners to sequence multi-system retrofits rather than defer maintenance. This regulatory acceleration is restructuring vendor relationships toward integrated service providers capable of bundling HVAC, envelope, and control system upgrades under single accountability structures.
Growth Catalysts
- US EPA Benchmarking Mandates:Large commercial building owners must now report annual energy and emissions data, creating immediate audit demand and retrofit prioritization based on disclosed performance gaps.
- Heat Pump Technology Maturation:Cold-climate heat pumps achieving coefficient of performance above 3.0 at minus 15°C are displacing fossil fuel heating in Nordic and Northeast US retrofit projects.
- Utility-Backed Financing:On-bill repayment programs in Germany, Japan, and the United Kingdom are removing upfront capital barriers for multi-family residential and small commercial building owners.
Market Restraints
- Copper and Aluminum Price Volatility:HVAC equipment and electrical infrastructure represent 35-45% of retrofit material costs, exposing project margins to London Metal Exchange commodity swings.
- Certified Installer Scarcity:Germany's KfW efficiency loan programs and the UK's PAS 2035 certification requirements are constraining qualified labor supply below program demand levels.
- Natural Gas Infrastructure Lock-In:Existing district heating networks and building-level gas distribution in Eastern European and Northeast US markets create technical and economic friction for full electrification retrofits.
Strategic Opportunities
- India's ECBC-R Compliance Wave:The Energy Conservation Building Code for residential structures is creating first-mover advantage for envelope and cooling system specialists in high-rise construction.
- Grid-Interactive Building Controls:Convergence of building automation systems with utility demand response programs enables revenue stacking from frequency regulation services.
- Commercial Real Estate Portfolio Aggregation:Institutional owners with cross-border assets are consolidating retrofit procurement through framework agreements, favoring vendors with multi-country service capabilities.
Industry Challenges
- Deep Energy Modeling Skill Shortage:Whole-building simulation expertise required for EU Energy Performance Certificate A-rated retrofits exceeds current training pipeline output.
- Interoperability Friction:Legacy BACnet and proprietary control protocols in existing commercial buildings complicate integration with cloud-based energy management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Retrofit Systems Market |
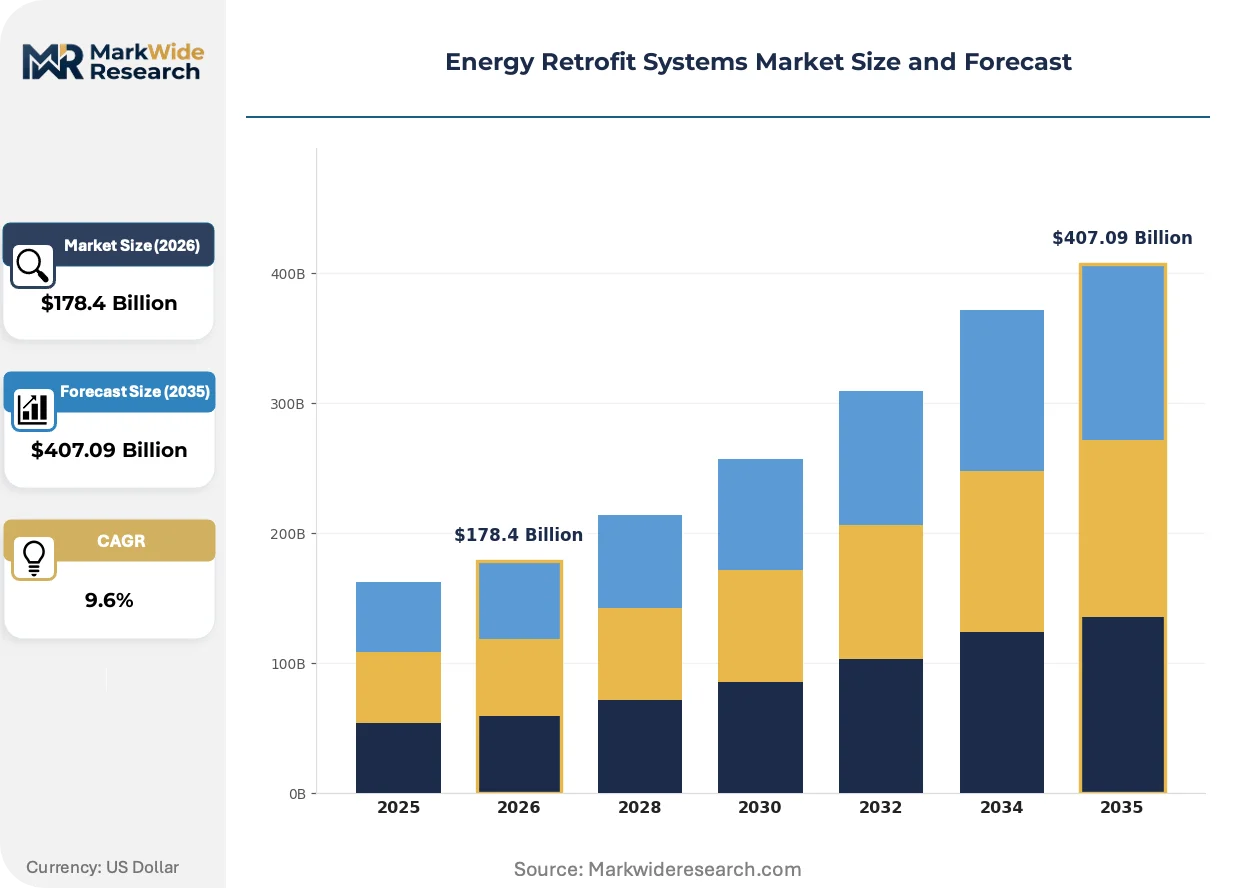
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $407.09 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: HVAC Systems, Insulation Materials, Lighting Solutions, Building Automation Application: Commercial Buildings, Residential Units, Industrial Facilities, Educational Institutes Technology: Smart Meters, Energy Management Systems, Solar Integration, LED Technology End User: Facility Managers, Homeowners, Contractors, Government Agencies |
| Companies Covered | Johnson Controls, Schneider Electric, Siemens, Ameresco, Daikin Industries Ltd., Trane Technologies, Eaton, AECOM, Orion Energy Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Retrofit Systems Market Emerging Trajectories
Digital twin technology and prefabricated building envelope systems are compressing retrofit timelines from years to months, while policy frameworks increasingly mandate performance guarantees rather than equipment-only specifications. These shifts are elevating service integration capabilities above component manufacturing scale as the primary competitive differentiator.
Building-integrated photovoltaics with thin-film or crystalline silicon laminates is fragmenting the traditional separation between envelope contractors and solar installers. Commercial building owners in California and the Netherlands are specifying BIPV replacements during facade refurbishment at accelerating rates. This convergence is compressing vendor margins in standalone roofing and glazing categories while creating integrated design-build opportunities for firms controlling both envelope and electrical competencies.
The EU F-Gas Regulation phase-down schedule is forcing refrigerant transitions in existing HVAC infrastructure before natural equipment end-of-life. Building operators in France and Germany are accelerating chiller and heat pump replacement cycles to avoid hydrofluorocarbon supply constraints and quota price spikes. Equipment manufacturers are responding with propane and hydrofluoroolefin product lines, though flammability codes in several member states remain misaligned with new refrigerant safety standards.
Performance-based service contracts are displacing capital expenditure models for lighting and HVAC upgrades in US commercial real estate. Institutional owners with net-zero commitments are contracting energy savings companies to retain equipment ownership and guarantee kilowatt-hour reductions. This shift is most visible in Class A office portfolios in New York, Boston, and San Francisco, where lease structures already pass utility costs to tenants and owners prioritize operational expenditure predictability over asset control.
Energy Retrofit Systems Market Segmentation
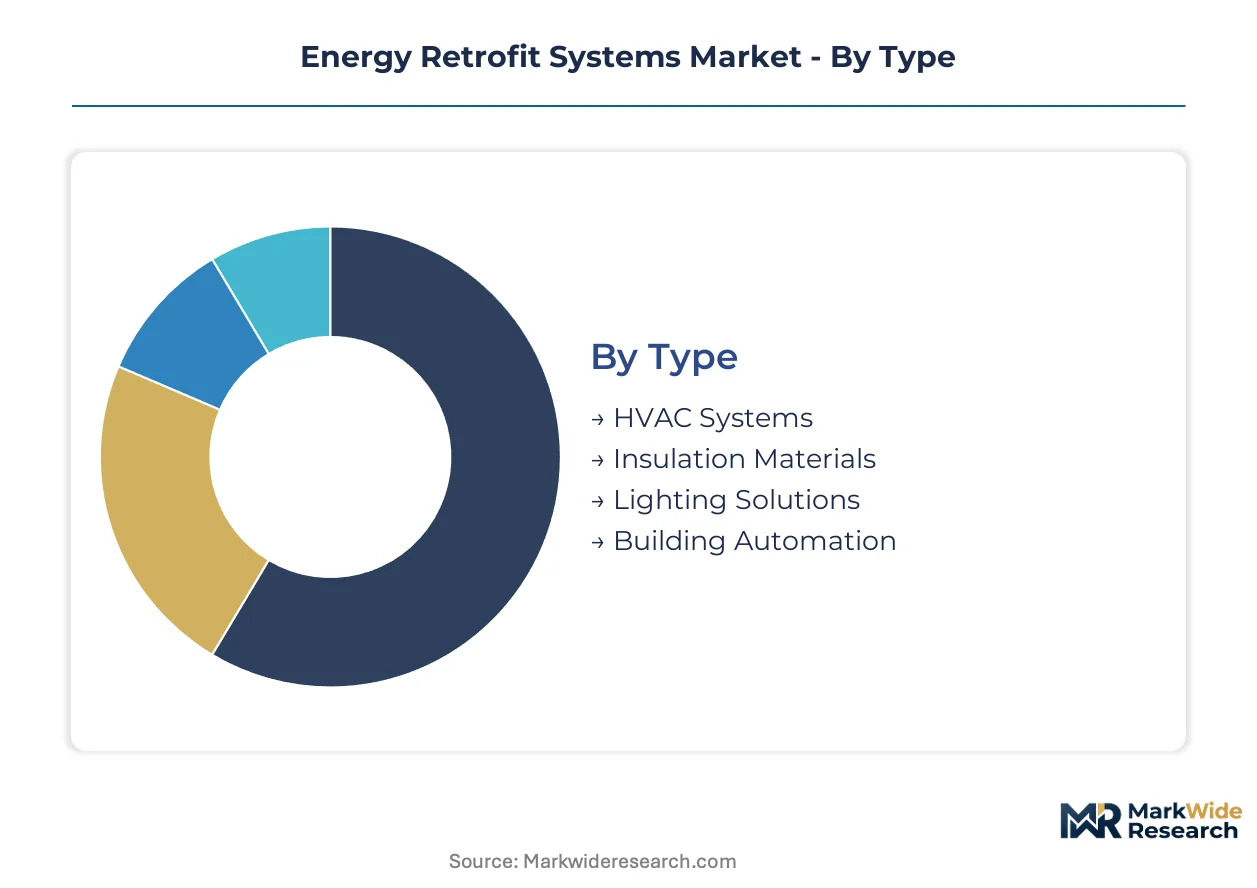
Energy retrofit systems fragment across four distinct taxonomies that shape procurement patterns and vendor positioning. Channel dynamics vary sharply by segment—integrated contractors dominate HVAC and automation rollouts, while material distributors and electrical wholesalers capture insulation and lighting flows.
Type:
Channel-mix patterns concentrate high-value system sales through design-build contractors, while material-heavy segments flow through specialized distributors with regional fabrication capabilities.
- HVAC Systems:Heat pumps, chillers, and air handling units with cold-climate performance ratings above COP 3.0. Demand clusters in Germany and the Northeast US where utility incentive programs and gas-to-electric mandates compress replacement cycles.
- Insulation Materials:Mineral wool, rigid foam, and aerogel systems targeting thermal performance coefficients below 0.25 W/m²K. Retrofit contractors in the United Kingdom and Japan are specifying prefabricated envelope panels to accelerate installation timelines.
- Lighting Solutions:LED retrofits and daylight harvesting controls distributed through electrical supply houses.
- Building Automation:BACnet and cloud-based energy management platforms sold through systems integrators with commissioning capabilities.
HVAC Systems dominates installed base. Building Automation is where expansion concentrates.
Application:
Cost-tier stratification separates premium Class A office retrofits from economy-grade multi-family residential projects, with margin structures diverging by factor of two.
- Commercial Buildings:Office towers, retail portfolios, and hospitality assets with net-zero disclosure mandates. Lease structures in New York, Boston, and San Francisco pass utility costs to tenants, accelerating owner investment in performance-guaranteed upgrades.
- Residential Units:Single-family and multi-family structures where financing access constrains uptake. On-bill repayment programs in Germany and Japan are unlocking volume in apartment buildings with centralized heating infrastructure.
- Industrial Facilities:Manufacturing plants and warehouses with process-load integration requirements.
- Educational Institutes:K-12 and university buildings with public procurement cycles and voter-approved bond financing.
Commercial Buildings captures premium project value. Residential Units is climbing the fastest.
Technology:
Volume concentration favors mature LED and metering hardware, while emerging platforms in solar integration and AI-driven controls command development-stage margins.
- Smart Meters:Interval metering and submetering infrastructure for tenant-level billing and demand response enrollment. Deployment accelerates in California and the Netherlands where net-metering policies and time-of-use rates create revenue visibility.
- Energy Management Systems:Cloud-based analytics platforms with fault detection and automated commissioning. Integration friction with legacy BACnet protocols in existing US commercial stock is constraining rollout velocity.
- Solar Integration:Rooftop PV and building-integrated photovoltaics during envelope refurbishment.
- LED Technology:Solid-state lighting with power densities under 9 W/m² and tunable white controls.
LED Technology dominates installed base. Energy Management Systems is gaining share fastest.
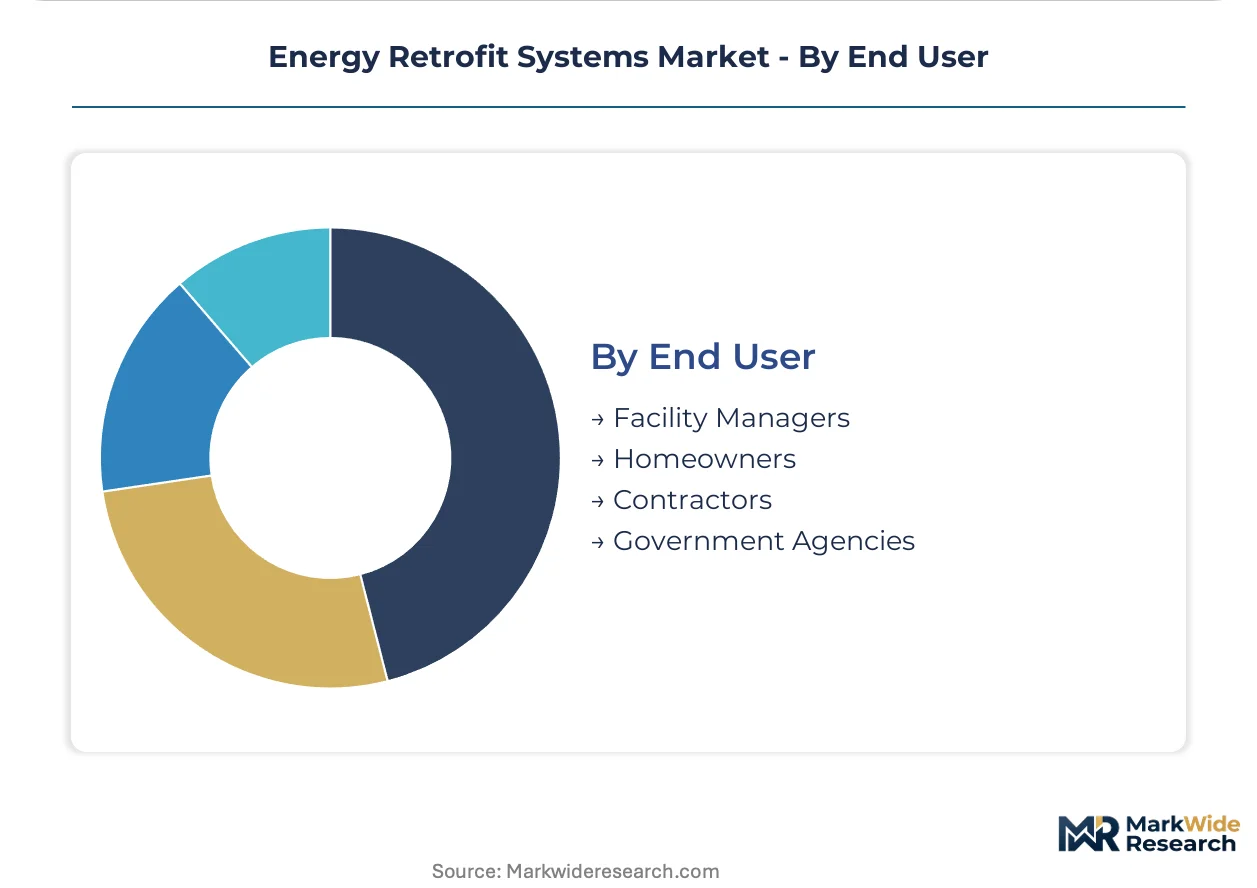
End User:
Customer-type segmentation separates institutional purchasers with framework agreements from fragmented residential decision-makers with high acquisition costs.
- Facility Managers:Corporate and institutional portfolio operators with multi-site retrofit sequencing mandates. US EPA benchmarking requirements and EU Energy Performance Certificate compliance are forcing capital planning cycle compression across large holdings.
- Contractors:Design-build and performance-contracting firms with single-accountability project structures. Germany's KfW efficiency loan programs and the UK's PAS 2035 certification requirements are constraining qualified installer supply below program demand.
- Homeowners:Individual residential decision-makers with financing sensitivity and information asymmetry.
- Government Agencies:Federal, state, and municipal building operators with public procurement compliance.
Facility Managers dominate project value. Contractors is where vendor relationship investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing for energy retrofit systems concentrates in Germany, Japan, and the United States where HVAC and automation vendors maintain integrated production and service networks. Regional demand patterns diverge sharply based on building stock age, utility tariff structures, and enforcement timelines for emissions disclosure mandates.
United States
Commercial building owners in New York, Boston, and San Francisco face compressed capital planning cycles due to EPA benchmarking mandates and local gas-phaseout ordinances. The Inflation Reduction Act's commercial clean energy tax credits are accelerating heat pump and envelope upgrade procurement. Class A office portfolios in Manhattan and downtown Chicago are sequencing multi-system retrofits through performance-contracting structures.
Germany
Aging multi-family housing stock and the KfW efficiency loan program are driving envelope and heating system replacement across North Rhine-Westphalia and Bavaria. The EU F-Gas Regulation is forcing refrigerant transitions in existing HVAC infrastructure ahead of natural end-of-life. Berlin and Hamburg building operators are specifying prefabricated facade panels to accelerate installation timelines.
Japan
METI building energy efficiency standards and utility demand response programs are reshaping retrofit procurement in Tokyo and Osaka commercial districts. Cold-climate heat pump adoption is expanding in Hokkaido as coefficient-of-performance ratings improve. On-bill repayment programs are unlocking volume in apartment buildings with centralized heating infrastructure.
United Kingdom
The Future Homes Framework and PAS 2035 certification requirements are constraining qualified installer supply below program demand levels. London commercial landlords are bundling HVAC, lighting, and control upgrades to meet Energy Performance Certificate compliance thresholds. Manchester and Birmingham retrofit contractors are reporting project backlogs tied to certified assessor scarcity.
India
The Energy Conservation Building Code for residential structures is creating specification demand for envelope and cooling system specialists in high-rise construction across Mumbai and Delhi-NCR. Maharashtra and Gujarat states are seeing accelerated deployment of smart metering and submetering infrastructure. Bangalore and Hyderabad IT park developers are integrating building automation with utility demand response programs.
Energy Retrofit Systems Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the energy retrofit systems value chain. The market structure tilts toward integrated service providers capable of bundling HVAC, envelope, and control system upgrades under single accountability structures. Three archetypes dominate: building automation specialists with digital energy management platforms, performance-contracting firms that transfer efficiency risk to service providers, and diversified industrial conglomerates with manufacturing scale in core equipment categories. Competitive moves concentrate on strategic partnerships for technology integration and geographic expansion through regional installer network acquisitions.
Within the integrated service provider tier, Johnson Controls and Siemens exemplify archetypes combining automation capabilities with multi-system project accountability. Ameresco occupies a position representing the performance-contracting model where equipment ownership and savings guarantees shift risk from building owners. These three companies anchor the competitive landscape by demonstrating alternative paths to capturing value in a market where procurement is shifting from component sales to outcome-based service structures.
| Leading Market Players |
|---|
| Johnson Controls |
| Schneider Electric |
| Siemens |
| Ameresco |
| Daikin Industries Ltd. |
| Trane Technologies |
| Eaton |
| AECOM |
| Orion Energy Systems, Inc. |
| Others |
Supply Flow & Price Mechanics
PAS 2035 certification requirements in the United Kingdom gate both installer qualification and project pricing tiers simultaneously, compressing margins for uncertified contractors while elevating premiums for accredited assessors across Manchester and Birmingham retrofit markets.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across HVAC replacement cycles, with refrigerant quota costs stratifying equipment premiums from standard to economy levels. Price differentiation rests on certification grade and geographic delivery cost, with London commercial landlords showing lowest sensitivity due to lease pass-through structures while German multi-family housing associations face acute financing constraints. Cost compression in mid-tier heat pump installations is intensifying because copper and aluminum commodity exposure erodes project margins.
Supply Chain Analysis
Germany and Japan anchor HVAC equipment manufacturing, with the United States controlling building automation platform development. Raw material dependencies draw from copper wiring, aluminum heat exchangers, and rare-earth magnet supply for compressor motors. Single-source vulnerability concentrates in Chinese-processed rare earths for high-efficiency heat pump compressors. Distribution runs through design-build contractors for integrated systems and electrical wholesalers for lighting and insulation materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Energy retrofit systems represent a high-growth disruption as EPA benchmarking mandates and EU Green Deal renovation directives compress capital planning cycles from deferral to immediate multi-system sequencing.
For Market Incumbents: Consolidate installer network control through PAS 2035 certification pipeline investments in the United Kingdom and KfW-accredited partnership structures in Germany. Vertical integration into prefabricated envelope manufacturing counters margin erosion from commodity volatility in copper-intensive HVAC components. For New Entrants and Emerging Players: Performance-contracting capability gaps in US Class A office portfolios offer white-space entry where institutional owners prioritize operational expenditure predictability over asset control. India's ECBC-R compliance wave presents the most penetrable geography for envelope specialists targeting high-rise residential construction in Mumbai and Delhi-NCR. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-defined energy management platforms as cloud-native architectures displace on-premise building automation deployments. Acquisition targets should emphasize firms with whole-building simulation expertise for EU Energy Performance Certificate A-rated retrofits. The signal to watch is utility demand response program enrollment velocity as a proxy for grid-interactive building control adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Installer Certification Pipeline | PAS 2035 and KfW accreditation requirements in the United Kingdom and Germany constrain qualified labor supply below program demand. |
| Prefabricated Envelope Manufacturing | Berlin and Hamburg building operators specify facade panels to accelerate installation timelines and reduce on-site labor exposure. |
| Performance-Contracting Structure | New York and Boston Class A office portfolios shift equipment ownership to energy savings companies for operational expenditure predictability. |
| Cloud-Native Platform Migration | Integration friction with legacy BACnet protocols in existing US commercial stock constrains rollout velocity for traditional vendors. |
| Refrigerant Transition Product Lines | EU F-Gas Regulation phase-down forces chiller and heat pump replacement cycles ahead of natural end-of-life in France and Germany. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EIA building energy consumption data, IEA efficiency policy databases, and EPA emissions disclosure filings. Primary interviews engaged facilities managers at commercial portfolios, retrofit contractors with PAS 2035 certification, utility demand response program officers, and HVAC equipment procurement leads. Bottom-up project pipeline analysis triangulates against top-down regulatory mandate enforcement timelines.
Segmentation dimensions modeled span HVAC systems, insulation materials, lighting solutions, and building automation across commercial buildings, residential units, industrial facilities, and educational institutes. Technology segmentation incorporates smart meters, energy management systems, solar integration, and LED retrofits. CAGRs derive from regulatory enforcement schedule phasing and utility incentive program budget trajectories. Forecast inputs include copper and aluminum price volatility bands and certified installer training pipeline capacity.
Underlying assumptions cover EPA benchmarking mandate adherence rates and EU Green Deal renovation wave funding continuity, with deviation risk concentrated in utility tariff restructuring and natural gas infrastructure lock-in persistence. Recalibration cycles align with material shifts in F-Gas Regulation quota pricing and heat pump coefficient-of-performance technology thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Efficiency Solutions
Energy Efficient Windows Market
Energy Efficiency Solutions
Residential Air to Water Heat Pump Market
Energy Efficiency Solutions
Heat Pump Water Heater Market
Energy Efficiency Solutions
Residential Energy-Efficient Technologies Market
Energy Efficiency Solutions
Energy Retrofits Market
Energy Efficiency Solutions
Global Energy Efficient Lamps and Ballasts Market
Energy Efficiency Solutions
Energy Efficient Warehouse Lighting System Market
Energy Efficiency Solutions
Energy-Saving Constant Humidity Storage Cabinet Market
Energy Efficiency Solutions
Waste Heat Recovery System Market
Energy Efficiency Solutions
Economizer Market
Energy Efficiency Solutions
Energy Efficient Lighting Technology Market
Energy Efficiency Solutions
Energy Efficient Lighting Market
Energy Efficiency Solutions
Energy Efficiency Gamification Market